
 UHF RFID Inlays Market | 2026-2036
UHF RFID Inlays Market Size, Share, and Industry Trends Forecast 2026-2036
UHF RFID Inlays Market Analytics
Retail apparel tagging is rebalancing the UHF RFID inlays demand profile as brands mandate item-level serialization for omnichannel fulfillment. Avery Dennison Corporation leverages its adhesive materials science to dominate high-volume apparel label contracts. Impinj sustains R&D intensity in RAIN RFID endpoint IC design, anchoring its position in chip-centric value capture. Zebra Technologies competes through printer-encoder hardware integration, extending its channel control across enterprise deployment workflows.
UHF RFID inlays are laminated assemblies combining an antenna substrate, an integrated circuit, and an adhesive face for attachment to products or packaging, typically operating in the 860–960 MHz band with read ranges exceeding ten meters in open-air configurations. Paper-based substrates lead unit volumes in retail and logistics applications where single-use disposable economics dominate, while flexible inlays capture expanding demand in healthcare asset tagging where conformal adhesion to curved medical devices matters. Passive technology anchors the installed base due to zero-maintenance battery-free operation, though hybrid architectures are gaining traction in cold-chain logistics where environmental sensors must co-reside with identification functions.
GS1 EPCglobal standards shape interoperability requirements across the value chain, while FCC Part 15 rules in the United States and ETSI EN 302 208 in Europe constrain transmit power and spectrum allocation, directly affecting read-range performance claims and cross-border equipment certification burdens. The EU Green Deal's packaging waste directives are pressing inlay makers to eliminate non-recyclable layers and validate circular material flows. Stakeholders must monitor whether regional spectrum harmonization advances or fragments, as this determines whether single-SKU inlay designs can scale across multinational retail footprints or force costly geographic product variants.
Market Dynamics
Serialized item-level tracking mandates from major retailers are compressing deployment timelines and forcing inlay manufacturers to prioritize read sensitivity and antenna miniaturization over unit cost alone.
Growth Catalysts
- EPC Gen2v3 Standards:GS1's tightened sensitivity benchmarks are accelerating performance differentiation among inlay suppliers. Logistics operators in Germany and the Netherlands are mandating compliance for supplier qualification.
- China Manufacturing Scale:XINDECO IOT and Invengo Technology anchor concentrated production capacity for Asia-Pacific logistics deployments. Domestic demand from smart factory initiatives absorbs regional output before export allocation.
- Healthcare Asset Conformity:Flexible substrate inlays are capturing demand from hospital systems requiring adhesion to curved surgical instruments and portable diagnostic equipment. Passive operation eliminates battery maintenance in sterile environments.
Market Restraints
- Copper and Aluminum Volatility:Antenna substrate materials face input cost swings that compress inlay margins at high volumes. Smaller converters lack hedging capacity against base metal futures.
- Single-Source IC Dependency:RAIN RFID chip supply concentrates among three foundry-qualified vendors. Any fabrication disruption propagates through the laminated assembly chain within weeks.
- ETSI EN 302 208 Power Limits:European transmit power restrictions constrain read-range performance claims versus FCC Part 15 allowances in the United States. Cross-border equipment certification forces geographic product variants.
Strategic Opportunities
- EU Green Deal Packaging Directives:Circular material flow mandates are pressing inlay makers to eliminate non-recyclable adhesive layers. Early compliance positions suppliers for preferred-retailer status.
- Cold-Chain Sensor Fusion:Hybrid architectures combining passive identification with temperature logging are opening pharmaceutical distribution contracts. Battery-assisted sensors address gaps where environmental monitoring exceeds pure RFID capability.
- India PLI Scheme Absorption:Electronics manufacturing incentives are drawing assembly capacity toward Mumbai and Chennai industrial corridors. Local production avoids import duty friction for domestic logistics deployments.
Industry Challenges
- RAIN RFID Protocol Engineering Talent:The intersection of RF design, semiconductor physics, and adhesive materials science creates hiring bottlenecks. Universities produce few graduates with cross-functional endpoint IC expertise.
- GS1 Certification Timelines:Interoperability validation for new inlay designs stretches six to nine months. Retailer-mandated serialization deadlines compress product development windows.
- Legacy Warehouse Management Integration:Enterprise ERP systems require middleware adaptation to ingest item-level RFID data streams. Implementation friction slows pilot-to-scale transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UHF RFID Inlays Market |
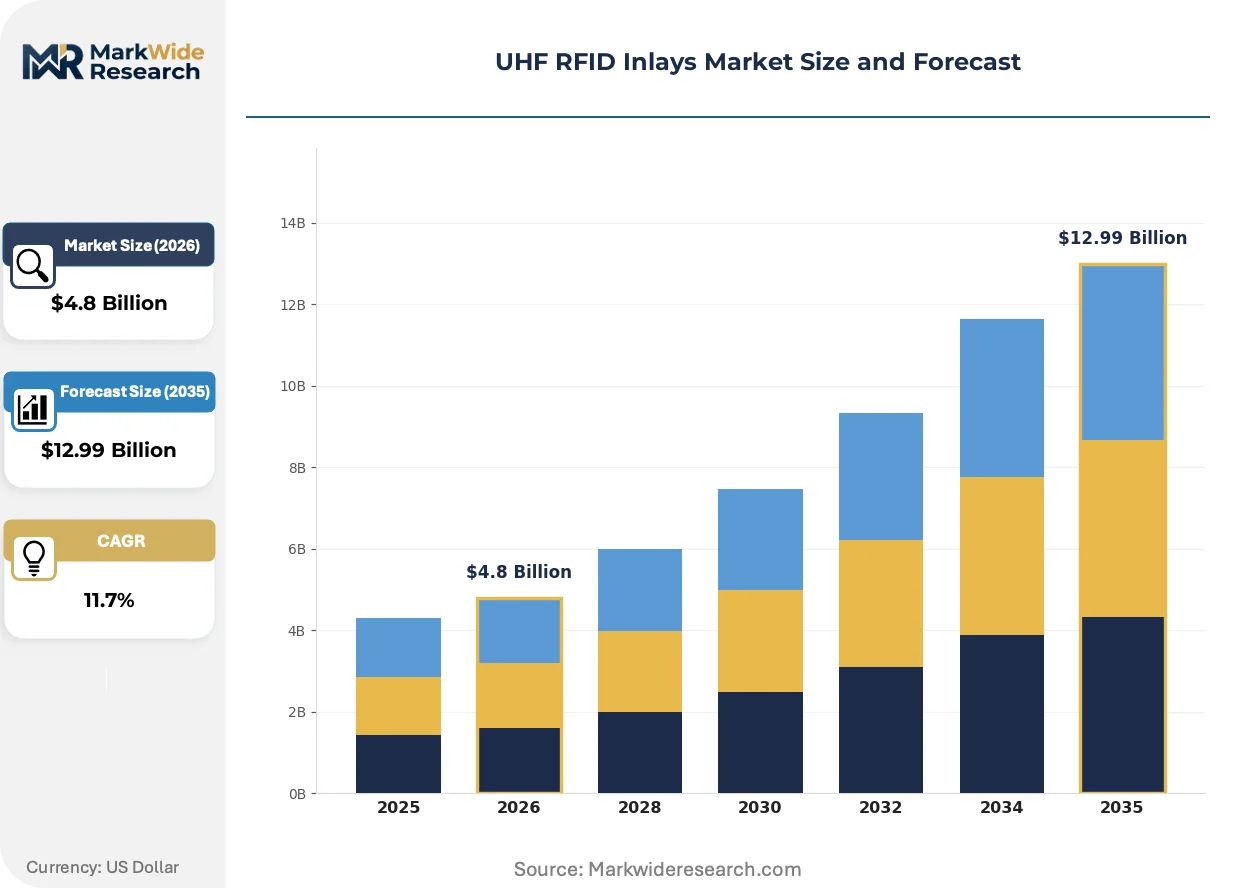
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper-based, Plastic-based, Metal-coated, Flexible End User: Retail, Logistics, Healthcare, Manufacturing Application: Asset Tracking, Inventory Management, Access Control, Smart Labels Technology: Passive, Active, Bifrequency, Hybrid |
| Companies Covered | Avery Dennison Corporation, SMARTRAC N.V, Invengo Technology Pte. Ltd, Alien Technology, NXP Semiconductors, Impinj, XINDECO IOT, Zebra Technologies, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UHF RFID Inlays Market Evolving Landscape
Antenna substrate engineering and regulatory packaging mandates are converging to reshape how inlay suppliers compete on performance, sustainability credentials, and supply chain integration depth.
Chipless RFID encoding is electrifying traceability economics for low-value consumables where silicon IC costs previously prohibited tagging. Fast-moving consumer goods distributors in Brazil and Southeast Asia are piloting printed resonant structures for pallet-level identification. The technology is electrifying volume-tier market entry by removing semiconductor dependency from unit economics.
EU Green Deal packaging waste directives are forcing elimination of polyethylene terephthalate layers and solvent-based adhesives from inlay laminates. Inlay converters in Italy and Poland are validating paper-only substrates with water-based bonding for circular material recovery. Healthcare tagging in Switzerland and Germany faces the strictest compliance timelines due to extended producer responsibility frameworks.
Retailer-driven omnichannel fulfillment is compressing supplier qualification cycles from annual reviews to quarterly performance audits. Apparel brands are unbundling inlay procurement from label printing contracts to secure direct chip sourcing leverage. This pattern is most visible in North American and British retail networks where inventory accuracy metrics determine vendor retention.
UHF RFID Inlays Market Segmentation
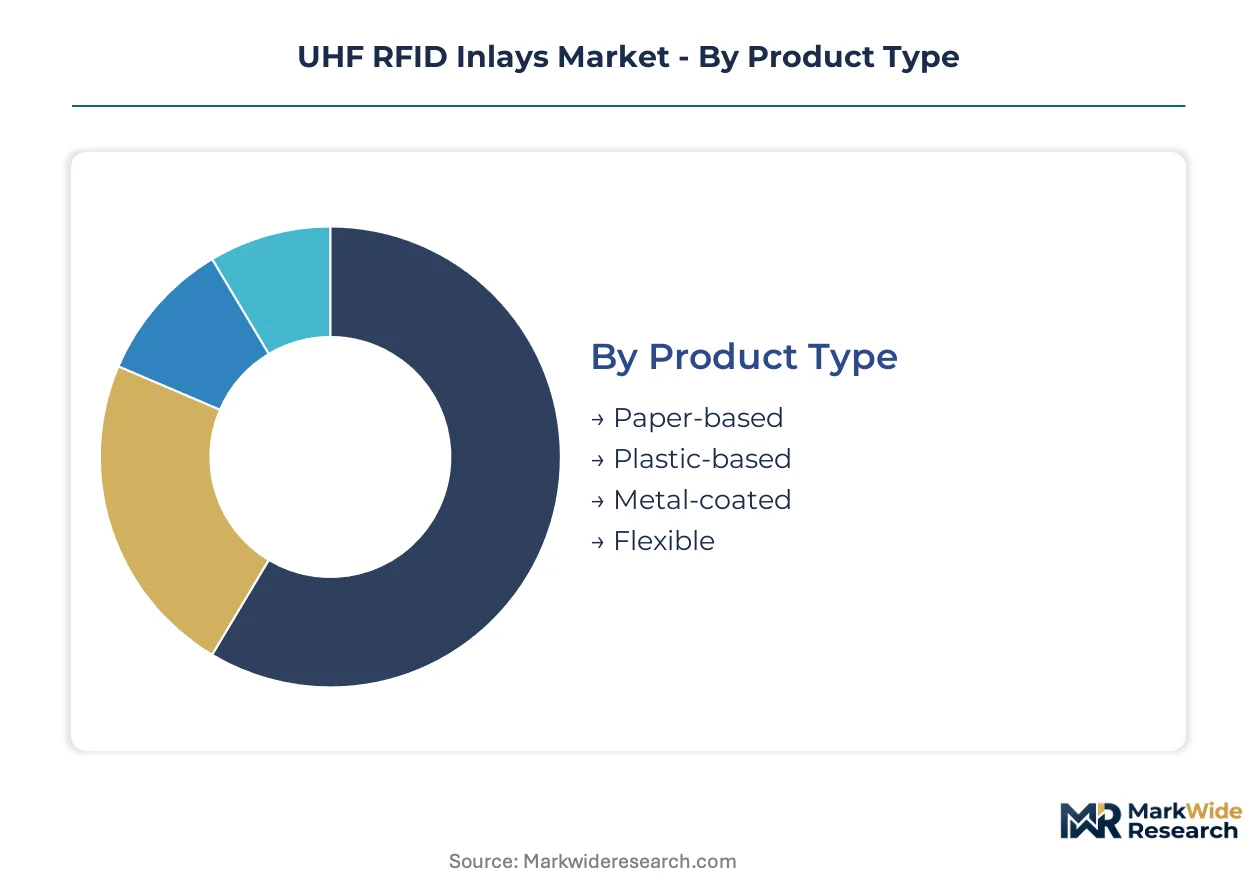
UHF RFID inlays segment across material substrates, operational technologies, and deployment contexts. Each dimension carries distinct margin profiles and supply chain requirements that shape supplier positioning.
Product Type:
Paper-based substrates dominate unit volumes through single-use economics, while flexible and metal-coated variants command premium positioning in specialized adhesion environments.
- Paper-based:Cellulose substrates laminated with aluminum or copper antenna traces deliver lowest unit cost for disposable retail apparel labels. Demand concentrates in North American and European omnichannel fulfillment networks where GS1 serialization mandates drive high-volume consumption.
- Flexible:Polyimide or polyethylene terephthalate substrates enable conformal adhesion to curved medical devices and irregular packaging geometries. Swiss and German hospital systems are absorbing regional converter capacity for surgical instrument tracking where sterile field compatibility eliminates battery-powered alternatives.
- Plastic-based:Rigid polymer carriers suit reusable container applications in automotive component logistics.
- Metal-coated:Specialty substrates with conductive layering address on-metal tagging requirements for industrial asset management.
Today's leader: Paper-based. Tomorrow's challenger: Flexible.
End User:
Retail and logistics absorb the majority of laminated assembly output, though healthcare is climbing fastest as asset conformity requirements tighten.
- Retail:Apparel brands mandate serialized item-level tracking for omnichannel inventory accuracy. British and North American retailers are unbundling inlay procurement from label printing contracts to secure direct chip sourcing leverage against RAIN RFID supply concentration.
- Logistics:Pallet and case-level identification drives consumption in German and Dutch distribution hubs where EPC Gen2v3 compliance gates supplier qualification.
- Healthcare:Hospital systems require passive operation in sterile environments to eliminate battery maintenance risks.
- Manufacturing:Smart factory initiatives in China absorb domestic XINDECO IOT and Invengo Technology output before export allocation.
Retail commands current volume leadership. Healthcare presents the steepest expansion trajectory.
Application:
Inventory management and asset tracking anchor functional demand, while smart labels integrate sensing capabilities for environmental monitoring.
- Inventory Management:Real-time stock visibility across warehouse and storefront environments. Chinese e-commerce fulfillment centers deploy paper-based inlays at scale for automated sorting.
- Asset Tracking:Equipment location monitoring in healthcare and industrial settings. German automotive suppliers track reusable containers through closed-loop logistics.
- Access Control:Personnel and vehicle entry systems in corporate and secured facilities.
- Smart Labels:Temperature and humidity logging for pharmaceutical cold chains. Hybrid architectures with battery-assisted sensors address gaps where passive RFID alone cannot capture environmental data.
Inventory management holds installed base dominance. Smart labels are gaining share fastest through sensor fusion contracts.
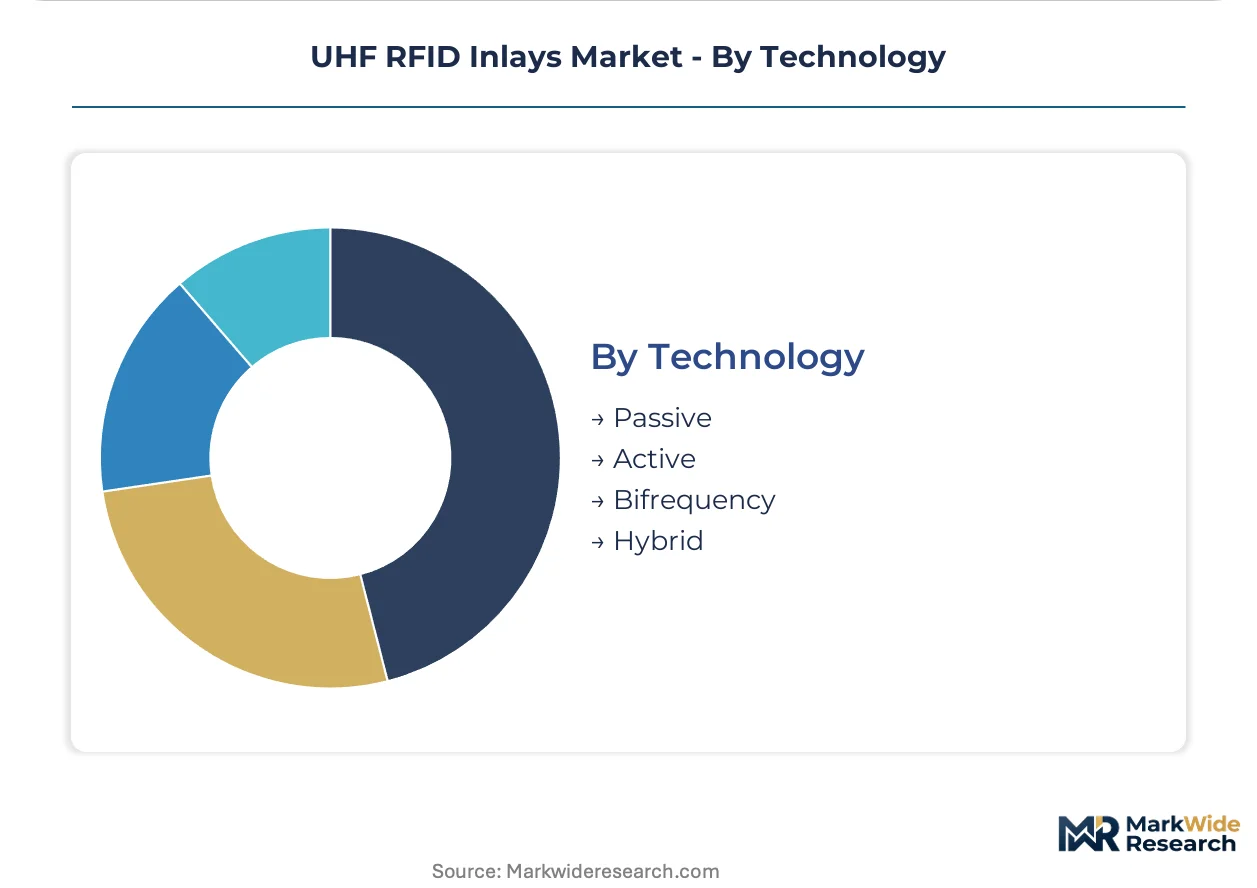
Technology:
Passive architectures anchor the installed base through zero-maintenance operation, though hybrid designs are penetrating cold-chain monitoring where environmental sensing co-resides with identification.
- Passive:Backscatter-dependent operation requires no onboard power source. RAIN RFID chip supply concentrates among three foundry-qualified vendors, creating single-source dependency risks that propagate through laminated assembly chains within weeks.
- Hybrid:Combines passive identification with battery-assisted sensing for temperature logging. Pharmaceutical distributors in Switzerland and Germany are piloting these architectures for validated cold-chain documentation under EU GDP guidelines.
- Active:Onboard power enables extended read range and sensor telemetry for high-value asset monitoring.
- Bifrequency:Dual-band operation bridges HF and UHF protocols for legacy system interoperability.
Passive technology maintains installed base leadership. Hybrid architectures represent the most dynamic growth vector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as inlay manufacturers migrate capacity toward jurisdictions with streamlined certification timelines and lower compliance costs. The divergence between FCC Part 15 power allowances in the United States and ETSI EN 302 208 constraints across Europe is creating locational advantages for export-oriented assembly operations.
United States
Omnichannel retail serialization mandates from apparel brands are compressing supplier qualification cycles. FCC Part 15 rules permit higher transmit power than European equivalents, extending read-range performance for domestic logistics deployments. Converter capacity concentrates in Ohio and Illinois industrial corridors serving Midwest distribution hubs.
Germany
Logistics operators in Hamburg and Rotterdam-connected distribution networks are mandating EPC Gen2v3 compliance for supplier qualification. ETSI EN 302 208 power limits constrain read-range claims versus North American benchmarks. Industrial converter clusters in Bavaria are validating paper-only substrates for circular material recovery under EU Green Deal timelines.
China
Smart factory initiatives under MIIT guidance are absorbing domestic XINDECO IOT and Invengo Technology output before export allocation. GB standards for RFID interoperability shape domestic procurement specifications. Yangtze River Delta manufacturing corridors anchor concentrated antenna substrate production capacity.
Switzerland
Healthcare asset tagging demand is climbing fastest as hospital systems require sterile-field-compatible passive operation. Swissmedic and extended producer responsibility frameworks impose strictest EU Green Deal compliance timelines for medical device labeling. Converter operations in Basel and Zurich industrial zones specialize in flexible substrate conformal adhesion.
India
Electronics manufacturing incentives under the PLI scheme are drawing assembly capacity toward Mumbai and Chennai industrial corridors. DGFT import duty structures favor domestic production for logistics deployments. Domestic demand from e-commerce fulfillment centers is accelerating paper-based inlay consumption for automated sorting infrastructure.
UHF RFID Inlays Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers add laminating lines to capture serialized retail tagging contracts. The vendor base separates into three tiers: adhesive materials specialists controlling high-volume apparel label economics, semiconductor-centric designers capturing chip-level value, and hardware-integrated players extending channel control through printer-encoder bundling. Strategic archetypes include substrate science leaders, RAIN RFID chip architects, and enterprise workflow integrators. Geographic expansion and portfolio diversification represent the two dominant competitive moves as suppliers seek qualification across multiple retailer networks.
Among adhesive materials specialists, Avery Dennison Corporation exemplifies the substrate-science archetype through its laminated assembly expertise. Impinj occupies a position within the semiconductor-centric tier, anchoring chip-level design capabilities. Zebra Technologies represents the hardware-integration archetype, extending enterprise deployment workflows through printer-encoder channel control. XINDECO IOT and Invengo Technology sit within the China-based manufacturing tier, serving domestic smart factory demand before export allocation.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| SMARTRAC N.V |
| Invengo Technology Pte. Ltd |
| Alien Technology |
| NXP Semiconductors |
| Impinj |
| XINDECO IOT |
| Zebra Technologies |
| Honeywell International Inc. |
| Others |
Value Network & Pricing Analysis
RFID antenna design engineers concentrated in Bavaria and the Yangtze River Delta command wage premiums that compress margins at mid-tier converters, widening the spread between economy paper-based inlays and premium flexible substrates qualified for Swiss healthcare deployments.
Pricing Analysis
Distributor margins on RAIN RFID chip bundles absorb 12-18 points before inlays reach label converters, with direct-to-OEM contracts commanding steeper volume discounts. Three-tier pricing structure across premium, standard, and economy levels reflects EPC Gen2v3 certification status and antenna sensitivity grades. Cost compression in paper-based retail tags is intensifying because aluminum foil input volatility outpaces hedging capacity at smaller converters. Logistics operators in Germany and the Netherlands exhibit lowest price sensitivity due to mandated serialization compliance, while Indian e-commerce fulfillment centers drive hardest unit-cost negotiations.
Supply Chain Analysis
Dual-sourcing requirements from major apparel brands now mandate qualified secondary chip vendors before contract award, pressuring laminators to maintain relationships with all three RAIN RFID foundry-qualified suppliers. Production concentrates in China, Germany, and the United States, with antenna substrate etching anchored in Yangtze River Delta facilities and precision converting clustered in Bavaria and Ohio. Copper and aluminum foil supplies draw from Chilean mining output and Chinese smelter capacity. Single-source IC vulnerability propagates through laminated assembly chains within weeks of any fabrication disruption. Distribution runs through converter-label printer relationships serving retailer-specific qualification protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UHF RFID inlays market has entered a late-cycle quality phase where EPC Gen2v3 sensitivity benchmarks separate premium suppliers from commodity converters facing margin erosion.
For Market Incumbents: Deploy substrate science R&D to lock in healthcare flexible-inlay contracts before EU Green Deal circular-material mandates eliminate non-compliant competitors. Consolidate converter relationships in Germany and Switzerland where extended producer responsibility frameworks tighten fastest. Chipless RFID printed resonant structures threaten silicon-dependent incumbents in pallet-level logistics tiers. For New Entrants and Emerging Players: Mid-sized Indian pharmaceutical distributors represent an underserved buyer archetype seeking hybrid temperature-logging inlays for domestic cold-chain compliance. Local assembly under PLI scheme incentives bypasses DGFT import duty friction. Target Mumbai and Chennai industrial corridors with paper-based inlays qualified for automated e-commerce sorting infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among adhesive materials specialists lacking direct chip-sourcing leverage against RAIN RFID supply concentration. Five-to-ten year viability hinges on circular-material compliance certification rather than unit-scale economics. Watch for GS1 spectrum harmonization announcements as inflection signal determining whether single-SKU designs scale across multinational footprints or force costly geographic variants.| Strategic Initiative | Industry Significance |
|---|---|
| EPC Gen2v3 Certification Investment | GS1 tightened sensitivity benchmarks now gate supplier qualification at German and Dutch logistics operators. |
| Backward Integration into Antenna Substrates | In-house etching capacity insulates margins from copper foil volatility at high-volume retail converters. |
| Circular Material Flow Validation | EU Green Deal packaging directives eliminate non-recyclable adhesive layers from qualified supplier pools. |
| Hybrid Sensor Fusion Development | Battery-assisted temperature logging opens pharmaceutical distribution contracts exceeding pure RFID capability. |
| India PLI Scheme Manufacturing Footprint | Domestic assembly avoids DGFT import duty friction for Mumbai and Chennai logistics deployments. |
Research Methodology
Multiple input streams — converter production data, retailer procurement specifications, and semiconductor foundry output records — were reconciled against GS1 certification databases and FCC/ETSI regulatory filings. Primary interviews with RFID label converters, apparel brand supply chain directors, hospital biomedical engineers, and logistics operator technology procurement leads informed demand-side validation. Secondary sources included customs trade records, MIIT smart factory initiative disclosures, EU Green Deal directive texts, and SEC filings from adhesive materials and semiconductor suppliers. Bottom-up unit shipment estimates triangulated against top-down value projections.
Data-stream reconciliation across substrate material grades, operational technology architectures, and end-use deployment contexts structured the analytical framework over the projection horizon. Segmentation dimensions modeled include substrate type, technology configuration, application function, and regional regulatory cluster. CAGRs were derived from fitted growth curves anchored to EPC Gen2v3 adoption timelines and retailer serialization mandate schedules. Forecast inputs incorporated RAIN RFID chip supply concentration risks and EU circular-material compliance trajectory assumptions.
Underlying measurement precision varies by segment; paper-based retail inlays carry tighter precision than emerging hybrid sensor fusion architectures where pilot volumes dominate. Forecasts reflect documented assumptions regarding GS1 standard harmonization progress and copper foil input cost stability. Deviation in ETSI transmit power regulations or RAIN RFID foundry capacity allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Multiband Booster Market
RF Components
US RFID Tags Market
RF Components
Dielectric Resonator Market
RF Components
Radio Frequency Duplexer Market
RF Components
Millimeter Wave Equipment Market
RF Components
Radiofrequency Identification (RFID) Market
RF Components
Embedded Antenna Systems Market
RF Components
Z-Wave Products Market
RF Components
Global Bulk Acoustic Wave (BAW) Filters Market
RF Components
RF-Microwave for 5G Market
RF Components
High Power RF Amplifier Module Market
RF Components
Japan Small Signal Transistor Market
RF Components
Radio Frequency Front End Market
RF Components
GPS Low Noise Amplifier Market
RF Components
Radio Frequency Integrated Circuit (RFIC) Market
RF Components
RF Over Fiber (Rfof) Market