
 US RFID Tags Market | 2026-2036
US RFID Tags Market Size, Share, and Industry Trends Forecast 2026-2036
US RFID Tags Market Analytics
FDA's Unique Device Identification rule is pivoting the cost-of-entry calculus for healthcare RFID suppliers, forcing compliance-grade tag investments across medical device supply chains. Zebra Technologies dominates enterprise-grade printing and encoding systems for hospital asset tracking. Impinj specializes in RAIN RFID chipsets that anchor high-volume pharmaceutical serialization programs. Avery Dennison controls adhesive-integrated inlay manufacturing for disposable medical packaging applications.
US RFID tags are wireless identification devices comprising a microchip and antenna substrate, typically operating across UHF, HF, or LF frequency bands to store and transmit electronic product codes via radio waves. Passive tags harvest interrogator energy for backscatter communication, enabling sub-dollar unit economics at billion-unit scale. Active tags carry onboard power for extended read ranges up to 100 meters in cold-chain logistics. NFC segments leverage 13.56 MHz proximity coupling for consumer payment and access control applications where tap-to-authenticate workflows displace magnetic stripe infrastructure. Inventory management applications lead volume deployment as retailers mandate source-tagging requirements upstream to suppliers.
FDA, FCC, and OSHA collectively shape US RFID market access through medical device traceability mandates, spectrum allocation for UHF industrial operations, and workplace safety standards for forklift-mounted readers. FCC Part 15 rules constrain transmitter power and spurious emissions, directly determining read-range performance specifications for warehouse gateway installations. State-level pharmaceutical pedigree laws in California and Florida layer additional serialization requirements beyond federal baselines. Stakeholders must monitor FDA's pending guidance on RFID-enabled drug authentication to anticipate next-generation tag encryption and tamper-evidence specifications.
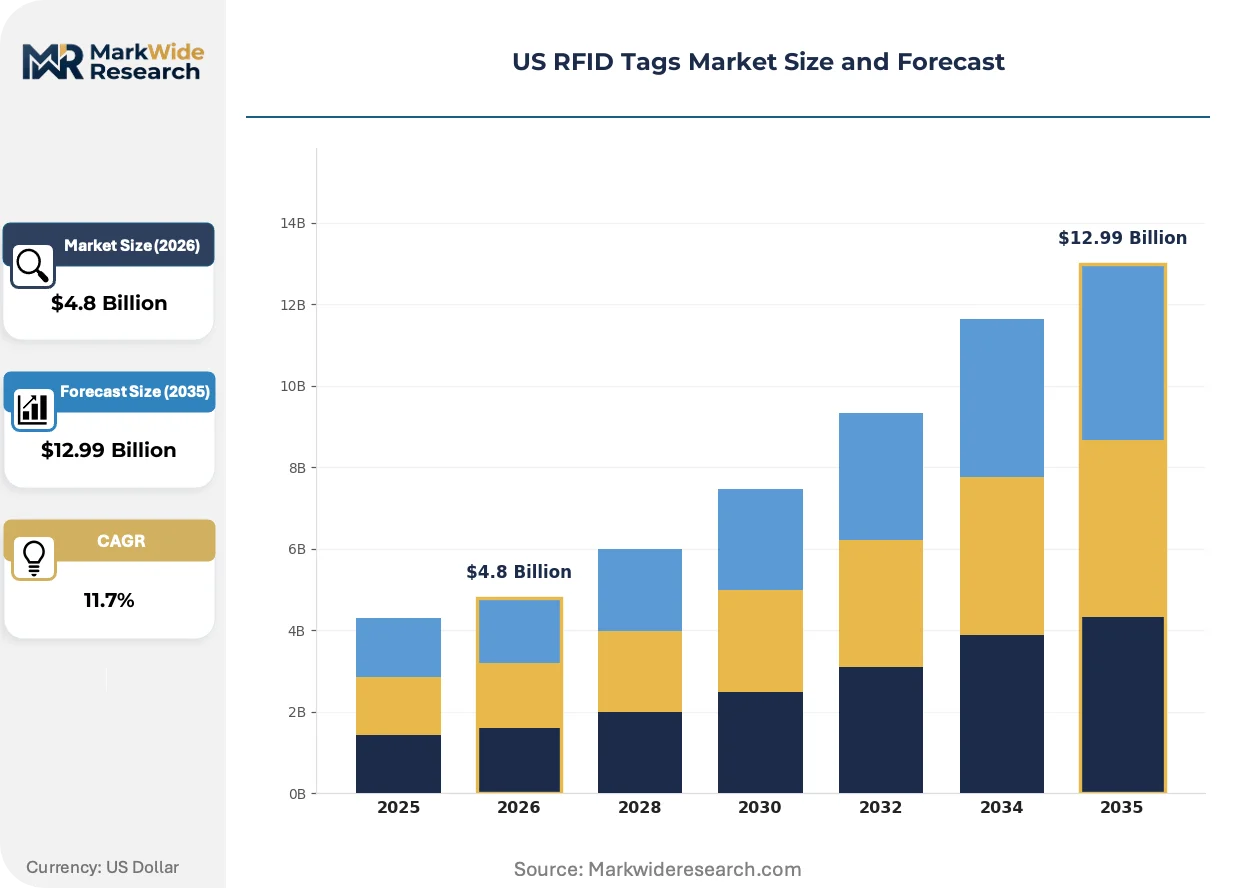
Market Dynamics
FDA's Unique Device Identification mandate is compressing healthcare RFID deployment timelines, forcing medical device manufacturers to integrate serialized tags at the unit level rather than case level. This regulatory pressure cascades through supply chains, reshaping procurement specifications and supplier qualification criteria.
Growth Catalysts
- Retail source-tagging mandates:Major US retailers now require suppliers to embed UHF RFID tags at manufacturing origin, eliminating distribution-center encoding bottlenecks and accelerating inventory velocity.
- FDA UDI compliance deadlines:The phased implementation of medical device traceability rules is expanding Class II and III device tagging requirements, creating recurring revenue streams for compliance-grade tag suppliers.
- California pharmaceutical pedigree laws:State-level serialization requirements for drug distribution exceed federal baselines, driving tag density in West Coast pharmaceutical logistics corridors.
Market Restraints
- Silicon wafer supply concentration:RAIN RFID chip fabrication depends on a limited number of foundry sources, exposing tag manufacturers to input cost volatility and allocation constraints.
- FCC Part 15 power limits:Regulatory caps on UHF transmitter output constrain read-range performance in dense warehouse environments, forcing redundant infrastructure investments.
- Barcode substitution in low-value goods:One-dimensional and two-dimensional optical codes retain cost advantages for sub-dollar retail items, limiting RFID penetration in commodity apparel and fast-moving consumer goods.
Strategic Opportunities
- Texas cold-chain expansion:Dallas-Fort Worth distribution hub growth is creating demand for active RFID tags with temperature-logging capabilities in pharmaceutical and perishable logistics.
- NFC payment infrastructure convergence:Tap-to-authenticate workflows in transit and access control are expanding 13.56 MHz tag applications beyond retail into transportation and corporate security.
- OSHA forklift-reader safety standards:Emerging workplace regulations for industrial RFID installations are creating certified-system integration service opportunities.
Industry Challenges
- RF engineer talent scarcity:Antenna design and spectrum optimization expertise concentrates among legacy defense and telecommunications specialists, constraining product development velocity for mid-tier tag manufacturers.
- Legacy WMS integration friction:Enterprise warehouse management systems require custom middleware development to ingest real-time RFID data streams, extending deployment timelines and inflating project costs.
- Multi-protocol certification complexity:Tags must simultaneously satisfy EPC Gen2, ISO 18000-6C, and retailer-specific performance thresholds, multiplying testing cycles and qualification expenses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US RFID Tags Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive, Active, Semi-Passive, NFC Application: Inventory Management, Supply Chain, Asset Tracking, Access Control End User: Retail, Healthcare, Logistics, Manufacturing Technology: Frequency Modulation, Phase Modulation, Amplitude Modulation, Digital Processing |
| Companies Covered | Alien Technology, HID Global, Zebra Technologies, GAO RFID, NXP Semiconductors, Impinj, Honeywell, Omni-ID, Avery Dennison, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US RFID Tags Market Evolving Landscape
Chipless RFID architectures and sensor-integrated tags are compressing unit economics while expanding functional scope beyond identification into environmental monitoring and condition sensing. These developments are redrawing competitive boundaries between component suppliers and system integrators.
Sensor-embedded passive tags is automating cold-chain compliance documentation by capturing temperature excursion data without battery dependence. Pharmaceutical distributors operating FDA-regulated logistics networks are piloting these devices for lane-level shipment monitoring. The technology is automating audit trail generation, reducing manual probe-reading labor and eliminating documentation gaps that trigger regulatory citations.
OSHA workplace safety standards for industrial RFID installations are mandating electromagnetic exposure assessments and equipment certification for forklift-mounted readers. Warehouse operators in California and Texas logistics hubs are engaging third-party testing laboratories to validate compliance before deployment. Food and beverage distribution centers face the tightest compliance timelines as unionized workforces drive safety scrutiny.
Retailer-mandated source-tagging programs are consolidating supplier qualification around a shrinking pool of approved tag converters. Apparel manufacturers serving multiple US retail banners must maintain parallel inventory streams with distinct encoding formats and adhesive specifications. Vendor-managed inventory arrangements are shifting tag procurement responsibility upstream, compressing margins for brand owners while expanding volume commitments for qualified inlay suppliers.
US RFID Tags Market Segmentation
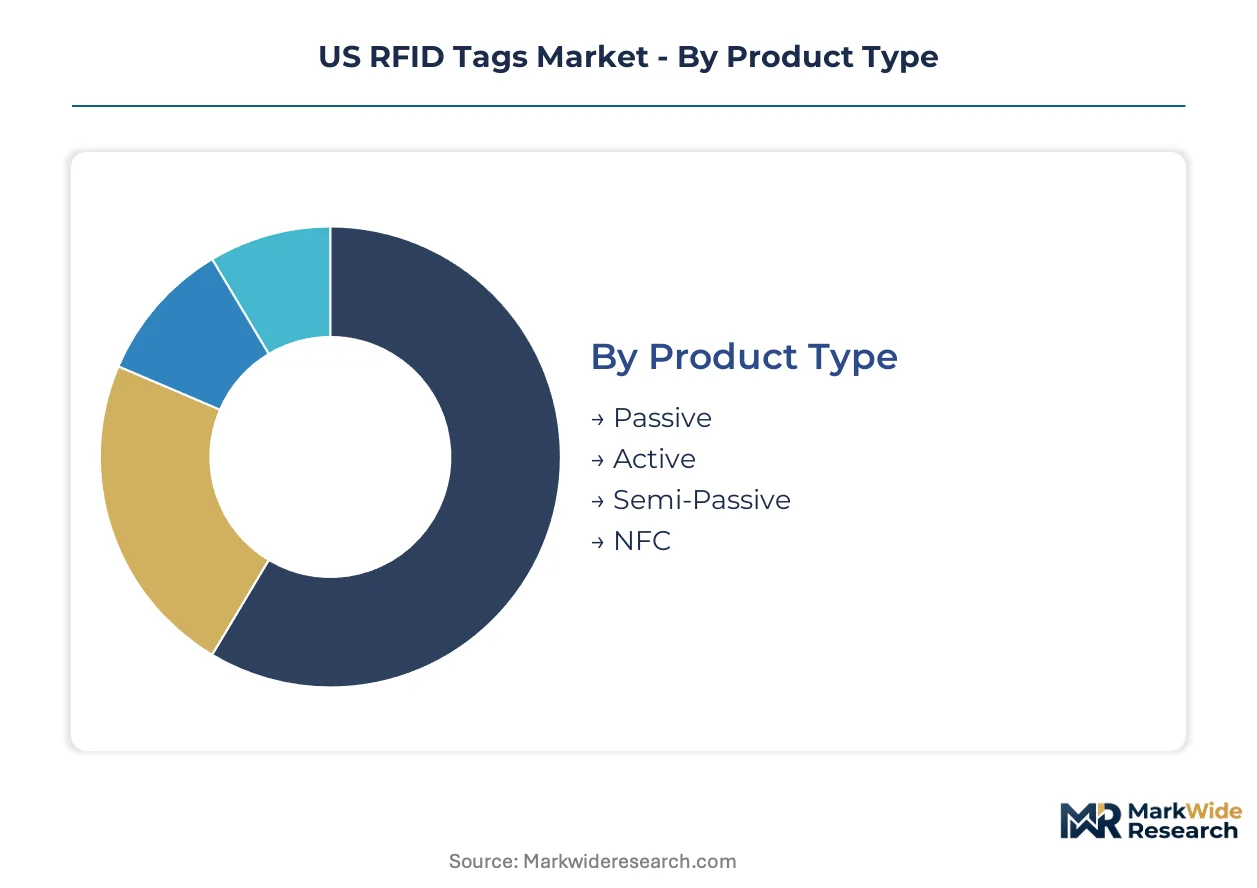
US RFID tag procurement splits sharply between commodity passive volumes and engineered active systems, with frequency architecture and integration depth determining supplier margins. Segmentation reveals where standardization yields scale economies versus where customization commands premium pricing.
Product Type:
Customization intensity varies from fully standardized passive inlays to engineered active systems with bespoke power management and sensor integration.
- Passive:Backscatter-powered tags harvest interrogator energy through UHF, HF, or LF antenna coupling, enabling sub-dollar unit economics. Retail source-tagging mandates across Walmart and Target networks concentrate demand in apparel and general merchandise supply chains, where billion-unit scale justifies dedicated inlay converting capacity.
- Active:Battery-powered transmitters achieve 100-meter read ranges with onboard temperature, shock, and humidity logging. Cold-chain pharmaceutical distribution through Texas and California logistics hubs is driving adoption for FDA-regulated biologics transport where excursion documentation is mandatory.
- Semi-Passive:Hybrid architectures combine passive communication with battery-assisted sensor operation for extended environmental monitoring.
- NFC:13.56 MHz proximity tags enable tap-to-authenticate workflows in corporate access control and transit payment infrastructure.
Most installed capacity flows through Passive tags. Expansion is steepest in Active tags.
Application:
Volume concentration versus solution complexity defines procurement patterns across use cases, with inventory velocity applications dominating unit shipments.
- Inventory Management:Source-tagged UHF labels enable real-time stock visibility from factory floor to store shelf. Major US retailers mandate EPC Gen2 encoding at manufacturing origin, eliminating distribution-center bottlenecks and accelerating replenishment cycles for seasonal apparel and consumer electronics.
- Supply Chain:Serialized unit-level tagging satisfies pharmaceutical pedigree laws in California and Florida, exceeding federal serialization baselines. Lane-level shipment tracking through Dallas-Fort Worth and Inland Empire corridors is expanding tag density in high-value drug distribution.
- Asset Tracking:Hospital equipment location systems leverage UHF and BLE hybrid tags for real-time bed, pump, and wheelchair positioning.
- Access Control:NFC-enabled employee badges and visitor credentials displace magnetic stripe infrastructure in corporate and healthcare campuses.
Inventory Management absorbs the majority of annual tag volumes. Supply Chain applications are gaining share fastest.
End User:
Regulatory mandate intensity and integration sophistication separate end-user segments, with healthcare compliance requirements driving specification escalation.
- Retail:Apparel and general merchandise networks mandate supplier-encoded UHF tags, consolidating procurement around approved converter pools. Vendor-managed inventory arrangements shift tag cost responsibility upstream to brand owners while locking in volume commitments for qualified inlay suppliers.
- Healthcare:FDA Unique Device Identification rules compel Class II and III medical device manufacturers to integrate serialized tags at unit level. Hospital asset tracking systems from Zebra Technologies and Impinj anchor enterprise-grade deployments for pump and bed location services.
- Logistics:Third-party cold-chain operators pilot sensor-embedded passive tags for automated temperature excursion documentation.
- Manufacturing:Work-in-process tracking and tool management applications leverage ruggedized UHF tags for metallic and high-temperature environments.
Retail channels dominate absolute tag consumption. Healthcare is climbing the fastest as UDI deadlines compress deployment timelines.
Technology:
Signal processing architecture determines read reliability in dense RF environments and metallic interference conditions.
- Frequency Modulation:UHF backscatter systems modulate carrier frequency for EPC Gen2 compliance, achieving 10-meter read ranges in warehouse gateway configurations. Dense multipath environments in California and Texas distribution centers favor FM architectures for collision avoidance and tag singulation.
- Phase Modulation:Advanced encoding schemes improve read accuracy in liquid and metal-proximity applications where signal phase distortion is critical.
- Amplitude Modulation:Legacy HF 13.56 MHz systems retain dominance in payment and access control where near-field coupling is sufficient.
- Digital Processing:Software-defined radio architectures enable multi-protocol readers and adaptive anti-collision algorithms.
Frequency Modulation carries the bulk of industrial UHF installations. Digital Processing is expanding most quickly as reader intelligence requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RFID engineering talent clusters along three distinct US corridors, with antenna design expertise concentrating near defense and telecommunications legacy bases. State-level pharmaceutical regulations and retailer headquarters location drive deployment density.
California
Pharmaceutical distributors in the Inland Empire corridor deploy serialized UHF tags to satisfy state pedigree laws exceeding federal baselines. FDA-regulated cold-chain operators pilot sensor-embedded passive tags for automated temperature documentation. Los Angeles and Long Beach port complexes anchor West Coast RFID infrastructure for apparel imports subject to retailer source-tagging mandates.
Texas
Dallas-Fort Worth distribution hub expansion generates demand for active RFID tags with temperature-logging capabilities in biologics transport. OSHA workplace safety standards for forklift-mounted readers prompt third-party electromagnetic exposure assessments. Houston's petrochemical corridor applies ruggedized UHF tags for metallic-environment asset tracking.
Illinois
Chicago's consolidated rail and intermodal terminals deploy gateway RFID systems for cross-dock inventory velocity. FCC Part 15 power constraints force redundant reader infrastructure in dense warehouse environments. Midwest manufacturing networks source EPC Gen2-encoded tags for work-in-process tracking across automotive supplier parks.
Georgia
Savannah port modernization integrates RFID-enabled container tracking with customs automation systems. Retail distribution centers near Atlanta mandate supplier-encoded tags for seasonal apparel replenishment. State logistics incentives attract pharmaceutical cold-chain operators expanding from Florida pedigree-law markets.
Pennsylvania
Philadelphia pharmaceutical manufacturing corridors integrate FDA UDI-compliant tags at unit level for Class II device serialization. Pittsburgh's robotics and automation cluster supplies reader hardware for industrial asset tracking deployments. Northeast corridor freight rail operators test passive tag systems for intermodal chassis management.
US RFID Tags Market Competitive Landscape
The competitive structure tilts toward component specialists controlling critical chokepoints in chip and inlay supply. Tier-one enterprise integrators compete with mid-tier converters on qualification speed and retailer approval status. Two strategic archetypes dominate: RAIN RFID chipset designers and adhesive-integrated inlay manufacturers. Capacity expansion and retailer qualification partnerships represent the dominant competitive moves.
Among US-based technology developers, Impinj, Zebra Technologies, and Alien Technology exemplify divergent positioning within the ecosystem. Impinj anchors the semiconductor layer with RAIN RFID chipsets. Zebra Technologies occupies the enterprise systems tier with hospital asset tracking infrastructure. Alien Technology represents the legacy inlay conversion segment with established retail qualification credentials. Each sits within a distinct value-capture position rather than competing directly.
| Leading Market Players |
|---|
| Alien Technology |
| HID Global |
| Zebra Technologies |
| GAO RFID |
| NXP Semiconductors |
| Impinj |
| Honeywell |
| Omni-ID |
| Avery Dennison |
| Others |
Value Network & Pricing Analysis
RFID antenna design engineers concentrate in California's defense-telecom corridor and Texas semiconductor hubs, creating labor-cost differentials that widen spreads between premium custom-engineered tags and commodity passive inlays.
Pricing Analysis
Bundled encoding-and-conversion services command premiums over unbundled raw inlay supply. Three-tier pricing structure across FDA-validated, retailer-qualified, and generic unbranded levels separates healthcare compliance-grade tags from apparel source-tagging volumes. Cost compression in passive UHF inlays is intensifying because retailer-mandated encoding specifications eliminate distribution-center value-add steps. Small medical device manufacturers show highest price sensitivity as UDI compliance deadlines force unbudgeted tag integration investments.
Supply Chain Analysis
Warehouse-distribution layer consolidation in Dallas-Fort Worth and Inland Empire corridors shapes downstream fulfillment economics for tagged pharmaceutical shipments. RAIN RFID chip fabrication draws from Taiwan, South Korea, and USA foundry sources. Adhesive substrate supply rests on petrochemical feedstocks and specialty paper pulp. Single-source vulnerability in silicon wafer allocation exposes tag converters to input rationing during demand spikes. Distribution runs through qualified converter networks holding active retailer approval status.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US RFID Tags Market represents a late-cycle quality story as FDA UDI mandates and retailer source-tagging programs shift procurement specifications toward traceability-validated premium tiers.
For Market Incumbents: Cement retailer qualification status through dedicated converting capacity commitments in Texas and California logistics corridors. Deepen backward integration into antenna design talent pools near defense-telecom legacy bases to defend against specialized engineering consultancies entering tag optimization services.
For New Entrants and Emerging Players: Begin with sensor-embedded passive tag development for pharmaceutical cold-chain documentation, the most penetrable white-space segment before FDA guidance finalizes encryption specifications. Pursue third-party laboratory partnerships for OSHA electromagnetic exposure certification to unlock forklift-reader integration contracts.
For Investors and Strategic Acquirers: Enterprise healthcare systems are the most active acquirer in this space, consolidating hospital asset-tracking infrastructure around integrated hardware-software platforms. Acquisition targets should display active FDA 510(k) submission support capabilities and existing GPO contract relationships. Watch FDA draft guidance publication timing on RFID-enabled drug authentication as the signal for encryption-capable tag demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Retailer Qualification Partnership | Locks in volume commitments from apparel suppliers serving Walmart and Target networks. |
| Sensor-Integrated Tag Development | Captures pharmaceutical cold-chain compliance documentation automation demand. |
| OSHA Certification Investment | Unlocks forklift-mounted reader installation contracts in unionized distribution centers. |
| Antenna Design Talent Acquisition | Secures scarce RF engineering expertise concentrated near defense legacy bases. |
| Backward Integration into Chip Sourcing | Reduces exposure to Taiwan and South Korea foundry allocation constraints. |
Research Methodology
Multiple input streams — executive interviews with RFID converter operations managers, primary discussions with hospital biomedical engineering directors, and secondary validation against FCC equipment authorization databases — were reconciled through bottom-up shipment modeling and top-down market sizing triangulation. Stakeholder roles engaged included pharmaceutical distribution logistics officers, retail category sourcing managers, and industrial safety compliance consultants. Secondary sources encompassed FDA UDI implementation guidance documents, EPC Gen2 protocol specifications, and OSHA electromagnetic field exposure standards.
Historical volume trajectories were cross-referenced against panel input from tag converter executives to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include product architecture (passive, active, semi-passive, NFC), frequency band deployment, application intensity (inventory velocity versus compliance documentation), and end-user regulatory mandate exposure. CAGRs were derived from segment-level unit economics and pricing trend synthesis. Industry-specific forecast inputs incorporated retailer source-tagging mandate rollout schedules and FDA UDI compliance phase deadlines.
Several conditions sit outside the modeled scope, including potential FCC spectrum reallocation decisions, breakthrough chipless RFID commercialization timelines, and tariff disruptions affecting adhesive substrate imports. Forecasts reflect documented assumptions about retailer mandate adherence rates and foundry capacity expansion plans. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Z-Wave Products Market
RF Components
Radio Frequency Components Market
RF Components
Multi-Mode Receiver Market
RF Components
Radio Frequency Integrated Circuit (RFIC) Market
RF Components
Radio Frequency Counter Market
RF Components
RF Tunable Filters Market
RF Components
RF Duplexer Market
RF Components
Americas Small Signal Transistor Market
RF Components
Europe Small Signal Transistor Market
RF Components
RF Microwave MLCC Market
RF Components
RF Switches Market
RF Components
Gaas RF Switch Market
RF Components
RF Acoustic Wave Filters Market
RF Components
High Power RF Amplifier Module Market
RF Components
RF Spectrum Analyzer Market
RF Components
SMD Resonator Market