
 Interconnects and Passive Components Market | 2026-2036
Interconnects and Passive Components Market Size, Share, and Industry Trends Forecast 2026-2036
Interconnects and Passive Components Market Intelligence
Automotive-grade AEC-Q200 qualification is rotating demand toward temperature-hardened passive components and vibration-resistant interconnects. TE Connectivity leverages vertical integration across sensor-to-connector architectures to anchor high-reliability supply chains. Murata Manufacturing dominates ceramic capacitor output through in-house material science and dielectric formulation expertise. Vishay Intertechnology specializes in broad-spectrum resistor and inductor portfolios that sustain margin pools across industrial and automotive end users.
Interconnects and passive components encompass electrically passive elements—capacitors, resistors, inductors, connectors, filters, and transformers—that store, filter, or transfer energy without signal amplification, typically specified by parameters such as capacitance tolerance, insertion loss, and operating temperature ranges from minus 55 to 150 degrees Celsius. These components serve as the foundational infrastructure in electronic systems, enabling signal integrity, power distribution, and electromagnetic compatibility across circuit boards and subassemblies. Connectors and capacitors together command the largest value share, with connectors benefiting from high-speed data transmission requirements and multilayer ceramic capacitors capturing expanding slot counts in electric vehicle inverters and 5G base station power amplifiers. Surface mount technology leads unit volume due to miniaturization trends, while wirewound and thin film resistor categories retain pricing power in precision instrumentation and aerospace applications.
REACH and RoHS frameworks in Europe restrict hazardous substances in electrical components, compelling reformulation of plating chemistries and substrate materials. The EPA and FAA in the United States impose flammability and reliability standards that govern connector selection in avionics and defense procurement channels. Stakeholders must monitor evolving material compliance deadlines and qualification protocols to secure long-term supply positions without disrupting existing manufacturing footprints.
Market Dynamics
Automotive electrification is forcing rapid recalibration of component specifications, as electric vehicle inverters demand ceramic capacitors rated for 150°C continuous operation and vibration-resistant interconnects that legacy designs cannot satisfy.
Growth Catalysts
- RoHS Compliance Mandates:European ECHA deadlines for lead-free solder systems are accelerating substrate reformulation across connector manufacturers, expanding addressable markets for halogen-free laminates.
- 5G Infrastructure Deployment:Base station power amplifiers require multilayer ceramic capacitors with ultra-low equivalent series resistance, pulling capacity expansion from Japanese and Korean dielectric suppliers.
- China Domestic Production Policy:Beijing's import substitution targets for MLCCs and advanced interconnects are redirecting capital toward local OEM qualification programs.
Market Restraints
- Palladium and Silver Price Volatility:Precious metal plating chemistries constitute 15-25% of connector material costs, exposing margins to London Metal Exchange fluctuations.
- Japanese Ceramic Powder Concentration:Three suppliers control 70% of high-purity barium titanate feedstock, creating single-source vulnerability for AEC-Q200 capacitor production.
- Thermal Cycling Limitations:Standard epoxy-based substrates crack under thermal shock beyond 500 cycles, constraining adoption in aerospace engine control modules.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor packaging are creating captive demand for precision resistors and inductors in Gujarat and Tamil Nadu clusters.
- Copper-Nickel-Tin Alloy Substitution:Beryllium copper elimination in high-reliability connectors opens formulation patents for spinodal-hardened alternatives.
- SAMR Green Certification:China's dual carbon goals are mandating recycled content thresholds in passive components, rewarding early compliance with state procurement preference.
Industry Challenges
- AEC-Q200 Qualification Timelines:1,000-hour high-temperature operational life testing extends new product introduction cycles to 18-24 months, freezing design wins.
- Legacy System Integration:Through-hole connector footprints persist in industrial automation, forcing hybrid surface-mount solutions that increase assembly complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interconnects and Passive Components Market |
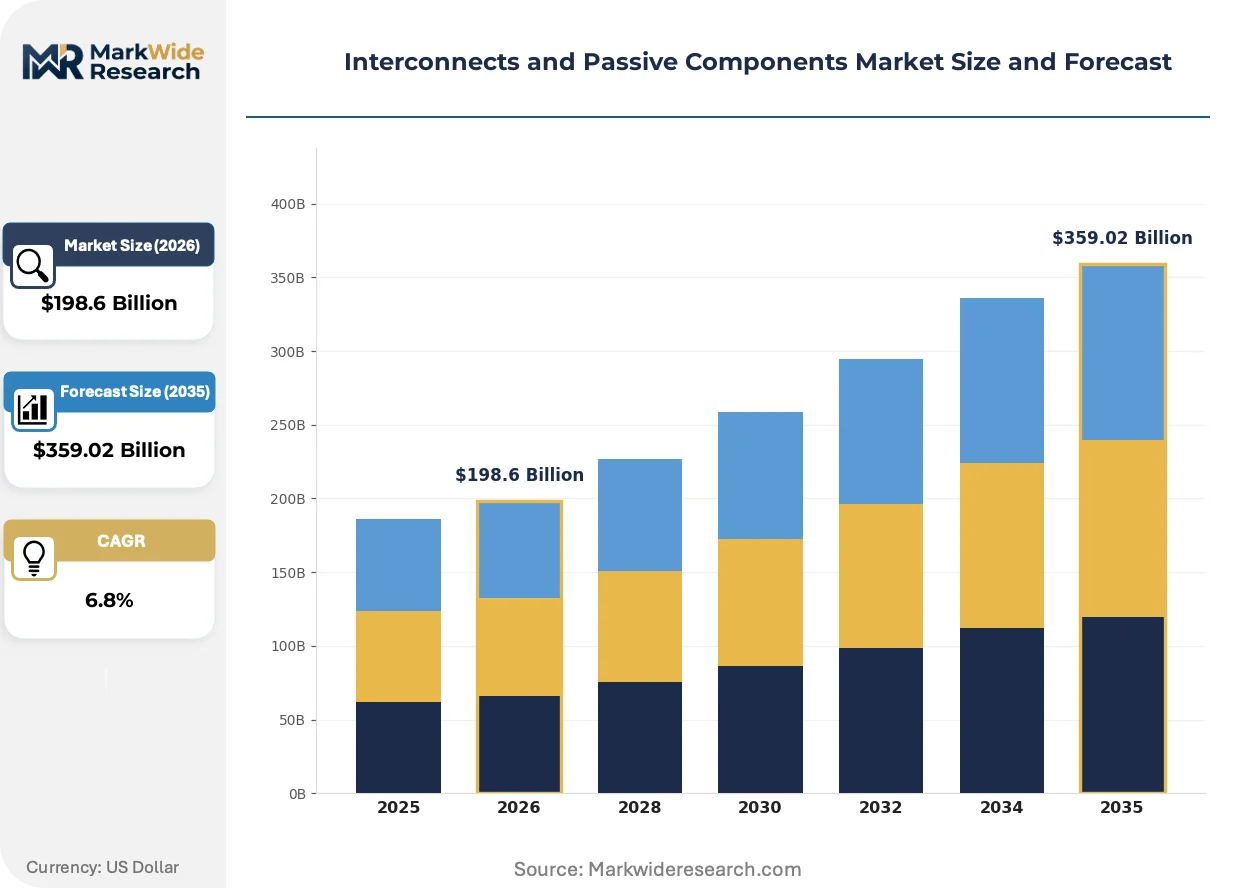
| Market Size in 2026 | $198.6 Billion |
| Market Size in 2035 | $359.02 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitors, Resistors, Inductors, Connectors, Filters, Transformers Technology: Surface Mount, Through Hole, Wirewound, Thin Film, Thick Film, Chip Application: Consumer Electronics, Telecommunications, Aerospace Systems, Defense Equipment, Semiconductor Manufacturing, Renewable Energy Systems End User: OEMs, Aftermarket Suppliers, Electronic Contract Manufacturers, Equipment Integrators |
| Companies Covered | TE Connectivity, Amphenol Corporation, Molex Incorporated, Murata Manufacturing Co., Ltd., TDK Corporation, Hirose Electric Co., Ltd., Panasonic Corporation, Vishay Intertechnology, Inc., YAGEO Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interconnects and Passive Components Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory chemistry bans are actively restructuring how passive components are specified, manufactured, and qualified across end-use verticals.
Silicon carbide power modules are decomposing traditional aluminum electrolytic capacitor hierarchies in electric vehicle onboard chargers. Tier 1 automotive suppliers are qualifying 800V-rated MLCC banks with nanocrystalline dielectrics that withstand 10,000-hour load life tests. This technology compression is collapsing the voltage-grade segmentation that historically separated automotive from industrial capacitor portfolios.
REACH Annex XVII restrictions on nickel release are compelling connector manufacturers to migrate from sulfamate nickel to electroless palladium-nickel plating architectures. German KBA type-approval protocols now require documentation of plating thickness uniformity across 10,000-unit production lots. Automotive harness suppliers in Stuttgart and Wolfsburg are absorbing qualification costs that smaller industrial connector vendors cannot shoulder.
Consolidated vendor-managed inventory programs are displacing spot-market purchasing for MLCCs among contract electronics manufacturers. Foxconn and Jabil are mandating 26-week demand signals with price lock provisions, transferring inventory carrying costs upstream to Murata and TDK distribution arms. This contractual shift is most pronounced in Taiwanese and Vietnamese assembly facilities serving North American networking equipment brands.
Interconnects and Passive Components Market Segmentation
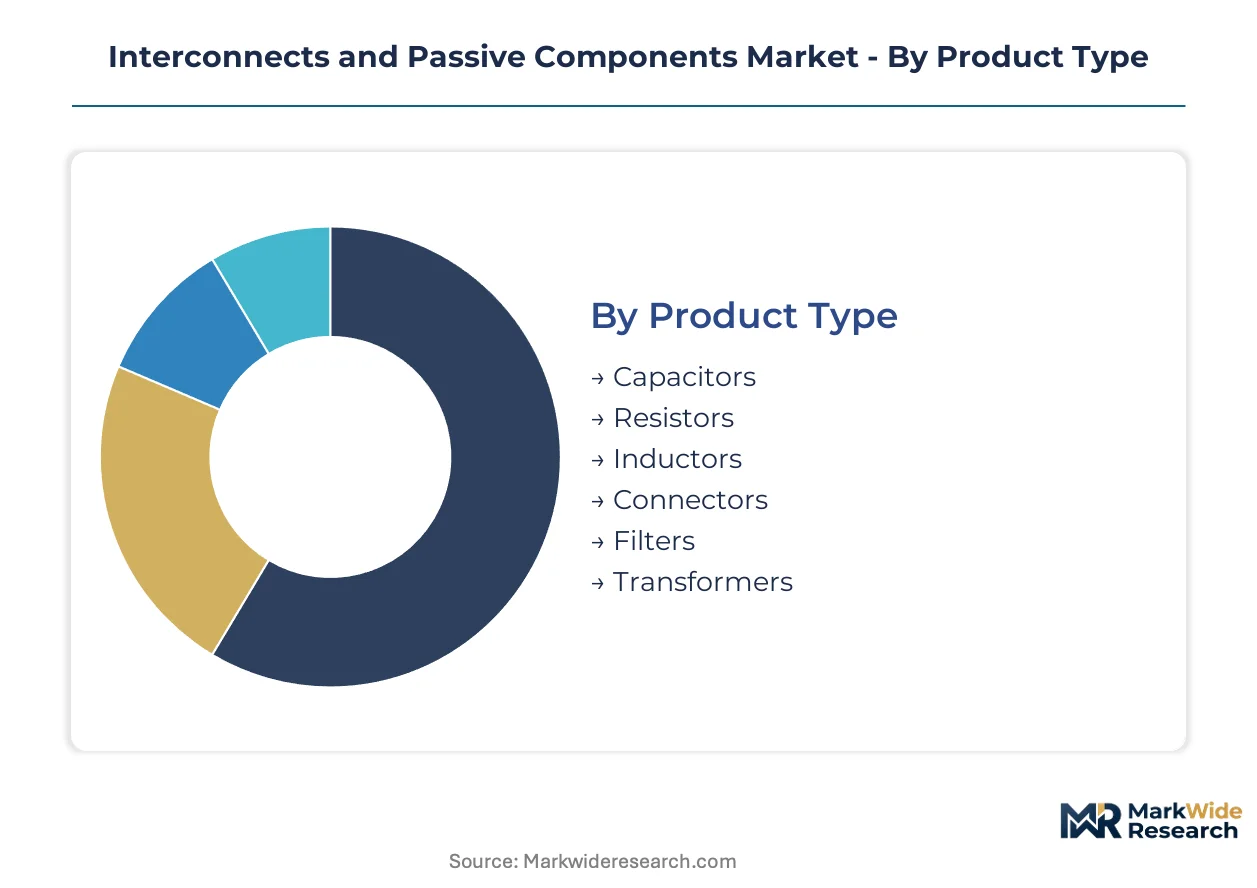
Component specification hierarchies in interconnects and passive components fragment across mounting technologies, dielectric formulations, and thermal performance grades. Procurement teams segment supplier qualifications by AEC-Q200 automotive ratings versus commercial-grade tolerances, creating parallel sourcing channels that resist consolidation.
Product Type:
Substitution pressure from silicon carbide power modules is collapsing traditional voltage-grade boundaries between capacitor categories, forcing dielectric reformulation across multiple segments.
- Capacitors:Multilayer ceramic constructions with barium titanate dielectrics dominate electric vehicle inverter banks. Beijing's import substitution targets are pulling capacity expansion toward domestic Chinese suppliers serving local OEMs.
- Connectors:High-speed data transmission architectures require controlled impedance specifications and vibration-resistant locking mechanisms. TE Connectivity anchors supply chains through sensor-to-connector vertical integration across Stuttgart and Wolfsburg automotive clusters.
- Resistors:Thin film and wirewound constructions sustain precision instrumentation demand.
- Inductors:Ferrite core and air core variants filter switching noise in power supplies.
- Filters:EMI suppression components shield sensitive analog circuits from digital switching harmonics.
- Transformers:Isolation and impedance matching units condition power delivery in grid-tied inverters.
Connectors retain volume leadership across assembly-intensive electronics; capacitors hold the steepest expansion curve from electrification demand.
Technology:
Cost tier stratification separates precision thin film deposition from commodity thick film screening, with wirewound constructions occupying the premium thermal endurance niche.
- Surface Mount:Miniaturized packages enable high-density PCB assembly for consumer electronics and telecommunications infrastructure. Foxconn and Jabil mandate 26-week demand signals with price lock provisions, transferring inventory carrying costs upstream to Japanese and Korean dielectric suppliers.
- Thin Film:Sputtered metal layers achieve sub-1% tolerance for aerospace guidance systems and medical instrumentation. Vishay Intertechnology specializes in broad-spectrum portfolios that sustain margin pools across industrial and automotive end users.
- Through Hole:Mechanical stability suits high-vibration industrial automation environments.
- Wirewound:Ceramic or fiberglass cores dissipate heat in power resistor applications.
- Thick Film:Screen-printed resistive inks balance cost and performance for general-purpose circuits.
- Chip:Bare die formats integrate into multichip modules and system-in-package assemblies.
Surface mount commands unit volume dominance; thin film delivers the highest value-per-unit trajectory.
Application:
Customer type concentration varies sharply, with semiconductor manufacturing equipment demanding qualification documentation that consumer electronics assemblers rarely require.
- Consumer Electronics:Smartphones and wearables drive miniaturization toward 0201 and 01005 chip sizes. Murata Manufacturing dominates ceramic capacitor output through in-house material science and dielectric formulation expertise.
- Telecommunications:5G base station power amplifiers require multilayer ceramic capacitors with ultra-low equivalent series resistance. Korean and Japanese suppliers are expanding capacity to meet base station deployment timelines.
- Aerospace Systems:FAA flammability standards govern connector selection in avionics procurement channels.
- Defense Equipment:ITAR and DFARS compliance constraints limit supplier pools to domestic-qualified manufacturers.
- Semiconductor Manufacturing:Vacuum-compatible passive components withstand process chamber environments.
- Renewable Energy Systems:Grid-tied inverters demand film capacitors rated for 100,000-hour operational life.
Consumer electronics anchors shipment volume; telecommunications infrastructure is climbing the fastest on 5G deployment cycles.
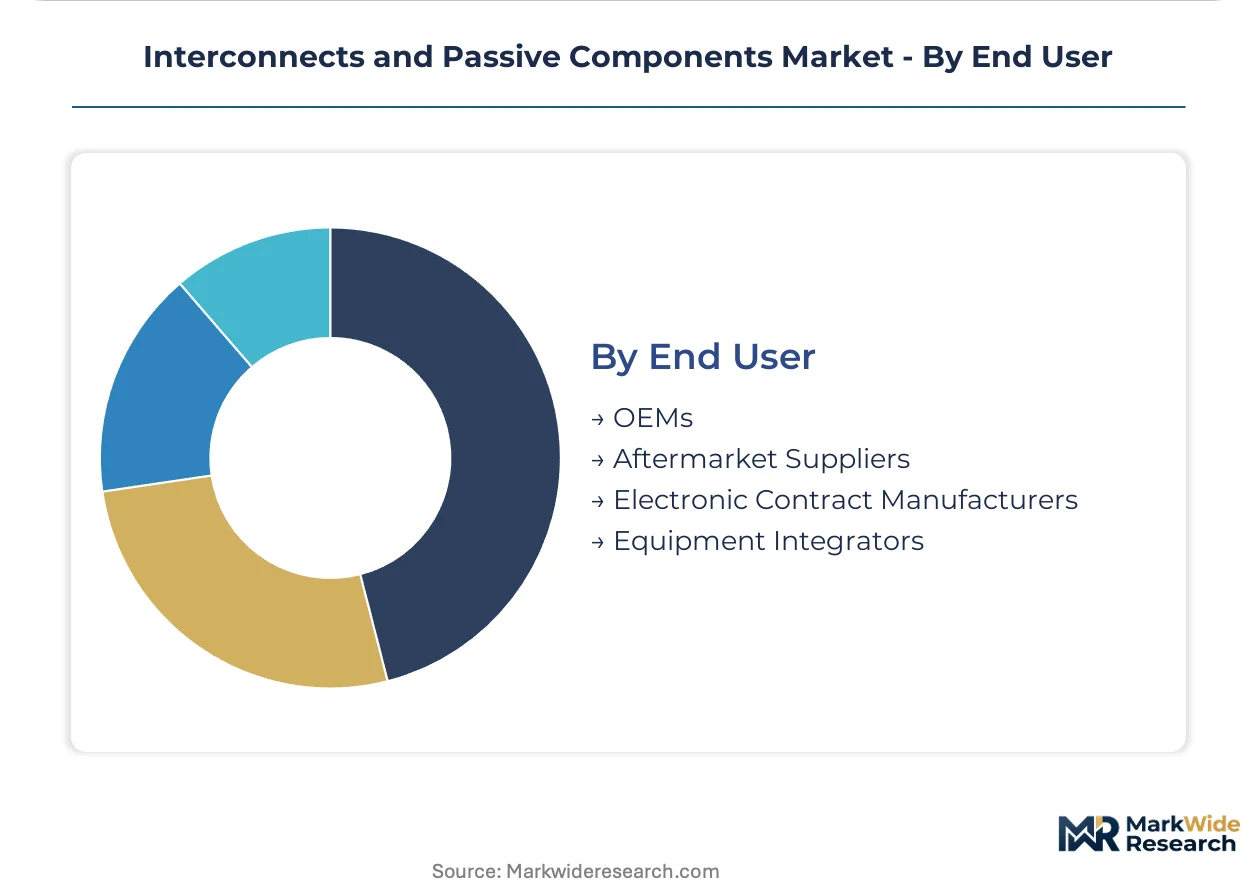
End User:
Supply concentration among Japanese ceramic powder suppliers creates single-source vulnerability that OEMs mitigate through vendor-managed inventory programs.
- OEMs:Original equipment manufacturers specify AEC-Q200 qualified components for automotive platforms. German KBA type-approval protocols now require documentation of plating thickness uniformity across 10,000-unit production lots.
- Electronic Contract Manufacturers:Foxconn and Jabil consolidate purchasing power through consolidated vendor-managed inventory programs that displace spot-market purchasing for MLCCs.
- Aftermarket Suppliers:Repair and replacement channels source cross-reference equivalents to original specifications.
- Equipment Integrators:Subsystem assemblers specify interconnect bundles for industrial automation and test equipment.
Electronic contract manufacturers drive procurement volume consolidation; OEMs hold the steepest specification escalation curve from electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan exhibit the least price elasticity for AEC-Q200 qualified components, while contract manufacturers in Vietnam and Mexico drive hard volume negotiations on standard-grade passives.
United States
FAA flammability standards and NHTSA automotive safety mandates sustain premium demand for avionics-grade connectors and temperature-hardened capacitors. The EPA imposes reliability benchmarks that govern connector selection in defense procurement channels. Aerospace clusters in Southern California and Greater Seattle concentrate qualification testing for mission-critical interconnect systems.
Germany
Automotive harness suppliers in Stuttgart and Wolfsburg absorb qualification costs for electroless palladium-nickel plating architectures that KBA type-approval protocols now mandate. REACH Annex XVII restrictions on nickel release are compelling substrate reformulation across connector manufacturers. The country's industrial automation corridor anchors demand for vibration-resistant locking mechanisms in precision instrumentation.
China
Beijing's import substitution targets for MLCCs and advanced interconnects are redirecting capital toward local OEM qualification programs. SAMR green certification mandates recycled content thresholds that reward early compliance with state procurement preference. Yangtze River Delta production clusters are expanding dielectric capacity to serve domestic electric vehicle inverter banks.
Japan
METI industrial policy supports high-purity barium titanate feedstock production that three suppliers control for AEC-Q200 capacitor manufacturing. JIS standards govern precision tolerances for thin film resistors in aerospace guidance applications. Kansai and Chubu regions concentrate material science expertise for nanocrystalline dielectric formulations.
India
PLI scheme incentives for semiconductor packaging are creating captive demand for precision resistors and inductors in Gujarat and Tamil Nadu clusters. BIS certification requirements are tightening for passive components in telecommunications infrastructure. Electronics manufacturing hubs in Karnataka and Telangana are absorbing vendor-managed inventory programs from contract assemblers.
Interconnects and Passive Components Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with Japanese and Korean suppliers dominating dielectric formulation while Taiwanese and Chinese fabricators compete on scale economics. The market structures around three tiers: integrated material-to-component specialists, pure-play connector architects, and broad-spectrum passive portfolios. Consolidation pressure concentrates among ceramic powder suppliers, while connector segments fragment across application-specific niches. Capacity expansion and strategic partnerships represent the dominant competitive moves as electrification timelines compress qualification windows.
Within the integrated specialist tier, Murata Manufacturing and TDK Corporation exemplify material science depth that captive dielectric production confers. Vishay Intertechnology occupies a position across broad-spectrum resistor and inductor portfolios that sustain margin pools through industrial and automotive diversification. TE Connectivity anchors high-reliability supply chains through sensor-to-connector architectural control across Stuttgart and Wolfsburg automotive clusters.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol Corporation |
| Molex Incorporated |
| Murata Manufacturing Co., Ltd. |
| TDK Corporation |
| Hirose Electric Co., Ltd. |
| Panasonic Corporation |
| Vishay Intertechnology, Inc. |
| YAGEO Group |
| Others |
Cost & Logistics Intelligence
Dielectric capacity utilization rates above 85 percent in Japanese and Korean ceramic powder facilities create scale-driven cost floors that smaller Chinese entrants struggle to match. This concentration simultaneously anchors premium pricing for AEC-Q200 qualified components and compresses margins in commercial-grade segments where spot-market purchasing still dominates.
Pricing Analysis
REACH and RoHS compliance mandates dictate the pricing tier structure across European connector procurement, separating halogen-free laminate premiums from standard substrate offerings. Certification grade and volume scale drive price differentiation, with automotive OEMs absorbing 20-40 percent premiums for KBA type-approved plating architectures while contract manufacturers in Vietnam negotiate hard on standard-grade passives. Cost compression in commercial MLCC tiers is intensifying because Foxconn and Jabil have consolidated vendor-managed inventory programs with 26-week demand signals. Electronic contract manufacturers exhibit the highest price sensitivity, whereas German automotive harness suppliers show the least elasticity for qualified components.
Supply Chain Analysis
Just-in-time inventory strategies dominate consumer electronics assembly in Taiwan and Vietnam, while strategic stockpiling of barium titanate feedstock persists among Japanese capacitor manufacturers facing single-source vulnerability. Supply concentrates in Japan, South Korea, and China, with high-purity ceramic powder production drawing from concentrated mining operations in Australia and synthetic processing expertise in East Asia. Palladium and silver plating chemistries, plus epoxy-based substrate laminates, constitute critical input dependencies. Tariff exposure on Chinese-sourced components creates structural risk for North American networking equipment brands. Distribution runs through consolidated vendor-managed inventory programs that displace spot-market purchasing among tier-one contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
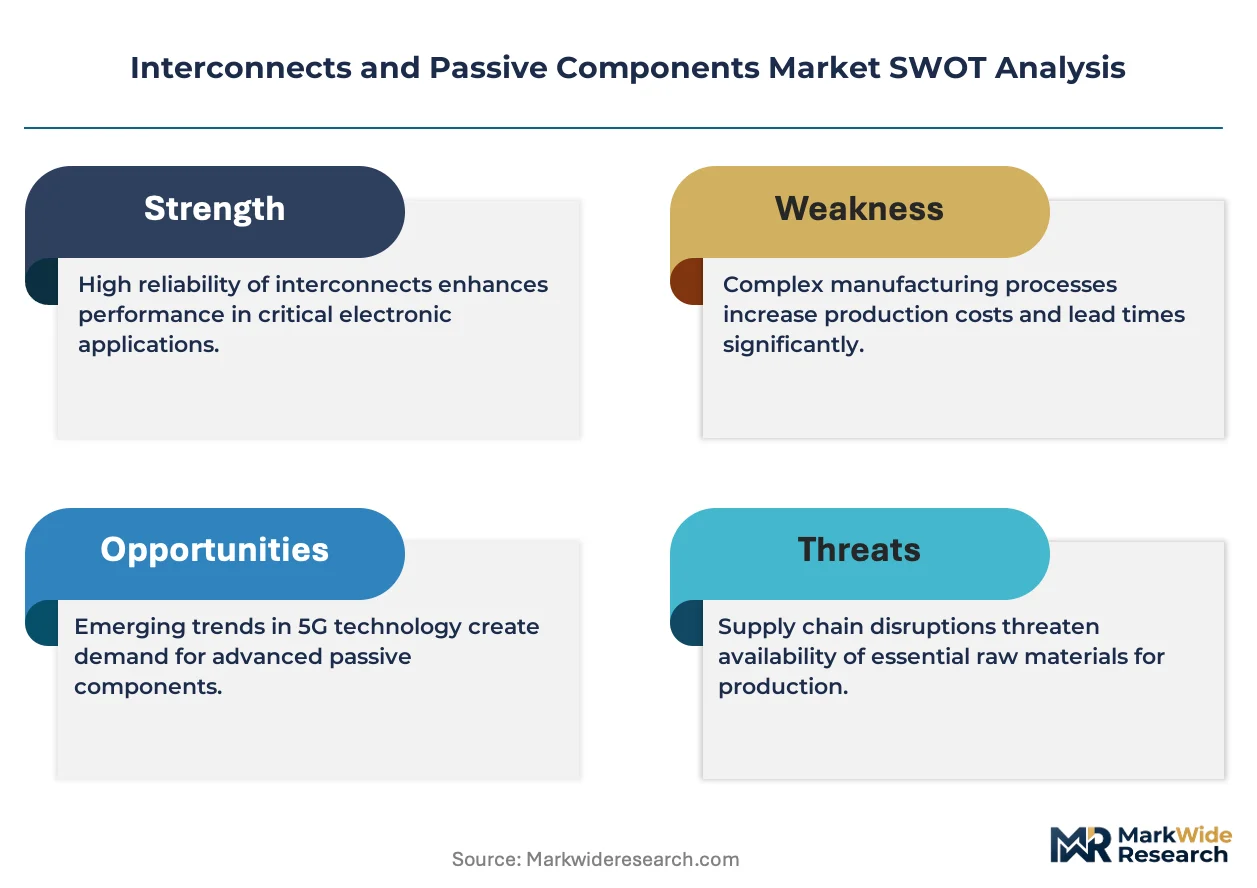
This market functions as a defensive-moat arena where regulatory entrenchment creates switching costs that freeze design wins for 18-24 month qualification cycles. Incumbents who capture AEC-Q200 certification early secure multi-year supply positions that resist price-based displacement.
For Market Incumbents: Secure captive supply of high-purity barium titanate feedstock through backward integration or long-term offtake agreements with Japanese ceramic powder suppliers. Deepen in-house production of nanocrystalline dielectric formulations to defend against emerging Chinese entrants benefiting from Beijing's import substitution subsidies. Capacity addition in Yangtze River Delta clusters represents the priority geographic lever for serving domestic Chinese electric vehicle OEMs. For New Entrants and Emerging Players: Aftermarket documentation gaps for plating thickness uniformity create service-layer white space where smaller vendors can capture repair-channel share without absorbing 10,000-unit KBA qualification costs. India's PLI scheme for semiconductor packaging offers the most penetrable geography, with Gujarat and Tamil Nadu clusters absorbing precision resistor and inductor demand that domestic suppliers currently underserve. A go-to-market angle anchored to SAMR green certification compliance unlocks state procurement preference in China's dual carbon procurement channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated material-to-component specialists with captive dielectric production and long-term vendor-managed inventory contracts with Foxconn or Jabil. Over a five-to-ten year horizon, acquisition targets should display backward integration into ceramic powder processing or electroless palladium-nickel plating architectures. The signal to watch is consolidation among the three Japanese barium titanate suppliers, which would reshape pricing power across AEC-Q200 capacitor tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder Processing | Murata and TDK anchor margin pools through captive barium titanate feedstock production in Kansai and Chubu regions. |
| AEC-Q200 Certification Investment | TE Connectivity leverages 1,000-hour high-temperature operational life testing to freeze design wins across Stuttgart and Wolfsburg automotive clusters. |
| Vendor-Managed Inventory Program Expansion | Foxconn and Jabil transfer inventory carrying costs upstream to Japanese and Korean dielectric suppliers through 26-week demand signals. |
| Halogen-Free Substrate Reformulation | REACH Annex XVII compliance opens premium pricing tiers for connector manufacturers serving German KBA type-approval protocols. |
| Copper-Nickel-Tin Alloy Substitution R&D | Spinodal-hardened alternatives to beryllium copper unlock formulation patents for high-reliability connector architectures. |
Research Approach
Initial hypotheses were tested against primary input from Tier 1 automotive supplier procurement officers, connector plating engineering leads, MLCC demand planners at contract manufacturers, and dielectric materials scientists, then refined through secondary validation against METI industrial policy filings, ECHA REACH substance restriction updates, KBA type-approval documentation databases, and SEC 10-K disclosures from listed component manufacturers. Bottom-up shipment data from Taiwanese and Vietnamese assembly facilities was triangulated against top-down electric vehicle inverter content-per-vehicle estimates.
Variance decomposition across product type, technology tier, application vertical, and end-user channel shaped the analytical framework over the projection horizon. Modeled segmentation captured mounting technology distinctions, dielectric formulation grades, thermal performance thresholds, and regional regulatory cluster effects. CAGRs were derived from installed base growth in electric vehicle power electronics and 5G base station deployment trajectories, with cross-referencing to silicon carbide power module adoption curves and automotive platform electrification timelines.
Forecasts assume regulatory continuity in REACH and RoHS frameworks, KBA type-approval protocols, and SAMR green certification mandates; material policy shifts would require re-modeling of substrate reformulation costs and qualification timeline assumptions. Revision becomes warranted when palladium and silver price volatility on the London Metal Exchange crosses thresholds that trigger connector manufacturer margin compression responses.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Global Thin and Thick Film Resistors Market
Passive And Interconnecting Electronic Components
Electrical Wiring Interconnection System (EWIS) Market
Passive And Interconnecting Electronic Components
Fuse Market
Passive And Interconnecting Electronic Components
Wirewound Variable Resistors Market
Passive And Interconnecting Electronic Components
Fiber Splice Closure Market
Passive And Interconnecting Electronic Components
Soft Ferrite Market
Passive And Interconnecting Electronic Components
Discrete Diodes Market
Passive And Interconnecting Electronic Components
Hybrid Capacitor Market
Passive And Interconnecting Electronic Components
United Kingdom MLCC Market
Passive And Interconnecting Electronic Components
Molded Interconnect Devices (MID) Market
Passive And Interconnecting Electronic Components
Ultra-Thin Electronic PI Film Market
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Global EMI Shielding Market
Passive And Interconnecting Electronic Components
High Density Interconnect Market
Passive And Interconnecting Electronic Components
Multilayer Ceramic Capacitor Market
Passive And Interconnecting Electronic Components
LAMEA Thermal Protector Market