
 Radio Frequency Front End Module Market | 2026-2036
Radio Frequency Front End Module Market Size, Share, and Industry Trends Forecast 2026-2036
Radio Frequency Front End Module Market Outlook
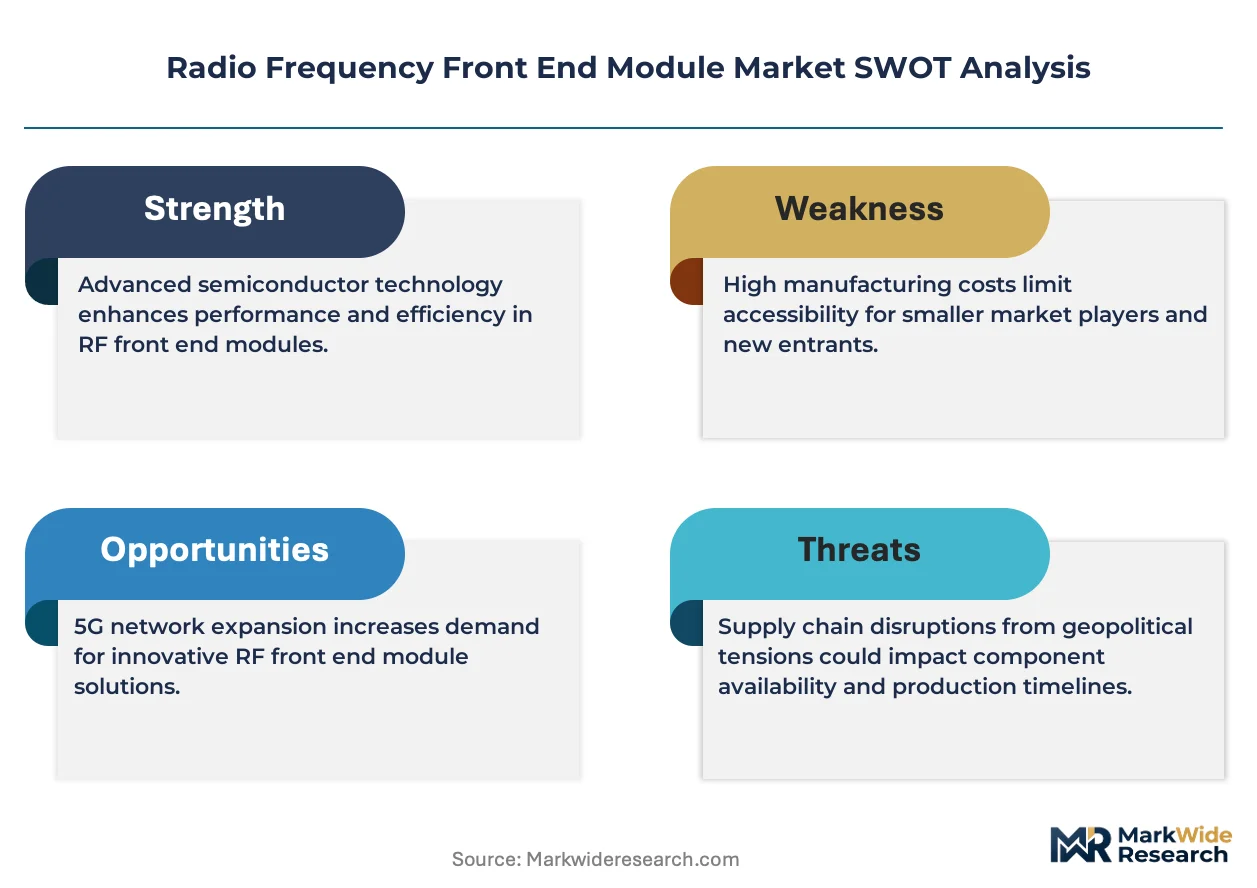
Asset-light foundry partnerships and fabless operating models are rewriting competitive economics in RF front-end supply. Murata Manufacturing leverages captive ceramic filter capacity to anchor premium sub-6 GHz portfolios. Qualcomm Technologies sustains design wins through modem-to-antenna integration that spans multiple foundry nodes.
A radio frequency front end module integrates power amplifiers, filters, switches, and low-noise amplifiers into a compact assembly managing signal conditioning between antennas and transceivers, typically operating from 600 MHz to 100 GHz depending on protocol. Its primary purpose is to ensure linearity, efficiency, and interference rejection across cellular, Wi-Fi, and Bluetooth links in congested spectrum environments. Amplifiers and filters capture the dominant share of component value as thermal management and insertion loss specifications tighten with 5G carrier aggregation. By technology dimension, 5G modules are outpacing LTE attach rates in telecommunications infrastructure while Wi-Fi front ends compete on cost in consumer electronics volumes.
FCC Part 27 rules on flexible-use spectrum, EU Radio Equipment Directive compliance mandates, and China's MIIT radio transmission type approval shape product certification timelines and geographic launch sequencing. These frameworks force modular architectures that can be regionally customized without full hardware redesigns. Stakeholders must monitor spectrum reallocation proceedings and antenna-in-package roadmaps to align R&D spending with operator deployment cadence.
Market Dynamics
Carrier aggregation complexity in 5G sub-6 GHz and mmWave bands is forcing module suppliers to consolidate discrete components into single-package solutions. Smartphone OEMs now demand turnkey RF front-end assemblies that eliminate board-level tuning, compressing the supplier base toward integrated platform providers.
Growth Catalysts
- 5G mmWave infrastructure buildout:Base station densification in China, South Korea, and the United States is pulling high-band module volumes. Tower operators require beamforming-capable front ends that integrate power amplifiers and phase shifters.
- FCC Part 27 flexible-use rules:Spectrum reallocation in the 3.5 GHz and 28 GHz bands is mandating new filter architectures. Module suppliers must certify region-specific variants for C-band and mmWave coexistence.
- Ceramic filter substitution:Surface acoustic wave devices are losing share to temperature-compensated bulk acoustic wave filters in premium smartphones. TC-BAW insertion loss specifications below 1 dB enable tighter carrier aggregation.
Market Restraints
- Gallium arsenide wafer supply concentration:Six-inch GaAs substrate production clusters in Taiwan and Japan create single-source vulnerability for power amplifier foundry access. Price volatility in epitaxial wafer contracts squeezes fabless module designers.
- EU Radio Equipment Directive electromagnetic compatibility testing:Harmonized standards for spurious emissions require iterative redesign cycles. Certification timelines extend 4-6 months for multi-band modules targeting European operator channels.
- Silicon-on-insulator switch displacement:SOI-based antenna tuning and switching solutions are commoditizing discrete RF switch margins. Module suppliers must absorb SOI integration or cede socket share to baseband-integrated alternatives.
Strategic Opportunities
- India PLI scheme for telecom equipment:Production-linked incentives for 5G base station manufacturing are attracting module assembly investments. Domestic value-add requirements favor local filter tuning and final test operations.
- Automotive V2X front-end integration:C-V2X and DSRC coexistence architectures in connected vehicles require automotive-qualified RF modules. Temperature-grade certifications open a premium pricing tier absent in consumer electronics.
- Wi-Fi 7 and 5G convergence in enterprise access points:Tri-band 6E/7 front ends that unify cellular and unlicensed spectrum conditioning reduce board space. Enterprise WLAN OEMs are consolidating RF procurement around converged module suppliers.
Industry Challenges
- Electromagnetic simulation talent scarcity:Finite-element modeling for antenna-in-package co-design requires rare combinations of RF physics and semiconductor packaging expertise. Foundry partnerships do not close the simulation-to-silicon correlation gap.
- Multi-node foundry qualification overhead:Modem-to-antenna integration strategies require simultaneous process development across GaAs, SOI, and CMOS nodes. Cross-node IP reuse is limited by incompatible design kits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radio Frequency Front End Module Market |
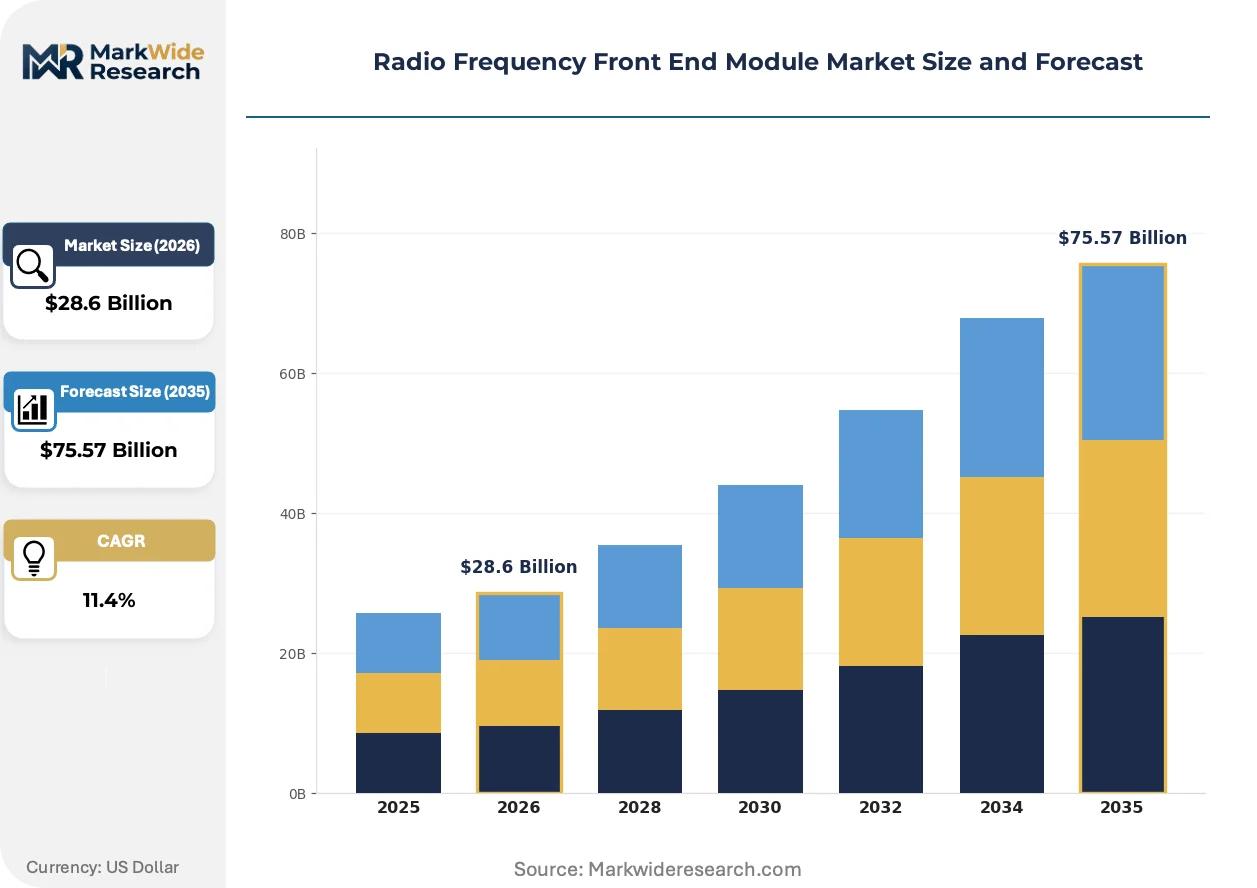
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Amplifiers, Filters, Antennas, Transceivers Technology: 5G, LTE, Wi-Fi, Bluetooth Application: Telecommunications, Consumer Electronics, Automotive, Aerospace End User: OEMs, Telecommunications Providers, System Integrators, Research Institutions |
| Companies Covered | Murata Manufacturing Co. Ltd, Infineon Technologies AG, Broadcom Inc, TDK Corp, NXP Semiconductors NV, Skyworks Solutions, Inc, Qualcomm Technologies, Inc, STMicroelectronics NV, Qorvo Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radio Frequency Front End Module Market Strategic Shifts
Digital pre-distortion and adaptive impedance matching are displacing fixed analog compensation networks. Module suppliers now embed machine learning inference engines that optimize linearity in real time.
Antenna-in-package technology is virtualizing traditional board-level RF routing. Qualcomm and MediaTek reference designs now specify AiP modules that integrate phased-array antennas with transceiver die. Smartphone OEMs adopting these platforms eliminate discrete antenna switch matrices and reduce board area by 30 percent. The shift is virtualizing the historical separation between semiconductor and passive component supply chains.
China MIIT radio transmission type approval timelines are compressing product launch windows. New certification categories for 5G-Advanced equipment require additional spurious emission testing in the 26 GHz band. Module suppliers targeting Chinese operator procurement must pre-validate designs against draft standards 6-9 months before formal publication. Premium smartphone launches in China now stagger 8-12 weeks behind other regions due to regulatory sequencing.
Smartphone OEM procurement is consolidating around platform-level RF front-end contracts. Apple and Samsung now negotiate multi-year supply agreements that bundle sub-6 GHz, mmWave, and Wi-Fi modules under single-source arrangements. This displaces the historical practice of discrete component sourcing across specialized filter, amplifier, and switch vendors. Korean and Chinese OEMs are replicating this model, squeezing mid-tier module suppliers without full-stack integration capabilities.
Radio Frequency Front End Module Market Segmentation
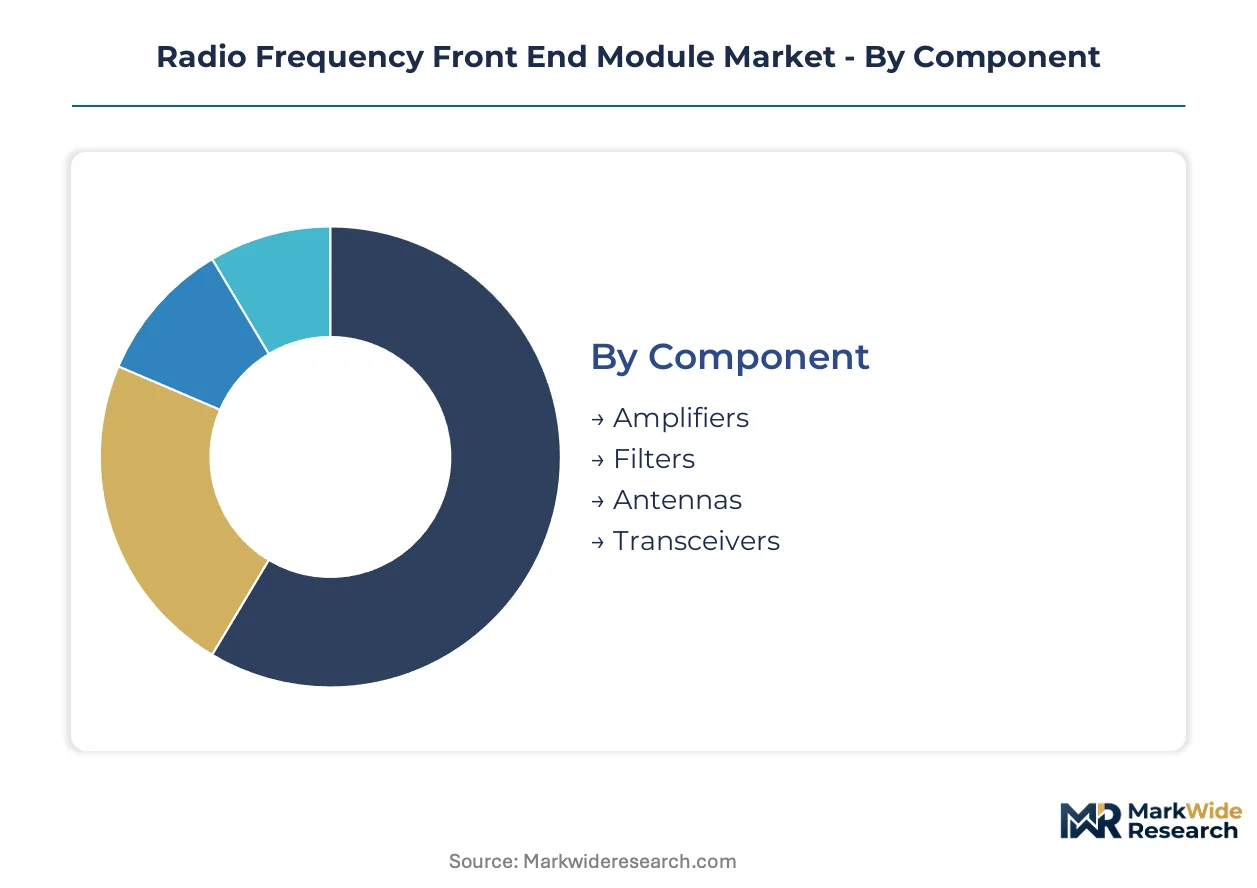
RF front-end module segmentation reflects competing pressures from carrier aggregation complexity, spectrum fragmentation, and end-use thermal requirements. Each dimension shapes procurement patterns and supplier qualification criteria differently.
Component:
Cost tier stratification separates high-value active components from commodity passive elements in module bill-of-materials.
- Amplifiers:Power amplifiers dominate thermal budgets and linearity specifications in 5G handsets. GaAs HBT devices from Taiwan and Japan supply premium sub-6 GHz sockets where efficiency exceeds 45 percent.
- Filters:TC-BAW and SAW devices manage carrier aggregation interference in congested spectrum. Ceramic filter capacity anchors Murata's premium portfolio as smartphone OEMs consolidate sourcing.
- Antennas:Phased-array implementations in mmWave modules integrate directly with transceiver die. AiP configurations from Qualcomm reference designs eliminate discrete switch matrices.
- Transceivers:Modem-to-antenna integration spans multiple foundry nodes simultaneously. Cross-node IP reuse remains limited by incompatible design kits.
Amplifiers hold installed capacity. Filters are rotating up the share rankings.
Technology:
Application maturity determines whether segments compete on performance specifications or unit cost economics.
- 5G:Sub-6 GHz and mmWave architectures force consolidation of discrete components into single-package solutions. FCC Part 27 flexible-use rules mandate new filter designs for C-band coexistence.
- LTE:Legacy infrastructure sustains volume demand in emerging markets with delayed 5G spectrum allocation. Module suppliers maintain dual-technology qualification to capture transition windows.
- Wi-Fi:Tri-band 6E/7 front ends unify cellular and unlicensed spectrum conditioning. Enterprise WLAN OEMs consolidate procurement around converged module suppliers.
- Bluetooth:Low-power requirements favor CMOS integration over discrete module assembly. Consumer electronics volumes compete primarily on die size and test cost.
5G commands premium positioning. Wi-Fi is expanding most quickly in enterprise access points.
Application:
Customer type differentiation separates qualification-intensive automotive sockets from high-volume consumer electronics procurement.
- Telecommunications:Base station densification in China, South Korea, and the United States pulls beamforming-capable front ends. Tower operators demand integrated power amplifiers with phase shifters.
- Consumer Electronics:Smartphone OEMs negotiate multi-year platform contracts bundling sub-6 GHz, mmWave, and Wi-Fi modules. Korean and Chinese OEMs replicate Apple's single-source consolidation model.
- Automotive:C-V2X and DSRC coexistence architectures require automotive-qualified RF modules. Temperature-grade certifications open premium pricing tiers absent in consumer electronics.
- Aerospace:Military and satellite applications impose radiation-hardening and extended temperature specifications. Procurement cycles extend 24-36 months with sole-source qualification requirements.
Telecommunications holds defense contractor relationships. Consumer Electronics is climbing the fastest in absolute unit terms.
End User:
Volume concentration shapes whether procurement emphasizes design flexibility or manufacturing scale.
- OEMs:Apple and Samsung negotiate turnkey RF front-end assemblies eliminating board-level tuning. Multi-year agreements compress the supplier base toward integrated platform providers.
- Telecommunications Providers:China Mobile, Verizon, and SK Telecom specify module performance for base station deployment. Operator procurement cadence aligns with MIIT, FCC, and spectrum auction timelines.
- System Integrators:Enterprise WLAN and private 5G network deployments demand tri-band convergence modules. Distribution partnerships with module suppliers reduce RF engineering overhead.
- Research Institutions:University and national laboratory procurement supports early-stage antenna-in-package development. Funding cycles from NSF and EU Horizon programs shape R&D roadmaps.
OEMs anchor contract manufacturing capacity. System Integrators are gaining share fastest in private network deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes in India and China's MIIT radio transmission type approval timelines are redrawing procurement geography. Spectrum auction cadence in the United States and EU Radio Equipment Directive compliance windows dictate regional launch sequencing. Module suppliers must pre-validate designs against draft standards months before formal publication.
United States
FCC Part 27 flexible-use rules on C-band and 28 GHz spectrum are mandating new filter architectures for carrier aggregation. Verizon and AT&T procurement specifications drive beamforming-capable front-end demand. Tower operators in Texas and California densification corridors require integrated power amplifiers with phase shifters for mmWave deployment.
China
MIIT radio transmission type approval for 5G-Advanced equipment adds 26 GHz spurious emission testing requirements. China Mobile procurement volumes anchor module demand as domestic base station deployment accelerates. Shenzhen and Shanghai industrial clusters concentrate final test and filter tuning operations for premium smartphone sockets.
South Korea
SK Telecom and KT Corporation specify module performance for sub-6 GHz and mmWave coexistence architectures. The country's national spectrum regulator tightens electromagnetic compatibility standards ahead of 5G-Advanced commercialization. Seoul metropolitan area foundry partnerships sustain GaAs HBT power amplifier supply for premium handset OEMs.
Germany
EU Radio Equipment Directive harmonized standards extend certification timelines 4-6 months for multi-band modules targeting European operator channels. Automotive OEMs in Bavaria and Baden-Württemberg demand C-V2X front ends with temperature-grade certifications. Stuttgart industrial corridor suppliers qualify modules for DSRC coexistence architectures in connected vehicles.
India
PLI scheme production-linked incentives for 5G base station manufacturing attract module assembly investments with domestic value-add requirements. TRAI spectrum allocation proceedings shape operator deployment cadence for sub-6 GHz infrastructure. Tamil Nadu and Karnataka electronics manufacturing clusters host filter tuning and final test operations for telecom equipment procurement.
Radio Frequency Front End Module Market Competitive Environment
Channel-controlling players compete with product-specialist players across procurement tiers. Smartphone OEM consolidation around platform-level contracts compresses the supplier base toward integrated providers with full-stack capabilities. Three archetypes dominate: captive filter manufacturers with ceramic capacity, fabless designers leveraging multi-foundry access, and modem-to-antenna integrators spanning transceiver and front-end domains. Strategic moves concentrate on foundry partnership expansion and automotive qualification investments.
Among Japan-based component manufacturers, Murata Manufacturing Co. Ltd anchors premium sub-6 GHz portfolios through captive ceramic filter capacity. German-origin semiconductor suppliers Infineon Technologies AG and Broadcom Inc occupy positions across automotive and telecommunications verticals. These three exemplify the divergence between materials-integrated and design-fabless competitive vectors.
| Leading Market Players |
|---|
| Murata Manufacturing Co. Ltd |
| Infineon Technologies AG |
| Broadcom Inc |
| TDK Corp |
| NXP Semiconductors NV |
| Skyworks Solutions, Inc |
| Qualcomm Technologies, Inc |
| STMicroelectronics NV |
| Qorvo Inc |
| Others |
Value Chain & Pricing Dynamics
Shanghai-to-Shenzhen freight corridors absorb premium logistics costs that cascade through GaAs wafer procurement and amplify price spreads between automotive-qualified modules and consumer-grade alternatives. This transport-cost layer compounds with foundry capacity scarcity to compress margins for fabless designers while rewarding integrated platform providers with captive ceramic filter supply.
Pricing Analysis
Certification level creates the primary spread, with automotive AEC-Q100 temperature-grade modules commanding substantial premiums over handset-grade equivalents. Three-tier pricing structure across premium, standard, and economy levels reflects TC-BAW filter performance, GaAs HBT efficiency thresholds, and MIIT pre-validation status. Cost compression in mid-tier smartphone sockets intensifies as Korean and Chinese OEMs consolidate procurement around single-source platform contracts. Enterprise system integrators exhibit lowest price sensitivity due to RF engineering overhead reduction, while emerging market telecommunications providers face acute budget constraints.
Supply Chain Analysis
Extended payment terms from smartphone OEMs strain working capital for module assembly houses, forcing supply-chain finance facilities at foundry partners. Manufacturing concentrates in Taiwan, Japan, and China, with six-inch GaAs substrate production anchoring power amplifier supply. Raw material dependencies span high-purity gallium arsenide wafers, aluminum nitride ceramic substrates, and rare-earth dopants for filter fabrication. Single-source vulnerability in epitaxial wafer contracts exposes fabless designers to price volatility. Distribution runs through direct platform contracts with Apple and Samsung, displacing historical component distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern RF front-end procurement as modem-to-antenna integration eliminates board-level RF engineering discretion. This shift mirrors Qualcomm's reference design ecosystem expansion and Apple's multi-year supply agreement consolidation.
For Market Incumbents: Harden GaAs HBT foundry partnerships against SOI-based displacement by securing multi-node qualification across Taiwan and Japan facilities. Invest in automotive AEC-Q100 certification capacity before C-V2X deployment accelerates, as temperature-grade qualifications create defensible pricing tiers. Absorb ceramic filter tuning operations to maintain premium sub-6 GHz positioning against Murata's captive supply advantage.
For New Entrants and Emerging Players: Build out India PLI scheme assembly partnerships with domestic value-add operations in Tamil Nadu and Karnataka electronics clusters. Target private 5G enterprise network deployments where system integrators seek tri-band convergence modules without incumbent platform lock-in. Pursue Wi-Fi 7 front-end sockets in enterprise access points as WLAN OEMs consolidate RF procurement.
For Investors and Strategic Acquirers: Fabless module designers with multi-foundry access and automotive qualification pipelines represent priority acquisition archetypes. Long-term viability hinges on antenna-in-package co-design capabilities spanning electromagnetic simulation and semiconductor packaging expertise. Monitor FCC Part 27 spectrum reallocation proceedings and China MIIT 5G-Advanced draft standard releases as inflection indicators for filter architecture refresh cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Expansion | Multi-node GaAs and SOI access secures supply against Taiwan substrate concentration. |
| Automotive Qualification Investment | AEC-Q100 certification opens premium C-V2X pricing tiers in Stuttgart and Bavaria corridors. |
| Antenna-in-Package Development | Qualcomm reference design adoption eliminates discrete switch matrices and reduces board area. |
| Ceramic Filter Capacity Addition | Captive TC-BAW production anchors Murata-style premium sub-6 GHz portfolio positioning. |
| India Manufacturing Localization | PLI scheme compliance attracts telecom equipment procurement with domestic value-add requirements. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FCC spectrum auction records, MIIT radio transmission type approval filings, and EU Radio Equipment Directive harmonized standards documentation. Primary interviews engaged RF front-end procurement managers at smartphone OEMs, base station deployment leads at China Mobile and Verizon, and electromagnetic simulation specialists at foundry partners. Secondary validation drew from SEC 10-K semiconductor disclosures, customs trade data for GaAs wafer imports, and tower operator capex announcements. Bottom-up module shipment triangulation against top-down telecommunications infrastructure investment flows anchored value estimates.
Forecast inputs span component-level bill-of-materials analysis, carrier aggregation complexity trajectories, and spectrum auction cadence across the analysis window. Segmentation dimensions modeled include technology generation, certification grade, application vertical, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, 5G attach rate assumptions, and foundry capacity expansion announcements. Industry-specific inputs incorporate MIIT 5G-Advanced certification timeline compression and FCC Part 27 flexible-use rule implementation pacing.
Practitioners should monitor FCC spectrum reallocation proceedings, China MIIT draft standard publication schedules, and GaAs wafer contract pricing volatility for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Radio Frequency Front End Market
RF Components
Tunable Capacitors Market
RF Components
Analog Phase Shifter Market
RF Components
RF Over Fiber (Rfof) Market
RF Components
Global Small Cell Power Amplifier Market
RF Components
Global Ceramic Dielectric Filters Market
RF Components
RF Switches Market
RF Components
Latin America RFID Tags Market
RF Components
Global Gan RF Devices Market
RF Components
UHF RFID Inlays Market
RF Components
Radio Frequency Integrated Circuit (RFIC) Market
RF Components
Global RF and Microwave Power Transistors Market
RF Components
Global RF Power Semiconductor Market
RF Components
RF Gan Market
RF Components
433MHz Active RFID Reader Market
RF Components
Harness-Level EMI and Shielding Component Systems Market