
 5G Millimeter Wave RF Transceiver Market | 2026-2036
5G Millimeter Wave RF Transceiver Market Size, Share, and Industry Trends Forecast 2026-2036
5G Millimeter Wave RF Transceiver Market Insights
South Korea's nationwide 5G infrastructure build-out is rewriting procurement patterns for millimeter wave components. Qualcomm leverages its modem-RF integration to dominate baseband-to-antenna design wins across Korean carriers. Samsung Electronics anchors domestic supply chains through captive semiconductor fabrication and in-house handset production. Analog Devices specializes in high-speed data converter architectures that sustain signal integrity at 28 GHz and 39 GHz operating bands.
A 5G millimeter wave RF transceiver converts modulated digital signals to analog waveforms in the 24–100 GHz range, with critical specifications including EVM below 3% and phase noise better than -90 dBc/Hz at 1 MHz offset for reliable beamforming. RF front-end modules and power amplifiers capture the largest value pools due to thermal management complexity and compound semiconductor content, while GaN-on-SiC technology is displacing GaAs in base station applications where output power exceeds 1 Watt. CMOS-based transceivers for mobile devices compete on cost at frequencies below 30 GHz, though SiGe BiCMOS retains advantages in automotive radar-derivative V2X implementations.
The FCC governs spectrum allocation and device certification through Part 30 rules for upper microwave flexible use, while the ETSI framework in Europe mandates harmonized frequency bands under the 5G Pioneer Bands spectrum decision. China's MIIT issues network equipment licenses that restrict market access to transceivers meeting domestic security and electromagnetic compatibility protocols. Stakeholders must monitor evolving national spectrum reassignments and semiconductor export control classifications that determine which process technologies remain available for next-generation transceiver development.
Market Dynamics
Beamforming complexity at 28 GHz and 39 GHz is compressing design cycles and forcing module-level consolidation across baseband-to-antenna signal chains.
Growth Catalysts
- Fixed Wireless Access expansion:Telecom operators in the United States bypass fiber deployment constraints by deploying millimeter wave customer premises equipment, accelerating RF front-end module procurement.
- South Korean infrastructure mandates:Nationwide 5G coverage targets drive sustained demand for 28 GHz base station transceivers and handset-integrated modules.
- GaN-on-SiC thermal performance:Compound semiconductor substrates enable output power above 1 Watt in macro cell power amplifiers, displacing legacy GaAs architectures in high-density urban deployments.
Market Restraints
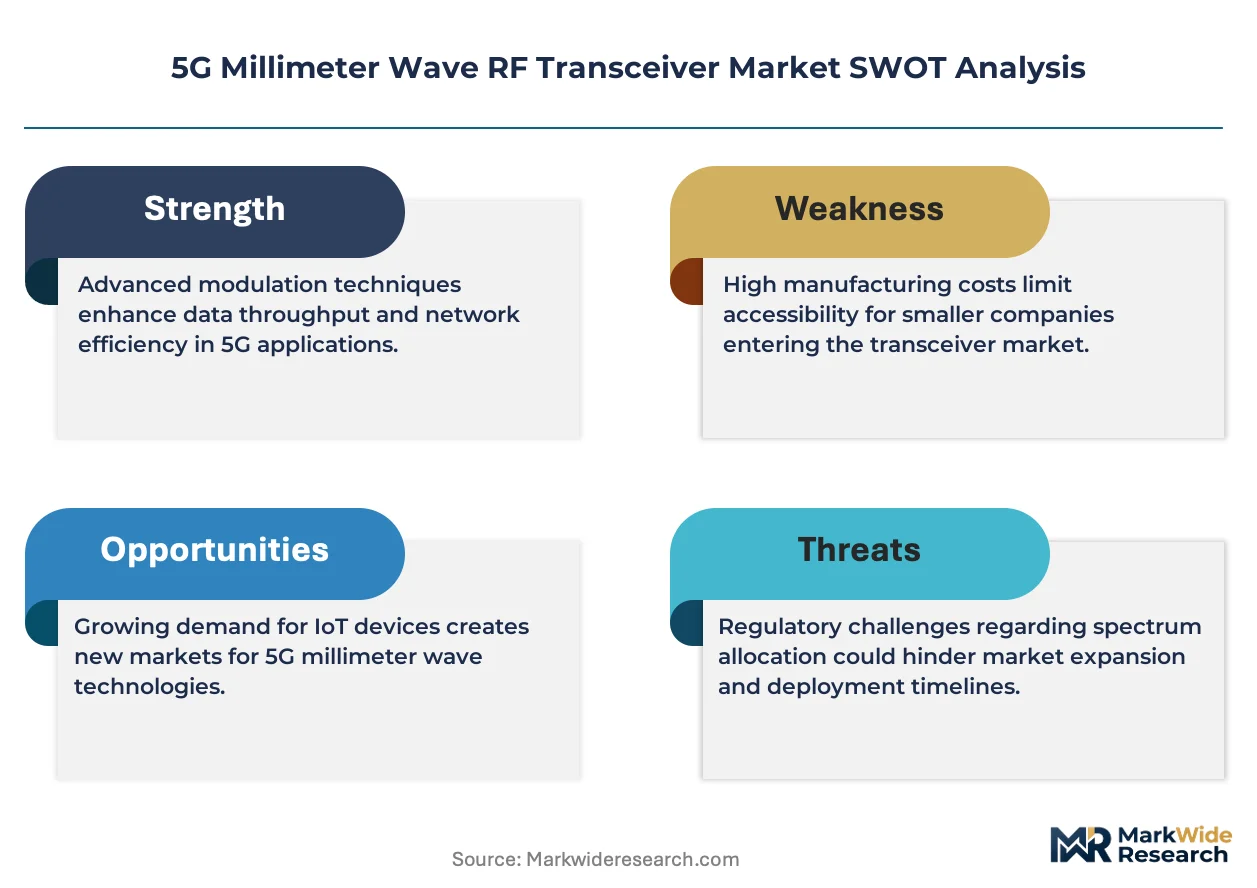
- Compound semiconductor supply concentration:GaN-on-SiC epitaxial wafer production clusters in specific Asian manufacturing corridors, creating single-source vulnerability for base station amplifier suppliers.
- Part 30 certification friction:FCC device authorization timelines for upper microwave flexible use equipment extend development schedules by 6-12 months versus sub-6 GHz equivalents.
- Silicon photonics substitution threat:Co-packaged optical interconnects for data center applications reduce reliance on millimeter wave backhaul in fiber-rich environments.
Strategic Opportunities
- V2X automotive radar convergence:SiGe BiCMOS transceiver architectures from 77 GHz automotive platforms adapt to 5G NR-V2X roadside units, opening roadside infrastructure procurement channels.
- India spectrum harmonization:TRAI recommendations for 26 GHz and 28 GHz band allocation create first-mover positioning for equipment vendors ahead of anticipated 2025-2026 network tenders.
- Modem-RF integration:Baseband-to-antenna reference designs consolidate discrete component counts, enabling cost reduction in sub-30 GHz mobile device implementations.
Industry Challenges
- Millimeter wave test and calibration expertise:Vector network analyzer operation at 50-110 GHz and over-the-air chamber validation require specialized RF engineering talent pools concentrated in limited geographic clusters.
- Legacy 4G infrastructure coexistence:Dual-connectivity implementations mandating simultaneous LTE anchor and NR mmWave operation complicate thermal management and battery system design in handset form factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Millimeter Wave RF Transceiver Market |
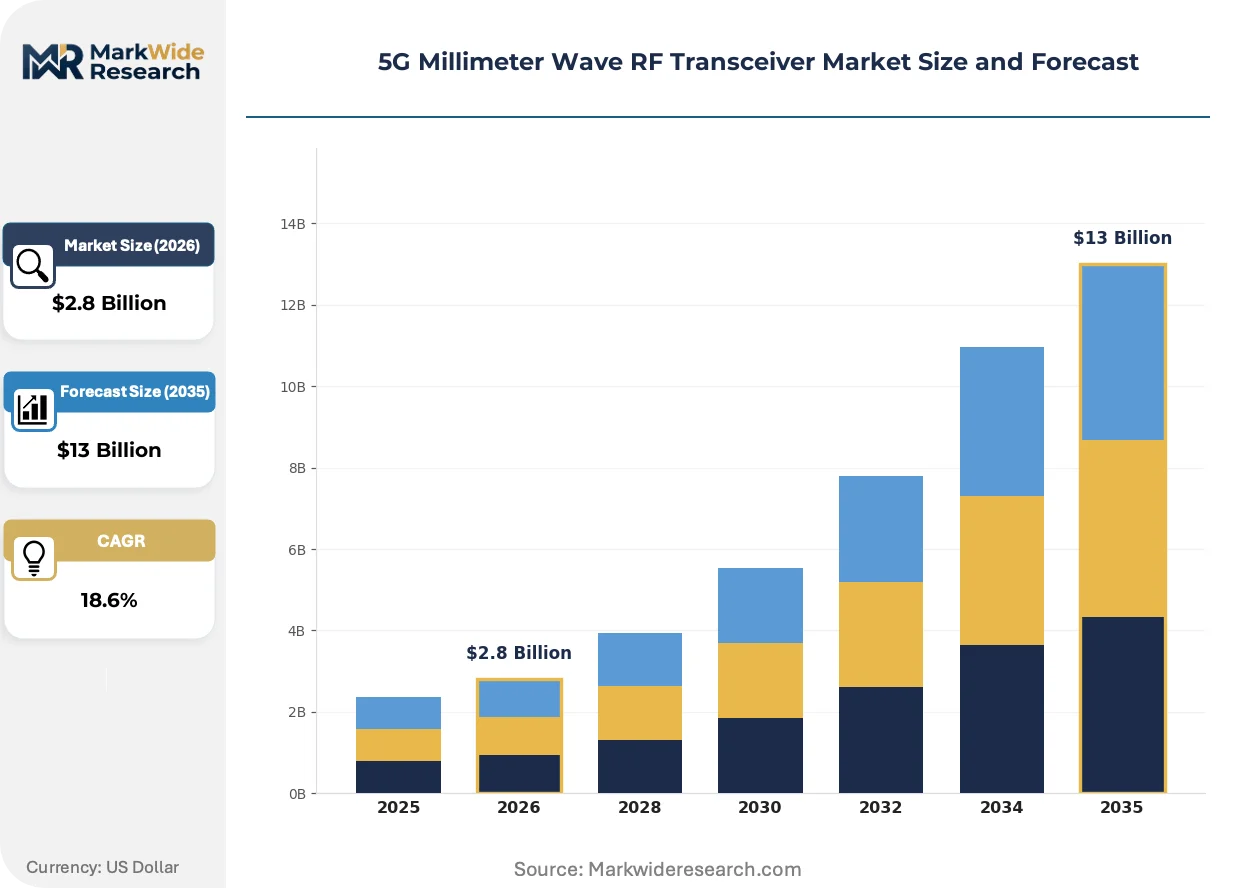
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RF Front-End Modules, Power Amplifiers, Low Noise Amplifiers, Mixers, Frequency Synthesizers Technology: SiGe, GaAs, CMOS, BiCMOS, GaN Application: Mobile Devices, Fixed Wireless Access, Small Cells, Enhanced Mobile Broadband, Vehicle-to-Everything End User: Telecom Operators, Network Infrastructure Providers, Equipment Manufacturers, System Integrators |
| Companies Covered | Qualcomm, Samsung Electronics, Intel, Analog Devices, Texas Instruments, Broadcom, Qorvo, Skyworks Solutions, Keysight Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Millimeter Wave RF Transceiver Market Trends and Innovations
Silicon integration roadmaps and packaging advances are collapsing discrete component boundaries while spectrum policy fragmentation forces multi-band architecture flexibility.
CMOS-based phased array transceivers are hybridizing digital beamforming with analog front-end paths to achieve cost targets for consumer handset volumes. Samsung Electronics and Qualcomm have shipped 28 GHz modules integrating power amplifiers, switches, and antennas in antenna-in-package configurations since 2019. This convergence is compressing the addressable market for discrete RF front-end suppliers while expanding total available units.
ETSI's 5G Pioneer Bands spectrum decision mandates harmonized 26 GHz coverage across European Union member states by 2025. Equipment manufacturers must certify transceivers for CE marking under RED 2014/53/EU while accommodating national derogations for specific band segments. German and French regulators are accelerating local licensing frameworks to synchronize with this harmonization timeline.
Carrier aggregation requirements across sub-6 GHz and millimeter wave carriers are compressing handset OEM qualification cycles from 18 months to 12 months. Tier-one smartphone manufacturers now mandate simultaneous lab validation across FCC, CE, and MIIT certification regimes before volume commitment. South Korean carriers enforce the most stringent over-the-air performance thresholds, effectively setting the global specification baseline for premium device launches.
5G Millimeter Wave RF Transceiver Market Segmentation
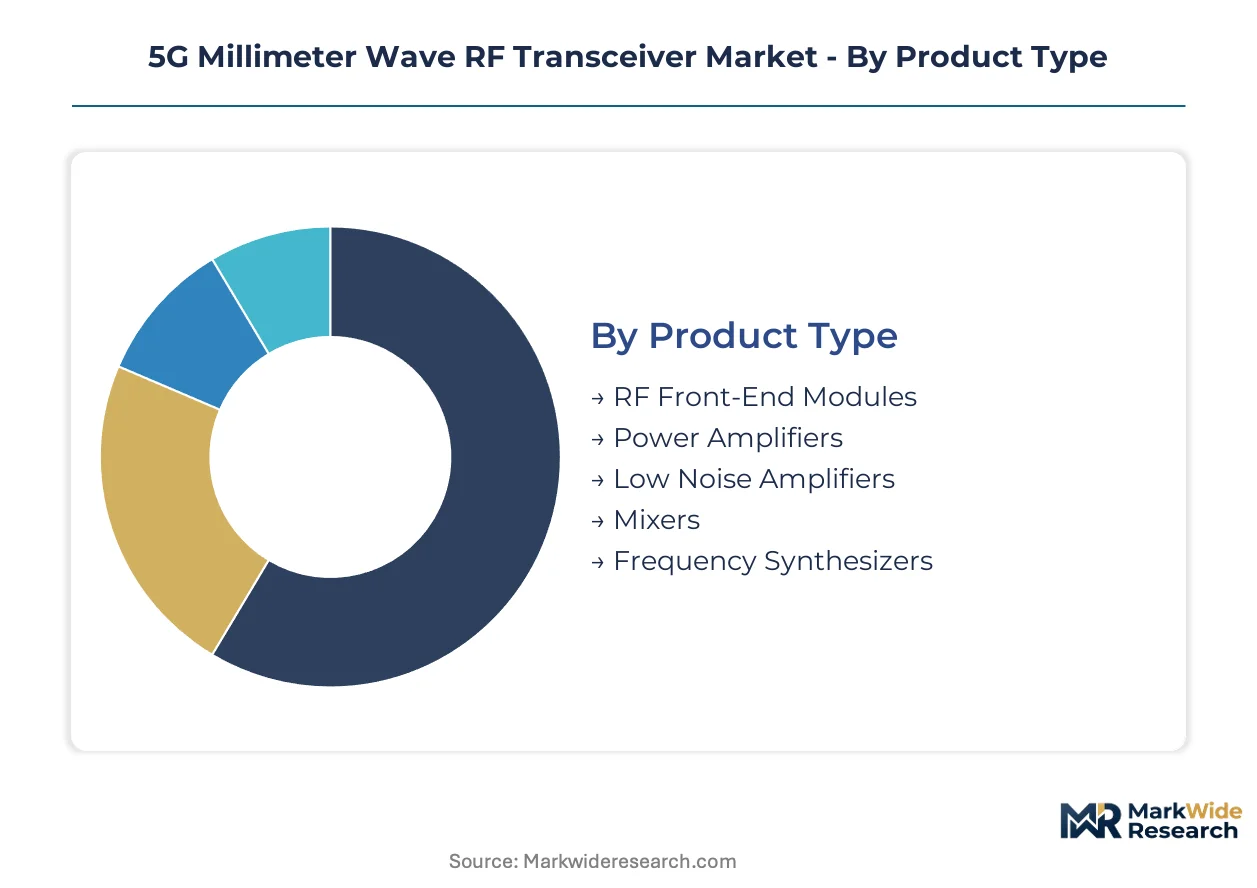
Millimeter wave component procurement varies sharply across deployment scenarios. Signal chain position and semiconductor process technology determine thermal budgets, certification complexity, and supplier qualification timelines for 5G infrastructure build-outs.
Product Type:
RF front-end modules span the complete signal path from power amplification through antenna interface, with integration density dictating handset versus base station suitability.
- RF Front-End Modules:These assemblies integrate power amplifiers, switches, filters, and antenna elements in antenna-in-package configurations. South Korean carriers drive qualification standards for 28 GHz implementations in premium smartphones, compressing supplier development cycles.
- Power Amplifiers:Compound semiconductor devices deliver output power above 1 Watt in macro cell applications. GaN-on-SiC substrates displace GaAs in urban base stations where thermal dissipation limits enclosure density.
- Low Noise Amplifiers:First-stage receive chain components set noise figure budgets for beamforming arrays. CMOS implementations compete below 30 GHz while SiGe BiCMOS dominates automotive radar-derivative V2X platforms.
- Mixers:Frequency translation stages convert between intermediate frequency and millimeter wave carriers. Linear intermodulation specifications determine suitability for dense modulation schemes.
- Frequency Synthesizers:Phase-locked loop architectures generate local oscillator signals with phase noise below -90 dBc/Hz at 1 MHz offset. Integer-N versus fractional-N topologies trade spurious performance against lock time.
The dominant share belongs to RF Front-End Modules, while Power Amplifiers is closing the gap fastest.
Technology:
Process node selection hinges on frequency, power level, and integration requirements across mobile and infrastructure endpoints.
- SiGe:Silicon-germanium heterojunction bipolar transistors achieve cutoff frequencies above 300 GHz with moderate noise performance. Foundry capacity concentrates in European and North American manufacturing corridors for automotive radar-derivative V2X transceivers.
- GaAs:Gallium arsenide pseudomorphic high electron mobility transistors retain cost advantages in sub-6 GHz handset power amplifiers. Process maturity supports high-volume manufacturing though thermal conductivity limits millimeter wave output power.
- CMOS:Bulk and SOI complementary metal-oxide-semiconductor processes enable digital beamforming integration at frequencies below 30 GHz. Samsung Electronics and Qualcomm have shipped integrated transceivers since 2019, collapsing discrete component counts.
- BiCMOS:Combined bipolar and CMOS fabrication supports mixed-signal architectures with precision analog front-ends. SiGe BiCMOS specifically enables 77 GHz automotive radar platforms that adapt to roadside unit applications.
- GaN:Gallium nitride on silicon carbide substrates delivers the highest power density for macro cell base stations. Epitaxial wafer supply concentrates in Asian manufacturing corridors, creating qualification bottlenecks for European and North American amplifier vendors.
CMOS commands the largest production volumes, though GaN is expanding most quickly in base station procurement.
Application:
Deployment scenarios impose distinct link budget, mobility, and environmental constraints on transceiver specifications.
- Mobile Devices:Handset-integrated modules prioritize thermal management and battery consumption over absolute output power. South Korean carriers enforce the most stringent over-the-air performance thresholds, effectively setting global premium device specifications.
- Fixed Wireless Access:Customer premises equipment bypasses fiber deployment constraints in the United States. 28 GHz and 39 GHz implementations require outdoor-rated enclosures with phased array beam steering.
- Small Cells:Dense urban deployments demand compact form factors with coordinated multipoint operation. Indoor versus outdoor ratings split procurement between enterprise and carrier-managed installations.
- Enhanced Mobile Broadband:Macro layer capacity augmentation uses carrier aggregation across sub-6 GHz and millimeter wave carriers. Dual-connectivity implementations complicate thermal management in smartphone form factors.
- Vehicle-to-Everything:Roadside units and onboard units exchange safety-critical messages with sub-10 millisecond latency. 5G NR-V2X specifications adapt 77 GHz automotive radar architectures for cellular sidelink operation.
Mobile Devices retains the dominant procurement volume, while Fixed Wireless Access is gaining share fastest.
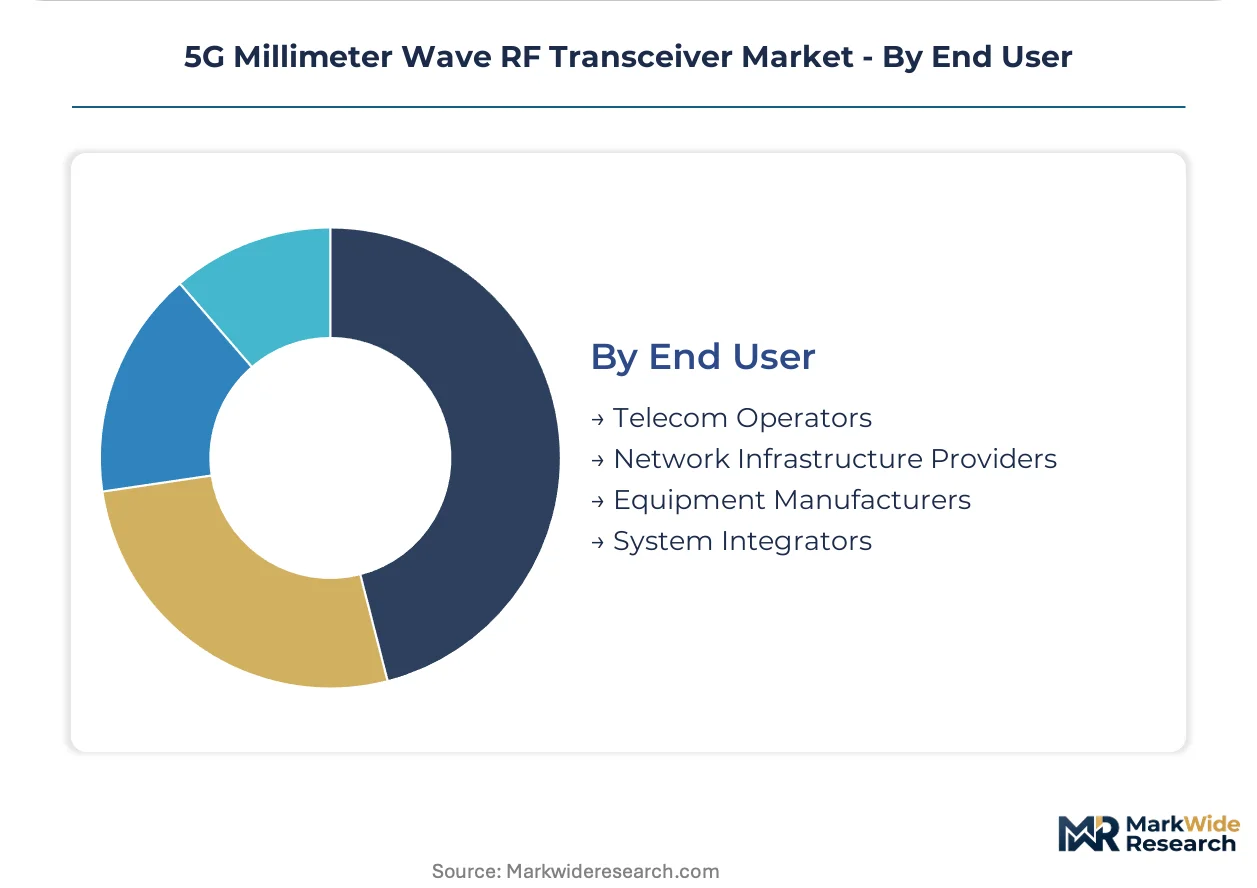
End User:
Procurement authority and technical specification control vary across the deployment value chain.
- Telecom Operators:Verizon, AT&T, and T-Mobile in the United States specify interoperability requirements that cascade through equipment vendor supply chains. South Korean carriers SK Telecom, KT, and LG Uplus enforce performance thresholds that become de facto global standards.
- Network Infrastructure Providers:Ericsson, Nokia, and Samsung Networks integrate transceiver subsystems into radio units and baseband equipment. Their reference designs determine qualified supplier lists for component vendors.
- Equipment Manufacturers:Handset OEMs including Samsung Electronics and Apple source modules through qualified vendor programs with 12-month qualification cycles. Carrier aggregation requirements compress these timelines from historical 18-month baselines.
- System Integrators:Enterprise and private network deployers assemble multi-vendor solutions for manufacturing, logistics, and campus environments. Their procurement emphasizes interoperability certification over absolute performance specifications.
Telecom Operators control the dominant specification authority, while Equipment Manufacturers are consolidating procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC's Part 30 framework governs spectrum allocation and device certification for upper microwave flexible use in the United States. South Korea's nationwide 5G infrastructure mandates and India's pending spectrum harmonization create divergent procurement timelines across major deployment corridors.
United States
Verizon, AT&T, and T-Mobile deploy millimeter wave fixed wireless access equipment to bypass fiber deployment constraints in suburban and rural markets. The FCC's Part 30 certification timelines extend development schedules by 6-12 months versus sub-6 GHz equivalents. Austin and Dallas anchor RF front-end module testing clusters where vector network analyzer operations at 50-110 GHz concentrate engineering talent.
South Korea
SK Telecom, KT, and LG Uplus enforce over-the-air performance thresholds that effectively set global specifications for premium smartphone launches. The country's national telecommunications regulator mandates nationwide 5G coverage targets that sustain demand for 28 GHz base station transceivers. Seoul's Pangyo Techno Valley hosts concentrated R&D facilities for antenna-in-package integration.
China
MIIT issues network equipment licenses that restrict market access to transceivers meeting domestic security and electromagnetic compatibility protocols. The regulator's spectrum assignments in the 24.75-27.5 GHz and 37-42.5 GHz bands shape equipment vendor qualification requirements. Shenzhen and Beijing anchor manufacturing corridors for CMOS-based phased array transceiver production.
Germany
ETSI's 5G Pioneer Bands spectrum decision mandates harmonized 26 GHz coverage across European Union member states by 2025. The country's national automotive regulator accelerates local licensing frameworks to synchronize with this harmonization timeline. Munich and Stuttgart anchor automotive radar-derivative V2X development clusters where 77 GHz platforms adapt to roadside unit applications.
India
TRAI recommendations for 26 GHz and 28 GHz band allocation create first-mover positioning for equipment vendors ahead of anticipated 2025-2026 network tenders. The central telecommunications regulator's spectrum harmonization process determines equipment certification timelines for domestic deployment. Bengaluru and Hyderabad anchor emerging RF engineering talent pools for millimeter wave test and calibration expertise.
5G Millimeter Wave RF Transceiver Market Competitive Landscape
Modem-RF integrators and discrete component specialists split the market along integration-density lines. Tier-one smartphone manufacturers consolidate procurement through qualified vendor programs with compressed 12-month qualification cycles. Three strategic archetypes dominate: baseband-to-antenna platform vendors, compound semiconductor substrate suppliers, and test and measurement equipment providers. Capacity expansion in Asian manufacturing corridors and strategic partnerships for antenna-in-package technology represent the dominant competitive moves.
Within the integration-focused tier, Qualcomm and Samsung Electronics exemplify platform-level consolidation through modem-RF reference designs that collapse discrete component counts. Analog Devices occupies a position among high-speed data converter specialists sustaining signal integrity at 28 GHz and 39 GHz operating bands. These three anchors span distinct competitive vectors: cellular platform integration, captive semiconductor fabrication, and precision analog front-end architectures.
| Leading Market Players |
|---|
| Qualcomm |
| Samsung Electronics |
| Intel |
| Analog Devices |
| Texas Instruments |
| Broadcom |
| Qorvo |
| Skyworks Solutions |
| Keysight Technologies |
| Others |
Pricing and Supply Chain Analysis
GaN-on-SiC epitaxial wafer undercapacity in Asian manufacturing corridors is tightening supplier pricing power while compressing procurement timelines for base station amplifier vendors. This utilization squeeze feeds directly into contract renegotiation leverage for compound semiconductor foundries and accelerates vertical integration moves among RF front-end module suppliers.
Pricing Analysis
Price spreads between South Korean and Indian procurement contracts for 28 GHz RF front-end modules exceed 40 percent due to certification stringency differentials. The dominant structure is tiered pricing across premium, standard, and economy levels, with differentiation driven by EVM performance grade and FCC Part 30 certification status. Cost compression in the standard tier is intensifying because CMOS-based transceivers below 30 GHz commoditize faster than anticipated. Equipment manufacturers exhibit the highest price sensitivity, while telecom operators prioritize performance thresholds over unit economics.
Supply Chain Analysis
Export control classifications under US Commerce Department restrictions are fragmenting millimeter wave semiconductor flows between allied and non-allied manufacturing corridors. Supply concentrates in Taiwan for CMOS fabrication, South Korea for antenna-in-package integration, and Japan for high-frequency substrate materials. Raw material dependencies include silicon carbide wafers, gallium nitride epitaxy, and low-loss laminates for antenna substrates. Single-source vulnerability in GaN-on-SiC epitaxial supply creates qualification bottlenecks for European and North American amplifier vendors. Distribution runs through qualified vendor programs administered by tier-one smartphone OEMs and network infrastructure providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is crossing into platform economics as modem-RF integration collapses discrete component boundaries and locks in ecosystem control points. Interoperability requirements cascading from South Korean carrier specifications are creating winner-take-most dynamics across baseband-to-antenna reference designs.
For Market Incumbents: Pre-empt silicon photonics substitution in data center backhaul by accelerating antenna-in-package roadmaps with integrated beamforming ASICs. Defend against emerging CMOS-only entrants by deepening captive GaN-on-SiC capacity in Taiwan and South Korea. Lock in multi-year supply agreements with epitaxial wafer suppliers before export control expansions tighten further.
For New Entrants and Emerging Players: Pursue V2X roadside infrastructure as the most penetrable segment, where SiGe BiCMOS automotive radar expertise transfers directly to 5G NR-V2X specifications with lower certification barriers than handset modules. Target Indian equipment vendors ahead of anticipated network tenders by pre-certifying transceivers for TRAI's 26 GHz and 28 GHz band allocations. Lead with test and calibration service offerings to bypass capital-intensive fabrication entry barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across GaN-on-SiC substrate production as epitaxial equipment lead times extend and cleanroom construction costs escalate. Long-term viability favors compound semiconductor specialists with backward integration into SiC crystal growth rather than fabless design houses exposed to foundry pricing cycles. The acquisition target archetype is mid-cap RF front-end module vendors with qualified supplier status at Samsung Electronics or Qualcomm. Watch for inflection signals in FCC Part 30 certification timeline compression, which would indicate regulatory prioritization of millimeter wave deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Modem-RF Platform Integration | Consolidates discrete component counts and locks in baseband-to-antenna design wins at Korean carriers. |
| GaN-on-SiC Capacity Expansion | Secures thermal performance advantages for macro cell power amplifiers above 1 Watt output. |
| Antenna-in-Package Technology Partnership | Compresses form factors for 28 GHz handset modules while raising barriers for discrete suppliers. |
| V2X Roadside Unit Certification | Opens procurement channels from 77 GHz automotive radar platforms adapting to cellular sidelink. |
| India Spectrum Pre-Certification | Positions equipment vendors ahead of TRAI's 26 GHz and 28 GHz allocation implementation. |
Research Methodology
The analysis maps RF front-end modules, power amplifiers, and frequency synthesizers, each validated through procurement directors at telecom operators, RF engineering leads at network infrastructure providers, and supply chain managers at equipment manufacturers. Primary interviews with these stakeholders combined with secondary validation from FCC Part 30 filing databases, MIIT network equipment license registries, and ETSI harmonization documentation. Bottom-up unit shipment estimates triangulated against top-down semiconductor content value analysis.
Assumptions held fixed include current FCC, ETSI, and MIIT spectrum allocation frameworks, while GaN-on-SiC substrate availability and CMOS process node migration timelines were varied across sensitivity scenarios. The projection horizon spans product type, technology, application, and end user dimensions, with additional segmentation by regional regulatory cluster. CAGRs derived from curve-fitting historical infrastructure deployment cycles against carrier capex guidance disclosures. Forecast inputs include base station transceiver procurement schedules and handset OEM qualification cycle compression trends.
Sensitivities concentrate around export control expansions, spectrum reassignments, and compound semiconductor substrate supply disruptions. Forecasts reflect documented assumptions regarding carrier aggregation requirements and thermal management specifications. Material shifts in FCC Part 30 certification timelines or MIIT security protocol amendments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
UHF RFID Inlays Market
RF Components
Flat Antenna Market
RF Components
Power Amplifier Market
RF Components
RF Passive Component Market
RF Components
High-Volume RF Front-End Module Test Systems Market
RF Components
Global Small Cell Power Amplifier Market
RF Components
Smart Antenna Market
RF Components
RF Isolator Market
RF Components
LTCC Power Dividers Market
RF Components
Space Traveling Wave Tube Amplifiers Market
RF Components
RF Duplexer Market
RF Components
Frequency Synthesizer Market
RF Components
Monolithic Microwave Integrated Circuit (MMIC) Market
RF Components
Z-Wave Products Market
RF Components
RF Power Dividers Market
RF Components
Multiband Booster Market