
 RFID Antenna Market | 2026-2036
RFID Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
RFID Antenna Market Outlook
Retail inventory tracking is shifting from barcode-dominant workflows to RFID-enabled real-time visibility, pulling antenna demand toward UHF passive configurations. Zebra Technologies Corp. leverages its end-to-end retail solutions footprint to anchor hardware deployment across North American distribution centers. Impinj, Inc. specializes in RAIN RFID chip connectivity, sustaining R&D intensity at the silicon-antenna interface. Invengo Information Technology Co., Ltd. dominates manufacturing and logistics deployments across Asia-Pacific production corridors.
An RFID antenna is a transducer that converts electrical current into electromagnetic waves and vice versa, typically operating across 860–960 MHz for UHF applications with gain specifications between 6 dBi and 12 dBi depending on read-range requirements. The component enables non-contact identification and data capture in automated supply chain, asset tracking, and access control systems. Passive antennas command the largest installed base due to lowest unit cost and battery-free operation, though integrated antennas are capturing margin pools as OEMs embed RF front-ends directly into equipment housings. UHF technology leads volume shipments for logistics and retail, while HF maintains position in payment and pharmaceutical authentication where shorter read ranges and near-field coupling provide security advantages.
FCC Part 15 regulations in the United States govern unlicensed UHF operation and directly shape antenna power limits and spectrum allocation for RFID deployments. ETSI EN 302 208 in Europe mandates specific channel plans and listen-before-talk protocols, forcing antenna manufacturers to design region-specific radiation patterns and frequency agility. ISO/IEC 18000-63 and EPCglobal Gen 2 standards provide the interoperability framework that determines which antenna designs qualify for multinational retail and logistics contracts. Stakeholders must monitor regulatory harmonization progress between FCC and ETSI frameworks, as divergence in spectral masks and power limits continues to fragment antenna SKUs and complicate global rollout strategies.
Market Dynamics
Retail inventory automation is compressing deployment timelines for UHF passive antenna systems, forcing manufacturers to prioritize gain consistency and frequency agility over legacy form-factor compatibility.
Growth Catalysts
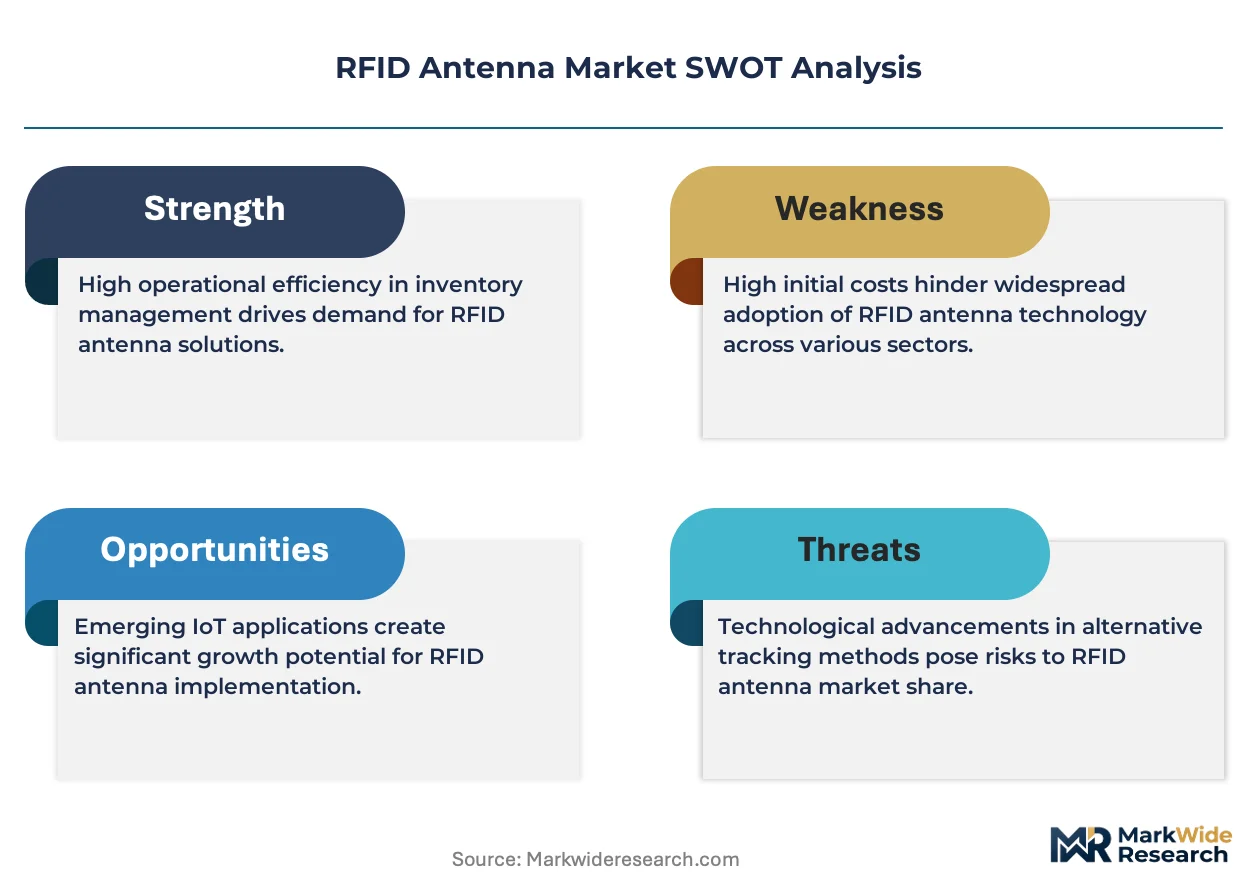
- EPC Gen 2 Protocol Harmonization:Alignment between FCC Part 15 in the United States and ETSI EN 302 208 in Europe reduces antenna SKU fragmentation and accelerates multinational retail rollout timelines.
- Smart Factory Deployment:Manufacturing clusters in Shenzhen and Shanghai require embedded antenna integration for automated material handling and work-in-process tracking.
- Pharmaceutical Authentication Mandates:HF antenna demand from serialization requirements in pharmaceutical supply chains sustains near-field coupling deployments despite UHF logistics dominance.
Market Restraints
- Copper and Ferrite Cost Volatility:Raw material price swings for antenna core substrates compress margin pools for passive UHF manufacturers operating at high volume.
- Regional Regulatory Divergence:Persistent spectral mask differences between FCC and ETSI frameworks force antenna designers to maintain separate radiation pattern inventories.
- Barcode Substitution Threat:Low-cost 2D imaging systems in last-mile delivery and small-format retail limit RFID antenna penetration in price-sensitive segments.
Strategic Opportunities
- India Manufacturing Incentives:PLI scheme subsidies for electronics manufacturing create localized antenna production opportunities serving domestic logistics and retail modernization.
- Healthcare Asset Tracking Convergence:Integration of RAIN RFID with BLE beacon networks opens hospital equipment visibility applications requiring hybrid antenna architectures.
- Direct-to-Installer Channel Expansion:Bypassing traditional distribution through embedded-systems marketplaces reduces antenna procurement friction for mid-sized OEM integrators.
Industry Challenges
- RF Engineering Talent Scarcity:Shortage of electromagnetic simulation specialists delays antenna optimization cycles for integrated OEM deployments.
- Multi-Protocol Certification Timelines:ISO/IEC 18000-63 and EPCglobal Gen 2 compliance testing extends product launch schedules by 4-6 months for new antenna form factors.
- Legacy WMS Integration Friction:Warehouse management system retrofit requirements complicate antenna deployment in brownfield distribution centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RFID Antenna Market |
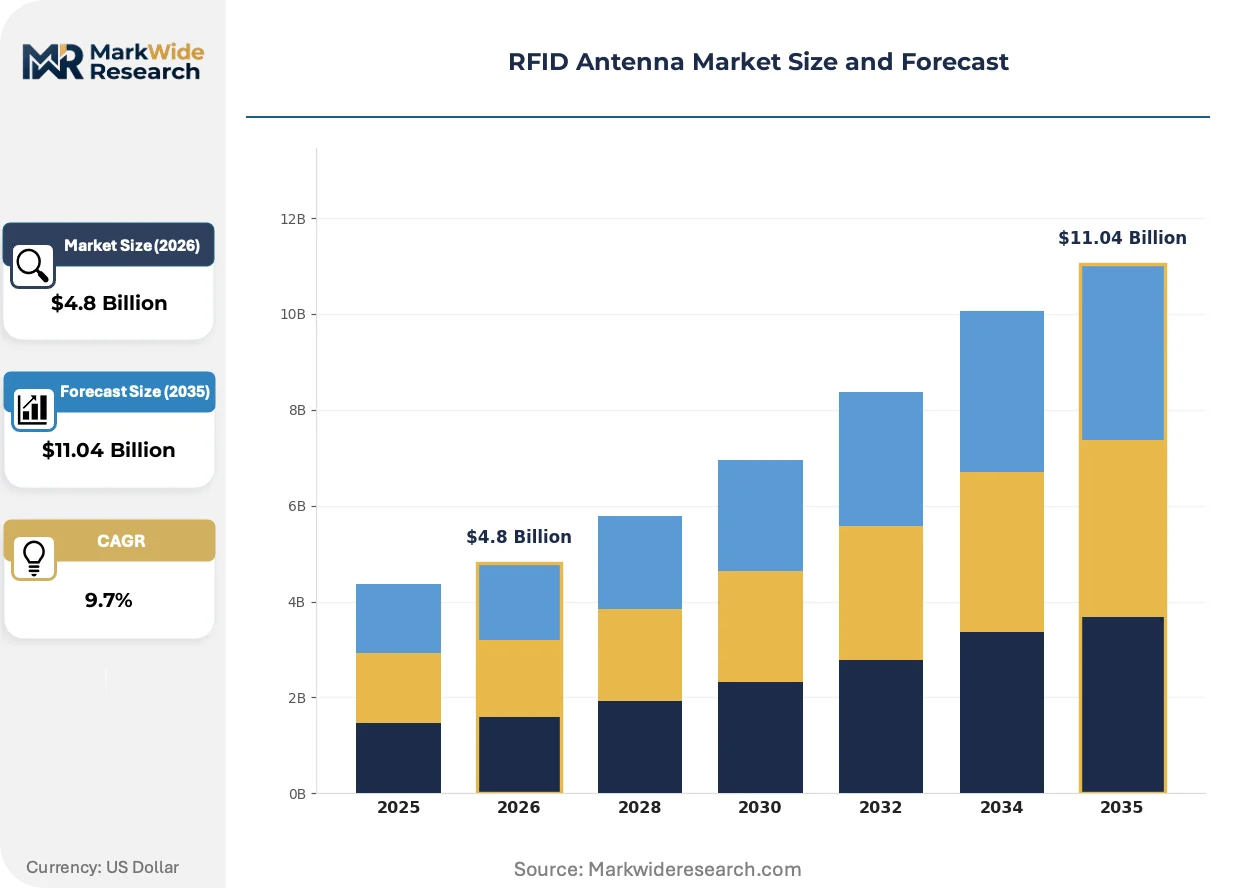
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
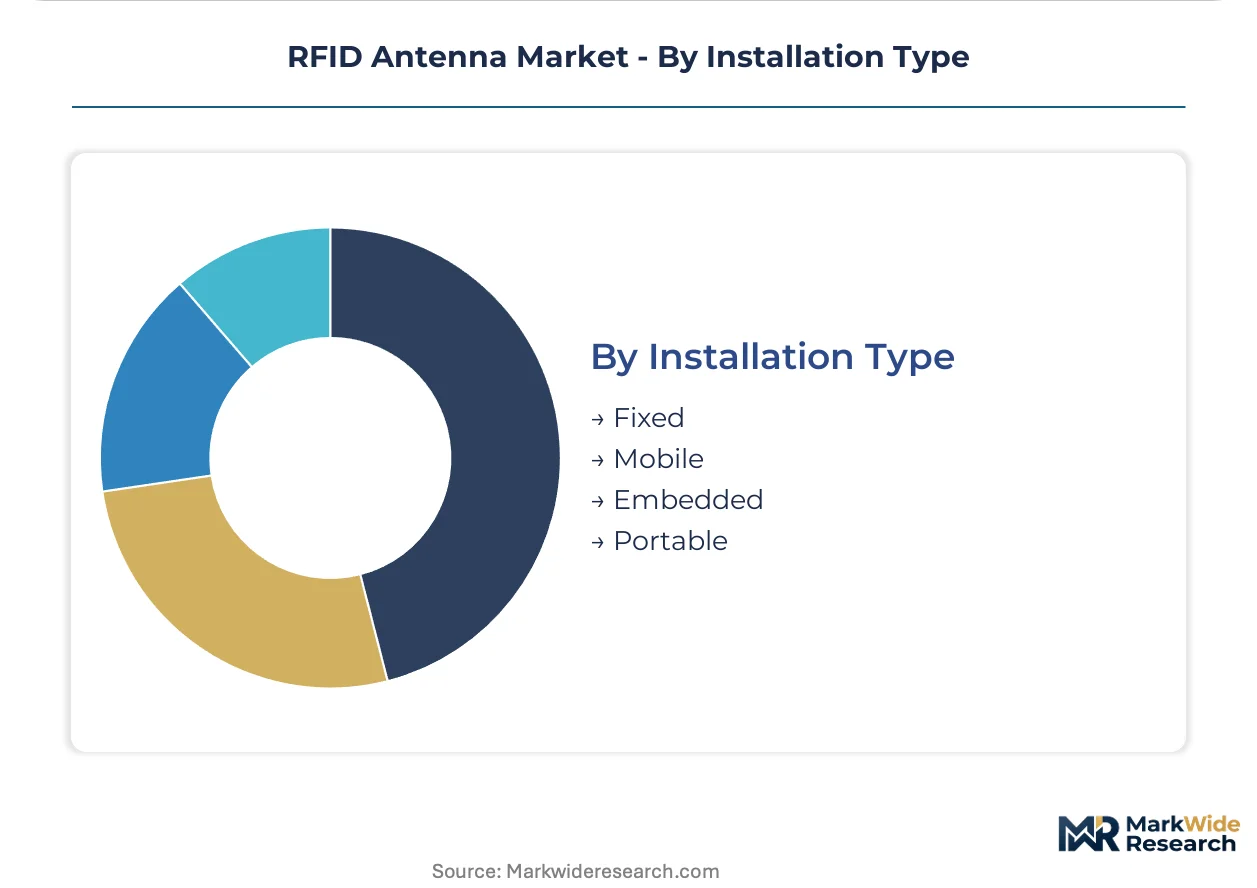
| Segmentation | Product Type: Passive Antennas, Active Antennas, Semi-Passive Antennas, Integrated Antennas Technology: UHF, HF, LF, Microwave End User: Retail, Logistics, Healthcare, Manufacturing Installation Type: Fixed, Mobile, Embedded, Portable |
| Companies Covered | Zebra Technologies Corp., TE Connectivity, Impinj, Inc., NXP Semiconductors, GAO RFID Inc., Avery Dennison, Honeywell International Inc., Invengo Information Technology Co., Ltd., Times-7, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RFID Antenna Market Strategic Shifts
Antenna architecture is fragmenting across application-specific gain profiles and embedded integration requirements, displacing universal-form-factor dominance.
Printed electronics manufacturing is modularizing antenna production workflows. Conductive ink deposition on flexible substrates enables conformal antenna geometries for curved packaging and wearable applications. Apparel and pharmaceutical packaging converters are adopting roll-to-roll antenna fabrication at pilot scale. This manufacturing shift is modularizing supply chain relationships between antenna designers and label converters.
ETSI EN 302 208 listen-before-talk protocol enforcement is tightening radiation pattern specifications for European logistics deployments. Antenna manufacturers must embed frequency-hopping agility to maintain read-range performance under reduced duty-cycle limits. German automotive suppliers and French pharmaceutical distributors face the steepest compliance recertification burdens.
Buyer concentration among omnichannel retailers is compressing antenna vendor qualification cycles. Tier-one distributors now demand guaranteed gain deviation thresholds and multi-year supply commitments before hardware approval. North American big-box retail and Chinese e-commerce fulfillment networks drive this procurement intensity.
RFID Antenna Market Segmentation
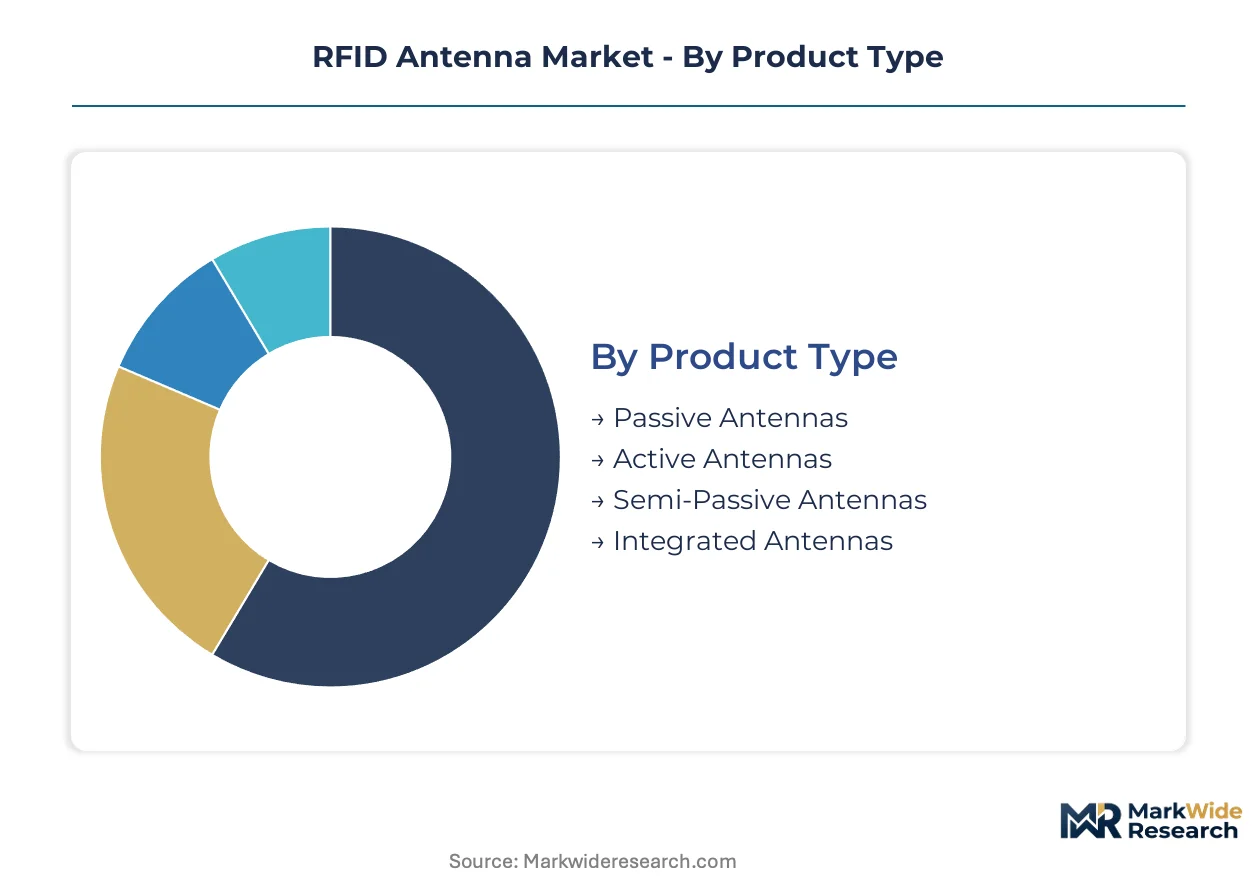
Antenna procurement decisions in this market pivot on power sourcing, frequency band, deployment environment, and physical integration requirements. Buyers weight total cost of ownership against read-range performance and regulatory compliance across their specific operational geographies.
Product Type:
Cost tier determines the bulk of purchasing volume, with passive configurations dominating high-volume retail and logistics contracts.
- Passive Antennas:These transducers harvest energy from the interrogator signal to power tag communication, eliminating battery maintenance. Retail inventory management in North American distribution centers and European apparel chains pulls the majority of unit demand toward this segment due to lowest per-unit cost and unlimited operational lifespan.
- Active Antennas:Incorporating onboard power sources, these configurations deliver extended read ranges exceeding 100 meters for real-time location systems in yard management and container tracking. Cold chain monitoring in pharmaceutical logistics and high-value asset tracking in oil and gas operations concentrate demand here despite higher unit economics.
- Semi-Passive Antennas:Hybrid designs using battery-assisted backscatter for sensor-enabled applications.
- Integrated Antennas:RF front-ends embedded directly into OEM equipment housings, capturing margin pools through design-in relationships.
Volume sits with Passive Antennas; growth tilts toward Integrated Antennas as smart factory deployments accelerate embedded RF requirements.
Technology:
Application requirements around read range, penetration capability, and regulatory band availability shape technology selection.
- UHF:Operating across 860–960 MHz with 6–12 dBi gain specifications, this band enables non-contact identification at distances up to 12 meters for pallet-level tracking. Logistics automation in Chinese manufacturing clusters around Shenzhen and Shanghai, plus North American retail distribution networks, drive the steepest expansion trajectory for this segment.
- HF:Near-field coupling at 13.56 MHz delivers shorter read ranges with superior security for payment and pharmaceutical authentication applications. European pharmaceutical serialization mandates under the EU Falsified Medicines Directive sustain deployment concentration here despite UHF logistics dominance.
- LF:Low-frequency operation provides reliable performance in liquid-rich and metal-heavy environments for animal identification and industrial automation.
- Microwave:2.45 GHz and 5.8 GHz bands support specialized applications requiring high data rates or anti-collision performance in dense tag environments.
Logistics procurement favors UHF; pharmaceutical authentication anchors HF demand.
End User:
Customer operational models determine antenna specification priorities, from read-density requirements to environmental hardening.
- Retail:Omnichannel inventory visibility demands UHF passive antenna deployment across back-of-store, sales floor, and fulfillment network nodes. German big-box retailers and Chinese e-commerce fulfillment networks compress vendor qualification cycles with guaranteed gain deviation thresholds.
- Logistics:Automated material handling and yard management require frequency-agile antenna architectures. Indian logistics modernization under PLI scheme subsidies creates localized production opportunities serving domestic demand.
- Healthcare:Asset tracking convergence with BLE beacon networks opens hospital equipment visibility applications requiring hybrid antenna architectures.
- Manufacturing:Work-in-process tracking and automated guided vehicle integration demand embedded antenna form factors.
Retail commands current procurement volume; healthcare asset tracking expands most quickly through hybrid RAIN-BLE architectures.
Installation Type:
Physical deployment constraints and mobility requirements differentiate antenna mounting and connectivity approaches.
- Fixed:Permanent mounting at dock doors, conveyor transitions, and storage zones provides continuous coverage for automated inventory tracking. Brownfield warehouse management system retrofits complicate deployment timelines despite hardware readiness.
- Mobile:Handheld and vehicle-mounted configurations enable episodic inventory counts and exception handling in field service applications.
- Embedded:Direct integration into smart shelves, automated guided vehicles, and packaging machinery eliminates external antenna infrastructure. RF engineering talent scarcity delays optimization cycles for these OEM design-ins.
- Portable:Rapid-deployment kits for temporary asset audits and event-based tracking applications.
Fixed installations anchor current infrastructure spend; embedded configurations gain share fastest through smart factory integration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Shenzhen Special Economic Zone concentrates embedded antenna manufacturing capacity, pulling regional investment toward smart factory integration clusters across Guangdong Province.
United States
FCC Part 15 regulations govern unlicensed UHF operation and directly shape antenna power limits for retail distribution center deployments. Distribution automation investments by omnichannel retailers compress vendor qualification cycles with guaranteed gain deviation thresholds. The Dallas-Fort Worth logistics corridor anchors North American antenna procurement volume for automated material handling systems.
China
MIIT spectrum allocation frameworks and GB standards compliance requirements drive embedded antenna design specifications for manufacturing automation. Smart factory deployments across Shenzhen and Shanghai manufacturing clusters require integrated RF front-ends for work-in-process tracking. The Yangtze River Delta concentration of electronics OEMs accelerates design-in relationships for embedded antenna architectures.
Germany
ETSI EN 302 208 listen-before-talk protocols mandate frequency-hopping agility in antenna designs for European logistics compliance. Automotive suppliers and pharmaceutical distributors face steep recertification burdens under tightened radiation pattern specifications. The Stuttgart industrial corridor concentrates demand for UHF passive configurations serving automated guided vehicle integration.
India
PLI scheme subsidies for electronics manufacturing create localized antenna production opportunities serving domestic logistics modernization. TRAI spectrum management frameworks shape UHF deployment parameters for warehouse automation projects. The Maharashtra industrial belt around Pune anchors pilot-scale rollouts for retail inventory tracking infrastructure.
Japan
METI industrial digitization programs accelerate embedded antenna adoption for precision manufacturing traceability requirements. JIS standards compliance shapes antenna form factor specifications for automotive and electronics OEM integration. The Nagoya manufacturing cluster concentrates demand for hybrid RAIN-BLE antenna architectures in smart factory deployments.
RFID Antenna Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with end-to-end solution providers anchoring retail deployment contracts while component specialists capture design-in relationships with OEM equipment builders. The vendor base organizes around three strategic archetypes: integrated platform providers spanning hardware and software stacks, silicon-antenna interface specialists concentrating R&D at the chip connectivity layer, and regional fabricators serving localized logistics modernization programs. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as players seek to secure multi-year supply commitments from tier-one distributors.
Among North American platform providers, Zebra Technologies Corp. and Impinj, Inc. occupy positions representing the integrated solution and silicon connectivity archetypes respectively. Zebra Technologies Corp. anchors hardware deployment relationships across distribution center networks through its end-to-end retail solutions footprint. Impinj, Inc. exemplifies the specialist tier with concentrated R&D intensity at the RAIN RFID chip-antenna interface. Invengo Information Technology Co., Ltd. represents the Asia-Pacific regional fabricator archetype, with its corporate structure indicating Chinese market orientation and manufacturing corridor proximity.
| Leading Market Players |
|---|
| Zebra Technologies Corp. |
| TE Connectivity |
| Impinj, Inc. |
| NXP Semiconductors |
| GAO RFID Inc. |
| Avery Dennison |
| Honeywell International Inc. |
| Invengo Information Technology Co., Ltd. |
| Times-7 |
| Others |
Value Chain & Pricing Dynamics
EU Falsified Medicines Directive serialization mandates gate qualified supply for pharmaceutical-grade antenna configurations and sustain premium-tier pricing access for HF-certified manufacturers serving European pharmaceutical distributors. Copper and ferrite substrate cost volatility compresses margin pools across passive UHF producers while embedding sustainability compliance into supplier qualification criteria.
Pricing Analysis
Short lead-time premiums of 15-25% apply to antenna configurations with guaranteed four-week delivery windows, while spot inventory from regional distributors trades at standard contract rates. Three-tier pricing structure across premium certified-grade, standard commercial-grade, and economy unbranded tiers separates EPCglobal Gen 2 validated products from uncertified alternatives. Cost compression in economy-tier passive antennas intensifies because Chinese manufacturing clusters expand high-volume output. Small-format retailers and last-mile logistics operators exhibit highest price sensitivity, while automotive OEMs and pharmaceutical distributors demonstrate lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Shanghai, and Stuttgart anchor hub-and-spoke patterns for antenna component logistics, with secondary nodes in Dallas-Fort Worth and Pune serving continental fulfillment. Manufacturing concentration rests on China, Germany, and the United States for finished antenna production, with Taiwan and South Korea supplying RF front-end semiconductors. Copper coil substrates, ferrite magnetic cores, and polyimide flexible laminates constitute critical input dependencies. Single-source vulnerability in rare-earth ferrite processing from Chinese refiners poses structural risk. Distribution runs through authorized distributor networks and direct OEM design-in channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RF engineering talent scarcity props antenna pricing by constraining qualified design capacity and extending optimization cycles for integrated OEM deployments.
For Market Incumbents: Deepen backward integration into ferrite core substrate production to defend against copper cost volatility and secure supply continuity for high-gain UHF configurations. Expand certification laboratory capacity in Germany and the United States to compress EPCglobal Gen 2 compliance timelines and accelerate product launch schedules. For New Entrants and Emerging Players: Enter via India's PLI-subsidized electronics manufacturing corridors to capture domestic logistics modernization demand with localized cost structures. Target hybrid RAIN-BLE antenna architectures for healthcare asset tracking convergence, deploying through embedded-systems marketplaces to bypass established distributor relationships. For Investors and Strategic Acquirers: Multi-year supply commitment announcements from tier-one omnichannel retailers are the leading indicator that antenna vendor consolidation windows are opening. Position acquisition screening around mid-cap specialists with captive RF simulation talent and established MIIT or FCC certification track records. Watch for ETSI-FCC spectral harmonization progress as the signal for reduced SKU fragmentation and improved margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| RF Engineering Talent Acquisition | Captures scarce electromagnetic simulation capacity to accelerate OEM design-in cycles. |
| Regional Certification Laboratory Expansion | Reduces EPCglobal Gen 2 compliance timelines by 4-6 months for new antenna form factors. |
| Backward Integration into Ferrite Processing | Insulates margin pools from rare-earth supply concentration in Chinese refineries. |
| Hybrid RAIN-BLE Architecture Development | Opens hospital equipment visibility applications requiring converged antenna connectivity. |
| Direct-to-Installer Channel Buildout | Bypasses traditional distribution friction for mid-sized OEM integrators through embedded-systems marketplaces. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with antenna design engineers, RFID systems integrators, retail procurement directors, pharmaceutical supply chain managers, and smart factory automation leads. EPCglobal certification databases, FCC equipment authorization records, ETSI harmonized standard documents, and MIIT radio transmission equipment approvals provided compliance tracking foundations. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Data-stream reconciliation across antenna unit production volumes, regional regulatory approval counts, and end-user deployment announcements shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include power sourcing architecture, frequency band specification, end-use vertical, installation type, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to validated baseline estimates, with cross-reference to smart factory capital expenditure trajectories and retail automation investment cycles.
Revisions become necessary when ETSI-FCC spectral harmonization stalls, copper and ferrite commodity prices experience sustained volatility, or barcode imaging systems achieve cost parity in logistics applications. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
RF Mixers Market
RF Components
Silicon Tuners Market
RF Components
US RFID Tags Market
RF Components
RF Semiconductor Market
RF Components
Analog Phase Shifter Market
RF Components
Millimeter Wave Equipment Market
RF Components
RF Transceiver Chip Market
RF Components
5G Millimeter Wave RF Transceiver Market
RF Components
Global Bulk Acoustic Wave (BAW) Filters Market
RF Components
EMI Microwave Absorber Market
RF Components
Radio Frequency Components Market
RF Components
5G Gain Block Amplifier Market
RF Components
Gaas RF Switch Market
RF Components
RF Switches Market
RF Components
Tunable Inductors Market
RF Components
RF Front End Module Market