
 Smart Antenna Market | 2026-2036
Smart Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Antenna Market Intelligence
The smart antenna market is recalibrating around a widening split between premium phased array systems for defense and telecommunications and commodity-level Wi-Fi antennas for consumer electronics. Winegard leverages its manufacturing scale to dominate the North American residential antenna segment. Antennas Direct competes through specialized outdoor directional designs that sustain brand loyalty among cord-cutting households. Mohu anchors the indoor flat antenna category with streamlined aesthetics that appeal to urban consumers.
Smart antennas integrate multiple radiating elements with digital signal processing to dynamically steer, shape, or adapt RF beams for optimized connectivity, with typical phased arrays operating across sub-6 GHz and mmWave bands for 5G base stations. MIMO antenna configurations lead in telecommunications infrastructure due to their proven spectral efficiency gains, while beamforming technology captures expanding margin pools in defense radar and satellite ground terminals. Adaptive antennas remain a smaller segment but show structural promise for automotive V2X applications where real-time environment sensing demands continuous pattern adjustment.
The FCC governs spectrum licensing and device certification in the United States, directly shaping product roadmaps through millimeter-wave auction rules and open RAN incentives. ETSI and 3GPP standards in Europe enforce interoperability benchmarks that determine market access for cross-border equipment vendors. Stakeholders must monitor evolving national spectrum strategies and open interface mandates to anticipate which antenna architectures will secure procurement preference in next-generation network rollouts.
Market Dynamics
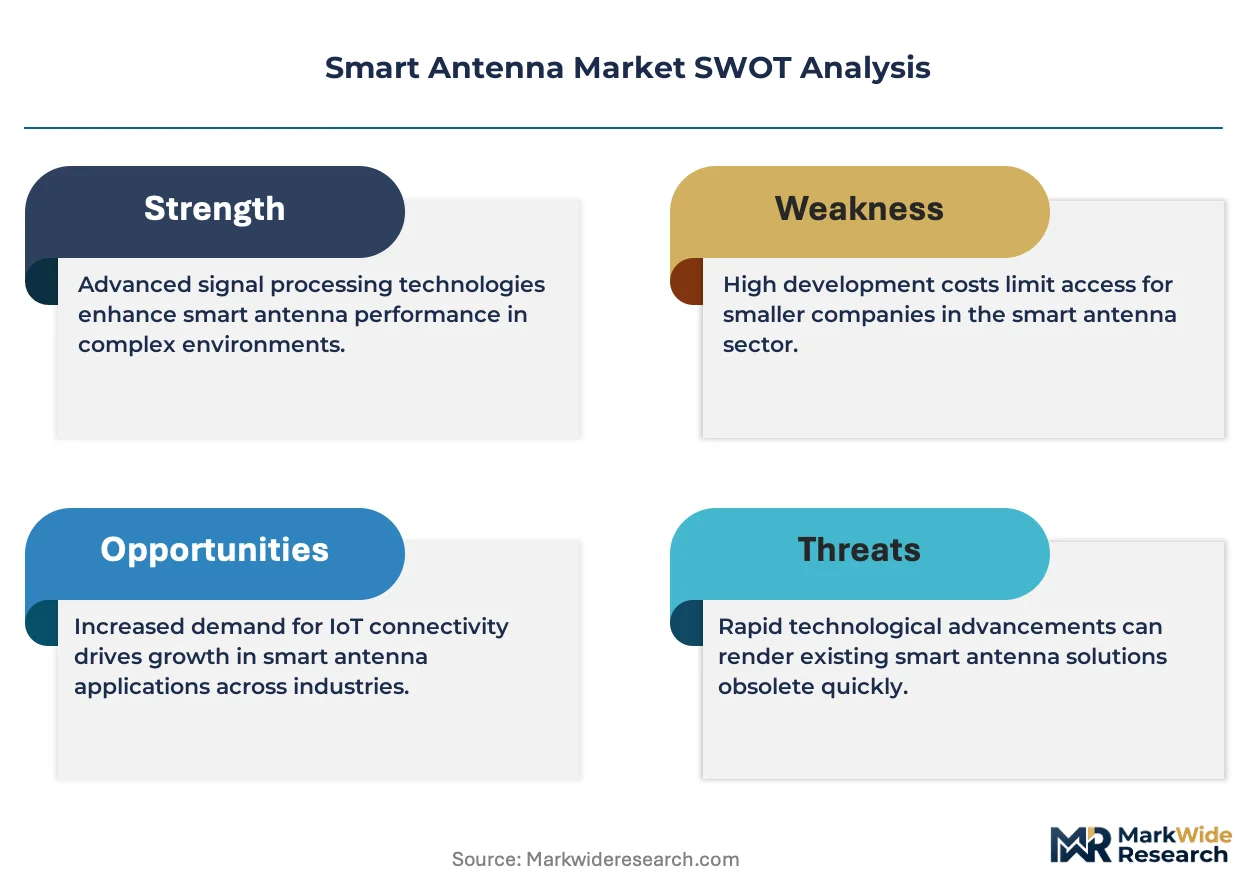
The smart antenna market is bifurcating sharply between high-performance phased arrays for 5G infrastructure and cost-optimized designs for consumer electronics, with beamforming algorithms becoming the primary battleground for differentiation.
Growth Catalysts
- Millimeter-wave spectrum auctions:The FCC's ongoing allocation of 24-47 GHz bands compels carriers to deploy dense small-cell grids requiring advanced beam-steering capabilities.
- Defense modernization cycles:Electronic warfare programs across NATO member states are procuring software-defined phased arrays for radar and communications jamming resilience.
- Automotive V2X mandates:Connected vehicle regulations in Germany and Japan are mandating C-V2X compatibility, driving demand for adaptive antenna modules.
Market Restraints
- Gallium nitride substrate costs:Wafer shortages for GaN-on-SiC RF power amplifiers constrain output from specialized foundries in Japan and the United States.
- Patent thickets in beamforming:Intellectual property concentration among three US defense contractors blocks licensing access for commercial entrants.
- Copper and rare earth volatility:Magnet supply chains from China's processing facilities create input cost instability for ferrite-based antenna components.
Strategic Opportunities
- Open RAN interface mandates:The FCC's interoperability incentives are creating procurement preference for disaggregated antenna-radio units from non-incumbent vendors.
- Satellite ground terminal expansion:Low-earth orbit constellation operators in the United States require flat-panel phased arrays for consumer broadband dishes.
- AI-driven pattern optimization:Machine learning inference at the edge is integrating with adaptive arrays to enable real-time null-steering against interference.
Industry Challenges
- RF engineer scarcity:Specialized electromagnetic simulation expertise for mmWave design remains concentrated among aging workforces in California and Massachusetts.
- Multi-band certification timelines:FCC and ETSI testing protocols for simultaneous sub-6 GHz and mmWave operation extend product launch cycles by 8-14 months.
- Legacy base station integration:Retrofitting existing 4G towers with active antenna systems demands structural reinforcement and power supply upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Antenna Market |
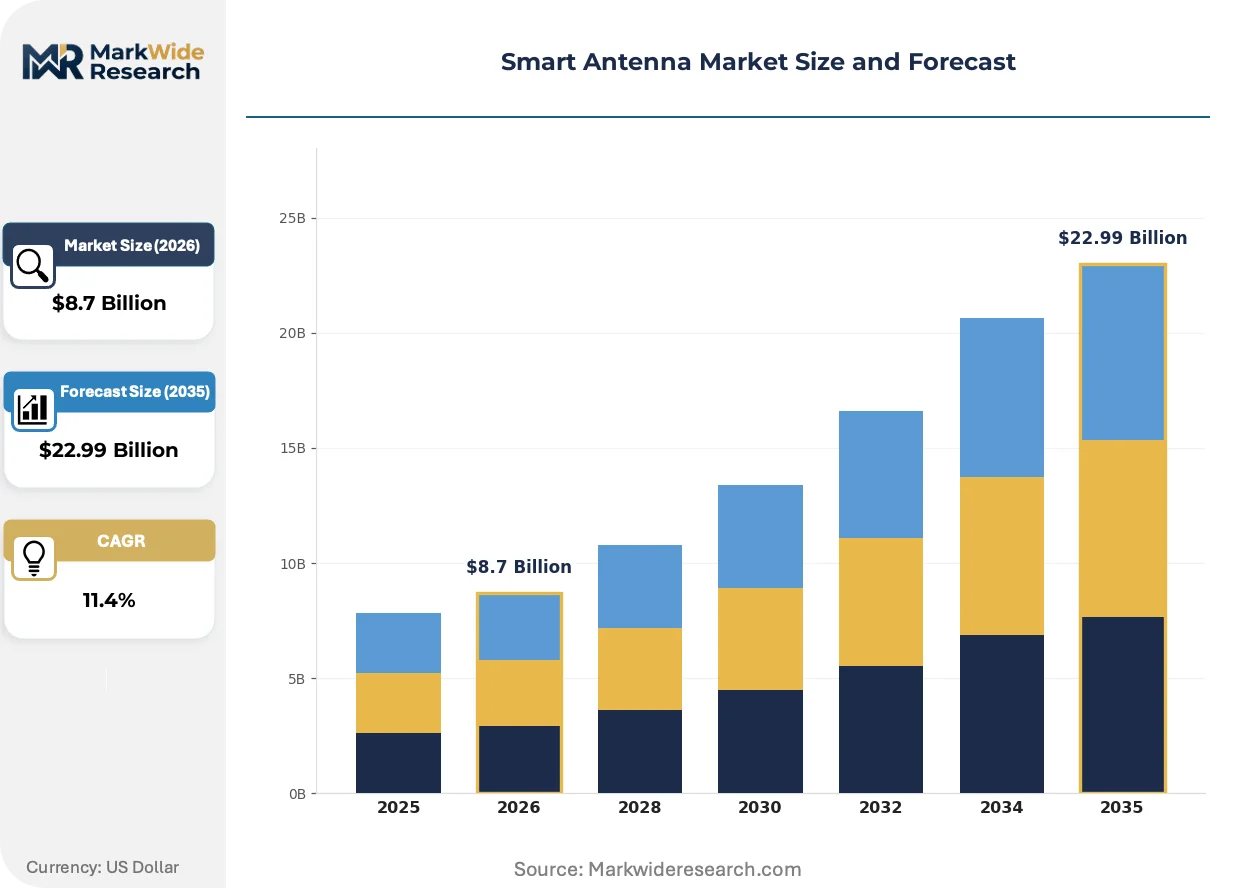
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phased Array Antennas, MIMO Antennas, Adaptive Antennas, Beamforming Antennas Application: Telecommunications, Satellite Communications, Defense, Automotive Technology: 5G Technology, LTE Technology, Wi-Fi Technology, Bluetooth Technology End User: Network Operators, Military, Automotive Manufacturers, Consumer Electronics |
| Companies Covered | Winegard, Best Buy Essentials, Antennas Direct, Mohu Leaf, Televes, Mohu, Antop, ClearStream, Channel Master, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Antenna Market Strategic Shifts & Innovations
Digital beamforming is displacing analog architectures across telecommunications infrastructure, while semiconductor packaging advances compress module footprints for mobile platforms.
Metamaterial surfaces are integrating tunable electromagnetic properties that enable frequency-agile antenna apertures without mechanical steering. Defense contractors in the United States and Sweden are adopting these structures for conformal radar installations on unmanned aerial platforms. This integration is compressing the tradeoff between antenna gain and physical volume that has constrained airborne applications.
The EU AI Act's risk classification framework is mandating transparency in autonomous RF decision-making for safety-critical communications infrastructure. Equipment vendors must now document beam-steering logic for certification in European 5G networks. Germany's Federal Network Agency is enforcing these provisions most stringently, delaying approvals for black-box adaptive algorithms.
Enterprise buyers are consolidating procurement through systems integrators rather than sourcing antennas as discrete components. Network operators in South Korea and Japan are bundling antenna-radio units into single-vendor managed service contracts. This concentration is squeezing standalone antenna manufacturers and favoring vertically integrated equipment suppliers with software capabilities.
Smart Antenna Market Segmentation
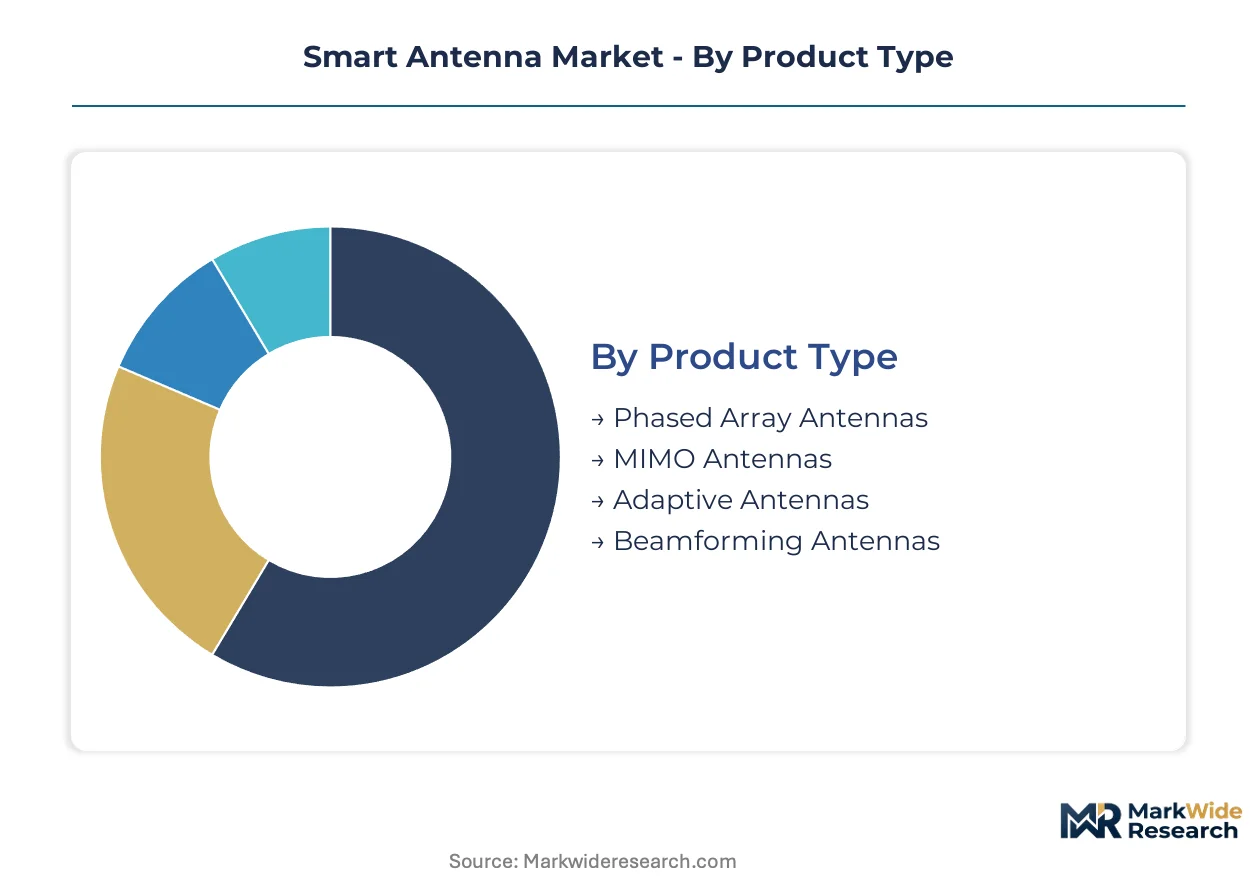
Smart antenna procurement decisions hinge on performance specifications, spectrum compatibility, and integration complexity. Buyers across telecommunications, defense, and automotive sectors evaluate architectures against distinct operational requirements and total cost of ownership constraints.
Product Type:
Buyers select antenna architectures based on beam-steering precision requirements and power budget constraints for their deployment environments.
- Phased Array Antennas:These architectures deploy multiple radiating elements with phase-shifting networks to electronically steer beams without mechanical movement. Defense radar installations in the United States and satellite ground terminals drive procurement volumes, with GaN-on-SiC substrates enabling higher power density for mmWave operation.
- MIMO Antennas:Multiple-input multiple-output configurations exploit spatial multiplexing to multiply spectral efficiency in dense urban environments. 5G base station buildouts in China concentrate demand, as carriers deploy massive MIMO arrays to manage high subscriber density with limited spectrum allocation.
- Adaptive Antennas:Real-time pattern adjustment algorithms respond to environmental interference and platform motion. Automotive V2X modules in Germany incorporate these systems for reliable connectivity during high-speed maneuvers.
- Beamforming Antennas:Signal processing techniques focus energy toward intended receivers while suppressing interference in unintended directions. Enterprise Wi-Fi infrastructure in Japan adopts these designs for high-density office deployments.
Phased Array Antennas lead on scale; Adaptive Antennas lead on momentum.
Application:
Application selection correlates directly with spectrum licensing regimes and capital expenditure cycles across end-use industries.
- Telecommunications:Cellular infrastructure deployment accounts for the dominant revenue share, with carriers upgrading macro towers and deploying small-cell grids. FCC spectrum auctions in the United States and MIIT licensing in China determine equipment procurement timelines.
- Satellite Communications:Low-earth orbit constellation operators require flat-panel phased arrays for consumer broadband terminals. Ground station buildouts in the United States and Sweden concentrate manufacturing demand for steerable Ka-band systems.
- Defense:Electronic warfare and radar modernization programs prioritize software-defined architectures with rapid frequency hopping. NATO member states procure conformal arrays for unmanned aerial platforms.
- Automotive:Connected vehicle mandates in Germany and Japan drive C-V2X module integration. Adaptive beam steering compensates for vehicle motion and multipath interference in urban canyons.
Telecommunications dominates volume; Satellite Communications exhibits the steepest expansion trajectory.
Technology:
Technology adoption tracks cellular generation transitions and unlicensed spectrum utilization patterns in target deployment scenarios.
- 5G Technology:Sub-6 GHz and mmWave implementations demand advanced beam management and massive MIMO configurations. Network operators in South Korea and Japan lead deployment velocity for enhanced mobile broadband and ultra-reliable low-latency services.
- LTE Technology:Legacy 4G infrastructure continues requiring antenna upgrades for capacity expansion and spectral efficiency gains. Rural coverage extensions in India rely on cost-optimized LTE antenna systems.
- Wi-Fi Technology:IEEE 802.11ax and emerging 802.11be standards drive enterprise and residential access point refresh cycles. High-density venue deployments in the United States adopt beamforming for interference mitigation.
- Bluetooth Technology:Direction-finding capabilities in Bluetooth 5.1 and 5.3 enable indoor positioning and asset tracking applications. Smart building installations in Japan integrate angle-of-arrival antenna arrays.
5G Technology commands premium pricing; Wi-Fi Technology delivers the broadest installed base expansion.
End User:
End-user procurement patterns diverge sharply between centralized network infrastructure buyers and distributed consumer electronics manufacturers.
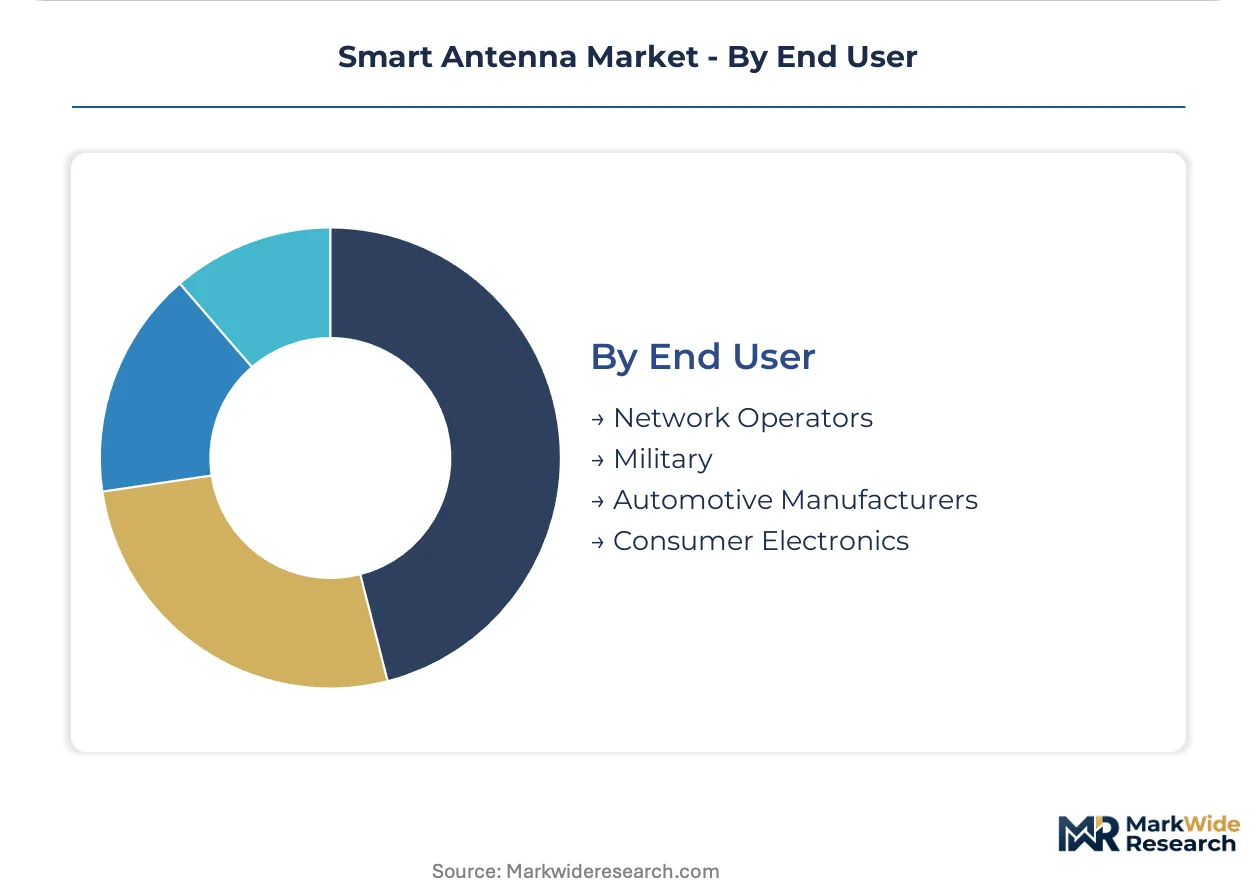
- Network Operators:Mobile carriers and fixed wireless access providers issue large-scale tenders for active antenna systems with integrated radio units. Open RAN interoperability requirements from the FCC influence vendor selection criteria in the United States.
- Military:Defense procurement emphasizes software-defined flexibility and electronic warfare resilience. Electronic warfare programs across NATO member states specify conformal phased arrays with rapid reconfiguration capabilities.
- Automotive Manufacturers:Tier-1 suppliers integrate antenna modules into vehicle telematics and infotainment systems. German and Japanese OEMs mandate C-V2X compatibility for new vehicle platforms.
- Consumer Electronics:Smartphone, tablet, and laptop manufacturers specify compact multi-band antenna designs. Manufacturing concentration in China drives volume procurement for Wi-Fi and Bluetooth antenna modules.
Network Operators generate the largest contract values; Automotive Manufacturers show the most rapid adoption acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF engineering talent clusters in California and Massachusetts anchor antenna design capabilities, while manufacturing scale concentrates in Shenzhen and Dongguan. Spectrum regulators in multiple jurisdictions are accelerating infrastructure deployment timelines.
United States
FCC millimeter-wave auctions and Open RAN incentives drive carrier procurement of active antenna systems. The regulator's 24-47 GHz band allocations compel dense small-cell grid deployment. Silicon Valley hosts software-defined radio startups integrating AI-driven beam optimization.
China
MIIT licensing for 5G base station buildouts sustains massive MIMO array demand from state-owned carriers. The ministry's spectrum coordination policies prioritize sub-6 GHz infrastructure density. Dongguan manufacturing corridors supply ferrite components and phased array modules to domestic equipment vendors.
Germany
Automotive V2X mandates from the Federal Network Agency require C-V2X-compatible adaptive antennas in new vehicle platforms. The EU AI Act's risk classification framework delays certification for black-box beam-steering algorithms. Stuttgart engineering centers develop conformal arrays for automotive integration.
Japan
METI directs R&D funding toward satellite ground terminals for low-earth orbit broadband services. The ministry's connectivity targets accelerate Ka-band flat-panel phased array procurement. Nagoya industrial clusters manufacture compact beamforming modules for enterprise Wi-Fi infrastructure.
South Korea
Network operators bundle antenna-radio units into managed service contracts under government 5G penetration targets. The Korea Communications Commission enforces interoperability benchmarks for equipment vendors. Seoul Capital Area hosts system integrators consolidating enterprise procurement decisions.
Smart Antenna Market Key Industry Players
Top-tier vendors anchor defense and telecommunications infrastructure, while consumer electronics specialists compete on manufacturing scale and retail channel presence. The market structure separates premium phased array developers from cost-optimized residential antenna fabricators. Three archetypes dominate: semiconductor-integrated equipment suppliers, specialized defense contractors, and consumer-facing electronics brands. Competitive moves concentrate on strategic partnerships for Open RAN compliance and backward integration into GaN-on-SiC substrate supply.
Among North American residential antenna specialists, Winegard, Antennas Direct, and Mohu occupy distinct positioning archetypes. Winegard exemplifies manufacturing scale advantages in outdoor directional systems. Antennas Direct represents specialized engineering focused on cord-cutting household retention. Mohu anchors the indoor flat antenna segment through industrial design differentiation for urban consumers.
| Leading Market Players |
|---|
| Winegard |
| Best Buy Essentials |
| Antennas Direct |
| Mohu Leaf |
| Televes |
| Mohu |
| Antop |
| ClearStream |
| Channel Master |
| Others |
Cost & Logistics Intelligence
Network operator bundling of antenna-radio units into single-vendor managed service contracts is compressing margins for standalone component suppliers and forcing upstream foundries to absorb cost compression or risk volume displacement. This procurement consolidation is reshaping how GaN-on-SiC substrate pricing and ferrite component sourcing are negotiated across the supplier base.
Pricing Analysis
The bundled-versus-unbundled service split separates pricing models between integrated equipment suppliers and discrete antenna manufacturers. Three-tier pricing structure across defense-grade, telecommunications-certified, and consumer electronics tiers reflects certification level and volume scale differentiation. Pricing pressure stems from enterprise buyers consolidating procurement through systems integrators in South Korea and Japan. Consumer electronics manufacturers exhibit the highest price sensitivity due to manufacturing concentration in China, while defense contractors maintain lowest sensitivity given electronic warfare program budgets.
Supply Chain Analysis
Domestic-content mandates from the FCC's Open RAN incentives and China's MIIT localization policies are reshaping sourcing patterns for critical RF components. Manufacturing concentrates in China for ferrite processing and module assembly, Japan for GaN-on-SiC foundry capacity, and the United States for defense-grade phased array integration. Supply chains draw from gallium nitride wafers, rare earth magnets, and copper conductors. Single-source vulnerability in China's rare earth processing facilities creates structural exposure. Distribution runs through systems integrators and direct carrier procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on semiconductor packaging advances compressing module footprints and AI-driven pattern optimization commanding premium pricing for adaptive arrays.
For Market Incumbents: Anchor defense procurement relationships through software-defined architecture investments that satisfy NATO electronic warfare requirements. Deepen captive supply of GaN-on-SiC substrates to offset Japanese foundry pricing power. Counter emerging Chinese equipment vendors by accelerating Open RAN certification timelines. For New Entrants and Emerging Players: Begin with automotive V2X module supply to German and Japanese OEMs facing C-V2X mandates, where incumbent concentration remains lowest. Target flat-panel phased arrays for low-earth orbit satellite ground terminals as the most penetrable segment. Pursue direct partnerships with constellation operators bypassing systems integrator consolidation. For Investors and Strategic Acquirers: Asymmetric upside sits with semiconductor-integrated equipment suppliers possessing in-house beamforming algorithm development. Long-term viability favors vendors controlling both antenna hardware and radio software stacks. Monitor FCC millimeter-wave auction velocity as the signal indicating infrastructure procurement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Certification Investment | FCC interoperability incentives create procurement preference for disaggregated antenna-radio units from non-incumbent vendors. |
| GaN-on-SiC Substrate Integration | Backward integration into RF power amplifier supply reduces exposure to Japanese foundry pricing and wafer shortages. |
| AI-Driven Beam Optimization Development | Machine learning inference integration enables real-time null-steering against interference for premium defense and satellite applications. |
| Automotive V2X Module Partnership | C-V2X mandates in Germany and Japan create captive demand for adaptive antenna systems in next-generation vehicle platforms. |
| Satellite Ground Terminal Scale-Up | Low-earth orbit constellation operators in the United States require flat-panel phased arrays for consumer broadband dish manufacturing. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with RF engineering directors at defense contractors, procurement leads at network operators, antenna module specialists at automotive Tier-1 suppliers, and semiconductor foundry planning officers with secondary validation against FCC spectrum auction records, MIIT licensing disclosures, ETSI interoperability benchmarks, 3GPP standardization documents, and customs trade data for ferrite and rare earth magnet flows. Bottom-up component demand modeling and top-down infrastructure deployment projections were cross-referenced for triangulation.
Comparable historical reference periods anchored the forecast window across the projection horizon, with segmentation dimensions spanning product architecture, application vertical, cellular generation technology, and end-user procurement archetype. CAGRs were derived from installed base evolution and replacement cycle analysis. Industry-specific inputs included carrier capex disclosure patterns, defense modernization program announcements, and automotive platform electrification timelines.
Several conditions sit outside the modeled scope, including unannounced spectrum reallocation decisions, breakthroughs in alternative semiconductor substrates, and geopolitical disruptions to rare earth supply chains. Forecasts reflect documented assumptions about infrastructure deployment velocity and regulatory enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Toroid Inductor Market
RF Components
Radio Frequency Counter Market
RF Components
RFID Antenna Market
RF Components
RF Isolator Market
RF Components
Radio Frequency Front End Market
RF Components
Wi-Fi Module Market
RF Components
RF Acoustic Wave Filters Market
RF Components
Radiofrequency Identification (RFID) Market
RF Components
Global Inductors Market
RF Components
RF Tester Market
RF Components
Stand-Alone Radio Receivers Market
RF Components
UHF RFID Inlays Market
RF Components
China Small Signal Transistor Market
RF Components
433MHz Active RFID Reader Market
RF Components
RF Antenna Market
RF Components
RF Duplexer Market