
 Digital Radio Frequency Market | 2026-2036
Digital Radio Frequency Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Radio Frequency Market Analysis
A shortage of RF systems engineers is unwinding traditional development timelines across the defense electronics supply chain. Raytheon Company leverages captive semiconductor fabrication to sustain classified program delivery schedules. Northrop Grumman Corporation anchors its position through deep vertical integration in gallium nitride power amplifier technology. Thales Group competes across European NATO procurement channels with software-defined waveform portfolios.
Digital radio frequency denotes signal generation, conditioning, and processing architectures where analog waveforms are digitized at intermediate or radio frequencies, typically employing 12-bit to 16-bit resolution at sampling rates exceeding 1 GSPS for direct-conversion transceivers. These systems enable frequency-agile communications, electronic warfare, and radar operations by replacing analog hardware with reprogrammable digital signal processing. Transmitters and receivers command the largest installed base, though software-defined platforms represent the fastest-expanding margin pool as military customers demand multi-band, multi-mission flexibility. Amplifiers retain structural importance in high-power radar and satellite uplink chains, while hybrid analog-digital architectures persist in cost-sensitive broadcast infrastructure.
The FCC governs spectrum allocation and equipment authorization for commercial digital RF systems in the United States, while the EU AI Act and CE marking frameworks under ECHA influence component traceability for European defense integrators. Military end users face additional compliance layers from ITAR export controls and country-specific cryptographic module validations. Stakeholders must weigh sovereign supply chain requirements against the capital intensity of captive GaN and RF CMOS fabrication capacity.
Market Dynamics
The transition from hardware-defined to software-defined radio architectures is compressing product lifecycles and forcing capital reallocation across the defense electronics supply chain. This architectural shift demands simultaneous investment in high-speed data converters, FPGA fabrics, and RF front-end integration.
Growth Catalysts
- Defense procurement modernization:United States military programs are mandating multi-band, multi-mission radio platforms that require digital RF cores. Congressional appropriations for tactical communications modernization are accelerating fielding timelines.
- Spectrum reallocation mandates:The FCC's auction of C-band and 3.45 GHz spectrum is forcing commercial infrastructure operators to replace analog transmitters with digitally agile systems. Equipment refresh cycles are compressing from ten years to five.
- Gallium nitride maturation:GaN-on-SiC power amplifier technology is achieving price-performance parity with gallium arsenide in radar and satellite uplink applications. Foundry capacity expansion in the United States and Japan is easing supply constraints.
Market Restraints
- Semiconductor fabrication concentration:Advanced RF CMOS and GaN foundry capacity concentrates in Taiwan and the United States, creating single-source vulnerability for European and Asian defense integrators.
- ITAR export control friction:United States International Traffic in Arms Regulations restrict digital RF component transfers to allied nations, fragmenting procurement pools and duplicating qualification costs.
- High-resolution ADC cost structure:12-bit to 16-bit analog-to-digital converters sampling above 1 GSPS remain prohibitively expensive for cost-sensitive broadcast infrastructure, preserving hybrid analog-digital architectures.
Strategic Opportunities
- Dual-use technology convergence:Commercial 5G massive MIMO beamforming algorithms are migrating into military electronic warfare systems. Companies with footholds in both domains capture cross-subsidized R&D.
- India domestic manufacturing incentives:The country's Production Linked Incentive scheme for telecom equipment is attracting RF component assembly investments. Local value-add requirements favor joint ventures with established GaN foundries.
- LEO satellite constellation buildouts:Starlink and competing constellations demand phased-array terminals with digital beamforming at consumer price points. Volume scaling promises cost reduction for adjacent military applications.
Industry Challenges
- RF systems engineering scarcity:The specialized intersection of microwave design, digital signal processing, and embedded firmware lacks sufficient trained practitioners. Defense primes report 18-month hiring timelines for qualified architects.
- Multi-domain integration complexity:Software-defined radios must simultaneously support communications, electronic warfare, and signals intelligence waveforms. Verification and validation of concurrent operation modes consumes 40% of program schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Radio Frequency Market |
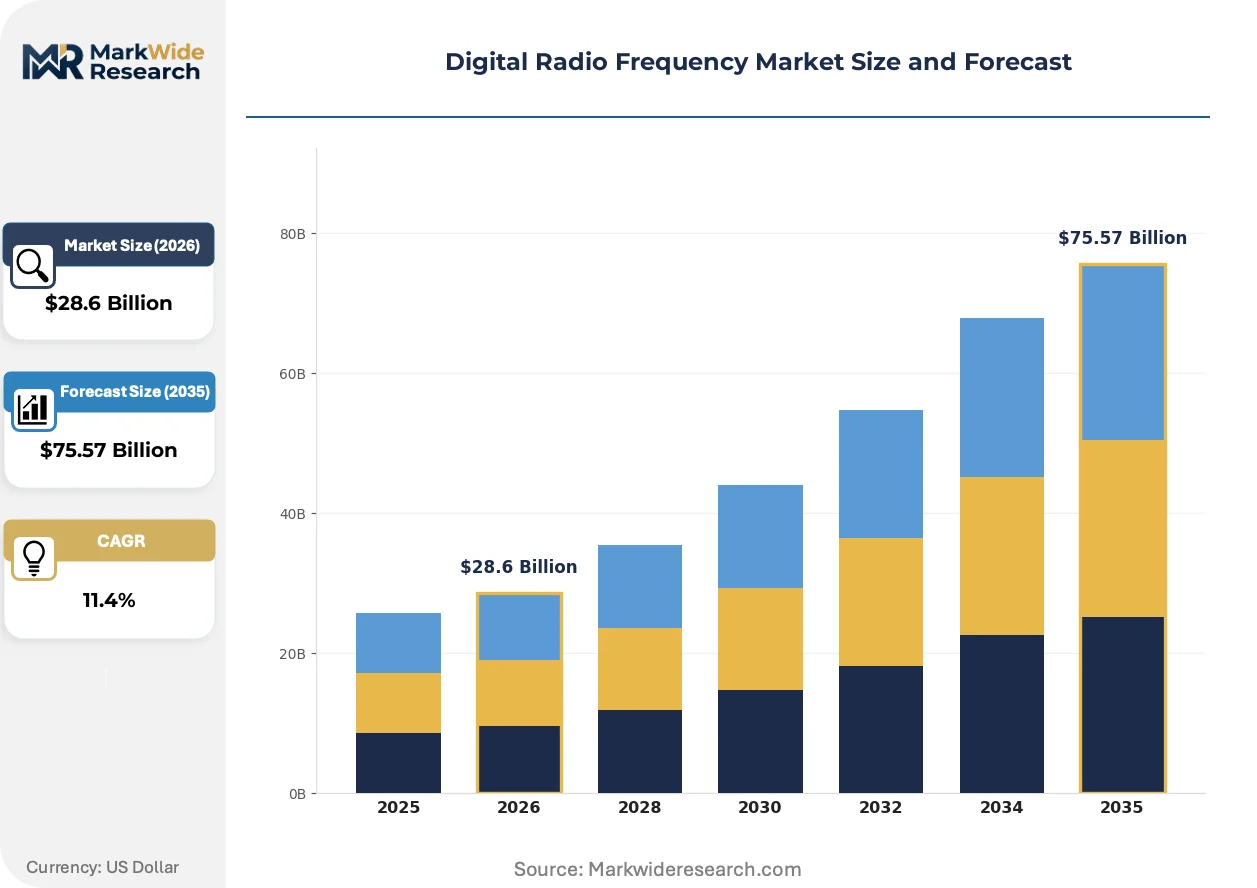
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transmitters, Receivers, Amplifiers, Processors Technology: Analog, Digital, Hybrid, Software-Defined End User: Defense, Telecommunications, Broadcast, Aerospace Application: Satellite Communications, Broadcasting, Military Operations, Scientific Research |
| Companies Covered | Raytheon Company, Northrop Grumman Corporation, Thales Group, BAE Systems, ROHDE & SCHWARZ, Israel Aerospace Industries Ltd., Airbus, Curtiss-Wright Corporation, Leonardo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Radio Frequency Market Emerging Trajectories
Direct RF sampling architectures are eliminating intermediate frequency stages and collapsing traditional transceiver form factors. This architectural simplification is redrawing competitive boundaries between analog component suppliers and digital processing vendors.
Direct digital synthesis at microwave frequencies is displacing traditional mixer-oscillator-filter chains in military and satellite communications hardware. Defense primes including the United States Navy's Next Generation Jammer program are adopting 14-bit, 3 GSPS converters for instantaneous bandwidth exceeding 1 GHz. This technology is displacing legacy superheterodyne architectures and compressing board area by 60% while enabling real-time waveform reconfiguration.
The European Union's Cyber Resilience Act and Radio Equipment Directive are imposing mandatory security-by-design requirements on RF equipment sold in member states. Manufacturers must demonstrate cryptographic module compliance and supply chain traceability under ECHA substance restrictions. Military integrators face the steepest compliance burden, as dual-use equipment must satisfy both CE marking and national cryptographic validation regimes.
Defense procurement offices are consolidating vendor relationships and demanding open architecture standards to reduce vendor lock-in. The United States Army's Handheld, Manpack, and Small Form Fit radio program is mandating modular open systems approach compliance, forcing incumbents to publish interface control documents. This behavioral shift is most visible in NATO procurement channels, where interoperability certification now precedes price evaluation in source selection.
Digital Radio Frequency Market Segmentation
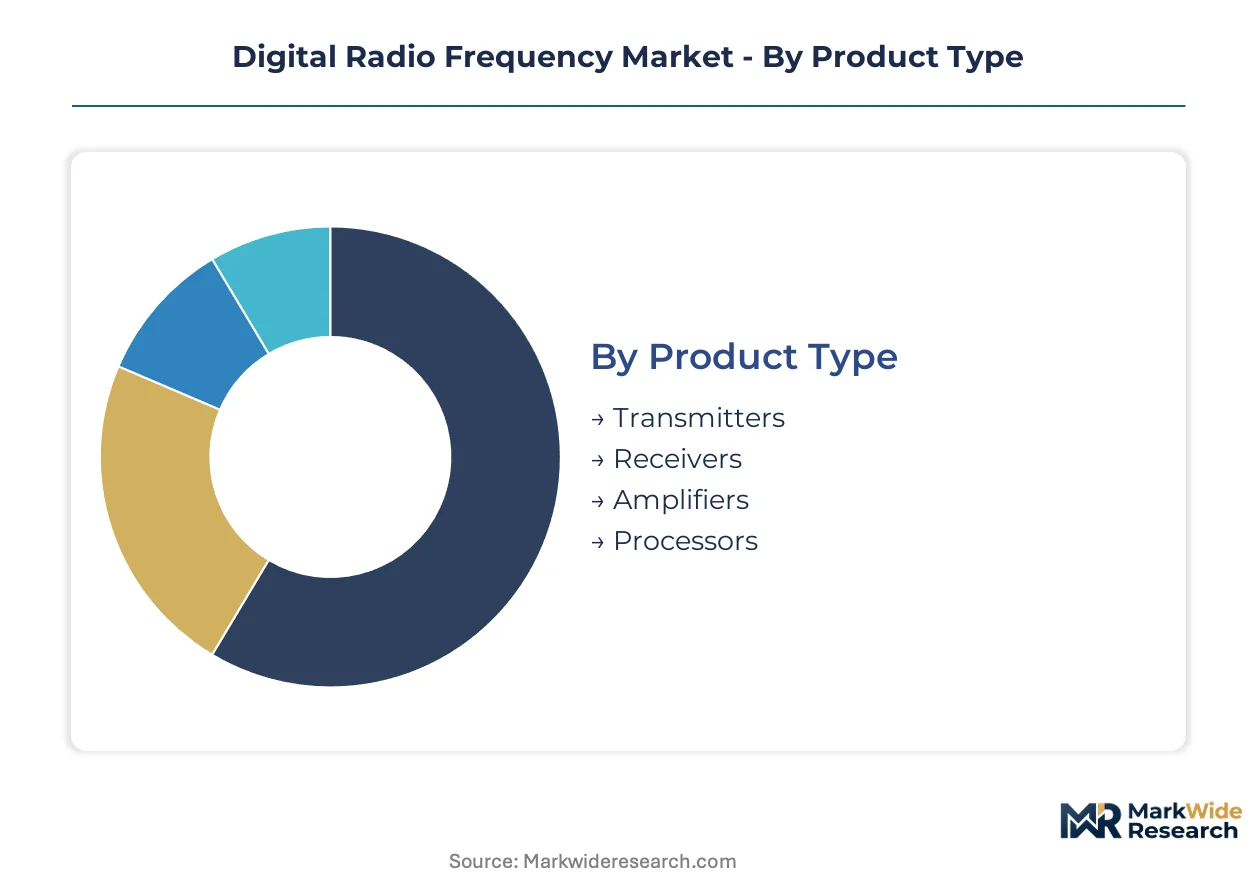
Digital radio frequency markets fragment along architectural boundaries that determine substitution risk and margin durability. Component-level segmentation reveals where analog hardware persists against digital encroachment, while end-user segmentation exposes divergent procurement cycles and compliance burdens.
Product Type:
Substitution pressure concentrates in transceiver components where software-defined architectures displace discrete hardware functions.
- Transmitters:These units convert baseband digital signals to RF power for radiation, employing direct digital synthesis or traditional upconversion chains. United States defense procurement for multi-band tactical radios sustains demand for 1-50 watt solid-state transmitters with embedded FPGA waveform engines.
- Receivers:Direct RF sampling receivers digitize signals at antenna frequencies using 12-16 bit ADCs sampling above 1 GSPS, eliminating mixer-oscillator stages. China's 5G infrastructure buildouts and satellite ground terminal programs absorb high volumes of compact receiver modules.
- Amplifiers:GaN-on-SiC power amplifiers achieve 40-60% efficiency in radar and satellite uplink chains. Foundry capacity constraints in Taiwan and the United States limit supply elasticity for defense-qualified devices.
- Processors:FPGA and SoC devices execute digital beamforming, modulation, and encryption in software-defined platforms. Broadcast infrastructure operators delay adoption due to high-resolution ADC cost structures.
Transmitters anchor the volume base while receivers gain share at the steepest rate.
Technology:
Cost tier stratification separates premium digital architectures from legacy analog systems serving price-sensitive broadcast markets.
- Analog:Superheterodyne architectures with discrete mixer-filter-oscillator chains persist in cost-driven broadcast transmitters and legacy military maintenance programs. Hybrid analog-digital designs dominate mid-tier commercial infrastructure where refresh cycles stretch to ten years.
- Digital:Direct RF sampling with high-speed data converters enables real-time reconfiguration across 1 GHz instantaneous bandwidth. The United States Navy's Next Generation Jammer program exemplifies procurement of 14-bit, 3 GSPS converter systems.
- Hybrid:Mixed-signal architectures partition functions between analog front-ends and digital back-ends, balancing performance against converter costs. European broadcast operators favor these configurations under ECHA substance restriction compliance timelines.
- Software-Defined:Fully programmable transceivers execute communications, electronic warfare, and signals intelligence waveforms through firmware updates. NATO procurement channels now mandate modular open systems approach compliance for these platforms.
Analog systems retain the widest installed base while software-defined platforms climb the fastest.
End User:
Customer type determines procurement rhythm, with defense programs running 18-36 month qualification cycles against commercial telecommunications' compressed refresh schedules.
- Defense:Military end users demand multi-band, multi-mission flexibility with ITAR-controlled supply chains. Congressional appropriations for United States tactical communications modernization accelerate fielding timelines for handheld, manpack, and small form fit radio programs.
- Telecommunications:5G massive MIMO deployments and C-band infrastructure replacement drive demand for digital beamforming components. FCC spectrum reallocation mandates compress equipment refresh cycles from ten years to five.
- Broadcast:Terrestrial and satellite broadcasters maintain hybrid analog-digital architectures due to ADC cost barriers. India's Production Linked Incentive scheme for telecom equipment diverts domestic manufacturing investment toward telecommunications over broadcast.
- Aerospace:Commercial aviation and satellite operators require phased-array terminals with digital beamforming at consumer price points. LEO constellation buildouts promise volume scaling for adjacent military applications.
Defense anchors procurement value while telecommunications expands most quickly.
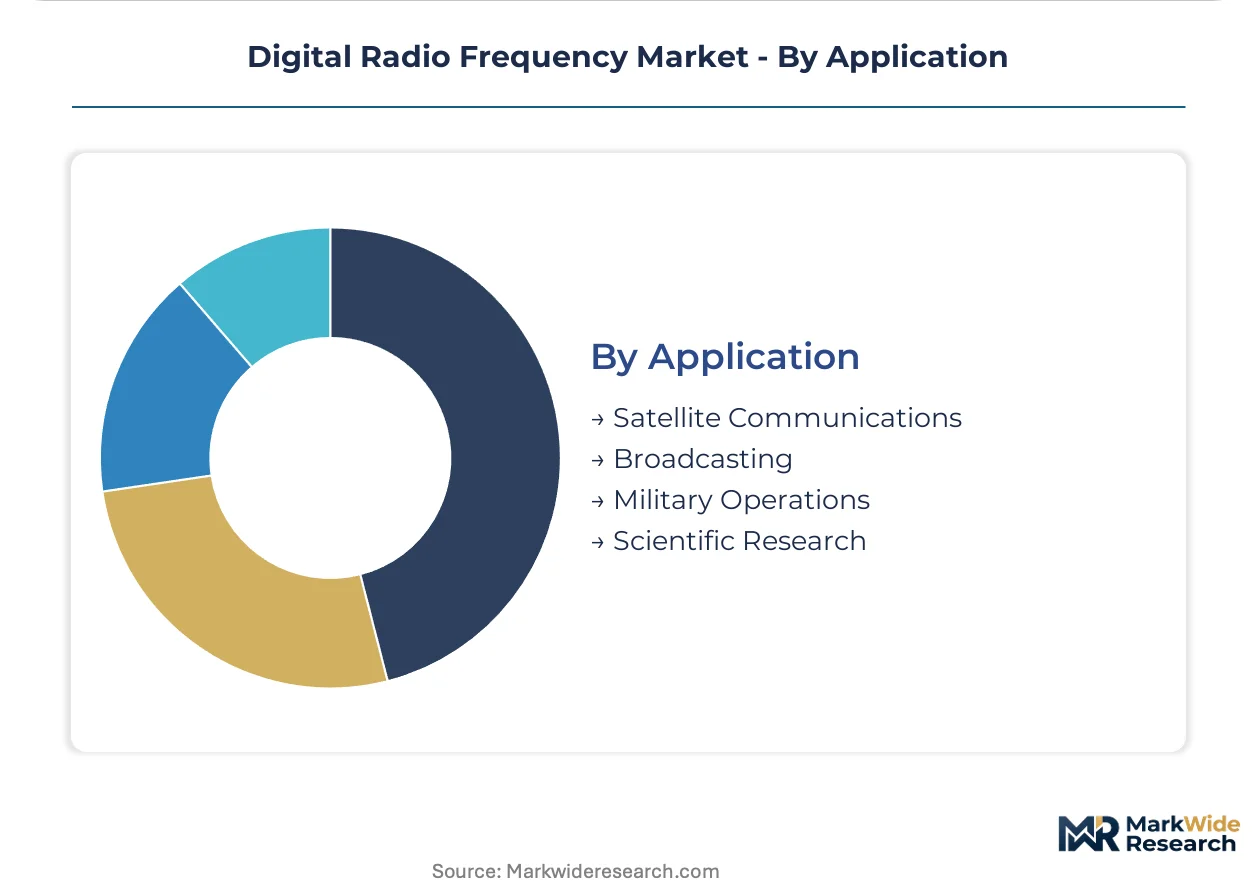
Application:
Application maturity varies sharply, with military operations commanding longest development timelines and scientific research presenting smallest addressable revenue pools.
- Satellite Communications:Phased-array user terminals for LEO constellations demand digital beamforming at mass-market price points. Starlink and competing programs drive GaN power amplifier miniaturization.
- Broadcasting:Terrestrial television and radio transmitters face FCC and EU Radio Equipment Directive compliance burdens for spectrum efficiency. Equipment refresh concentrates in C-band relocation markets.
- Military Operations:Electronic warfare, signals intelligence, and tactical communications converge on software-defined platforms. Verification and validation of concurrent operation modes consumes 40% of program schedules.
- Scientific Research:Radio astronomy and particle physics applications require ultra-low noise receivers with cryogenic amplification. Small order volumes limit supplier engagement.
Military operations anchor program complexity while satellite communications shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in digital RF systems concentrates in United States defense procurement channels, while Chinese domestic infrastructure buildouts extract cost efficiencies through scale manufacturing. This asymmetry shapes regional investment priorities and technology transfer patterns.
United States
Defense procurement modernization and C-band spectrum reallocation drive equipment refresh cycles. Congressional appropriations for tactical communications accelerate fielding timelines under FCC equipment authorization mandates. Boston-Cambridge and Dallas-Fort Worth clusters concentrate GaN foundry investments and software-defined radio development.
China
Domestic 5G massive MIMO deployments and satellite ground terminal programs absorb high volumes of receiver modules. MIIT spectrum allocation policies prioritize indigenous semiconductor fabrication capacity. Shenzhen and Shanghai manufacturing corridors scale phased-array terminal production for LEO constellation applications.
Germany
European NATO procurement channels and broadcast infrastructure replacement sustain hybrid analog-digital demand. CE marking and ECHA substance restrictions under EU Radio Equipment Directive impose compliance burdens. Munich and Stuttgart industrial clusters specialize in RF test equipment and automotive radar integration.
Japan
GaN-on-SiC foundry capacity expansion and satellite communications terminal exports anchor regional supply. METI industrial policy supports domestic RF semiconductor fabrication against Taiwan concentration risk. Tokyo-Yokohama and Osaka-Kobe corridors concentrate high-speed data converter packaging expertise.
India
Production Linked Incentive schemes for telecom equipment attract RF component assembly investments. TRAI spectrum auction timelines compress infrastructure deployment schedules. Bengaluru and Hyderabad technology corridors host joint ventures between domestic integrators and established GaN foundries.
Digital Radio Frequency Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. United States defense primes anchor premium-tier procurement through ITAR-controlled supply chains and classified program access. European integrators compete across NATO interoperability certification channels. Scale-oriented Asian manufacturers capture commercial telecommunications volume through foundry partnerships. Dominant competitive moves include captive semiconductor fabrication investments and modular open systems approach compliance for defense procurement.
Within the defense prime tier, Raytheon Company and Northrop Grumman Corporation exemplify technology leadership through vertical integration into classified supply chains. Thales Group occupies a position bridging European NATO procurement and dual-use commercial applications. These three entities represent distinct archetypes: captive fabrication dominance, GaN power amplifier specialization, and software-defined waveform portfolio breadth.
| Leading Market Players |
|---|
| Raytheon Company |
| Northrop Grumman Corporation |
| Thales Group |
| BAE Systems |
| ROHDE & SCHWARZ |
| Israel Aerospace Industries Ltd. |
| Airbus |
| Curtiss-Wright Corporation |
| Leonardo |
| Others |
Supply Flow & Price Mechanics
Eighteen-month hiring timelines for RF systems engineers compress development schedules and concentrate pricing power with captively integrated defense primes. This scarcity dynamic intersects with GaN foundry bottlenecks to stratify procurement costs across ITAR-controlled and commercial supply channels.
Pricing Analysis
Configured-to-order pricing for defense-qualified transmitters commands substantial premiums over standard commercial receiver modules. Three-tier pricing structure across ITAR-restricted, NATO-interoperable, and commercial-off-the-shelf levels reflects certification burden and volume scale differentiation. Cost compression in broadcast infrastructure tiers intensifies because high-resolution ADCs remain prohibitively expensive for hybrid architecture operators. Defense integrators exhibit lowest price sensitivity due to congressional appropriation security, while terrestrial broadcasters face acute budget constraints.
Supply Chain Analysis
Trans-Pacific container availability constraints elevate inbound logistics costs for GaN-on-SiC substrates and high-speed data converter packages. Manufacturing concentrates in Taiwan, the United States, and Japan for advanced RF CMOS and GaN foundry capacity. Production draws from silicon carbide wafers, rare-earth magnet materials, and multi-layer ceramic capacitors. Single-source vulnerability pervades European and Asian defense integrators lacking captive fabrication. Distribution runs through prime contractor-tiered subcontractor networks with ITAR-controlled material handling protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital Radio Frequency Market sits at a platform-economics inflection where modular open systems approach compliance restructures vendor lock-in dynamics. NATO procurement channels now mandate interoperability certification before price evaluation, creating ecosystem-level competitive barriers.
For Market Incumbents: Secure captive GaN foundry capacity in the United States or Japan to sustain classified program delivery against Taiwan concentration risk. Deepen software-defined waveform portfolios to defend against commercial 5G algorithm migration into electronic warfare applications. ITAR export control friction threatens to fragment procurement pools; accelerate joint venture structures with Indian domestic manufacturers under PLI scheme incentives. For New Entrants and Emerging Players: Differentiate on dual-use technology convergence by positioning 5G massive MIMO beamforming algorithms for military electronic warfare procurement channels. India's domestic manufacturing incentives present the most penetrable geography for RF component assembly joint ventures with established GaN foundries. Target LEO satellite constellation terminal programs as the fastest-expanding application with consumer price-point tolerance. For Investors and Strategic Acquirers: Carve-out targets emerge from defense prime non-core divisions with stranded broadcast infrastructure assets or hybrid analog-digital product lines facing ADC cost barriers. Long-term viability centers on software-defined platform economics with recurring firmware update revenue streams. Watch for modular open systems approach compliance mandates spreading beyond NATO to Five Eyes procurement channels as the definitive inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Captive GaN Foundry Investment | Backward integration into GaN-on-SiC fabrication insulates defense primes from Taiwan supply concentration. |
| Modular Open Systems Certification | MOSA compliance unlocks NATO procurement channels and reduces vendor lock-in exposure. |
| Dual-Use Algorithm Licensing | 5G beamforming IP migration into military electronic warfare captures cross-subsidized R&D economics. |
| India PLI Joint Venture Formation | Domestic value-add requirements favor partnerships with established GaN foundries for telecom equipment. |
| Direct RF Sampling Architecture Transition | 14-bit 3 GSPS converter adoption collapses board area by 60% and enables real-time waveform reconfiguration. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with RF systems architects, defense procurement officers, GaN foundry operations managers, and telecommunications infrastructure planners. Secondary validation drew from FCC equipment authorization databases, ITAR-controlled commodity jurisdiction rulings, EU Radio Equipment Directive compliance filings, and congressional defense appropriation committee records. Bottom-up component demand modeling triangulated against top-down procurement budget analysis.
Across the analysis window, forecasts integrated product type segmentation by transmitter, receiver, amplifier, and processor categories with technology tiers spanning analog, digital, hybrid, and software-defined architectures. End-user segmentation captured defense, telecommunications, broadcast, and aerospace procurement rhythms. CAGRs were derived from installed base replacement cycles, spectrum reallocation mandate timelines, and GaN price-performance parity trajectories against gallium arsenide benchmarks.
The analysis sits within stated boundaries; outcomes outside sustained congressional tactical communications modernization appropriations, FCC C-band relocation enforcement, or GaN foundry capacity expansion would require recalibration. Forecasts reflect assumptions regarding ITAR regulatory stability, NATO interoperability certification propagation, and LEO constellation deployment schedules. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
RF Transceiver Chip Market
RF Components
CATV RF Amplifiers Market
RF Components
Global Gan RF Devices Market
RF Components
UHF RFID Inlays Market
RF Components
Radio Frequency Duplexer Market
RF Components
Space Traveling Wave Tube Amplifiers Market
RF Components
Gaas RF Switch Market
RF Components
RF Antenna Market
RF Components
Global Inductors Market
RF Components
Frequency Synthesizer Market
RF Components
Digital Radio Frequency Memory Market
RF Components
Ultra-Wideband (UWB) Market
RF Components
High-Frequency RF Evaluation Board Market
RF Components
Smartphone RF Power Amplifier Market
RF Components
Silicon Tuners Market
RF Components
Asia-Pacific Small Signal Transistor Market