
 Ultra-Wideband (UWB) Market | 2026-2036
Ultra-Wideband (UWB) Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra-Wideband (UWB) Market Analytics
FCC Part 15 rules for unlicensed ultra-wideband emissions is decoupling hardware design from legacy narrowband compliance costs, lowering barriers for new entrants while raising performance verification standards. Texas Instruments leverages its broad analog and embedded processing portfolio to sustain integrated UWB chipset offerings across automotive and industrial tiers. Qorvo anchors its position through RF front-end specialization, competing on filter and amplifier integration that reduces bill-of-materials complexity for device makers.
Ultra-wideband denotes a radio technology transmitting across bandwidths exceeding 500 MHz or fractional bandwidth above 20%, typically occupying 3.1–10.6 GHz with pulse durations in the nanosecond range, enabling centimeter-level positioning precision through time-of-flight measurements. Consumer electronics applications dominate current volume, with Apple driving ecosystem adoption through device-to-device spatial awareness, while automotive tracking represents the fastest-expanding segment as UWB replaces passive entry systems and enables secure ranging for autonomous valet parking. Chirp UWB technology leads in industrial automation deployments where longer range and Doppler resilience matter, whereas pulsed UWB occupies the cost-optimized tier for short-range consumer tags and asset beacons.
The FCC governs UWB emissions under Part 15 Subpart F in the United States, while ETSI mandates EN 302 567 for European device certification, and Japan's TELEC sets parallel limits through ARIB STD-T91. These frameworks shape power spectral density caps, out-of-band emission guards, and coexistence protocols that directly determine antenna design choices and market access timelines for vendors. Stakeholders must monitor spectrum harmonization negotiations between the FCC and European regulators, as divergent mask definitions threaten to fragment chipset architectures and delay single-SKU global product strategies.
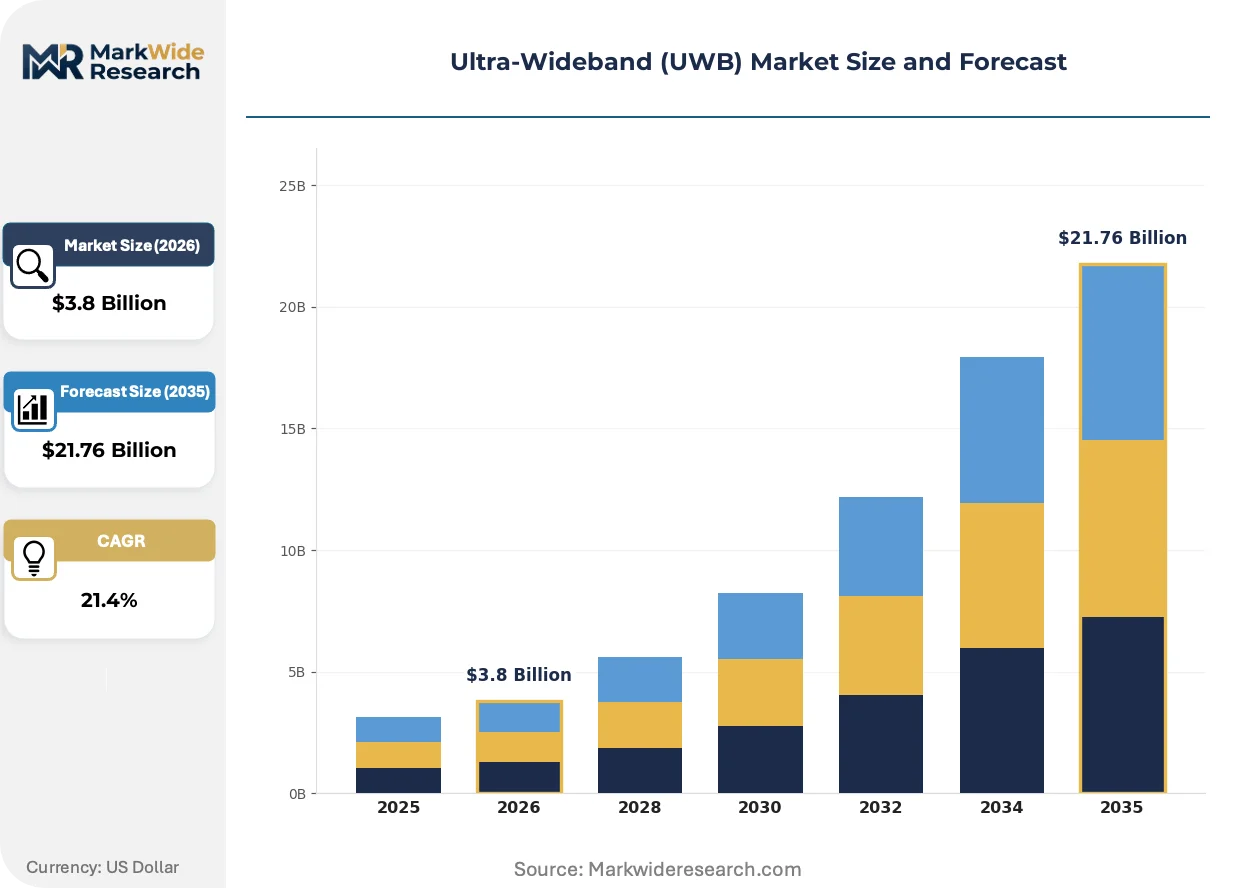
Market Dynamics
Automotive OEMs are embedding UWB as the default secure ranging layer for keyless entry and child-presence detection, compressing development cycles and forcing tier-1 suppliers to requalify legacy passive entry architectures. This demand surge from vehicle electrification programs is restructuring procurement priorities across the RF component stack.
Growth Catalysts
- FCC Part 15 Subpart F:The framework permits unlicensed UWB emissions across 3.1–10.6 GHz with relaxed power limits, enabling rapid certification for consumer device manufacturers seeking indoor positioning capabilities.
- Automotive child-presence detection mandates:Regulatory pressure in the United States and European Union is accelerating UWB sensor integration into rear occupant alert systems, creating dedicated hardware slots in vehicle electrical architectures.
- Chirp UWB modulation:The technology delivers superior Doppler resilience and extended range for industrial automation deployments, displacing legacy RFID in high-velocity asset tracking environments.
Market Restraints
- RF front-end concentration:Filter and amplifier supply chains concentrate among specialized compound semiconductor foundries, exposing module makers to gallium arsenide wafer allocation volatility.
- Spectrum fragmentation risk:Divergent mask definitions between FCC Part 15 and ETSI EN 302 567 threaten to fragment chipset architectures and delay single-SKU global product strategies.
- Bluetooth Low Energy substitution:Direction-finding enhancements in BLE 5.1 and 5.3 specifications are capturing cost-sensitive consumer tag applications where centimeter precision is not mandatory.
Strategic Opportunities
- India industrial automation:The country's PLI scheme for electronics manufacturing is attracting UWB module assembly investments targeting smart factory localization requirements.
- Healthcare asset tracking:Hospital systems are deploying UWB real-time location systems to reduce equipment search time and improve patient flow metrics in emergency departments.
- Secure access control convergence:Integration of UWB with biometric authentication modules is creating premium-tier building entry systems for financial services and data center verticals.
Industry Challenges
- Antenna design specialization:Nanosecond pulse fidelity demands electromagnetic simulation expertise that remains scarce among mid-tier IoT hardware developers, extending prototyping timelines.
- Multi-regulatory certification pipelines:Simultaneous FCC, TELEC ARIB STD-T91, and ETSI compliance testing creates sequential validation bottlenecks for vendors targeting rapid global rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra-Wideband (UWB) Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $21.76 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Consumer Electronics, Automotive Tracking, Healthcare Monitoring, Industrial Automation Technology: Pulsed UWB, Chirp UWB, Impulse UWB, Time Hopping UWB End User: Manufacturers, Retailers, Transportation Firms, Healthcare Providers Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Texas Instruments Incorporated, Samsung Electronics Co. Ltd., Qorvo, Inc., Murata Manufacturing Co., Ltd., STMicroelectronics, Apple Inc., Zebra Technologies Corp., Microchip Technology Inc., NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra-Wideband (UWB) Market Evolving Landscape
UWB system architectures are fragmenting into application-specific configurations as automotive, industrial, and consumer verticals diverge on range, power, and security requirements. This specialization is compressing development timelines while complicating cross-vertical IP reuse.
System-in-package integration is modularizing UWB radio functions into discrete tiles that combine PHY, MAC, and security layers with application processors. Automotive tier-1 suppliers are adopting these pre-integrated modules to accelerate child-presence detection system validation. The approach is compressing RF subsystem qualification from 18-month cycles toward 9-month windows.
ETSI EN 302 567 is tightening out-of-band emission guards for European UWB deployments, forcing antenna redesigns that sacrifice peak gain for spectral containment. Industrial automation vendors serving dual US-EU markets are absorbing duplicate certification costs. The regulation is accelerating filter-integrated module adoption among European device makers seeking streamlined compliance paths.
Buyer procurement patterns are consolidating around pre-certified module suppliers rather than discrete component sourcing, compressing vendor qualification lists to three-to-five approved partners. Automotive OEMs are driving this concentration through approved vendor list mandates for UWB subsystems. The shift is most visible in Germany and Japan, where tier-1 supplier consolidation has advanced furthest.
Ultra-Wideband (UWB) Market Segmentation
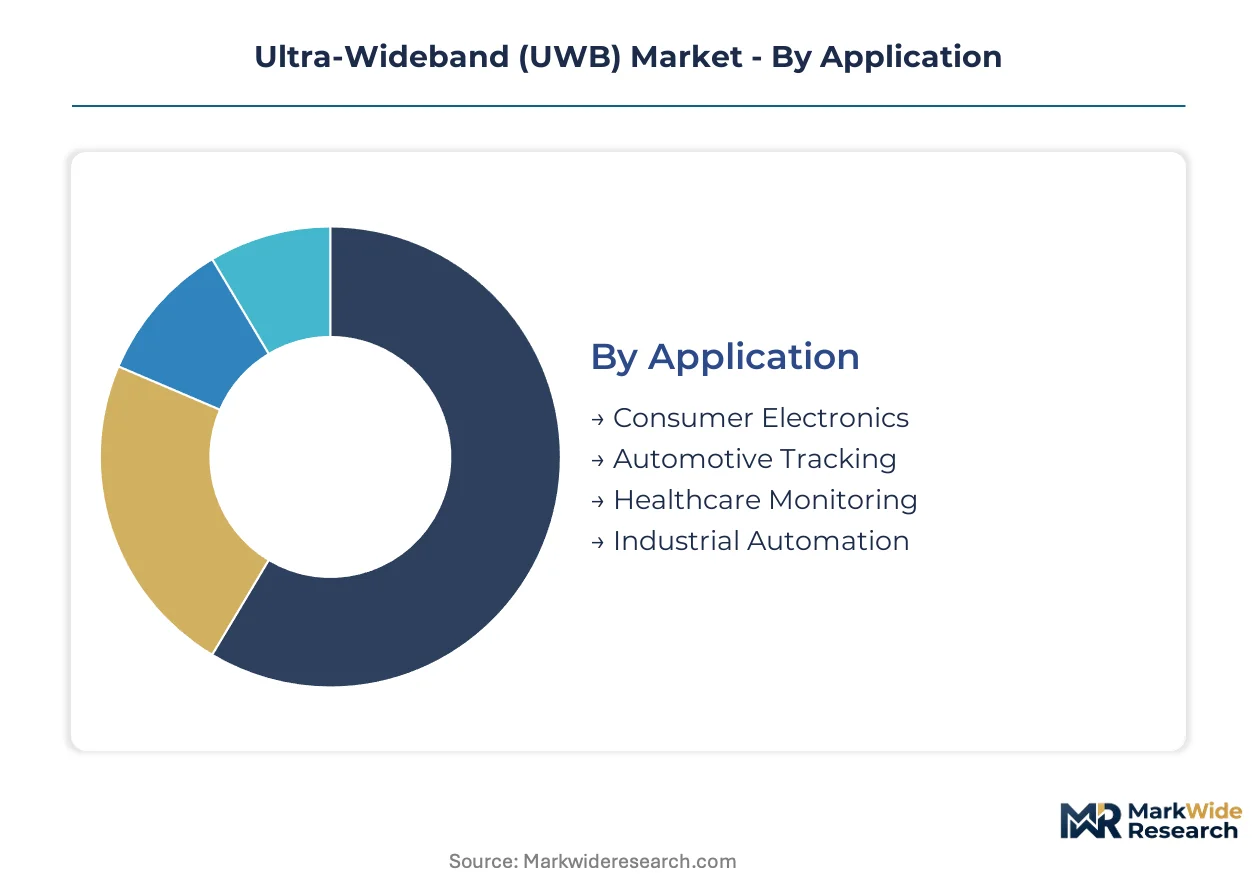
UWB market segmentation reveals divergent technical requirements across consumer, automotive, and industrial verticals. Each application tier demands distinct range, power, and security specifications that reshape chipset architectures and procurement patterns.
Application:
Consumer electronics commands volume leadership through smartphone spatial awareness integration, while automotive tracking delivers premium pricing through safety-critical ranging requirements.
- Consumer Electronics:Device-to-device spatial awareness and precise indoor positioning dominate current shipments. Apple ecosystem integration has normalized UWB in smartphones, earbuds, and smart home controllers, with demand concentrating in the United States and China for premium handset tiers.
- Automotive Tracking:Secure keyless entry and child-presence detection systems are displacing legacy passive entry architectures. European Union and United States regulatory mandates for rear occupant alerts are forcing tier-1 suppliers to requalify RF subsystems around UWB-specific electromagnetic compatibility requirements.
- Healthcare Monitoring:Real-time location systems for medical equipment and patient flow optimization are gaining traction in hospital emergency departments.
- Industrial Automation:High-velocity asset tracking and Doppler-resilient positioning are displacing RFID in smart factory deployments.
Mature deployment sits with Consumer Electronics. Newer deployment is concentrated in Automotive Tracking.
Technology:
Modulation schemes split between cost-optimized pulse architectures and performance-focused chirp implementations for extended range environments.
- Chirp UWB:Frequency-modulated continuous-wave approaches deliver superior Doppler resilience and extended operational range exceeding 100 meters in industrial settings. German and Japanese automation vendors favor this technology for high-velocity conveyor tracking and robotic localization where multipath rejection matters.
- Pulsed UWB:Nanosecond-duration pulse transmissions occupy the cost-optimized tier for short-range consumer tags and asset beacons. Texas Instruments and Qorvo compete on integrated transceiver architectures that reduce bill-of-materials complexity for device makers targeting sub-$5 module price points.
- Impulse UWB:Ultra-short pulse generation enables centimeter-level time-of-flight precision for secure ranging applications.
- Time Hopping UWB:Pseudorandom pulse timing sequences provide interference robustness in dense multipath environments.
Volume production centers on Pulsed UWB. Performance-critical applications are migrating toward Chirp UWB.
End User:
Procurement authority concentrates with integrated device manufacturers rather than system integrators, compressing vendor qualification timelines.
- Manufacturers:Electronics OEMs and automotive tier-1 suppliers drive chipset specification through approved vendor list mandates. Their procurement teams prioritize pre-certified modules that compress RF subsystem validation from 18-month cycles toward 9-month windows.
- Healthcare Providers:Hospital systems deploy UWB real-time location systems to reduce equipment search time and improve patient throughput metrics in emergency departments.
- Transportation Firms:Logistics operators leverage UWB for yard management and container tracking in high-velocity port environments.
- Retailers:Asset tracking and customer analytics applications are emerging in premium retail formats.
Specification authority sits with Manufacturers. Implementation diversity is expanding fastest among Healthcare Providers.
Deployment:
Infrastructure models diverge between edge-resilient industrial architectures and cloud-dependent consumer ecosystems.
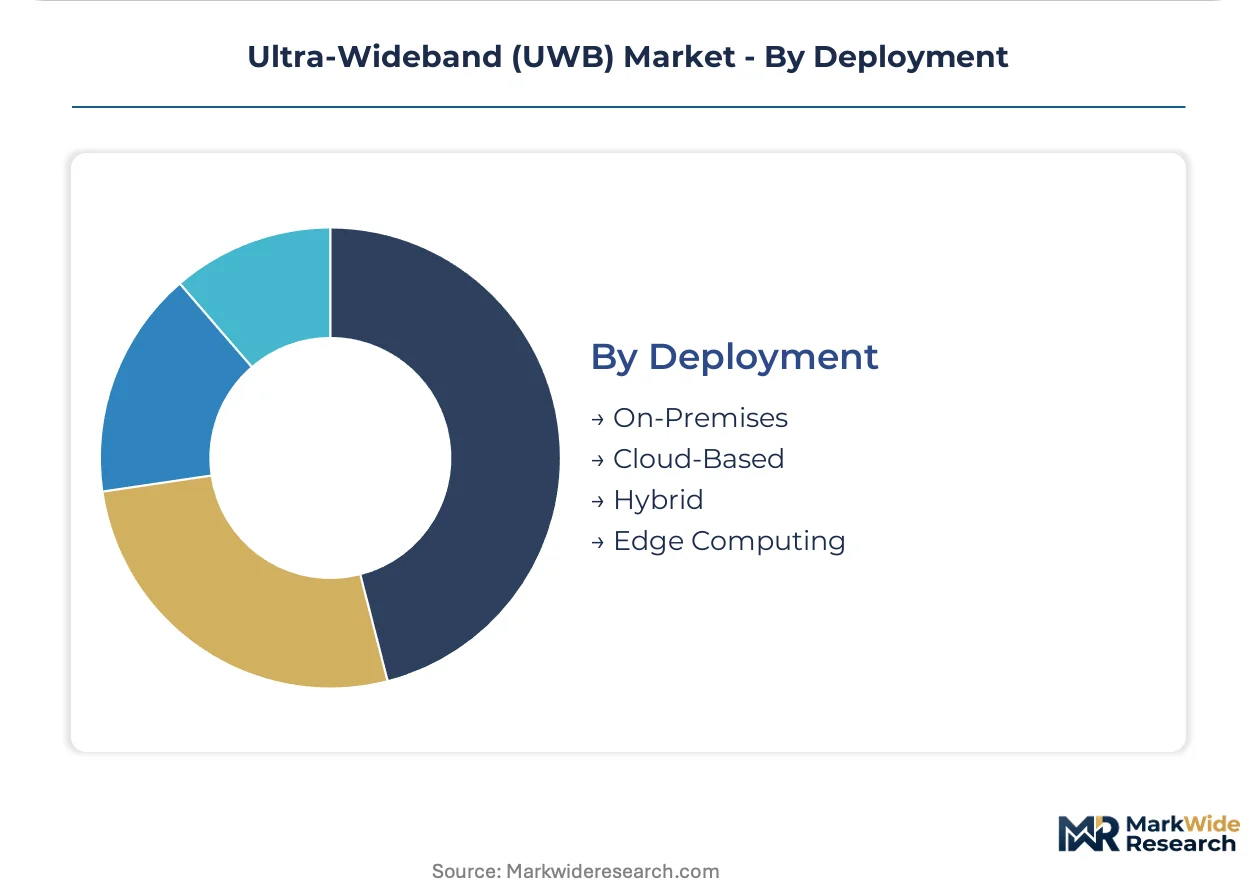
- Edge Computing:Localized processing architectures eliminate latency for safety-critical automotive ranging and deterministic industrial automation. German automotive OEMs mandate edge-resident UWB processing to meet functional safety requirements for autonomous valet parking systems.
- On-Premises:Dedicated infrastructure deployments serve healthcare and industrial verticals with strict data sovereignty requirements.
- Cloud-Based:Centralized location analytics platforms support consumer device ecosystems and retail analytics applications.
- Hybrid:Partitioned architectures balance real-time positioning at the edge with historical analytics in cloud environments.
Latency-sensitive applications are consolidating around Edge Computing. Cloud-Based deployment retains traction in consumer analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Bangalore are concentrating UWB module assembly investments as manufacturers seek proximity to smartphone OEMs and automotive electronics clusters.
United States
Automotive child-presence detection mandates and Apple ecosystem integration drive UWB demand across California and Michigan manufacturing corridors. The FCC's Part 15 Subpart F framework permits unlicensed emissions across 3.1–10.6 GHz, accelerating certification timelines for device makers. Austin and Detroit automotive electronics clusters are embedding UWB into secure ranging architectures for keyless entry systems.
Germany
Industrial automation vendors favor Chirp UWB for high-velocity conveyor tracking in Bavarian smart factory deployments. ETSI EN 302 567 tightens out-of-band emission guards, forcing antenna redesigns that sacrifice peak gain for spectral containment. Stuttgart and Munich automotive tier-1 suppliers are requalifying RF subsystems around UWB-specific electromagnetic compatibility requirements.
China
Smartphone spatial awareness integration and smart home controller manufacturing dominate volume production in Shenzhen and Dongguan electronics zones. MIIT spectrum allocation frameworks shape power spectral density caps and coexistence protocols for domestic device certification. Yangtze River Delta industrial clusters are deploying UWB real-time location systems for high-velocity asset tracking.
Japan
Automotive secure ranging and robotic localization applications concentrate demand in Nagoya and Tokyo metropolitan manufacturing belts. TELEC ARIB STD-T91 sets parallel emission limits that determine antenna design choices and market access timelines for module vendors. Kansai region electronics assemblers are adopting pre-integrated UWB tiles to compress RF subsystem qualification cycles.
India
Electronics manufacturing PLI scheme incentives are attracting UWB module assembly investments targeting smart factory localization requirements. TRAI spectrum consultations influence unlicensed band allocation for industrial IoT deployments. Karnataka and Tamil Nadu industrial corridors are establishing test facilities for FCC and ETSI pre-certification of export-bound modules.
Ultra-Wideband (UWB) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the UWB chipset and module landscape. The vendor base stratifies into three tiers: integrated semiconductor conglomerates with broad analog portfolios, RF front-end specialists with compound semiconductor expertise, and module integrators serving approved vendor lists. Competitive dynamics center on system-in-package integration capabilities and multi-regulatory certification velocity. M&A activity targets antenna design boutiques and filter-integrated module capabilities, while strategic partnerships concentrate on automotive tier-1 qualification pipelines.
Among diversified semiconductor conglomerates, Texas Instruments Incorporated and STMicroelectronics exemplify integrated portfolio approaches spanning automotive and industrial application tiers. Qorvo, Inc. occupies a position within the RF front-end specialist archetype, competing on filter and amplifier integration that reduces bill-of-materials complexity. Samsung Electronics Co. Ltd. represents the vertically integrated device OEM model, driving ecosystem adoption through captive demand and standardization influence. These three anchors illustrate the structural divergence between broad-line suppliers and focused RF specialists competing for automotive and industrial sockets.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Samsung Electronics Co. Ltd. |
| Qorvo, Inc. |
| Murata Manufacturing Co., Ltd. |
| STMicroelectronics |
| Apple Inc. |
| Zebra Technologies Corp. |
| Microchip Technology Inc. |
| NXP Semiconductors |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between automotive safety-qualified modules and consumer-grade consumer electronics tags manifests in both pricing premiums and supply chain sourcing strategies. Tier-1 automotive suppliers absorb 18-month qualification cycles and multi-regulatory testing pipelines that commodity tag manufacturers bypass entirely, concentrating premium-tier procurement among pre-certified module vendors in Germany and Japan while cost-optimized tiers source from Shenzhen assembly clusters.
Pricing Analysis
Lead-time-driven pricing angles dominate module procurement, with automotive OEMs paying premiums for 9-month qualification windows versus standard 18-month cycles. Three-tier pricing structure across automotive-qualified, industrial-grade, and consumer-economy levels separates FCC Part 15 pre-certified modules from ETSI EN 302 567 dual-compliant variants. Pricing pressure stems from Bluetooth Low Energy 5.3 direction-finding capture of cost-sensitive consumer tag applications. Healthcare providers exhibit highest price sensitivity due to capital equipment budget constraints, while automotive tier-1s prioritize qualification velocity over unit cost.
Supply Chain Analysis
Compound semiconductor feedstock rests on gallium arsenide wafer allocation from Japanese and Taiwanese foundries, with filter and amplifier die sourcing concentrated among Qorvo and specialized RF front-end houses. Texas Instruments and STMicroelectronics draw from captive analog fabrication, while module integrators in China and India feed from offshore die banking. Single-source vulnerability concentrates in ARIB STD-T91 pre-certified antenna design boutiques. Distribution runs through approved vendor list mandates at automotive OEMs, compressing qualified supplier bases to three-to-five partners per platform.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration race dynamics intensify as chipset vendors pursue captive antenna design capabilities and module makers seek backward integration into compound semiconductor fabrication. Control over gallium arsenide wafer allocation and electromagnetic simulation talent represents the decisive upstream lever.
For Market Incumbents: Hedge against Bluetooth Low Energy substitution by accelerating Chirp UWB industrial automation deployments where Doppler resilience creates defensible performance gaps. Deepen backward integration into gallium arsenide foundry partnerships to secure wafer allocation against fabless competitor disruption. Prioritize ETSI EN 302 567 dual-certification investment to capture European automotive child-presence detection mandates before regional specialists consolidate tier-1 supplier slots. For New Entrants and Emerging Players: Capture white-space in India PLI scheme electronics manufacturing zones where UWB module assembly investments lag smartphone OEM demand. Target healthcare real-time location systems as the most penetrable vertical, with hospital equipment tracking applications underserved by incumbent automotive-focused vendors. Pursue electromagnetic simulation-as-a-service go-to-market angle to bypass scarce antenna design talent bottlenecks plaguing mid-tier IoT developers. For Investors and Strategic Acquirers: Re-rating potential sits with filter-integrated module specialists given ETSI tightening of out-of-band emission guards forcing antenna redesigns. Long-term viability across the analysis window favors vendors with multi-regulatory certification velocity and system-in-package integration capabilities. Watch FCC-ETSI spectrum harmonization negotiations as the critical inflection signal—divergent mask definitions would fragment chipset architectures and strand single-SKU global product strategies.| Strategic Initiative | Industry Significance |
|---|---|
| System-in-Package Integration | Automotive tier-1 suppliers compress RF subsystem qualification from 18-month cycles toward 9-month windows. |
| Multi-Regulatory Certification Investment | Dual FCC Part 15 and ETSI EN 302 567 compliance unlocks single-SKU global product strategies for module vendors. |
| Compound Semiconductor Backward Integration | Captive gallium arsenide wafer allocation insulates against supply volatility in RF front-end filter and amplifier die. |
| Antenna Design Boutique Acquisition | Scarce electromagnetic simulation expertise for nanosecond pulse fidelity extends prototyping timelines for competitors. |
| Healthcare Vertical Partnership | Hospital system real-time location system deployments reduce equipment search time and improve emergency department throughput metrics. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated against primary interviews with RF chipset product managers, automotive tier-1 procurement directors, electromagnetic simulation engineers, and hospital biomedical equipment planners. FCC Part 15 Subpart F docket archives, ETSI EN 302 567 certification databases, MIIT spectrum allocation notices, and TELEC ARIB STD-T91 registration logs supplied regulatory boundary conditions. Bottom-up module shipment aggregation and top-down semiconductor revenue analysis cross-validated segment sizing.
Data-stream reconciliation across application-tier volume splits, technology-modulation adoption curves, and end-user procurement authority concentration informed the analytical framework. Segmentation dimensions modeled encompass consumer electronics, automotive tracking, healthcare monitoring, and industrial automation applications; Chirp, pulsed, impulse, and time-hopping modulation schemes; and edge, on-premises, cloud, and hybrid deployment architectures. CAGRs derived from installed base growth rates and content-per-vehicle trajectories in automotive electrification programs, with UWB-specific electromagnetic compatibility requalification timelines and child-presence detection mandate implementation schedules as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FCC-ETSI spectrum harmonization negotiations, gallium arsenide foundry capacity allocation shifts, and Bluetooth Low Energy direction-finding specification advancement. Forecasts reflect documented assumptions regarding automotive OEM approved vendor list consolidation velocity and healthcare capital equipment procurement cycle recovery. A small set of named triggers—regulatory divergence, compound semiconductor supply disruption, and substitute technology performance convergence—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
RF Power Dividers Market
RF Components
RF Tester Market
RF Components
Wireless Module Market
RF Components
Silicon Tuners Market
RF Components
RF Mixers Market
RF Components
China Small Signal Transistor Market
RF Components
RF Duplexer Market
RF Components
High Power RF Amplifier Module Market
RF Components
Gan RF Semiconductor Devices Market
RF Components
Low Noise Amplifier Market
RF Components
5G Driver Amplifier Market
RF Components
Global RF Transceiver Market
RF Components
Flat Antenna Market
RF Components
High-Frequency RF Evaluation Board Market
RF Components
RFID Tags Market
RF Components
Radio Frequency Integrated Circuit (RFIC) Market