
 Stand-Alone Radio Receivers Market | 2026-2036
Stand-Alone Radio Receivers Market Size, Share, and Industry Trends Forecast 2026-2036
Stand-Alone Radio Receivers Market Intelligence
The capability gap between high-volume automated assembly and boutique, hand-finished production is unwinding the traditional price-performance curve. Sony Corporation leverages its global supply chain and R&D in digital signal processing for mass-market offerings. In contrast, specialists like Ruark Audio and Roberts Radio differentiate through high-fidelity audio engineering and premium material finishes. Sangean Electronics occupies a niche focused on ruggedized, multi-band receivers for emergency and outdoor use.
Stand-alone radio receivers are electronic devices dedicated to capturing and demodulating radio frequency broadcasts for audio playback. Their performance is often defined by tuner sensitivity, which dictates the ability to lock onto weak or distant signals. While traditional Analog Receivers maintain a base, Digital Receivers supporting DAB technology represent the fastest-growing product segment. The market's core demand originates from Home Users and Hobbyists, with Online Retailers emerging as the primary distribution channel for reaching these fragmented customer bases.
Product design is shaped by a matrix of international regulations, including FCC Part 15 rules on radio frequency emissions in the United States. In Europe, compliance with CE marking for safety and the RoHS directive for material content is mandatory for market access. Future vendor success will hinge on navigating the multi-standard digital transition while defending the product's value proposition against encroachment from internet-connected smart speakers.
Market Dynamics
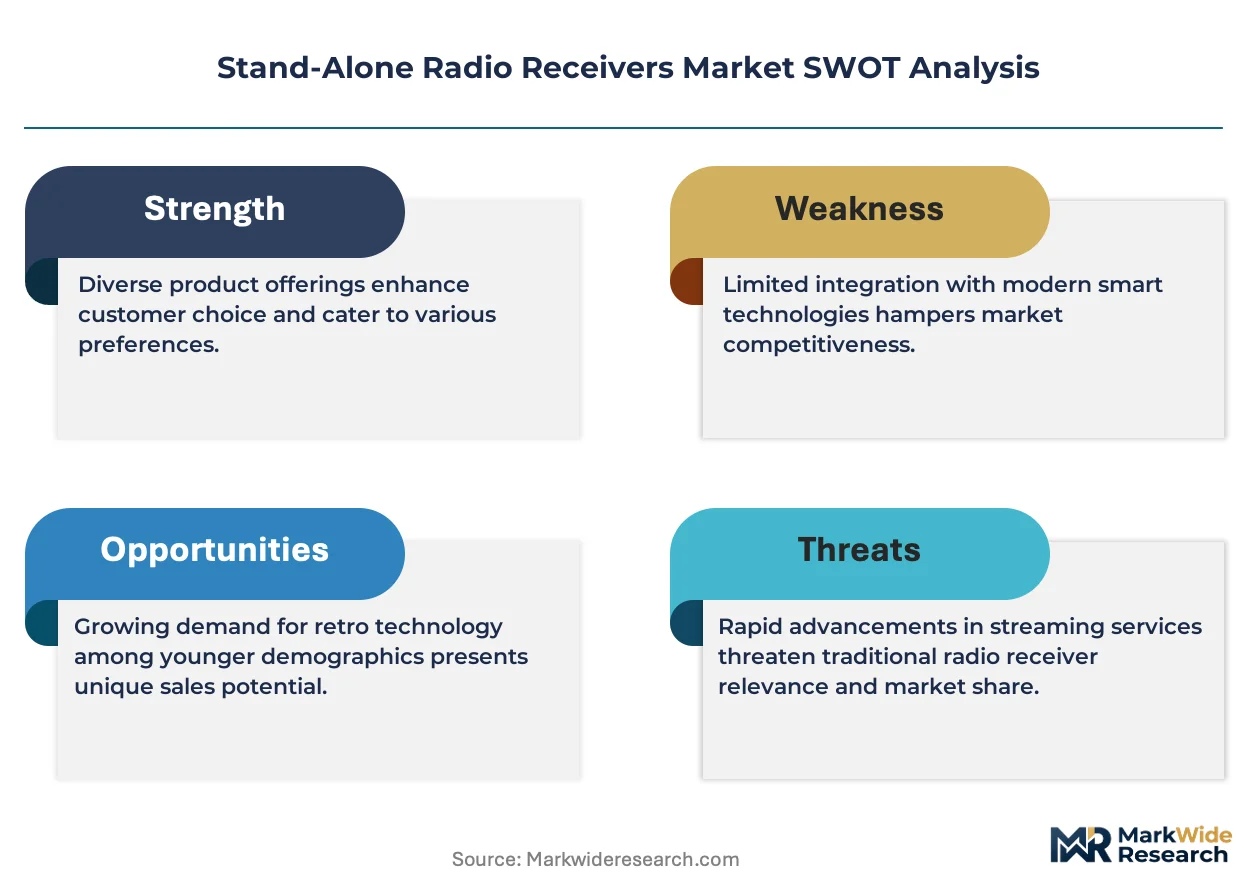
The market's central dynamic is the mandated technological transition from analog to Digital Audio Broadcasting (DAB). This shift creates a replacement cycle, bifurcates product development, and redefines performance benchmarks for both mass-market and specialty receiver manufacturers.
Growth Catalysts
- Digital Transition Mandates:Government-led initiatives in European nations to switch off analog FM broadcasts and mandate DAB capability create a non-discretionary replacement demand for compliant home and portable receivers.
- Hobbyist Community Expansion:A growing base of radio hobbyists and shortwave listeners seeks specialized, high-sensitivity receivers for long-distance (DX) signal reception, driving demand for multi-band and software-defined radio (SDR) units.
- Audio Fidelity Focus:Renewed consumer interest in high-quality audio, distinct from compressed streaming formats, supports the market for premium receivers engineered for superior sound reproduction and acoustic performance.
Market Restraints
- Substitution by Smart Speakers:Internet-connected smart speakers and mobile devices with streaming apps offer a compelling substitute for casual radio listening, eroding the addressable market for basic, single-function receivers.
- Component Scarcity:The reliance on specialized, high-performance tuner and digital signal processor integrated circuits, often sourced from a few suppliers in Asia, creates vulnerability to supply chain disruptions and price volatility.
- High-Fidelity Cost Barrier:The use of premium materials like machined aluminum, real wood veneers, and advanced audio components in boutique models results in high retail prices, limiting their appeal to a narrow segment of audiophiles.
Strategic Opportunities
- Emergency Preparedness Niche:Expanding the feature set of ruggedized, battery-powered receivers with capabilities like solar charging and hand-crank power addresses the needs of the emergency preparedness and off-grid living segments.
- Hybrid Product Development:Integrating Bluetooth connectivity and access to internet radio streams into traditional DAB/FM receivers creates a hybrid product that bridges the gap between broadcast and streamed audio, countering the threat from smart speakers.
- Geographic Expansion in DAB+ Markets:Targeting countries with established but not yet saturated DAB+ networks, such as Australia and parts of Central Europe, offers significant growth potential before market maturity.
Industry Challenges
- Navigating Regulatory Fragmentation:Manufacturers face the complex operational challenge of ensuring products comply with a diverse set of global regulations, including FCC Part 15 in the US and CE marking and RoHS directives in Europe.
- Multi-Standard Digital Support:The lack of a single global digital radio standard requires vendors to develop and manage distinct product lines for different technologies like DAB, DAB+, and HD Radio, increasing R&D and inventory costs.
- IP Licensing Complexity:Securing licenses for essential digital radio patents and codecs represents a significant operational cost and administrative burden, particularly for smaller manufacturers entering the market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stand-Alone Radio Receivers Market |
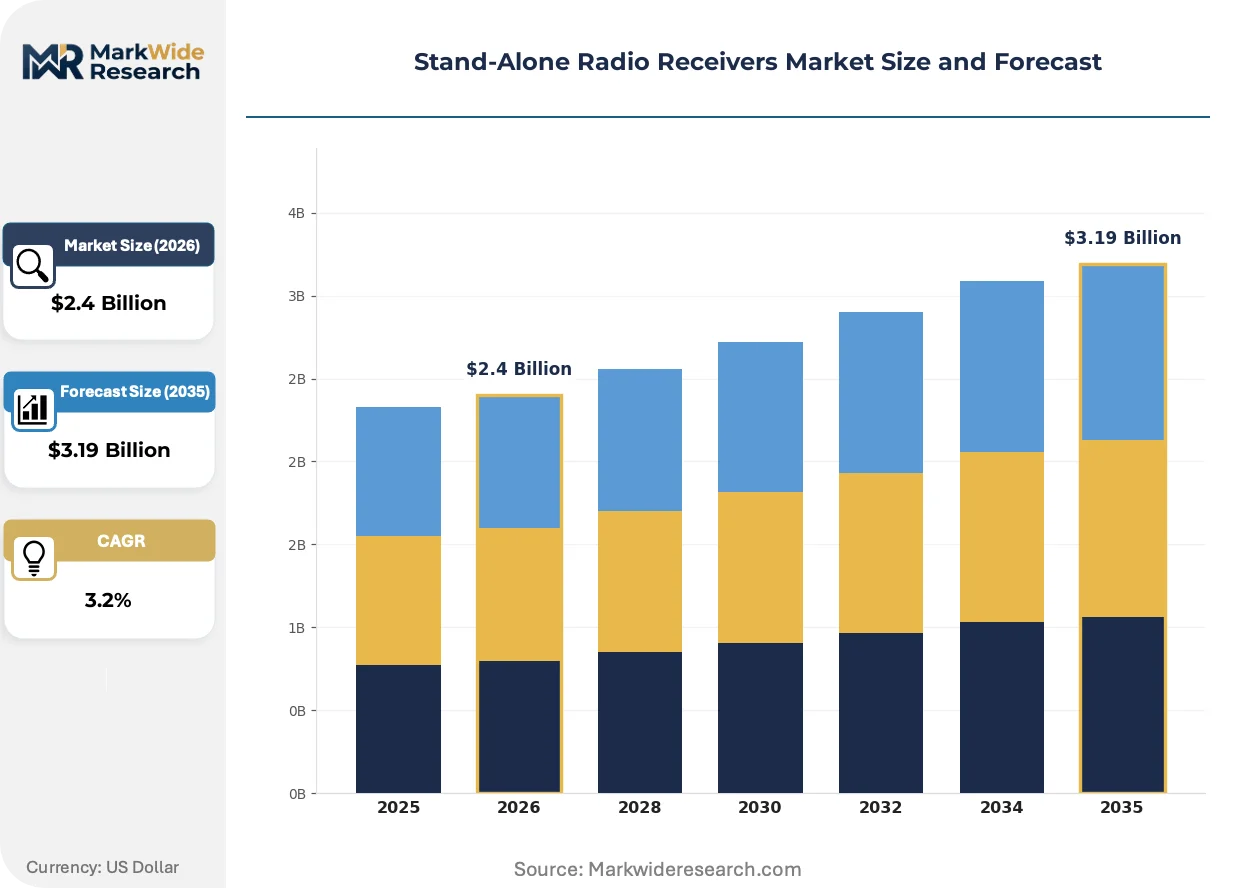
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.19 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Receivers, Digital Receivers, Hybrid Receivers, Bluetooth Receivers Technology: FM Technology, AM Technology, DAB Technology, Internet Streaming End User: Home Users, Automotive Manufacturers, Commercial Establishments, Hobbyists Distribution Channel: Online Retailers, Electronics Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Bose, Tivoli Audio, Sony Corporation, Pioneer Corporation, Sangean Electronics, Panasonic Corporation, Roberts Radio, Ruark Audio, Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stand-Alone Radio Receivers Market Strategic Shifts & Innovations
The market is defined by a push to integrate modern digital functionality without sacrificing the core tenets of high-performance radio frequency reception. This involves balancing new connectivity features with the fundamental engineering required for superior tuner sensitivity and audio fidelity.
Digital signal processing (DSP) is the core technology replacing discrete analog components for filtering and demodulation. Enthusiasts and mainstream consumers alike are adopting DSP-based radios for their enhanced selectivity and noise reduction. Ultimately, the software-defined nature of DSP is decomposing the rigid link between hardware cost and reception performance, enabling smaller devices to achieve high-end results.
Regulatory frameworks in Europe are accelerating the digital transition. The European Electronic Communications Code encourages member states to promote digital radio, while national-level mandates, such as in Norway, have already phased out FM broadcasting. This action forces a technology replacement cycle for home users, directly impacting inventory and sales strategies for analog-only products in the region.
A notable behavioral change is the shift in purchasing from mass-market electronics stores to specialized online retailers and direct-to-consumer channels. This trend allows niche manufacturers to bypass traditional distribution and connect directly with a global audience of audiophiles and radio hobbyists. This disintermediation is most pronounced in the United Kingdom and Germany for high-fidelity and multi-band receiver categories.
Stand-Alone Radio Receivers Market Segmentation
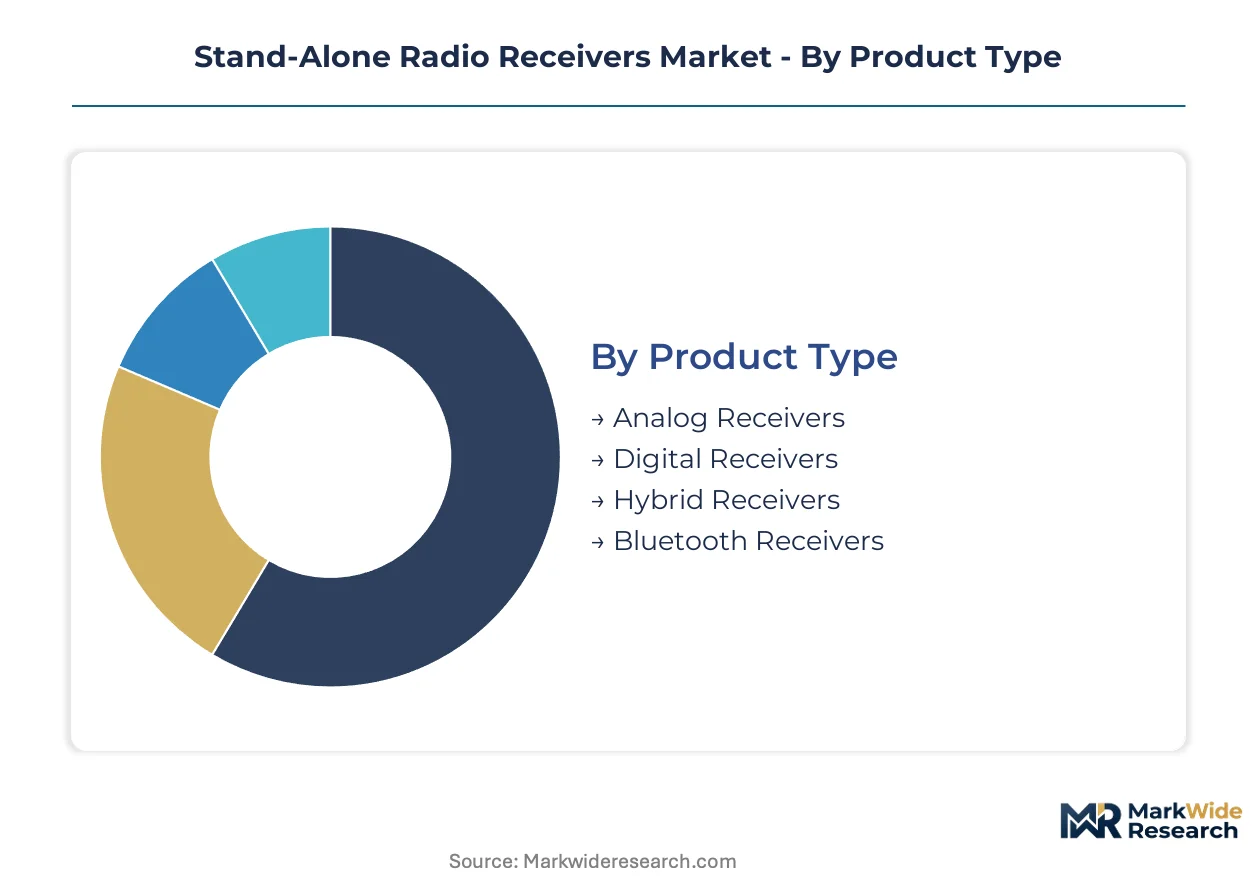
Segmentation within the stand-alone radio receivers market reveals critical shifts in consumer preferences and technological adoption. Analyzing these distinct categories illuminates where demand concentrates, how digital transitions influence purchasing decisions, and the evolving competitive landscape for manufacturers.
Product Type:
The product type segmentation highlights which receiver categories face the most significant substitution pressure from alternative audio consumption devices.
- Digital Receivers:These devices are engineered to receive Digital Audio Broadcasting (DAB) signals, providing enhanced audio fidelity and more station choices. Demand is accelerating in European nations like Norway and the United Kingdom due to government-mandated analog switch-offs.
- Hybrid Receivers:These advanced units integrate traditional broadcast reception (FM/DAB) with modern connectivity features, such as Bluetooth and Wi-Fi for internet radio streaming. They directly address the threat from smart speakers by offering a versatile listening experience.
- Analog Receivers:These traditional devices capture and demodulate analog FM and AM radio signals. They maintain a base among price-sensitive consumers and specific hobbyist groups.
- Bluetooth Receivers:Primarily designed for wireless audio streaming from external devices, these units often include basic FM tuners as a secondary feature for portable convenience.
Analog Receivers anchor the volume base while Digital Receivers gains share at the steepest rate.
Technology:
The technology segmentation delineates the underlying broadcast standards and connectivity options that define receiver functionality across various listening environments.
- DAB Technology:This digital broadcast standard delivers superior sound quality and data services compared to analog FM. Its adoption is a primary driver for market growth, particularly in countries with strong public broadcasting traditions.
- Internet Streaming:This technology allows receivers to access global radio stations and podcasts via an internet connection, often through Wi-Fi. It expands content availability significantly, countering the limited station choices of traditional broadcast.
- FM Technology:This long-established analog modulation technique provides widespread radio coverage. While still prevalent, its market share is declining in regions transitioning to digital broadcasts.
- AM Technology:Amplitude modulation technology supports long-distance signal reception, particularly for shortwave bands. This niche technology primarily caters to specialized radio hobbyists and emergency preparedness segments.
DAB Technology represents the core of future product development, while FM Technology faces progressive obsolescence in key markets.
End User:
The end user segmentation clarifies distinct demand patterns and purchasing motivations across different consumer groups for stand-alone radio receivers.
- Home Users:This segment comprises general consumers purchasing receivers for domestic listening, often driven by the replacement cycle created by the digital transition. Their demand often focuses on ease of use and aesthetic integration into home environments.
- Hobbyists:This group includes shortwave listeners, DXers, and amateur radio enthusiasts seeking specialized, high-sensitivity receivers for long-distance signal reception and technical exploration. Online retailers are a primary channel for this fragmented global community.
- Automotive Manufacturers:These entities integrate radio receivers directly into vehicle infotainment systems. Their demand is for embedded solutions rather than stand-alone units, focusing on compliance with regional broadcast standards.
- Commercial Establishments:Businesses like restaurants, offices, and retail stores use receivers for background music or public announcements. Their purchasing criteria often include reliability and multi-zone audio capabilities.
Home Users collectively represent the largest volume segment, though Hobbyists drive innovation in specialized receiver capabilities.
Distribution Channel:
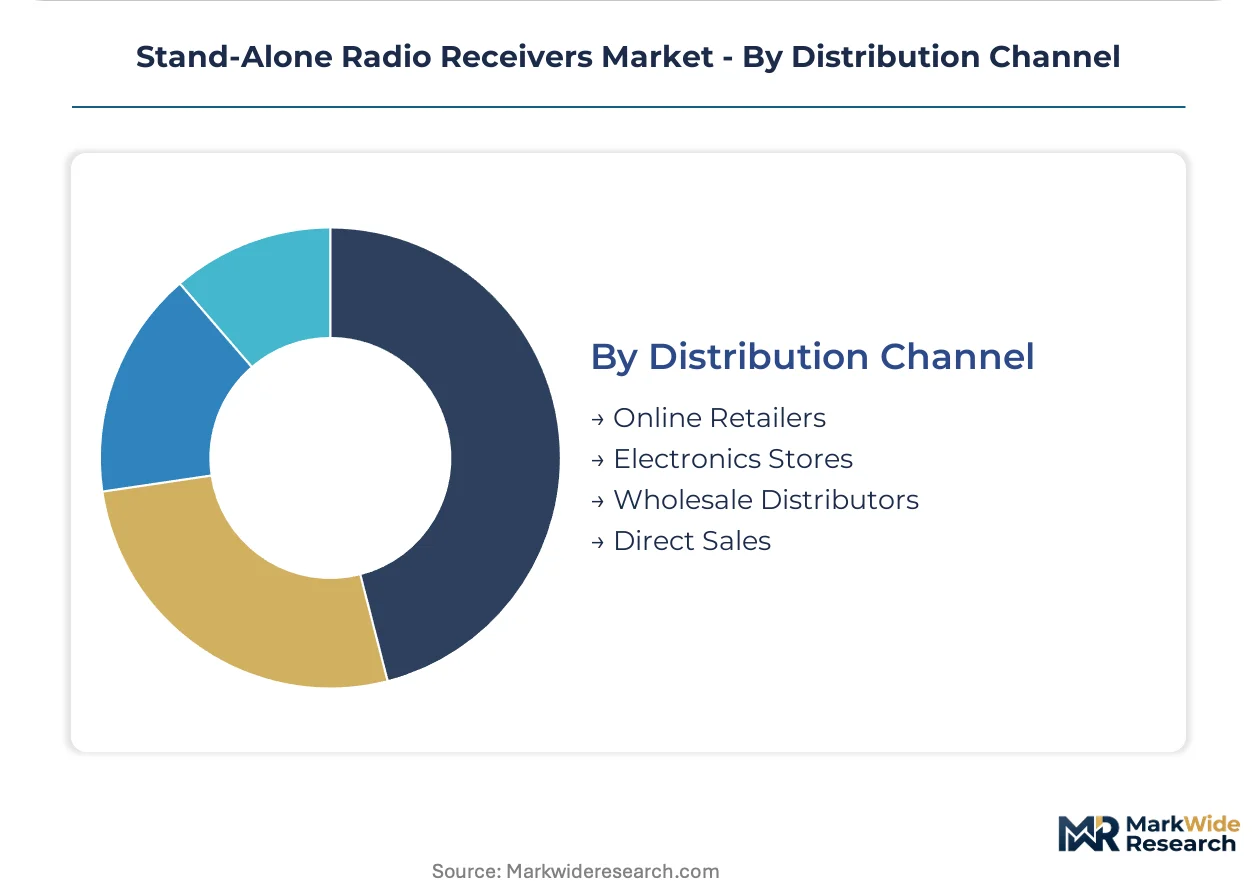
The distribution channel segmentation illustrates how manufacturers reach fragmented customer bases and adapt to evolving retail landscapes for radio receivers.
- Online Retailers:These platforms serve as the primary channel for reaching a global, fragmented customer base, particularly for niche and premium products. They facilitate direct-to-consumer sales and provide extensive product information.
- Electronics Stores:Traditional brick-and-mortar electronics stores offer physical product demonstrations and immediate purchase options. They remain relevant for mass-market consumers seeking basic or mid-range receivers.
- Wholesale Distributors:These intermediaries supply smaller independent retailers and commercial clients. They manage logistics and inventory for a broad range of products, streamlining market access for manufacturers.
- Direct Sales:This channel involves manufacturers selling directly to end-users, often through their own websites or dedicated showrooms. It allows for greater control over branding and customer relationships, especially for boutique brands.
Online Retailers are reshaping the market's reach and pricing transparency, while traditional Electronics Stores face margin compression due to declining foot traffic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global trade balance for stand-alone radio receivers shifts as regions with strong manufacturing capabilities export to markets undergoing digital broadcast transitions. Demand concentrates in countries where public broadcasting traditions are deeply embedded, creating specific import needs for compliant devices. This dynamic shapes regional market development and product availability.
United Kingdom
The United Kingdom experiences robust demand for digital radio receivers due to its strong public broadcasting tradition and government-led DAB transition. The country's regulatory framework, including Ofcom's digital radio policies, encourages the adoption of DAB+ technology. Retailers in London and other major cities prioritize stocking compliant DAB and hybrid units for home users.
Germany
Germany represents a significant market for stand-alone radio receivers, driven by consumer interest in high-fidelity audio and the ongoing digital radio migration. Compliance with CE marking for market access is mandatory for all electronic devices sold within the nation. Major electronics manufacturers in Munich and Berlin develop advanced DSP-based receivers for discerning audiophiles.
Japan
Japan maintains a steady demand for stand-alone radio receivers, supported by a strong legacy electronics market and a dedicated community of radio hobbyists. Manufacturers comply with ARIB standards for broadcast technologies, ensuring product interoperability. Tokyo's Akihabara district remains a hub for specialized and high-performance receiver models.
United States
United States demand for stand-alone radio receivers stems from a growing hobbyist community and the emergency preparedness segment. Products must adhere to FCC Part 15 rules on radio frequency emissions before market entry. Manufacturers in Silicon Valley and other tech hubs focus on developing advanced software-defined radio units.
Stand-Alone Radio Receivers Market Key Industry Players
Concentration sits with established electronics manufacturers possessing global supply chains and extensive research and development capabilities. The market structure is tiered, featuring both high-volume mass-market producers and specialized boutique brands. Strategic archetypes include high-volume digital receiver providers, premium audio engineering specialists, and ruggedized multi-band unit developers. Companies pursue portfolio diversification into hybrid products and geographic expansion into new DAB+ markets to secure market share.
At the scale-driven end, Sony Corporation exemplifies a global electronics giant leveraging its extensive supply chain and digital signal processing expertise for mass-market digital and analog offerings. In contrast, Ruark Audio represents a premium segment specialist, focusing on high-fidelity audio engineering and sophisticated material finishes for discerning consumers seeking superior sound reproduction. Sangean Electronics occupies a distinct niche, providing ruggedized, multi-band receivers designed for emergency preparedness and outdoor use, catering to a specialized user base with specific durability requirements.
| Leading Market Players |
|---|
| Bose |
| Tivoli Audio |
| Sony Corporation |
| Pioneer Corporation |
| Sangean Electronics |
| Panasonic Corporation |
| Roberts Radio |
| Ruark Audio |
| Philips |
| Others |
Cost & Logistics Intelligence
CE marking for European market access gates both supply qualification and price differentiation for stand-alone radio receivers. Compliance with diverse international standards impacts manufacturing complexity and ultimately influences retail price points across regions.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing for integrated solutions within vehicle infotainment systems. Pricing stratifies across premium, standard, and economy tiers based on tuner sensitivity and audio fidelity. Price differentiation also stems from brand premium, with Ruark Audio commanding higher prices for its high-fidelity engineering. Pricing softness reflects widespread substitution by internet-connected smart speakers for basic units. Home Users represent the most price-sensitive segment, while audiophiles and hobbyists exhibit lower price sensitivity for specialized receivers.
Supply Chain Analysis
Component lead times for specialized tuner and DSP integrated circuits often extend due to high demand and limited fabrication capacity. Geographic supply concentration centers in Asia for advanced ICs and in Europe for boutique audio components. Critical raw material dependencies include specialized semiconductor chips and premium enclosure materials like machined aluminum. Single-source vulnerability for high-performance digital components presents a structural supply chain risk. Distribution runs through online retailers for fragmented customer bases and electronics stores for mass-market availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stand-alone radio receivers market is experiencing an early-cycle expansion, driven by the non-discretionary replacement demand from digital broadcast transitions.
For Market Incumbents: Shield core market share against smart speaker encroachment through hybrid product development. Invest in digital signal processing R&D to maintain a performance edge in tuner sensitivity and audio fidelity. Leverage existing global supply chains to optimize manufacturing costs for mass-market digital offerings. Focus on consolidating market presence in regions with active DAB transition mandates.
For New Entrants and Emerging Players: Differentiate on specialized niche capabilities, such as ruggedized multi-band receivers for emergency preparedness. Target the global hobbyist community, which seeks high-sensitivity units for long-distance signal reception. Online retailers provide a direct-to-consumer go-to-market angle for reaching these fragmented, technically discerning segments. Focus on superior build quality and unique feature sets.
For Investors and Strategic Acquirers: Mandated DAB transition reshapes the acquisition landscape, creating opportunities for consolidating digital radio technology providers. Long-term viability depends on a blend of regulatory-driven replacement cycles and sustained niche demand from hobbyists. Target boutique audio engineering specialists or ruggedized receiver manufacturers with strong brand loyalty. The signal to watch is the acceleration of national analog switch-off timelines beyond Europe.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Diversification into Hybrid Receivers | Integrating internet streaming into DAB/FM units counters smart speaker substitution. |
| Geographic Expansion in DAB+ Markets | Targeting countries like Australia offers significant growth potential for digital units. |
| Supply Chain Resilience Investment | Diversifying sourcing for tuner ICs mitigates single-source vulnerability risks. |
| Niche Market Penetration for Emergency Use | Developing ruggedized, battery-powered units addresses emergency preparedness needs. |
| Brand Premium Cultivation through Audio Fidelity | Focusing on superior sound reproduction attracts audiophiles and discerning consumers. |
Research Approach
Initial hypotheses were tested against primary input from product development engineers, retail channel managers, radio hobbyist community leaders, and regulatory compliance officers, and refined through iterative analysis. This approach combined in-depth primary interviews with rigorous secondary validation, drawing from sources like Ofcom reports, FCC filings, national broadcasting authority statistics, and electronics industry trade publications. Bottom-up data aggregation and top-down market sizing provided comprehensive triangulation.
The analytical framework employs a variance-decomposition approach to segment and forecast the market across the modeling period. Segmentation dimensions modeled include Product Type, Technology, End User, Distribution Channel, and regional regulatory mandates. Compound Annual Growth Rates were derived from historical adoption rates and projected digital transition timelines. Key industry-specific forecast inputs included digital broadcast penetration rates and smart speaker adoption curves.
Material uncertainties — unforeseen regulatory shifts or component supply shocks — sit outside the modeled envelope. Forecasts reflect assumptions documented through extensive primary and secondary research. Geopolitical events impacting global supply chains or faster-than-expected smart speaker substitution represent specific risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
RF-Microwave for 5G Market
RF Components
CATV RF Amplifiers Market
RF Components
Flat Panel Antenna Market
RF Components
High Power RF Amplifier Module Market
RF Components
Digital Radio Frequency Memory Market
RF Components
RF Microwave MLCC Market
RF Components
SMD Resonator Market
RF Components
RF Tester Market
RF Components
Global RF Power Semiconductor Market
RF Components
Radio Frequency Duplexer Market
RF Components
Tunable Inductors Market
RF Components
Ultra-Wideband (UWB) Market
RF Components
LTCC Power Dividers Market
RF Components
Radio Frequency Components Market
RF Components
Radio Frequency Counter Market
RF Components
Global Bulk Acoustic Wave (BAW) Filters Market