
 CATV RF Amplifiers Market | 2026-2036
CATV RF Amplifiers Market Size, Share, and Industry Trends Forecast 2026-2036
CATV RF Amplifiers Market Outlook
Chinese RF component manufacturing is expanding capacity for CATV amplifier modules serving both domestic cable networks and export markets. Skyworks leverages its compound semiconductor expertise to sustain leadership in high-linearity gain blocks for headend applications. Qorvo anchors North American supply through its broadband GaN and GaAs amplifier portfolios optimized for HFC infrastructure.
CATV RF amplifiers are electronic devices that boost radio-frequency signals within the 5 MHz to 1.2 GHz range across coaxial cable distribution networks, typically employing gallium nitride or gallium arsenide transistor technology to achieve low noise figures and high output power with minimal distortion. These amplifiers compensate for signal attenuation over long cable runs, enabling reliable delivery of television, internet, and voice services to subscriber premises. Multi-channel configurations dominate installed base volumes due to their efficiency in consolidating amplification across downstream and upstream spectrum bands, while hybrid product variants are capturing incremental share as operators transition toward fiber-deep architectures. Optical technology segments within the broader amplifier ecosystem represent the fastest-growing category as cable operators deploy RF-over-fiber solutions to extend network reach beyond traditional coaxial limitations.
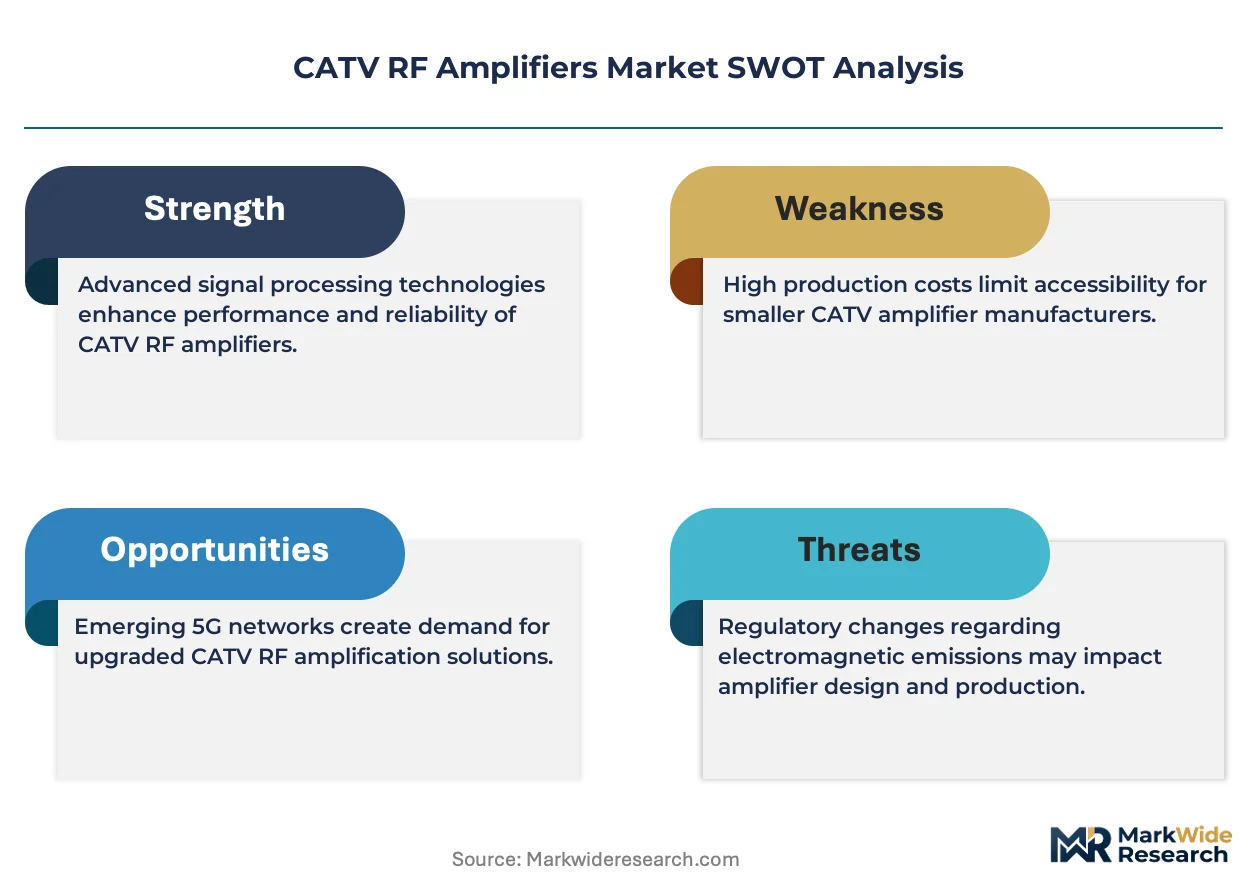
The FCC governs RF emissions and out-of-band spurious limits for cable equipment in the United States, while CE marking under the EU Radio Equipment Directive shapes product compliance for European deployments. Operators must navigate divergent electromagnetic compatibility testing protocols across these jurisdictions, adding certification complexity for multinational equipment vendors. Stakeholders should monitor spectrum policy evolution and DOCSIS specification advances to align amplifier development roadmaps with next-generation network requirements.
Market Dynamics
The DOCSIS 4.0 transition is forcing wholesale infrastructure replacement across North American cable networks, compressing amplifier procurement cycles while elevating performance specifications for upstream spectrum extension.
Growth Catalysts
- DOCSIS 4.0 specification:The new standard mandates 1.8 GHz downstream and upstream symmetry, requiring high-linearity amplification that obsolete equipment cannot support.
- FCC spectrum reallocation:Ongoing 3.7-3.98 GHz C-band repurposing pressures cable operators to harden RF plant against interference, accelerating amplifier refresh programs.
- Hybrid fiber-coax evolution:Fiber-deep architectures extend optical nodes closer to subscribers, creating demand for compact, high-efficiency distribution amplifiers in reduced-footprint housings.
Market Restraints
- Gallium nitride substrate costs:GaN wafer pricing volatility constrains margin expansion for high-power amplifier variants dependent on compound semiconductor foundries.
- Single-source RF component concentration:Critical GaN HEMT die supply concentrates among limited merchant foundries, exposing procurement timelines to geopolitical trade friction.
- Legacy coaxial plant inertia:Decades-old amplifier cascades in tier-2 and tier-3 operator footprints resist full replacement due to capital prioritization toward fiber overbuilds.
Strategic Opportunities
- Rural broadband subsidy programs:USDA ReConnect and FCC Rural Digital Opportunity Fund disbursements incentivize amplifier deployment in unserved census blocks previously bypassed by major MSOs.
- RF-over-fiber convergence:Integration of optical transceivers with traditional RF amplification creates unified headend-to-subscriber signal chains, collapsing separate procurement categories.
- Remote PHY and MACPHY distributed access:Virtualized CMTS architectures displace centralized headend equipment, shifting amplifier intelligence toward the network edge.
Industry Challenges
- Compound semiconductor process engineering:Qualified GaN and GaAs device physicists remain scarce relative to silicon CMOS talent pools, constraining internal R&D scaling.
- Multi-jurisdiction certification synchronization:Divergent FCC Part 76, CE marking under EU Radio Equipment Directive, and Industry Canada RSS testing timelines delay product launches by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CATV RF Amplifiers Market |
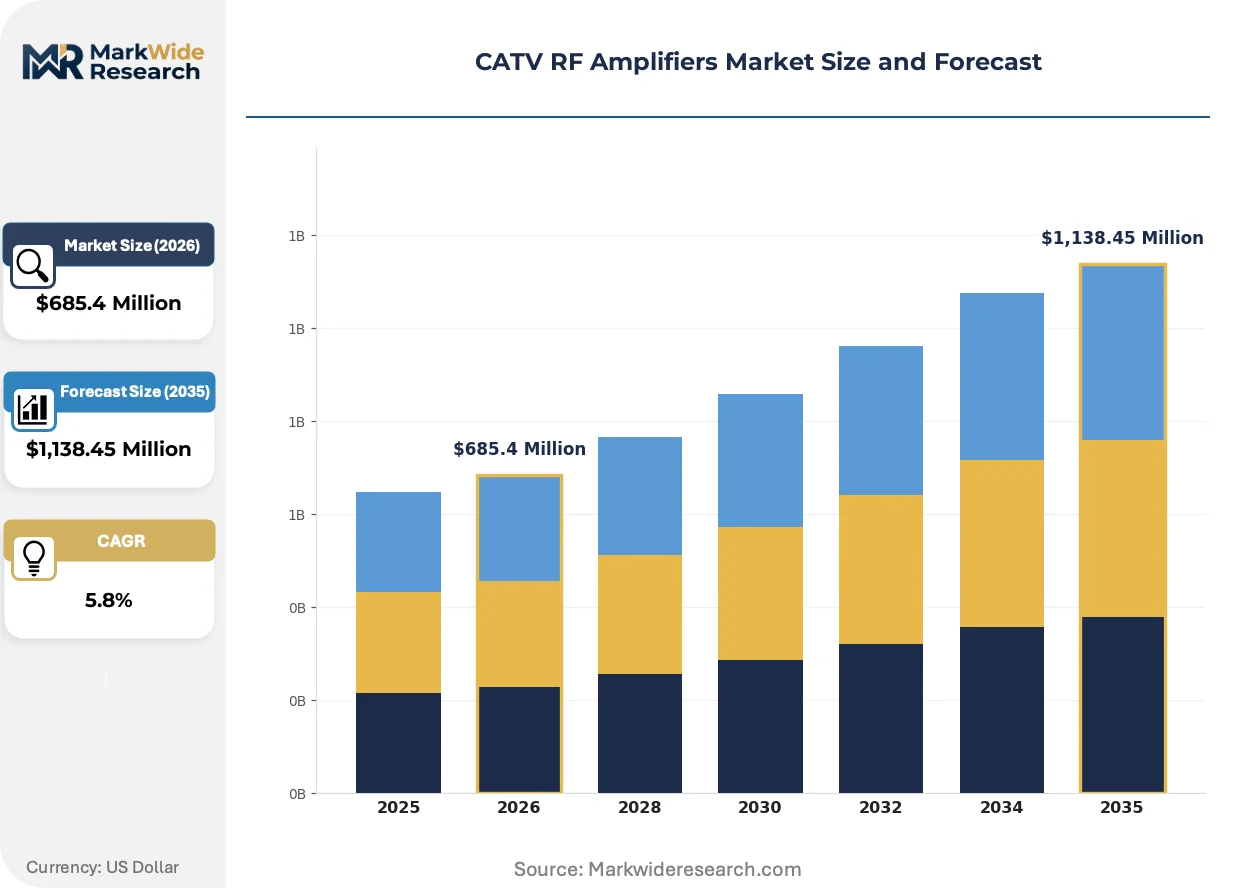
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Channel, Multi-Channel, Hybrid, Line Amplifiers Technology: Analog, Digital, Optical, Frequency Modulation End User: Cable Operators, Broadcasters, Streaming Services, Telecommunications Installation: Indoor, Outdoor, Rack-Mounted, Wall-Mounted |
| Companies Covered | Skyworks, NXP Semiconductors, Texas Instruments, Blonder Tongue, ShenZhen ChuangMo Electronics, Analog Devices, II VI Incorporated, SOFTEL, Qorvo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CATV RF Amplifiers Market Strategic Shifts
Amplifier architecture is bifurcating between high-density headend consolidation and distributed edge intelligence, with transistor technology and network virtualization as the twin levers of differentiation.
GaN-on-SiC power transistors are expanding into CATV line extender and bridger amplifier applications previously dominated by silicon LDMOS. Major MSOs in the United States and Canada have accelerated qualification timelines for GaN-based outdoor plant equipment. This technology shift is expanding into upstream spectrum amplification above 204 MHz, where thermal efficiency and linearity specifications are most demanding.
CE marking under the EU Radio Equipment Directive is tightening electromagnetic compatibility testing for cable equipment exported to European markets. The directive's 2024 amendments impose stricter out-of-band emission limits that legacy amplifier designs struggle to meet. Manufacturers serving both North American and European operators must maintain dual certification tracks, elevating compliance overhead for mid-tier vendors.
Procurement centralization among the largest North American MSOs is compressing vendor negotiation leverage and standardizing amplifier specifications across multiple franchise territories. Tier-1 operators now mandate unified DOCSIS 4.0-ready platforms across their entire footprint, displacing the historical patchwork of regional equipment preferences. This concentration is most visible in the United States, where Comcast, Charter, and Cox collectively dictate amplifier roadmaps for the merchant supply base.
CATV RF Amplifiers Market Segmentation
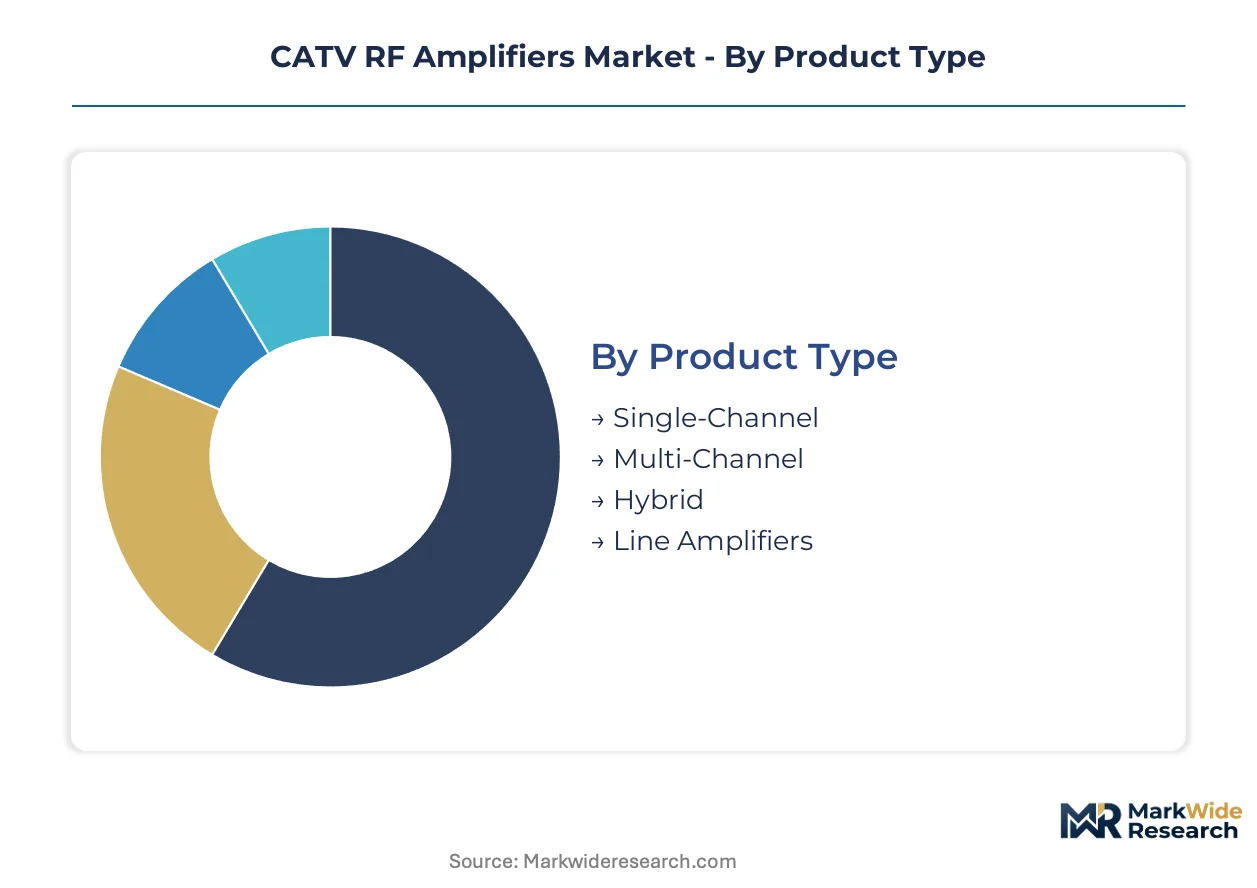
CATV RF amplifier procurement patterns diverge sharply by deployment context, with network architecture choices dictating power handling, thermal management, and spectral efficiency requirements. Equipment vendors must configure product portfolios across four distinct segmentation axes to capture operator upgrade cycles.
Product Type:
Supply concentration for high-power output stages favors multi-channel and hybrid architectures, while single-channel legacy units face accelerating obsolescence.
- Multi-Channel:Consolidated amplification across downstream and upstream spectrum bands reduces rack space and power consumption in headend facilities. United States cable operators driving DOCSIS 4.0 deployments specify these configurations for 1.8 GHz spectrum support.
- Hybrid:Integrated optical-electrical conversion enables fiber-deep architectures extending RF signal distribution beyond traditional coaxial reach. Demand concentrates in Comcast and Charter footprint expansions where node segmentation strategies require compact, high-efficiency housings.
- Single-Channel:Legacy bridger amplifiers serving narrowband spectrum allocations in tier-3 operator networks.
- Line Amplifiers:Cascade repeaters maintaining signal integrity across long coaxial trunk segments in rural distribution plants.
Multi-channel configurations absorb the bulk of installed capacity; hybrid variants are expanding most quickly as fiber-deep architectures displace traditional HFC topologies.
Technology:
Cost tier differentiation separates mature analog implementations from premium digital and optical platforms commanding higher ASPs.
- Optical:RF-over-fiber transceivers paired with amplification stages collapse separate procurement categories into unified signal chains. United States MSOs prioritize these for remote PHY and distributed access architecture migrations.
- Digital:Adaptive predistortion and software-defined gain control enable precise linearity management across extended upstream spectrum. Broadcasters in metropolitan markets specify digital platforms for multiplexed content delivery.
- Analog:Fixed-gain amplification without signal processing capabilities serves cost-constrained maintenance of legacy plant.
- Frequency Modulation:Specialized modulation schemes for satellite backhaul and specialized broadcast applications.
Analog platforms retain residual volume in replacement cycles; optical technology is climbing the fastest as operators consolidate headend-to-subscriber signal chains.
End User:
Customer type determines specification rigor, with cable operators mandating carrier-grade compliance while streaming services prioritize cost-optimized throughput.
- Cable Operators:Multi-system operators in the United States and Canada drive qualification timelines for GaN-based outdoor plant equipment with stringent FCC Part 76 emission controls.
- Telecommunications:Fiber-to-the-premises providers leverage CATV amplifiers for hybrid service delivery in multi-dwelling unit applications.
- Broadcasters:Terrestrial television transmission networks requiring high-power amplification for over-the-air signal distribution.
- Streaming Services:Content delivery networks sourcing cost-optimized amplification for edge caching and localized distribution.
Cable operators absorb the bulk of installed capacity; telecommunications providers are gaining share fastest as fiber-copper convergence accelerates.
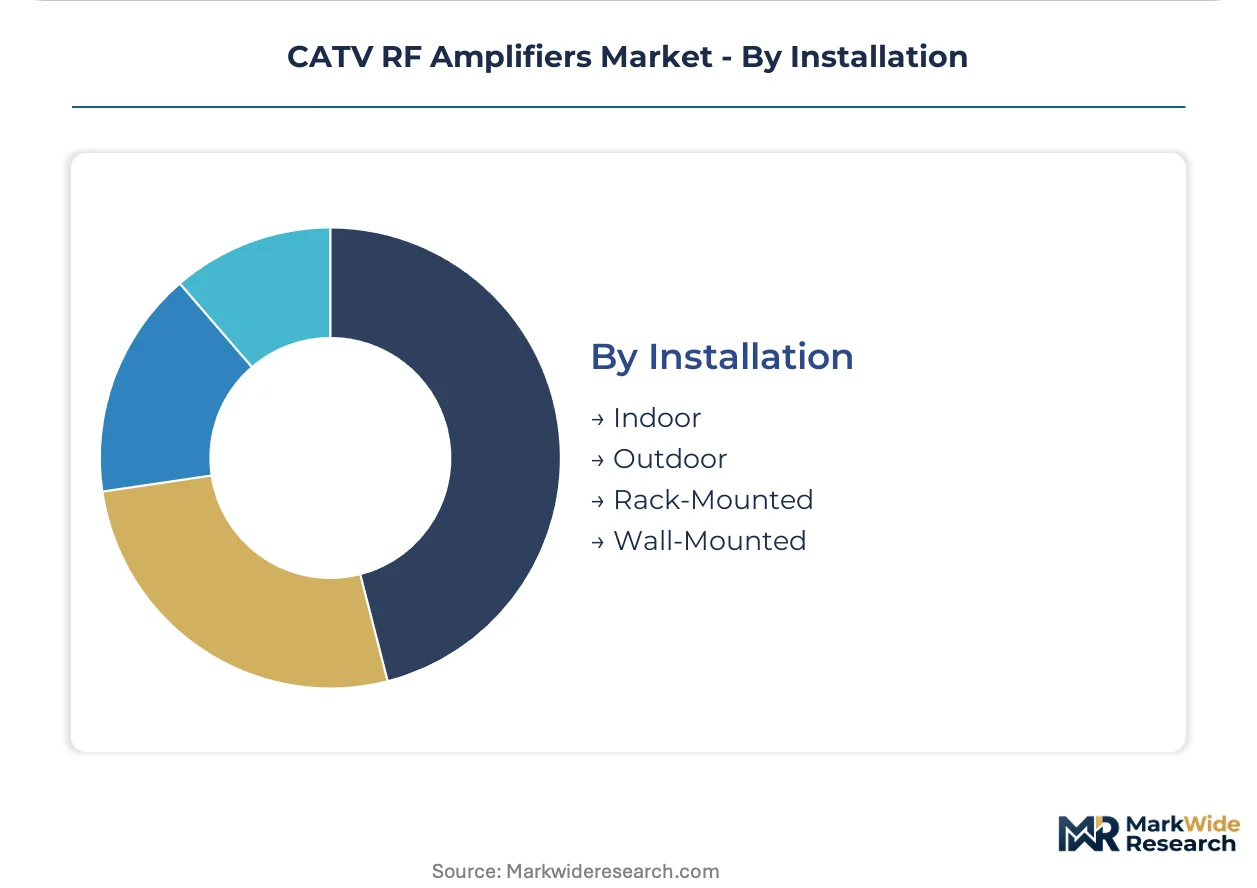
Installation:
Volume concentration favors outdoor hardened enclosures, while rack-mounted configurations face displacement from virtualized CMTS architectures.
- Outdoor:Weather-sealed housings with passive thermal management withstand temperature extremes across aerial and underground plant. United States rural broadband subsidy programs prioritize these for unserved census block deployments.
- Rack-Mounted:Standardized 19-inch chassis configurations for headend consolidation in centralized facilities.
- Indoor:Climate-controlled environments for customer premises equipment and small-scale distribution.
- Wall-Mounted:Compact form factors for multi-dwelling unit basement installations and utility room deployments.
Outdoor installations absorb the bulk of installed capacity; rack-mounted configurations face steepest contraction as distributed access architectures shift intelligence toward the network edge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium nitride substrate manufacturing concentrates in East Asian foundries, while compound semiconductor packaging gravitates toward North American and European facilities serving cable infrastructure operators.
United States
Major MSOs including Comcast, Charter, and Cox drive DOCSIS 4.0 amplifier procurement cycles across their combined footprint. FCC Part 76 emission controls and ongoing C-band spectrum reallocation mandate hardened RF plant specifications. Boston and Denver anchor headend equipment engineering clusters where GaN qualification timelines accelerate.
China
Domestic cable network expansion and export manufacturing capacity for RF amplifier modules shape demand patterns. MIIT spectrum allocation policies and GB standards compliance requirements govern equipment certification. Shenzhen and Zhengzhou host concentrated electronics manufacturing services producing CATV amplification components for global distribution.
Germany
European cable operators including Vodafone Deutschland pursue HFC infrastructure modernization under EU Green Deal energy efficiency mandates. CE marking under the EU Radio Equipment Directive imposes stringent electromagnetic compatibility testing. Munich and Stuttgart anchor precision RF component engineering centers serving continental network upgrades.
Japan
Terrestrial broadcasting networks and cable MSOs specify high-linearity amplification for multiplexed content delivery. METI industrial policy and JIS standards shape equipment procurement frameworks. Tokyo and Osaka concentrate RF semiconductor design houses collaborating with compound semiconductor foundries.
Canada
Rural broadband subsidy programs through the Universal Broadband Fund incentivize amplifier deployment in unserved census blocks. Industry Canada RSS testing requirements parallel FCC frameworks with jurisdiction-specific modifications. Toronto and Vancouver anchor cable equipment distribution networks serving tier-2 and tier-3 operator footprints.
CATV RF Amplifiers Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue optical-RF convergence and distributed access architectures. The vendor base stratifies across three tiers: integrated semiconductor conglomerates with compound semiconductor foundry access, specialized CATV equipment houses with deep operator relationships, and contract manufacturers serving cost-optimized replacement cycles. Competitive positioning hinges on GaN device qualification timelines and multi-jurisdiction certification synchronization. Consolidation pressures intensify as procurement centralization among tier-1 MSOs compresses vendor margins and standardizes specifications.
Within the integrated semiconductor tier, Skyworks Solutions, Qorvo, and Analog Devices occupy positions anchored by compound semiconductor expertise and broadband amplification portfolios. Skyworks exemplifies the GaN-on-SiC technology vector for high-linearity gain blocks. Qorvo represents North American supply security through its broadband GaN and GaAs amplifier portfolios. Analog Devices sits within the signal processing convergence archetype, bridging traditional RF amplification with digital predistortion capabilities. These three entities collectively illustrate how transistor technology leadership and operator qualification relationships determine competitive standing in DOCSIS 4.0 transition markets.
| Leading Market Players |
|---|
| Skyworks |
| NXP Semiconductors |
| Texas Instruments |
| Blonder Tongue |
| ShenZhen ChuangMo Electronics |
| Analog Devices |
| II VI Incorporated |
| SOFTEL |
| Qorvo |
| Others |
Value Chain & Pricing Dynamics
Gallium nitride wafer costs cascade through CATV RF amplifier pricing tiers, with substrate pricing volatility from East Asian foundries compressing margins on high-power GaN variants while silicon LDMOS alternatives retain cost advantage in legacy replacement cycles.
Pricing Analysis
Warranty and field-service bundling separates premium-tier GaN-based outdoor amplifiers from unbundled standard configurations where maintenance contracts carry separate fees. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—FCC Part 76 and CE marking compliance tiers command 15-25% premiums. Pricing pressure stems from procurement centralization among Comcast, Charter, and Cox compressing vendor negotiation leverage. Tier-2 and tier-3 operators exhibit highest price sensitivity, while tier-1 MSOs prioritize qualification timelines and DOCSIS 4.0 readiness over unit cost.
Supply Chain Analysis
Ocean freight and air cargo rate volatility from East Asia to North American cable equipment hubs elevates landed costs for GaN HEMT die and ceramic substrate materials. Manufacturing concentrates in China for RF component module assembly, the United States for compound semiconductor packaging, and Japan for precision RF testing equipment. Critical dependencies include GaN-on-SiC wafers, gold wire bonding materials, and hermetic sealing ceramics. Single-source vulnerability around merchant GaN foundry capacity in Taiwan and China exposes procurement timelines to geopolitical trade friction. Distribution runs through authorized distributor networks serving MSO procurement departments with consignment inventory programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CATV RF amplifier competition is becoming a vertical-integration race, with GaN device foundry access and operator qualification relationships as the decisive upstream and downstream levers separating sustainable positioning from margin erosion.
For Market Incumbents: Lock in multi-year GaN HEMT supply agreements with compound semiconductor foundries to defend against single-source concentration risks. Secure exclusive operator qualification slots for DOCSIS 4.0-ready platforms before procurement centralization among tier-1 MSOs forecloses late entrants. Prioritize backward integration into GaN-on-SiC epitaxy to capture substrate cost volatility and differentiate thermal performance specifications. For New Entrants and Emerging Players: Capture rural broadband subsidy deployment opportunities in USDA ReConnect and FCC Rural Digital Opportunity Fund census blocks where tier-2 operator price sensitivity and relaxed qualification timelines lower barriers. Target RF-over-fiber convergence architectures where optical-electrical integration creates white space outside established RF amplifier vendor relationships. Pursue channel partnerships with regional cable equipment distributors serving tier-3 operator footprints. For Investors and Strategic Acquirers: GaN device qualification acceleration by major North American MSOs is the leading indicator that compound semiconductor expertise commands sustained valuation premiums over legacy silicon LDMOS capabilities. Over the coming decade, vertically integrated specialists with captive foundry relationships and established operator certification tracks represent the most defensible acquisition archetype. Monitor FCC spectrum reallocation announcements and DOCSIS specification revision timelines as inflection signals for amplifier refresh cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Foundry Partnership | Secures substrate supply for DOCSIS 4.0 high-linearity amplification requirements. |
| Multi-Jurisdiction Certification Investment | Accelerates CE marking and FCC Part 76 parallel tracks for European and North American operator access. |
| RF-over-Fiber Platform Development | Collapses separate optical and RF procurement categories into unified headend-to-subscriber solutions. |
| Rural Broadband Subsidy Program Alignment | Positions equipment for USDA ReConnect and FCC Rural Digital Opportunity Fund disbursement flows. |
| Distributed Access Architecture Integration | Aligns amplifier intelligence with Remote PHY and MACPHY virtualization roadmaps at Comcast and Charter. |
Study Parameters
Independent corroboration across primary interviews with cable operator network engineers, RF semiconductor procurement managers, and compound semiconductor foundry executives underwrites the qualitative findings in this study. Secondary validation draws from FCC equipment authorization databases, SEC filings of publicly traded RF component vendors, and DOCSIS specification releases from CableLabs. Bottom-up demand modeling from operator deployment schedules triangulates against top-down market sizing from equipment vendor revenue disclosures.
Comparable-period anchoring to historical DOCSIS 3.1 transition cycles informed the projection horizon, with segmentation modeling across product type, technology platform, end-user category, and installation environment. CAGRs derive from unit shipment trajectories and average selling price evolution across the analysis window. Industry-specific forecast inputs include GaN device qualification timelines at major MSOs and FCC spectrum reallocation implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to compound semiconductor substrate pricing volatility and geopolitical trade policy shifts affecting East Asian foundry access. Forecasts reflect documented assumptions about DOCSIS 4.0 deployment pacing and operator capital allocation priorities. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Silicon Tuners Market
RF Components
Global Small Cell Power Amplifier Market
RF Components
Ultra-Wideband (UWB) Market
RF Components
RF Power Detector Market
RF Components
Multi-Mode Receiver Market
RF Components
RF Tester Market
RF Components
Global Bulk Acoustic Wave (BAW) Filters Market
RF Components
RF Front End Module Market
RF Components
Monolithic Microwave Integrated Circuit (MMIC) Market
RF Components
Radio Frequency Integrated Circuit (RFIC) Market
RF Components
RFID Tags Market
RF Components
RF Over Fiber (Rfof) Market
RF Components
Global RF Transceiver Market
RF Components
RF Microwave MLCC Market
RF Components
Stand-Alone Radio Receivers Market
RF Components
Smartphone RF Power Amplifier Market