
 TC-SAW Filter Market | 2026-2036
TC-SAW Filter Market Size, Share, and Industry Trends Forecast 2026-2036
TC-SAW Filter Market Analytics
Component licensing revenue is fragmenting across TC-SAW intellectual property holders as patent pools for temperature-compensated architectures lose exclusivity. Murata Manufacturing sustains leadership in thin-film deposition techniques for LiTaO3 substrates. Qualcomm Technologies leverages its modem-filter co-design strategy to anchor premium smartphone sockets. Broadcom competes through captive supply integration with its wireless semiconductor division.
A TC-SAW filter employs a piezoelectric substrate with a SiO2 compensation layer to stabilize frequency response across temperature swings from -40°C to 125°C, serving RF signal selection in crowded spectrum environments. High-frequency filters lead volume shipments as sub-6 GHz 5G bands multiply carrier aggregation requirements. MEMS Technology represents the fastest-growing fabrication approach for miniaturized modules in wearable devices. Bandpass filters occupy the deepest margin pools due to precision tuning complexity and qualification barriers.
FCC spectrum auctions in the United States and METI material certification in Japan shape product roadmaps by mandating tighter adjacent-channel rejection ratios. REACH substance restrictions in Europe force reformulation of electrode metallization stacks to eliminate restricted dopants. Stakeholders must monitor regulatory divergence between RoHS exemptions for high-reliability aerospace applications and automotive AEC-Q200 qualification timelines.
Market Dynamics
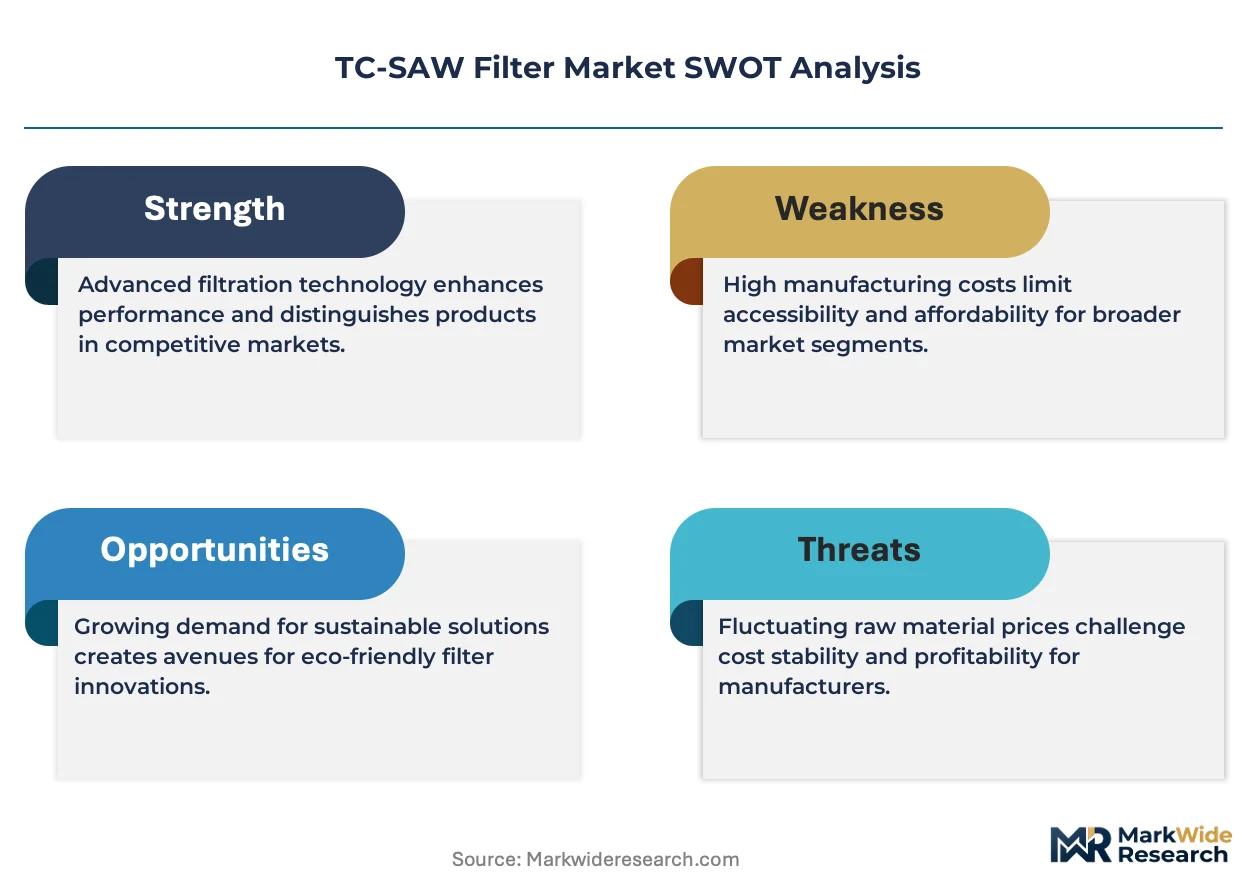
Patent expiration cycles for temperature-compensated architectures are eroding exclusivity premiums while 5G mid-band deployment concentrates procurement power among smartphone OEMs. This structural compression forces filter suppliers to defend margins through deposition process differentiation and captive substrate supply.
Growth Catalysts
- 5G Carrier Aggregation Mandates:Sub-6 GHz band multiplication requires precision RF filtering in crowded spectrum environments, pulling volume demand from smartphone OEMs.
- METI Material Certification:Japan's tightened substrate purity standards for acoustic wave devices accelerate qualification of next-generation LiTaO3 suppliers.
- Wearable Miniaturization:MEMS fabrication approaches enable module size reduction for hearables and medical patches, opening incremental sockets outside handsets.
Market Restraints
- Substrate Supply Concentration:High-purity LiTaO3 wafer production clusters in Japanese and Chinese suppliers, creating single-source vulnerability for tier-two filter vendors.
- REACH Metallization Reformulation:European substance restrictions force electrode stack redesigns, extending qualification timelines for existing product lines.
- BAW Filter Substitution:Bulk acoustic wave alternatives encroach above 2.5 GHz where TC-SAW thermal stability advantages attenuate.
Strategic Opportunities
- Automotive AEC-Q200 Qualification:V2X and satellite positioning modules create filter demand outside consumer electronics, with longer product lifecycles and higher ASP retention.
- India PLI Scheme:Domestic handset assembly incentives attract RF front-end module localization, opening captive filter sourcing relationships with emerging EMS clusters.
- Modem-Filter Co-Design Convergence:Integration of filter specification into baseband architecture definition enables premium socket capture through early engagement.
Industry Challenges
- Thin-Film Deposition Talent Scarcity:Precision SiO2 compensation layer engineering requires specialized process engineers concentrated in Japanese and South Korean facilities.
- Dual Certification Burden:Aerospace RoHS exemptions and automotive AEC-Q200 timelines impose conflicting qualification protocols on multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TC-SAW Filter Market |
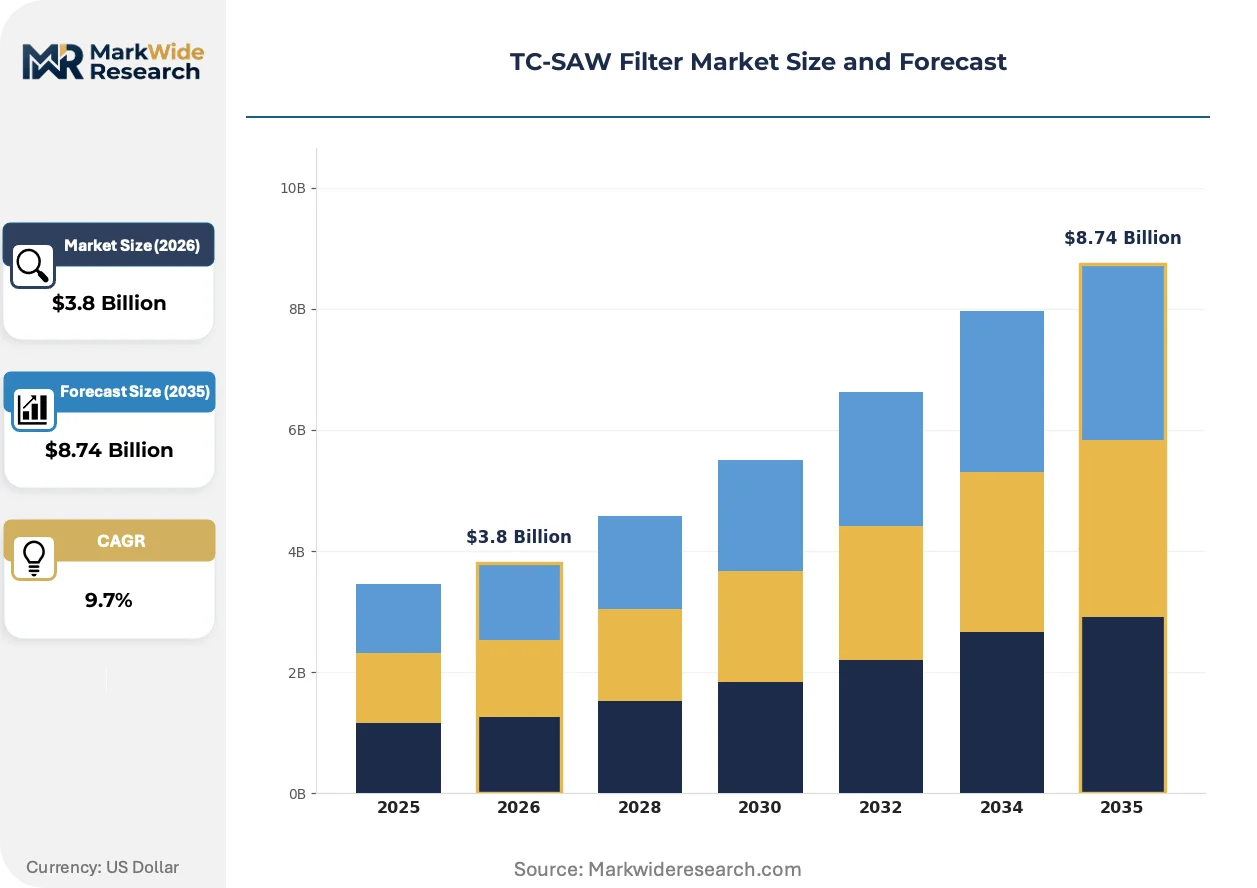
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Frequency Filters, Low-Frequency Filters, Bandpass Filters, Notch Filters Technology: Surface Acoustic Wave, Bulk Acoustic Wave, Hybrid Wave, MEMS Technology End User: Telecommunications, Aerospace, Consumer Electronics, Automotive Application: Signal Processing, Frequency Control, RF Communication, Wireless Transmission |
| Companies Covered | Taiyo Yuden Co., Ltd., Broadcom Inc., Skyworks Solutions, Kyocera Corporation, TDK Corporation, Murata Manufacturing Co., Ltd., Qualcomm Technologies, Inc., Sappland Microelectronics Technology, Qorvo, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TC-SAW Filter Market Evolving Landscape
Process innovation and regulatory compression are restructuring competitive advantage in acoustic wave devices. Three developments dominate the current cycle.
Wafer-level packaging for TC-SAW filters is collapsing the form factor gap with discrete BAW solutions while preserving cost structures. Smartphone OEMs are qualifying these modules for mid-band 5G diversity receive paths. The technology is collapsing the traditional performance-premium associated with bulk acoustic alternatives.
REACH substance restrictions in Europe are forcing electrode metallization reformulations across the supplier base. Manufacturers are substituting restricted dopants with alternative alloy stacks, extending qualification cycles by 12-18 months. Bandpass filter vendors serving automotive and industrial verticals face the steepest compliance burden.
Smartphone OEMs are consolidating RF front-end procurement into annual framework agreements with module integrators rather than discrete component sourcing. This channel compression favors suppliers with captive filter design and modem platform relationships. South Korean and Chinese handset brands are driving the fastest adoption of consolidated procurement models.
TC-SAW Filter Market Segmentation
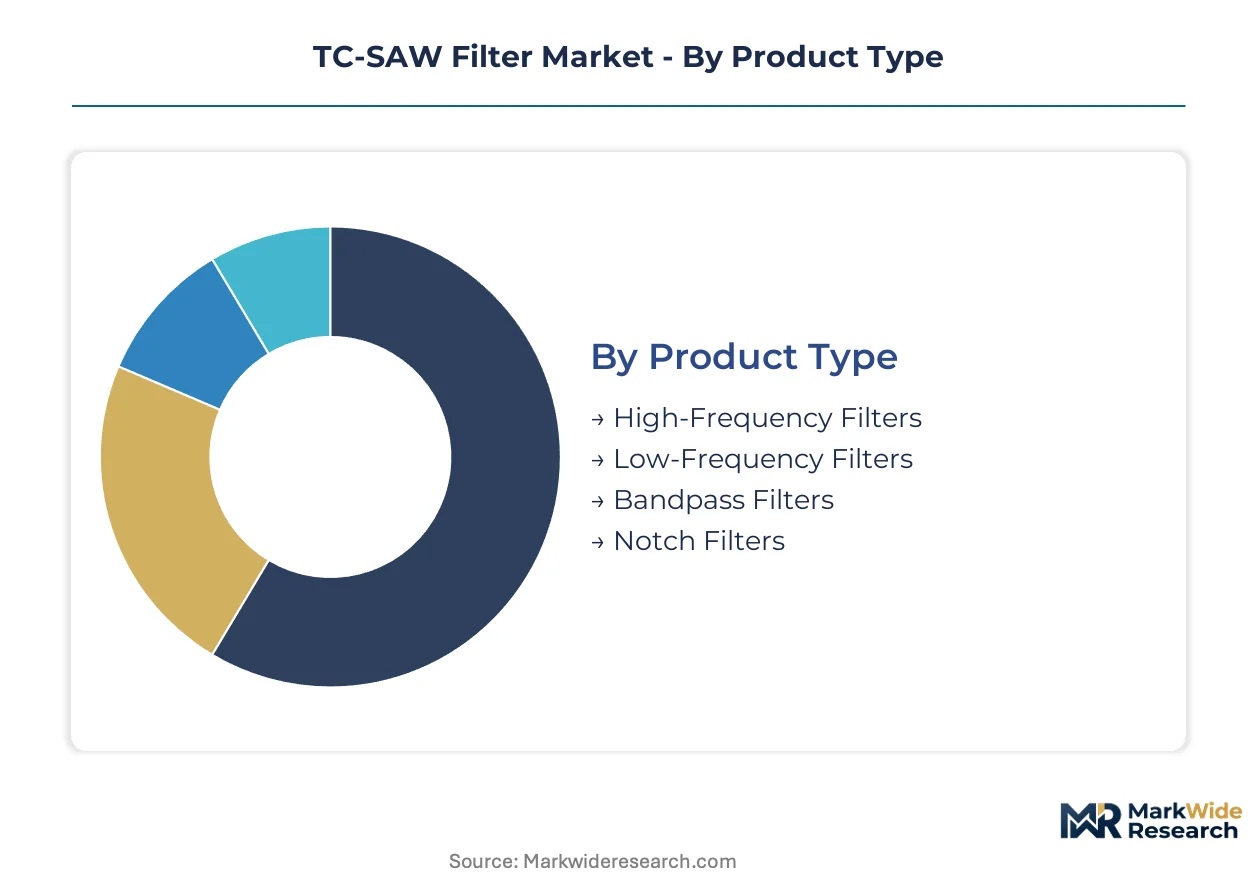
TC-SAW filter procurement patterns diverge sharply across frequency bands, fabrication methods, and end-use qualification requirements. Segment boundaries determine margin retention, certification burden, and supplier competitive positioning in this acoustic wave device market.
Product Type:
Cost tier stratification across filter categories reflects precision engineering requirements and thermal compensation complexity.
- Bandpass Filters:These devices combine precise center frequency definition with steep roll-off characteristics for adjacent-channel rejection. Demand concentrates in smartphone RF front-end modules where 5G carrier aggregation mandates multi-band coexistence. FCC spectrum auction timelines are compressing design-to-qualification cycles for premium-tier suppliers.
- High-Frequency Filters:Operating above 2.5 GHz, these filters address sub-6 GHz 5G mid-band deployment with SiO2 compensation layers stabilizing frequency drift. South Korean system semiconductor clusters around Seoul anchor procurement volume as domestic smartphone OEMs scale 5G handset output.
- Low-Frequency Filters:Sub-1 GHz designs serve legacy cellular bands and industrial telemetry with relaxed thermal compensation requirements.
- Notch Filters:These suppress narrow interference bands in crowded spectrum environments for aerospace and military communication systems.
Bandpass filters command the established base. The steepest expansion runs through high-frequency variants.
Technology:
Application requirements across telecommunications, automotive, and wearable devices are fragmenting fabrication approach selection.
- MEMS Technology:Miniaturized fabrication enables module footprint reduction below 1.0 mm x 0.8 mm for hearables and medical patches. Wearable OEMs in Japan's precision manufacturing corridor are qualifying these processes for continuous glucose monitoring devices.
- Surface Acoustic Wave:Established piezoelectric substrate architectures dominate cost-sensitive smartphone sockets with mature deposition equipment ecosystems.
- Bulk Acoustic Wave:Solidly mounted resonator structures encroach above 3.5 GHz where thermal stability requirements favor alternative acoustic modes.
- Hybrid Wave:Combined SAW-BAW architectures address wideband carrier aggregation with single-package multi-filter integration.
Surface acoustic wave processes command the established base. MEMS fabrication is climbing the fastest as wearable socket qualification accelerates.
End User:
Customer type diversity spans consumer volume, automotive longevity, and aerospace reliability qualification tiers.
- Consumer Electronics:Smartphone OEM procurement concentrates annual framework agreements with module integrators, compressing discrete component sourcing channels. Chinese handset brands are consolidating RF front-end procurement into single-supplier relationships.
- Automotive:V2X communication and satellite positioning modules require AEC-Q200 qualification with 15-year product lifecycle guarantees. German automotive tier-1 suppliers are qualifying TC-SAW filters for C-V2X roadside unit deployment.
- Telecommunications:Base station infrastructure demands high-reliability filters with RoHS exemption compliance for aerospace-grade metallization stacks.
- Aerospace:Military communication systems specify hermetic packaging and extended temperature range operation from -55°C to 125°C.
Consumer electronics commands the established base. Automotive qualification is gaining share fastest as connected vehicle deployment scales.
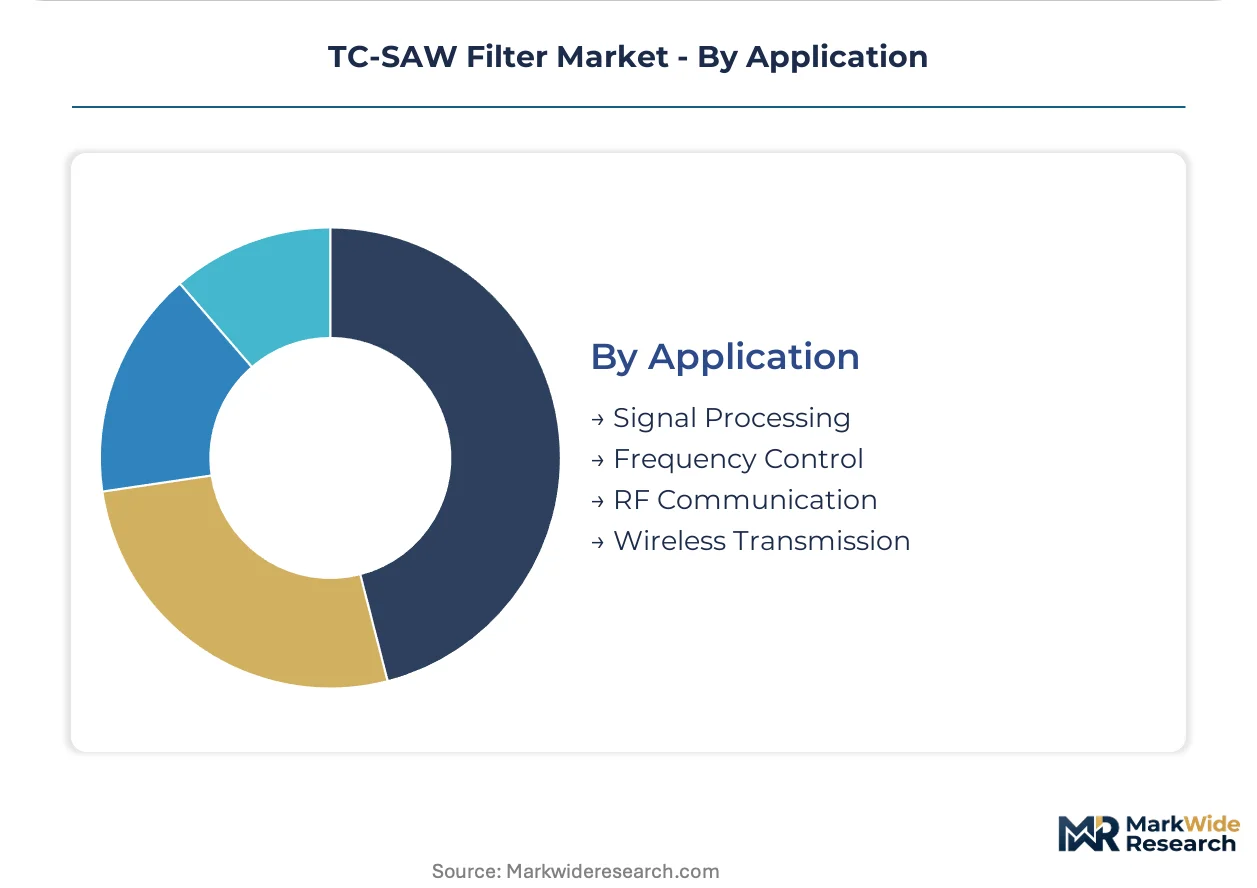
Application:
Volume distribution across functional use cases reflects RF architecture evolution in wireless systems.
- RF Communication:Transceiver front-end filtering dominates unit shipments as 5G mid-band deployment multiplies filter count per handset. Japanese METI material certification timelines are accelerating qualification of next-generation LiTaO3 substrate suppliers.
- Wireless Transmission:Power amplifier output filtering requires high power handling with minimal insertion loss for infrastructure base stations.
- Signal Processing:Intermediate frequency filtering in software-defined radio architectures demands programmable bandwidth characteristics.
- Frequency Control:Oscillator stabilization applications specify parts-per-million frequency accuracy for timing distribution networks.
RF communication commands the established base. Wireless transmission infrastructure is expanding most quickly as macro cell densification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smartphone OEMs in South Korea and China squeeze component pricing most aggressively, while automotive qualification requirements in Germany and Japan preserve margin premiums for suppliers meeting extended lifecycle guarantees.
United States
FCC spectrum auctions for sub-6 GHz bands are accelerating RF front-end module procurement timelines. The country's telecommunications regulator mandates tighter adjacent-channel rejection ratios for 5G mid-band deployment. Austin and Dallas semiconductor design centers are expanding filter specification teams for modem-filter co-design convergence.
South Korea
Domestic smartphone OEMs are consolidating annual framework agreements with module integrators, compressing discrete component sourcing channels. The country's national standards body enforces electromagnetic compatibility certification for V2X communication modules. Seoul's system semiconductor cluster anchors procurement volume as 5G handset output scales.
Japan
METI tightened substrate purity standards for acoustic wave devices, accelerating qualification of next-generation LiTaO3 suppliers. The ministry's material certification timelines are compressing design-to-production cycles for premium-tier filter vendors. Nagoya precision manufacturing corridors are qualifying MEMS fabrication processes for wearable medical devices.
Germany
Automotive tier-1 suppliers are qualifying TC-SAW filters for C-V2X roadside unit deployment under AEC-Q200 protocols. ECHA REACH substance restrictions force electrode metallization reformulations, extending qualification timelines by 12-18 months. Bavaria's automotive electronics cluster is expanding RF module testing capacity for connected vehicle programs.
China
Domestic handset brands are driving the fastest adoption of consolidated RF front-end procurement models. MIIT spectrum allocation policies for 5G mid-band are multiplying filter count requirements per device. Shenzhen and Dongguan EMS clusters are attracting captive filter sourcing relationships through localization incentives.
TC-SAW Filter Market Competitive Landscape
Capability concentration sits with deposition process specialists; scale advantage sits with captive substrate suppliers and modem-integrated platform vendors. The market structure shows tiered competition between thin-film engineering houses, integrated RF module suppliers, and semiconductor conglomerates with wireless divisions. Two strategic archetypes dominate: process-technology defenders leveraging proprietary SiO2 compensation layer expertise, and platform integrators capturing sockets through early baseband architecture engagement. Competitive moves center on backward integration into high-purity LiTaO3 wafer supply and strategic partnerships with smartphone OEMs for annual framework agreements.
Among Japanese precision component manufacturers, Taiyo Yuden Co., Ltd. and TDK Corporation exemplify the process-technology defender archetype through established thin-film deposition ecosystems. Murata Manufacturing Co., Ltd. occupies a position bridging substrate supply control with module integration capabilities. Qualcomm Technologies, Inc. anchors the platform-integrator tier through modem-filter co-design strategies that capture premium smartphone sockets.
| Leading Market Players |
|---|
| Taiyo Yuden Co., Ltd. |
| Broadcom Inc. |
| Skyworks Solutions |
| Kyocera Corporation |
| TDK Corporation |
| Murata Manufacturing Co., Ltd. |
| Qualcomm Technologies, Inc. |
| Sappland Microelectronics Technology |
| Qorvo, Inc. |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese LiTaO3 substrate finishing is compressing margin retention for tier-two filter vendors while Japanese deposition specialists maintain pricing power through METI-certified purity tiers. Utilization differentials between these regional supplier bases directly shape procurement leverage for smartphone OEMs negotiating annual framework agreements.
Pricing Analysis
Long-term offtake contracts dominate premium-tier procurement as smartphone OEMs lock capacity with Japanese deposition specialists holding METI-certified LiTaO3 supply. Three-tier pricing structure across automotive AEC-Q200, aerospace RoHS-exempt, and consumer-grade qualification levels separates margin pools sharply. Cost compression in consumer electronics sockets is intensifying because Chinese handset brands are consolidating RF front-end procurement into single-supplier relationships. Automotive OEMs show least price sensitivity due to 15-year lifecycle guarantees and qualification switching costs.
Supply Chain Analysis
Contract manufacturing concentration sits with Seoul-based system semiconductor clusters and Shenzhen-Dongguan EMS corridors serving smartphone OEM assembly. Raw material dependencies center on high-purity LiTaO3 wafers from Japanese suppliers, SiO2 compensation layer precursors from South Korean chemical specialists, and noble metal electrode alloys subject to REACH reformulation. Single-source vulnerability in substrate supply creates qualification risk for tier-two filter vendors. Distribution runs through module integrators capturing annual framework agreements rather than discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. METI material certification and AEC-Q200 qualification timelines create switching costs that protect incumbent positioning.
For Market Incumbents: Build process-technology moats through captive LiTaO3 substrate supply and proprietary SiO2 deposition expertise. Deepen backward integration into high-purity wafer production to defend against Chinese substrate cost competition. Accelerate automotive AEC-Q200 qualification pipelines to capture V2X socket expansion before BAW filter substitution encroaches above 2.5 GHz.
For New Entrants and Emerging Players: Build out MEMS fabrication capabilities for wearable medical device sockets where Japanese precision manufacturing corridors are qualifying miniaturized modules. Target India's PLI-scheme handset assembly clusters for captive filter sourcing relationships with emerging EMS players. Pursue modem-filter co-design partnerships with baseband platform vendors to bypass module integrator channel compression.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because patent expiration cycles for temperature-compensated architectures are eroding exclusivity premiums and forcing process-technology differentiation. Acquire deposition specialists with METI-certified substrate relationships and thin-film engineering talent concentrated in Japanese and South Korean facilities. Monitor BAW filter substitution rates above 2.5 GHz as inflection signal for TC-SAW thermal stability advantage erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LiTaO3 Substrate Supply | Captive wafer production insulates margin from Japanese supplier concentration and METI certification bottlenecks. |
| Automotive AEC-Q200 Qualification Expansion | V2X and satellite positioning modules extend product lifecycles beyond consumer electronics volatility. |
| MEMS Fabrication Scale-Up for Wearables | Miniaturized modules penetrate hearables and medical patches outside handset volume dependence. |
| Modem-Filter Co-Design Partnerships | Early baseband architecture engagement captures premium smartphone sockets through specification integration. |
| India PLI Localization Relationships | Domestic handset assembly incentives attract captive sourcing with emerging EMS clusters in Noida and Chennai. |
Research Methodology
A standing panel of RF front-end procurement managers, thin-film deposition process engineers, LiTaO3 substrate quality specialists, and smartphone OEM supply chain directors provided ongoing calibration. Primary fieldwork combined structured interviews with secondary validation through FCC spectrum auction filings, METI material certification databases, and AEC-Q200 qualification registries. Bottom-up unit shipment modeling across frequency bands and fabrication approaches triangulated against top-down RF module value chain estimates.
Scenario-bracketing around 5G mid-band deployment pace, BAW substitution thresholds, and REACH metallization reformulation timelines bounded forecast uncertainty. Segmentation dimensions spanned product type, fabrication technology, end-user qualification tier, and regional regulatory cluster. CAGRs derived from installed base evolution and content-per-device trajectories across the projection horizon. Forecast inputs incorporated carrier aggregation mandates, wearable miniaturization adoption curves, and automotive V2X module penetration.
Sensitivities concentrate around METI certification timeline delays, REACH substance restriction enforcement variance, and Chinese substrate supplier qualification rates. Forecasts reflect documented assumptions regarding patent expiration impact on exclusivity premiums and smartphone OEM procurement consolidation velocity. Quarterly review of BAW filter performance benchmarks, LiTaO3 wafer pricing indices, and automotive qualification pipeline backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Semiconductor Device Market
Semiconductor Devices
Global Layer Pads Market
Semiconductor Devices
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market
Semiconductor Devices
Americas Semiconductor Device Market
Semiconductor Devices
China Semiconductor Device Market
Semiconductor Devices
5G Modems Market
Semiconductor Devices
Chip on Flex Market
Semiconductor Devices
Advanced IC Substrates Market
Semiconductor Devices
Embedded Multimedia Card Market
Semiconductor Devices
Bipolar Transistors Market
Semiconductor Devices
Field Effect Transistor Market
Semiconductor Devices
Global Thermoelectric Modules Market
Semiconductor Devices
Modular Plating System Market
Semiconductor Devices
Europe Microcontroller (MCU) Market
Semiconductor Devices
Non-Volatile Dual in-Line Memory Module Market
Semiconductor Devices
Precision Link Carrier Market