
 Multiband Booster Market | 2026-2036
Multiband Booster Market Size, Share, and Industry Trends Forecast 2026-2036
Multiband Booster Market Analytics
The EU Green Deal's digital infrastructure targets are restructuring investment priorities for low-power, wide-coverage signal amplification across European commercial real estate. Wilson Electronics sustains strong channel control through specialized distribution partnerships in North American residential markets. Corning Incorporated anchors its position through captive supply of proprietary coaxial and fiber-fed booster architectures. Nextivity Inc. differentiates via cloud-managed, software-defined signal optimization platforms targeting enterprise deployments.
Multiband boosters are radio frequency amplification devices that capture weak cellular signals across multiple frequency bands, typically ranging from 700 MHz to 2700 MHz, then rebroadcast them at higher power to eliminate dead zones in buildings, vehicles, and remote installations. Indoor boosters command the largest installed base due to persistent penetration challenges in dense urban construction, while 5G-enabled units represent the fastest-expanding technology category as carriers sunset legacy UMTS spectrum. Emergency services applications carry premium margin pools because first-responder agencies require hardened, interoperable amplification systems that comply with stringent reliability benchmarks.
The FCC enforces Part 20 certification mandates that restrict booster gain levels to prevent network interference, directly shaping product design constraints for manufacturers serving the United States. ETSI harmonized standards under the EU Radio Equipment Directive govern electromagnetic compatibility and spectrum efficiency, creating divergent testing burdens for vendors operating across both jurisdictions. India's WPC licensing framework and BIS quality norms add further compliance layers for equipment imported into South Asian infrastructure projects. Stakeholders must monitor spectrum reallocation schedules and evolving national security screening protocols for telecommunications hardware as primary determinants of market access and product roadmap viability.
Market Dynamics
5G network densification is compressing deployment timelines across commercial real estate and emergency services infrastructure, forcing multiband booster architectures to absorb wider spectrum blocks while maintaining backward compatibility with legacy public safety bands.
Growth Catalysts
- Germany's Public Safety Mandates:Federal agencies now require carrier-agnostic signal amplification in all new public safety buildings, creating standardized procurement pools for hardened multiband systems.
- India's Smart City Corridors:Municipal authorities in urban connectivity zones are deploying multiband infrastructure as foundational digital layer for integrated city operations.
- Spectrum Reallocation:Carrier sunsetting of UMTS bands below 2.1 GHz is accelerating hardware refresh cycles as enterprises replace single-band legacy units.
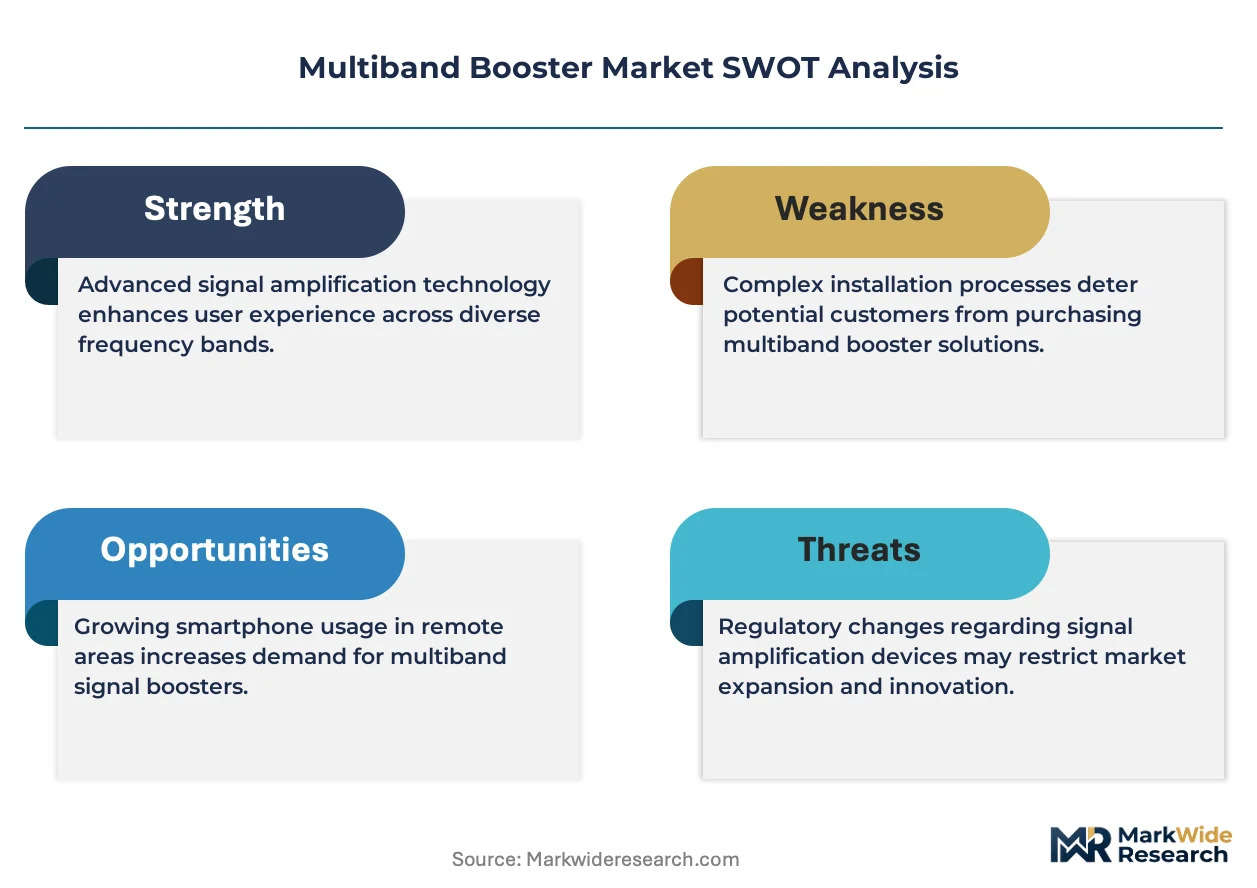
Market Restraints
- FCC Part 20 Gain Caps:Strict certification limits on amplification power constrain product design freedom and fragment R&D investment across jurisdiction-specific variants.
- GaN Substrate Concentration:Gallium nitride semiconductor supply concentrates among a handful of East Asian foundries, exposing amplifier module costs to input volatility.
- Passive DAS Substitution:Fiber-fed distributed antenna systems in greenfield commercial construction capture projects that might otherwise deploy active boosters.
Strategic Opportunities
- EU Green Deal Digital Targets:Low-power wide-coverage mandates for commercial building retrofits open premium positioning for energy-efficient amplification architectures.
- Cloud-Managed Enterprise Platforms:Software-defined signal optimization enables recurring revenue models through subscription-based remote monitoring and automatic carrier reconfiguration.
- Emergency Services Hardening:First-responder agencies in North America and Europe require interoperable systems with 99.999% reliability benchmarks, sustaining margin pools above consumer tiers.
Industry Challenges
- ETSI-FCC Divergence:Electromagnetic compatibility testing burdens multiply as vendors maintain parallel certification tracks for EU Radio Equipment Directive and United States Part 20 rules.
- RF Engineering Talent Scarcity:Specialized expertise in multiband interference mitigation and spectrum coexistence remains concentrated among legacy telecom equipment veterans nearing retirement.
- Legacy Building Integration:Dense urban construction with steel-reinforced concrete and low-E glass creates site-specific propagation modeling requirements that complicate standardized product deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiband Booster Market |
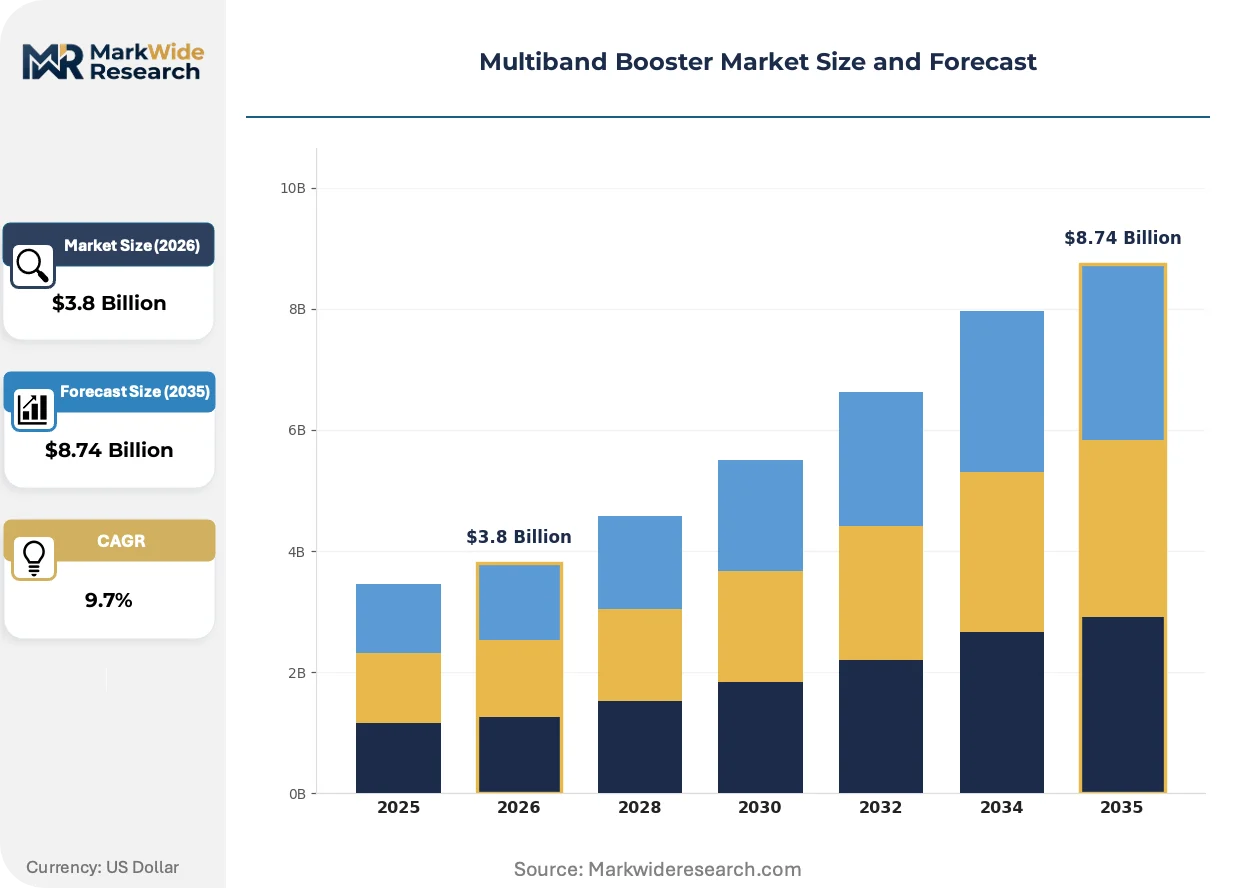
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Boosters, Outdoor Boosters, Portable Boosters, Fixed Boosters Technology: LTE, 5G, UMTS, CDMA Application: Residential, Commercial, Industrial, Emergency Services End User: Enterprises, Consumers, Government, Hospitality |
| Companies Covered | CommScope Holding Company Inc., Wilson Electronics Inc., Corning Incorporated, Amphenol Corporation, Nextivity Inc., Sunwave Communications Co. Ltd., HiBoost, SureCall, Kathrein Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiband Booster Market Evolving Landscape
Three forces are compressing the traditional booster value chain: semiconductor integration is collapsing discrete component counts, regulatory harmonization attempts are creating temporary compliance turbulence, and buyer sophistication is shifting procurement toward performance-guaranteed service models rather than hardware ownership.
Wideband power amplifiers using gallium nitride-on-silicon carbide substrates are unifying previously separate amplification chains for 700 MHz through 3.7 GHz into single hardware modules. Enterprise IT departments in healthcare and logistics facilities are adopting these consolidated architectures to reduce rack space and cooling loads. This unification is compressing vendor margins on mid-tier products while concentrating premium pricing on software-configurable platforms that can absorb future spectrum reallocations without hardware swaps.
The EU Radio Equipment Directive's 2024 harmonized standards for electromagnetic compatibility are forcing redesigns of outdoor-rated booster enclosures and antenna assemblies. Manufacturers serving both European and North American markets must now maintain dual certification tracks, with some vendors prioritizing FCC Part 20 compliance first and treating ETSI testing as secondary. Emergency services equipment faces the tightest timeline pressure, as agencies in Germany and France require updated certifications before next fiscal procurement cycles.
Building owners and facility managers are migrating from capital purchase models toward performance-based connectivity service contracts where booster vendors guarantee minimum signal strength thresholds. This shift transfers operational risk to equipment suppliers and demands remote monitoring infrastructure that most legacy manufacturers lack. The pattern is most visible in United States commercial real estate, where property technology platforms are bundling cellular amplification with WiFi and IoT sensor networks into single vendor relationships.
Multiband Booster Market Segmentation
Multiband booster procurement varies sharply by deployment environment, with capital intensity ranging from consumer-grade plug-in units to hardened emergency services installations requiring extensive RF engineering. Understanding segment boundaries clarifies where margin pools concentrate and which technology transitions reshape competitive positioning.
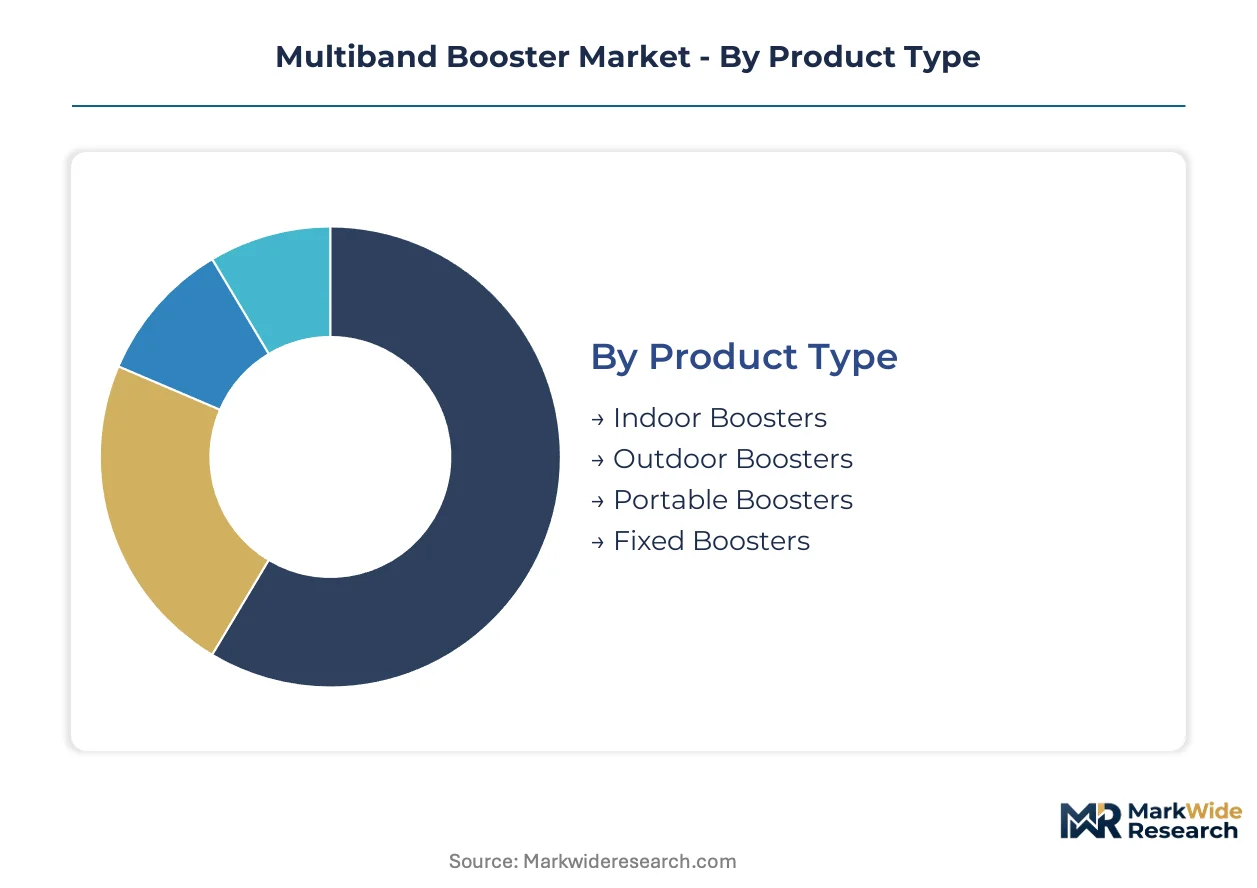
Product Type:
Capital intensity escalates from portable consumer devices through permanently installed outdoor systems requiring weatherproofing and regulatory certification.
- Indoor Boosters:Wall-mounted or rack-based amplification systems designed for building interiors, typically operating at lower gain levels to prevent interference with macro networks. Dense urban construction in Germany and India drives demand as steel-reinforced concrete and low-emissivity glass block outdoor signal penetration. These units command the largest installed base due to persistent coverage gaps in commercial and residential structures.
- Outdoor Boosters:Hardened enclosures with IP65+ ratings and directional donor antennas engineered for pole or tower mounting in exposed environments. First-responder agencies in North America specify these for remote installations and temporary incident command posts where infrastructure reliability is non-negotiable. Weatherproofing, lightning protection, and thermal management add substantial BOM cost over indoor equivalents.
- Portable Boosters:Battery-powered or vehicle-DC units for mobile deployment in recreational vehicles, marine craft, and field operations. Compact form factors prioritize ease of transport over maximum amplification power.
- Fixed Boosters:Permanent installations with dedicated power and backhaul integration, common in enterprise campuses and industrial facilities requiring guaranteed coverage footprints.
Indoor boosters absorb the bulk of installed capacity; outdoor boosters are expanding most quickly as emergency services harden infrastructure resilience.
Technology:
Technology selection determines backward compatibility obligations and future-proofing value, with carrier spectrum strategies forcing hardware refresh decisions.
- 5G:New radio architectures supporting sub-6 GHz and emerging C-band allocations, requiring wider instantaneous bandwidth and lower latency processing than legacy platforms. Enterprise IT departments in healthcare and logistics facilities prioritize these consolidated modules to reduce rack space and cooling loads while accommodating future spectrum reallocations without hardware swaps.
- LTE:Mature amplification platforms optimized for 700 MHz through 2.6 GHz bands with proven interference mitigation algorithms. Commercial real estate in the United States continues deploying these as carriers maintain LTE anchors for voice fallback, though procurement is shifting toward 5G-ready variants.
- UMTS:Legacy 3G amplification chains facing accelerated obsolescence as carriers sunset spectrum below 2.1 GHz for 5G refarming. Replacement cycles concentrate in European markets where regulators have published firm network shutdown timelines.
- CDMA:Specialized architectures serving remaining carrier networks with circuit-switched voice requirements, primarily in rural North American markets with delayed LTE migration.
LTE retains the deepest installed base; 5G is climbing the fastest as carrier densification timelines compress enterprise procurement windows.
Application:
Application context dictates reliability specifications, with mission-critical use cases demanding hardened components and redundant power architectures.
- Commercial:Office complexes, retail centers, and hospitality venues requiring consistent coverage for tenant satisfaction and operational technology connectivity. Property technology platforms in United States commercial real estate increasingly bundle cellular amplification with WiFi and IoT networks into single vendor relationships.
- Emergency Services:Police, fire, and medical response facilities requiring 99.999% availability and interoperability across multiple carrier networks. Federal agencies in Germany now mandate carrier-agnostic signal amplification in all new public safety buildings, creating standardized procurement pools with premium margin structures.
- Residential:Single-family homes and multi-dwelling units addressing consumer complaints about dropped calls and slow data speeds in suburban and rural fringe areas.
- Industrial:Manufacturing plants, warehouses, and extraction sites with metallic structures that create RF shadows and hazardous area classifications limiting equipment options.
Commercial applications dominate unit volume; emergency services sustain the steepest expansion trajectory as hardened reliability requirements proliferate across jurisdictions.
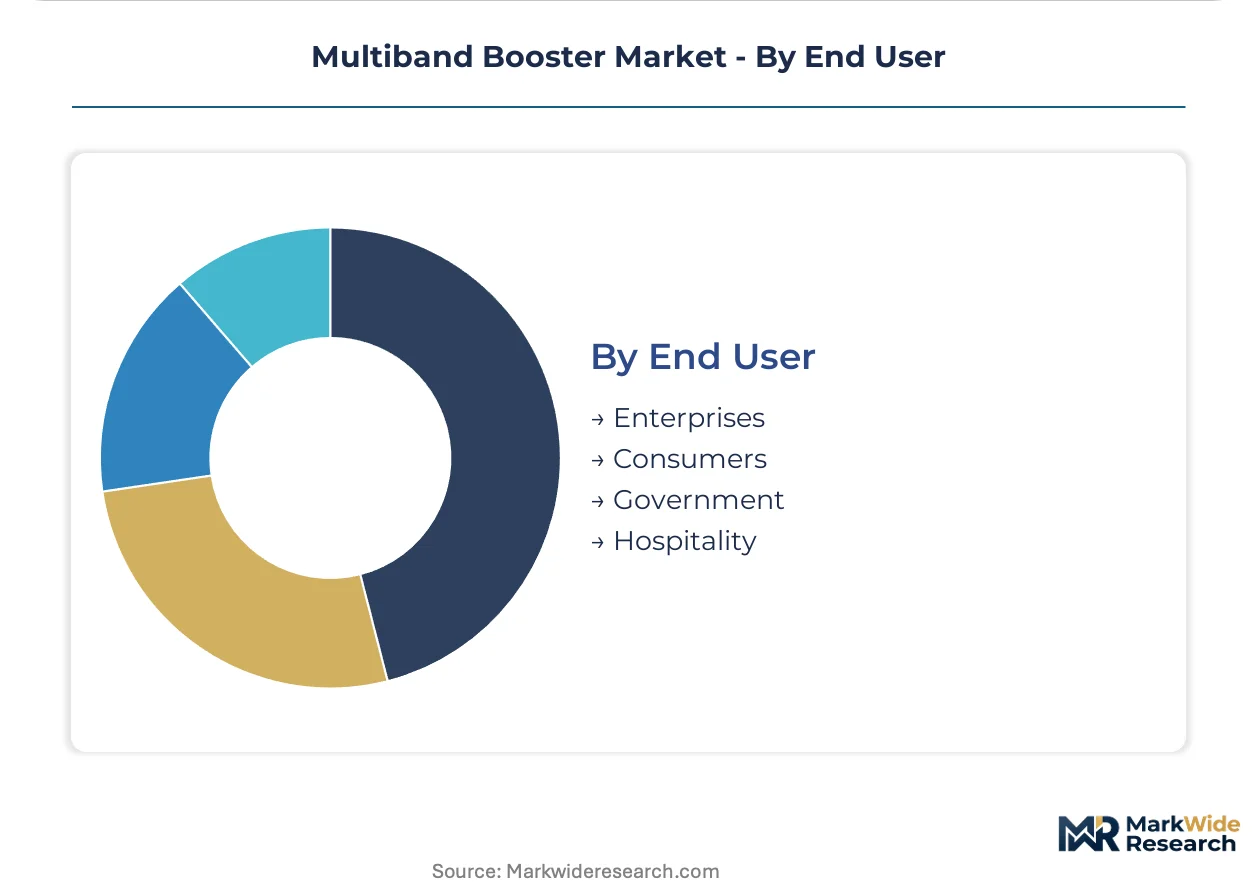
End User:
End user category shapes procurement sophistication, from price-sensitive consumer retail to complex enterprise RFP processes with performance guarantees.
- Enterprises:Corporate IT and facilities teams with dedicated connectivity budgets and technical evaluation capabilities. These buyers are migrating from capital purchase models toward performance-based service contracts where vendors guarantee minimum signal strength thresholds, transferring operational risk to equipment suppliers.
- Government:Federal, state, and municipal agencies with stringent certification requirements and extended procurement cycles. India's smart city corridors exemplify this segment as municipal authorities deploy multiband infrastructure as foundational digital layer for integrated urban operations.
- Consumers:Individual purchasers through retail channels and direct-to-consumer e-commerce, highly sensitive to price point and installation simplicity.
- Hospitality:Hotels, resorts, and event venues where guest experience metrics directly tie to cellular coverage quality and online review scores.
Enterprises account for the largest revenue concentration; government procurement is gaining share fastest as public safety mandates and smart city programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangalore's smart city corridors anchor South Asian deployment momentum as municipal authorities install multiband infrastructure for integrated urban operations. Procurement patterns across emergency services and commercial real estate are diverging sharply by jurisdiction.
United States
Commercial real estate in Dallas and Atlanta drives enterprise procurement as property technology platforms bundle cellular amplification with WiFi networks. FCC Part 20 rules enforce strict gain caps that constrain product design freedom for manufacturers. Healthcare facilities in the Boston metro prioritize 5G-ready architectures to reduce rack space and cooling loads.
Germany
Federal agencies mandate carrier-agnostic signal amplification in all new public safety buildings, creating standardized procurement pools for hardened systems. The EU Radio Equipment Directive's harmonized standards force redesigns of outdoor-rated booster enclosures. Industrial corridors in North Rhine-Westphalia deploy multiband infrastructure for manufacturing connectivity.
India
Municipal authorities in Gujarat and Maharashtra deploy multiband infrastructure as foundational digital layers for smart city operations. WPC licensing and BIS quality norms add compliance layers for imported equipment. Telangana's urban connectivity zones concentrate government procurement for integrated city operations.
China
MIIT spectrum reallocation schedules accelerate hardware refresh cycles as carriers refarm legacy bands for 5G deployment. Yangtze River Delta manufacturing clusters absorb wideband power amplifiers using gallium nitride substrates. Shenzhen's telecommunications hardware ecosystem supplies amplifier modules across Asia-Pacific infrastructure projects.
United Kingdom
London commercial real estate migrates from capital purchase models toward performance-based connectivity service contracts. ETSI electromagnetic compatibility standards govern certification requirements alongside post-Brexit regulatory divergence. Scotland's emergency services procurement requires hardened systems with 99.999% reliability benchmarks.
Multiband Booster Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and software-configurability dimensions. The vendor base stratifies into three tiers: integrated conglomerates with captive component supply, specialized RF engineering houses with deep certification expertise, and regional assemblers competing on price. Dominant competitive moves include M&A to absorb RF engineering talent and strategic partnerships with property technology platforms for recurring revenue service models.
Among North American specialists, Wilson Electronics and Nextivity occupy positions at opposite ends of the sophistication spectrum. Wilson Electronics exemplifies the channel-control archetype through specialized distribution partnerships in residential markets. Nextivity represents the software-defined platform approach with cloud-managed signal optimization targeting enterprise deployments. Corning Incorporated anchors the integrated conglomerate tier through captive supply of proprietary coaxial and fiber-fed architectures. CommScope Holding Company Inc. sits within the infrastructure-scale tier, its portfolio breadth spanning passive and active distribution systems.
| Leading Market Players |
|---|
| CommScope Holding Company Inc. |
| Wilson Electronics Inc. |
| Corning Incorporated |
| Amphenol Corporation |
| Nextivity Inc. |
| Sunwave Communications Co. Ltd. |
| HiBoost |
| SureCall |
| Kathrein Inc. |
| Others |
Value Network & Pricing Analysis
Captive supply of proprietary coaxial and fiber-fed booster architectures anchors both manufacturing control and premium pricing power for integrated conglomerates serving emergency services and enterprise segments. This integration choice insulates tier-one vendors from GaN substrate volatility while forcing price discipline on regional assemblers competing through outsourced amplifier module procurement.
Pricing Analysis
Value-based pricing anchored to guaranteed signal strength thresholds dominates enterprise procurement as building owners shift from capital purchase to performance-contract models. Three-tier pricing structure across hardened emergency services, certified commercial, and unlicensed consumer levels separates premium margin pools from commodity segments. Pricing pressure stems from carrier-agnostic mandate standardization in Germany compressing differentiation scope. Government buyers exhibit lowest price sensitivity due to 99.999% reliability specifications, while residential consumers drive cost compression through retail channel price transparency.
Supply Chain Analysis
Refurbishment flows for outdoor-rated booster enclosures create secondary supply channels as EU Radio Equipment Directive redesigns accelerate hardware obsolescence. GaN-on-siC substrate production concentrates in China, Japan, and South Korea, with amplifier module assembly tethered to Shenzhen's telecommunications hardware ecosystem. Supply chain risk centers on single-source vulnerability for wideband power amplifier foundry capacity. Distribution runs through specialized RF engineering distributors in North America and direct municipal procurement in India's smart city corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The multiband booster market sits in a technology-transition phase as 5G NR architectures displace legacy LTE and UMTS amplification chains across enterprise and emergency services infrastructure.
For Market Incumbents: Deepen captive supply control over GaN semiconductor sourcing to offset East Asian foundry concentration risk. Expand cloud-managed platform R&D to capture recurring revenue from performance-based service contracts, defending against software-defined entrants eroding hardware margins through subscription models. For New Entrants and Emerging Players: Capture white-space in India's smart city corridors where WPC licensing complexity disadvantages established Western vendors. Target municipal authorities in Gujarat and Maharashtra with localized certification support and direct government sales channels, bypassing saturated North American distribution. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated infrastructure conglomerates seeking RF engineering talent and certification expertise. Long-term viability favors vendors with software-configurable platforms capable of absorbing spectrum reallocations without hardware refresh cycles. Monitor FCC Part 20 and ETSI harmonization timelines for regulatory divergence inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Managed Platform Development | Enables recurring revenue from remote monitoring and automatic carrier reconfiguration for enterprise deployments. |
| GaN Substrate Supply Agreement | Secures amplifier module cost stability against East Asian foundry concentration and input volatility. |
| Emergency Services Certification Investment | Unlocks premium margin pools through 99.999% reliability benchmarks mandated by German federal agencies. |
| Smart City Direct Procurement Partnership | Bypasses channel complexity to capture municipal infrastructure spend in India's urban connectivity zones. |
| Dual-Track Regulatory Compliance | Maintains market access across FCC Part 20 and EU Radio Equipment Directive jurisdictions without redesign delays. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across RF engineering directors, emergency services procurement officers, commercial real estate facilities managers, and telecommunications carrier network planners. FCC Part 20 certification databases, ETSI harmonized standards documentation, India's WPC licensing registers, and carrier spectrum reallocation notices provided bottom-up validation triangulated against top-down market sizing.
Data-stream reconciliation across shipment volumes, installation permits, and certification approvals informed the analytical framework. Segmentation dimensions modeled include product type, technology generation, application environment, and end-user procurement sophistication across the projection horizon. CAGRs derived from unit economics of GaN substrate cost curves, carrier densification timelines, and regulatory mandate implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to spectrum reallocation timing and semiconductor supply concentration. Practitioners should monitor FCC-ETSI regulatory divergence, GaN foundry capacity announcements, and smart city procurement award patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Gan RF Semiconductor Devices Market
RF Components
China Small Signal Transistor Market
RF Components
Global RF and Microwave Power Transistors Market
RF Components
Acoustic Wave Filters Market
RF Components
RF Gan Market
RF Components
RF Spectrum Analyzer Market
RF Components
Global RF Plasma Generator Market
RF Components
Dielectric Resonator Market
RF Components
Small Signal Mosfets Market
RF Components
Radio Frequency Front End Module Market
RF Components
Radio Frequency Counter Market
RF Components
RF Microwave MLCC Market
RF Components
Embedded Antenna Systems Market
RF Components
RF Interconnect Market
RF Components
RF Antenna Market
RF Components
RF Acoustic Wave Filters Market