
 Digital Vacuum Regulators Market | 2026-2036
Digital Vacuum Regulators Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Vacuum Regulators Market Insights
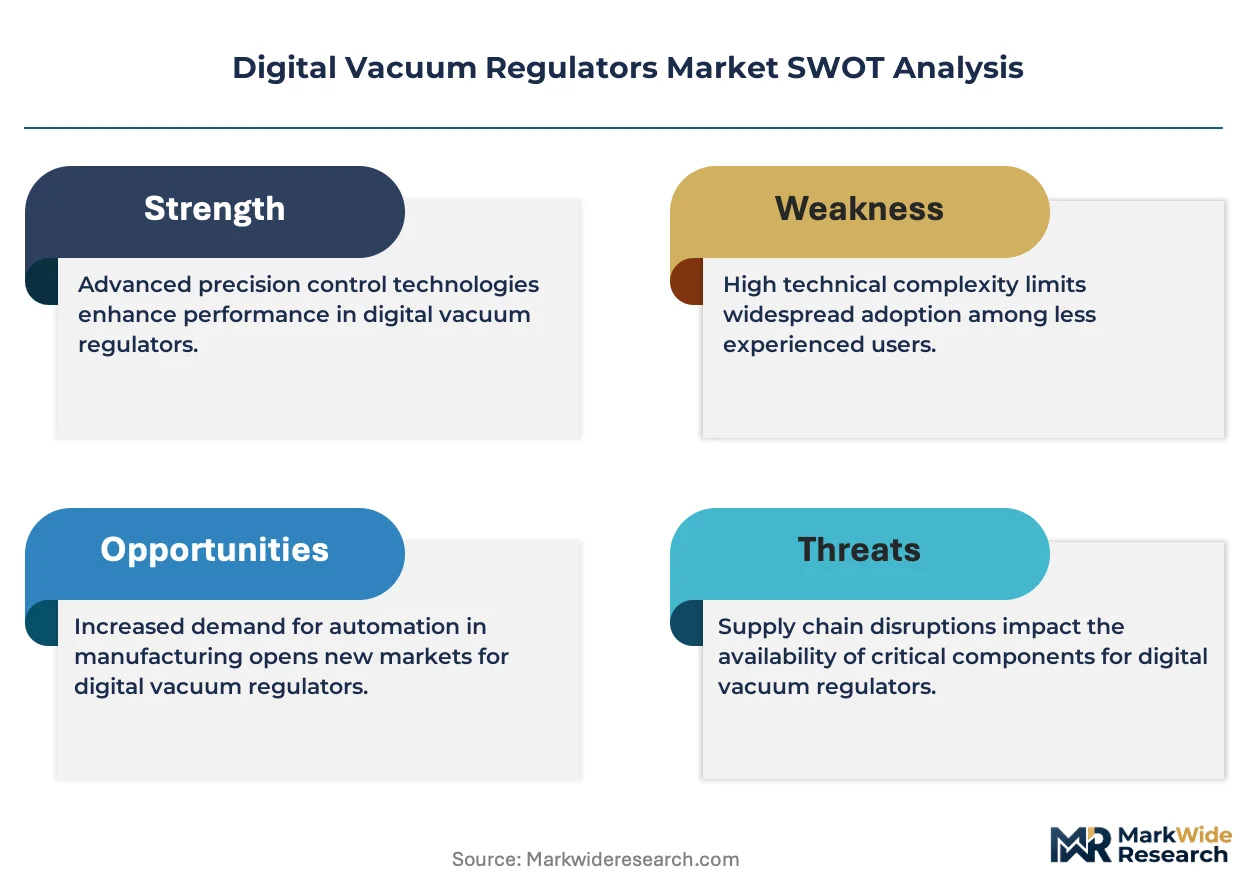
Asset-light leasing models for precision vacuum equipment are narrowing the competitive field for capital-constrained entrants. Pfeiffer Vacuum Technology AG leverages its captive service network to sustain long-term customer lock-in. MKS Instruments anchors its position through backward integration into pressure sensor substrates. Leybold GmbH differentiates via geographic dominance in European semiconductor installations.
Digital vacuum regulators are electromechanical devices that maintain precise sub-atmospheric pressure setpoints using closed-loop feedback from integrated pressure or flow sensors, typically achieving control accuracy within 0.1% of full scale. They serve critical process stability roles in thin-film deposition, freeze-drying, and analytical instrumentation where pressure excursions ruin batch yields. Electronic regulators command the widest margin pools due to sensor fusion complexity and firmware customization barriers. Microcontroller-based technology leads unit growth as fabs demand EtherCAT and Profinet digital interfaces for Industry 4.0 integration. Pharmaceuticals represents the most defensible end-user segment given validation requirements and replacement inertia.
FDA 21 CFR Part 11 compliance shapes pharmaceutical buyer specifications for audit trails and electronic signatures on regulator controllers. The EU F-Gas Regulation and REACH restrict elastomer seal chemistries, forcing redesigns of pneumatic regulator valve trains. EPA emissions guidelines for chemical processing push demand toward sealed electronic architectures with zero vent-to-atmosphere designs. Stakeholders must weigh sensor interoperability standards against proprietary ecosystem bets as fabs consolidate supplier panels.
Market Dynamics
Semiconductor fabs in Taiwan and South Korea are consolidating supplier panels around EtherCAT-compatible electronic regulators, compressing the addressable vendor base while elevating firmware customization barriers for remaining participants.
Growth Catalysts
- EU F-Gas Regulation:Tightening permissible leak rates for fluorinated gases is pushing OEMs toward microcontroller-based units with real-time sensor feedback loops in etching and deposition chambers.
- Thin-film deposition:Process stability requirements in advanced node manufacturing are elevating demand for closed-loop pressure control achieving 0.1% full-scale accuracy.
- Taiwan electronics clusters:Concentrated procurement from Hsinchu Science Park fabs is creating volume anchors that fund R&D amortization across product generations.
Market Restraints
- Pressure sensor substrate concentration:Backward integration into MEMS substrates by dominant suppliers limits second-source availability for mid-tier regulator assemblers.
- REACH elastomer restrictions:Compliance-driven redesigns of pneumatic valve trains are extending qualification timelines and freezing engineering resources.
- Capacitive manometer substitution:Direct pressure measurement systems in certain analytical instrumentation applications are bypassing regulator-mediated control loops entirely.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO validation requirements and replacement inertia in freeze-drying equipment create defensible installed bases for audit-trail-compliant controllers.
- Profinet-OPC UA convergence:Dual-protocol firmware stacks are opening retrofit opportunities in European chemical processing plants seeking Industry 4.0 integration without full line replacement.
- Asset-light leasing:Service-contract bundling of precision vacuum equipment is narrowing the competitive field and extending customer lock-in through captive calibration networks.
Industry Challenges
- FDA 21 CFR Part 11 compliance:Pharmaceutical buyers require electronic signatures and immutable audit trails on regulator controllers, compressing vendor qualification pools to firmware-validated suppliers.
- Legacy analog integration:Semiconductor fabs operating mixed-vintage toolsets face signal interoperability failures when deploying digital regulators alongside 4-20mA legacy architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Vacuum Regulators Market |
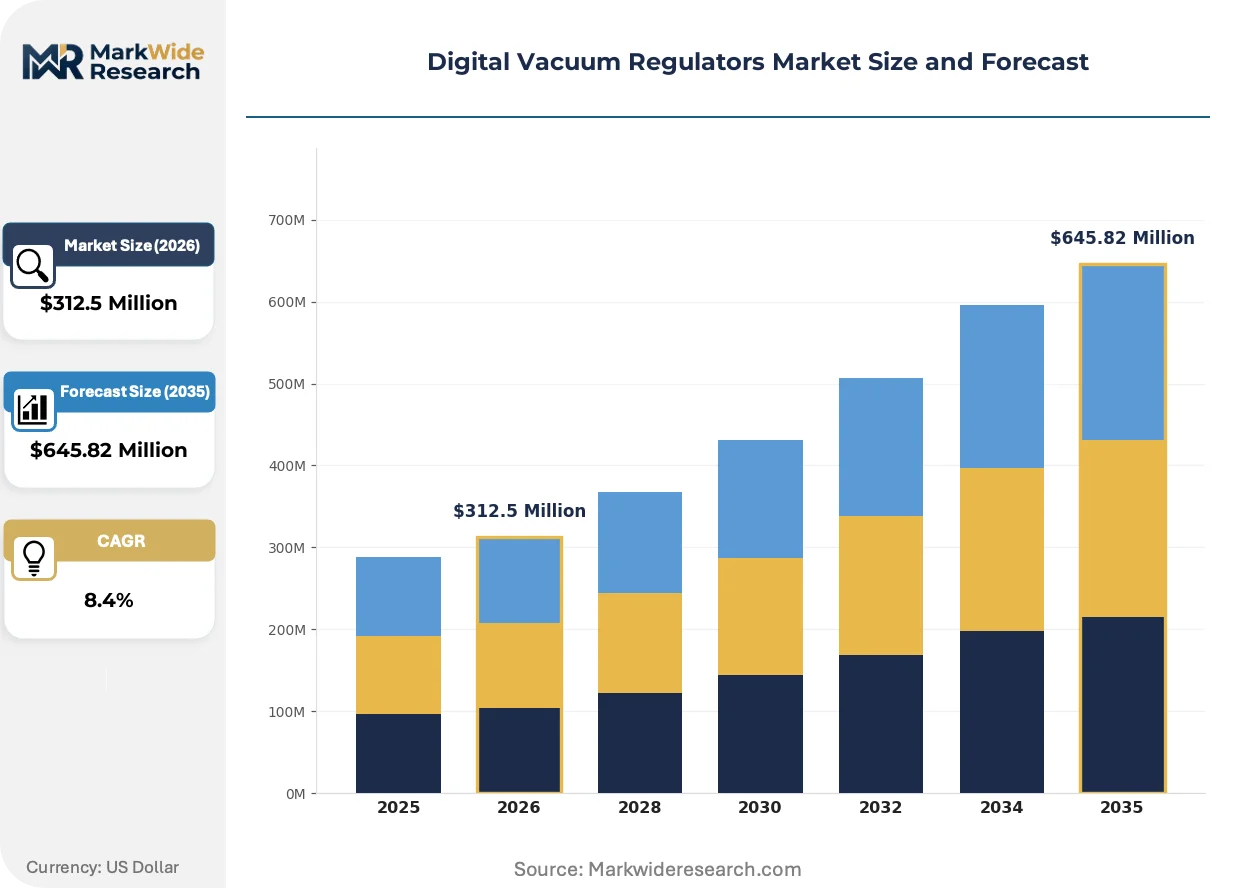
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic Regulators, Electronic Regulators, Handheld Regulators, Fixed Regulators Technology: Microcontroller-Based, Analog-Digital Hybrid, Pressure Sensors, Flow Sensors End User: Pharmaceuticals, Food Processing, Electronics Manufacturing, Chemical Processing Installation: Wall-Mounted, Portable, Inline, Bench-Mounted |
| Companies Covered | Pfeiffer Vacuum Technology AG, Edwards Vacuum, Brooks Automation, MKS Instruments, Leybold GmbH, ULVAC, Atlas Copco, Parker Hannifin Corporation, Festo AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Vacuum Regulators Market Trends and Innovations
Digital vacuum regulation is pivoting from discrete component sales toward embedded sensor-fusion platforms, with firmware-defined functionality displacing hardware-differentiated competition across process industries.
Sensor fusion is collapsing the traditional separation between pressure measurement and flow control functions into unified microcontroller architectures. Fabs in South Korea are adopting these integrated units at replacement-cycle velocity. This compression is eliminating standalone transducer suppliers from regulator bill-of-materials.
REACH and the EU F-Gas Regulation are jointly restricting elastomer chemistries and leak-rate thresholds for pneumatic systems. Equipment OEMs are responding with sealed electronic architectures that eliminate vent-to-atmosphere designs. Pharmaceutical freeze-dryer manufacturers face the steepest redesign curves under these combined pressures.
Buyer concentration among Taiwan and South Korean semiconductor foundries is compressing negotiation leverage for smaller regulator vendors. Direct procurement contracts with fab operators are displacing distributor-mediated sales channels in East Asian electronics manufacturing clusters. Equipment lessors with captive service networks are capturing margin pools previously held by component suppliers.
Digital Vacuum Regulators Market Segmentation
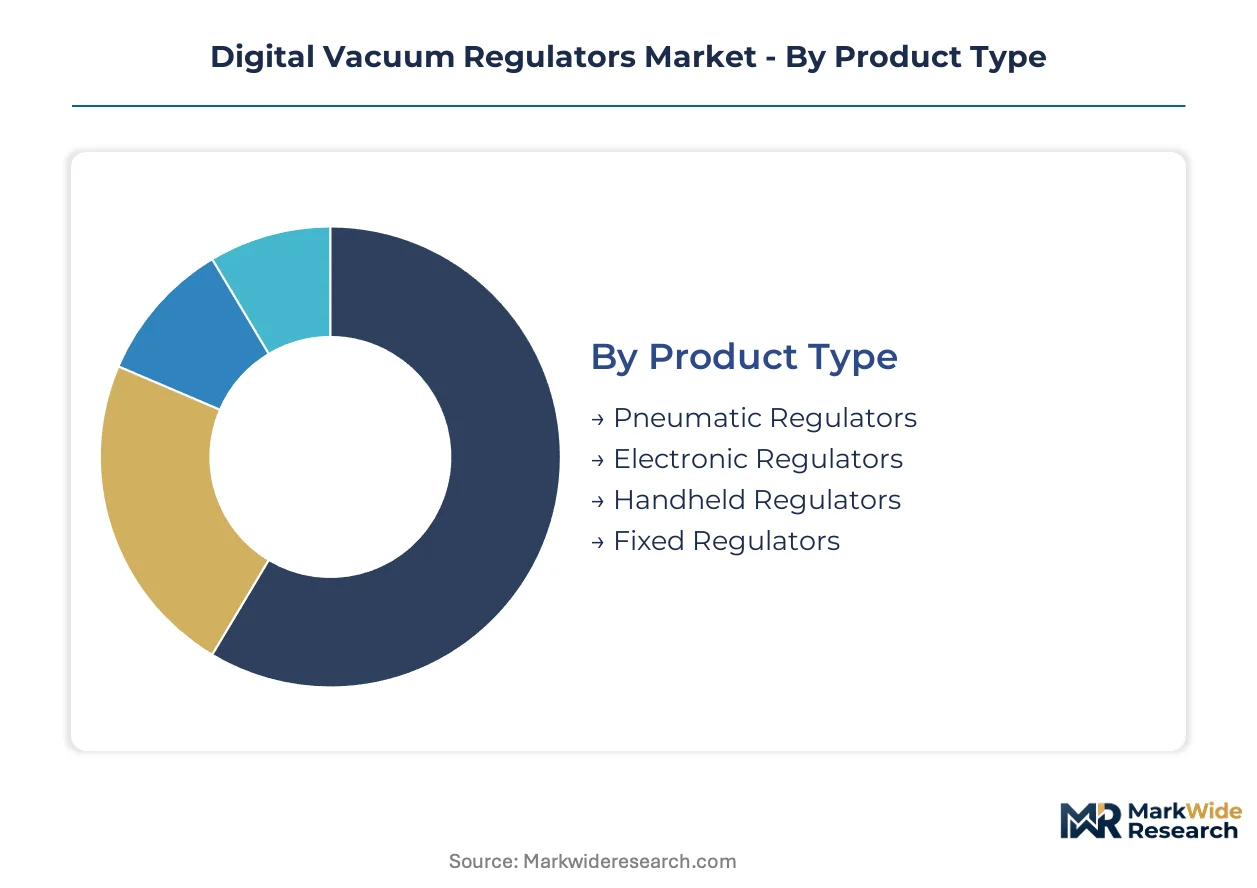
Segmentation in digital vacuum regulators reveals how pressure control architectures align with distinct process requirements. Product type and technology choices determine firmware complexity, while end-user verticals impose divergent validation and connectivity standards.
Product Type:
Use-case spectrum spans legacy pneumatic systems to EtherCAT-enabled electronic platforms serving semiconductor etching chambers.
- Electronic Regulators:Closed-loop architectures integrate MEMS pressure sensors with microcontroller firmware, achieving 0.1% full-scale accuracy. Taiwan and South Korean fabs concentrate procurement for advanced node deposition tools, driven by Industry 4.0 digital interface requirements.
- Pneumatic Regulators:Mechanical feedback systems using compressed air pilot signals dominate legacy chemical processing installations. REACH elastomer restrictions and EU F-Gas leak-rate thresholds are forcing redesigns of valve train architectures.
- Handheld Regulators:Battery-powered portable units serve field calibration and maintenance workflows in distributed pharmaceutical facilities.
- Fixed Regulators:Pre-set mechanical devices anchor cost-sensitive food packaging lines where pressure stability requirements remain modest.
The dominant share belongs to Electronic Regulators, while Pneumatic Regulators is closing the gap fastest through sealed-architecture retrofits.
Technology:
Cost tier separation runs from commodity sensor components to firmware-defined platforms commanding premium positioning.
- Microcontroller-Based:Unified architectures collapse pressure measurement and flow control into single-chip designs with EtherCAT and Profinet protocol stacks. South Korean fabs are adopting these at replacement-cycle velocity, displacing standalone transducer suppliers from regulator bill-of-materials.
- Pressure Sensors:Capacitive and piezoresistive MEMS elements provide primary feedback loops for sub-atmospheric setpoint maintenance. Backward integration by dominant suppliers limits second-source availability for mid-tier assemblers.
- Analog-Digital Hybrid:Bridge architectures ease migration from 4-20mA legacy toolsets in mixed-vintage semiconductor fabs facing signal interoperability failures.
- Flow Sensors:Thermal mass and differential pressure elements enable direct mass flow control in analytical instrumentation bypassing regulator-mediated loops entirely.
Microcontroller-Based systems command the premium tier, with Pressure Sensors expanding most quickly through captive substrate production.
End User:
Application maturity varies sharply across validation-intensive pharmaceuticals versus price-sensitive food processing.
- Electronics Manufacturing:Taiwan's Hsinchu Science Park and South Korean foundry clusters drive concentrated demand for closed-loop deposition chamber control. Direct procurement contracts with fab operators are displacing distributor channels.
- Pharmaceuticals:Freeze-drying equipment manufacturers face FDA 21 CFR Part 11 audit trail requirements and replacement inertia, creating defensible installed bases for firmware-validated suppliers.
- Chemical Processing:EPA emissions guidelines push demand toward sealed electronic architectures with zero vent-to-atmosphere designs in US Gulf Coast installations.
- Food Processing:Modified atmosphere packaging lines employ basic fixed regulators where pressure excursion tolerance remains higher than pharmaceutical or semiconductor standards.
Electronics Manufacturing holds the volume anchor position, though Pharmaceuticals shows the steepest expansion trajectory through CDSCO validation requirements in India.
Installation:
Customer type and facility configuration dictate mounting architecture tradeoffs between permanent integration and operational flexibility.
- Inline:Direct pipeline integration serves continuous chemical processing and semiconductor gas distribution systems requiring minimal footprint.
- Wall-Mounted:Permanent installations anchor central vacuum supply infrastructure in pharmaceutical manufacturing suites.
- Portable:Mobile units support multi-line servicing in contract manufacturing organizations with fluctuating equipment layouts.
- Bench-Mounted:Laboratory-scale configurations serve analytical instrumentation and R&D prototyping workflows.
Inline configurations dominate capital-intensive process installations, while Portable units are gaining share fastest through asset-light leasing models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Taiwanese and South Korean electronics clusters where direct fab procurement contracts squeeze component margins, while European pharmaceutical and chemical processing markets reward firmware-validated suppliers with premium positioning.
United States
EPA emissions guidelines for chemical processing push Gulf Coast installations toward sealed electronic architectures with zero vent-to-atmosphere designs. FDA 21 CFR Part 11 compliance requirements shape pharmaceutical buyer specifications for audit trails and electronic signatures on regulator controllers. Greater Boston and Research Triangle Park host analytical instrumentation manufacturers demanding closed-loop pressure control accuracy.
Germany
REACH elastomer restrictions and EU F-Gas leak-rate thresholds force redesigns of pneumatic valve train architectures in chemical processing equipment. Profinet-OPC UA convergence opens retrofit opportunities in Rhineland chemical plants seeking Industry 4.0 integration. Baden-Württemberg's precision engineering cluster anchors European semiconductor equipment supply chains.
South Korea
Samsung and SK Hynix fabs in Pyeongtaek and Icheon drive concentrated procurement of EtherCAT-compatible electronic regulators at replacement-cycle velocity. MFDS pharmaceutical validation requirements create defensible installed bases for audit-trail-compliant freeze-drying equipment controllers. Busan-Ulsan industrial corridor hosts petrochemical processors adopting sealed electronic architectures.
Taiwan
TSMC and UMC fabs in Hsinchu Science Park consolidate supplier panels around microcontroller-based units with real-time sensor feedback loops for etching and deposition chambers. Direct procurement contracts with fab operators displace distributor-mediated sales channels. Tainan Science Park expansion extends demand concentration into southern Taiwan.
India
CDSCO validation requirements and replacement inertia in pharmaceutical freeze-drying equipment create defensible installed bases for firmware-validated suppliers. Maharashtra's pharmaceutical manufacturing belt in Thane and Pune drives demand for audit-trail-compliant controllers. Gujarat's chemical processing corridor faces EPA-aligned emissions pressure toward sealed electronic architectures.
Digital Vacuum Regulators Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in sensor substrates and valve trains. The vendor base organizes around three strategic archetypes: captive service networks extending customer lock-in through calibration bundling, backward-integrated pressure sensor substrate producers, and geographic-dominant installation specialists. Consolidation pressure intensifies as semiconductor fabs narrow supplier panels. M&A activity targets firmware capabilities and regional service footprints.
Among Germany-based vacuum technology specialists, Pfeiffer Vacuum Technology AG and Leybold GmbH occupy positions shaped by European semiconductor installation density and captive service network scale. MKS Instruments exemplifies the sensor-substrate-integrated archetype through its pressure measurement upstream control. These three anchors illustrate how geographic concentration and backward integration into MEMS elements define sustainable positioning.
| Leading Market Players |
|---|
| Pfeiffer Vacuum Technology AG |
| Edwards Vacuum |
| Brooks Automation |
| MKS Instruments |
| Leybold GmbH |
| ULVAC |
| Atlas Copco |
| Parker Hannifin Corporation |
| Festo AG |
| Others |
Pricing and Supply Chain Analysis
The Kaohsiung-Tokyo-Nagoya maritime corridor carries MEMS pressure sensor substrates and microcontroller components that feed East Asian electronics clusters, with freight cost volatility amplifying price spreads between configured-to-order electronic regulators and standard pneumatic units while compressing margins for distributors serving Taiwan's Hsinchu Science Park fabs.
Pricing Analysis
The customization-premium spread separates EtherCAT-compatible electronic regulators—commanding firmware-validated pricing—from legacy pneumatic architectures facing cost compression. Three-tier pricing structure across premium, standard, and economy levels stratifies by Industry 4.0 protocol certification and FDA 21 CFR Part 11 compliance grade. Price differentiation hinges on sensor fusion complexity and captive calibration network access. Semiconductor fabs in South Korea show lowest price sensitivity given yield-loss economics, while food packaging lines anchor the economy tier with fixed-regulator procurement. Margins are tightening in mid-tier pneumatic retrofits due to REACH-driven elastomer redesign costs.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwan-based EMS providers and South Korean system integrators holding captive capacity for microcontroller-based regulator assembly. Geographic supply concentration centers on Taiwan for MEMS pressure sensor substrates, Germany for precision valve train components, and Japan for capacitive manometer elements. Raw material dependencies draw from fluorosilicone elastomers, silicon wafers for MEMS fabrication, and rare-earth magnets for proportional valve actuators. Single-source vulnerability in MEMS substrate supply threatens second-source availability for mid-tier assemblers. Distribution runs through direct fab procurement contracts in East Asia, displacing traditional industrial distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against capacitive manometer systems that bypass regulator-mediated control loops entirely in analytical instrumentation applications.
For Market Incumbents: Pre-empt displacement by capacitive manometer substitution through firmware-defined sensor fusion platforms that collapse pressure measurement and flow control into unified architectures. Anchor customer lock-in via captive calibration networks extending service-contract bundling. Defend against panel consolidation by Taiwan and South Korean fabs through EtherCAT and Profinet protocol pre-certification.
For New Entrants and Emerging Players: India's pharmaceutical manufacturing belt in Maharashtra and Gujarat offers underpenetrated terrain where CDSCO validation requirements create replacement inertia for audit-trail-compliant controllers. Target European chemical processing retrofits seeking Profinet-OPC UA convergence without full line replacement. Pursue asset-light leasing partnerships with regional service providers to bypass capital-intensive captive network requirements.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with neglected vacuum technology divisions holding dormant semiconductor fab relationships. Five-to-ten year viability hinges on firmware capabilities and regional service footprint scale rather than hardware differentiation. Watch for inflection in semiconductor capital expenditure cycles signaled by Hsinchu and Tainan Science Park expansion announcements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Substrates | MKS Instruments exemplifies how upstream sensor control limits second-source availability for competitors. |
| Dual-Protocol Firmware Stack Development | EtherCAT-Profinet convergence opens European chemical retrofit opportunities without full line replacement. |
| Captive Calibration Network Expansion | Pfeiffer Vacuum's service bundling extends customer lock-in beyond component sales cycles. |
| Asset-Light Leasing Model Deployment | Equipment lessors capture margin pools previously held by component suppliers in Taiwan clusters. |
| FDA 21 CFR Part 11 Compliance Investment | Pharmaceutical freeze-dryer manufacturers face qualification pools compressed to firmware-validated suppliers. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with semiconductor fab procurement officers, pharmaceutical equipment validation engineers, and chemical processing plant maintenance directors; alongside secondary validation through SEC filings of vacuum technology specialists, EU F-Gas Regulation implementation reports, and Taiwan's Hsinchu Science Park investment disclosures. Bottom-up triangulation across product-type unit economics and top-down reconciliation against end-user vertical expenditure patterns anchored value estimates.
Forecast inputs considered microcontroller adoption velocity in South Korean replacement cycles, REACH elastomer restriction compliance timelines, and semiconductor node advancement pressure-control requirements across the analysis window. Segmentation dimensions modeled include product architecture, technology tier, end-user vertical validation intensity, and regional regulatory cluster. CAGRs derived from installed-base replacement curves and new-fab equipment procurement trajectories, with cross-reference to EPA emissions guideline enforcement patterns and CDSCO validation requirement phase-ins.
The forecast holds incumbent behavior within observed patterns; aggressive moves by sensor-substrate-integrated suppliers or capacitive manometer specialists would shift outcomes beyond modeled ranges. Quarterly review of Taiwan and South Korean fab capital expenditure announcements, EU F-Gas leak-rate threshold enforcement actions, and pharmaceutical FDA warning letter trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Handheld Optical Gas Imaging Camera Market
Detection and Regulation Devices
X-Ray Detectors Market
Detection and Regulation Devices
Global a-Si X-Ray Flat Panel Detectors Market
Detection and Regulation Devices
Duct Smoke Detectors Market
Detection and Regulation Devices
Infrared Detection Chip Market
Detection and Regulation Devices
Digital Metal Detector Market
Detection and Regulation Devices
Magnetic Crack Detectors Market
Detection and Regulation Devices
Indeflator Devices Market
Detection and Regulation Devices
Gas Detectors Market
Detection and Regulation Devices
Global Counterfeit Money Detection Market
Detection and Regulation Devices
Radar Detector Market
Detection and Regulation Devices
Global Ultrasonic Air Bubble Detectors Market
Detection and Regulation Devices
Carbon Monoxide (Co) Detector Market
Detection and Regulation Devices
Volatile Organic Compound (VOC) Detector Market
Detection and Regulation Devices
Global Portable Gas Detector Market
Detection and Regulation Devices
Positive Temperature Coefficient (PTC) Thermistor Market