
 Radio Frequency Cables Market | 2026-2036
Radio Frequency Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Radio Frequency Cables Market Intelligence
Defense contractors are reorganizing procurement priorities toward higher-specification RF cable assemblies for electronic warfare and satellite uplink systems. TE Connectivity Ltd. leverages vertical integration across connector and cable manufacturing to capture classified program contracts. HUBER+SUHNER AG anchors European supply networks for military-aerospace interconnects through Swiss precision manufacturing. Amphenol Corporation dominates commercial telecommunication backhaul with broad coaxial and waveguide portfolios.
Radio frequency cables transmit electromagnetic signals between components with controlled impedance, typically 50 or 75 ohms, using dielectric insulation and braided or solid shielding to minimize attenuation and interference. Coaxial and semi-rigid constructions lead military and test equipment applications where phase stability and mechanical precision command premium pricing. Flexible and waterproof technologies represent the fastest-expanding technology categories as 5G infrastructure and outdoor broadcast deployments multiply. Application demand concentrates in telecommunication systems and satellite communication, though radar systems and military communication retain the deepest margin pools due to qualification barriers and long-term program visibility.
FCC spectrum allocation rulings and the EU's RoHS and REACH frameworks constrain halogenated materials and mandate recyclability disclosures across supply chains. China's MIIT enforces GB standards for base station interconnection that foreign suppliers must certify against for market access. Defense contractors and network operators must monitor evolving ITAR export controls and dual-use technology classifications that reshape supplier eligibility and cross-border sourcing strategies.
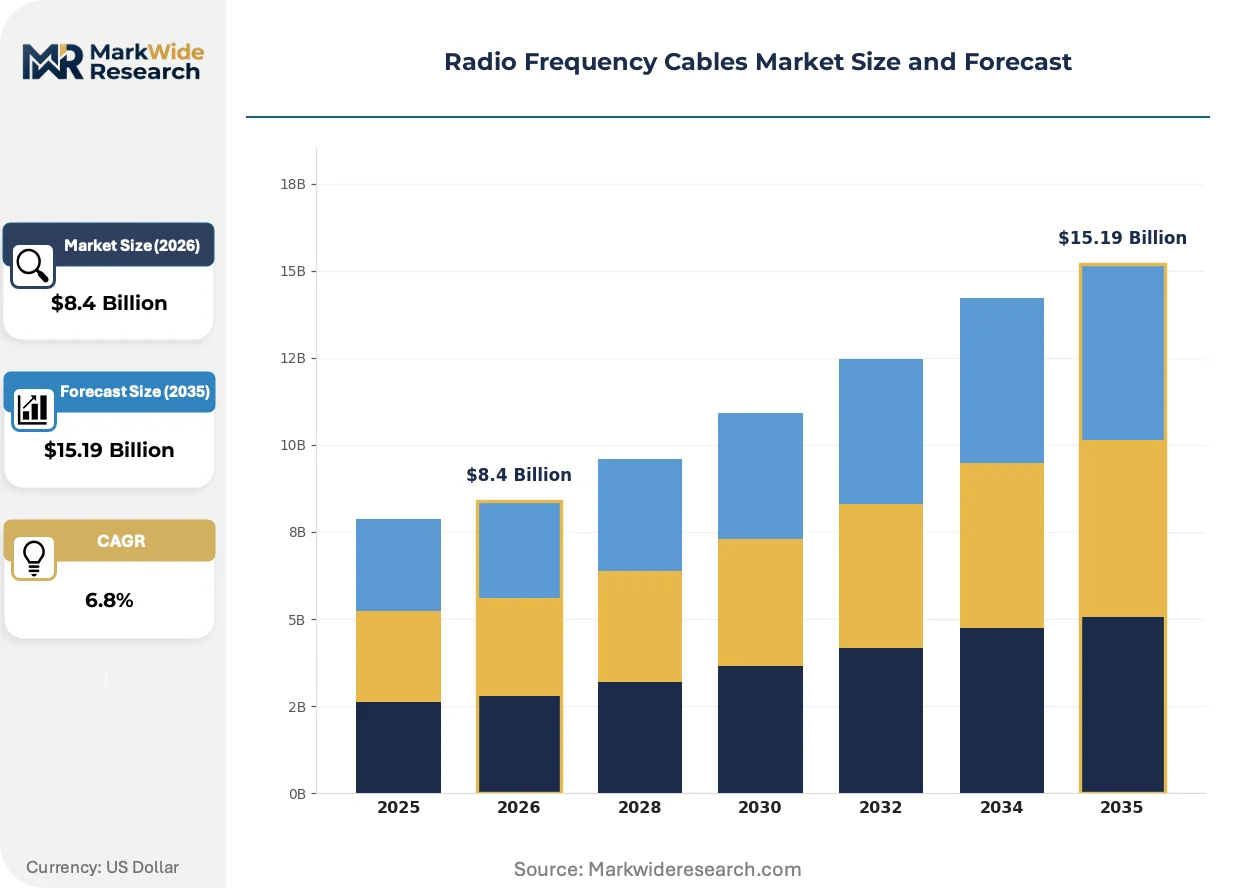
Market Dynamics
Defense procurement concentration around classified radar and electronic warfare programs is compressing supplier qualification timelines while elevating performance specifications for phase-stable coaxial assemblies. This structural force is redrawing competitive access barriers across military-aerospace supply chains.
Growth Catalysts
- REACH material mandates:ECHA enforcement of halogen-free flame retardants in European defense and telecom infrastructure is accelerating certified cable replacements across base station and naval platform installations.
- 5G mmWave densification:Network operators in the United States are deploying low-loss flexible assemblies for street-level small cells, creating pull-through demand for weatherproof connector-cable systems.
- GaN radar transmitters:Solid-state power amplifiers operating at higher frequencies and voltages are forcing upgrades to high-temperature dielectric cables in fighter aircraft and naval phased arrays.
Market Restraints
- Silver and copper price volatility:Raw conductor materials constitute 35-45% of cable assembly cost, and London Metal Exchange fluctuations directly compress margin buffers for mid-tier fabricators.
- Fluoropolymer supply concentration:PTFE and FEP resin production clusters in China and the United States create single-source vulnerability for high-frequency dielectric formulations.
- ITAR classification friction:Dual-use technology controls on precision phase-matched assemblies restrict cross-border sourcing options for non-US primes bidding on F-35 and satellite programs.
Strategic Opportunities
- India defense indigenization:The country's PLI scheme for electronic components and mandatory domestic content thresholds for military procurement create opening for certified local cable assembly partnerships.
- LEO constellation ground infrastructure:Flat-panel terminal manufacturing for Starlink and competitor networks demands high-volume, cost-optimized RF interconnects at consumer price points.
- EU Green Deal circularity:CSRD-mandated recyclability disclosures and extended producer responsibility frameworks favor suppliers with closed-loop material recovery capabilities.
Industry Challenges
- Phase-matching technician scarcity:Precision cable trimming and time-domain reflectometry calibration require 18-24 month apprenticeship pipelines that military-qualified shops struggle to staff.
- DO-160G certification timelines:Commercial aerospace qualification cycles for temperature, altitude, and vibration testing extend 14-18 months, freezing design iterations for new platform introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radio Frequency Cables Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coaxial, Twinaxial, Triaxial, Semi-Rigid, Flexible, Waveguide Technology: Low Loss, High Power Handling, Waterproof, Flame Retardant, Corrosion Resistant, Shielded Application: Telecommunication Systems, Satellite Communication, Radar Systems, Broadcast, Aerospace Communication, Military Communication End User: Network Operators, Telemetry Firms, Defense Contractors, Aerospace Manufacturers, Broadcasting Agencies, Research Institutions |
| Companies Covered | TE Connectivity Ltd., HUBER+SUHNER AG, Amphenol Corporation, Radiall SA, A.H. Systems, inc., Times Microwave Systems, Pasternack Enterprises, Inc., Molex LLC, Carlisle Interconnect Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radio Frequency Cables Market Strategic Shifts & Innovations
Material science advances and procurement model compression are simultaneously elevating performance floors and collapsing traditional specification hierarchies in RF interconnect supply. These forces are fragmenting established tiering structures across defense and commercial segments.
Low-density PTFE and microporous dielectric formulations are fragmenting the traditional solid-PTFE dominance in high-frequency applications. Satellite payload manufacturers and test equipment OEMs are adopting these materials for 40-110 GHz applications where velocity of propagation stability commands premium positioning. The technology is fragmenting supplier tiers by enabling mid-cap specialists to meet performance specifications previously captive to vertically integrated primes.
EU REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of cable jacketing and dielectric materials across European defense and infrastructure deployments. Industrial consequence includes accelerated qualification of thermoplastic elastomer alternatives that trade some temperature rating for recyclability compliance. Telecommunication backbone projects in Germany and France are most affected, with procurement teams rewriting material specifications to exclude legacy fluorinated compounds.
Prime contractors are consolidating RF cable procurement under single-source system integration contracts that bundle interconnects with antennas and active electronics. This channel compression displaces traditional component distributor relationships in favor of direct OEM-tiered supply agreements. The pattern is most visible in United States defense programs, where Lockheed Martin and Northrop Grumman are absorbing cable assembly sourcing into platform-level vendor management systems.
Radio Frequency Cables Market Segmentation
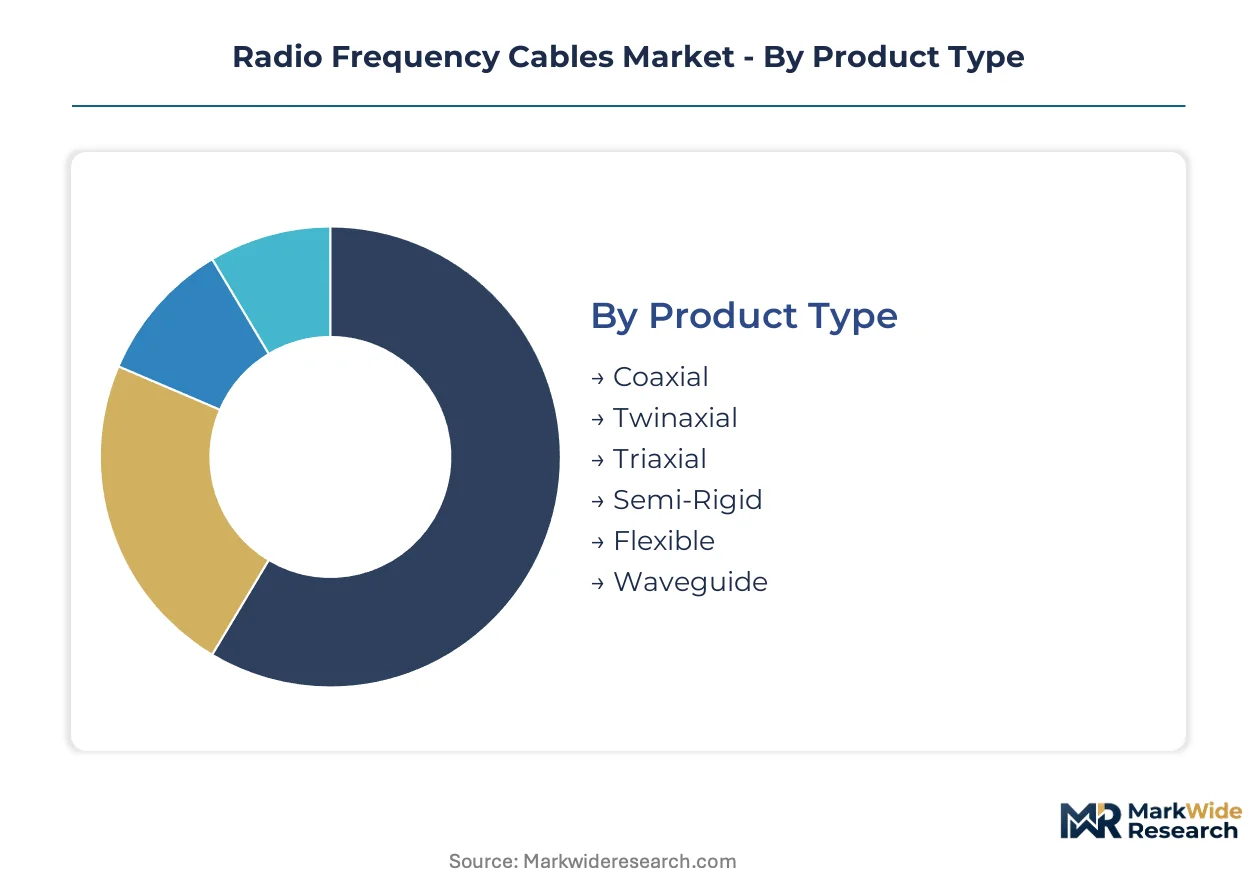
RF cable segmentation reveals how performance specifications, regulatory compliance, and end-use qualification barriers fragment procurement across defense, telecommunications, and aerospace verticals. Margin concentration varies sharply by segment, with phase-matched military assemblies commanding multiples over commercial telecommunication bulk orders.
Product Type:
Margin pools concentrate in constructions requiring precision phase stability and mechanical durability for deployed military platforms.
- Coaxial:Braided or solid outer conductor surrounding dielectric-insulated center conductor, typically 50 or 75 ohm impedance. Demand concentrates in United States defense clusters around fighter aircraft radar upgrades and naval electronic warfare systems, where GaN transmitter integration forces higher voltage tolerance specifications.
- Semi-Rigid:Solid outer conductor tube provides dimensional stability critical for phase-matched array applications. United States prime contractors source these for F-35 and satellite payload programs, with ITAR classification restricting qualified supplier pools to domestic fabricators with 18-24 month apprenticeship pipelines.
- Twinaxial:Dual inner conductors within shared shielding for balanced signal transmission.
- Triaxial:Additional outer shield layer for enhanced electromagnetic interference protection in sensitive measurement environments.
- Flexible:Stranded center conductor and corrugated outer shield enable routing in confined spaces. 5G mmWave small cell deployments in United States urban corridors are pulling weatherproof flexible assemblies for street-level infrastructure.
- Waveguide:Hollow metallic transmission lines for millimeter-wave frequencies above 30 GHz.
The dominant share belongs to Coaxial, while Flexible is closing the gap fastest.
Technology:
Technology selection tracks directly to operating environment severity and regulatory jurisdiction.
- Low Loss:Microporous or low-density PTFE dielectrics minimize signal attenuation across 40-110 GHz. Satellite payload manufacturers in Switzerland and test equipment OEMs in Germany are adopting these formulations where velocity of propagation stability commands premium positioning.
- Flame Retardant:Halogen-free jacketing compounds meeting ECHA REACH Annex XVII restrictions on per- and polyfluoroalkyl substances. German and French telecommunication backbone projects are rewriting specifications to exclude legacy fluorinated compounds, accelerating thermoplastic elastomer qualification.
- High Power Handling:Enhanced thermal conductivity dielectrics for solid-state radar amplifiers.
- Waterproof:Sealed connector-cable interfaces for outdoor broadcast and marine deployments.
- Corrosion Resistant:Nickel-plated conductors and fluoropolymer jackets for naval salt spray environments.
- Shielded:Multi-layer braiding and foil wraps for electromagnetic compatibility in dense electronic environments.
Flame Retardant specifications are expanding most quickly under EU regulatory pressure, while Low Loss maintains the deepest margin structure.
Application:
Application segmentation separates qualified defense-aerospace programs from commercial infrastructure cycles.
- Telecommunication Systems:Base station interconnection and fiber-to-the-antenna links. China's MIIT enforces GB standards for base station interconnection that foreign suppliers must certify against for market access, creating compliance friction for European and United States manufacturers.
- Military Communication:Secure tactical networks and electronic warfare platforms. United States defense procurement concentration around classified radar programs compresses supplier qualification timelines while elevating performance specifications for phase-stable coaxial assemblies.
- Satellite Communication:Ground station uplink and space-qualified payload interconnects.
- Radar Systems:Phased array antenna feeds and transmit-receive modules.
- Broadcast:Studio distribution and outdoor transmission infrastructure.
- Aerospace Communication:Commercial and military aircraft avionics with DO-160G certification requirements.
Military Communication captures the highest margin per kilometer, though Telecommunication Systems generates the largest aggregate volume.
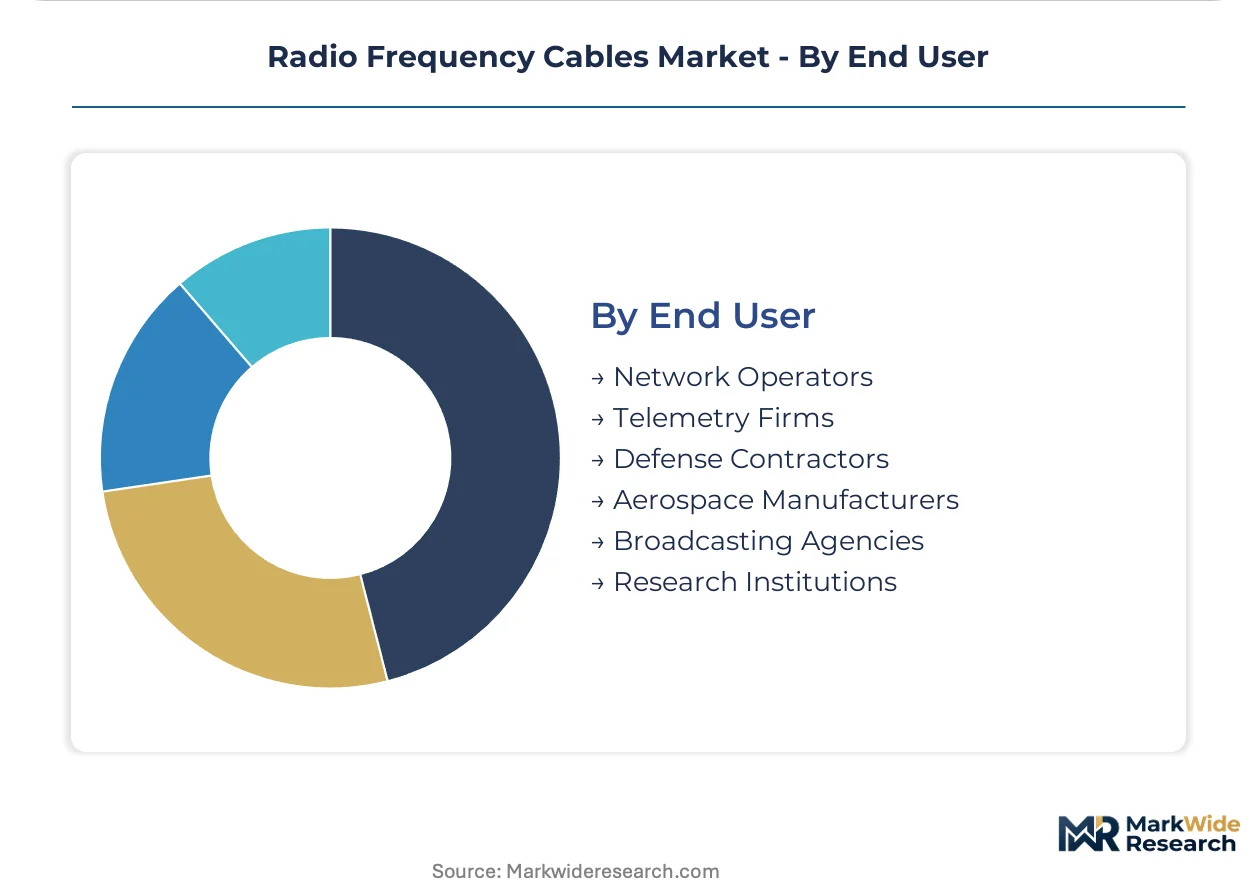
End User:
End user type determines procurement channel structure and contract visibility duration.
- Defense Contractors:Prime and tier-one suppliers to classified military platforms. Lockheed Martin and Northrop Grumman in the United States are consolidating RF cable procurement under single-source system integration contracts that bundle interconnects with antennas and active electronics, displacing traditional distributor relationships.
- Network Operators:Mobile and fixed-line carriers deploying 5G infrastructure. United States operators are deploying low-loss flexible assemblies for street-level small cells, creating pull-through demand for weatherproof connector-cable systems at consumer price points.
- Aerospace Manufacturers:Commercial and business aircraft OEMs with 14-18 month DO-160G qualification cycles.
- Telemetry Firms:Test range and flight test data acquisition specialists.
- Broadcasting Agencies:National and regional television network operators.
- Research Institutions:National laboratories and university test facilities.
Defense Contractors dominate premium-tier procurement, while Network Operators are scaling fastest in absolute unit terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cable fabricators export precision coaxial assemblies to United States defense primes for F-35 and satellite programs, while Swiss manufacturers supply European military-aerospace clusters with ITAR-compliant interconnects.
United States
Defense procurement for next-generation radar platforms and electronic warfare systems drives demand in California and Texas aerospace clusters. FCC spectrum allocation rulings constrain material specifications for 5G infrastructure deployments. Lockheed Martin and Northrop Grumman in Fort Worth and Palmdale consolidate RF cable sourcing under platform-level vendor management systems.
Germany
Telecommunication backbone projects and automotive radar integration create dual demand streams for low-loss and flame-retardant formulations. ECHA REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force thermoplastic elastomer qualifications across defense and infrastructure deployments. Industrial procurement teams in Munich and Stuttgart rewrite specifications to exclude legacy fluorinated compounds.
China
MIIT-enforced GB standards for base station interconnection create compliance friction for foreign suppliers seeking telecommunications market access. Domestic content thresholds for military procurement accelerate local cable assembly partnerships. Yangtze River Delta manufacturing clusters concentrate PTFE and FEP resin production for high-frequency dielectric formulations.
Switzerland
Precision manufacturing capabilities anchor European supply networks for military-aerospace interconnects requiring phase-matched specifications. Swissmedic-equivalent quality frameworks for industrial components support qualification for classified programs. Geneva and Zurich clusters specialize in satellite payload and test equipment applications where velocity of propagation stability commands premium positioning.
India
PLI scheme incentives for electronic components and mandatory domestic content thresholds for military procurement create openings for certified local cable assembly partnerships. TRAI spectrum policies shape 5G infrastructure material specifications. Bengaluru and Hyderabad defense-aerospace clusters absorb technology transfer agreements for phase-stable coaxial production.
Radio Frequency Cables Market Key Industry Players
Player mix skews toward vertically integrated conglomerates with captive connector and cable manufacturing capabilities. Mid-cap specialists occupy niches requiring precision phase-matching and ITAR-compliant fabrication. Three archetypes dominate: defense-prime-integrated suppliers, commercial telecommunication scale players, and precision microwave specialists. Competitive moves center on single-source system integration contracts and backward integration into fluoropolymer resin compounding.
Among Swiss and German precision fabricators, HUBER+SUHNER AG exemplifies the military-aerospace interconnect specialist archetype through European supply network anchoring. TE Connectivity Ltd. represents the vertically integrated conglomerate model with cross-connector and cable manufacturing capabilities. Amphenol Corporation occupies a position as the commercial telecommunication scale player with broad coaxial and waveguide portfolios. These three named entities illustrate how geographic origin and corporate structure map to distinct competitive positioning vectors without requiring specific product or financial claims.
| Leading Market Players |
|---|
| TE Connectivity Ltd. |
| HUBER+SUHNER AG |
| Amphenol Corporation |
| Radiall SA |
| A.H. Systems, inc. |
| Times Microwave Systems |
| Pasternack Enterprises, Inc. |
| Molex LLC |
| Carlisle Interconnect Technologies |
| Others |
Cost & Logistics Intelligence
ITAR classification regimes for phase-matched assemblies simultaneously gate supplier qualification and stratify pricing power across United States defense programs. ECHA REACH mandates on halogen-free materials enforce parallel compliance costs that compress margins for non-certified fabricators while elevating premiums for qualified European suppliers.
Pricing Analysis
Next-generation GaN radar cables command substantial premiums over legacy solid-PTFE constructions, while prior-generation copper-clad steel assemblies face accelerating price erosion. Three-tier pricing structure across ITAR-certified military, commercial aerospace, and consumer telecommunication levels reflects certification burden and volume scale differentiation. Cost compression in flexible 5G small-cell assemblies intensifies because network operators demand consumer price points for street-level infrastructure. Defense contractors exhibit lowest price sensitivity due to program visibility and qualification barriers, while broadcast agencies show highest sensitivity to per-meter differentials.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for fluoropolymer resin shipments destined for German and Swiss cable fabricators. Manufacturing gravity centers on China for PTFE and FEP dielectric formulations, the United States for ITAR-compliant phase-matched assemblies, and Germany for automotive radar integration. Raw material dependencies encompass silver-plated copper conductors, microporous PTFE substrates, and thermoplastic elastomer jacketing compounds. Single-source vulnerability concentrates in Chinese fluoropolymer resin production clusters. Distribution runs through prime contractor vendor management systems in United States defense and OEM-tiered supply agreements in European aerospace.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radio frequency cables constitute a high-growth disruption as 5G mmWave densification and GaN radar transmitter integration simultaneously expand addressable demand and collapse traditional specification hierarchies.
For Market Incumbents: Compound defensive positioning through backward integration into fluoropolymer resin compounding and captive connector manufacturing to offset margin compression from silver price volatility. Lockheed Martin and Northrop Grumman vendor management system consolidation threatens traditional distributor relationships, demanding direct platform-level engagement. ITAR classification maintenance represents the critical certification lever for United States defense access.
For New Entrants and Emerging Players: Lead with thermoplastic elastomer formulations for EU Green Deal circularity compliance as a regulatory-aligned entry vector into German and French telecommunication backbone projects. India PLI scheme incentives and mandatory domestic content thresholds create the most penetrable defense-aerospace geography for certified local assembly partnerships. Target LEO constellation ground infrastructure for flat-panel terminal manufacturing at consumer price points.
For Investors and Strategic Acquirers: EU REACH Annex XVII expansion on per- and polyfluoroalkyl substances reshapes the acquisition landscape by devaluing legacy fluorinated compound capabilities and elevating reformulation-ready specialists. Five-to-ten-year viability favors precision phase-matching shops with established apprenticeship pipelines and ITAR-compliant fabrication infrastructure. The signal to monitor is ECHA enforcement acceleration against non-compliant cable imports.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin Compounding | Captive PTFE supply secures margin buffers against Chinese production concentration. |
| ITAR Compliance Investment and Apprenticeship Pipeline Expansion | Eighteen-to-twenty-four month technician training locks out unqualified competitors from F-35 programs. |
| Thermoplastic Elastomer Qualification for REACH Compliance | German telecommunication procurement teams rewrite specifications excluding legacy fluorinated compounds. |
| Direct Prime Contractor Engagement | Lockheed Martin and Northrop Grumman vendor management systems displace traditional distributor channels. |
| LEO Constellation Ground Infrastructure Partnership | Starlink and competitor flat-panel terminal manufacturing demands high-volume cost-optimized interconnects. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs and trade data, and ECHA regulatory enforcement records. Primary interviews encompassed defense procurement officers at United States prime contractors, cable fabrication plant managers in Germany and Switzerland, and telecommunications infrastructure procurement leads at European network operators. Secondary validation drew from FCC spectrum allocation rulings, MIIT GB standard certifications, and ITAR dual-use technology classification updates. Bottom-up demand modeling triangulated against top-down market sizing across product type, technology, application, and end-user segments.
Segmentation dimensions modeled encompass coaxial, semi-rigid, and flexible constructions; low-loss, flame-retardant, and waterproof technologies; telecommunication, military communication, and satellite communication applications; and defense contractor, network operator, and aerospace manufacturer end users. CAGRs derive from regression analysis against historical procurement cycles and technology substitution patterns. Industry-specific forecast inputs include GaN radar transmitter deployment schedules and 5G mmWave small-cell densification trajectories across the analysis window.
Forecasts assume regulatory continuity in ITAR export controls, ECHA REACH enforcement, and MIIT GB standard certification; material policy shifts would require re-modeling. Phase-matching technician scarcity and DO-160G certification timeline extensions represent specific risk factors that could constrain supply elasticity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Active Optical Cable Market
Cables
Global Cable Tie Market
Cables
Industrial Cable Reels Market
Cables
Hybrid Cables Market
Cables
Premise Cable Market
Cables
Class 1E Electric Cables Market
Cables
Submarine Cabling Systems Market
Cables
Patch Cable Market
Cables
Submarine Cables Market
Cables
Copper Stranded Wire Market
Cables
Cable Trunking Market
Cables
Submarine Data Cables Market
Cables
Insulated Wire and Cable Market
Cables
XLPE Cables Market
Cables
Low-Temperature Cable Market
Cables
South Africa Wire and Cable Market