

Low-Temperature Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Temperature Cable Market Insights
The gap between fluoropolymer-insulated premium cables and commodity PVC-based alternatives is repositioning procurement criteria across industrial buyers. Prysmian Group leverages its integrated compound manufacturing to sustain margin pools in aerospace-grade specifications. Nexans anchors European cryogenic project pipelines through specialized superconducting cable expertise. Sumitomo Electric Industries dominates Asian LNG terminal infrastructure with customized low-temperature power distribution systems.
Low-temperature cable denotes electrical conductors engineered to maintain dielectric integrity and mechanical flexibility at cryogenic thresholds, typically incorporating cross-linked polyethylene or fluoropolymer insulation rated for sustained operation below minus 40 degrees Celsius. These cables serve critical functions in liquefied natural gas transfer, superconducting magnet systems, and polar research installations where standard jacketing compounds embrittle and fail. Control cable and instrumentation cable categories command the deepest specification requirements and corresponding margin premiums due to signal fidelity demands in cryogenic measurement loops. Power cable applications in renewable energy systems, particularly offshore wind cold-climate extensions, represent the fastest-expanding segment as turbine operators push into Arctic and sub-Arctic zones. Fluoropolymer technology leads in aerospace and cryogenics despite elevated material costs, while low-smoke zero-halogen compounds gain traction in marine and enclosed infrastructure where fire toxicity regulations tighten.
Regulators including the EPA, ECHA under REACH, and China's MEE enforce progressively stricter limits on halogenated flame retardants and perfluorinated compounds in cable sheathing. These frameworks compel compound reformulation and recertification investments that reshape supplier qualification requirements. Buyers must monitor evolving substance restriction timelines and pre-qualify alternative insulation platforms before existing formulations face market withdrawal deadlines.
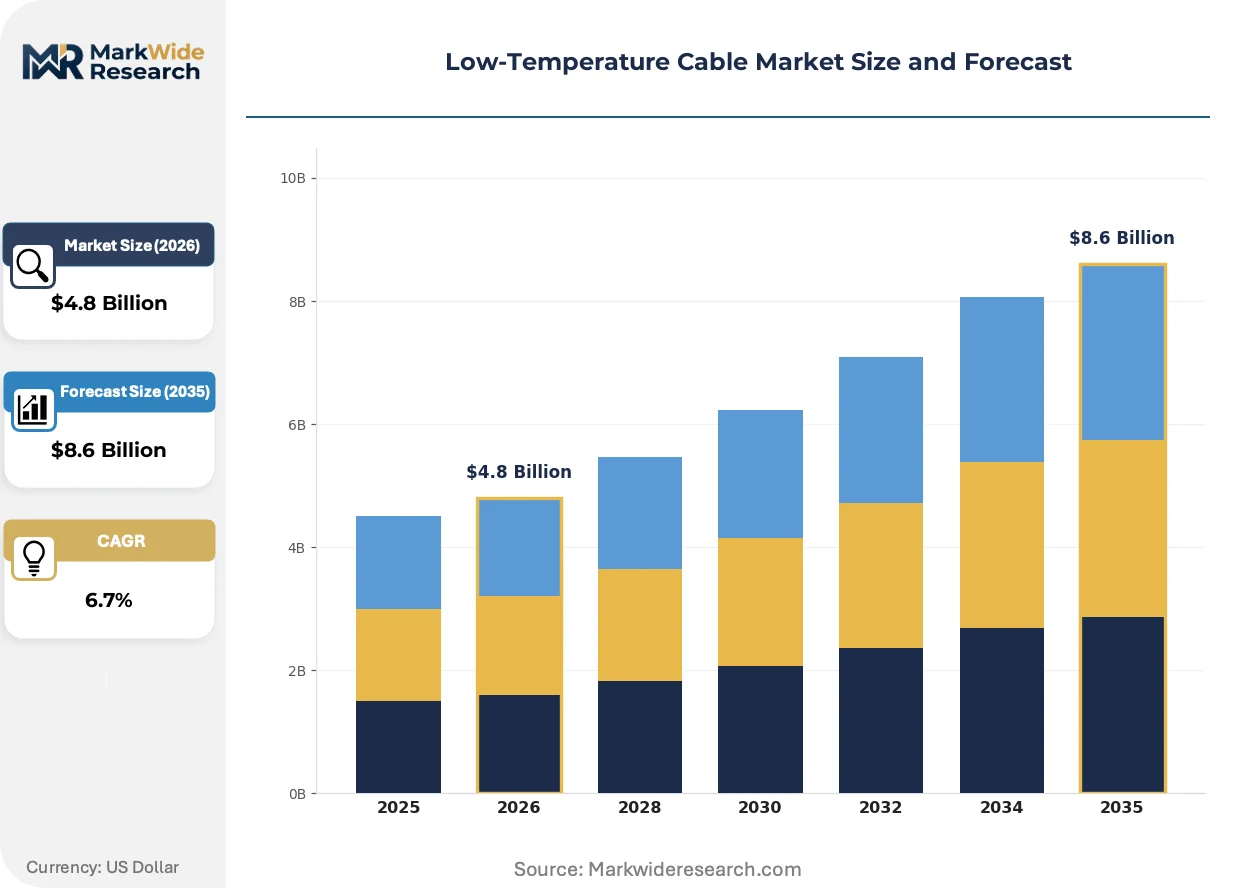
Market Dynamics
Material transition mandates from the EU F-Gas Regulation and REACH are forcing compound reformulation across insulation platforms faster than certification cycles can accommodate, compressing supplier qualification timelines and redrawing competitive boundaries between fluoropolymer specialists and emerging halogen-free alternatives.
Growth Catalysts
- EU F-Gas Regulation phase-down schedules:Accelerated hydrofluorocarbon reduction timelines are compelling LNG terminal operators and cryogenic storage developers to pre-qualify next-generation insulation systems ahead of formulation withdrawals.
- Offshore wind cold-climate extensions:Turbine operators pushing into Arctic and sub-Arctic zones are specifying low-temperature power cables for inter-array connections, creating sustained procurement volume in Norwegian and Scottish developments.
- Superconducting magnet deployment:Medical imaging and particle physics facilities are expanding cryogenic instrumentation cable specifications for quantum computing and fusion research applications.
Market Restraints
- Fluoropolymer feedstock concentration:Virgin PTFE and FEP resin supply concentrates among Japanese and Chinese chemical conglomerates, exposing cable manufacturers to input cost volatility and allocation constraints.
- REACH substance restriction timelines:ECHA's evolving candidate list for authorization creates regulatory friction as compounders face overlapping recertification deadlines for alternative insulation platforms.
- Halogen-free performance gaps:Low-smoke zero-halogen compounds exhibit inferior dielectric stability below minus 60 degrees Celsius, limiting substitution in aerospace and deep-cryogenics applications.
Strategic Opportunities
- India cold-chain infrastructure:PLI scheme incentives for refrigerated transport and food processing are stimulating first-time specification of low-temperature control cables in a historically underpenetrated market.
- CCUS pipeline networks:Carbon capture utilization and storage projects require cryogenic CO2 transfer lines with integrated power and instrumentation, converging pipeline engineering with cable system design.
- Marine LNG bunkering:Port authorities in Singapore and Rotterdam are mandating shore-power connections for LNG-fueled vessels, expanding demand for flexible low-temperature shore connection cables.
Industry Challenges
- Polymer chemist talent scarcity:Compound formulation expertise for cryogenic dielectrics concentrates among retiring specialists in European and Japanese materials laboratories, constraining R&D velocity.
- Type approval timeline compression:IEC 60092 and IEEE 1580 certification cycles for marine and offshore applications extend 18-24 months, misaligning with project construction schedules.
- Legacy system integration:Retrofit installations in existing LNG terminals must reconcile new low-temperature cable specifications with decades-old termination hardware and gland designs.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Temperature Cable Market Trends and Innovations
Cross-linked polyethylene formulations are absorbing performance requirements previously reserved for fluoropolymers, while regulatory pressure on perfluorinated compounds accelerates material science investment and procurement pre-qualification activity across industrial buyers.
Thermoplastic elastomer jacketing systems rated for sustained minus 196 degrees Celsius operation are absorbing market share in cryogenic transfer applications previously dominated by rigid fluoropolymer constructions. LNG infrastructure operators in Germany and the United States are adopting these flexible alternatives for loading arm and bunker hose integration, compressing total installed cost differentials against conventional specifications while maintaining IEC 60079 explosion protection compliance.
China's MEE enforcement of GB standards restricting halogenated flame retardants in enclosed infrastructure is compelling marine and tunnel cable specifications toward low-smoke zero-halogen platforms. Domestic compounders are accelerating certification under Lloyd's Register and DNV rules to capture retrofit demand from port electrification projects, with the Yangtze River Delta exhibiting the fastest specification conversion rates.
Integrated cable-and-connector systems with factory-tested termination integrity are displacing field-assembly approaches in polar research installations and offshore wind commissioning. Buyers in Norway and Scotland are specifying these pre-tested harnesses to reduce cold-weather installation risk and compress commissioning timelines, with after-sales service contracts unbundling from hardware supply to separate performance accountability.
Low-Temperature Cable Market Segmentation
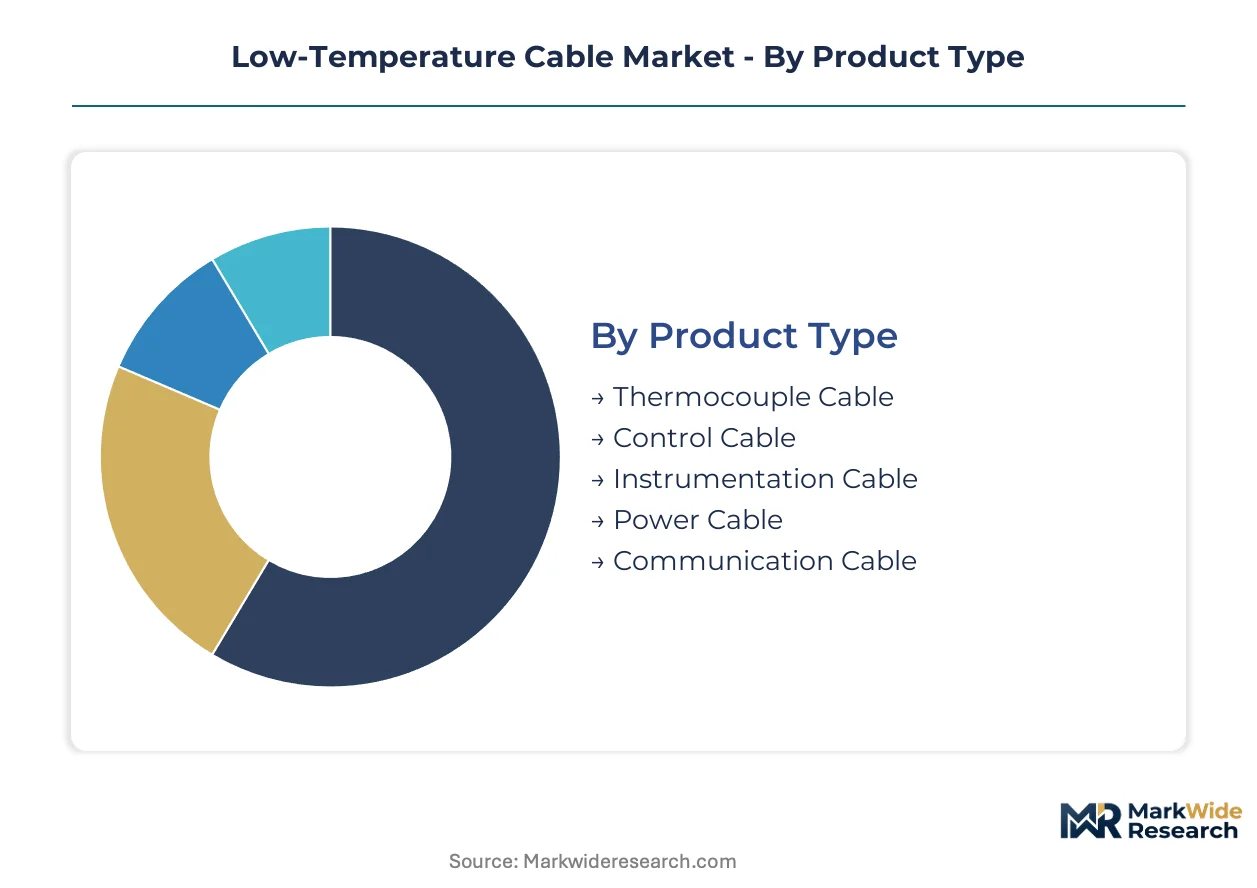
Low-temperature cable procurement stratifies sharply between specification-critical cryogenic applications and cost-driven cold-climate infrastructure. Buyers navigate trade-offs between fluoropolymer performance premiums and emerging halogen-free alternatives as regulatory deadlines compress qualification timelines.
Product Type:
Volume concentrates in power distribution, while margin pools concentrate in signal-integrity categories where cryogenic specifications command technical premiums.
- Control Cable:Multi-conductor assemblies with cross-linked polyethylene or fluoropolymer insulation rated for sustained minus 40 degrees Celsius operation. LNG terminal operators in Germany and the United States specify these for cryogenic valve actuation and process control loops where signal reliability failures trigger shutdown costs.
- Instrumentation Cable:Twisted-pair and triad constructions with precision capacitance control for cryogenic measurement accuracy. Superconducting magnet facilities and polar research stations in Norway absorb the deepest specification requirements, with individual project values reflecting decades-long deployment horizons.
- Power Cable:Medium-voltage distribution for offshore wind inter-array connections in Scottish and Norwegian developments.
- Thermocouple Cable:Compensating and extension grades for temperature measurement circuits in aerospace test stands.
- Communication Cable:Fiber-optic and copper data transmission for remote monitoring in Arctic pipeline infrastructure.
Today's leader: Control Cable. Tomorrow's challenger: Instrumentation Cable.
Technology:
Material platforms diverge across cost-performance frontiers, with regulatory pressure forcing substitution economics into procurement calculations.
- Fluoropolymer:PTFE and FEP formulations maintaining dielectric stability below minus 196 degrees Celsius. Aerospace-grade specifications in the United States and medical imaging installations absorb virgin resin premiums despite supply concentration among Japanese chemical conglomerates.
- Cross-Linked Polyethylene:Irradiation or silane-crosslinked formulations penetrating cryogenic applications previously reserved for fluoropolymers. Chinese port electrification projects and German LNG infrastructure are absorbing these alternatives as REACH substance restrictions accelerate recertification investment.
- Low-Smoke Zero-Halogen:Polyolefin-based compounds for enclosed marine and tunnel infrastructure where China's MEE enforces GB standard compliance.
- Rubber Insulation:EPR and CPE jacketing for flexible loading arm and bunker hose integration.
- Polyvinyl Chloride:Commodity formulations limited to minus 15 degrees Celsius thresholds in non-critical cold-climate extensions.
Fluoropolymer retains aerospace and deep-cryogenics dominance. Cross-Linked Polyethylene is climbing the fastest through LNG infrastructure substitution.
Application:
End-use requirements fragment across temperature thresholds, mechanical flexibility demands, and regulatory exposure profiles.
- Cryogenics:Liquid nitrogen and liquid helium transfer systems requiring sustained minus 196 degrees Celsius performance. Fusion research facilities and medical imaging OEMs in the United States and Germany specify factory-tested harnesses to eliminate field-termination risk in inaccessible installations.
- Renewable Energy Systems:Offshore wind cold-climate extensions driving inter-array and export cable procurement in Norwegian and Scottish waters. Turbine operators specify low-temperature power cables as Arctic zone development pushes mechanical reliability requirements beyond standard jacketing capabilities.
- Aerospace Systems:Aircraft and spacecraft wiring for altitude and space exposure conditions.
- Marine Equipment:LNG bunkering connections and polar vessel shore-power infrastructure.
- Oilfield Operations:Subsea and Arctic extraction equipment for cold-climate production.
Cryogenics commands specification premiums. Renewable Energy Systems are expanding most quickly through offshore wind geography expansion.
End User:
Customer types separate across specification authority, volume concentration, and aftermarket service attachment potential.
- OEM Manufacturers:Original equipment builders for superconducting magnets, MRI systems, and aerospace platforms. These buyers specify cable systems at design phase with decades-long service life requirements, capturing supplier technical collaboration and captive specification lock-in.
- Research Laboratories:National and institutional facilities for particle physics and polar science. CERN-scale projects and Antarctic research stations procure through extended qualification cycles with unique termination and harness integration demands.
- Transportation Providers:Rail, aviation, and maritime operators for cold-climate fleet infrastructure.
- Aftermarket Suppliers:Replacement and retrofit distributors for legacy LNG terminal and cold-chain equipment.
- Telecommunications Firms:Arctic and subsea cable system operators for remote connectivity infrastructure.
OEM Manufacturers anchor premium volume. Research Laboratories represent the steepest expansion trajectory through quantum computing and fusion investment acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's cryogenic infrastructure investments outpace United States procurement volumes, while China's port electrification accelerates specification conversion rates faster than either market.
United States
Fusion research facilities and medical imaging OEMs drive specification demand for factory-tested harnesses. The EPA enforces progressively stricter limits on halogenated flame retardants in cable sheathing. Boston-area superconducting magnet manufacturers absorb deep specification requirements with decades-long deployment horizons.
Germany
LNG terminal operators and cryogenic storage developers pre-qualify next-generation insulation systems ahead of formulation withdrawals. The EU F-Gas Regulation compels compound reformulation across insulation platforms faster than certification cycles accommodate. Hamburg and Wilhelmshaven infrastructure projects sustain procurement volume in inter-array connections.
China
Port electrification projects and Yangtze River Delta specification conversions absorb alternative insulation platforms. The MEE enforces GB standards restricting halogenated flame retardants in enclosed infrastructure. Domestic compounders accelerate certification under Lloyd's Register and DNV rules to capture retrofit demand.
Norway
Offshore wind cold-climate extensions push turbine operators into Arctic zone development. REACH substance restrictions accelerate recertification investment for marine and offshore applications. Scottish and Norwegian waters absorb sustained procurement volume in inter-array and export cable categories.
India
Refrigerated transport and food processing infrastructure stimulates first-time specification of low-temperature control cables. PLI scheme incentives reshape supplier qualification requirements in a historically underpenetrated market. Maharashtra and Gujarat industrial corridors exhibit the fastest conversion rates from commodity PVC to cross-linked polyethylene alternatives.
Low-Temperature Cable Market Competitive Landscape
Top-tier vendors anchor premium specification tiers, while mid-scale compounders and regional fabricators occupy cost-driven segments. The market structure concentrates around integrated resin-to-cable manufacturers with captive compound expertise and specialized cryogenic testing facilities. Three archetypes dominate: fluoropolymer specialists with aerospace-grade certification, cross-linked polyethylene innovators penetrating LNG infrastructure, and marine-grade harness integrators with factory-tested termination systems. Competitive moves center on backward integration into resin compounding and strategic partnerships with cryogenic equipment OEMs for captive specification lock-in.
Among European cable manufacturers, Prysmian Group, Nexans, and Leoni occupy positions across the premium specification spectrum. Prysmian exemplifies the integrated compound manufacturing archetype with aerospace-grade capabilities. Nexans anchors European cryogenic project pipelines through specialized superconducting cable expertise. Leoni represents the precision harness integration tier with factory-tested termination systems for polar research installations.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| Southwire Company |
| LS Cable & System |
| Sumitomo Electric Industries |
| Furukawa Electric |
| Fujikura |
| Leoni |
| Lapp Holding |
| Others |
Pricing and Supply Chain Analysis
OEM Manufacturers for superconducting magnets and medical imaging systems anchor pricing power through decades-long service life requirements and captive specification lock-in. Their procurement concentrates on factory-tested harnesses with unbundled after-sales accountability, compressing commodity alternatives into cost-driven cold-climate infrastructure segments.
Pricing Analysis
Factory-tested termination integrity is unbundling from hardware supply as Norwegian and Scottish offshore wind operators specify pre-tested harnesses to compress commissioning timelines. Three-tier pricing structure across aerospace-grade fluoropolymer, cross-linked polyethylene LNG infrastructure, and commodity PVC cold-climate extensions reflects certification grade and volume scale differentiation. Cost compression in the halogen-free tier is intensifying as REACH recertification deadlines force compound reformulation investments. Research Laboratories exhibit the least price sensitivity due to unique harness integration demands, while Indian cold-chain infrastructure buyers under PLI scheme incentives drive the most aggressive procurement cost targets.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the United States coordinate hub-and-spoke patterns for cryogenic compound feedstocks and finished cable assemblies. Virgin PTFE and FEP resin supply draws from Japanese and Chinese chemical conglomerates, while cross-linked polyethylene compound production rests on German and South Korean petrochemical infrastructure. Single-source vulnerability concentrates in aerospace-grade fluoropolymer resin allocation, exposing cable manufacturers to input cost volatility. Distribution runs through specialized cryogenic testing facilities and Lloyd's Register or DNV-certified marine harness integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through cross-linked polyethylene substitution economics displacing fluoropolymer premiums in LNG infrastructure, while aerospace-grade specifications sustain pricing power through supply concentration.
For Market Incumbents: Deepen backward integration into resin compounding to defend margin pools against emerging halogen-free compounders accelerating REACH recertification investment. Prysmian Group's integrated manufacturing archetype exemplifies this defensive posture. Lock in captive specification relationships with cryogenic equipment OEMs through collaborative R&D on next-generation insulation platforms ahead of EU F-Gas Regulation formulation withdrawals. For New Entrants and Emerging Players: Launch via factory-tested harness integration services for polar research installations and offshore wind commissioning, where Norwegian and Scottish buyers unbundle after-sales accountability from hardware supply. India's PLI scheme-stimulated cold-chain infrastructure represents the most penetrable geography for first-time cross-linked polyethylene specification. Target marine LNG bunkering shore-power connections in Singapore and Rotterdam port authorities mandating flexible low-temperature cable adoption. For Investors and Strategic Acquirers: Cryogenic equipment OEMs are the most active acquirer in this space, seeking captive cable specification lock-in for superconducting magnet and fusion research applications. Over the projection horizon, vertically integrated compound-to-cable manufacturers with specialized cryogenic testing facilities represent the highest viability acquisition archetype. Monitor ECHA candidate list expansion velocity as the inflection indicator for alternative insulation platform pre-qualification urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Prysmian Group sustains margin pools through captive aerospace-grade compound production. |
| Factory-Tested Harness Certification | Leoni captures Norwegian polar research demand with pre-tested termination integrity systems. |
| REACH Recertification Investment | German LNG operators pre-qualify cross-linked polyethylene alternatives ahead of formulation withdrawals. |
| Marine Certification Acceleration | Chinese compounders capture Yangtze River Delta retrofit demand under Lloyd's Register and DNV rules. |
| Cryogenic Equipment OEM Partnership | Nexans anchors European project pipelines through superconducting cable technical collaboration. |
Research Methodology
Coverage spans Germany, China, the United States, Norway, and India, with primary inputs from each regional cluster combining interviews with cryogenic equipment OEM procurement directors, LNG terminal engineering leads, superconducting magnet R&D specialists, marine classification surveyors, and cold-chain infrastructure project managers. Secondary validation draws from IEC 60092 and IEEE 1580 certification databases, ECHA REACH candidate list filings, EU F-Gas Regulation implementation schedules, and Lloyd's Register marine equipment approvals. Bottom-up project pipeline enumeration triangulates against top-down end-use demand aggregation.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include product type, insulation technology platform, application temperature threshold, and end-user procurement authority. CAGRs derive from fitted growth curves calibrated to disclosed infrastructure investment commitments and regulatory deadline impacts. Fusion research facility capital expenditure cycles and offshore wind inter-array connection procurement schedules serve as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU F-Gas Regulation phase-down schedules or extended IEC 60092 certification cycle delays. Outputs reflect documented assumptions on material substitution timelines and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.