
 Submarine Cables Market | 2026-2036
Submarine Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Submarine Cables Market Outlook
Multi-source procurement of cable systems is restructuring supply relationships across the subsea industry. NEC Corporation leverages its integrated manufacturing and installation fleet to compete on turnkey project delivery. Alcatel Submarine Networks anchors European supply through its Calais-based cable factory and marine operations center. Prysmian S.p.A extends its position in high-voltage subsea power cables while building optical transmission capabilities.
Submarine cables are fiber-optic or copper conductors sheathed in polyethylene and steel armor, designed to transmit data or electrical power across seabed environments at depths exceeding 8,000 meters. Their primary purpose is to establish high-capacity, low-latency intercontinental links for telecommunications and offshore energy grids. Fiber optic deployments dominate new installations as carriers prioritize terabit-scale capacity over legacy coaxial infrastructure. Offshore energy applications represent the fastest-expanding segment as floating wind farms require export cables and inter-array connections. Maintenance and upgrade services command durable margin pools given the technical complexity of deep-water retrieval and repair operations.
The International Cable Protection Committee coordinates seabed routing standards while national regulators including the FCC in the United States and Japan's Ministry of Internal Affairs and Communications enforce landing station licensing and cable protection zones. These frameworks shape project timelines by mandating environmental impact assessments and coastal access agreements. Stakeholders must monitor how permitting delays at landing points and evolving marine spatial planning rules affect route economics and deployment schedules.
Market Dynamics
Open cable architecture standards are dissolving traditional vendor lock-in arrangements and forcing suppliers to compete on component interoperability rather than proprietary system integration. This structural shift redistributes bargaining power toward consortium-led cable purchasers and away from turnkey providers.
Growth Catalysts
- Hyperscale Data Center Expansion:Cloud operators are commissioning dedicated fiber pairs on new cable systems to interconnect distributed compute infrastructure across oceanic routes. This end-use vertical now accounts for the majority of pre-sales capacity commitments on trans-Pacific projects.
- Marine Spatial Planning Directives:The EU Marine Strategy Framework Directive is accelerating route survey investments as developers secure seabed corridor reservations before competing uses proliferate. Early-mover cable systems are securing preferential routing through congested continental shelf zones.
- Space-Division Multiplexing:SDM technology multiplies fiber count per cable sheath beyond traditional limits, enabling petabit-scale systems without repeater power escalation. This process innovation compresses unit transmission costs for bandwidth-intensive applications.
Market Restraints
- Specialized Vessel Scarcity:Cable-laying ships and burial plows concentrate among three operator fleets, creating bottleneck risk during concurrent project windows. Charter rates spike when multiple systems enter marine installation phase simultaneously.
- Copper and Steel Armor Volatility:Raw material input costs for conductor and mechanical protection layers fluctuate with commodity cycles, compressing fixed-price contract margins. Suppliers lack pass-through mechanisms on multi-year build schedules.
- Permitting Timeline Uncertainty:Coastal state environmental review processes for landing station construction lack standardized durations, exposing project schedules to regulatory friction. FCC licensing and state-level coastal commission approvals operate on non-overlapping calendars.
Strategic Opportunities
- Floating Offshore Wind Export Cables:Dynamic high-voltage subsea power connections for pre-commercial floating wind arrays represent an emerging application with limited incumbent competition. Early entrants are establishing installation methodologies before market formalization.
- Indo-Pacific Island Connectivity:Underpenetrated archipelago routes linking Indonesia, Papua New Guinea, and Pacific island states lack redundant infrastructure and command premium pricing for resilience upgrades. Development finance institutions are co-funding feasibility studies.
- US Inflation Reduction Act Tax Credits:Domestic content incentives for subsea cable manufacturing equipment are stimulating capital investment in US-based armoring and sheathing facilities. This policy tailwind supports supply chain regionalization strategies.
Industry Challenges
- Deep-Water Splicing Expertise Gap:Technician pools capable of performing repeater repairs below 4,000 meters remain concentrated among retiring specialists. Training programs at marine technical institutes have not scaled to replacement demand.
- Legacy Coaxial System Integration:Upgrading operational amplifiers on 1990s-era copper coaxial cables requires obsolete component sourcing and proprietary diagnostic protocols. Maintenance contracts for these aging assets absorb disproportionate engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Submarine Cables Market |
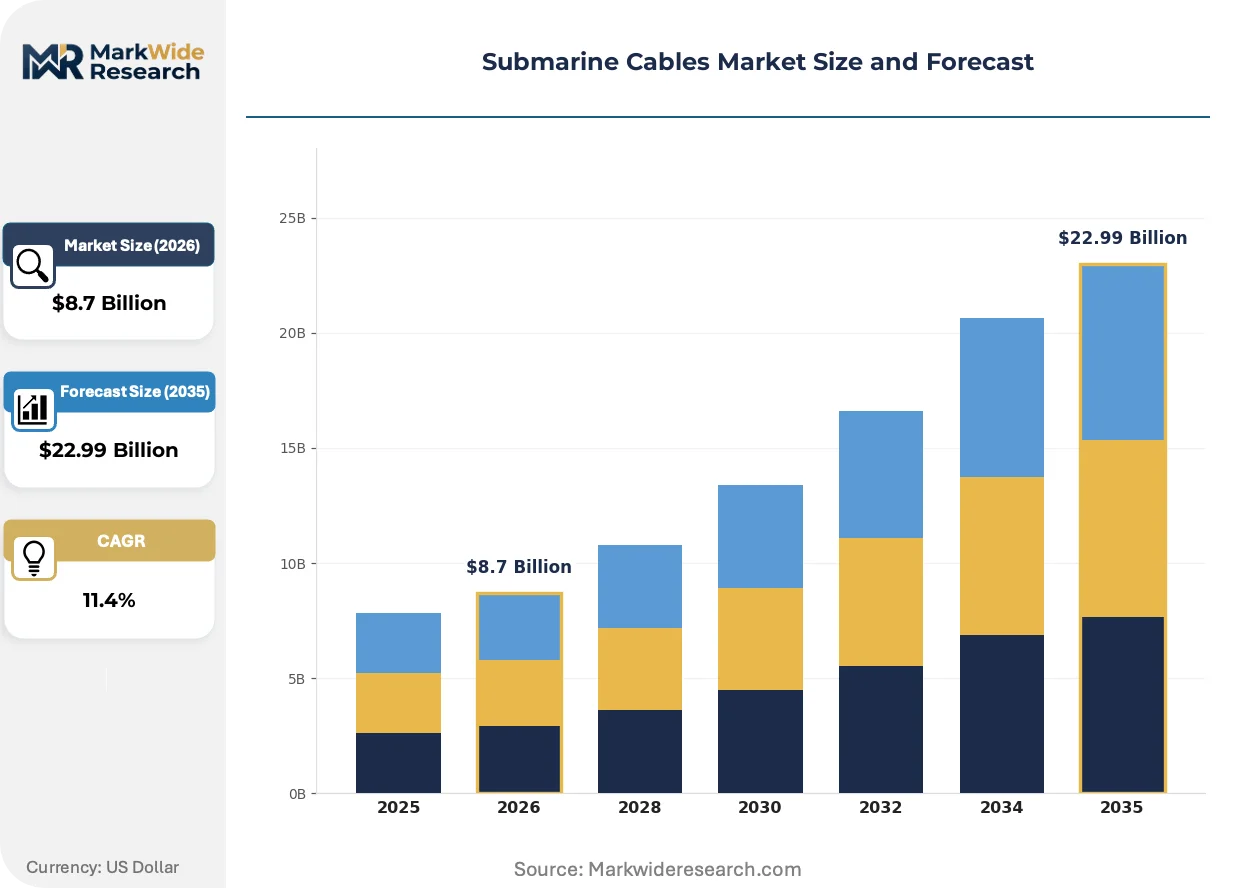
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Optic, Coaxial, Copper, Hybrid Application: Telecommunication, Data Transmission, Military, Offshore Energy Deployment: Installation, Maintenance, Upgrade, Decommissioning End User: Telecom Operators, Government Agencies, Research Institutions, Enterprises |
| Companies Covered | NEC Corporation, Hengtong Group, Alcatel Submarine Networks, Sumitomo Electric Industries, DOS Cable, Prysmian S.p.A, Nexans, LS Cable & System, SubCom, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Submarine Cables Market Strategic Shifts
Subsea transmission technology is bifurcating between ultra-high-capacity fiber systems for intercontinental routes and specialized power cables for offshore energy export. This divergence is fragmenting supplier capabilities and creating distinct competitive arenas.
Multi-core fiber designs with spatially separated light paths are overtaking conventional single-mode fiber as the default specification for new transpacific cable builds. Hyperscale purchasers are mandating SDM-compatible fiber counts in tender documents to preserve upgrade headroom. This technology compression is reducing the number of viable cable designs per route and concentrating procurement decisions around fiber pair quantity rather than spectral efficiency optimization.
The EU CSRD disclosure requirements are extending supply chain due diligence obligations to subsea cable manufacturers regarding seabed disturbance and end-of-life recovery planning. Industrial consequence includes mandatory third-party certification of burial depth compliance and materials traceability. European landing projects are most affected, with developers front-loading environmental impact assessment costs to secure construction windows.
Consortium purchasing arrangements are consolidating buyer power through multi-stakeholder cable ownership structures that displace bilateral carrier-supplier negotiations. Wholesale bandwidth trading platforms are emerging as the preferred channel for capacity allocation among non-operating investors. This behavioral shift is most visible across trans-Atlantic routes, where financial investors now participate directly in cable system economics without operating retail networks.
Submarine Cables Market Segmentation
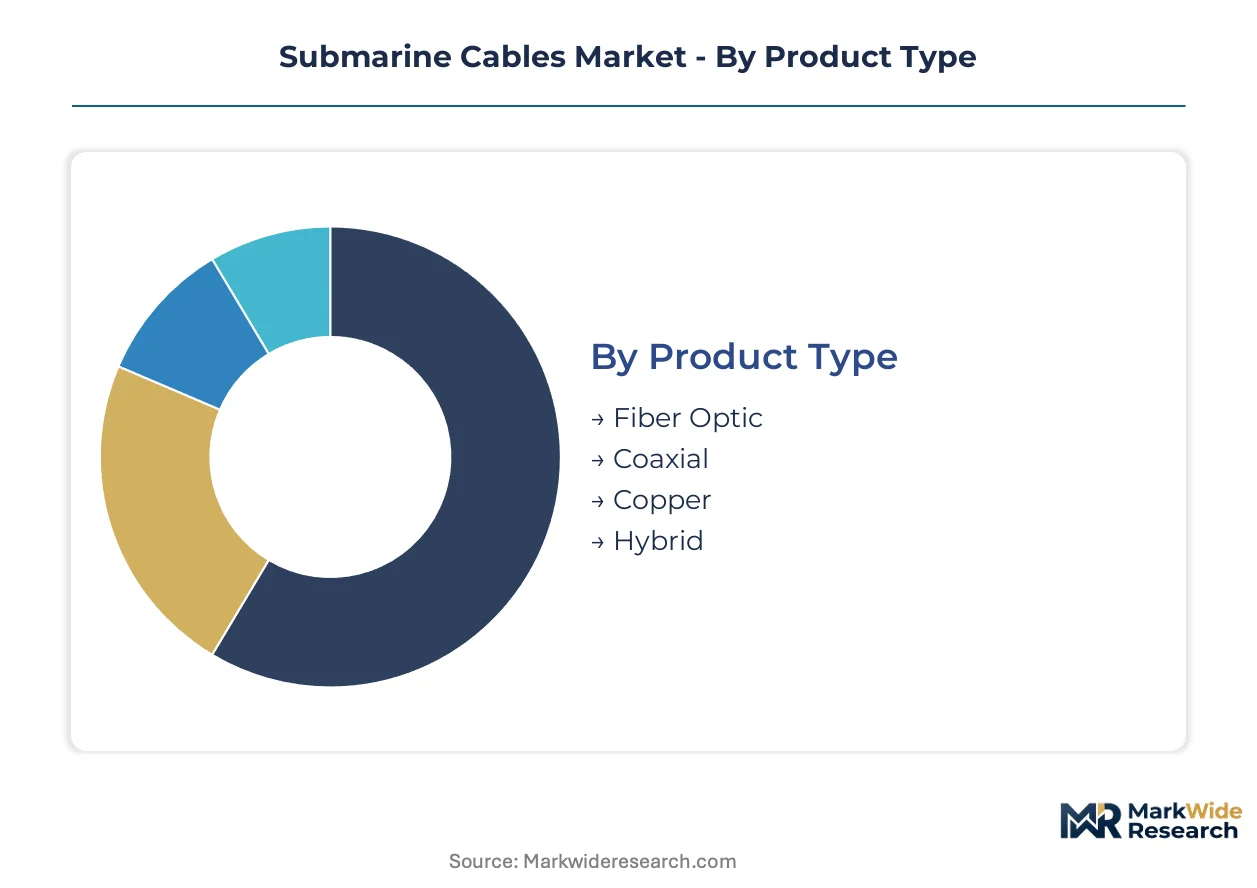
Submarine cable procurement patterns diverge sharply between turnkey system purchases and component-level sourcing. Understanding where each segment sits on this integration spectrum reveals which suppliers capture margin and which face commoditization pressure.
Product Type:
Fiber optic systems dominate standalone deployments while copper and hybrid configurations persist in embedded retrofit applications.
- Fiber Optic:Silica-core waveguides with repeater-amplified transmission enable petabit-scale capacity across trans-Pacific routes. Hyperscale cloud operators in the United States, Japan, and Australia now pre-commit dedicated fiber pairs before marine installation begins.
- Coaxial:Copper-core conductors with dielectric insulation and metallic shielding still carry legacy traffic on 1990s-era trans-Atlantic routes. Maintenance demand concentrates where full fiber replacement remains uneconomical for lower-traffic corridors.
- Copper:Solid or stranded conductor arrays for short-haul power transmission and legacy telegraph circuits.
- Hybrid:Combined fiber-power configurations serving offshore wind export with integrated communications tethering.
Fiber optic leads volumes today; hybrid designs are gaining share fastest.
Application:
Cost tier differentiation separates high-bandwidth telecommunications from specialized military and energy applications with divergent certification requirements.
- Telecommunication:Intercontinental voice and data trunking remains the volume anchor. FCC licensing in the United States and Japan's Ministry of Internal Affairs and Communications enforcement shape route economics through landing station permitting timelines.
- Data Transmission:Dedicated hyperscale fiber pairs for cloud provider data center interconnection. SDM technology adoption is compressing unit costs for bandwidth-intensive deployments.
- Military:Hardened cables with enhanced armor and encryption protocols for sovereign communications.
- Offshore Energy:Dynamic high-voltage export connections for floating wind arrays with limited incumbent competition.
Telecommunication leads volumes today; offshore energy is climbing the fastest.
Deployment:
Maturity gradients separate established installation services from emerging upgrade and decommissioning revenue pools with distinct capability requirements.
- Installation:Marine cable-laying and burial operations requiring specialized vessel fleets. Charter rate volatility spikes when concurrent projects concentrate demand among three operator fleets.
- Maintenance:Deep-water retrieval and repair services command durable margins given technician scarcity below 4,000 meters.
- Upgrade:Repeater replacement and fiber pair activation on existing sheaths.
- Decommissioning:Seabed recovery and materials processing under EU CSRD end-of-life traceability requirements.
Installation leads volumes today; decommissioning is expanding most quickly.
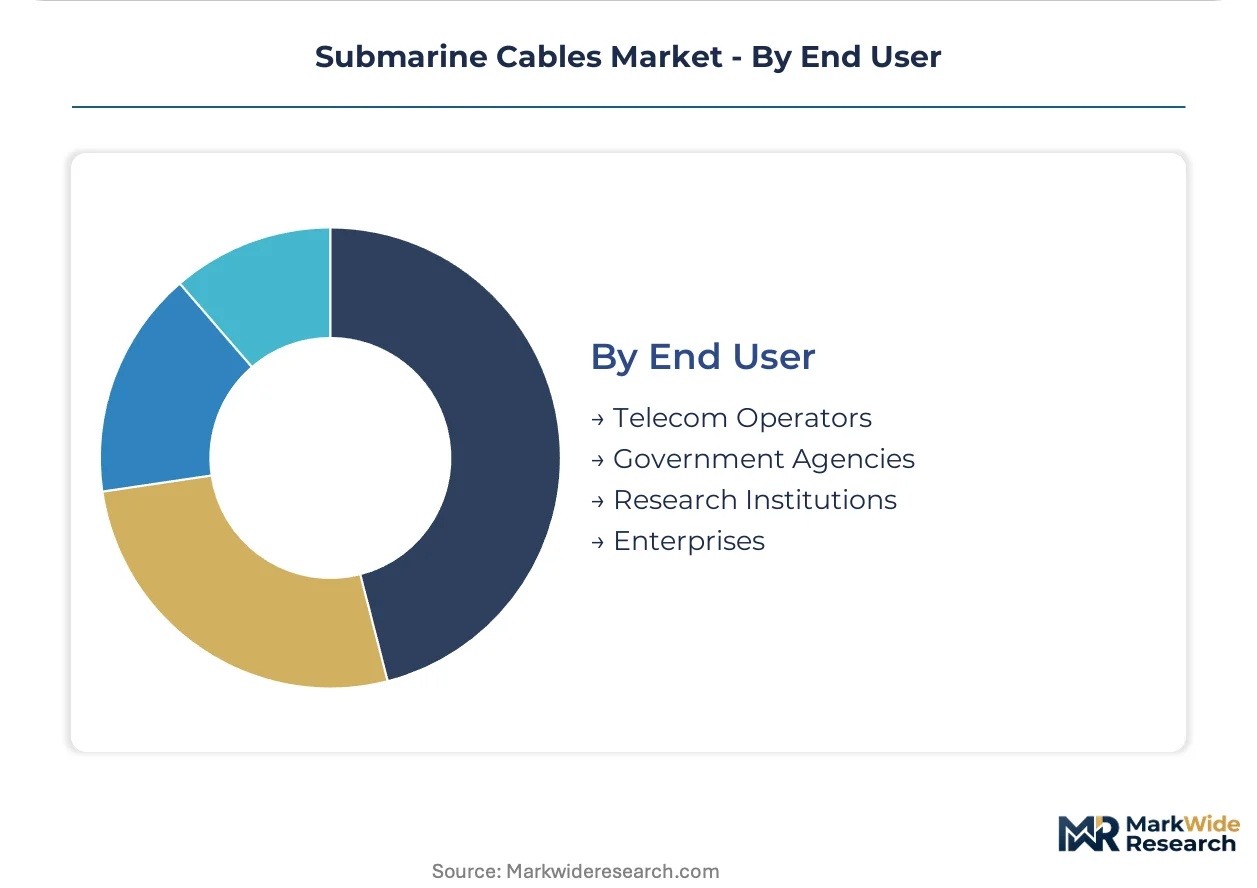
End User:
Customer type fragmentation concentrates procurement authority among consortium-structured carriers while government and enterprise buyers operate on different contracting calendars.
- Telecom Operators:Consortium-led cable ownership structures now displace bilateral carrier-supplier negotiations. Wholesale bandwidth trading platforms allocate capacity among non-operating investors on trans-Atlantic routes.
- Government Agencies:Sovereign security requirements drive hardened cable specifications with classified routing protocols.
- Research Institutions:Scientific observation networks with specialized sensor integration needs.
- Enterprises:Direct fiber pair leasing by financial and media firms seeking latency arbitrage.
Telecom operators lead volumes today; enterprises are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trans-Pacific cable corridors anchor submarine infrastructure deployment, with hyperscale cloud operators driving capacity expansion across the United States, Japan, and Australia. Landing station clusters in California, Tokyo, and Sydney concentrate marine installation activity and maintenance vessel home-porting.
United States
Cloud providers headquartered in Seattle and San Francisco Bay Area pre-commit dedicated fiber pairs on transpacific routes before marine installation begins. FCC licensing mandates environmental review for coastal landing stations, compressing project timelines where state-level California Coastal Commission approvals run on separate calendars. Los Angeles and San Diego anchor West Coast cable landing concentration with multiple redundant station facilities.
Japan
Tokyo-Osaka data center interconnection demand drives subsea procurement for domestic island links and transpacific extensions. The Ministry of Internal Affairs and Communications enforces cable protection zones and landing station licensing with standardized review periods shorter than North American counterparts. Chiba Prefecture hosts dense landing station clustering serving transpacific and intra-Asia routes.
Australia
Sydney-Perth domestic routes and transpacific extensions to Los Angeles command premium pricing for resilience upgrades on aging infrastructure. The Australian Communications and Media Authority coordinates seabed routing with marine spatial planning under national environmental frameworks. Sydney anchors landing concentration with redundant station infrastructure serving both Pacific and Indian Ocean corridors.
China
Domestic coastal connectivity and South China Sea island links drive procurement of specialized shallow-water installation services. The Ministry of Industry and Information Technology licenses international gateway facilities with national security review requirements extending project timelines. Shanghai and Guangdong Province concentrate cable manufacturing and marine operations capabilities.
United Kingdom
Trans-Atlantic route termination and North Sea offshore wind export cables sustain installation vessel demand through concurrent project windows. Ofcom licensing and Marine Management Organisation seabed leasing operate under EU-derived marine spatial planning frameworks post-Brexit. Cornwall and Scotland host Atlantic-facing landing stations with emerging floating wind cable installation activity.
Submarine Cables Market Competitive Environment
Global majors compete with regional champions across marine installation fleet ownership and turnkey project delivery capability. Market structure concentrates among three operator fleets controlling cable-laying ships and burial plows, creating bottleneck risk during concurrent project windows. Strategic archetypes separate integrated manufacturers with captive vessel fleets from component specialists and regional installation contractors. Dominant competitive moves include consortium purchasing arrangements that consolidate buyer power and open cable architecture standards that dissolve traditional vendor lock-in.
Within the integrated manufacturing tier, NEC Corporation and Alcatel Submarine Networks occupy positions exemplifying turnkey project delivery from cable production through marine installation. Hengtong Group represents the Asia-Pacific regional champion archetype with manufacturing scale serving domestic and export markets. These three entities anchor competitive positioning across the three dominant strategic vectors: integrated system delivery, component supply, and regional installation services.
| Leading Market Players |
|---|
| NEC Corporation |
| Hengtong Group |
| Alcatel Submarine Networks |
| Sumitomo Electric Industries |
| DOS Cable |
| Prysmian S.p.A |
| Nexans |
| LS Cable & System |
| SubCom, LLC |
| Others |
Value Chain & Pricing Dynamics
EU CSRD disclosure requirements for seabed disturbance and end-of-life recovery planning gate qualified supply access and premium-tier pricing for European landing projects. Developers front-loading environmental impact assessment costs to secure construction windows face bifurcated supplier tiers based on third-party burial depth certification and materials traceability compliance.
Pricing Analysis
Input-cost pass-through limitations on copper and steel armor compress fixed-price contract margins when commodity cycles spike during multi-year build schedules. Project-based long-term contracting dominates, with price differentiation resting on fiber pair count and SDM compatibility specifications. Pricing pressure stems from hyperscale purchaser consortiums consolidating bargaining power through multi-stakeholder ownership structures. Tier 1 cloud operators demonstrate lowest price sensitivity given dedicated fiber pair pre-commitments, while regional telecom carriers face acute cost compression on standard capacity allocations.
Supply Chain Analysis
US Inflation Reduction Act domestic content incentives for subsea cable manufacturing equipment are reshaping sourcing patterns toward US-based armoring and sheathing facilities. Geographic supply concentration centers on Japan, France, and China for integrated system delivery, with specialized cable-laying vessel fleets anchored in these markets. Raw material dependencies draw from copper conductor arrays, silica-core fiber, and polyethylene sheathing compounds. Single-source vulnerability concentrates among three operator fleets controlling burial plows and marine installation capacity. Distribution runs through consortium purchasing arrangements and wholesale bandwidth trading platforms allocating capacity among non-operating investors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where hyperscale cloud operators mandating SDM-compatible fiber counts in tender documents shift procurement toward premium specification tiers. Consortium purchasing arrangements and open cable architecture standards reward suppliers with certified interoperability capabilities.
For Market Incumbents: Deepen captive vessel fleet utilization through concurrent project scheduling to defend against charter rate volatility when multiple systems enter marine installation phase simultaneously. NEC Corporation and Alcatel Submarine Networks should extend turnkey project delivery capabilities into floating offshore wind export cable methodologies before market formalization erodes first-mover margins. Certification investment in EU CSRD-compliant burial depth verification preserves access to European landing project premiums.
For New Entrants and Emerging Players: Launch via development finance institution co-funding partnerships targeting underpenetrated archipelago routes linking Indonesia, Papua New Guinea, and Pacific island states. Indo-Pacific island connectivity commands premium pricing for resilience upgrades where redundant infrastructure remains absent. White-space concentration sits with specialized shallow-water installation services for domestic coastal connectivity and South China Sea island links. Go-to-market positioning should emphasize dynamic high-voltage subsea power connection expertise for pre-commercial floating wind arrays.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional installation contractors lacking integrated manufacturing capabilities but holding marine operations center licenses in high-activity landing clusters. Long-term viability framing centers on technician training program scale to address deep-water splicing expertise gaps below 4,000 meters as retiring specialist pools contract. Acquisition target archetype: component specialists with open cable architecture standard certification and established relationships with hyperscale procurement teams. The signal to watch is FCC licensing timeline compression versus state-level coastal commission approval acceleration as regulatory friction indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Consortium Purchasing Arrangement | Consolidates buyer power and displaces bilateral carrier-supplier negotiations across trans-Pacific routes. |
| Open Cable Architecture Certification | Dissolves vendor lock-in and forces competition on component interoperability rather than proprietary integration. |
| Floating Wind Export Cable Methodology Development | Establishes installation capabilities before market formalization in emerging offshore energy applications. |
| Deep-Water Splicing Training Program Scale-Up | Addresses technician scarcity below 4,000 meters threatening maintenance contract margins. |
| EU CSRD Compliance Certification Investment | Preserves premium-tier access to European landing projects with mandatory third-party burial depth verification. |
Study Parameters
Multiple input streams — cable system procurement databases, marine installation vessel charter records, and hyperscaler capex disclosures — were reconciled across primary interviews with submarine cable consortium procurement leads, marine operations directors at installation fleet operators, and regulatory affairs specialists at landing station developers. Secondary validation drew from FCC licensing filings, Japan Ministry of Internal Affairs and Communications cable protection zone registrations, EU Marine Strategy Framework Directive seabed corridor reservation records, and International Cable Protection Committee routing standards documentation. Bottom-up project pipeline aggregation and top-down bandwidth demand modeling were triangulated to cross-verify capacity expansion trajectories.
Historical deployment patterns against panel input from consortium structuring advisors and wholesale bandwidth trading platform operators informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type integration spectrum, application cost tier, deployment maturity gradient, and end-user procurement authority concentration. CAGRs were derived from fiber pair activation schedules and repeater upgrade cycles. Industry-specific forecast inputs encompassed SDM technology adoption curves and floating offshore wind array commissioning timelines.
Several conditions sit outside the modeled scope, including sovereign security-classified military cable specifications, force majeure marine weather delays, and unannounced hyperscale data center location shifts. Forecasts reflect documented assumptions regarding permitting timeline standardization and vessel fleet availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Insulated Wire and Cable Market
Cables
Global Wires and Cables Market
Cables
Ethernet Converters Market
Cables
Submarine Communication Cables Market
Cables
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market
Cables
Cable Management Accessories Market
Cables
Submarine Data Cables Market
Cables
Premise Cable Market
Cables
Downhole Cables Market
Cables
Direct Attach Cable Market
Cables
Cable Management System Market
Cables
High-Speed Interconnects Market
Cables
Radio Frequency Cables Market
Cables
Copper Cable Market
Cables
Mexico Wires and Cables Market
Cables
High Voltage Cable Termination Market