
 Submarine Cabling Systems Market | 2026-2036
Submarine Cabling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Submarine Cabling Systems Market Analytics
Multi-source procurement for armored cable cores is rebalancing toward vertically integrated suppliers with captive optical fiber drawing capacity. Prysmian SpA leverages Mediterranean manufacturing scale to dominate European offshore wind export cable contracts. SubCom, LLC anchors transoceanic route deployment through its specialized marine installation fleet. NEC Corporation differentiates in the Asia-Pacific theater with high-fiber-count repeatered systems.
Submarine cabling systems consist of pressure-resistant conductor bundles, typically steel-wire armored and polyethylene-sheathed, engineered to transmit optical signals or electrical power across seabed environments at depths exceeding 8,000 meters. Their primary purpose is to enable intercontinental data traffic and offshore energy grid interconnection without surface infrastructure vulnerability. Optical fiber cables sustain the dominant share of deployed route kilometers, while power cables command concentrated margin pools given bespoke engineering for high-voltage direct current transmission. Composite cables, integrating both signal and power elements, are gaining traction in offshore wind collector systems where installation cost minimization outweighs unit price premiums.
FCC submarine cable licensing rules in the United States, EU Green Deal marine spatial planning requirements, and Japan METI seabed corridor coordination protocols collectively shape route approval timelines and cable protection zone designations. ECHA REACH compliance on lead-free sheath compounds and GB standards referenced by China's MIIT for international gateway projects further constrain material substitution flexibility. Stakeholders must weigh regulatory pre-certification investments against the contracting windows of multilateral development bank-financed connectivity initiatives.
Market Dynamics
Trans-Pacific bandwidth demand from hyperscale cloud providers is compressing cable deployment cycles and forcing armored fiber suppliers to secure polyethylene-sheath compound inventories eighteen months ahead of marine installation windows.
Growth Catalysts
- EU Green Deal offshore wind mandates:North Sea grid interconnection targets are accelerating high-voltage direct current cable orders for collector systems connecting turbine arrays to onshore substations.
- Japan METI seabed corridor protocols:Coordinated route planning between Tokyo, Osaka, and Fukuoka landing points is reducing permitting delays for transpacific fiber builds.
- Cloud data center interconnectivity:Hyperscale operators in Virginia, Singapore, and Dublin are commissioning dedicated dark fiber pairs on new submarine routes to bypass terrestrial congestion.
Market Restraints
- Steel-wire armor supply concentration:Specialty metallurgical capacity for deep-water tensile strength requirements clusters in three East Asian wire-drawing facilities.
- ECHA REACH lead-free sheath compliance:Substitution timelines for halogen-free flame-retardant compounds are extending material qualification cycles by eight to fourteen months.
- Marine installation vessel scarcity:Purpose-built cable-laying ships with dynamic positioning systems face eighteen-month charter backlogs, compressing project execution windows.
Strategic Opportunities
- Offshore wind floating platform electrification:Dynamic cable solutions for tethered substations in waters exceeding sixty-meter depths represent uncontracted engineering demand.
- GB standards gateway projects:China's MIIT reference standards for international landing stations are creating certification pathways for European armor suppliers.
- Composite signal-power cable convergence:Integrated fiber-collector designs are unbundling installation contracts from pure cable supply, capturing margin from offshore wind EPCs.
Industry Challenges
- Deep-water splicing technician scarcity:Certified jointing specialists for eight-thousand-meter rated repeaters number fewer than two hundred globally.
- Multilateral development bank compliance timelines:FERC submarine cable licensing in the United States and concurrent EU marine spatial planning reviews are extending project finance close dates by twelve to eighteen months.
- Legacy copper coaxial remediation:Decommissioning obligations for retired transoceanic telephone cables are diverting capital from greenfield fiber deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Submarine Cabling Systems Market |
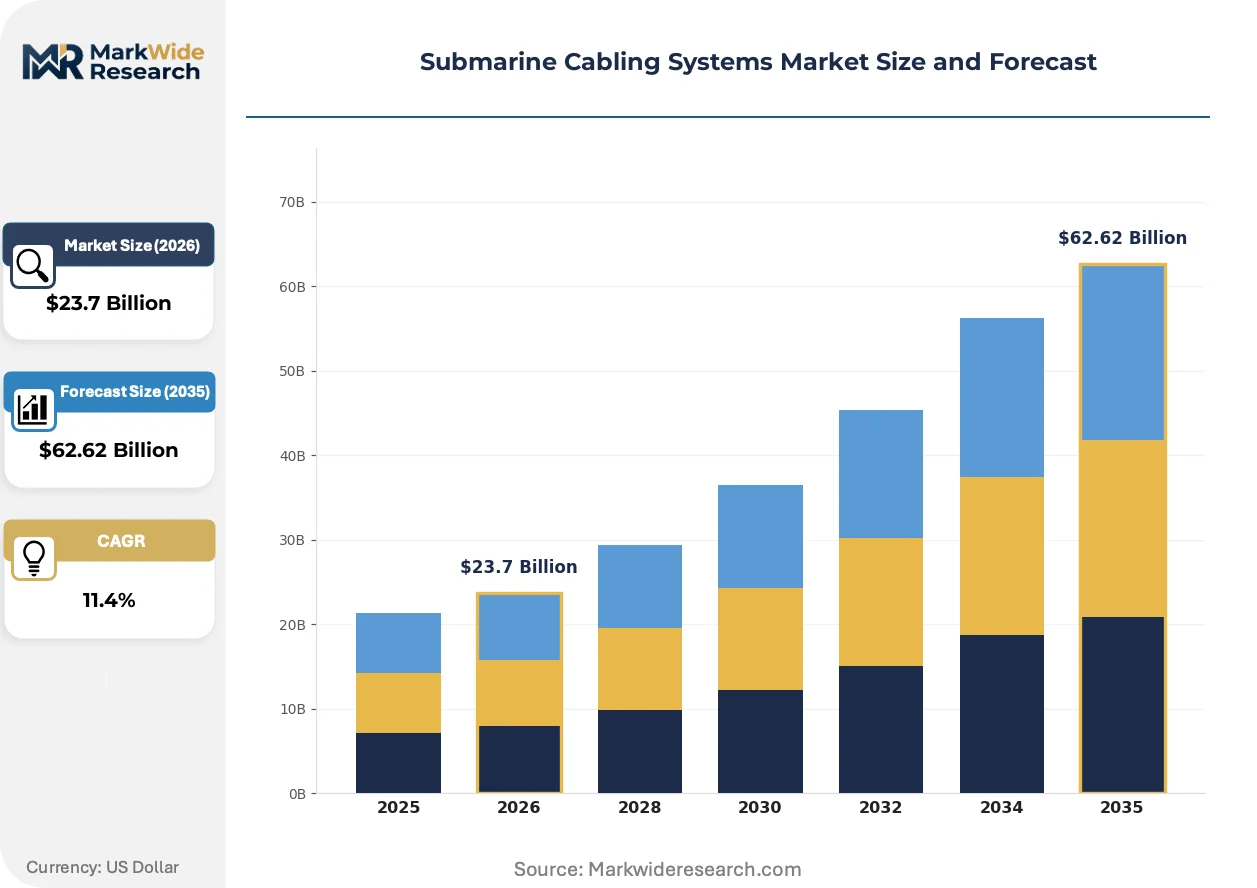
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Fiber Cables, Power Cables, Composite Cables, Communication Cables End User: Telecommunications Providers, Energy Companies, Government Agencies, Research Institutions Installation Type: Onshore Installation, Offshore Installation, Hybrid Installation, Subsea Installation Deployment Model: Private Network, Public Network, Hybrid Network, Dedicated Network |
| Companies Covered | Prysmian SpA, Alcatel Submarine Networks, SubCom, LLC, NEC Corporation, Nexans SA, Sumitomo Electric Industries Ltd, HMN Technologies Co., Ltd., NKT A/S, LS Cable & System Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Submarine Cabling Systems Market Evolving Landscape
Material science advances and regulatory coordination mechanisms are compressing the traditional tradeoff between optical transmission density and power-carrying capacity in subsea infrastructure.
Space-division multiplexing fiber architectures are unifying previously separate signal paths into single sheathed bundles. SubCom and NEC Corporation are deploying twenty-four fiber-pair systems on transpacific routes, displacing older sixteen-pair designs. This unifying technology is collapsing the cost-per-bit for cloud interconnectivity and enabling direct submarine links between previously uneconomical secondary landing points.
EU Green Deal marine spatial planning requirements are mandating cable burial depth minima and fisheries coordination zones across North Sea corridors. These rules are extending route survey durations but reducing post-lay repair incidence by standardizing seabed corridor widths. Offshore wind developers in Danish and German waters are absorbing these compliance costs into EPC contracts rather than passing through to cable suppliers.
Buyers are consolidating procurement authority into centralized infrastructure investment vehicles rather than maintaining separate carrier procurement functions. This consolidation is compressing supplier negotiation cycles and favoring vendors with integrated marine installation capabilities. The shift is most pronounced among European telecommunications incumbents restructuring subsea assets into standalone wholesale operators.
Submarine Cabling Systems Market Segmentation
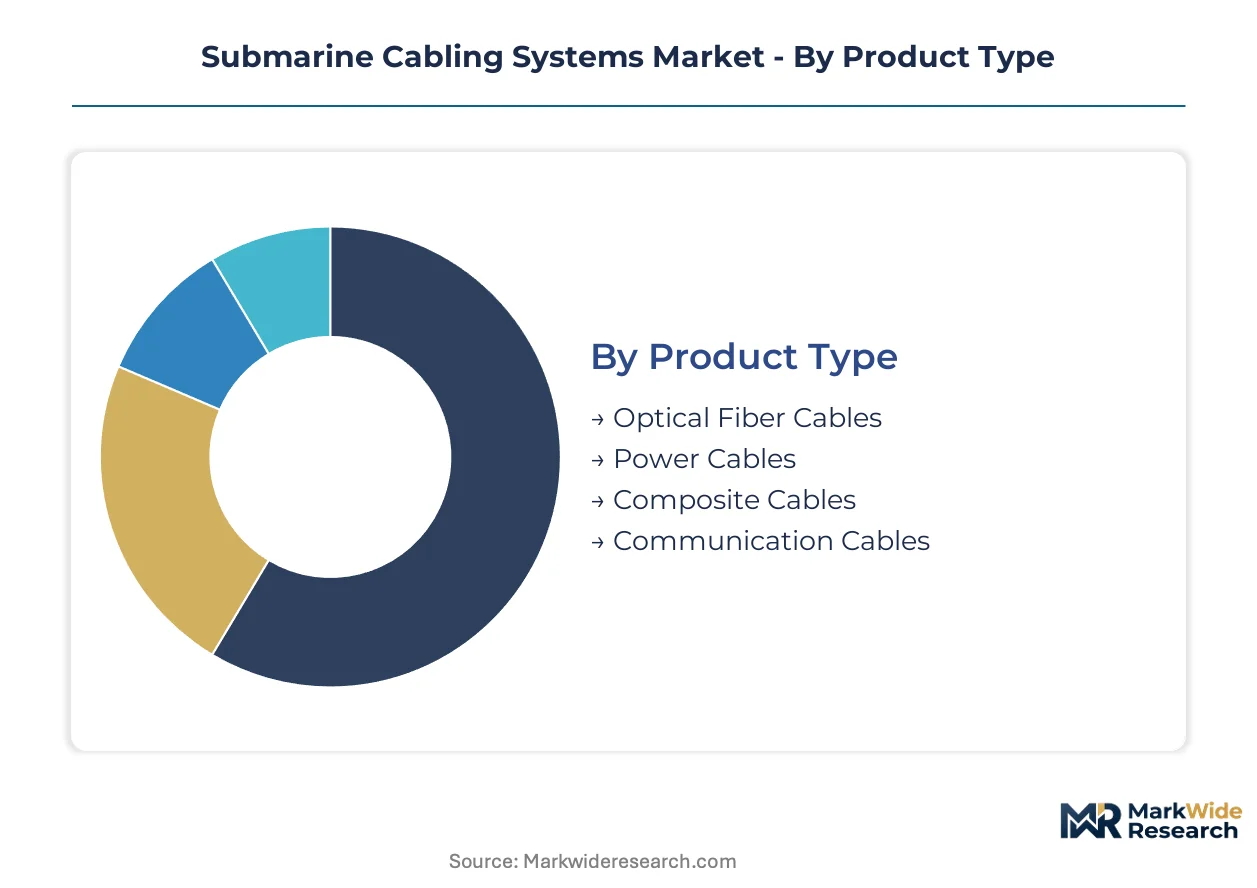
Segmentation in submarine cabling systems reveals how engineering specifications diverge across route depths, voltage classes, and ownership structures. Procurement patterns track closely to these technical boundaries, with distinct supplier qualifications governing each category.
Product Type:
Standardization dominates armored fiber and power conductor designs, while composite configurations demand bespoke engineering for each offshore wind array.
- Optical Fiber Cables:Steel-wire armored bundles with polyethylene sheathing transmit optical signals across seabed environments exceeding 8,000 meters depth. Trans-Pacific corridors linking Japan, the United States, and Australia concentrate hyperscale cloud provider demand for high-fiber-count repeatered systems. FCC submarine cable licensing rules shape route approval timelines for these deployments.
- Power Cables:High-voltage direct current conductors engineered for offshore grid interconnection command concentrated margin pools given bespoke insulation engineering. EU Green Deal offshore wind mandates in the North Sea are accelerating orders for collector systems connecting turbine arrays to onshore substations. ECHA REACH compliance on lead-free sheath compounds constrains material substitution flexibility.
- Composite Cables:Integrated signal-power designs are gaining traction in offshore wind collector systems where installation cost minimization outweighs unit price premiums.
- Communication Cables:Legacy copper coaxial systems face decommissioning obligations that divert capital from greenfield fiber deployments.
Most installed capacity flows through Optical Fiber Cables. Expansion is steepest in Composite Cables.
End User:
Procurement authority concentrates differently across these stakeholders, with telecommunications incumbents consolidating into wholesale operators while energy companies retain project-specific EPC contracting.
- Telecommunications Providers:Hyperscale operators in Virginia, Singapore, and Dublin are commissioning dedicated dark fiber pairs on new submarine routes to bypass terrestrial congestion. These buyers are consolidating procurement into centralized infrastructure investment vehicles, compressing supplier negotiation cycles and favoring vendors with integrated marine installation capabilities.
- Energy Companies:Offshore wind developers in Danish and German waters absorb EU Green Deal marine spatial planning compliance costs into EPC contracts rather than passing through to cable suppliers. Floating platform electrification in waters exceeding sixty-meter depths represents uncontracted engineering demand for dynamic cable solutions.
- Government Agencies:Multilateral development bank-financed connectivity initiatives require stakeholders to weigh regulatory pre-certification investments against contracting windows.
- Research Institutions:Seabed observation networks and oceanographic monitoring systems drive demand for specialized low-data-rate cables with extended design lives.
Telecommunications Providers anchor current order volumes. Energy Companies are climbing the fastest as offshore wind scales.
Installation Type:
Marine installation vessel scarcity creates the sharpest cost tier differentiation, with charter backlogs extending eighteen months for purpose-built cable-laying ships.
- Offshore Installation:Purpose-built cable-laying ships with dynamic positioning systems face eighteen-month charter backlogs, compressing project execution windows. Deep-water splicing technician scarcity—fewer than two hundred certified jointing specialists globally for eight-thousand-meter rated repeaters—further constrains capacity.
- Subsea Installation:Full seabed deployment including burial and post-lay survey commands premium day rates given specialized trenching equipment requirements. Japan METI seabed corridor protocols are reducing permitting delays for transpacific fiber builds through coordinated route planning between Tokyo, Osaka, and Fukuoka landing points.
- Onshore Installation:Terrestrial cable landing station construction and beach manhole preparation precede marine operations.
- Hybrid Installation:Combined onshore-offshore contracting unbundles installation from pure cable supply, capturing margin from offshore wind EPCs.
Subsea Installation commands the highest contract values. Hybrid Installation is gaining share fastest as integrated procurement expands.
Deployment Model:
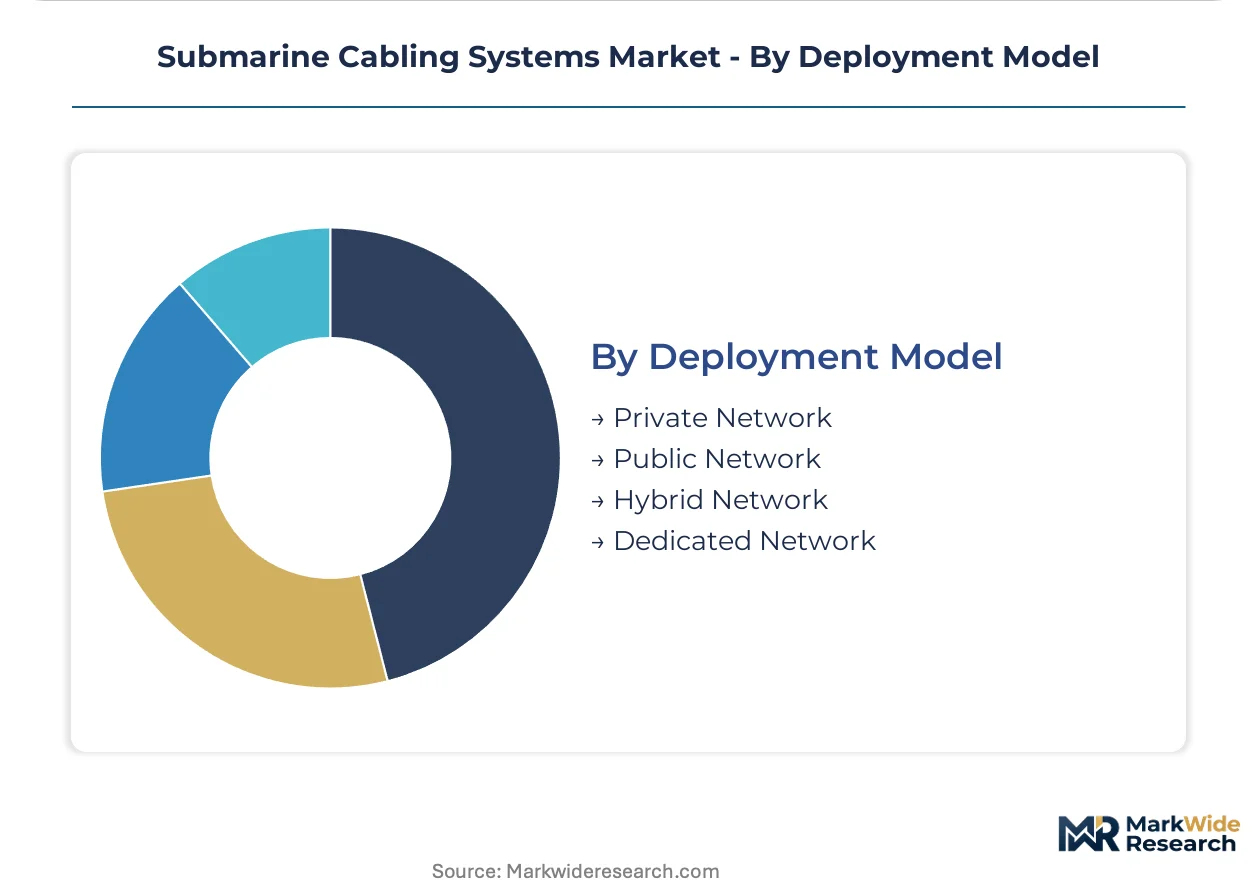
Ownership structure determines regulatory exposure and margin retention, with private networks avoiding wholesale pricing pressure.
- Private Network:Hyperscale cloud operators deploy dedicated submarine fiber pairs outside carrier consortium structures, retaining full capacity control. These deployments bypass terrestrial congestion between data center clusters in Virginia, Singapore, and Dublin.
- Dedicated Network:Single-purpose infrastructure for financial exchanges or defense applications carries sovereign security requirements and restricted supplier lists.
- Public Network:Open-access submarine cable systems sell capacity to multiple carriers under standardized interconnection agreements.
- Hybrid Network:Mixed ownership structures blend private fiber pairs with wholesale capacity sales to optimize capital recovery.
Private Network deployments absorb the largest capital commitments. Dedicated Network expansion is accelerating most quickly on security-driven procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea offshore wind corridor anchors submarine cable demand through 2035, with trans-Pacific fiber routes and European grid interconnections forming secondary concentration zones.
United States
Virginia Beach and Los Angeles landing stations absorb hyperscale cloud provider investments for transpacific capacity. FCC submarine cable licensing rules extend approval timelines for new Pacific routes. SubCom, LLC maintains marine installation fleet positioning from its East Coast operations base.
China
MIIT reference standards for international gateway projects create certification pathways for armor suppliers serving Pearl River Delta data center clusters. GB standards compliance constrains material substitution flexibility for sheath compounds. Qingdao and Shanghai manufacturing bases concentrate optical fiber drawing capacity.
Japan
METI seabed corridor protocols coordinate route planning between Tokyo, Osaka, and Fukuoka landing points. NEC Corporation deploys high-fiber-count repeatered systems from its domestic engineering centers. Chubu region manufacturing supplies armored cable cores for Asia-Pacific routes.
Germany
North Sea offshore wind mandates accelerate high-voltage direct current cable orders for turbine array connections. EU Green Deal marine spatial planning requirements standardize seabed corridor widths across Danish and German waters. Hamburg and Bremen ports serve as cable loading hubs for Baltic and North Sea installations.
United Kingdom
Scottish and English east coast offshore zones drive floating platform electrification demand for dynamic cable solutions. ECHA REACH compliance on lead-free sheath compounds extends material qualification cycles. Teesside and Hunterston landing stations anchor trans-Atlantic fiber capacity.
Submarine Cabling Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue composite cable integration and floating platform electrification. The vendor base stratifies across three capability tiers: integrated marine installation operators, captive fiber drawing specialists, and project-specific EPC contractors. Strategic archetypes include vertically integrated system suppliers, regional armor fabricators, and installation fleet operators. Competitive moves concentrate on backward integration into optical fiber production and charter agreements for purpose-built cable-laying vessels.
Among European cable specialists, Prysmian SpA and Nexans SA exemplify the integrated system supplier archetype with Mediterranean and North Sea manufacturing scale. SubCom, LLC occupies a distinct position as a marine installation fleet operator anchoring transoceanic route deployment. NEC Corporation represents the Asia-Pacific engineering specialist tier with domestic fiber system capabilities. These three entities collectively illustrate how geographic concentration and capability specialization shape competitive positioning without overlapping strategic territory.
| Leading Market Players |
|---|
| Prysmian SpA |
| Alcatel Submarine Networks |
| SubCom, LLC |
| NEC Corporation |
| Nexans SA |
| Sumitomo Electric Industries Ltd |
| HMN Technologies Co., Ltd. |
| NKT A/S |
| LS Cable & System Ltd. |
| Others |
Value Network & Pricing Analysis
Specialty steel-wire armor for deep-water tensile strength feeds through East Asian wire-drawing facilities into three distinct pricing tiers for telecommunications carriers, offshore wind EPCs, and government connectivity initiatives. Polyethylene-sheath compound inventories secured eighteen months ahead of marine installation windows compress margin flexibility for armored fiber suppliers serving hyperscale cloud routes.
Pricing Analysis
Input-cost pass-through from metallurgical feedstock and halogen-free flame-retardant compounds shapes contract structures across the industry. Project-based long-term offtake agreements dominate, with price differentiation driven by fiber pair count and ECHA REACH certification tier. Pricing pressure stems from marine installation vessel scarcity extending charter backlogs, compressing execution premiums. Telecommunications carriers exhibit highest price sensitivity due to wholesale capacity arbitrage, while energy companies absorb compliance costs into EPC contracts with lower elasticity.
Supply Chain Analysis
Photoresist-grade optical fiber preform supply rests on Japanese and American specialty chemical producers with limited alternative sourcing. Raw material dependencies center on high-purity silicon tetrachloride, germanium tetrachloride, and steel wire rod rated for 8,000-meter depth tolerance. Single-source vulnerability concentrates in East Asian wire-drawing capacity for deep-water armor. Distribution runs through vertically integrated system suppliers with captive marine installation fleets, bypassing pure component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as EU Green Deal offshore wind mandates and Japan METI seabed corridor protocols shift procurement toward premium-specification cables with integrated signal-power architectures.
For Market Incumbents: To counter emerging Asian fiber system specialists with state-backed manufacturing scale, Prysmian and Nexans should deepen backward integration into optical fiber drawing capacity in Mediterranean and North Sea hubs. Securing charter agreements for purpose-built cable-laying vessels with dynamic positioning systems locks in installation capacity against eighteen-month backlogs. ECHA REACH pre-certification investments on lead-free sheath compounds defend qualification timelines against regulatory compression. For New Entrants and Emerging Players: Offshore wind floating platform electrification in waters exceeding sixty-meter depths offers the most penetrable white space, with uncontracted engineering demand for dynamic cable solutions. Composite signal-power cable convergence unbundles installation contracts from pure supply, capturing margin from European EPCs burdened by marine spatial planning compliance costs. Partnership with Danish or German port authorities for cable loading hub access accelerates route to market. For Investors and Strategic Acquirers: Roll-up economics work for regional armor fabricators with captive metallurgical capacity because EU Green Deal standardization is collapsing bespoke engineering premiums into scale-driven procurement. Five-to-ten-year viability hinges on consolidation of installation fleet operators facing charter scarcity. Watch Japan METI corridor protocol adoption rates across Asia-Pacific landing points as inflection signal for repeatered system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Fiber Drawing | Captive preform supply secures margin against East Asian specialty chemical concentration. |
| Marine Installation Fleet Charter Expansion | Dynamic positioning vessel access compresses project execution windows for trans-Pacific routes. |
| Composite Cable System Certification | ECHA REACH lead-free sheath compliance opens EU offshore wind collector contract eligibility. |
| Seabed Corridor Protocol Alignment | Japan METI coordination reduces permitting delays for Tokyo-Osaka-Fukuoka landing point networks. |
| Floating Platform Dynamic Cable Development | Sixty-meter-plus water depth solutions capture uncontracted offshore wind electrification demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured conversations with submarine cable procurement directors, offshore wind EPC project managers, marine installation fleet operators, and regulatory affairs leads at telecommunications incumbents with secondary validation. FCC submarine cable licensing databases, EU marine spatial planning filings, Japan METI seabed corridor coordination records, and hyperscale cloud provider capex disclosures anchored demand-side estimates. Bottom-up route deployment tallies and top-down infrastructure investment flow analysis triangulated market sizing.
Historical reference periods spanning completed trans-Pacific and North Sea cable deployments anchored projection methodologies across the analysis window. Segmentation dimensions modeled include product type, end-user archetype, installation depth class, and deployment ownership structure. CAGRs derived from weighted average of unit deployment growth and value-per-kilometer expansion, with fiber pair density trends and high-voltage direct current voltage class migration as primary industry-specific forecast inputs.
Revisions become necessary when marine installation vessel charter availability shifts, ECHA REACH compliance timelines extend, or multilateral development bank financing windows compress. Forecasts reflect documented assumptions on hyperscale cloud demand continuity and EU offshore wind installation pace. A small set of triggers—steel-wire armor supply concentration events, seabed corridor protocol adoption delays, and floating platform electrification contract awards—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Management Accessories Market
Cables
United States Cable Accessories Market
Cables
Europe Cable Management Market
Cables
Cable Lugs Market
Cables
North America HVAC Cables Market
Cables
Electric Submersible Cable Sales Market
Cables
Downhole Cables Market
Cables
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market
Cables
Electric Vehicle Unshielded HV Cables Market
Cables
Radio Frequency Cables Market
Cables
Cable Drum Market
Cables
Copper Stranded Wire Market
Cables
Data Center Wire and Cable Market
Cables
LED Cable Market
Cables
Global Low Voltage Cable Market
Cables
EDM Wires Market