
 Global Cable Tie Market | 2026-2036
Global Cable Tie Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cable Tie Market Analysis
REACH is pivoting the cost-of-entry calculus for European cable tie suppliers by mandating stricter substance-of-very-high-concern disclosures across polyamide supply chains. HellermannTyton leverages its vertically integrated polymer compounding operations to sustain compliance without sourcing disruption. Panduit dominates North American data center channel partnerships through specification engineering programs that lock in bundle management standards. ABB Installation Products anchors industrial utility demand with IEC-rated stainless steel tie portfolios designed for substation and renewable energy farm deployments.
A cable tie is a fastening device manufactured from injection-molded nylon 6/6, polypropylene, or cold-rolled stainless steel strip, designed to bundle, secure, and route cables, wires, and tubing assemblies across commercial and industrial environments. Tensile strength ratings typically span 18 to 250 pounds depending on material grade and width, with operating temperature thresholds from -40°C to 85°C for standard nylon formulations. Nylon cable ties command the largest volume share due to cost efficiency and universal compatibility with indoor electrical installations, though stainless steel variants capture disproportionate margin pools in offshore oil, gas, and heavy infrastructure applications where corrosion resistance and extreme load bearing justify premium positioning. The automotive end-user segment is expanding fastest as electric vehicle architectures multiply high-voltage harness routing complexity and thermal management requirements beyond conventional internal combustion platforms.
The EPA regulates volatile organic compound emissions from nylon resin production facilities, pushing compounders toward closed-loop manufacturing or regional sourcing adjustments to maintain US market access. ECHA's evolving SVHC candidate list under REACH directly impacts colorant and plasticizer formulations used in colored cable tie variants, particularly blue and green grades common in food processing and marine identification protocols. China's SAMR enforces GB/T flame-retardant standards that export-oriented manufacturers must certify against to serve domestic infrastructure projects. Stakeholders must monitor regulatory divergence between EU chemical hazard frameworks and Asia-Pacific national standards, as misalignment in polymer additive approvals threatens to fragment global product lines and force regional SKU proliferation.
Market Dynamics
Data center infrastructure expansion is compressing specification cycles for high-temperature nylon cable ties, forcing compounders to validate flame-retardant grades against diverging national standards before volume deployment.
Growth Catalysts
- Hyperscale data center builds:Fiber-optic and power cable management systems in cloud computing facilities are pulling specialized tie grades with enhanced thermal ratings and color-coding protocols.
- China's GB/T flame-retardant mandates:SAMR-enforced standards for polymer grades are tightening material specifications across export supply chains, elevating certified suppliers.
- Electric vehicle architectures:High-voltage harness routing complexity and thermal management requirements are multiplying tie counts per vehicle platform beyond internal combustion baselines.
Market Restraints
- Caprolactam price volatility:Nylon 6/6 resin feedstock costs fluctuate with benzene and cyclohexane derivatives, compressing margin stability for injection molders.
- REACH SVHC disclosure burdens:ECHA's evolving candidate list mandates costly substance-of-very-high-concern tracking across polyamide supply chains, particularly for colorant formulations.
- Stainless steel substitution ceiling:Cold-rolled strip ties face demand limits in cost-sensitive commercial installations where nylon tensile ratings suffice.
Strategic Opportunities
- Southeast Asia electronics zones:Vietnam and Thailand manufacturing clusters are emerging as demand concentrations for high-temperature nylon ties serving contract assembly operations.
- Renewable energy farm deployments:IEC-rated stainless steel portfolios for substation and solar/wind infrastructure offer premium positioning outside commodity nylon segments.
- Closed-loop manufacturing incentives:EPA volatile organic compound regulations are rewarding compounders with captive resin recovery systems and regional sourcing flexibility.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for halogen-free flame-retardant grades sits concentrated with aging technical workforces in Germany and Japan.
- Multi-jurisdiction certification timelines:Simultaneous GB, REACH, and UL validation cycles extend product launch windows by eight to fourteen months.
- Legacy injection tooling retrofit costs:Existing mold cavities require modification to process bio-based polyamide alternatives without cycle time penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cable Tie Market |
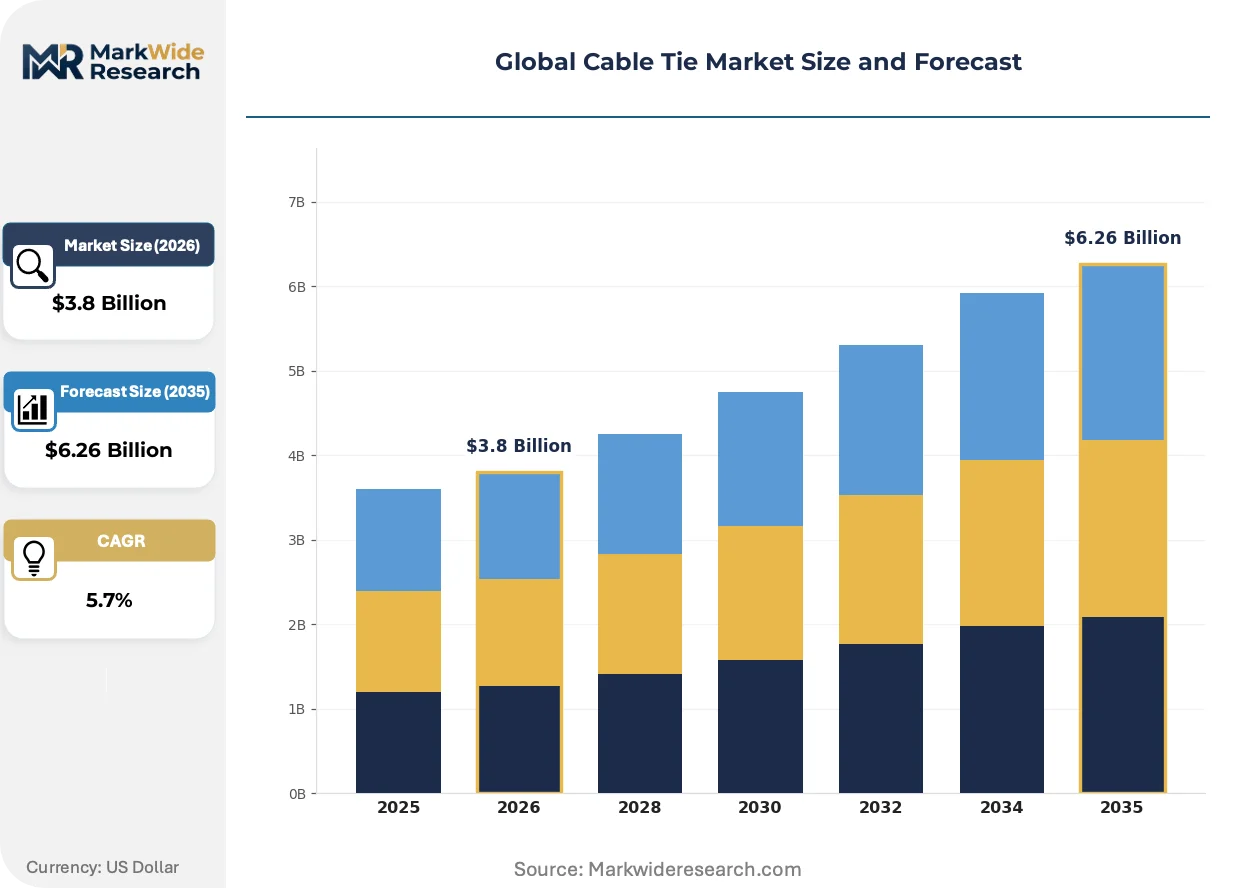
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nylon, Polypropylene, Stainless Steel, Rubber Color: Natural, Black, Blue, Green End User: Electronics, Automotive, Construction, Aerospace Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | 3M Company, Avery Dennison Corporation, Amphenol RF, ABB Installation Products Inc., BAND-IT Inc., Advanced Cable Ties Inc., HellermannTyton Corporation, Legrand S.A., Panduit Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cable Tie Market Emerging Trajectories
Material science convergence and regulatory chemistry mandates are fragmenting product architectures, compelling suppliers to maintain parallel formulation tracks for regional compliance.
Halogen-free flame-retardant nylon compounds are unifying previously separate indoor and outdoor product lines into single-grade platforms. Data center operators in Singapore and Ireland are specifying these materials for unified procurement across climate zones. This convergence is compressing SKU proliferation while demanding higher additive loading precision from compounders.
REACH SVHC candidate list expansion is forcing reformulation of blue and green colorant systems used in food processing and marine identification protocols. European cable tie distributors are demanding batch-level substance declarations from Asian molders. Colored variants face eighteen-month reformulation cycles as ECHA reviews additional phthalate and heavy metal candidates.
Specification engineering programs are displacing traditional distributor relationships in North American data center channels. Engineering firms in Ashburn and Phoenix are embedding bundle management standards directly into construction documents, locking preferred suppliers into multi-year sole-source positions. This pattern is visible across hyperscale builds in Virginia, Texas, and Ohio.
Global Cable Tie Market Segmentation
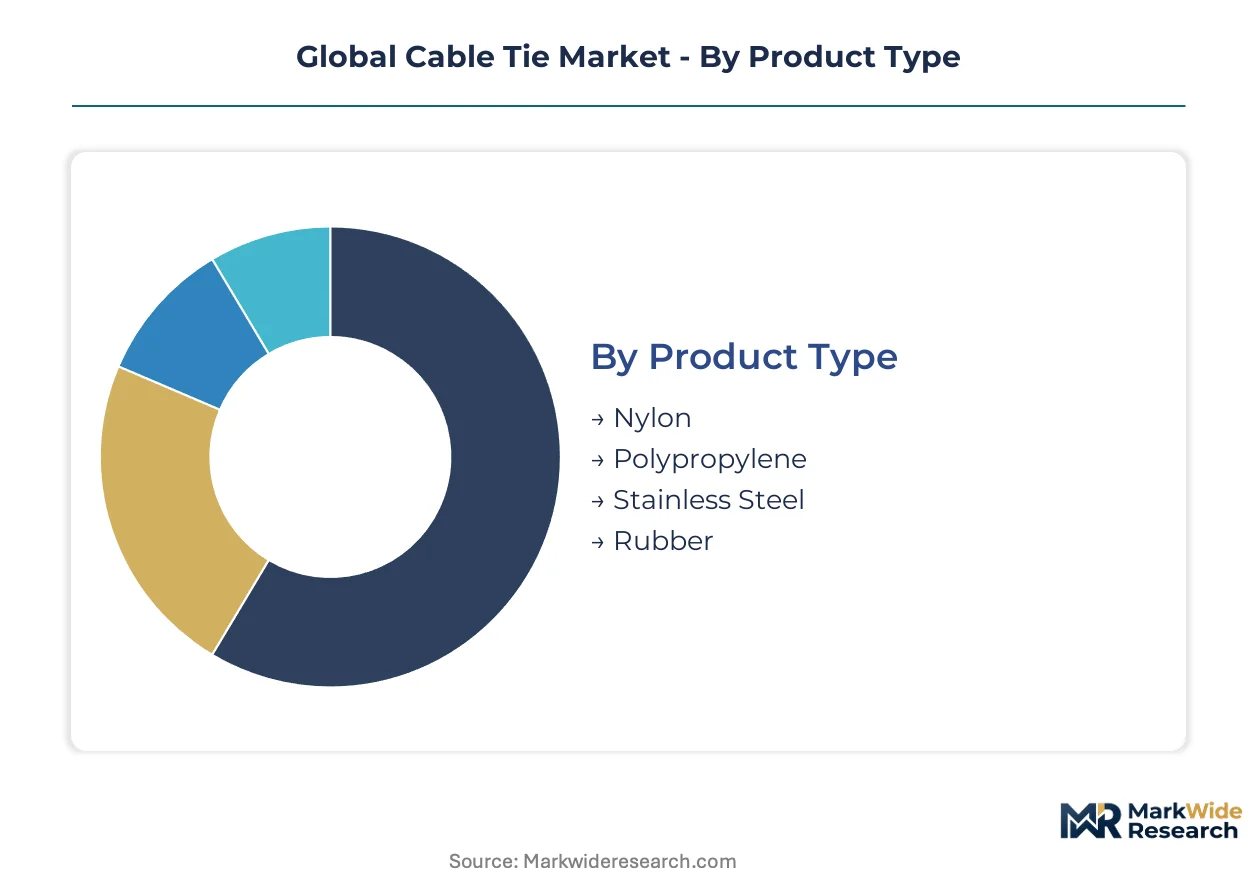
Cable tie segmentation reflects divergent performance requirements across electrical infrastructure, automotive assembly, and heavy industrial applications. Material chemistry, color protocols, and tensile specifications determine procurement decisions in each vertical. Suppliers must maintain parallel production lines to serve commodity bulk buyers alongside precision-engineered contract manufacturers.
Product Type:
Standardization dominates commodity grades while specialized formulations command specification-engineered procurement in critical infrastructure.
- Nylon:Injection-molded nylon 6/6 delivers 18-250 pound tensile ratings with operating thresholds from -40°C to 85°C. Data center construction in Ashburn and Phoenix specifies flame-retardant grades for fiber-optic bundle management. ECHA's evolving SVHC list forces batch-level substance tracking for European-bound shipments.
- Stainless Steel:Cold-rolled strip construction provides corrosion resistance and extreme load-bearing capacity for offshore oil platforms and substation deployments. IEC-rated portfolios anchor renewable energy farm specifications where nylon tensile ratings prove insufficient. Premium positioning captures disproportionate margins in heavy infrastructure.
- Polypropylene:Lower-cost thermoplastic serves indoor commercial installations with moderate tensile requirements. Cost-sensitive construction sectors in Southeast Asia specify polypropylene for non-critical cable routing.
- Rubber:Flexible elastomeric compounds accommodate vibration-dampening applications in marine and transportation equipment. Specialized formulations address niche harness securing in heavy machinery.
Most installed capacity flows through Nylon. Expansion is steepest in Stainless Steel.
Color:
Identification protocols and regulatory visibility standards drive color selection across food processing, marine, and electrical safety applications.
- Natural:Unpigmented nylon 6/6 serves standard indoor electrical installations where visibility against dark cable bundles aids inspection routines. Bulk procurement from construction distributors favors natural grades for cost efficiency.
- Black:Carbon-black loaded formulations provide UV stabilization for outdoor telecommunications and solar farm deployments. UV resistance extends service life in exposed infrastructure across Texas and Arizona renewable installations.
- Blue:Food-grade pigment systems meet FDA visibility requirements for processing equipment maintenance identification. REACH-mandated reformulation cycles extend eighteen months as ECHA reviews phthalate candidates in colorant chemistry.
- Green:Marine and grounding identification protocols specify green variants for safety-critical electrical separation. ECHA's SVHC expansion forces European distributors to demand substance declarations from Asian compounders.
Natural commands volume leadership in construction procurement. Black is gaining share fastest in renewable energy infrastructure.
End User:
Application-specific thermal, chemical, and mechanical requirements fragment demand across manufacturing verticals with divergent certification standards.
- Electronics:High-temperature nylon ties manage densely packed harness routing in server racks and telecommunications switching equipment. Singapore and Ireland data center operators specify unified halogen-free grades across climate zones.
- Automotive:Electric vehicle architectures multiply high-voltage harness complexity beyond internal combustion baselines. OEMs in Germany and Japan specify heat-stabilized grades for battery pack cable management.
- Construction:Bulk procurement of standard nylon and polypropylene ties dominates commercial building electrical rough-in. Cost-sensitive installers prioritize tensile rating sufficiency over specialized formulations.
- Aerospace:FAA-compliant flame-retardant grades with traceable batch documentation serve commercial aircraft manufacturing. Specification engineering locks preferred suppliers into sole-source positions for airframe harness systems.
Construction absorbs the highest unit volumes. Automotive represents the steepest expansion trajectory as electrification accelerates harness complexity.
Distribution Channel:
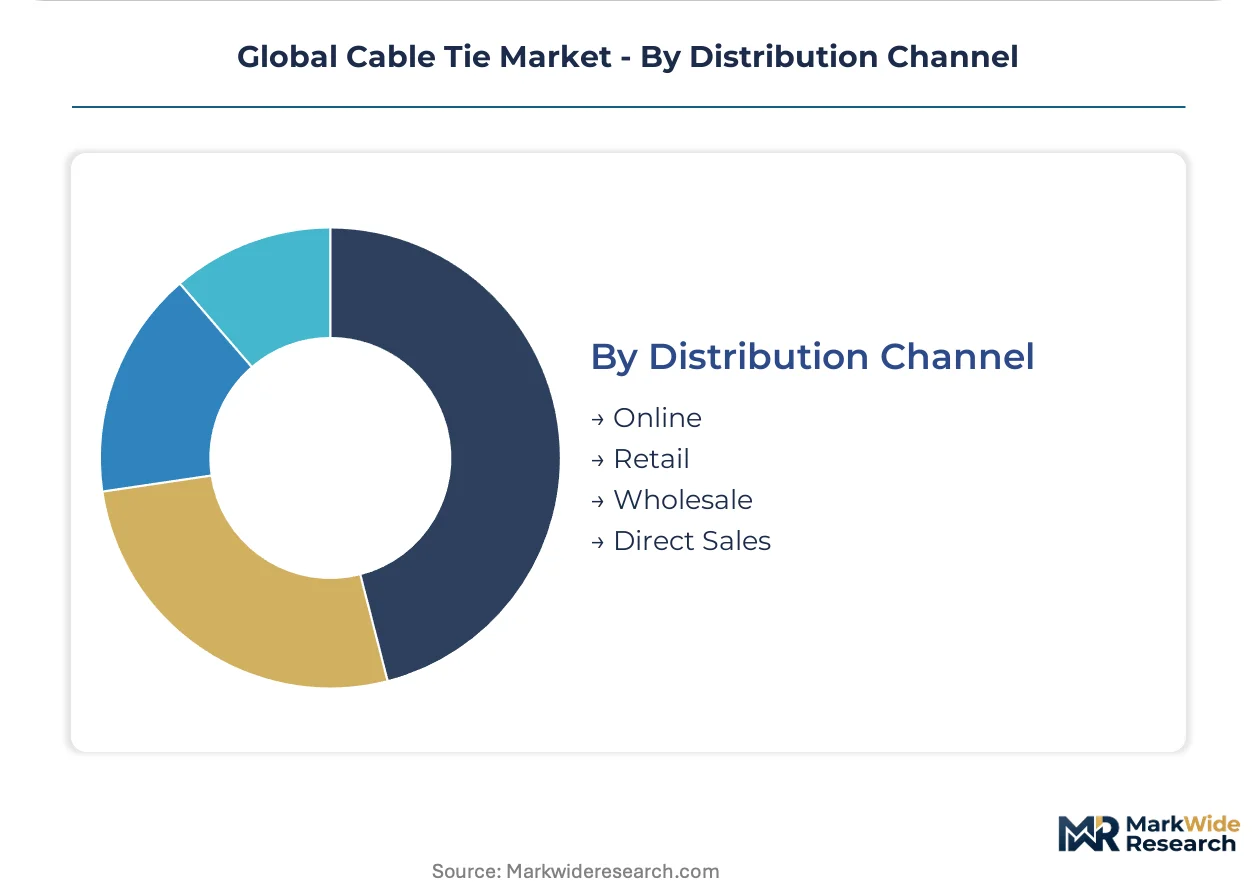
Channel selection reflects order scale, technical specification requirements, and procurement integration with construction or manufacturing workflows.
- Online:E-commerce platforms serve maintenance-repair-operations procurement and small-contractor spot buying. Amazon Business and specialized electrical supply marketplaces capture fragmented demand.
- Retail:Big-box hardware chains stock commodity nylon grades for residential and light commercial electrical work. Home Depot and Lowe's shelf placement determines brand visibility in consumer-facing segments.
- Wholesale:Electrical and industrial distributors aggregate bulk procurement for construction contractors and facility maintenance operations. WESCO and Graybar channel partnerships lock in specification-grade volumes.
- Direct Sales:Manufacturer field engineers embed bundle management standards directly into hyperscale data center construction documents. Panduit and HellermannTyton specification programs bypass distributor markup for strategic accounts.
Wholesale moves the highest volume tonnage. Direct Sales is climbing the fastest as specification engineering displaces traditional distribution in critical infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German polymer chemists anchor the technical workforce for halogen-free flame-retardant formulation, while Chinese injection molding clusters dominate volume manufacturing. India's electrical distribution networks and Vietnam's electronics assembly zones are pulling distinct specification grades.
United States
Hyperscale data center construction in Ashburn and Phoenix specifies flame-retardant nylon grades for fiber-optic bundle management. EPA volatile organic compound regulations push compounders toward closed-loop manufacturing or regional sourcing adjustments. Texas and Arizona renewable energy installations drive UV-stabilized black tie procurement for solar farm cable routing.
China
SAMR-enforced GB/T flame-retardant standards tighten material specifications across export supply chains. The Yangtze River Delta concentration of injection molders serves both domestic infrastructure and electronics manufacturing demand. Zhejiang and Jiangsu provinces house the largest certified capacity for high-temperature nylon compounding.
Germany
Automotive OEMs in Stuttgart and Munich specify heat-stabilized grades for electric vehicle battery pack cable management. ECHA's REACH SVHC candidate list mandates costly substance tracking across polyamide supply chains. Bavaria's aging technical workforce concentrates formulation expertise for halogen-free flame-retardant chemistry.
Vietnam
Electronics manufacturing zones in Bac Ninh and Hai Phong are emerging as demand concentrations for high-temperature nylon ties serving contract assembly operations. The country's national standards regulator enforces import certification for polymer grades used in export-oriented production. Northern industrial provinces attract cable tie distributors establishing regional warehousing.
India
Electrical distribution expansion and commercial construction drive bulk procurement of standard nylon and polypropylene grades. BIS certification requirements for polymer additives create compliance barriers for uncertified imports. Maharashtra and Gujarat manufacturing clusters are developing domestic compounding capacity to serve price-sensitive construction channels.
Global Cable Tie Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across material grades and end-use verticals. The vendor base organizes around three tiers: integrated polymer compounders with captive resin operations, specification-engineered solution providers, and regional injection molding job shops. Two dominant competitive moves are reshaping positioning: backward integration into polymer compounding to secure REACH compliance, and specification engineering programs that embed bundle management standards directly into construction documents.
Within the diversified industrial tier, 3M Company and ABB Installation Products Inc. exemplify conglomerate structures spanning multiple electrical infrastructure categories. HellermannTyton Corporation occupies a specialist position among focused cable management providers. Panduit Corporation anchors the specification-engineered tier through direct field engineering relationships with hyperscale data center developers. Legrand S.A. represents European electrical component diversification into fastening systems.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| Amphenol RF |
| ABB Installation Products Inc. |
| BAND-IT Inc. |
| Advanced Cable Ties Inc. |
| HellermannTyton Corporation |
| Legrand S.A. |
| Panduit Corporation |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between REACH-compliant European shipments and standard-grade Asian exports manifests in parallel pricing ladders and geographically segmented compounding operations. Nylon cable tie suppliers serving ECHA-regulated channels absorb batch-level substance tracking costs that commodity molders bypass, while stainless steel portfolios command premium positioning through IEC-rated corrosion resistance that justifies separate distribution networks.
Pricing Analysis
Specification engineering services bundled with direct sales contracts separate Panduit and HellermannTyton from unbundled wholesale transactions. Three-tier pricing structure across premium, standard, and economy levels tracks material grade, with flame-retardant nylon and stainless steel variants priced above commodity polypropylene. Price erosion runs through standard nylon grades as Chinese injection molding capacity expands. Construction contractors exhibit highest price sensitivity, while data center engineering firms prioritize specification compliance over unit cost.
Supply Chain Analysis
Reverse logistics for polymer scrap recovery operates through compounder-led closed-loop systems serving EPA-regulated US facilities. Manufacturing gravity centers on China, Germany, and Vietnam, with Zhejiang and Jiangsu provinces hosting certified high-temperature nylon capacity. Feedstock supply draws from caprolactam producers tethered to benzene derivative markets. Single-source vulnerability concentrates in halogen-free flame-retardant additive suppliers based in Germany and Japan. Distribution runs through electrical wholesalers WESCO and Graybar for construction volumes, with direct manufacturer engineering teams bypassing markup for hyperscale data center accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in REACH-compliant formulation tiers and specification-engineered direct sales channels, with cost compression available through captive resin recovery systems and regional sourcing adjustments.
For Market Incumbents: Lock in specification engineering relationships with hyperscale data center developers in Ashburn and Phoenix before construction documentation finalizes. Deepen backward integration into polymer compounding to secure ECHA compliance without sourcing disruption. Defend against stainless steel substitution threats by elevating flame-retardant nylon thermal ratings for renewable energy farm deployments.
For New Entrants and Emerging Players: Begin with Vietnam's Bac Ninh and Hai Phong electronics manufacturing zones, where import certification requirements create compliance barriers for uncertified competitors. Target high-temperature nylon demand from contract assembly operations serving export markets. Establish channel partnerships with regional distributors building warehousing capacity in northern industrial provinces.
For Investors and Strategic Acquirers: Consolidation pressure builds where aging polymer chemist workforces in Germany and Japan concentrate formulation expertise for halogen-free flame-retardant grades. Long-term viability favors compounders with captive resin operations and validated multi-jurisdiction certification pipelines. Monitor ECHA SVHC candidate list expansion velocity as inflection indicator for reformulation cost cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | HellermannTyton's captive resin operations sustain REACH compliance without Asian sourcing disruption. |
| Specification Engineering Program Expansion | Panduit embeds bundle management standards directly into Ashburn and Phoenix construction documents. |
| Halogen-Free Flame-Retardant Grade Development | Singapore and Ireland data center operators specify unified materials across climate zones. |
| Closed-Loop Manufacturing Investment | EPA volatile organic compound regulations reward compounders with scrap recovery systems. |
| Regional Warehousing in Southeast Asia | Northern Vietnam industrial provinces attract distributors serving electronics manufacturing clusters. |
Methodological Framework
Multiple input streams — primary interviews with polymer compounders, injection molding operations managers, and data center procurement leads; secondary validation through customs trade data, ECHA SVHC candidate list filings, and SEC 10-K disclosures from diversified industrial conglomerates — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations captured formulation expertise constraints, certification timeline pressures, and channel shift dynamics across electrical distribution networks.
Historical volume trajectories were cross-referenced against panel input from procurement directors at hyperscale operators and Tier 1 automotive suppliers. Segmentation dimensions modeled include material chemistry, tensile specification tier, end-use vertical, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and content-per-vehicle multiplication in electric vehicle architectures. Forecast inputs incorporated GB/T flame-retardant standard adoption curves and data center construction pipeline data from Virginia, Texas, and Ohio development authorities.
Several conditions sit outside the modeled scope, including sudden caprolactam price shocks, accelerated ECHA SVHC list expansion beyond historical review cycles, and trade policy shifts affecting Chinese injection molding exports. Practitioners should monitor REACH candidate list publication velocity and EPA enforcement patterns for closed-loop manufacturing compliance for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Insulated Wire and Cable Market
Cables
United States Cable Accessories Market
Cables
Europe Wire and Cable Market
Cables
Industrial Cable Reels Market
Cables
Cable Tray Market
Cables
Power Cable Accessories Market
Cables
Direct Attach Cable Market
Cables
North America Copper Wire and Cable Market
Cables
High Voltage Cables Market
Cables
Asia-Pacific Premise Cable Market
Cables
Global Low Voltage Cable Market
Cables
Electric Vehicle Unshielded HV Cables Market
Cables
Electric Submersible Cables (ESP) Market
Cables
South Africa Wire and Cable Market
Cables
Aluminium Battery Cable Market
Cables
Fire Resistance Cable Market