
 APAC Temperature Sensors Market | 2026-2036
APAC Temperature Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Temperature Sensors Market Outlook
Automotive electrification is consolidating demand across the APAC Temperature Sensors Market as battery thermal management systems displace conventional engine monitoring. Panasonic Holdings Corporation leverages its automotive-grade thermistor portfolio to anchor supply relationships with EV manufacturers across Japan and China. Denso Corporation competes through backward integration into ceramic sensing elements, sustaining margin control amid component cost volatility. Omron Corporation specializes in digital temperature transmitters for semiconductor fabrication, occupying a premium tier in cleanroom process control.
Temperature sensors are transducer devices that convert thermal energy into electrical signals, typically operating across ranges from -200°C to 1750°C depending on sensing element composition. Thermocouples generate voltage through the Seebeck effect at dissimilar metal junctions, serving heavy-industry process control where extreme thermal cycling tolerance outweighs precision requirements. RTDs dominate pharmaceutical and food safety applications where platinum-element stability delivers measurement repeatability within ±0.1°C. Infrared sensors are displacing contact methods in HVAC energy management, particularly across China's smart building retrofit programs where non-invasive surface temperature mapping reduces installation labor.
China's MIIT enforces GB standards for industrial IoT device interoperability, compelling sensor manufacturers to embed digital communication protocols that raise product development costs but lock out non-compliant imports. Japan's METI administers JIS certification for automotive thermal management components, creating a qualification barrier that favors established domestic suppliers. India's BIS mandates ISI marking for electrical equipment deployed in hazardous manufacturing environments, redirecting procurement toward certified vendors. Stakeholders must monitor divergence between China's SAMR-directed data localization requirements and ASEAN nations' emerging mutual recognition frameworks for test laboratory accreditations.
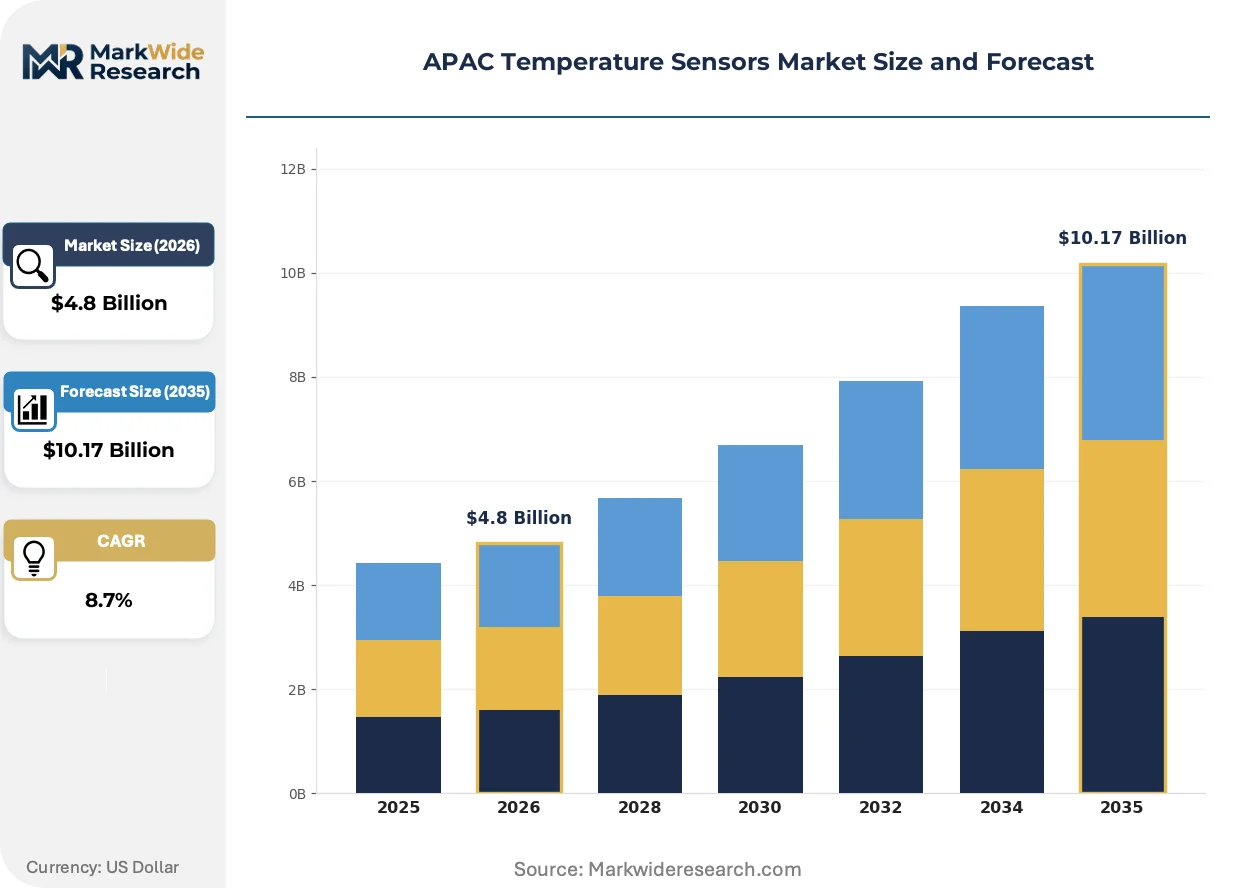
Market Dynamics
Automotive battery thermal management is consolidating procurement patterns across the APAC Temperature Sensors Market as EV platforms displace internal combustion architectures and demand precision sensing at cell-module and pack-level monitoring points.
Growth Catalysts
- China's GB Standards for Industrial IoT:MIIT-mandated digital protocol interoperability is compelling sensor manufacturers to embed Modbus and IO-Link communication stacks, expanding addressable applications in smart manufacturing infrastructure.
- Semiconductor Fabrication Expansion:Cleanroom process control requirements in Taiwan and South Korea are accelerating procurement of platinum RTD assemblies with ±0.1°C stability for wafer thermal mapping.
- India's PLI Scheme for Automotive:Production-linked incentives for EV component manufacturing are redirecting capital toward localized thermistor and thermocouple assembly capacity in Tamil Nadu and Gujarat industrial corridors.
Market Restraints
- Platinum Price Volatility:RTD element costs fluctuate with precious metal commodity markets, compressing margins for precision sensor manufacturers serving pharmaceutical validation applications.
- Japan Supply Concentration:Ceramic sensing element production clusters in Nagoya and Osaka prefectures create geographic single-point vulnerability for automotive-grade thermistor supply.
- Infrared Substitution Ceiling:Non-contact temperature measurement cannot achieve the ±0.05°C precision required for biopharma cold chain validation, limiting displacement of contact methods in regulated applications.
Strategic Opportunities
- Vietnam Electronics Manufacturing:Underpenetrated sensor assembly capacity in Bac Ninh and Hai Phong industrial zones offers first-mover positioning for suppliers qualifying under emerging ASEAN mutual recognition frameworks.
- Wireless Sensor Convergence:Integration of Bluetooth Low Energy transmitters with thermocouple transmitters is enabling retrofit deployment in legacy process plants without control wiring infrastructure.
- India's BIS Hazardous Environment Mandate:ISI marking requirements for electrical equipment in chemical processing are creating certified-vendor preference windows for flameproof RTD assembly specialists.
Industry Challenges
- Metrology Talent Scarcity:Calibration technician shortages in precision temperature measurement are extending lead times for ISO 17025-accredited sensor validation services.
- Multi-Standard Certification Burden:Divergent GB, JIS, and BIS testing protocols force redundant laboratory accreditation investments for pan-APAC sensor portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Temperature Sensors Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermocouples, RTDs, Thermistors, Infrared Sensors Technology: Wireless, Wired, Analog, Digital End User: Manufacturing, Automotive, HVAC, Healthcare Application: Process Control, Environmental Monitoring, Food Safety, Electronics |
| Companies Covered | Panasonic Holdings Corporation, Denso Corporation, Omron Corporation, Murata Manufacturing Co. Ltd., TDK Corporation, Yokogawa Electric Corporation, STMicroelectronics NV, TE Connectivity Ltd., Siemens AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Temperature Sensors Market Strategic Shifts
Digitalization of sensing elements and communication protocols is compressing the traditional transmitter-sensor value chain, while regulatory data-traceability mandates are reshaping product architecture requirements across industrial and automotive verticals.
Silicon-based integrated temperature sensors with on-chip ADC and digital output are electrifying the low-cost HVAC and appliance segments. Chinese white goods manufacturers in Guangdong and Zhejiang provinces are adopting these devices at scale for smart thermostat and inverter compressor control. This integration is electrifying margin compression in the sub-five-dollar sensor tier and forcing discrete thermistor suppliers toward higher-precision industrial applications.
Japan's METI JIS certification for automotive thermal management components is tightening qualification protocols for battery pack sensing assemblies. The regulation mandates accelerated thermal cycling validation and electromagnetic compatibility testing that extends product development timelines by eight to twelve months. Tier-1 automotive suppliers in Toyota City and Hiroshima prefectures are responding by consolidating vendor qualification lists to pre-certified domestic specialists.
Direct procurement from sensor manufacturers by EV platform engineering teams is displacing traditional distribution through industrial automation distributors. Battery OEMs in South Korea's Incheon cluster and China's Ningbo region are establishing technical specification relationships directly with thermistor and RTD designers. This pattern is most visible in high-volume platform contracts where annual call-off agreements exceed ten million units and technical integration support is bundled with supply agreements.
APAC Temperature Sensors Market Segmentation
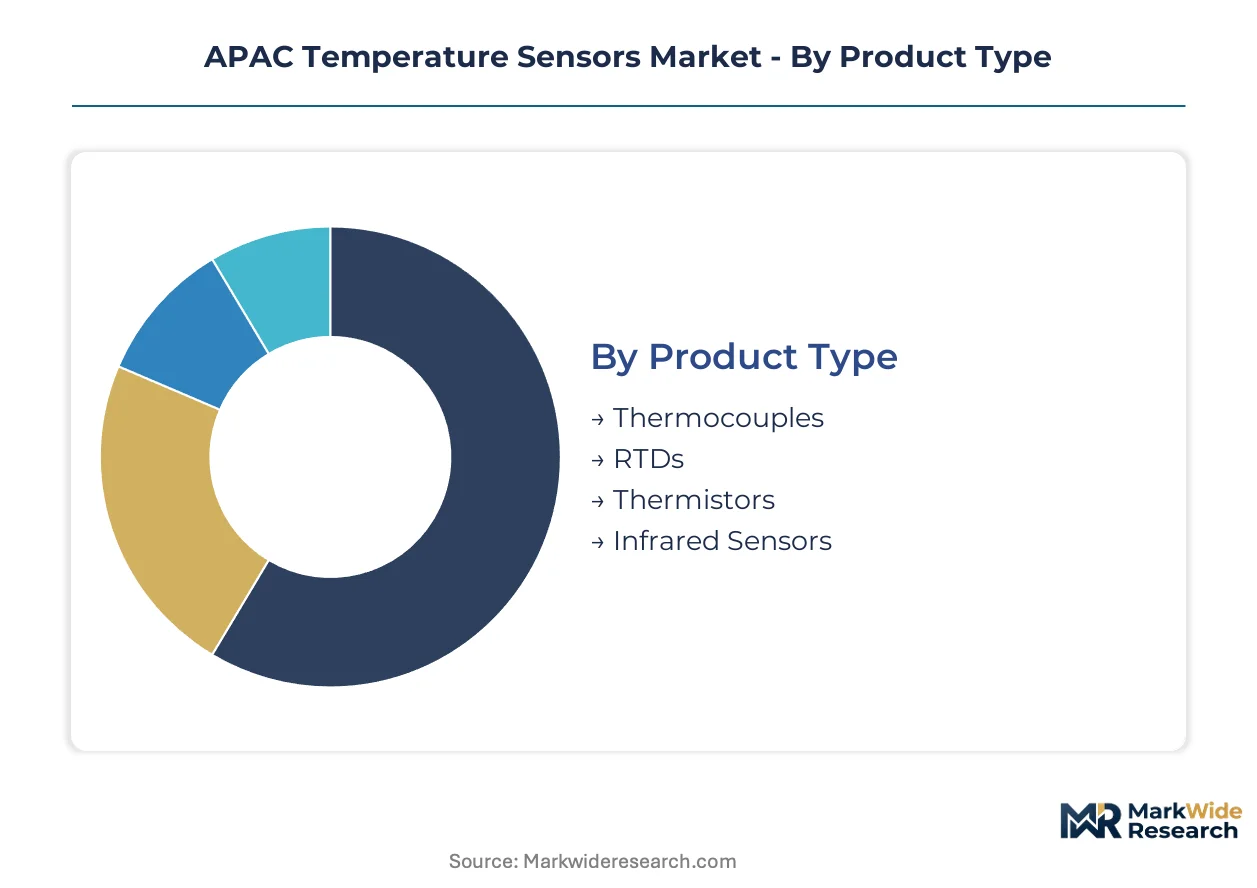
Segmentation in the APAC Temperature Sensors Market reveals how technical specifications and communication architectures align with distinct procurement budgets across Japan's automotive clusters, China's electronics corridors, and India's emerging industrial zones. Understanding these divisions exposes where standardization drives volume and where customization commands premium positioning.
Product Type:
Standardized thermocouple designs dominate commodity procurement, while platinum RTD assemblies require engineered-to-order configurations for pharmaceutical validation protocols.
- Thermocouples:These junction-based devices exploit the Seebeck effect across dissimilar metal pairings to generate millivolt signals proportional to temperature differentials. Demand concentrates in China's steel and petrochemical complexes along the Bohai Rim and Yangtze River Delta, where extreme thermal cycling tolerance outweighs absolute precision requirements in blast furnace and cracking unit monitoring.
- RTDs:Platinum-element resistance temperature detectors deliver measurement stability within ±0.1°C through pure metal resistive thermal response. Taiwan's semiconductor fabrication expansion and South Korea's display panel manufacturing are accelerating procurement of ceramic-sheathed RTD assemblies for wafer thermal mapping and vacuum chamber control.
- Thermistors:Ceramic oxide semiconductor elements exhibit steep resistance-temperature curves enabling high sensitivity in narrow ranges. Japan's automotive OEMs specify NTC thermistors for battery pack cell-level monitoring.
- Infrared Sensors:Non-contact thermal radiation detectors measure surface temperature through emitted infrared energy detection. China's smart building retrofit programs in Beijing and Shanghai are deploying pyrometers for HVAC energy optimization.
Leading the category by volume: Thermocouples. Expanding most quickly: RTDs.
Technology:
Cost tier stratification separates legacy analog outputs from digital protocol-embedded devices carrying 40-60% price premiums.
- Wireless:Bluetooth Low Energy and LoRa-enabled transmitters eliminate control wiring infrastructure in retrofit deployments. India's process plants in Gujarat are piloting wireless thermocouple networks to bypass conduit installation in aged facilities.
- Wired:4-20mA and thermocouple extension cable installations remain baseline for greenfield industrial automation. China's MIIT GB standards for industrial IoT are mandating wired digital protocols over pure analog outputs in new smart manufacturing infrastructure.
- Analog:Voltage and current loop outputs persist in cost-sensitive appliance and white goods applications. Guangdong province manufacturers specify analog thermistors for refrigerator compressor protection.
- Digital:IO-Link and Modbus-embedded sensors enable direct PLC integration with diagnostic data transmission. Japan's METI JIS certification for automotive thermal management is requiring digital output validation for battery pack sensing assemblies.
Highest volume share: Wired. Steepest expansion trajectory: Digital.
End User:
Application maturity determines whether procurement favors catalog-standard devices or application-engineered assemblies with extended qualification cycles.
- Manufacturing:Process control applications in chemical, steel, and cement production demand ruggedized thermocouple and RTD configurations with thermowells and head-mounted transmitters. China's Yangtze River Delta electronics manufacturing cluster consumes precision sensors for SMT reflow oven profiling.
- Automotive:Battery thermal management systems require automotive-grade thermistors with accelerated thermal cycling validation per Japan's METI JIS protocols. South Korea's Incheon battery OEMs are establishing direct technical relationships with sensor designers for platform-specific cell-module monitoring.
- HVAC:Building automation systems prioritize cost-optimized silicon integrated sensors and infrared surface measurement for energy management. China's northern district heating retrofits are scaling infrared deployment for radiator flow balancing.
- Healthcare:Cold chain validation and sterilization equipment demand ISO 17025-traceable RTD accuracy within ±0.05°C. India's pharmaceutical manufacturing in Hyderabad and Mumbai is tightening procurement specifications for warehouse temperature mapping.
Dominant procurement volume: Manufacturing. Gaining share fastest: Automotive.
Application:
Regulatory intensity separates food safety and pharmaceutical applications with mandatory calibration traceability from electronics manufacturing where speed-to-qualification drives supplier selection.
- Process Control:Closed-loop industrial automation requires real-time temperature feedback for reactor, furnace, and extruder regulation. China's petrochemical complexes along the Fujian coast specify duplex thermocouples with redundant measurement paths.
- Environmental Monitoring:Ambient and stack emission measurement applications favor infrared and thermistor-based weather stations. Japan's metropolitan air quality networks deploy platinum RTD aspirated shields for urban heat island tracking.
- Food Safety:HACCP-compliant cold chain and thermal processing operations mandate calibrated probe assemblies with data logging. India's FSSAI enforcement is tightening temperature monitoring requirements for dairy processing cooperatives in Gujarat and Maharashtra.
- Electronics:Semiconductor wafer processing and PCB assembly require ultra-stable platinum RTDs for thermal uniformity control. Taiwan's TSMC-led foundry expansion is concentrating demand for ceramic-sheathed sensors with sub-0.1°C stability.
Largest application segment: Process Control. Climbing the fastest: Electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of APAC temperature sensors while Japan and South Korea consume the most advanced automotive and semiconductor-grade variants. Domestic production capacity in India and Vietnam is expanding to serve localized electrification and industrial automation programs.
China
MIIT-mandated GB standards for industrial IoT interoperability are compelling sensor manufacturers to embed Modbus and IO-Link communication stacks in new devices. The Yangtze River Delta electronics manufacturing cluster dominates procurement volumes for SMT reflow oven profiling and semiconductor process control applications.
Japan
METI-administered JIS certification for automotive thermal management components creates qualification barriers favoring established domestic suppliers. Nagoya and Osaka prefectures concentrate ceramic sensing element production for battery pack thermistors serving Toyota and Honda electrification platforms.
South Korea
Incheon battery OEMs are establishing direct technical specification relationships with thermistor designers for platform-specific cell-module monitoring. The country's national semiconductor regulator enforces cleanroom-grade calibration protocols for wafer fabrication RTD assemblies.
India
BIS mandates ISI marking for electrical equipment in hazardous manufacturing environments, redirecting procurement toward certified vendors. Tamil Nadu and Gujarat industrial corridors are attracting thermistor and thermocouple assembly investments under the PLI scheme for automotive components.
Vietnam
Underpenetrated sensor assembly capacity in Bac Ninh and Hai Phong industrial zones offers first-mover positioning for suppliers. Emerging ASEAN mutual recognition frameworks for test laboratory accreditations are reducing certification duplication for entrants.
APAC Temperature Sensors Market Competitive Environment
Top-tier vendors anchor premium automotive and semiconductor-grade supply, while mid-tier specialists compete on certification breadth and regional manufacturing proximity. The vendor base stratifies across three tiers: multinational component conglomerates with backward integration into ceramic sensing elements; regional specialists with JIS, GB, or BIS certification depth; and emerging assemblers in Vietnam and India leveraging cost-positioned labor. Dominant competitive moves include geographic expansion into underpenetrated ASEAN manufacturing zones and portfolio diversification from analog thermistors toward digital protocol-embedded transmitters.
Within the multinational tier, Panasonic Holdings Corporation and Denso Corporation exemplify integrated supply chain control through captive ceramic element production. Omron Corporation occupies a position emphasizing digital temperature transmitters for precision process control. These three Japanese entities anchor the premium-tier competitive vector, representing archetypes of certification-locked, vertically integrated, and application-specialized positioning respectively.
| Leading Market Players |
|---|
| Panasonic Holdings Corporation |
| Denso Corporation |
| Omron Corporation |
| Murata Manufacturing Co. Ltd. |
| TDK Corporation |
| Yokogawa Electric Corporation |
| STMicroelectronics NV |
| TE Connectivity Ltd. |
| Siemens AG |
| Others |
Value Chain & Pricing Dynamics
China's MIIT dual carbon goals for industrial energy efficiency gate qualified supply and premium-tier pricing access, compelling sensor manufacturers to embed certified digital protocols that raise development costs while locking out uncertified competitors from high-margin procurement channels.
Pricing Analysis
Margin tightening in the sub-five-dollar sensor tier reflects silicon integrated sensor electrification by Guangdong white goods manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified automotive assemblies from industrial-grade wired transmitters and commodity analog thermistors. Cost-down pressure on platinum RTD assemblies accelerates because precious metal commodity volatility compresses margins for pharmaceutical validation applications. HVAC and appliance OEMs exhibit highest price sensitivity, while semiconductor fabs accept premium positioning for ±0.1°C stability.
Supply Chain Analysis
Platinum element supply rests on South African and Russian mining operations, while ceramic oxide powders for thermistors concentrate in Japanese Nagoya and Osaka prefectures. Ceramic sensing element fabrication, platinum wire drawing, and semiconductor-grade packaging materials constitute critical input dependencies. Single-source vulnerability in Japanese ceramic element production creates geographic concentration risk for automotive-grade thermistor supply. Distribution runs through direct technical relationships between EV battery OEMs and sensor designers, displacing traditional industrial automation distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over ceramic sensing element production anchors margin defense against silicon-based substitution and commodity cost volatility.
For Market Incumbents: Deploy backward integration into ceramic oxide powder processing to defend against platinum price volatility and silicon sensor displacement in HVAC tiers. Consolidate vendor qualification relationships with Incheon and Ningbo battery OEMs through bundled technical integration support. Lock in JIS certification renewal cycles ahead of METI protocol tightening to extend qualification barriers for emerging competitors. For New Entrants and Emerging Players: India's BIS ISI marking mandate for hazardous environment electrical equipment opens a window for flameproof RTD assembly specialists to capture certified-vendor preference windows in Gujarat chemical processing corridors. Target Vietnam's Bac Ninh and Hai Phong industrial zones where underpenetrated sensor assembly capacity meets emerging ASEAN mutual recognition frameworks. Pursue wireless thermocouple retrofit pilots in India's aged Gujarat process plants as a beachhead for LoRa-enabled transmitter qualification. For Investors and Strategic Acquirers: Direct procurement pattern establishment by EV platform engineering teams is the leading indicator that technical specification relationships are displacing distribution-channel dependency as the value-capture mechanism. Focus acquisition screening on mid-tier specialists with depth in GB, JIS, or BIS certification portfolios rather than pure cost-positioned assemblers. Monitor divergence between China's SAMR data localization requirements and ASEAN mutual recognition framework progress as the signal for regional supply chain reconfiguration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Sensing Elements | Captive supply of oxide powders insulates margin from commodity volatility and Japanese supply concentration. |
| Digital Protocol Certification Investment | MIIT-mandated Modbus and IO-Link stacks unlock smart manufacturing infrastructure procurement in Yangtze Delta clusters. |
| Direct OEM Technical Relationship Development | Bypassing distributors captures high-volume platform contracts with Incheon and Ningbo battery manufacturers. |
| Wireless Sensor Platform Launch | Bluetooth Low Energy and LoRa retrofit deployment addresses India's aged process plant infrastructure gaps. |
| ASEAN Manufacturing Footprint Expansion | Bac Ninh and Hai Phong positioning leverages emerging mutual recognition frameworks for test laboratory accreditations. |
Study Parameters
Multi-period observation of MIIT GB standard implementation timelines, METI JIS certification protocol evolution, and BIS ISI marking enforcement patterns anchored the trend analysis, supplemented by interviews with ceramic sensing element procurement managers, automotive Tier 1 supplier quality engineers, semiconductor fab facilities managers, and industrial automation distributor technical sales leads. Secondary validation drew from MIIT policy circulars, METI technical standard updates, BIS certification registries, and customs trade data for temperature sensor component flows. Bottom-up sensor shipment estimates by product type and technology tier triangulated against top-down industrial automation capital expenditure tracking.
Segment-weighting across product type, technology, end user, and application dimensions calibrated volume and value distributions, with additional weighting for regional regulatory cluster intensity. CAGRs were derived from fitted growth curves against historical procurement pattern shifts, incorporating semiconductor fabrication capacity expansion schedules, EV platform production ramp timelines, and smart building retrofit program commitments as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for silicon integrated sensor displacement of discrete thermistors would alter the outlook for sub-five-dollar tier pricing and supplier viability. Forecasts reflect assumptions regarding sustained MIIT enforcement of digital protocol mandates and continued METI JIS certification tightening. Platinum commodity price trajectories, ASEAN mutual recognition framework ratification velocity, and metrology technician training pipeline expansion constitute a small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
North America Occupancy Sensors Market
Sensors and Controls
Smart Glove Market
Sensors and Controls
Laser Displacement Sensor Market
Sensors and Controls
Photoelectric Sensor Market
Sensors and Controls
Factory Automation Sensor Market
Sensors and Controls
Global Acoustic Wave Sensor Market
Sensors and Controls
Phototransistor Market
Sensors and Controls
Shutter Sensors Market
Sensors and Controls
Advanced Carbon Dioxide (CO2) Sensors Market
Sensors and Controls
Magnetometer Sensor Market
Sensors and Controls
Latin America Occupancy Sensors Market
Sensors and Controls
Tooth Mounted Sensor Market
Sensors and Controls
MEMS Gyroscope Market
Sensors and Controls
High-Performance IMU Market
Sensors and Controls
Torque Sensor Market
Sensors and Controls
Middle East Robotic Sensors Market