
 Insulated Wire and Cable Market | 2026-2036
Insulated Wire and Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Wire and Cable Market Intelligence
The EU Green Deal is pivoting procurement criteria across European utilities toward halogen-free, low-smoke insulation systems. Prysmian Group leverages its submarine cable manufacturing scale to dominate high-voltage interconnector projects between national grids. Nexans sustains competitive positioning through vertical integration into compound formulation and copper rod production. Sumitomo Electric Industries specializes in superconducting and high-temperature cable architectures for compact urban substations.
Insulated wire and cable comprises electrically conductive cores sheathed in dielectric materials—typically PVC, XLPE, or rubber compounds rated for specific thermal and voltage withstand thresholds—manufactured through extrusion, taping, or sintering processes to prevent short-circuit, ground-fault, and fire propagation in power distribution and signal transmission networks. Low voltage products occupy the largest revenue pool due to ubiquitous building wire replacement cycles, while high voltage and specialty wire segments capture disproportionate margin contributions from subsea, renewable interconnection, and data center applications. XLPE insulation is displacing PVC in medium and high voltage ratings because of superior thermal aging resistance and reduced dielectric losses.
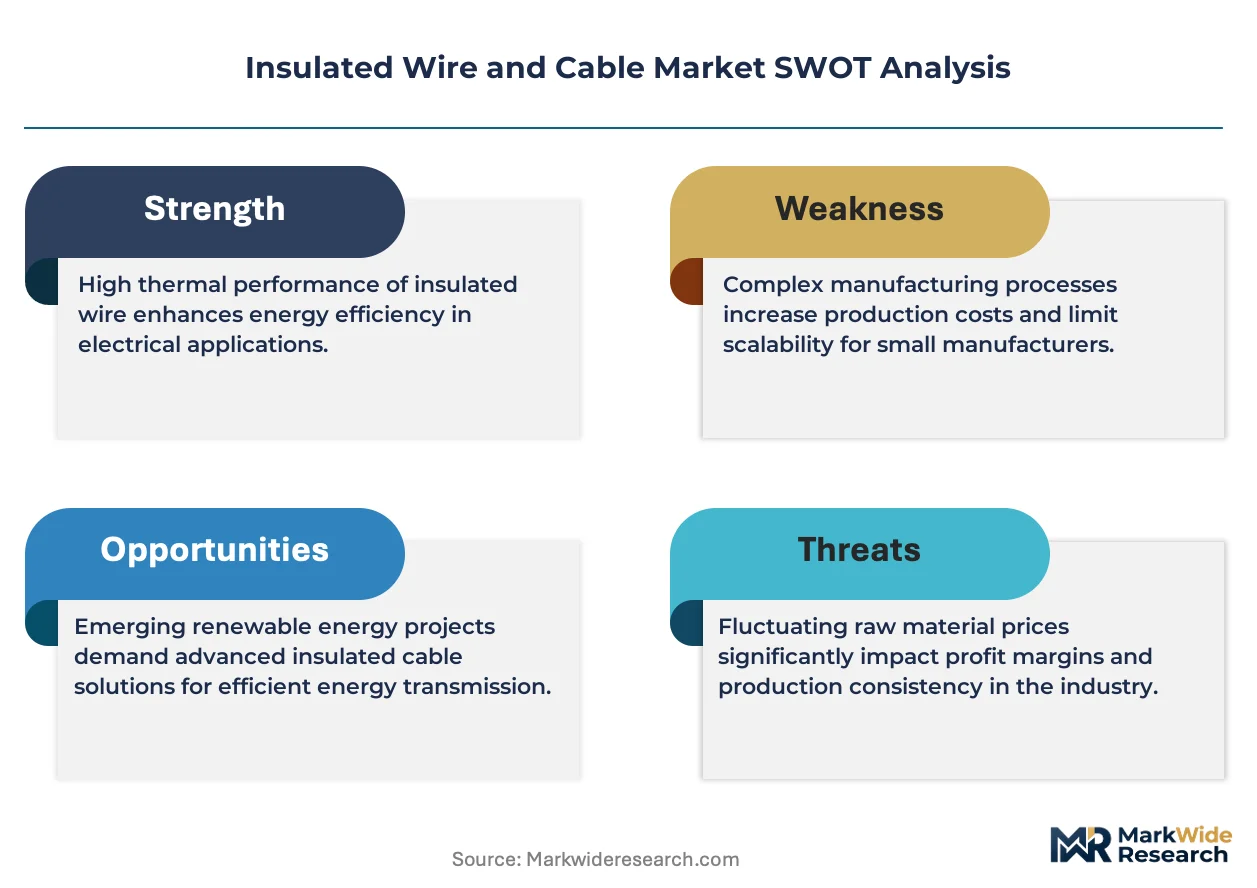
FDA oversight of fluoropolymer insulation in medical device cabling, EPA restrictions on halogenated flame retardants, and REACH compliance obligations for plasticizer and stabilizer chemistries collectively elevate formulation costs and favor suppliers with in-house regulatory affairs capabilities. The EU F-Gas Regulation and corresponding national implementation laws in Germany and France are accelerating transition toward blowing-agent-free insulation foaming technologies. Stakeholders must monitor evolving material compliance thresholds and grid code harmonization across multiple jurisdictions to preserve market access and avoid stranded inventory positions.
Market Dynamics
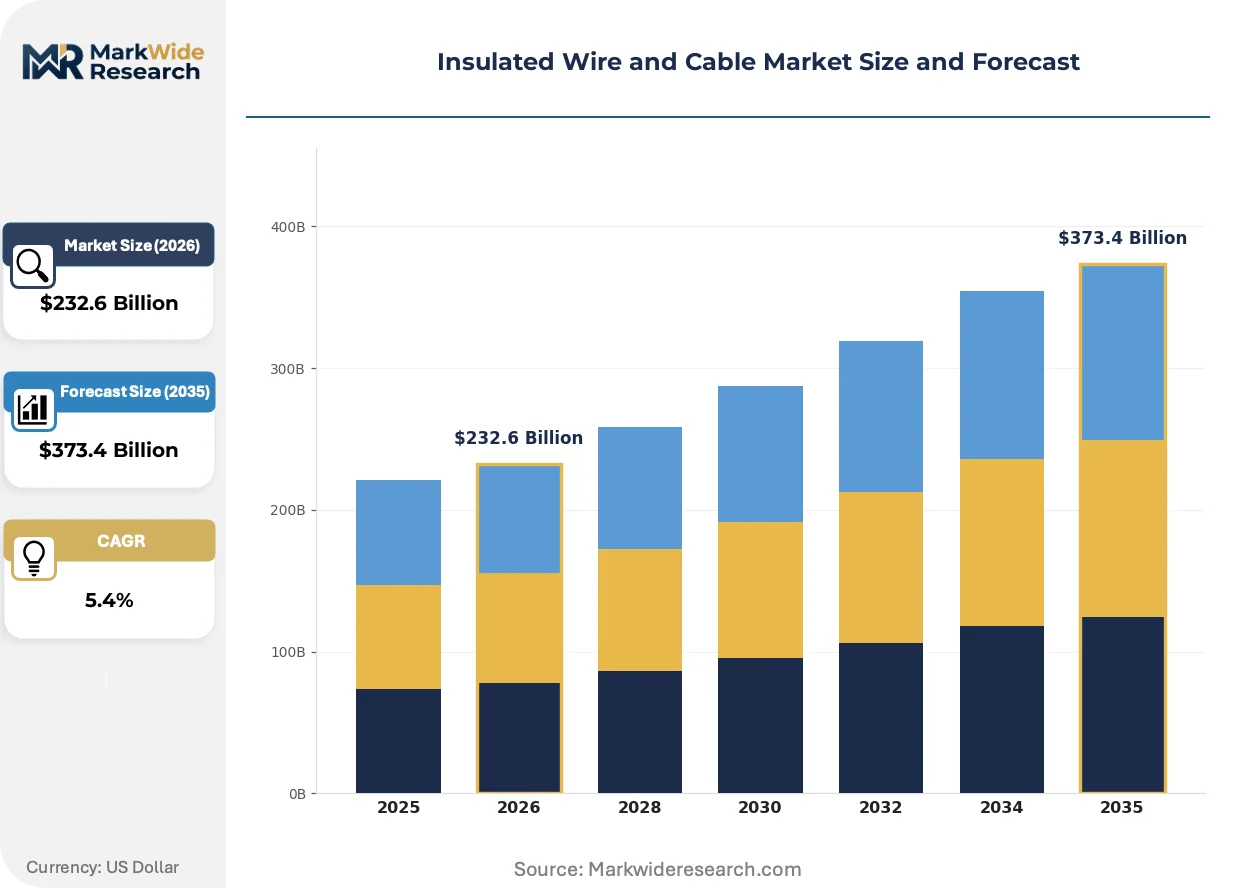
Grid modernization mandates and offshore wind interconnection buildouts are compressing procurement timelines for high-voltage transmission infrastructure, forcing cable manufacturers to prioritize compound formulation agility and extrusion capacity expansion over margin protection.
Growth Catalysts
- EU Green Deal electrification mandates:Germany, France, and Italy now require halogen-free insulation compounds in public infrastructure projects, redirecting utility procurement toward low-smoke zero-halogen formulations.
- Offshore wind transmission buildouts:China's coastal provinces are absorbing specialty subsea cable volumes through state grid modernization programs targeting inter-island and inter-provincial links.
- XLPE thermal aging superiority:Renewable developers specify cross-linked polyethylene for medium and high voltage ratings due to reduced dielectric losses and extended service life under cyclic loading.
Market Restraints
- Copper price volatility:Conductive core material swings compress margin visibility for manufacturers without captive smelter arrangements or long-term concentrate offtakes.
- REACH plasticizer compliance:ECHA restrictions on phthalate and stabilizer chemistries elevate reformulation costs and disqualify legacy compound inventories from EU market access.
- Subsea installation vessel scarcity:Specialized cable-laying fleet concentration in Nordic yards creates bottleneck risk for interconnector project schedules.
Strategic Opportunities
- Superconducting urban substations:High-temperature superconductor cable architectures enable compact footprint designs for dense metropolitan load centers in Japan and South Korea.
- Data center liquid cooling integration:Specialty power distribution cabling for immersion-cooled server racks represents underpenetrated specification channel in hyperscale builds.
- US Inflation Reduction Act domestic content:Tax credit localization requirements create procurement preference for North American-sourced insulation compounds and copper rod.
Industry Challenges
- Compound formulation chemist scarcity:Specialized expertise in halogen-free flame retardant systems commands premium compensation and extends R&D cycle timelines.
- Type approval harmonization gaps:Divergent grid code certification requirements between Germany's KBA-adjacent utility standards and France's national transmission operator specifications strand engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Wire and Cable Market |
| Market Size in 2026 | $232.6 Billion |
| Market Size in 2035 | $373.4 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Voltage, Medium Voltage, High Voltage, Specialty Wire Material: PVC, XLPE, Rubber, Fiberglass End User: Construction, Automotive, Telecommunications, Consumer Electronics Installation Type: Indoor, Outdoor, Underground, Aerial |
| Companies Covered | Fujikura Ltd, DowDuPont, Prysmian Group, Hitachi Cable, Borealis AG, Nexans, Southwire Company, TPC Wire & Cable Corp., Sumitomo Electric Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Wire and Cable Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry restrictions are converging to redefine insulation compound specifications, while procurement centralization among renewable developers compresses supplier qualification timelines.
Cross-linked polyethylene (XLPE) is integrating into medium and high voltage cable architectures as the dominant dielectric material. Offshore wind developers and national grid operators specify XLPE for its superior thermal aging resistance under cyclic renewable generation profiles. This material transition is integrating compact transmission designs that reduce right-of-way requirements for congested coastal corridors.
EPA restrictions on halogenated flame retardants are forcing reformulation of PVC-based building wire insulation compounds. US wire and cable manufacturers face compliance-driven R&D redirection toward phosphorus-nitrogen intumescent systems. Residential and commercial construction segments absorb cost pass-throughs while awaiting UL certification timeline clarity on alternative chemistries.
Renewable energy procurement centralization is consolidating buyer power among European and Chinese offshore wind developers. Engineering-procurement-construction contractors now bundle cable specification authority with turbine supply agreements, displacing traditional utility-driven material selection. This concentration is most visible in the North Sea basin, where TenneT and Ørsted procurement frameworks set compound standards across supplier bases.
Insulated Wire and Cable Market Segmentation
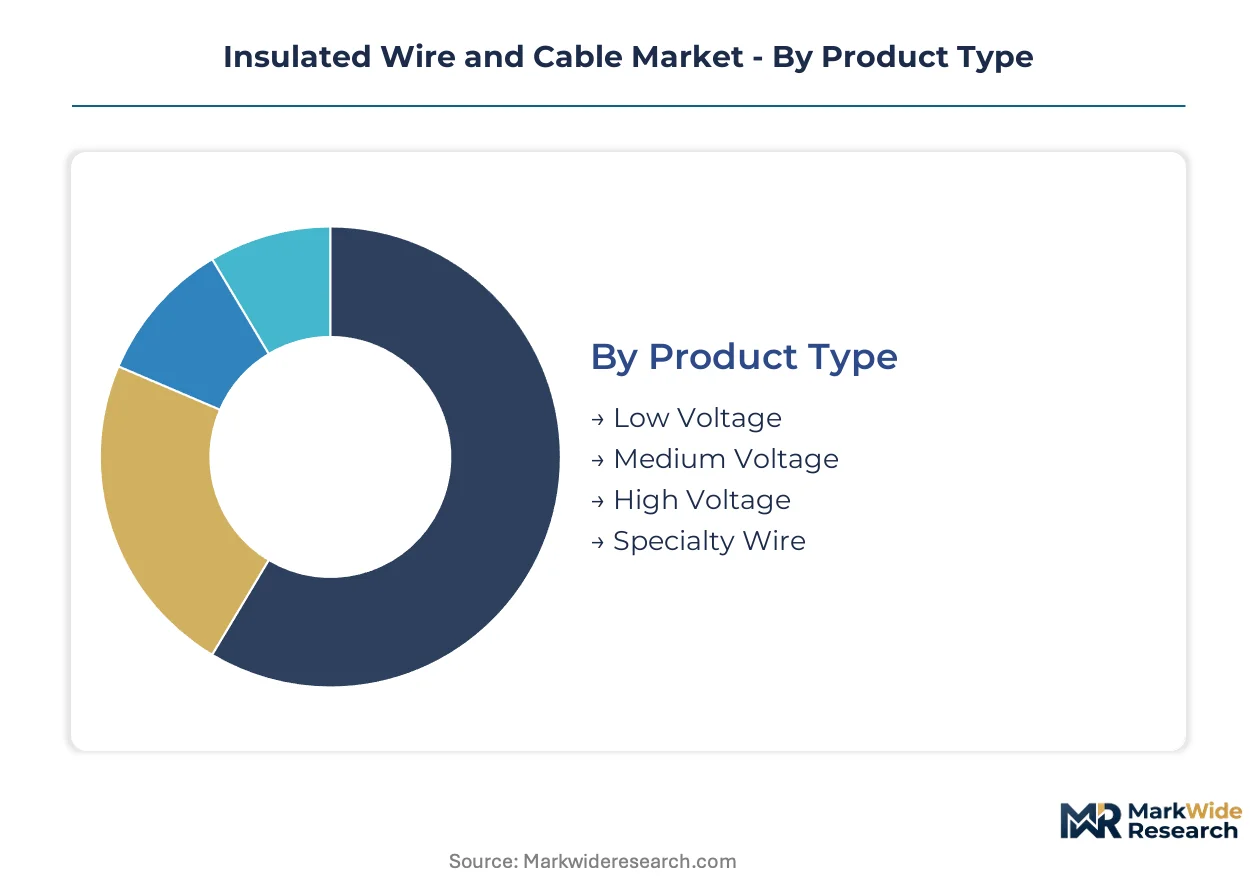
Segmentation in insulated wire and cable reveals divergent capital requirements across voltage classes and material systems. Procurement patterns concentrate where grid modernization intersects with regulatory chemistry transitions.
Product Type:
Capital intensity escalates sharply with voltage rating due to extrusion precision requirements and testing infrastructure. High voltage submarine cable plants demand billion-dollar fabrication facilities with vertical curing towers and cleanroom environments.
- Low Voltage:Building wire and appliance cabling utilize standard extrusion lines with modest tooling investment. Construction retrofit cycles in Germany and France absorb volumes as EU Green Deal mandates accelerate halogen-free compound transitions.
- Medium Voltage:Distribution grid cables rated 1kV to 35kV require cross-linking autoclaves and partial discharge testing bays. China's coastal provinces concentrate procurement through state grid distribution network expansions.
- High Voltage:Extruded XLPE submarine and land cables for transmission corridors demand the heaviest capital deployment. Interconnector projects between national grids in Europe require dedicated vessel partnerships and offshore installation capabilities.
- Specialty Wire:Superconducting, fire-resistant, and data center cabling segments command premium formulation expertise. Medical device and aerospace applications specify fluoropolymer and silicone insulation under FDA and EASA oversight.
Low voltage absorbs the bulk of installed capacity; high voltage is expanding most quickly.
Material:
Compound selection determines thermal performance ceilings and regulatory compliance pathways across end-use applications.
- PVC:Polyvinyl chloride dominates building wire economics through low base resin cost and established extrusion infrastructure. EPA restrictions on halogenated flame retardants are forcing phosphorus-nitrogen reformulation investments in US residential construction.
- XLPE:Cross-linked polyethylene offers superior dielectric strength and thermal aging resistance for medium and high voltage ratings. Offshore wind developers in the North Sea basin specify XLPE for cyclic loading endurance under variable renewable generation.
- Rubber:Ethylene-propylene and silicone rubber compounds deliver flexibility and abrasion resistance for mobile equipment and harsh environments. Mining and marine applications in Norway and Australia specify heavy-duty rubber sheathing.
- Fiberglass:High-temperature braided insulation withstands extreme thermal excursions in furnace wiring and aerospace harnesses. Industrial process equipment in Japan and South Korea drives specification for 450°C continuous service ratings.
PVC retains volume leadership in building wire; XLPE climbs the fastest on renewable interconnection demand.
End User:
Customer concentration varies sharply, with utility procurement centralization contrasting fragmented construction distribution.
- Construction:Residential, commercial, and infrastructure building wire moves through electrical distributor channels with high SKU fragmentation. German and French public infrastructure mandates now require low-smoke zero-halogen formulations for tunnel and hospital installations.
- Automotive:EV powertrain and charging infrastructure cabling demands high-flexibility silicone and XLPE insulation. Battery pack manufacturers specify shielded high-voltage harnesses under UN ECE R100 safety protocols.
- Telecommunications:Fiber optic and copper data transmission cables require precision dielectric control for signal integrity. Subsea fiber projects linking Japan to Southeast Asia absorb specialty cable-laying capacity.
- Consumer Electronics:Miniature coaxial and ribbon cables for devices and appliances operate at thin-margin, high-volume economics. USB-C and wireless charging coil specifications drive micro-cable form factor evolution.
Construction channels the largest material tonnage; automotive gains share fastest on electrification.
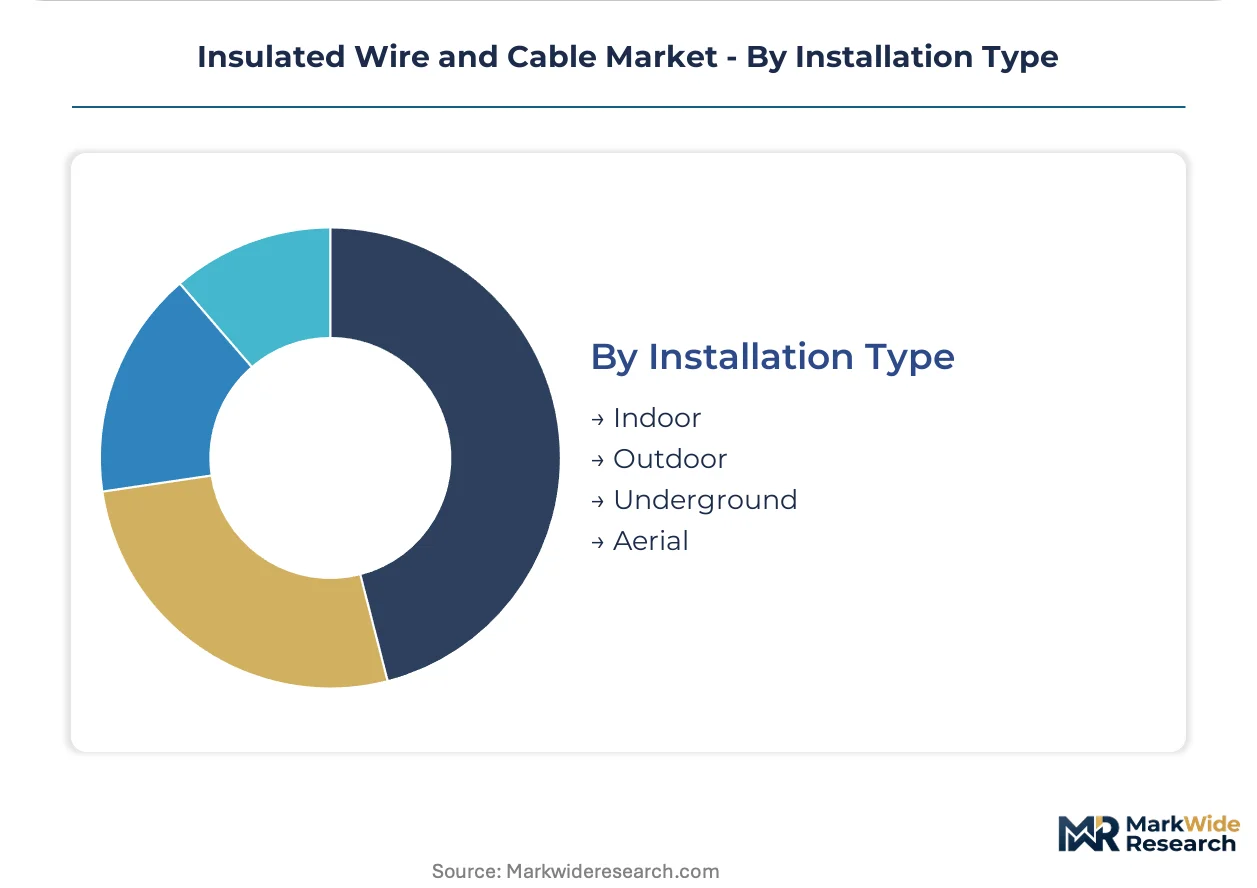
Installation Type:
Deployment environment dictates mechanical protection requirements and regulatory certification complexity.
- Indoor:Plenum and riser-rated cables for commercial buildings carry stringent smoke density and flame spread requirements. NFPA 262 and EN 50575 testing protocols govern conduit and tray installations.
- Outdoor:UV-resistant polyethylene jackets and water-blocking tapes protect aerial and exposed runs. Utility pole attachments in Italy and Spain face avian collision and wildfire ignition regulations.
- Underground:Direct-burial and duct-bank cables require crush-resistant armor and moisture barriers. Urban congestion in London and Paris drives preference for underground routing over aerial alternatives.
- Aerial:Messenger-supported and self-supporting designs span challenging terrain with reduced civil works. Norwegian fjord crossings and Scottish island links exploit aerial deployment economics.
Underground commands the dominant share of new transmission investment; aerial maintains niche applicability in rugged terrain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Yangshan Deep Water Port anchors the heaviest subsea cable manufacturing concentration, with state grid procurement absorbing specialty volumes for offshore wind interconnection buildouts.
China
State Grid Corporation's coastal modernization programs drive specialty cable procurement across Jiangsu and Fujian provinces. MIIT's dual carbon goals accelerate XLPE specification for renewable interconnection projects. Qingdao and Ningbo industrial clusters host extrusion facilities serving inter-island transmission corridors.
Germany
Offshore wind developers in the North Sea basin compress procurement timelines for high-voltage interconnectors. KBA-adjacent utility standards and EU Green Deal mandates enforce halogen-free compound requirements. Hamburg and Bremen port infrastructure supports cable-laying vessel mobilization for grid link projects.
United States
Data center buildouts in Northern Virginia and Texas absorb premium power distribution cabling volumes. EPA restrictions on halogenated flame retardants force phosphorus-nitrogen reformulation investments. Southwire's Georgia operations and regional distributors serve construction retrofit cycles under IRA domestic content incentives.
Japan
Superconducting cable architectures address compact urban substation constraints in Tokyo and Osaka metropolitan load centers. METI's grid resilience programs fund high-temperature conductor demonstrations. Yokohama industrial corridors concentrate precision extrusion capacity for specialty wire exports.
France
National transmission operator specifications diverge from neighboring grid codes, stranding engineering resources in certification harmonization gaps. ECHA REACH compliance elevates reformulation costs for plasticizer-dependent compounds. Marseille and Le Havre ports maintain subsea cable storage and splice facilities for Mediterranean interconnectors.
Insulated Wire and Cable Market Key Industry Players
The competitive structure tilts toward vertically integrated compound specialists with captive polymer formulation capabilities. Tier-one manufacturers command submarine cable fabrication through billion-dollar cleanroom facilities, while mid-scale players compete on construction wire agility and distributor channel density. Two dominant competitive moves define current positioning: extrusion capacity expansion in coastal industrial zones, and backward integration into copper rod production to buffer conductive core volatility.
Among diversified industrial conglomerates, Prysmian Group and Sumitomo Electric Industries exemplify scale-driven archetypes with integrated submarine manufacturing footprints. Nexans occupies a position within the compound-specialist tier, leveraging in-house formulation expertise to meet EU Green Deal halogen-free mandates. Fujikura Ltd anchors the precision-specialist vector, with Japanese headquarters signaling concentrated R&D allocation toward high-performance dielectric systems.
| Leading Market Players |
|---|
| Fujikura Ltd |
| DowDuPont |
| Prysmian Group |
| Hitachi Cable |
| Borealis AG |
| Nexans |
| Southwire Company |
| TPC Wire & Cable Corp. |
| Sumitomo Electric Industries |
| Others |
Cost & Logistics Intelligence
Sovereign-backed producers in China and family-owned mid-caps across Germany and Italy anchor supply concentration, translating captive copper rod capacity into pricing discipline that resists spot-market volatility while compressing margins for distributors without backward integration.
Pricing Analysis
Outcome-based pricing anchored to grid uptime performance governs high-voltage interconnector contracts, where transmission operators specify availability guarantees above material cost-plus baselines. Three-tier pricing structure across premium XLPE submarine cables, standard medium-voltage distribution lines, and economy PVC building wire reflects certification grade and volume scale differentiation. Cost compression in low-voltage residential construction intensifies because EPA-driven reformulation investments in phosphorus-nitrogen flame retardants cannot pass fully to price-sensitive homebuilder procurement. Data center developers exhibit least price sensitivity, prioritizing thermal performance and fire-safety ratings over unit economics.
Supply Chain Analysis
Compound formulation chemist scarcity in Shanghai's Yangshan corridor and Hamburg's industrial belt constrains extrusion capacity expansion timelines. Manufacturing gravity centers on China, Germany, and the United States, with raw material sourcing drawing from Chilean copper concentrate, Saudi petrochemical feedstocks, and Belgian specialty additive suppliers. Single-source vulnerability in Nordic cable-laying vessel fleets threatens interconnector project schedules. Distribution runs through electrical distributor networks for construction wire and direct EPC contractor relationships for transmission infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive copper smelting and in-house compound formulation determine margin survival against raw material volatility and regulatory chemistry transitions.
For Market Incumbents: To counter copper price volatility eroding margin visibility, Prysmian and Nexans prioritize backward integration into copper rod production and captive polymer formulation facilities. Certification investment in EU Green Deal halogen-free standards preserves utility procurement access against disqualification risk from REACH plasticizer restrictions. Channel control through EPC contractor partnerships secures specification authority in bundled offshore wind procurement.
For New Entrants and Emerging Players: E-commerce distributor platforms targeting electrical contractor procurement represent the most penetrable white-space channel for mid-scale manufacturers lacking vessel partnerships. Specialty data center liquid-cooled rack cabling offers underdefended specification territory against incumbent focus on submarine transmission. Direct-to-contractor digital sales bypass traditional distributor markups while building brand recognition for premium thermal performance claims.
For Investors and Strategic Acquirers: Distressed-cycle entries favor compound-specialist mid-caps with MIIT dual carbon compliance and Qingdao manufacturing footprints during Chinese state grid procurement pauses. Long-term viability hinges on regulatory chemistry adaptation capacity rather than scale alone. Watch ECHA plasticizer restriction enforcement timelines as inflection indicator for stranded inventory risk and reformulation capex requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Rod | Captive smelting buffers conductive core volatility for Prysmian and Nexans margin stability. |
| Halogen-Free Compound Certification | EU Green Deal compliance secures German and French utility procurement access against REACH disqualification. |
| Submarine Vessel Partnership | Dedicated cable-laying fleet access de-risks North Sea interconnector schedule compression. |
| Superconducting Cable R&D | High-temperature architectures address Tokyo and Osaka urban substation footprint constraints. |
| Data Center Liquid Cooling Integration | Immersion-cooled rack cabling captures hyperscale build specification in Northern Virginia and Texas. |
Research Approach
Independent corroboration across cable manufacturer technical directors, EPC contractor procurement leads, and electrical distributor category managers underwrites the qualitative findings. Primary fieldwork engaged compound formulation chemists, grid operator planning officers, and regulatory affairs specialists across China, Germany, and the United States. Secondary validation drew from MIIT dual carbon policy documents, ECHA REACH restriction registers, SEC 10-K disclosures, and customs trade data for copper concentrate flows. Bottom-up segment sizing and top-down macroeconomic cross-checks established analytical triangulation.
Rate-of-change decomposition across voltage class, material system, end-use application, and installation environment structures the projection framework. The analysis window spans from base-year market sizing through the forecast horizon. Segmentation dimensions modeled include low-medium-high voltage tiers, PVC-XLPE-rubber compound categories, construction-automotive-telecommunications end-use splits, and indoor-outdoor-underground-aerial deployment types. CAGRs derive from elasticity-adjusted demand drivers and capacity expansion schedules. Forecast inputs incorporate offshore wind interconnection pipelines, data center power density trends, and regulatory chemistry transition timelines.
The model holds under stable copper price corridors and consistent EU-China regulatory enforcement; deviation in ECHA plasticizer restriction acceleration or Nordic vessel fleet availability would shift volume and value trajectories. Forecasts reflect documented assumptions regarding grid modernization spend, renewable interconnection buildout rates, and compound reformulation capex recovery. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Testing Market
Cables
North America Wire and Cable Market
Cables
High Voltage Cables Market
Cables
Submarine Optical Fiber Cables Market
Cables
Cable Testing and Certification Market
Cables
Industrial Cable Reels Market
Cables
Cable Carrier Market
Cables
Class 1E Electric Cables Market
Cables
Copper Cable Market
Cables
Electric Vehicle Cables Market
Cables
Cable Drum Market
Cables
HVDC Cables Market
Cables
Cable Market
Cables
Wire and Cable Label Market
Cables
Global Cable Blowing Equipment Market
Cables
Copper Stranded Wire Market