
 Premise Cable Market | 2026-2036
Premise Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Premise Cable Market Intelligence
Data center infrastructure buildouts is broadening the end-use vertical mix for premise cable suppliers. Belden Inc. specializes in industrial-grade copper and fiber solutions for mission-critical environments. Prysmian Group leverages its global manufacturing footprint to serve large-scale telecommunications and building projects. Nexans S.A. competes through advanced fire-resistant cable portfolios aligned with evolving safety codes.
Premise cable denotes structured cabling deployed within buildings and campuses to transmit data, voice, and video signals across local networks, typically manufactured with copper conductors or glass optical fibers in standardized jacketing rated for flame propagation and bandwidth performance. Fiber optic cable is gaining share in backbone applications where bandwidth density and electromagnetic immunity matter most, while twisted pair cable retains dominance in horizontal distribution due to cost efficiency and Power over Ethernet compatibility. Copper cable faces margin compression from raw material volatility even as it sustains volume in commercial building retrofits.
The Federal Communications Commission in the United States governs telecommunications infrastructure standards that cascade into premise cabling specifications for carrier-neutral facilities. The European Telecommunications Standards Institute and CE marking requirements under the EU Construction Products Regulation enforce fire safety and electromagnetic compatibility testing for cables sold across member states. Stakeholders must monitor evolving PoE++ power delivery thresholds and their thermal implications for cable gauge selection in smart building deployments.
Market Dynamics
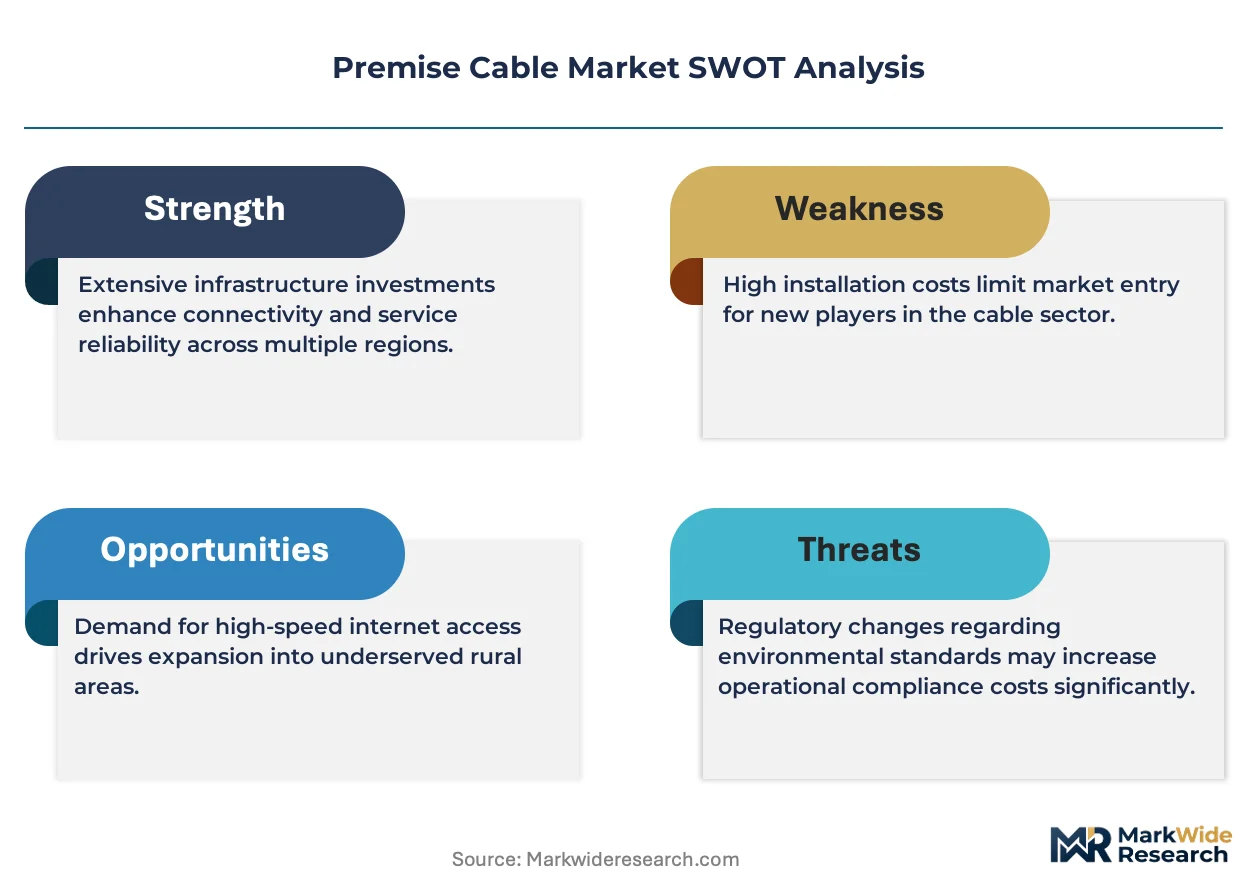
Data center power densities and PoE++ load thresholds are forcing cable gauge and thermal rating upgrades across commercial building infrastructure, compressing legacy copper specifications while accelerating fiber backbone deployment.
Growth Catalysts
- Hyperscale facility expansion:Cloud service providers in the United States are procuring bulk fiber and copper runs for multi-megawatt server halls, driving standardized cable bundle orders.
- EU Construction Products Regulation:CE marking mandates for low-smoke zero-halogen jacketing are pulling flame-retardant cable volumes across member state building retrofits.
- Power over Ethernet evolution:IEEE 802.3bt 90W delivery standards are requiring heavier gauge twisted pair in smart lighting and access control deployments.
Market Restraints
- Copper price volatility:London Metal Exchange copper fluctuations are compressing margins on high-volume twisted pair production.
- Optical fiber supply concentration:Preform and draw tower capacity clusters in China create procurement risk for European and North American installers.
- Installation skill bottlenecks:Certified fiber splicing technician shortages are extending project timelines in Germany and Japan.
Strategic Opportunities
- India smart city buildouts:Municipal fiber-to-the-building mandates in Delhi and Mumbai are opening greenfield structured cabling contracts.
- Building-integrated photovoltaics convergence:DC microgrid cabling for solar-integrated facades is creating new power-data hybrid cable specifications.
- Single-pair Ethernet emergence:IEEE 802.3cg 10BASE-T1L is enabling sensor network retrofits in industrial automation without full cable replacement.
Industry Challenges
- Multi-standard certification timelines:TIA-568, ISO/IEC 11801, and EN 50173 testing concurrency is prolonging product launch cycles.
- Legacy infrastructure integration:Category 5e plant compatibility requirements are constraining Category 8 deployment in aged commercial real estate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premise Cable Market |
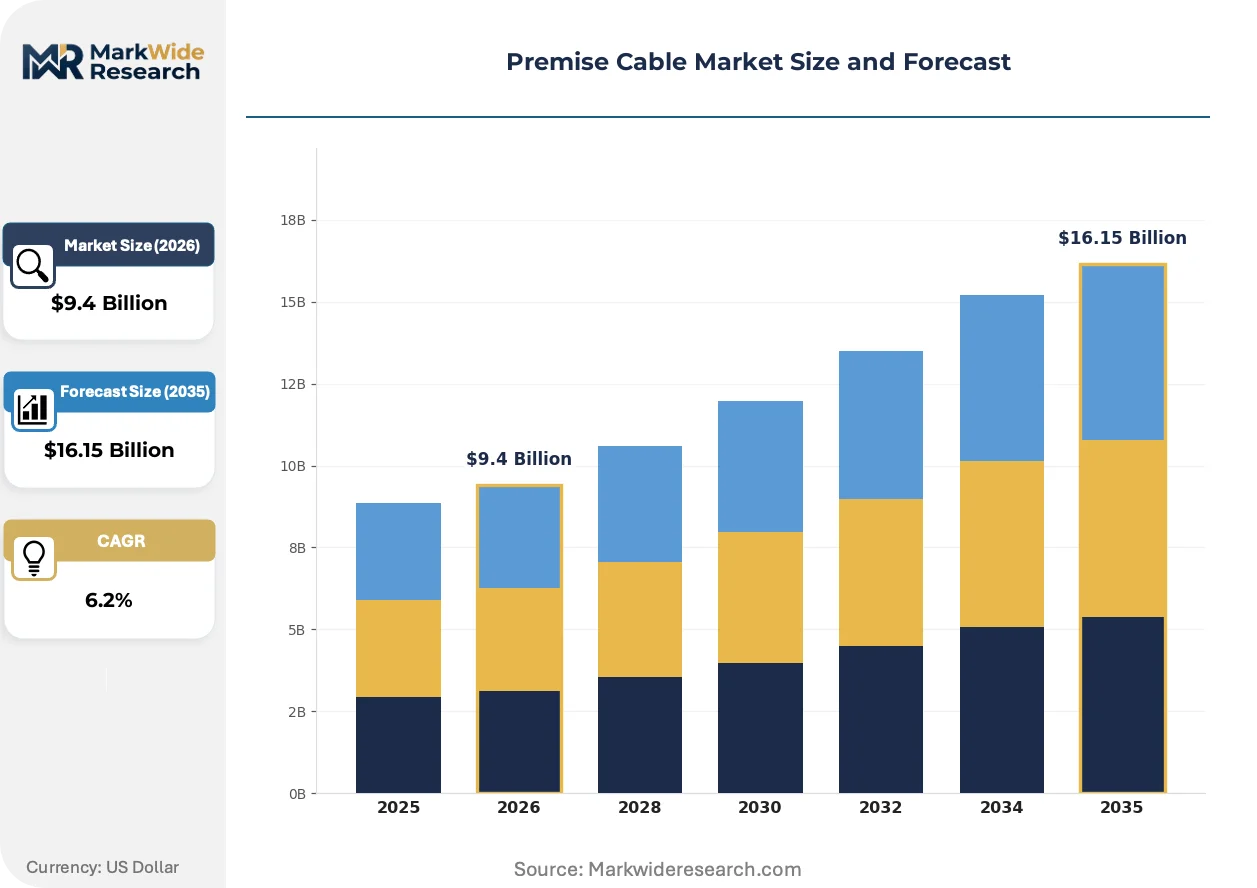
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.15 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Copper Cable, Fiber Optic Cable, Coaxial Cable, Twisted Pair Cable Application: Data Centers, Telecommunications, Industrial Automation, Commercial Buildings Installation Method: Above Ground, Underground, Aerial, Direct Burial Connector Type: Laptop Connectors, Network Switch Connectors, Patch Panel Connectors, Modular Connectors |
| Companies Covered | Belden Inc., Prysmian Group, Nexans S.A., Corning Incorporated, Schneider Electric, Siemens AG, HellermannTyton, Anixter Inc., CommScope Holding Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premise Cable Market Strategic Shifts & Innovations
Bandwidth density requirements and thermal load management are reshaping material selection and installation practices across premise cable categories. Three intersecting developments are altering competitive positioning and procurement patterns.
Single-mode fiber with bend-insensitive coating is expanding into horizontal distribution zones previously reserved for copper. Colocation operators in Frankfurt and Singapore are specifying OS2 fiber to rack units to eliminate electromagnetic interference risks. This migration is compressing copper backbone revenue pools while elevating termination hardware and cleaning protocol service contracts.
The EU F-Gas Regulation phase-down is accelerating hydrofluoroolefin adoption in cable jacketing foams. Manufacturers serving the German and French markets are reformulating insulation compounds to meet 2027 GWP thresholds. Jacketing suppliers with in-house polymer compounding capabilities are capturing specification preference from distributors facing compliance documentation burdens.
Direct-to-contractor digital procurement platforms are displacing traditional electrical wholesaler channels for standardized cable SKUs. MRO buyers in Texas and Bavaria are aggregating specifications through vendor-managed inventory portals. This channel shift is most visible in commercial retrofit verticals where project repeatability supports automated replenishment algorithms.
Premise Cable Market Segmentation
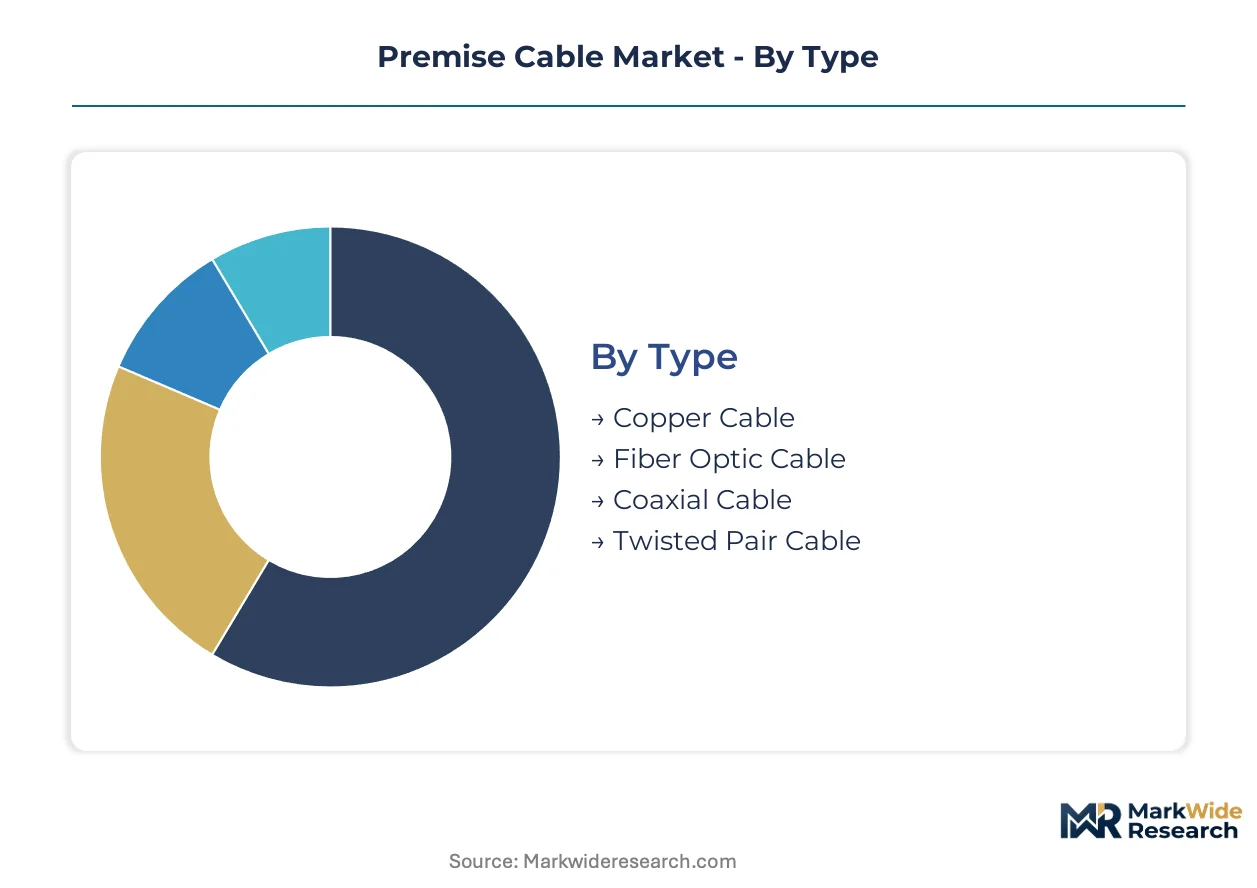
Premise cable procurement decisions hinge on bandwidth requirements, thermal load tolerance, and installation environment constraints. Understanding how these factors map to segment boundaries enables suppliers to align product portfolios with buyer priority hierarchies.
Type:
Material selection drives cost structure, bandwidth ceiling, and electromagnetic immunity trade-offs in buyer specifications.
- Copper Cable:Solid or stranded copper conductors in PVC or LSZH jacketing deliver electrical conductivity for power and data transmission. Demand concentrates in commercial building retrofits across Germany and Japan where PoE++ compatibility with legacy infrastructure constrains fiber migration.
- Fiber Optic Cable:Glass optical fibers with polymer cladding and protective outer jacketing enable high-bandwidth, interference-immune signal transmission. Hyperscale data centers in the United States and China are specifying single-mode fiber for backbone runs exceeding 10 Gbps, compressing copper share in high-density environments.
- Coaxial Cable:Central copper conductor with dielectric insulator and braided shielding maintains relevance in legacy video distribution and RF applications.
- Twisted Pair Cable:Paired insulated conductors twisted to cancel electromagnetic interference dominate horizontal distribution for Ethernet deployments.
Volume sits with twisted pair cable; growth tilts toward fiber optic cable.
Application:
End-use environment dictates fire safety ratings, bend radius tolerance, and termination complexity requirements.
- Data Centers:Structured cabling for server-to-switch interconnects and storage area networks demands low-latency, high-density connectivity. Operators in Frankfurt and Singapore are specifying OS2 single-mode fiber to rack units, eliminating electromagnetic interference risks in multi-tenant facilities.
- Telecommunications:Carrier-neutral facilities and central office interconnects require standardized cable bundles for voice, video, and broadband services. Municipal fiber-to-the-building mandates in Delhi and Mumbai are pulling flame-retardant cable volumes for last-mile infrastructure.
- Industrial Automation:Harsh-environment cabling for manufacturing floors and process control networks faces oil, chemical, and abrasion exposure.
- Commercial Buildings:Office, retail, and hospitality installations balance cost efficiency with smart building integration requirements.
Revenue concentrates in data centers; expansion accelerates most quickly in telecommunications.
Installation Method:
Deployment environment determines mechanical protection, moisture sealing, and accessibility for maintenance.
- Above Ground:Cable trays, conduit runs, and raceway installations in building interiors and campus distribution. Smart city buildouts in Texas and Bavaria are driving above-ground fiber deployment for rapid infrastructure scaling without excavation permits.
- Underground:Duct bank and direct-buried installations for campus backbone and metropolitan area networks. EU Construction Products Regulation CE marking mandates for low-smoke zero-halogen jacketing are tightening compliance documentation for underground cable procurement across member states.
- Aerial:Pole-mounted and messenger-supported deployments for rural and temporary connectivity.
- Direct Burial:Armored or gel-filled cables installed without conduit for cost-sensitive outdoor runs.
Procurement volume favors above-ground methods; underground installations are gaining specification preference for aesthetic and security reasons.
Connector Type:
Interface standardization affects interoperability, field termination complexity, and lifecycle upgrade paths.
- Laptop Connectors:RJ45 and USB-C interfaces for end-user device connectivity in office and educational environments. Corporate refresh cycles in Japan are standardizing on Category 6A patch cords with modular connectors to support 10GBASE-T deployment.
- Network Switch Connectors:SFP, QSFP, and RJ45 ports for aggregation and core switching infrastructure. Colocation operators in the United States are procuring MPO-16 multifiber push-on connectors for 400G switch-to-switch links, reducing port density and cable bulk.
- Patch Panel Connectors:Rear termination interfaces for structured cabling cross-connects and management.
- Modular Connectors:Field-terminable plugs for custom-length patch cord fabrication and repair.
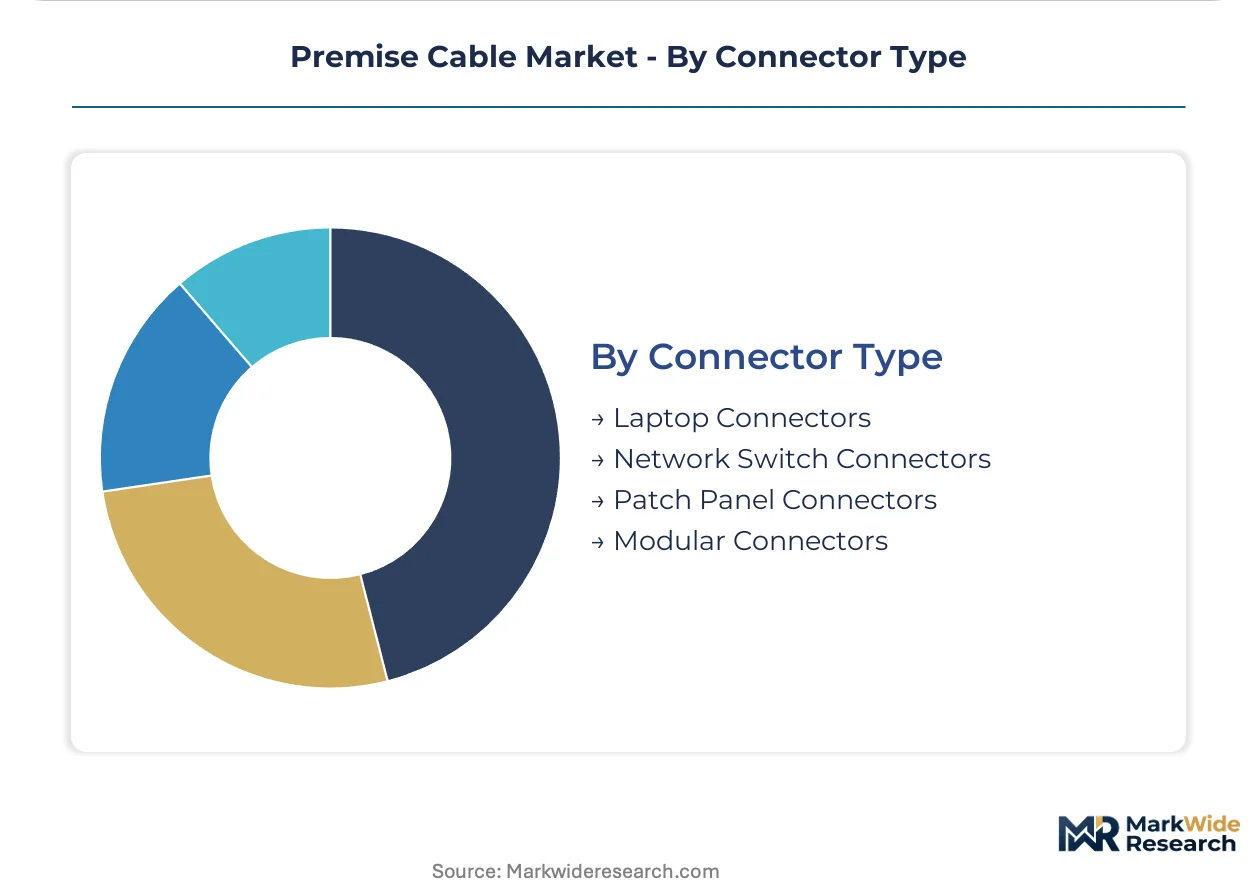
Network switch connectors command the largest volume; laptop connectors are climbing the fastest as device refresh accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Dubai Internet City are concentrating hyperscale data center investments and pulling structured cabling procurement toward Asia-Pacific and Middle East hubs.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth are procuring bulk fiber runs for multi-megawatt server halls. FCC telecommunications infrastructure standards cascade into premise cabling specifications for carrier-neutral facilities. Ashburn's Data Center Alley anchors the densest concentration of cross-connect demand in North America.
Germany
Colocation operators in Frankfurt specify OS2 single-mode fiber to rack units for electromagnetic immunity in multi-tenant environments. EU F-Gas Regulation phase-down mandates hydrofluoroolefin adoption in cable jacketing foams by 2027. Bavaria's industrial automation corridor sustains demand for PoE++-rated twisted pair in smart factory retrofits.
China
Municipal fiber-to-the-building mandates in Shanghai and Beijing are accelerating last-mile infrastructure deployment. MIIT and GB standards govern telecommunications cabling specifications for carrier facilities. Yangtze River Delta manufacturing clusters supply preform and draw tower capacity serving domestic and export markets.
India
Smart city buildouts in Delhi and Mumbai are opening greenfield structured cabling contracts for municipal fiber networks. TRAI broadband infrastructure directives shape procurement standards for telecom-grade installations. Karnataka's Bangalore-Chennai industrial corridor hosts expanding data center campuses driving cable bundle orders.
Japan
Corporate refresh cycles in Tokyo and Osaka standardize on Category 6A patch cords to support 10GBASE-T deployment. METI industrial standards and JIS cabling specifications enforce quality compliance for building infrastructure. Kanto region facility investments concentrate procurement volume for high-density fiber backbone installations.
Premise Cable Market Key Industry Players
Top-tier vendors anchor premium-grade fiber and fire-resistant portfolios, while mid-tier specialists compete on regional distribution density and project customization. The vendor base stratifies across three tiers: global cable conglomerates with integrated polymer compounding, regional system integrators with installation service bundles, and niche specialists in harsh-environment specifications. Two dominant competitive moves define positioning: backward integration into optical preform manufacturing to secure fiber supply, and acquisition of termination hardware vendors to capture installation service revenue.
Among diversified industrial conglomerates, Belden Inc., Prysmian Group, and Nexans S.A. exemplify the scale-driven archetype with integrated manufacturing footprints spanning multiple continents. These entities occupy positions where global certification breadth and polymer formulation capabilities create specification preference among distributor networks facing EU Construction Products Regulation compliance documentation burdens. Their market presence represents the consolidation endpoint for cable procurement standardization.
| Leading Market Players |
|---|
| Belden Inc. |
| Prysmian Group |
| Nexans S.A. |
| Corning Incorporated |
| Schneider Electric |
| Siemens AG |
| HellermannTyton |
| Anixter Inc. |
| CommScope Holding Company, Inc. |
| Others |
Cost & Logistics Intelligence
Backward integration into optical preform manufacturing anchors supply security and pricing leverage for tier-one cable suppliers serving hyperscale data center operators in Northern Virginia and Frankfurt. This captive production of critical fiber inputs insulates margin structures from London Metal Exchange copper volatility while compressing procurement timelines for multi-megawatt facility buildouts.
Pricing Analysis
Short-lead-time premiums command pricing separation from spot inventory liquidation in the premise cable market. Three-tier pricing structure across premium, standard, and economy levels stratifies by UL/CE certification grade and volume scale, with hyperscale cloud operators least price-sensitive due to total-cost-of-ownership framing. Pricing pressure stems from copper conductor cost compression in high-volume twisted pair production. Commercial building retrofit contractors exhibit acute price sensitivity, driving procurement toward distributor-managed inventory portals.
Supply Chain Analysis
Dual-sourcing requirements from hyperscale operators mandate multi-supplier qualification across preform and draw tower capacity clusters in China, South Korea, and the United States. Raw material dependencies center on copper cathode, glass optical fiber, and low-smoke zero-halogen polymer compounds. Single-source vulnerability concentrates in Chinese preform manufacturing. Distribution runs through electrical wholesaler networks and direct-to-contractor digital procurement platforms serving MRO buyers in Texas and Bavaria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Construction Products Regulation compliance documentation burdens are forcing consolidation among regional distributors lacking in-house polymer compounding capabilities. Margin compression from raw material volatility and certification cost inflation will eliminate sub-scale players within the analysis window.
For Market Incumbents: Acquire termination hardware vendors to capture installation service revenue streams from certified fiber splicing technician shortages in Germany and Japan. Defend specification preference by deepening backward integration into optical preform manufacturing, securing captive supply against Chinese capacity concentration. Channel control through vendor-managed inventory portals reinforces distributor lock-in against digital procurement displacement. For New Entrants and Emerging Players: Begin with single-pair Ethernet retrofit specifications for industrial automation corridors in Bavaria and Karnataka, where IEEE 802.3cg 10BASE-T1L enables sensor network deployment without full cable replacement. Municipal fiber-to-the-building mandates in Delhi and Mumbai represent the most penetrable geography. Go-to-market execution through direct-to-contractor digital platforms bypasses entrenched electrical wholesaler relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by global cable conglomerates seeking regional distribution density and fire-resistant portfolio expansion. Long-term viability favors mid-tier specialists with in-house polymer compounding capabilities aligned with EU F-Gas Regulation phase-down timelines. Watch IEEE 802.3bt 90W PoE++ deployment rates as inflection indicator for copper gauge upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Preform Manufacturing | Captive fiber supply secures margin protection against Chinese draw tower concentration. |
| Acquisition of Termination Hardware Vendors | Installation service revenue captures value from certified splicing technician shortages. |
| Low-Smoke Zero-Halogen Polymer Compounding Investment | In-house formulation capability meets EU Construction Products Regulation documentation requirements. |
| Direct-to-Contractor Digital Platform Launch | Automated replenishment algorithms displace traditional electrical wholesaler channels in commercial retrofits. |
| Single-Pair Ethernet Product Line Development | IEEE 802.3cg compliance opens industrial automation retrofit contracts without full infrastructure replacement. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving data center infrastructure planners, electrical contractor procurement leads, cable distributor category managers, and polymer compounding technical directors. TIA-568 standard documentation, FCC telecommunications infrastructure filings, EU Construction Products Regulation compliance databases, and London Metal Exchange copper price series provided validation benchmarks. Bottom-up facility investment tracking and top-down industry revenue estimates underwent iterative reconciliation.
Data-stream reconciliation across shipment volumes, import-export flows, and capital expenditure disclosures shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include cable type, installation environment, connector interface, and regional regulatory cluster. CAGRs derived from trend extrapolation against infrastructure buildout pipelines. Hyperscale cloud operator procurement patterns and smart city municipal mandate timelines served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; fiber optic cable and data center application categories carry tighter precision than coaxial legacy video distribution. Forecasts reflect documented assumptions regarding copper price trajectories, PoE++ adoption curves, and EU regulatory enforcement intensity. Deviation in Chinese preform export restrictions or IEEE power delivery standard revision timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Ethernet Converters Market
Cables
Smartphone Type-C Charging and Data Cable Market
Cables
Magnetic Charging Cable Market
Cables
Cable Drum Market
Cables
FFC/FPC Jumper Cables Market
Cables
United States Cable Accessories Market
Cables
Direct Attach Cable Market
Cables
Middle East and Africa Submarine Cable System Market
Cables
Sensing Cable Market
Cables
Asia Pacific MV and HV Underground Cables and Accessories Market
Cables
Cable Clamp Market
Cables
Power and Control Cable Market
Cables
Europe Cable Accessories Market
Cables
Multi-Core Land High Voltage Underground Cable Market
Cables
Global Cable Tie Market
Cables
Hybrid Cables Market