
 Hybrid Cables Market | 2026-2036
Hybrid Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Cables Market Intelligence
Bundle configurations that merge power conductors with fiber optic elements is shifting procurement preferences toward single-installation infrastructure. Prysmian Group leverages its submarine and terrestrial cable portfolio to anchor large-scale renewable energy interconnects across European offshore zones. Sumitomo Electric Industries sustains vertical integration from copper smelting to finished cable assemblies, controlling cost structures in high-voltage hybrid segments. Nexans competes through specialized manufacturing scale in corrugated armor designs for harsh-environment industrial deployments.
Hybrid cables integrate multiple transmission media—typically electrical conductors combined with optical fibers or coaxial elements—within a unified protective jacket, enabling simultaneous power delivery and high-bandwidth data communication through a single routing path. Armored and non-armored variants dominate the technology landscape, with armored configurations commanding premium positioning in mining and petrochemical applications where mechanical protection proves essential. Fiber optic hybrid products lead product-type demand as telecommunications infrastructure upgrades displace legacy copper backbones, while power and communication hybrid formats capture expanding share in data center environments where converged cabling reduces rack congestion and installation labor.
REACH and RoHS frameworks in Europe restrict halogenated flame retardants in cable sheathing, compelling compound reformulation across the supply base. The EU AI Act and CSRD reporting requirements are adding traceability mandates that affect material sourcing documentation for infrastructure-grade products. NMPA and GB standards in China enforce fire-performance testing protocols that shape export qualification requirements for manufacturers serving dual markets. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance-driven product fragmentation that fragments production economies.
Market Dynamics
Telecom operators are collapsing separate power and data infrastructure into unified jacket designs, forcing compound suppliers and cable assemblers to reconfigure production lines around converged conductor architectures rather than discrete product categories.
Growth Catalysts
- FTTP Deployment Mandates:National broadband programs in Germany and France require fiber-to-the-premises rollouts that bundle electrical conductors with optical elements, creating specification pull for hybrid formats.
- REACH Sheathing Reformulation:ECHA restrictions on halogenated flame retardants compel manufacturers to qualify halogen-free compounds, opening procurement windows for certified European compounders.
- Industrial Automation Density:Factory floor robotics clusters around Stuttgart and Munich drive armored hybrid cable demand for power-plus-communication tethering in motion control systems.
Market Restraints
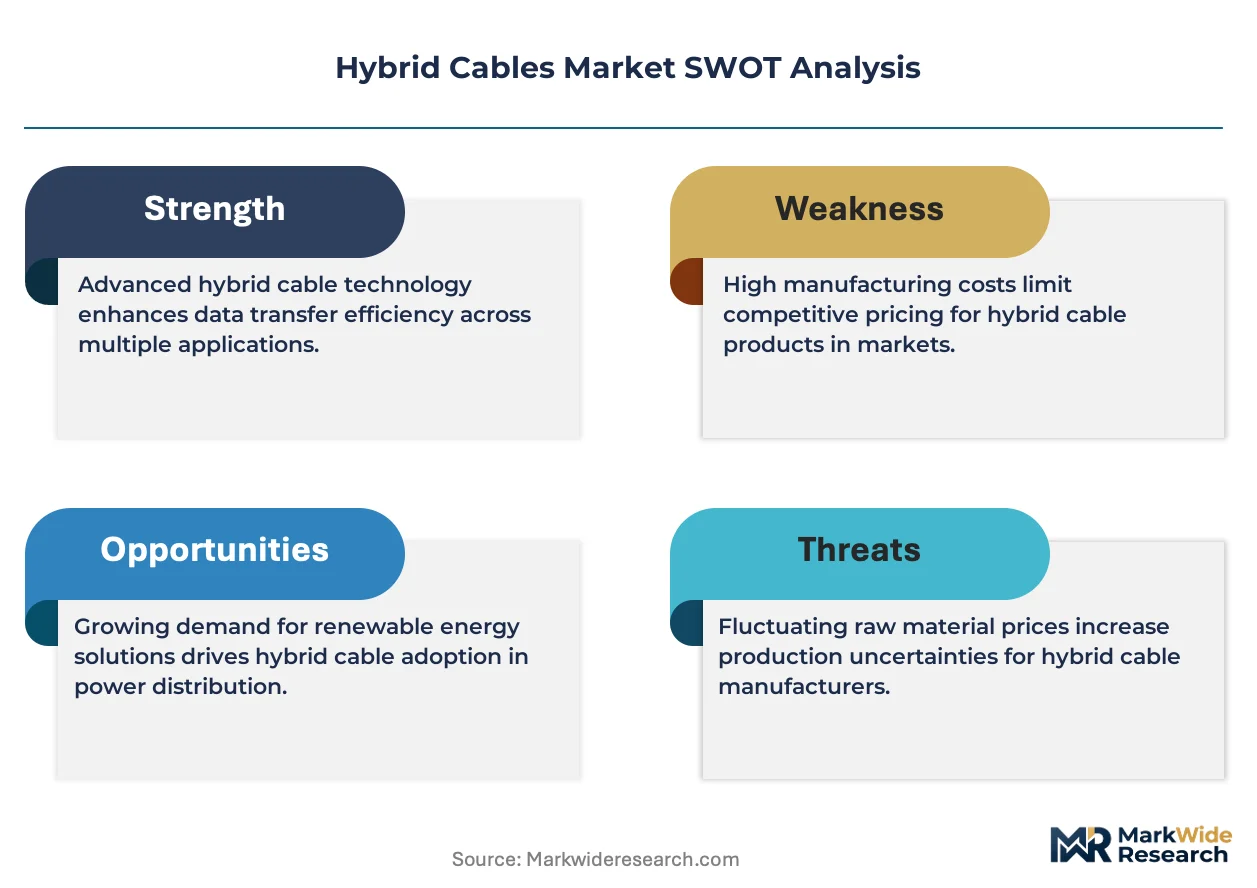
- Copper Price Volatility:LME copper fluctuations compress margin visibility for power conductor segments, forcing hedging costs onto cable assemblers with limited working capital buffers.
- Optical Fiber Supply Concentration:Preform and draw-tower capacity concentrates among three Asian suppliers, creating single-source risk for European hybrid cable manufacturers.
- Halogen-Free Performance Gap:Non-halogen sheathing compounds exhibit inferior low-temperature flexibility versus legacy PVC, limiting deployment in Arctic and subsea environments.
Strategic Opportunities
- Data Center Converged Cabling:Hyperscale facilities in Frankfurt and Amsterdam are adopting power-plus-fiber hybrid formats to reduce rack congestion and installation labor hours.
- Offshore Wind Interconnects:Submarine hybrid designs that combine medium-voltage conductors with fiber optic monitoring cores address turbine array cabling complexity in North Sea zones.
- EU Green Deal Procurement Incentives:Public infrastructure tenders with embodied carbon scoring favor domestic manufacturers with verified low-carbon compound supply chains.
Industry Challenges
- Cross-Disciplinary Installation Expertise:Field crews must certify simultaneously in electrical safety and fiber handling protocols, constraining workforce scalability for large-scale deployments.
- Dual Certification Timelines:Hybrid products require sequential testing against both IEC electrical standards and ITU-T optical specifications, extending time-to-market by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Cables Market |
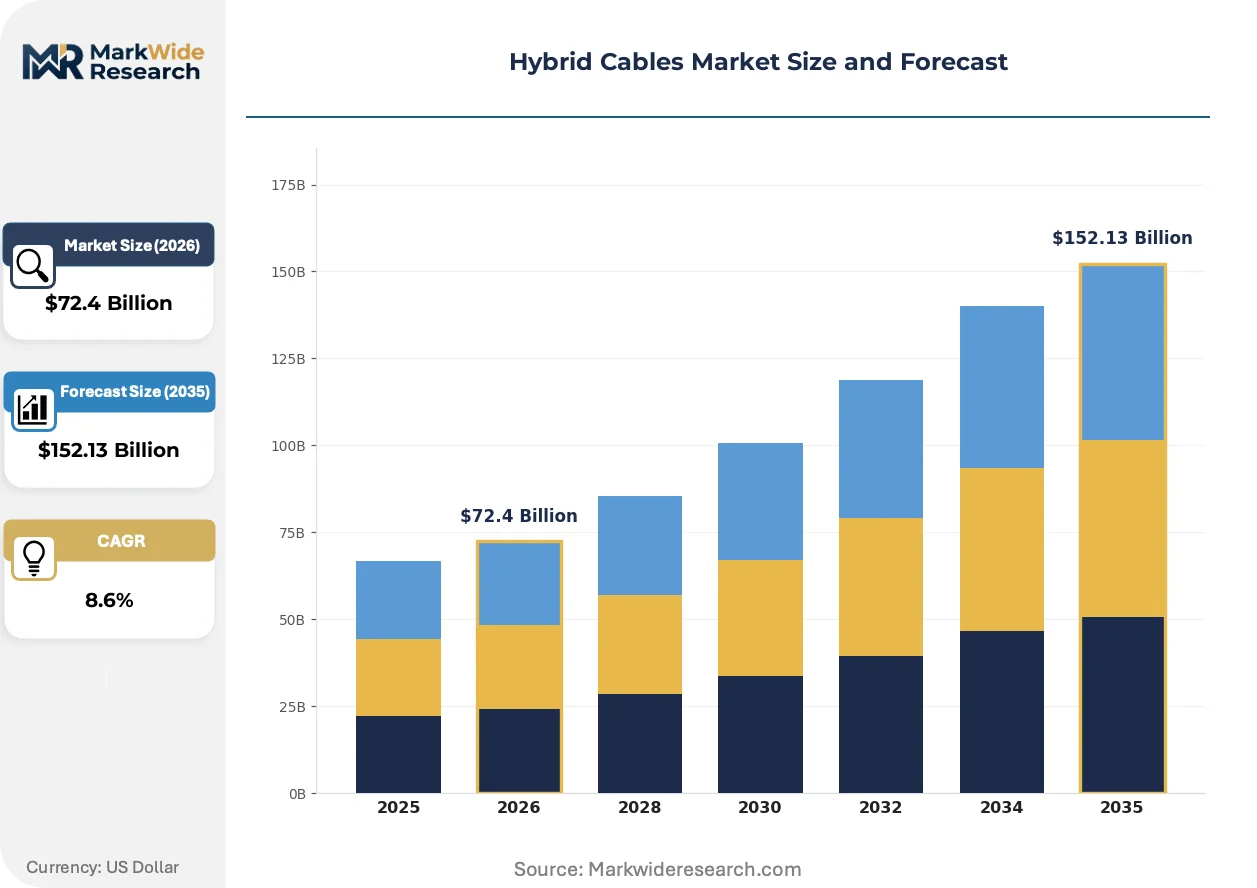
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $152.13 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Optic Hybrid, Coaxial Hybrid, Twisted Pair Hybrid, Power & Communication Hybrid Technology: Armored, Non-Armored, Corrugated, Aerial Application: Telecommunications, Data Centers, Industrial Automation, Renewable Energy End User Industry: Telecom Operators, Data Processing Units, Manufacturing Plants, Solar Power Plants |
| Companies Covered | Southwire, Sumitomo Electric Industries, Prysmian Group, Lapp Group, LEONI, Nexans, NKT, Belden Inc., LS Cable & System, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Cables Market Strategic Shifts & Innovations
Material science breakthroughs and procurement model compression are converging to redefine how infrastructure-grade cable gets specified, purchased, and deployed across industrial and telecommunications verticals.
Micro-duct fiber optic hybrid designs with integrated power conductors are rewriting installation economics for dense urban fiber builds. Municipal utilities in Barcelona and Milan are specifying these formats to avoid repeated street excavation. The technology compresses total project timelines by eliminating separate electrical trenching contracts.
China's NMPA and evolving GB standards are enforcing fire-performance testing protocols that exceed baseline IEC requirements. Export-oriented manufacturers must maintain dual qualification lines to serve domestic and international markets simultaneously. European suppliers with existing halogen-free portfolios capture first-mover advantage in this compliance tier.
Specification authority is migrating from general contractors to owner-operator engineering teams with lifecycle cost models. Data center developers in Frankfurt now issue performance-based cabling tenders that penalize installation labor hours rather than rewarding lowest unit pricing. This shift favors hybrid formats that reduce termination complexity and accelerate commissioning schedules.
Hybrid Cables Market Segmentation
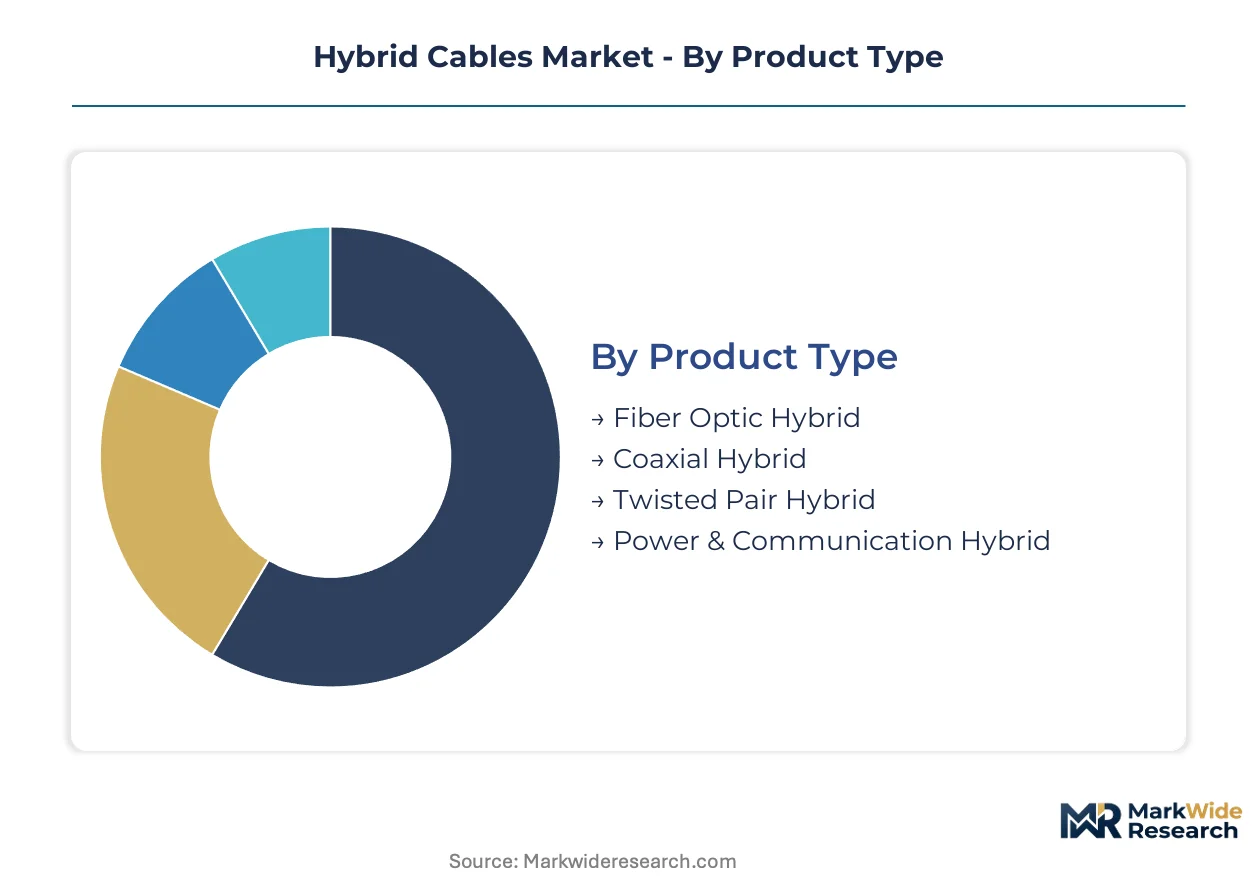
Hybrid cable procurement splits sharply across technical specifications and deployment environments. Buyers prioritize mechanical protection ratings in industrial settings while bandwidth density dominates telecommunications specifications.
Product Type:
Cost tiers separate commodity power-plus-data formats from precision-engineered fiber optic bundles with integrated conductors.
- Fiber Optic Hybrid:Combines single-mode or multimode optical fibers with copper power conductors in unified jacket constructions. Data center builds in Frankfurt and Amsterdam specify these formats to collapse separate electrical and fiber runs into single cable trays, cutting installation labor.
- Power & Communication Hybrid:Merges medium-voltage conductors with twisted pair or coaxial data elements for factory floor robotics. Stuttgart automotive clusters specify armored variants for motion control tethering in welding and assembly cells.
- Coaxial Hybrid:Integrates RF coaxial elements with DC power conductors for distributed antenna systems and broadcast infrastructure.
- Twisted Pair Hybrid:Pairs Category-rated copper data cables with power conductors for building automation and security system backbones.
Volume sits with Power & Communication Hybrid; growth tilts toward Fiber Optic Hybrid.
Technology:
Application environment dictates armor requirements more than conductor specifications.
- Armored:Steel wire or interlocked aluminum armor layers protect against crush loads and rodent damage. Mining operations in Germany's Ruhr district and petrochemical plants in Rotterdam mandate these specifications for regulatory compliance.
- Non-Armored:Flexible jacket constructions suit indoor riser and plenum installations where mechanical protection is unnecessary. Office building retrofits in Milan and Barcelona favor these for conduit fill efficiency.
- Corrugated:Continuous metal corrugated sheathing provides flexible armor for dynamic cable chains in industrial automation. Nexans maintains specialized manufacturing scale for these harsh-environment formats.
- Aerial:Self-supporting designs with integrated messenger wires span utility poles in rural fiber-to-the-premises deployments. French national broadband programs specify these for cost-effective last-mile extension.
Corrugated commands premium positioning; Non-Armored generates highest shipment volumes.
Application:
End-use maturity separates established telecom infrastructure from emerging renewable energy specifications.
- Telecommunications:Fiber-to-the-premises rollouts bundle optical elements with remote powering conductors for street cabinets and customer premises equipment. Germany and France drive specification activity through national broadband mandates.
- Data Centers:Hyperscale facilities converge power distribution and fiber trunking to reduce rack congestion and accelerate commissioning schedules.
- Industrial Automation:Factory floor robotics and motion control systems demand armored power-plus-communication tethering with million-flex-cycle ratings.
- Renewable Energy:Offshore wind arrays combine medium-voltage conductors with fiber optic monitoring cores for turbine interconnection and SCADA telemetry.
Telecommunications anchors current procurement; Renewable Energy shows steepest expansion trajectory.
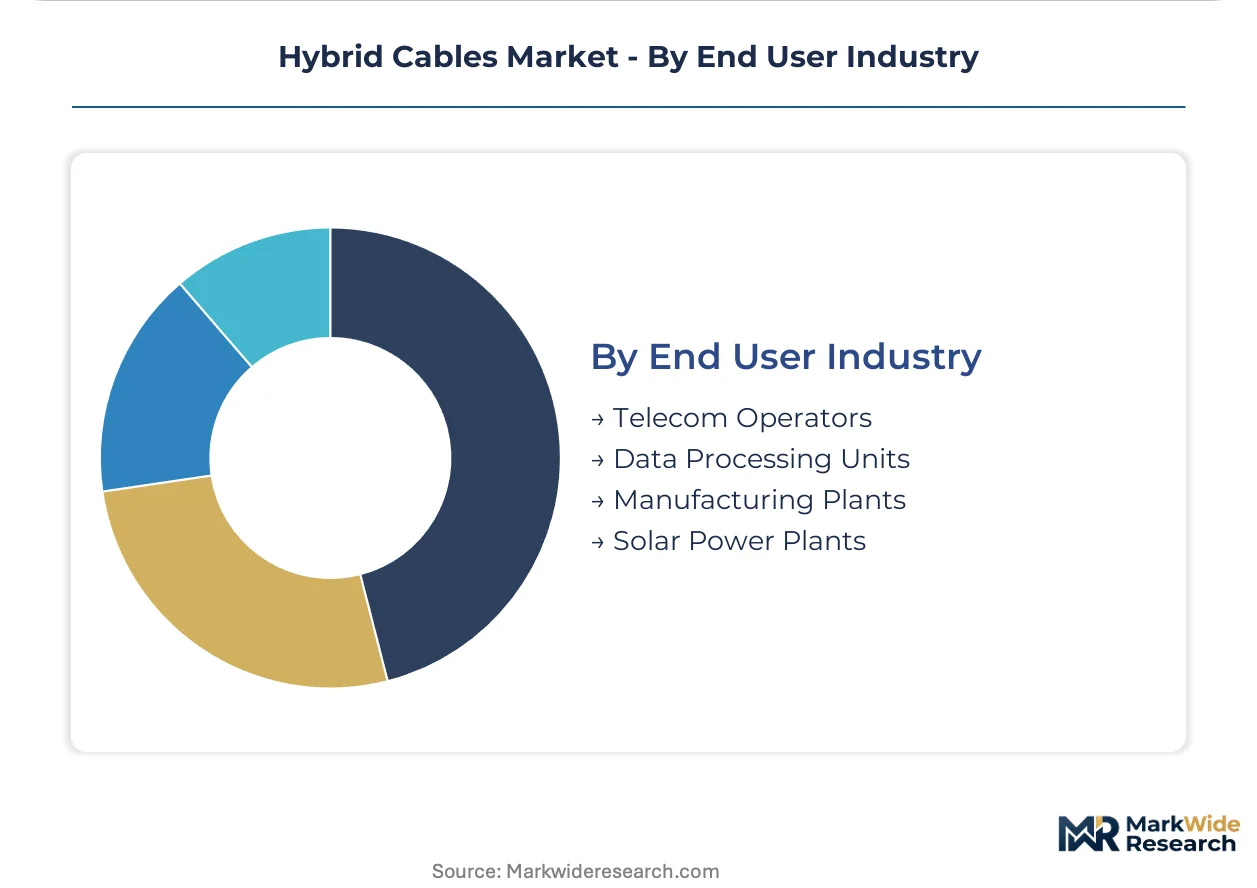
End User Industry:
Customer scale determines whether procurement favors standardized catalog formats or engineered-to-order specifications.
- Telecom Operators:National incumbents and alternative network providers issue multi-year framework agreements for fiber-to-the-premises infrastructure. Deutsche Telekom and Orange specify hybrid formats to accelerate subscriber connection timelines.
- Data Processing Units:Hyperscale cloud operators and colocation providers issue performance-based tenders penalizing installation labor hours rather than rewarding lowest unit pricing.
- Manufacturing Plants:Automotive and machinery producers source armored hybrid cables for robot workcells and automated guided vehicle charging circuits.
- Solar Power Plants:Utility-scale photovoltaic installations deploy power-plus-communication hybrid trunking between inverter stations and supervisory control systems.
Telecom Operators concentrate procurement volume; Data Processing Units expand specifications fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European cable fabricators dominate production capacity while Asian markets absorb the fastest consumption growth. Manufacturing concentrates in Germany and Italy with specialized armor and fiber integration lines. Demand expansion concentrates in national broadband programs and industrial automation clusters.
Germany
Stuttgart and Munich automotive clusters drive armored hybrid cable procurement for factory floor robotics and motion control systems. REACH compliance through ECHA mandates halogen-free sheathing compound reformulation. The Ruhr district mining operations specify steel-wire armor configurations for regulatory compliance in hazardous environments.
France
National broadband programs mandate fiber-to-the-premises rollouts bundling power and optical elements in unified jacket designs. ANSM and CNIL traceability requirements intersect with infrastructure procurement documentation standards. Paris-region data center developers issue performance-based tenders penalizing installation labor hours.
China
NMPA and evolving GB standards enforce fire-performance testing protocols exceeding baseline IEC requirements for export qualification. MIIT industrial policy accelerates smart manufacturing deployment in Yangtze River Delta clusters. Shenzhen and Shanghai compounders serve dual qualification lines for domestic and international market access.
United States
FCC broadband deployment incentives compress separate power and data infrastructure into converged jacket specifications. EPA material restrictions shape sheathing compound selection for federal infrastructure projects. Texas and California hyperscale data center developments specify power-plus-fiber formats to reduce rack congestion.
Japan
METI energy efficiency standards promote integrated cabling for building automation and distributed energy systems. PMDA documentation requirements affect material traceability for infrastructure-grade products. Osaka and Nagoya industrial machinery manufacturers source corrugated armor designs for dynamic cable chain applications.
Hybrid Cables Market Key Industry Players
The competitive structure tilts toward diversified cable conglomerates with integrated compound-to-assembly capabilities. European and Japanese incumbents anchor the premium tier through specialized armor manufacturing scale. Three archetypes dominate: submarine and terrestrial specialists, vertically integrated copper processors, and corrugated armor fabricators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure preform supply and qualify halogen-free portfolios.
Among European cable conglomerates, Prysmian Group and Nexans occupy positions exemplifying the premium-tier armor specialization archetype. Sumitomo Electric Industries represents the vertically integrated model with captive copper processing capabilities. These three anchors demonstrate how geographic concentration in Italian and Japanese manufacturing bases intersects with divergent strategic postures around compound integration and harsh-environment certification.
| Leading Market Players |
|---|
| Southwire |
| Sumitomo Electric Industries |
| Prysmian Group |
| Lapp Group |
| LEONI |
| Nexans |
| NKT |
| Belden Inc. |
| LS Cable & System |
| Others |
Cost & Logistics Intelligence
Copper conductor costs transmit directly from LME trading floors through to armored hybrid cable tier pricing, with Stuttgart automotive buyers absorbing volatility through indexed contract structures while data center developers in Frankfurt lock fixed-price multi-year frameworks.
Pricing Analysis
Cost-down pressure on standard-grade armored configurations accelerates because REACH-compliant halogen-free compounders command supply premiums. Three-tier pricing structure across premium, standard, and economy levels separates corrugated armor specifications from non-armored riser formats. Price differentiation traces to IEC certification grade and volume scale. Telecom operators exhibit highest price sensitivity due to national broadband program budget caps; offshore wind developers show lowest sensitivity given lifecycle cost modeling dominance.
Supply Chain Analysis
Optical fiber preform supply rests on Japanese and Chinese specialty glass manufacturers with draw-tower capacity concentrated in three Asian producers. Raw material dependencies span copper cathodes, fluorine-doped silica preforms, and halogen-free thermoplastic elastomers. Single-source vulnerability concentrates in high-purity glass preform supply. Distribution runs through authorized electrical distributors and direct OEM contracts with tier-one cable assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Preform supply concentration props pricing power for integrated fiber-copper assemblers, creating margin protection unavailable to compound-dependent competitors.
For Market Incumbents: Anchor armor manufacturing scale in German industrial clusters against emerging corrugated specialists from East Asia. Defend through captive halogen-free compound qualification under ECHA frameworks and capacity addition in Italian fiber integration lines. Prioritize certification investment for dual IEC-ITU-T hybrid product testing to compress 8-14 month approval timelines. For New Entrants and Emerging Players: Micro-duct fiber optic hybrid designs with integrated power conductors offer technology-first wedge into Barcelona and Milan municipal utility specifications. Target data center converged cabling in Amsterdam where performance-based tenders penalize installation labor hours. Pursue white-label supply agreements with European electrical distributors lacking fiber handling expertise. For Investors and Strategic Acquirers: ECHA enforcement actions against non-compliant sheathing imports are the leading indicator that halogen-free compound capabilities will consolidate valuation premiums. Long-term viability favors backward-integrated assemblers with captive copper processing and certified European compound supply chains. Watch NMPA GB standard harmonization pressure as signal for dual-qualification capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Smelting | Captive cathode supply insulates Prysmian and Sumitomo from LME volatility in high-voltage segments. |
| Halogen-Free Compound Qualification | ECHA REACH compliance opens procurement windows with Deutsche Telekom and Orange framework agreements. |
| Corrugated Armor Capacity Expansion | Nexans maintains specialized manufacturing scale for Stuttgart automotive robotics million-flex-cycle specifications. |
| Submarine Hybrid Cable Certification | Offshore wind interconnect demand in North Sea zones requires combined medium-voltage and fiber optic monitoring core validation. |
| Data Center Converged Cabling Partnerships | Frankfurt and Amsterdam hyperscale developers issue performance-based tenders favoring reduced rack congestion formats. |
Research Approach
Trade association filings, customs import records, and ECHA substance registration databases formed the secondary backbone, cross-referenced with primary interviews involving cable plant managers, OEM procurement leads at automotive manufacturers, and electrical distribution channel partners. Bottom-up and top-down triangulation validated segment sizing across armored and non-armored technology tiers.
Bottom-up unit economics modeled copper conductor weight, optical fiber count, and armor material specifications against installed cost data from municipal fiber and industrial automation projects. Segmentation dimensions spanned product type, armor technology, application vertical, and end-user industry scale. CAGRs derived from elasticity-adjusted demand projections tied to national broadband program commitments and offshore wind capacity pipelines.
Several conditions sit outside the modeled scope, including tariff rate fluctuations, preform supply disruption scenarios, and regulatory divergence between REACH and evolving GB fire-performance protocols. Forecasts reflect documented assumptions on raw material cost trajectories and certification timeline stability. A small set of named triggers warrants ongoing watch: ECHA enforcement intensity, NMPA standard harmonization pace, and data center developer tender specification migration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Fiber Optical Cable and Cable Assembly Products Market
Cables
Cable Market
Cables
Active Optical Cable Market
Cables
EPR Cable Market
Cables
Electric Submersible Cables (ESP) Market
Cables
Submarine Cable System Market
Cables
United States Cable Accessories Market
Cables
Europe HVAC Cables Market
Cables
Cable Racks Market
Cables
Sensor Cable Market
Cables
Polyurethane Cable Market
Cables
Cable Material Market
Cables
Global Wires and Cables Market
Cables
Power and Signal Cables Market
Cables
Anti-Static Space Wires Market
Cables
Cable Lugs Market