
 Copper Stranded Wire Market | 2026-2036
Copper Stranded Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Stranded Wire Market Analysis
India is rewriting regional supply dynamics through expanded copper rod and wire capacity additions in Gujarat and Tamil Nadu. Prysmian S.p.A. leverages its Mediterranean manufacturing base to anchor European utility procurement cycles. Polycab India Limited dominates domestic low-voltage distribution with backward integration into copper rod casting. Sumitomo Electric Industries, Ltd. specializes in ultra-fine stranded conductors for automotive harness applications across East Asian OEM networks.
Copper stranded wire consists of multiple thin copper conductors twisted together to improve flexibility while maintaining conductive performance, typically manufactured through bunching or concentric stranding processes with oxygen-free copper purity exceeding 99.9%. The product serves primarily as current-carrying infrastructure for power transmission, telecommunications signaling, and electromechanical systems requiring dynamic flexure resistance. Flexible and multi-strand product types command premium positioning in robotics and renewable energy cabling where installation bend radii are severe. Low voltage segments sustain volume leadership across residential and commercial electrical wiring applications. Industrial equipment and automotive applications represent the fastest-growing demand pools as electrification intensifies conductor specifications.
China's SAMR enforces GB standards for conductor resistance and thermal cycling performance that directly shape export eligibility for stranded wire manufacturers. India's BIS certification mandates for electrical cables create compliance thresholds that filter sub-scale domestic producers from utility tenders. The EU RoHS and REACH frameworks restrict hazardous substance content in insulated conductor assemblies, affecting material selection throughout the value chain. Stakeholders must monitor how evolving carbon border adjustments and conductor efficiency regulations redistribute competitive advantage between integrated smelter-wire producers and merchant cable fabricators.
Market Dynamics
Automotive electrification is compressing conductor specifications toward ultra-flexible stranded configurations that withstand vibration and thermal cycling across powertrain architectures. This demand pull is restructuring capacity allocation decisions at integrated copper processors and specialized cable fabricators alike.
Growth Catalysts
- GB Standards Compliance:China's SAMR mandates for conductor resistance and thermal cycling performance are filtering export-eligible manufacturers from commodity suppliers, tightening material purity thresholds across stranded wire production.
- EV Powertrain Wiring:Electric vehicle harness applications require multi-strand flexible conductors with enhanced flexure resistance, creating specification premiums for automotive-grade copper products.
- Southeast Asian Manufacturing:Vietnam and Indonesia are concentrating new cable plant investments as manufacturing corridors shift from coastal China, redirecting regional supply chain gravity.
Market Restraints
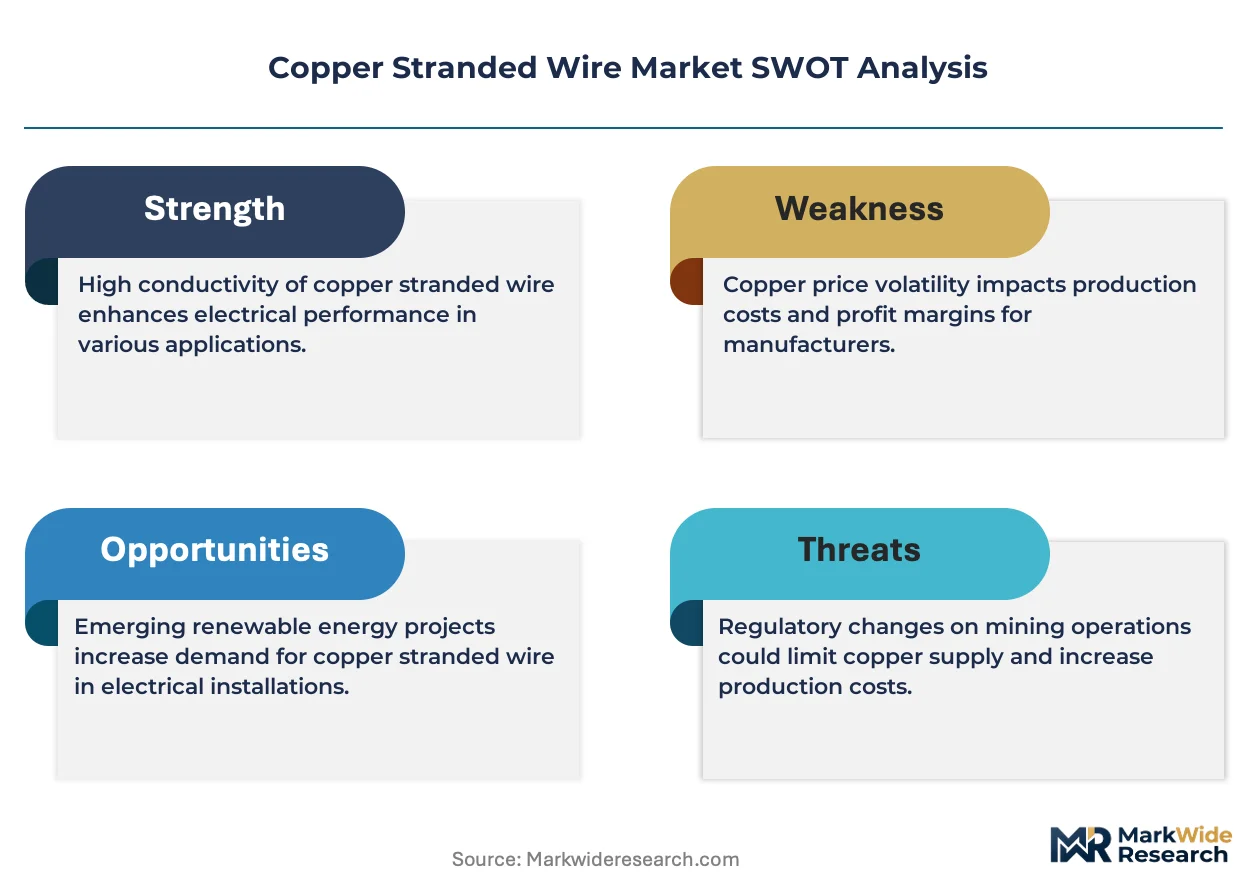
- Copper Price Volatility:LME copper price swings directly compress margin stability for merchant wire producers lacking captive smelter access or long-term concentrate offtake agreements.
- Chilean Concentrate Supply:Over half of global copper mining capacity concentrates in Chilean and Peruvian operations, exposing downstream wire manufacturers to geopolitical and labor disruption risks.
- Aluminum Substitution:Weight-driven automotive and aerial cable applications are migrating toward aluminum alloy conductors where conductivity-to-mass ratios favor non-copper solutions.
Strategic Opportunities
- India Capacity Expansion:Gujarat and Tamil Nadu are adding copper rod and wire capacity that redirects regional import dependency toward domestic sourcing for electrical infrastructure buildouts.
- Renewable Energy Cabling:Wind turbine nacelle wiring and solar farm interconnection demand severe bend-radius flexibility that multi-strand configurations uniquely satisfy.
- EU Carbon Border Adjustments:The EU's CBAM framework creates competitive advantage for low-carbon-intensity copper producers with verified Scope 1-3 emissions data.
Industry Challenges
- Oxygen-Free Copper Smelting Expertise:The specialized metallurgical knowledge required for 99.9%+ purity conductor production concentrates at a limited number of integrated processors, constraining quality-tier expansion.
- BIS Certification Timelines:India's Bureau of Indian Standards approval processes for electrical cables extend 12-18 months, filtering sub-scale domestic producers from utility tender participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Stranded Wire Market |
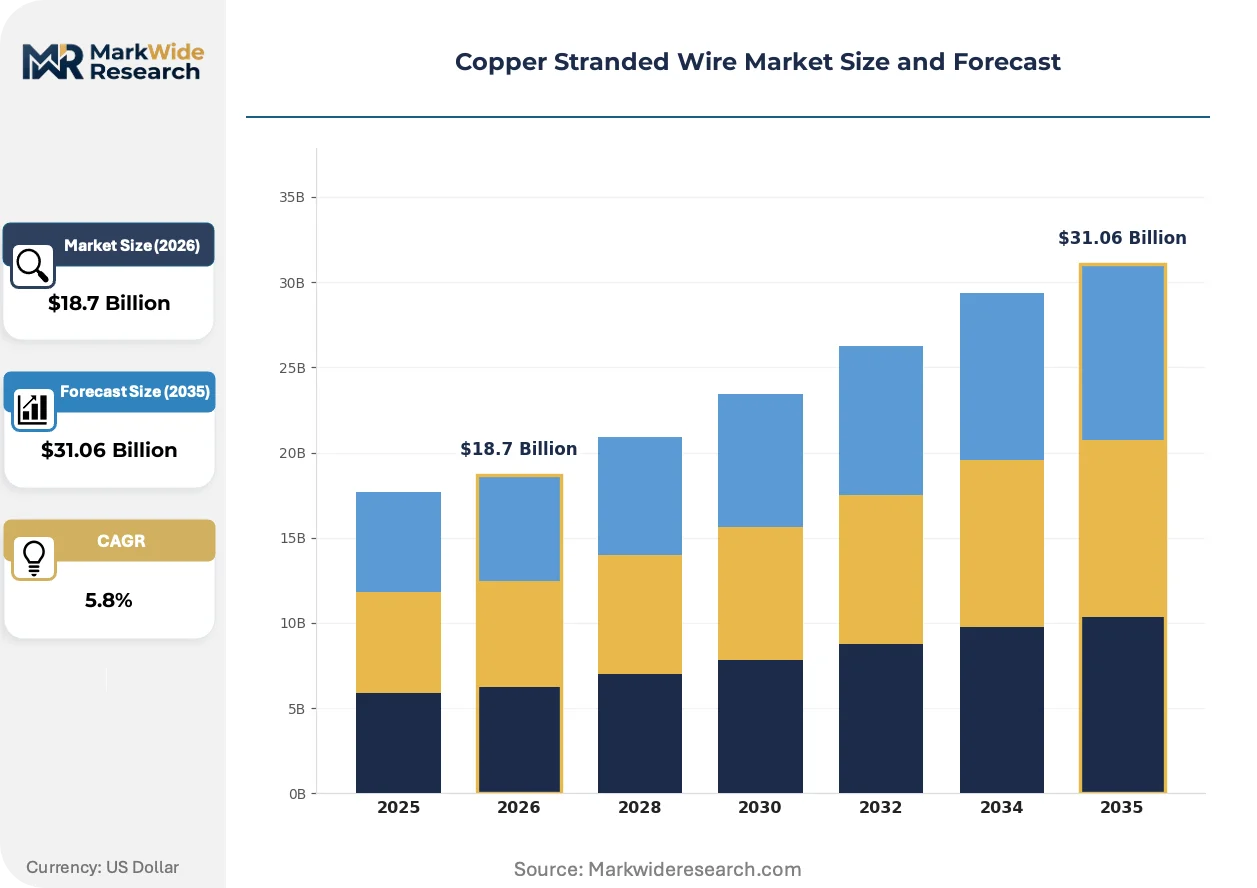
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Voltage, Low Voltage, Flexible, Multi-Strand Application: Electrical Wiring, Telecommunications, Automotive, Industrial Equipment End User: Manufacturers, Contractors, Utilities, OEMs Installation Type: Indoor, Outdoor, Underwater, Overhead |
| Companies Covered | Southwire Company, LLC, alfanar Group, Prysmian S.p.A, Polycab India Limited, International Wire, NEXANS, Alan Wire Company, Sarkuysan, Sumitomo Electric Industries, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Stranded Wire Market Emerging Trajectories
Conductor manufacturing is converging with precision metallurgy and digital process control, collapsing traditional quality-variation tolerances while enabling lot-traceable supply chains for automotive and renewable energy customers.
Continuous casting and rolling technology with inline annealing is collapsing the cost differential between standard and high-flexibility stranded wire products. Automotive harness suppliers in Germany and Japan are specifying these advanced conductors for 800V EV architectures. The technology is collapsing the traditional three-tier quality segmentation into a more compressed premium-standard spectrum.
REACH and RoHS frameworks in Europe are restricting hazardous substance content in insulated conductor assemblies, forcing material selection changes throughout cable fabrication value chains. Manufacturers serving EU markets are reformulating PVC and XLPE compounds to eliminate restricted phthalates and heavy metal stabilizers. Medical device and aerospace cable producers face the steepest compliance cost escalations under these evolving substance restrictions.
Consolidated procurement by automotive OEMs and renewable energy EPCs is compressing supplier bases toward tier-one cable fabricators with integrated copper rod casting and global certification portfolios. Tier-two wire merchants without captive smelter relationships are losing share in specification-intensive segments. This concentration is most visible in East Asian automotive supply chains and European offshore wind interconnection projects.
Copper Stranded Wire Market Segmentation
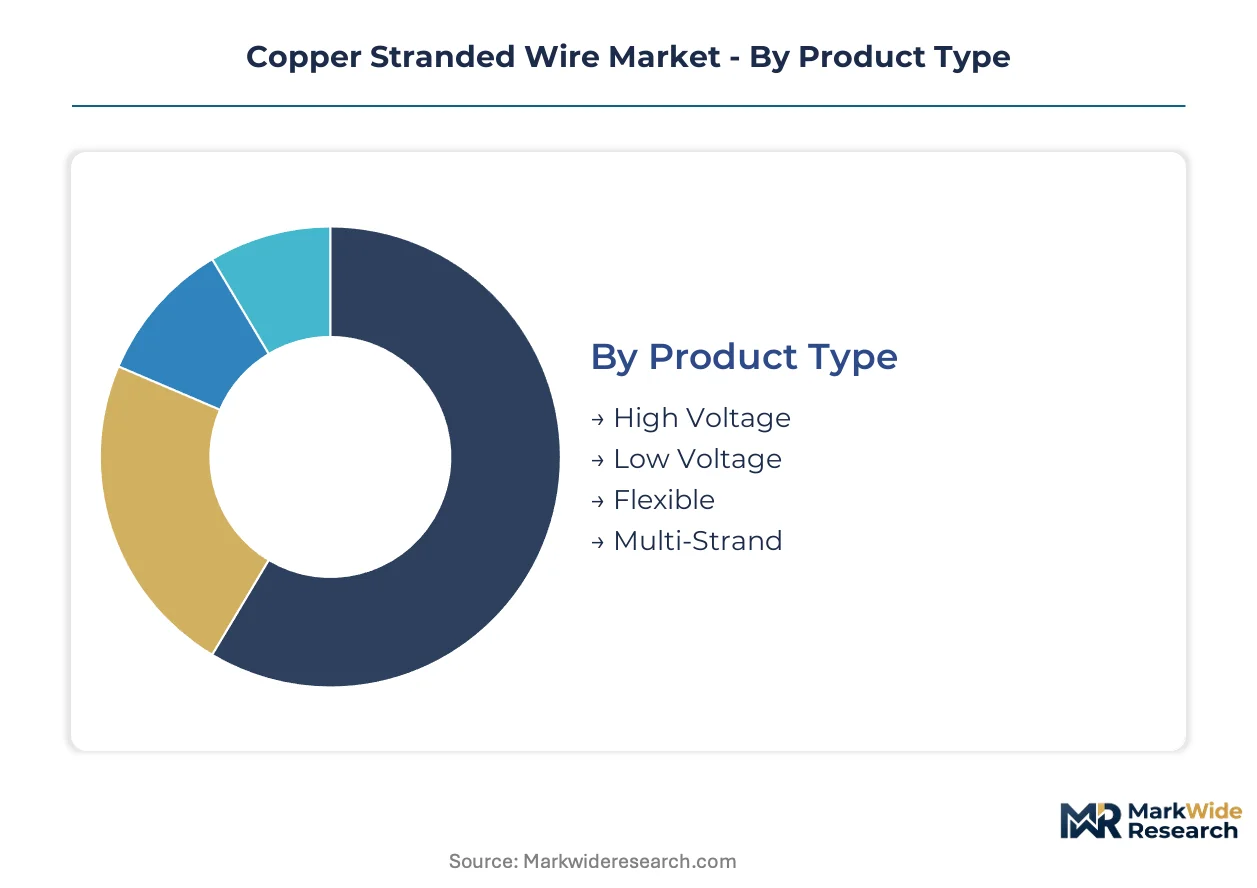
Copper stranded wire segmentation reveals how conductor specifications diverge across voltage classes, mechanical demands, and procurement channels. Each dimension carries distinct margin profiles and certification requirements that reshape competitive positioning.
Product Type:
After-sales service intensity varies sharply across product types, with flexible and multi-strand configurations demanding technical support for installation bending specifications and fatigue-life validation that commodity low-voltage products rarely require.
- Flexible:Multi-strand configurations with fine wire diameters below 0.1mm enable tight bend radii for robotics and renewable energy cabling. Wind turbine nacelle manufacturers in Germany and Japan specify these conductors for dynamic flexure zones where standard wire would fracture. China's SAMR GB standards for thermal cycling performance filter export-eligible suppliers from commodity producers.
- Multi-Strand:Complex twisting patterns with 19 to 61 individual wires deliver maximum flexibility for automotive harness applications. East Asian OEM networks specify these conductors for 800V EV powertrain architectures where vibration resistance is critical. The segment commands specification premiums over standard products.
- Low Voltage:Residential and commercial building wiring dominates volume, with BIS certification in India creating compliance thresholds that filter sub-scale domestic producers.
- High Voltage:Grid interconnection and substation applications require specialized insulation systems and corona-resistant designs for transmission-class performance.
By volume, Low Voltage leads. By growth pace, Flexible is ahead.
Application:
Cost tier stratification separates specification-intensive automotive and industrial segments from commoditized electrical wiring where price competition concentrates among merchant producers.
- Automotive:Electrification is compressing conductor specifications toward ultra-flexible stranded configurations that withstand thermal cycling across powertrain architectures. EV harness applications require multi-strand conductors with enhanced flexure resistance, creating specification premiums for automotive-grade copper products.
- Industrial Equipment:Motor leads, control panels, and machinery interconnection demand severe bend-radius flexibility that multi-strand configurations uniquely satisfy. Robotics manufacturers in Japan and Germany specify continuous-cast conductors with inline annealing for precision motion systems.
- Electrical Wiring:Building infrastructure sustains volume leadership across residential and commercial applications, with procurement consolidating toward integrated rod-cast fabricators.
- Telecommunications:Signaling and data transmission applications prioritize impedance stability and shielding effectiveness over current-carrying capacity.
By revenue concentration, Electrical Wiring dominates. By margin expansion, Automotive is climbing the fastest.
End User:
Customer type determines procurement sophistication, with OEMs and utilities imposing lot-traceability and carbon-intensity verification that merchant wire merchants struggle to match.
- OEMs:Automotive and industrial equipment manufacturers specify conductors with verified Scope 1-3 emissions data for EU CBAM compliance. Consolidated procurement is compressing supplier bases toward tier-one cable fabricators with integrated copper rod casting and global certification portfolios.
- Utilities:Grid operators in India and Southeast Asia mandate BIS or equivalent certification for conductor resistance and thermal cycling performance, extending approval timelines 12-18 months.
- Manufacturers:Cable fabricators and wire harness assemblers source rod and drawn wire based on oxygen-free copper purity exceeding 99.9% for premium applications.
- Contractors:Installation specialists prioritize availability and logistics reliability over metallurgical specifications for standard building wire applications.
By contract value, Utilities lead. By specification intensity, OEMs show the steepest expansion trajectory.
Installation Type:
Environmental exposure severity drives material selection and jacket compound formulation, with underwater and overhead installations demanding specialized corrosion resistance and mechanical strength.
- Outdoor:Aerial cable and exposed raceway applications face UV degradation and thermal expansion cycles that accelerate conductor fatigue. REACH and RoHS frameworks in Europe restrict hazardous substance content in insulated assemblies, forcing material selection changes throughout fabrication value chains.
- Underwater:Submarine power cables and marine applications require lead-sheathed or polymer-jacketed designs with specialized metallurgical knowledge for long-term corrosion resistance.
- Indoor:Climate-controlled environments permit standard PVC and XLPE insulation without extreme weatherproofing cost premiums.
- Overhead:Tensioned aerial installations balance conductivity against tensile strength, with aluminum substitution gaining ground where weight-driven economics favor non-copper solutions.
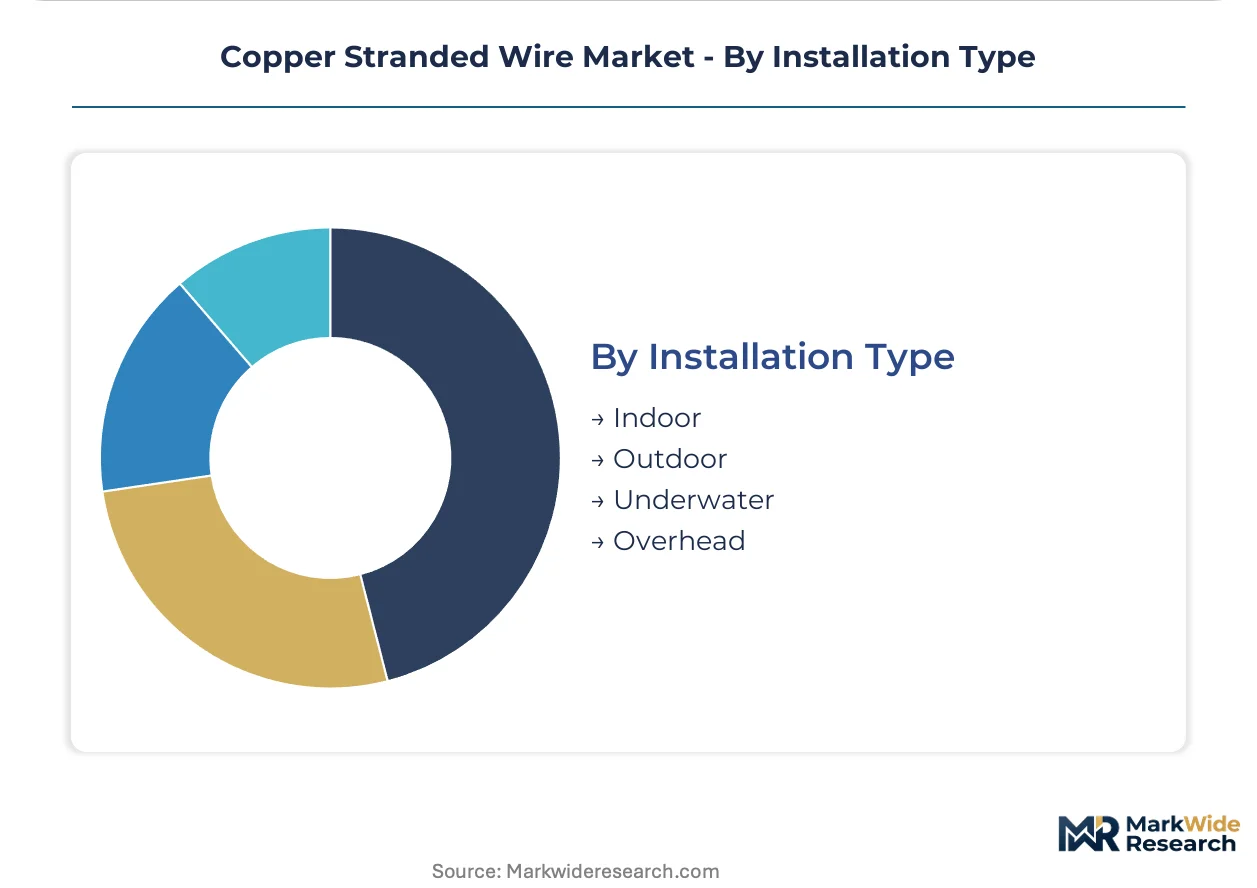
By installed length, Indoor leads. By project scale, Underwater is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Panama Canal expansion underwrites Latin America's logistics role for copper concentrate flows, while China's ultra-high-voltage grid interconnections anchor Asia-Pacific transmission demand.
China
Electric vehicle powertrain wiring and ultra-high-voltage grid buildouts drive conductor consumption. SAMR enforces GB standards for conductor resistance and thermal cycling performance that filter export-eligible manufacturers. Jiangsu and Zhejiang provinces concentrate continuous casting and rolling capacity for automotive-grade stranded wire.
India
Grid expansion under the National Infrastructure Pipeline and residential electrification sustain volume demand. BIS certification mandates for electrical cables extend 12-18 months, filtering sub-scale producers from utility tenders. Gujarat and Tamil Nadu are adding copper rod and wire capacity that redirects regional import dependency.
Germany
Offshore wind interconnection projects and automotive harness specifications pull high-flexibility multi-strand conductors. ECHA REACH and RoHS frameworks restrict hazardous substance content in insulated assemblies. Industrial clusters in Bavaria and Baden-Württemberg host precision cable fabricators serving 800V EV architectures.
United States
Data center power distribution and grid hardening investments expand medium-voltage stranded wire procurement. FERC interconnection standards and state-level renewable portfolio standards shape conductor specifications. Manufacturing corridors in Texas and the Southeast concentrate new cable plant investments.
Vietnam
Electronics manufacturing relocation from coastal China and export-oriented cable assembly drive wire demand. The country's national standards body aligns conductor certification with regional export market requirements. Northern industrial zones near Hanoi concentrate foreign-invested cable fabrication capacity.
Copper Stranded Wire Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in metallurgical processing. The vendor base compresses toward tier-one fabricators with integrated copper rod casting and global certification portfolios. Three archetypes dominate: integrated smelter-wire producers with captive concentrate access, specialized cable fabricators serving automotive OEM networks, and merchant wire merchants dependent on spot rod markets. Capacity expansion and backward integration into copper rod casting represent the dominant competitive vectors.
Among Mediterranean and South Asian fabricators, Prysmian S.p.A. and Polycab India Limited occupy positions reflecting distinct geographic anchoring strategies. Prysmian exemplifies the integrated European platform serving utility procurement cycles, while Polycab represents the backward-integrated domestic specialist capturing infrastructure buildouts. Sumitomo Electric Industries, Ltd. sits within the precision automotive tier, its name signaling East Asian specialization in conductor configurations for OEM harness networks.
| Leading Market Players |
|---|
| Southwire Company, LLC |
| alfanar Group |
| Prysmian S.p.A |
| Polycab India Limited |
| International Wire |
| NEXANS |
| Alan Wire Company |
| Sarkuysan |
| Sumitomo Electric Industries, Ltd. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Jiangsu and Zhejiang wire-drawing corridors is compressing spot-rod premiums and forcing merchant producers toward contract-based offtake structures. Utilization rates below threshold levels simultaneously erode supplier bargaining power and accelerate consolidation toward integrated rod-cast fabricators with captive concentrate access.
Pricing Analysis
Volume-discount tiering structures separate automotive-grade multi-strand conductors from commodity low-voltage building wire. Price differentiation rests on oxygen-free copper purity thresholds and SAMR GB certification status, with specification premiums widening as EV harness demand intensifies. Cost compression in standard products is intensifying because aluminum substitution gains ground in weight-sensitive aerial applications. Merchant wire merchants without captive smelter relationships exhibit the steepest price sensitivity, while tier-one cable fabricators serving OEM networks maintain pricing discipline through long-term supply agreements.
Supply Chain Analysis
Export-control regimes on advanced metallurgical equipment from Germany and Japan constrain oxygen-free copper smelting capacity expansion outside established integrated processors. Geographic supply concentration centers on Chilean and Peruvian concentrate operations, Chinese continuous-casting capacity, and German precision cable fabrication. Raw material dependencies draw from LME copper cathode, Chilean concentrate offtake, and specialized inline annealing equipment. Single-source vulnerability concentrates in Chilean mining operations exposed to labor disruption and water scarcity. Distribution runs through tier-one cable fabricators with integrated rod casting and global certification portfolios serving consolidated automotive OEM and utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through BIS, SAMR GB, and REACH certification timelines creates sticky supplier-customer relationships that resist price-based displacement.
For Market Incumbents: Pre-empt aluminum substitution threats by securing long-term concentrate offtake agreements that lock in cathode cost advantages against lightweight conductor competitors. Deepen backward integration into copper rod casting in Gujarat and Tamil Nadu to capture India's infrastructure buildout demand while BIS certification timelines filter sub-scale domestic challengers from utility tenders.
For New Entrants and Emerging Players: Vietnam's electronics manufacturing relocation from coastal China offers the most penetrable white-space target for export-oriented cable assembly operations serving regional automotive OEM networks. Target renewable energy cabling segments where severe bend-radius specifications for wind turbine nacelle wiring create technical barriers that favor specialized multi-strand configurations over commodity substitutes. Pursue joint venture structures with established concentrate traders to bypass captive smelter disadvantages.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated smelter-wire producers with long-term utility and automotive OEM supply agreements spanning multiple regulatory jurisdictions. Long-term viability favors fabricators with verified Scope 1-3 emissions data positioning for EU CBAM compliance. Target acquisition archetypes include precision automotive cable specialists serving 800V EV architectures. The signal to watch is carbon-border-adjustment implementation pace, which would accelerate competitive advantage for low-carbon-intensity copper producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rod Casting | Gujarat and Tamil Nadu capacity additions redirect India's import dependency toward domestic sourcing for grid expansion. |
| GB Standards Certification Investment | SAMR thermal cycling compliance filters export-eligible Chinese manufacturers from commodity wire suppliers. |
| Long-term Concentrate Offtake Agreement | Chilean mining relationships insulate integrated processors from LME price volatility compressing merchant margins. |
| Carbon Intensity Verification Program | Scope 1-3 emissions data positioning captures EU CBAM advantage as border adjustments reshape competitive tiers. |
| Continuous Casting Technology Licensing | Inline annealing capabilities collapse cost differentials between standard and high-flexibility automotive-grade conductors. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with wire harness procurement managers at automotive OEMs, cable fabrication plant engineers, copper concentrate traders, and utility tender evaluation officers. Secondary validation drew from SAMR GB standard filings, BIS certification registries, LME warehouse stock reports, and SEC 10-K disclosures by listed cable fabricators. Bottom-up segment sizing triangulated against top-down macro copper consumption forecasts.
Calibration anchored volume and value outputs to observed capacity utilization in Jiangsu and Zhejiang continuous-casting corridors alongside announced rod mill expansions in Gujarat and Tamil Nadu. Segmentation dimensions modeled included product type flexibility tiers, voltage class specifications, end-user procurement sophistication, and regional regulatory cluster alignment. CAGRs were derived from elasticity-adjusted demand projections across the analysis window, incorporating EV powertrain wiring content per vehicle and renewable energy interconnection buildout pipelines as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Chinese construction activity, Chilean mining labor stability, or LME copper price volatility bands would shift the trajectory. Forecasts reflect documented assumptions regarding SAMR enforcement continuity, BIS certification timeline stability, and EU CBAM implementation scope. Material shifts in aluminum alloy conductivity improvements or submarine cable demand surges would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Coaxial Cable Market
Cables
Usb Data Cable Market
Cables
Shipboard Cable Market
Cables
High Voltage Cables Market
Cables
North America Coaxial Cable Market
Cables
LASER Light Cables Market
Cables
Copper Cabling Systems Market
Cables
Military Cable Market
Cables
Low Voltage Cable Accessories Market
Cables
Sensor Cable Market
Cables
Solar Cable Market
Cables
Audio and Video Cables Market
Cables
Europe Cable Management Market
Cables
Aluminium Battery Cable Market
Cables
FFC/FPC Jumper Cables Market
Cables
Asia-Pacific Cable Joints Market