
 Class 1E Electric Cables Market | 2026-2036
Class 1E Electric Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Class 1E Electric Cables Market Insights
Aftermarket service revenue for legacy cable qualification and replacement is narrowing as original equipment manufacturers shift toward integrated lifecycle contracts. Nexans leverages its nuclear certification portfolio across European and North American utilities. Prysmian Group sustains R&D intensity in radiation-resistant compounds for reactor containment zones. RSCC Wire & Cable anchors its position through dominance in military-grade specifications that overlap with Class 1E nuclear requirements.
Class 1E electric cables are safety-related cables designed to perform specific functions during and following design basis events in nuclear power facilities, typically featuring fire-retardant, low-smoke, zero-halogen insulation systems rated for continuous radiation exposure up to 200 megarads. These cables ensure integrity of reactor shutdown systems, containment isolation, and emergency core cooling functions under loss-of-coolant accident conditions. Multi-core configurations command premium positioning due to complex shielding requirements for instrumentation circuits, while single-core products occupy higher volume tiers in power distribution applications. Nuclear power plant application segments lead absolute demand, though industrial automation represents the fastest-growing adjacent category as manufacturers adopt nuclear-grade reliability standards for critical process control.
The US Nuclear Regulatory Commission enforces 10 CFR 50 Appendix B quality assurance criteria that mandate traceable manufacturing records and environmental qualification testing for all safety-related cable installations. IEEE 383 and IEEE 1202 flame test standards govern vertical tray fire propagation performance, while IEC 60780-1 provides international baseline qualification for electrical equipment in nuclear safety systems. Stakeholders must monitor evolving small modular reactor design certifications, as novel coolant chemistries and compact containment geometries will demand revised cable insulation formulations and accelerated thermal aging protocols.
Market Dynamics
Small modular reactor certification timelines are compressing procurement cycles for safety-grade cable systems, forcing manufacturers to pre-qualify insulation formulations against novel coolant chemistries before design finalization.
Growth Catalysts
- 10 CFR 50 Appendix B Mandates:The US NRC's quality assurance criteria require traceable manufacturing records for all safety-related installations, creating captive demand for certified suppliers.
- Reactor Life Extension Programs:Operating license renewals at aging US facilities trigger wholesale cable replacement in containment zones and switchgear rooms.
- Radiation-Resistant Compound Advances:Cross-linked ethylene-tetrafluoroethylene formulations now withstand continuous exposure exceeding 200 megarads, extending service intervals.
Market Restraints
- Fluoropolymer Feedstock Concentration:Specialty resin supply concentrates among three global chemical producers, exposing cable manufacturers to price volatility.
- IEEE 383 Qualification Duration:Vertical tray flame testing and accelerated thermal aging protocols extend product development timelines to 24-36 months.
- Silicone Rubber Substitution:Lower-cost silicone-based insulation competes for non-safety applications in industrial automation adjacent markets.
Strategic Opportunities
- SMR Deployment Pipelines:NuScale and TerraPower design certifications in the United States will require compact cable routing solutions for reduced containment geometries.
- Industrial Automation Migration:Nuclear-grade reliability standards are penetrating chemical processing and semiconductor fabrication control systems.
- Integrated Lifecycle Contracts:Utilities are consolidating procurement under single-source agreements covering installation, environmental qualification, and decommissioning.
Industry Challenges
- Environmental Qualification Engineer Scarcity:Specialized expertise in radiation aging analysis and LOCA simulation is concentrated among retiring specialists at national laboratories.
- Legacy System Integration:Digital instrumentation cable retrofits must maintain electromagnetic compatibility with analog reactor protection systems installed in the 1970s-1980s.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Class 1E Electric Cables Market |
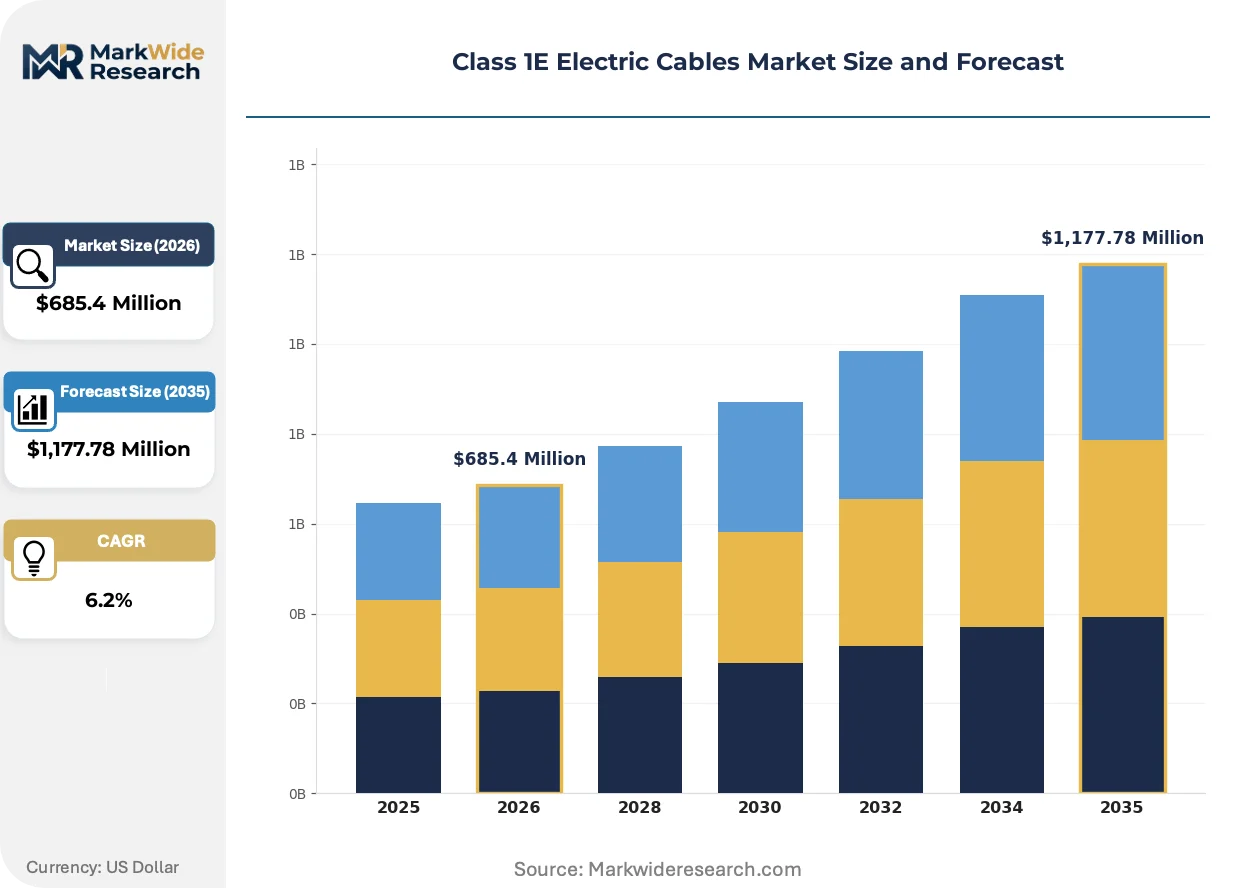
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Core, Multi-Core, Shielded, Unshielded Application: Nuclear Power Plants, Industrial Automation, High Voltage Equipment, Communication Systems Material: Copper, Aluminum, Tinned Copper, Polyurethane Installation Type: Indoor, Outdoor, Underground, Aerial |
| Companies Covered | Nexans, General Cable, RSCC Wire & Cable, Prysmian Group, Habia Cable, Kabelwerk Eupen, Southwire Company, Sumitomo Electric Industries, Tiankang, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Class 1E Electric Cables Market Trends and Innovations
Condition monitoring systems are penetrating cable infrastructure as utilities seek to replace time-based maintenance with predictive failure detection. Three developments are restructuring competitive positioning.
Silicone-free, low-smoke zero-halogen thermoset compounds are digitizing qualification workflows by embedding fiber-optic sensing elements directly into jacketing layers. US utilities deploying these smart cables at Vogtle and Plant Vogtle expansion sites receive real-time thermal and radiation dose data. This capability is digitizing asset management practices and compressing inspection intervals from annual physical surveys to continuous remote monitoring.
The US NRC's draft guidance on cable aging management programs is mandating expanded environmental qualification testing beyond original design basis events. License holders must now demonstrate insulation performance under extended thermal and radiation conditions. High-voltage power distribution cables in dry cask storage facilities face the most stringent new documentation requirements, driving qualification laboratory backlog.
Utility procurement departments are consolidating vendor panels and demanding turnkey qualification support rather than commodity supply. European and North American nuclear operators now specify cable suppliers who maintain in-house IEEE 383 testing capability and NRC audit history. This concentration is visible most acutely in US reactor life extension projects, where integrated lifecycle contracts are displacing discrete purchase orders for safety-related materials.
Class 1E Electric Cables Market Segmentation
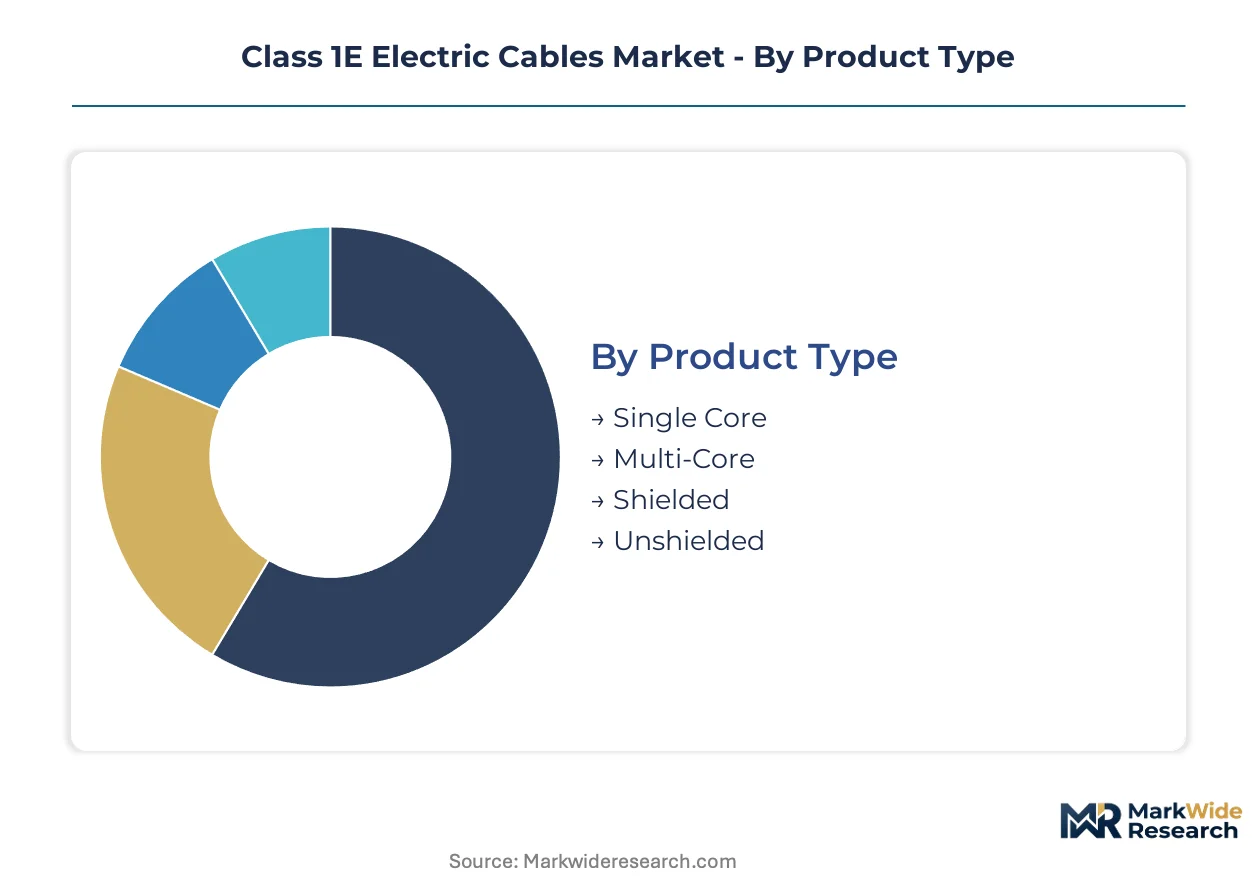
Segmentation in Class 1E electric cables reveals divergent replacement cycles across nuclear infrastructure. Product architecture and installation environment dictate qualification intensity, procurement lead times, and vendor certification requirements.
Product Type:
Replacement velocity varies sharply: multi-core configurations turn over fastest due to instrumentation complexity, while single-core power cables persist for decades.
- Multi-Core:Bundled conductor assemblies incorporate individual shielding layers and cross-talk isolation for reactor protection system circuits. Demand concentrates in containment zone instrumentation at US pressurized water reactors undergoing license renewal, where original 1970s-vintage cables face IEEE 383 requalification deadlines.
- Single Core:Unbundled power distribution conductors rated for medium-voltage feeder applications. These dominate replacement volumes at boiling water reactor facilities in the United States, where life extension programs prioritize switchgear room cable modernization over containment penetration replacements.
- Shielded:Electromagnetic interference protection for digital instrumentation retrofits.
- Unshielded:Cost-optimized configurations for non-safety power distribution in auxiliary systems.
Single Core dominates installed base. Multi-Core is where expansion concentrates.
Application:
End-use economics separate safety-grade qualification premiums from industrial reliability standards.
- Nuclear Power Plants:Safety-related installations demanding 10 CFR 50 Appendix B traceability and LOCA simulation testing. Procurement at US facilities concentrates on reactor life extension projects, where cable replacement in radiation zones triggers multi-year environmental qualification campaigns.
- Industrial Automation:Nuclear-grade reliability standards migrating into chemical process control and semiconductor fabrication. US chemical processors along the Gulf Coast are adopting IEEE 383 flame testing for critical safety instrumented systems, creating adjacent demand for pre-qualified cable suppliers.
- High Voltage Equipment:Dry cask storage and switchyard applications requiring extended thermal aging documentation.
- Communication Systems:Emergency response network cabling with lower radiation resistance thresholds.
Nuclear Power Plants command qualification premiums. Industrial Automation is climbing the fastest.
Material:
Conductor and insulation chemistry determines radiation tolerance and procurement cost structure.
- Copper:Baseline conductivity for safety-critical power and instrumentation circuits. Demand concentrates in US reactor containment applications, where original equipment specifications mandate oxygen-free high-conductivity copper to minimize corrosion-induced resistance shifts under radiation exposure.
- Tinned Copper:Tin-plated strands enhancing solderability and oxidation resistance for terminations in humid containment environments. Procurement is expanding at coastal US nuclear facilities, where salt air penetration accelerates bare copper degradation in outdoor electrical enclosures.
- Aluminum:Lightweight conductor for non-safety auxiliary power distribution.
- Polyurethane:Jacketing compound for flexible cable applications in robotics and maintenance equipment.
Copper dominates safety-grade specifications. Tinned Copper is gaining share fastest.
Installation Type:
Environmental exposure severity drives qualification protocol selection and replacement frequency.
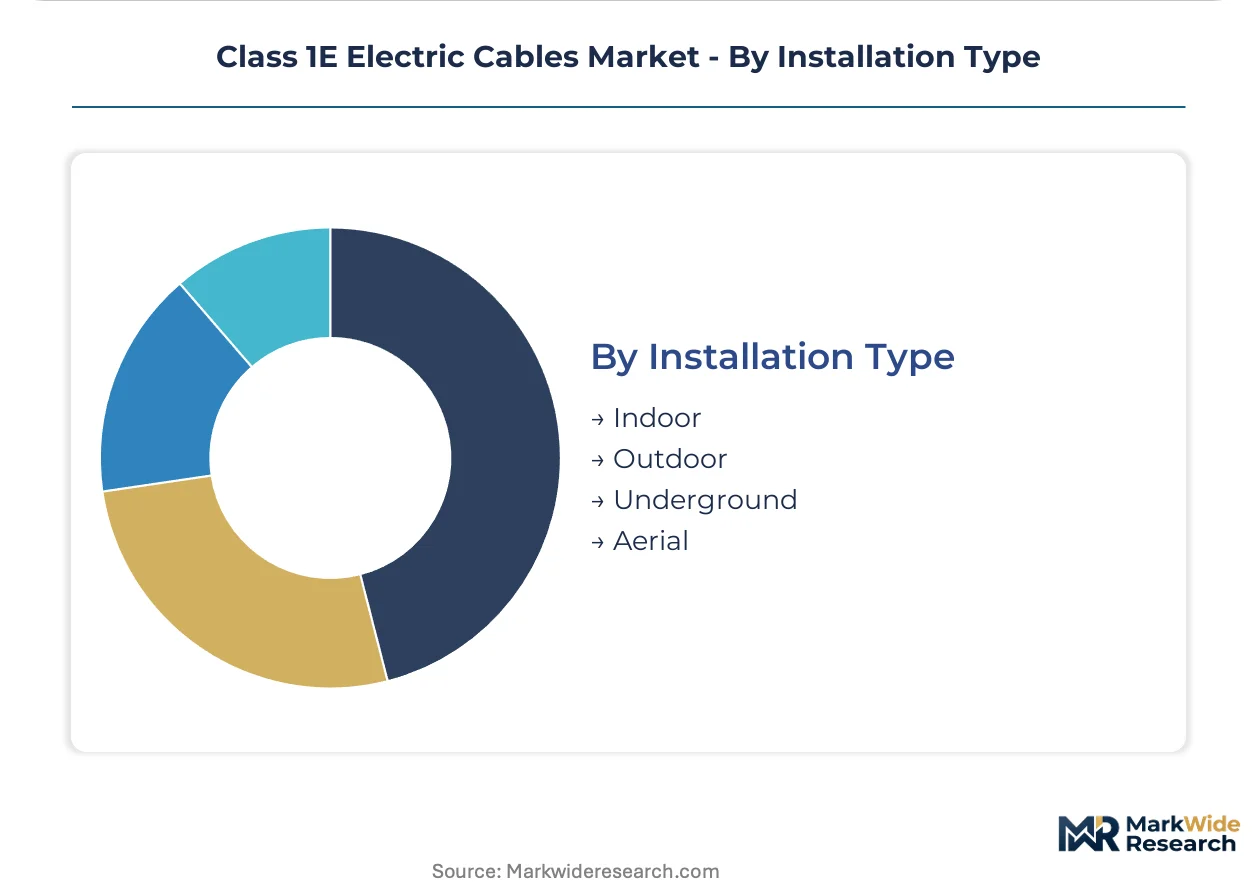
- Indoor:Controlled environment cabling in switchgear rooms and control centers. Demand concentrates in US life extension projects, where aging indoor installations face updated IEEE 1202 flame spread requirements that predate original construction.
- Underground:Direct-buried and duct-bank configurations for site power distribution. Procurement is accelerating at US nuclear facilities replacing 1960s-1970s vintage underground feeders, where moisture ingress has degraded insulation integrity beyond recoverable limits.
- Outdoor:Weather-resistant jacketing for yard lighting and auxiliary power.
- Aerial:Overhead routing for temporary and maintenance power applications.
Indoor dominates current replacement volumes. Underground is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for Class 1E electric cables diverge sharply by geography. The United States prioritizes reactor life extension cable replacement, while China concentrates procurement on new large-scale reactor builds, and European markets emphasize decommissioning-driven aftermarket services.
United States
The US Nuclear Regulatory Commission's 10 CFR 50 Appendix B mandates drive sustained procurement for safety-grade cable systems. Reactor license renewal programs at aging pressurized water and boiling water facilities trigger containment zone cable replacement cycles. Procurement concentrates in the Southeast, where Vogtle Units 3 and 4 expansion and existing fleet extensions at Duke Energy and Southern Company facilities sustain demand for IEEE 383-qualified suppliers.
China
State Power Investment Corporation and China National Nuclear Corporation accelerate procurement for new Hualong One reactor deployments. The National Energy Administration's nuclear safety supervision regulations tighten environmental qualification requirements for safety-related electrical equipment. Cable demand clusters in Fujian and Zhejiang provinces, where CNNC and CGN construct multiple third-generation reactor units requiring complete Class 1E cable infrastructure.
France
Électricité de France pursues cable replacement at 56 operating pressurized water reactors under ASN oversight. The French Nuclear Safety Authority's post-Fukushima stress test requirements mandate enhanced fire resistance qualification for existing installations. Industrial activity concentrates in the Nogent-sur-Seine and Gravelines reactor clusters, where Flamanville EPR completion and fleet-wide cable aging management programs sustain specialized supplier relationships.
Japan
Tokyo Electric Power and Kansai Electric restart procurement for safety-related cable systems at reactors cleared under Nuclear Regulation Authority revised standards. METI's strategic energy plan targets 20-22% nuclear generation share, requiring cable replacement at Kashiwazaki-Kariwa and Ohi facilities. Manufacturing demand centers in Fukui Prefecture, where multiple reactor restarts under NRA seismic and tsunami resilience protocols drive containment penetration cable upgrades.
South Korea
Korea Hydro & Nuclear Power advances cable replacement at Hanul and Hanbit reactor complexes under Nuclear Safety and Security Commission oversight. The government's energy transition roadmap maintains nuclear baseload, requiring continued safety-grade cable procurement for operating fleet maintenance. Supplier activity concentrates in Gyeongsang provinces, where KHNP operates 24 reactors and pursues Shin Hanul unit construction with complete Class 1E cable specifications.
Class 1E Electric Cables Market Competitive Landscape
Capability concentration sits with nuclear-certified specialists; scale advantage sits with diversified cable conglomerates. The market structures around three tiers: integrated energy infrastructure groups with dedicated nuclear divisions, specialized safety-grade cable manufacturers with IEEE 383 testing capability, and regional fabricators serving non-safety industrial applications. Dominant competitive moves include pre-qualification of insulation formulations against emerging small modular reactor coolant chemistries, and consolidation of utility procurement under integrated lifecycle service contracts spanning installation through decommissioning.
Among diversified European cable groups, Nexans and Prysmian Group occupy positions exemplifying the integrated infrastructure archetype, leveraging broad certification portfolios across nuclear and adjacent energy segments. RSCC Wire & Cable represents the specialized safety-grade tier, with military specification overlap providing qualification pathways into nuclear containment applications. These three anchors demonstrate how regulatory certification history and testing infrastructure ownership determine competitive positioning in procurement cycles governed by 10 CFR 50 Appendix B and IEEE 383 mandates.
| Leading Market Players |
|---|
| Nexans |
| General Cable |
| RSCC Wire & Cable |
| Prysmian Group |
| Habia Cable |
| Kabelwerk Eupen |
| Southwire Company |
| Sumitomo Electric Industries |
| Tiankang |
| Others |
Pricing and Supply Chain Analysis
Freight corridors connecting Belgian fluoropolymer resin producers to US Gulf Coast cable extrusion facilities transmit feedstock cost volatility directly into Class 1E cable pricing tiers, amplifying differentiation between IEEE 383-qualified specialists and commodity-grade suppliers serving adjacent industrial automation markets.
Pricing Analysis
Long-term offtake agreements dominate procurement between US nuclear utilities and certified cable manufacturers, compressing spot market liquidity while project-based contracting governs small modular reactor pre-qualification campaigns. Price differentiation rests on NRC 10 CFR 50 Appendix B certification tier and in-house IEEE 383 testing capability, with integrated lifecycle service bundles commanding substantial premiums over discrete cable supply. Cost compression in standard-grade industrial cables is intensifying as silicone rubber substitutes penetrate non-safety applications, while containment-rated multi-core configurations face inelastic demand from reactor life extension programs.
Supply Chain Analysis
Contract manufacturing for fluoropolymer compounding concentrates among three Belgian and German chemical producers, with cable extrusion and qualification testing distributed across US, French, and South Korean fabrication facilities. Raw material dependencies draw from ethylene-tetrafluoroethylene resin, oxygen-free high-conductivity copper rod, and radiation-stabilized filler compounds. Single-source vulnerability in specialty resin supply exposes manufacturers to force majeure disruptions. Distribution runs through direct utility procurement channels and nuclear-qualified distributor networks serving maintenance, repair, and operations demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in the gap between legacy reactor cable replacement cycles and emerging small modular reactor qualification requirements, as divergent thermal aging protocols and coolant chemistry specifications create distinct supplier tiers serving incompatible buyer archetypes.
For Market Incumbents: Pre-empt silicone rubber substitution in adjacent industrial automation markets by embedding IEEE 383 flame testing into standard product lines, while securing backward integration into fluoropolymer compounding to defend margin position against feedstock volatility. Prioritize in-house environmental qualification laboratory capacity to capture integrated lifecycle contract consolidation at US utilities. For New Entrants and Emerging Players: Small modular reactor supply chain pre-qualification campaigns represent the most penetrable entry point, as novel coolant chemistries reset incumbent certification advantages and create qualification backlogs at established testing facilities. Target NuScale and TerraPower engineering procurement organizations with compact cable routing solutions optimized for reduced containment geometries, leveraging partnerships with national laboratory aging specialists to compensate for limited NRC audit history. For Investors and Strategic Acquirers: NRC draft guidance on expanded cable aging management programs reshapes the acquisition landscape by elevating environmental qualification engineering capacity above manufacturing scale as the scarcest competitive asset. Long-term viability centers on suppliers with demonstrated LOCA simulation expertise and documented 10 CFR 50 Appendix B compliance history. The signal to monitor is IEEE 383 testing laboratory backlog duration, which indicates pricing power inflection for qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Qualification Against SMR Coolant Chemistries | NuScale and TerraPower design certifications require revised insulation formulations before construction licensing. |
| Integrated Lifecycle Contract Consolidation | Duke Energy and Southern Company procurement shifts displace discrete purchase orders with single-source agreements. |
| In-House IEEE 383 Testing Capability Investment | Vertical control over flame propagation and thermal aging protocols compresses product development timelines. |
| Fluoropolymer Compounding Backward Integration | Captive resin supply mitigates price volatility from Belgian and German chemical producer concentration. |
| Environmental Qualification Engineer Recruitment | Retiring national laboratory specialists concentrate radiation aging analysis expertise in scarce talent pools. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with nuclear utility procurement officers, cable manufacturer technical directors, NRC licensing specialists, and environmental qualification laboratory managers. Secondary validation drew from NRC 10 CFR 50 docket filings, IEEE standards documentation, utility integrated resource plans, and nuclear operator procurement disclosures. Bottom-up cable replacement volume estimates triangulated against top-down nuclear generation capacity projections.
Calibration against historical reactor life extension cable procurement patterns anchored forward projections across the analysis window. Segmentation modeling incorporated product architecture, installation environment, material chemistry, and regional regulatory framework dimensions. CAGRs derived from utility capital expenditure disclosures and reactor operating license renewal schedules. Industry-specific inputs included IEEE 383 qualification duration benchmarks and small modular reactor deployment pipeline status.
Practitioners should monitor NRC guidance finalization timelines, SMR design certification milestones, and fluoropolymer resin producer capacity announcements for early signals of forecast revision. Quarterly review of utility integrated lifecycle contract awards and environmental qualification laboratory backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Submarine Cables Market
Cables
Downhole Cables Market
Cables
Multi-Core Land High Voltage Underground Cable Market
Cables
Polyurethane Cable Market
Cables
US Medium Voltage Cable Accessories Market
Cables
Electric Submersible Cables (ESP) Market
Cables
Water Leak Sensing Cable Market
Cables
Medium Voltage Cables Accessories Market
Cables
Submarine Data Cables Market
Cables
Cable Fault Locator Market
Cables
Power and Signal Cables Market
Cables
FFC/FPC Jumper Cables Market
Cables
Cable Tray Market
Cables
Global Industrial Automation Cable Market
Cables
Medium Voltage Cables Market
Cables
Industrial Cable Reels Market