
 Pressure Transmitter Market | 2026-2036
Pressure Transmitter Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Transmitter Market Intelligence
The pressure transmitter supply base is consolidating around a widening gap between precision-engineered premium units and cost-optimized commodity devices. Emerson leverages its Rosemount technology lineage to dominate high-reliability process control installations. Honeywell sustains broad aerospace and industrial vertical coverage through integrated sensing platforms. Yokogawa anchors Asia-Pacific petrochemical demand with field-proven differential pressure architectures.
A pressure transmitter converts fluid or gas pressure into a standardized electrical signal, typically 4–20 mA or digital protocols such as HART and Foundation Fieldbus, enabling real-time process monitoring in hazardous and non-hazardous environments. Capacitive technology occupies the largest installed base due to proven stability in high-temperature hydrocarbon processing, while optical fiber sensing represents the fastest-expanding frontier as fiber Bragg grating designs penetrate subsea and nuclear applications where electromagnetic immunity is mandatory. Strain gauge transmitters retain entrenched positions in hydraulic power systems where cost sensitivity and mechanical ruggedness outweigh digital sophistication.
IEC 61508 and IEC 61511 functional safety standards compel manufacturers to certify SIL-rated devices for chemical processing and power generation, effectively raising engineering barriers for new entrants. The EPA in the United States enforces leak detection and repair protocols that mandate calibrated pressure instrumentation across refining and storage facilities. Stakeholders must weigh certification investment against modular platform architectures that can span both safety-critical and standard process tiers without duplicative development cycles.
Market Dynamics
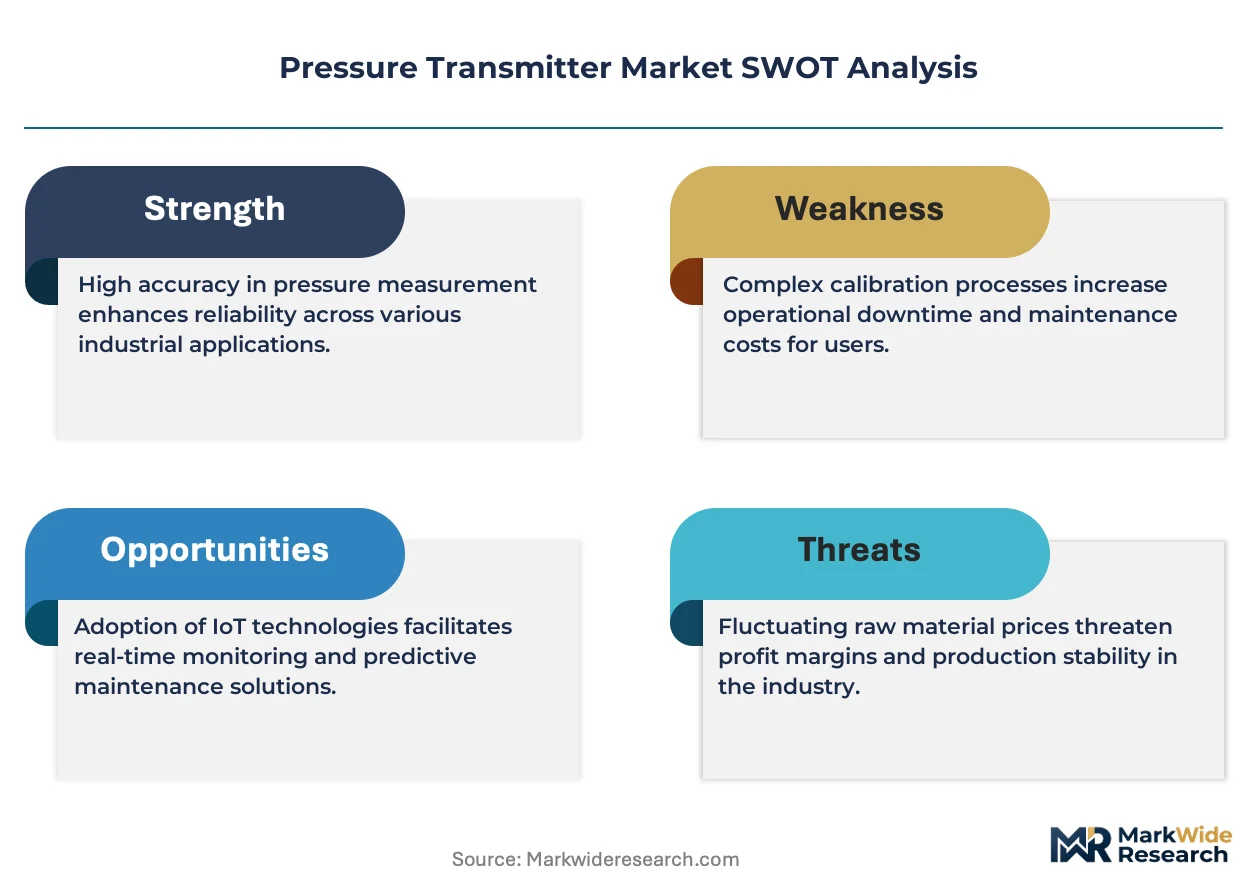
IEC 61508 functional safety certification requirements are bifurcating the pressure transmitter competitive landscape into SIL-rated precision suppliers and cost-optimized standard device manufacturers serving non-critical process monitoring.
Growth Catalysts
- EPA Leak Detection Mandates:Calibrated pressure instrumentation requirements across US refining and storage facilities are forcing systematic transmitter upgrades at wellheads and pipeline junctions.
- Optical Fiber Sensing:Fiber Bragg grating designs are penetrating subsea hydrocarbon extraction and nuclear containment monitoring where electromagnetic immunity eliminates conventional electronic alternatives.
- German Chemical Processing:BASF and Bayer facility modernization programs are driving differential pressure transmitter replacement cycles in Ludwigshafen and Leverkusen industrial clusters.
Market Restraints
- Stainless Steel Input Volatility:316L and Hastelloy price swings compress margin stability for manufacturers dependent on corrosion-resistant wetted parts.
- Single-Source Sensor Element Concentration:Japanese MEMS foundries control critical capacitive sensing die supply, creating geographic concentration risk for tier-two transmitter assemblers.
- IEC 61511 Compliance Friction:Extended SIL certification timelines delay product launches by 18-24 months, freezing engineering resources on legacy platform revisions.
Strategic Opportunities
- India Petrochemical Expansion:Reliance Jamnagar and Nayara Energy Vadinar complexes are commissioning greenfield process units requiring field-proven pressure measurement architectures.
- WirelessHART Convergence:Battery-powered transmitters eliminating conduit installation are opening brownfield retrofit opportunities in congested European chemical plants.
- EU Green Deal Carbon Accounting:Process efficiency mandates are elevating transmitter precision requirements for steam and compressed air system leak identification.
Industry Challenges
- Functional Safety Engineering Scarcity:SIL verification competency shortages constrain development velocity for safety-critical product lines.
- Legacy 4-20 mA Integration Complexity:Digital protocol migration demands dual-mode electronics that increase BOM cost without immediate customer willingness to pay.
- Subsea Pressure Hull Certification:API 6A and ISO 13628-4 qualification testing requires specialized hyperbaric facilities with 12-18 month queue times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Transmitter Market |
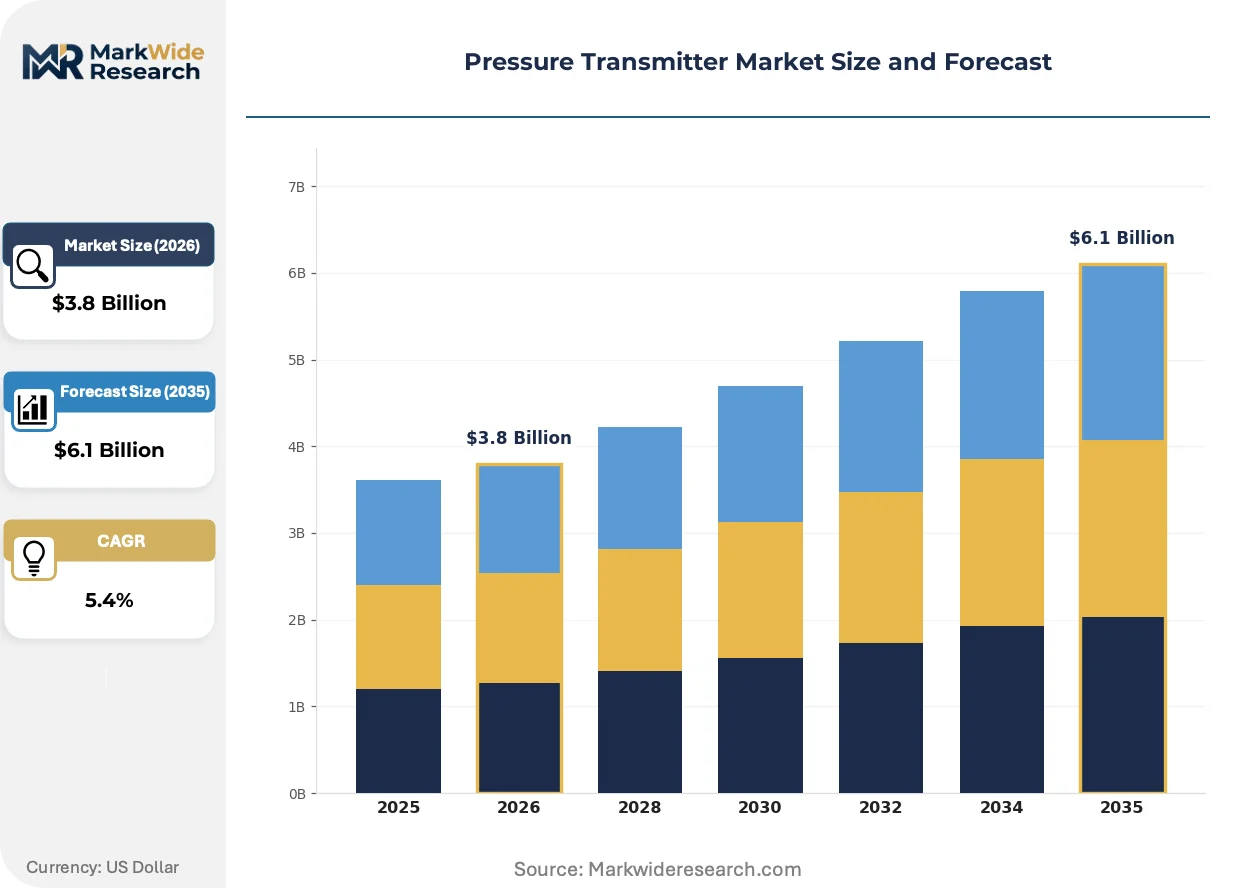
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Capacitive, Piezoelectric, Strain Gauge, Resonant Wire, Optical Fiber Application: Process Control, Hydraulic Systems, Pneumatic Systems, HVAC Monitoring, Water Treatment Industry Vertical: Oilfield Services, Chemical Processing, Aerospace, Food & Beverage, Power Generation Installation Type: Inline, Flanged, Sanitary, Threaded, Submersible |
| Companies Covered | Honeywell, Endress+Hauser, Emerson, Danfoss, Siemens, ABB, Schneider Electric, WIKA Instruments, Yokogawa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Transmitter Market Strategic Shifts & Innovations
Digital protocol migration and fiber-optic sensing architectures are compressing the technology lifecycle for conventional 4-20 mA transmitters while elevating cybersecurity and calibration traceability requirements.
Multivariable transmitters integrating differential pressure, static pressure, and temperature measurement into single housing architectures are electrifying custody transfer and flow computing applications. Oilfield services operators in the Permian Basin and North Sea are specifying these consolidated instruments to reduce piping penetrations and wiring terminations. The consolidation is compressing demand for standalone temperature and static pressure devices in greenfield installations.
REACH substance restrictions on mercury-containing pressure sensors are accelerating piezoresistive and capacitive technology substitution across European process industries. German chemical manufacturers face 2026 compliance deadlines for existing gauge inventory replacement. The regulatory pressure is elevating demand for hermetically sealed silicon sensing elements that eliminate fill fluid contamination risks.
Buyer consolidation among supermajor oil companies is compressing procurement cycles and unbundling after-sales service contracts from hardware supply agreements. ExxonMobil and Shell global framework agreements now specify multi-year calibration and spare parts provisioning as separately negotiable line items. The unbundling is visible most acutely in Middle Eastern downstream projects where EPC contractors face explicit service cost disclosure requirements.
Pressure Transmitter Market Segmentation
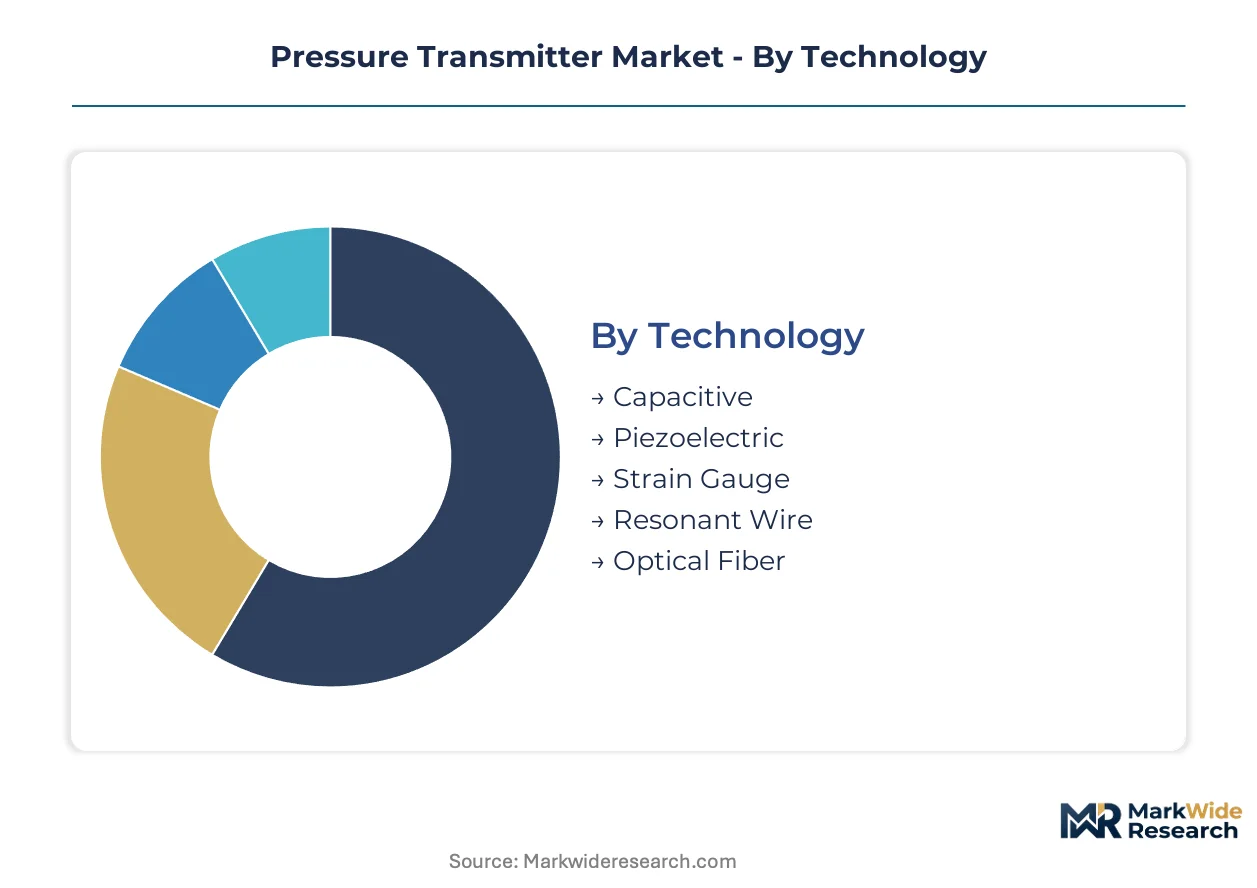
Pressure transmitter procurement patterns diverge sharply between safety-critical process industries and cost-sensitive utility applications. Technology selection, installation geometry, and certification requirements create distinct purchasing coalitions that manufacturers must address through modular platform strategies rather than universal product lines.
Technology:
Buyers in this category separate by environmental tolerance requirements and electromagnetic immunity needs.
- Capacitive:Ceramic or metallic diaphragm designs measure pressure through capacitance change between fixed and movable plates. Hydrocarbon processing facilities in the United States and Germany specify these for high-temperature catalytic reforming units where fill fluid stability determines measurement integrity.
- Optical Fiber:Fiber Bragg grating sensors encode pressure as wavelength shifts in embedded optical fibers. Subsea extraction installations off Norway and nuclear containment monitoring at French EDF facilities deploy these exclusively where electromagnetic interference would corrupt electronic signals.
- Piezoelectric:Quartz crystal elements generate charge proportional to dynamic pressure fluctuations. Aerospace test stands and combustion monitoring applications favor these for microsecond response times.
- Strain Gauge:Bonded metallic foil patterns detect elastic deformation in sensing diaphragms. Hydraulic power units in construction equipment and agricultural machinery specify these for mechanical ruggedness at low unit cost.
- Resonant Wire:Vibrating wire frequency shifts correlate with applied pressure in precision laboratory and custody transfer applications. Natural gas pipeline metering stations deploy these where 0.01% accuracy justifies premium positioning.
Volume sits with Capacitive; growth tilts toward Optical Fiber.
Application:
End-use concentration tracks process criticality and regulatory exposure intensity.
- Process Control:Continuous pressure monitoring in closed-loop automation systems demands SIL-rated transmitters with diagnostic coverage. Chemical processing clusters in Ludwigshafen and Houston specify these for reactor vessel protection where IEC 61511 compliance is mandatory.
- Hydraulic Systems:Mobile and industrial machinery fluid power monitoring prioritizes shock resistance and vibration immunity. Construction equipment OEMs in Germany and Japan source these for excavator and loader implement circuits.
- Pneumatic Systems:Compressed air distribution monitoring in manufacturing facilities requires cost-optimized devices without safety certification overhead. Automotive assembly plants across the United States deploy these for line pressure verification.
- HVAC Monitoring:Building automation differential pressure measurement for filter loading and airflow balancing. Commercial real estate developers in China specify these for green building certification compliance.
- Water Treatment:Filtration membrane and disinfection system pressure monitoring. Municipal utilities in the United States deploy these for EPA Clean Water Act compliance in drinking water distribution.
Process Control commands the revenue base; HVAC Monitoring is climbing the fastest as building electrification accelerates instrumentation retrofit cycles.
Industry Vertical:
Customer procurement sophistication correlates with safety regime stringency and unplanned shutdown costs.
- Oilfield Services:Wellhead, pipeline, and separation vessel monitoring in onshore and offshore extraction. Permian Basin operators and North Sea platforms specify API-certified devices with sour gas compatibility.
- Chemical Processing:Reactor, distillation column, and storage tank pressure measurement where toxic release prevention is paramount. BASF and Dow facilities demand SIL 2/3 rated transmitters with automated proof test capabilities.
- Aerospace:Flight test instrumentation and ground support equipment requiring miniature, lightweight packages. Boeing and Airbus test programs specify these for aerodynamic load measurement.
- Food & Beverage:Clean-in-place process monitoring with hygienic surface finishes. European dairy processors face EC 1935/2004 compliance deadlines for food contact materials.
- Power Generation:Steam turbine, boiler drum, and cooling system pressure measurement. Combined cycle gas turbine installations in the United States and Saudi Arabia require these for heat rate optimization.
Oilfield Services anchors current procurement volume; Food & Beverage shows the steepest expansion trajectory as traceability mandates tighten.
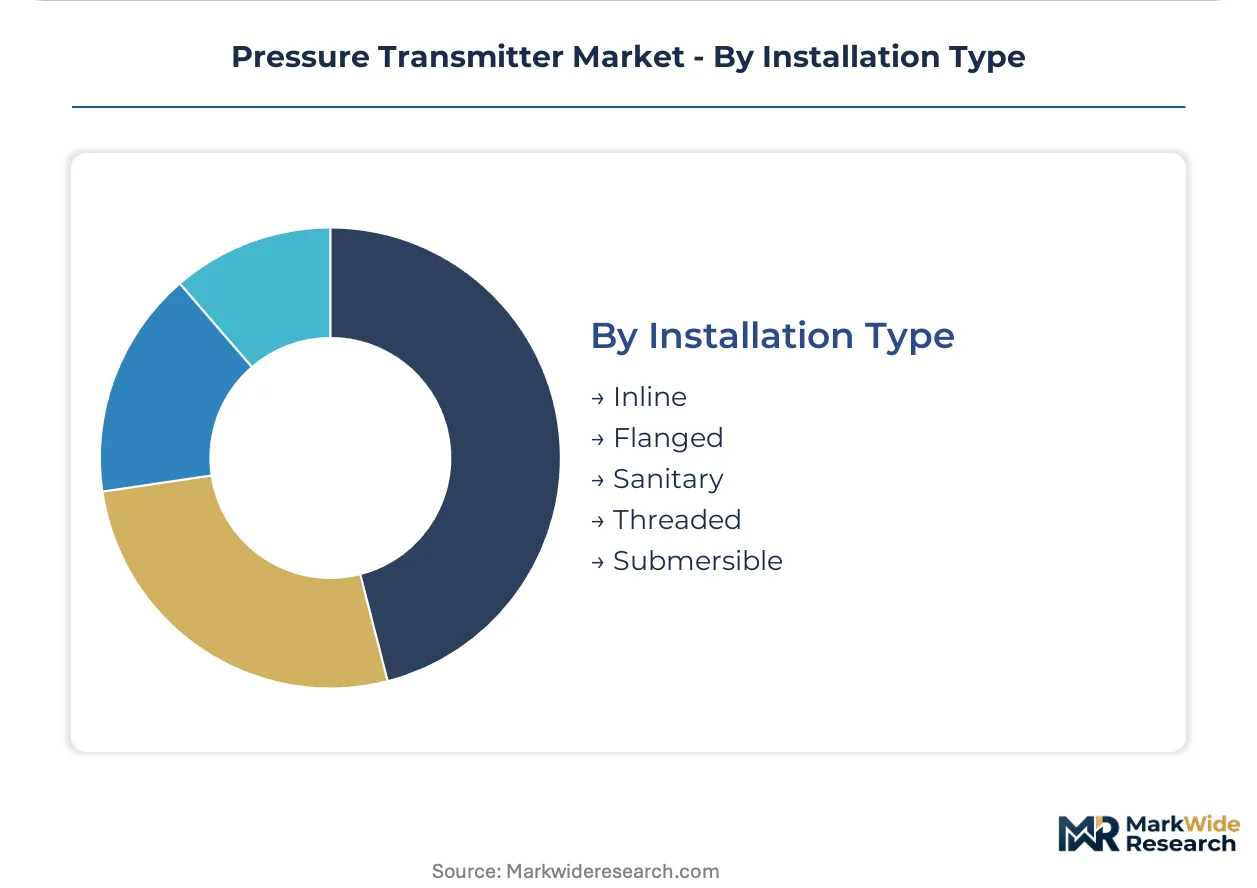
Installation Type:
Mounting geometry selection reflects piping configuration legacy and maintenance accessibility constraints.
- Flanged:ASME or DIN standard flange connections for high-pressure process lines in refining and petrochemical units. Reliance Jamnagar and Nayara Energy Vadinar complexes specify these for crude distillation unit feed lines.
- Inline:Compact wafer or threaded designs for space-constrained piping runs. Brownfield chemical plant retrofits in Europe favor these where existing conduit routing cannot accommodate additional junction boxes.
- Sanitary:Tri-clamp or dairy fitting configurations with surface finishes below 0.8 micrometers Ra. Pharmaceutical bioreactor installations demand these for US FDA 21 CFR Part 11 compliance.
- Threaded:NPT or BSP tapered connections for general industrial and utility applications. Water treatment and HVAC contractors specify these for lowest installed cost.
- Submersible:Sealed cable entry designs for level measurement in tanks, sumps, and boreholes. Wastewater treatment facilities deploy these for wet well level control.
Flanged dominates process industry procurement; Sanitary is gaining share fastest as biopharmaceutical manufacturing capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors the largest concentration of pressure transmitter procurement, with Permian Basin operators and Gulf Coast refiners driving systematic wellhead and pipeline instrumentation upgrades under EPA leak detection mandates.
United States
Permian Basin oilfield services operators are expanding transmitter deployments for wellhead pressure monitoring and pipeline junction surveillance. EPA leak detection and repair protocols mandate calibrated pressure instrumentation across refining and storage facilities nationwide. Houston and the Texas Gulf Coast industrial corridor host the densest concentration of end-user procurement activity for API-certified devices.
Germany
BASF and Bayer facility modernization programs in Ludwigshafen and Leverkusen are accelerating differential pressure transmitter replacement cycles. REACH substance restrictions on mercury-containing sensors are forcing 2026 compliance deadlines for existing gauge inventory replacement. The chemical processing clusters along the Rhine River represent Europe's most sophisticated demand for SIL-rated instrumentation with automated proof test capabilities.
China
Industrial automation investments are concentrating demand in coastal manufacturing zones and expanding petrochemical complexes. National standards under GB certification frameworks are elevating product qualification requirements for safety-critical installations. The Yangtze River Delta petrochemical corridor and Shandong Peninsula refining bases are commissioning greenfield process units requiring field-proven pressure measurement architectures.
India
Reliance Jamnagar and Nayara Energy Vadinar complexes are commissioning greenfield process units requiring extensive pressure instrumentation deployment. Central Electricity Authority regulations are tightening measurement accuracy requirements for power generation applications. The Gujarat petrochemical belt and Maharashtra industrial corridor are emerging as the fastest-expanding procurement zones for flanged and inline transmitter configurations.
Norway
North Sea subsea extraction platforms are specifying fiber Bragg grating optical sensors exclusively for electromagnetic immunity in deepwater installations. Norwegian Petroleum Directorate safety cases mandate redundant pressure monitoring for subsea wellhead integrity. The Stavanger-Bergen offshore engineering cluster is pioneering optical fiber sensing adoption for subsea hydrocarbon extraction where conventional electronics fail.
Pressure Transmitter Market Key Industry Players
Premium-margin players sit above commodity-margin players across functional safety certification tiers, with SIL-rated precision suppliers commanding pricing power while cost-optimized standard device manufacturers compete on volume and delivery speed. The competitive landscape bifurcates into three strategic archetypes: diversified industrial conglomerates with integrated sensing platforms, specialized instrumentation houses with deep process industry relationships, and regional fabricators serving utility and HVAC applications. Dominant competitive moves include modular platform architectures that span safety-critical and standard process tiers, and geographic expansion through local calibration and service center establishment.
Within the diversified industrial tier, Honeywell and Emerson exemplify integrated sensing platform strategies that sustain broad aerospace and industrial vertical coverage. Endress+Hauser occupies a position as a specialized instrumentation house with entrenched process industry relationships. These three anchors represent distinct competitive vectors: conglomerate scale and cross-selling capability, pure-play technical depth and application engineering intensity, and modular platform architectures that compress development cycles across certification grades.
| Leading Market Players |
|---|
| Honeywell |
| Endress+Hauser |
| Emerson |
| Danfoss |
| Siemens |
| ABB |
| Schneider Electric |
| WIKA Instruments |
| Yokogawa |
| Others |
Cost & Logistics Intelligence
316L stainless steel price volatility cascades through pressure transmitter manufacturing, compressing margins for corrosion-resistant wetted parts while amplifying pricing power for suppliers with captive metallurgical capabilities or long-term alloy contracts.
Pricing Analysis
Value-based pricing anchored to process uptime guarantees and unplanned shutdown avoidance separates premium SIL-rated suppliers from commodity assemblers. Certification grade and after-sales service bundling drive price differentiation, with IEC 61508 SIL 2/3 devices commanding substantial premiums over standard process transmitters. Cost compression in standard-tier electronics is intensifying because Japanese MEMS foundry concentration limits sourcing alternatives. Water treatment and HVAC contractors exhibit highest price sensitivity, while chemical processing clusters show lowest sensitivity due to failure-cost exposure.
Supply Chain Analysis
Refurbishment and remanufacturing flows for legacy 4-20 mA transmitters are expanding as European chemical plants extend asset life under REACH compliance deadlines. Manufacturing concentrates in Germany, Japan, and the United States for precision sensing elements, with China dominating enclosure fabrication and cable assembly. Critical dependencies include 316L/Hastelloy alloys, ceramic capacitive sensing dies, and hermetic sealing glass. Single-source vulnerability at Japanese MEMS foundries creates geographic concentration risk for tier-two assemblers. Distribution runs through authorized calibration centers and EPC contractor procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pressure transmitter market is becoming a vertical-integration race, with manufacturers pursuing backward integration into sensor element fabrication to escape MEMS foundry bottlenecks and secure margin control.
For Market Incumbents: Lock in sensor element supply through equity stakes in Japanese MEMS foundries or in-house silicon sensing die development to counter single-source vulnerability. Deepen IEC 61508 certification moats by automating proof test capabilities, raising engineering barriers for emerging competitors attempting SIL-rated product entry.
For New Entrants and Emerging Players: Optical fiber sensing architectures offer a technology-first wedge into subsea hydrocarbon extraction and nuclear containment monitoring where electromagnetic immunity eliminates incumbent electronic alternatives. Target Norway's Stavanger-Bergen offshore engineering cluster and French EDF facility modernization programs. Pursue direct EPC contractor relationships to bypass entrenched distributor networks.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized instrumentation houses with deep process industry relationships in Germany's Rhine River chemical corridor, where REACH compliance deadlines are forcing systematic gauge replacement. Long-term viability hinges on modular platform architectures spanning safety-critical and standard process tiers. Monitor EPA enforcement intensity around leak detection mandates as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Fabrication | Captive supply of capacitive sensing dies eliminates Japanese foundry dependency for tier-one manufacturers. |
| SIL Certification Automation | Automated proof test capabilities differentiate suppliers serving BASF and Dow chemical processing clusters. |
| Optical Fiber Sensing Scale-Up | Fiber Bragg grating manufacturing expansion captures Norwegian Petroleum Directorate subsea safety case requirements. |
| WirelessHART Platform Convergence | Battery-powered transmitter lines open brownfield retrofit opportunities in congested European chemical plants. |
| Calibration Service Center Geographic Expansion | Local service presence in India's Gujarat petrochemical belt addresses Reliance and Nayara Energy procurement frameworks. |
Research Approach
Independent corroboration across instrumentation procurement managers at chemical processing facilities, aftermarket service directors at oilfield services operators, and EPC contractor technical specifications teams underwrites the qualitative findings. Primary interviews with plant engineers, OEM procurement leads, and calibration center operators combined with secondary validation from IEC certification databases, EPA enforcement records, and customs trade data. Bottom-up transmitter shipment analysis triangulates against top-down process industry capital expenditure patterns.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include technology type, application criticality, industry vertical, and installation geometry, with additional modeling of certification tier adoption curves. CAGRs derive from fitted growth curves calibrated to historical replacement cycle data and regulatory mandate implementation timelines. Forecast inputs incorporate wellhead deployment rates in the Permian Basin and REACH substance restriction compliance deadlines.
Several conditions sit outside the modeled scope, including abrupt alloy price spikes, trade restriction imposition on sensor element exports, and accelerated wireless protocol migration beyond projected adoption curves. Forecasts reflect documented assumptions about regulatory enforcement continuity and OEM procurement consolidation trajectories. Practitioners should monitor EPA leak detection audit frequency and German chemical plant modernization program announcements for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Digital Automation Temperature Regulator Market
Sensors and Controls
Thermistor Temperature Sensor Market
Sensors and Controls
Fiber Bragg Grating Sensor Market
Sensors and Controls
60GHz Radar Evaluation Kit Market
Sensors and Controls
Distance Measurement Sensor Market
Sensors and Controls
Smart Sensor Market
Sensors and Controls
Magnetometer Market
Sensors and Controls
Optical Chemical Sensor Market
Sensors and Controls
Europe Advanced CO2 Sensor Market
Sensors and Controls
US Temperature Sensors Market
Sensors and Controls
On-Board Magnetic Sensors Market
Sensors and Controls
North America Acoustic Sensors Market
Sensors and Controls
Quantum Sensors Market
Sensors and Controls
Asia-Pacific Nano Radiation Sensors Market
Sensors and Controls
Europe MEMS and Sensors Market
Sensors and Controls
MEMS Inertial Sensors Market