
 Industrial Cable Reels Market | 2026-2036
Industrial Cable Reels Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Cable Reels Market Analysis
Contractors deploying portable power distribution on remote job sites is unwinding historical reliance on fixed electrical infrastructure among electrical utilities. Reelcraft Industries leverages captive manufacturing in the Midwest to sustain rapid fulfillment for North American contractor channels. Hannay Reels Inc. anchors its position through deep specialization in custom-engineered reels for harsh-environment applications. Schill GmbH & Co. dominates European supply through precision aluminum fabrication and direct OEM relationships with German construction equipment builders.
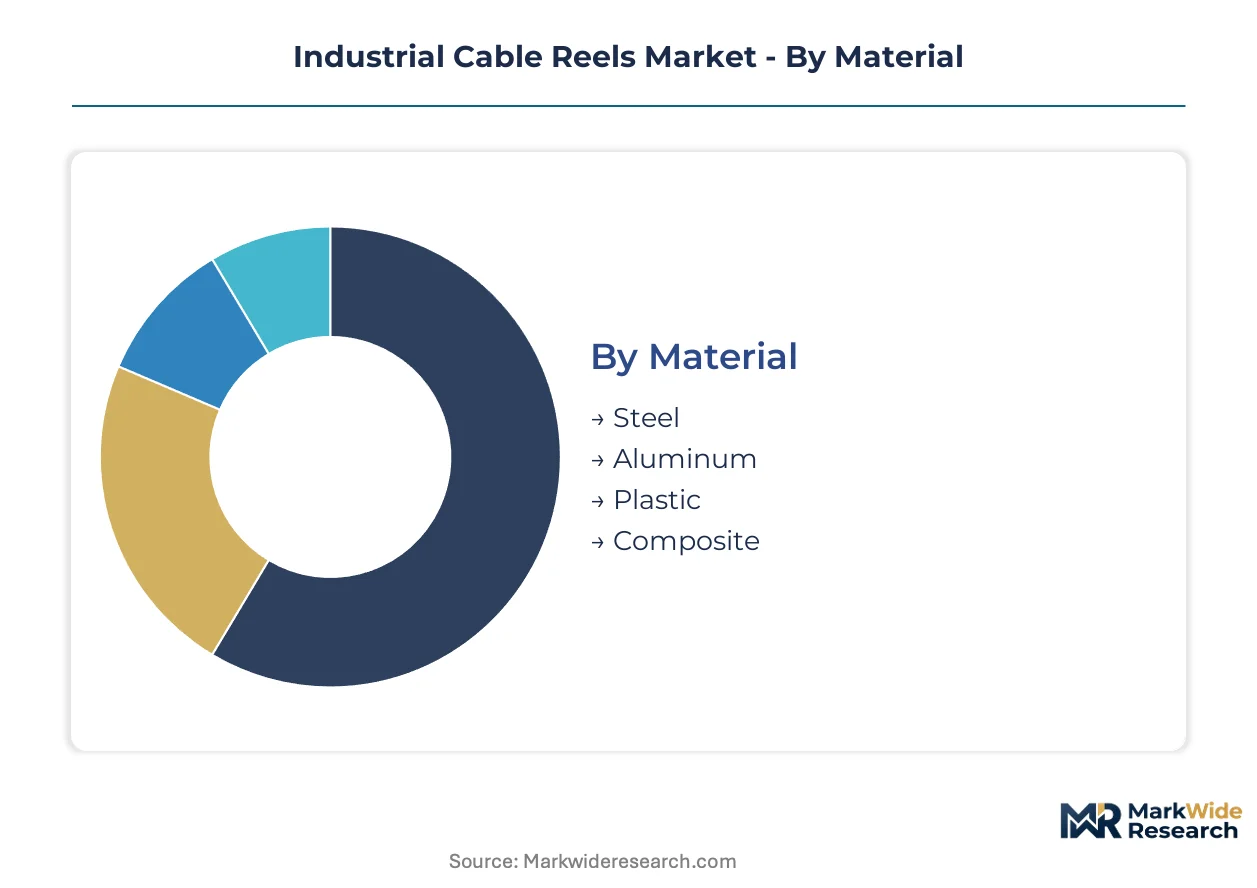
Industrial cable reels are mechanical devices engineered to store, deploy, and retrieve flexible electrical cables or hoses through spring-driven, motor-driven, or hand-cranked mechanisms, typically constructed with flanged drums rated for specific bending radii and tensile loads to prevent conductor fatigue. Their primary industrial purpose centers on maintaining cable integrity across repeated extension and retraction cycles in mobile equipment, temporary power systems, and automated machinery where unmanaged cable slack creates safety hazards and operational downtime. Steel reels command the largest material share due to load-bearing requirements in mining and heavy construction, though composite segments are gaining fastest as weight reduction becomes critical for aerial work platforms and robotic cable carriers. Medium and large size categories generate the dominant revenue pool, while extra-large reels for bulk material handling conveyors and ship-to-shore cranes capture the highest per-unit margins.
FCC equipment authorization rules govern electromagnetic compatibility for motorized reel systems deployed in US industrial facilities, while OSHA electrical safety standards mandate cable protection protocols that directly specify reel deployment in construction zones. REACH substance restrictions and CE marking requirements under the EU Machinery Directive shape material selection and export market access for European and Asia-Pacific manufacturers. Stakeholders must monitor evolving MEE enforcement patterns in China and assess whether backward integration into composite drum molding or aluminum die-casting offers superior margin protection against volatile steel input costs.
Market Dynamics
Mobile equipment electrification across mining and construction sectors is compressing replacement cycles for heavy-duty cable management systems as fleet operators prioritize uptime reliability over capital longevity.
Growth Catalysts
- MEE enforcement of GB standards:China's Ministry of Ecology and Environment is tightening industrial electrical safety certifications, forcing facility upgrades that incorporate motorized reel systems for compliant cable deployment.
- Australian mining fleet expansion:Pilbara and Bowen Basin operators are adding autonomous haul trucks and electric shovels that require robust spring-driven reels for trailing cable management in high-cycle operations.
- Composite drum adoption:Aerial work platform manufacturers are specifying carbon-fiber reinforced polymer reels to reduce boom weight and extend hydraulic reach without sacrificing load capacity.
Market Restraints
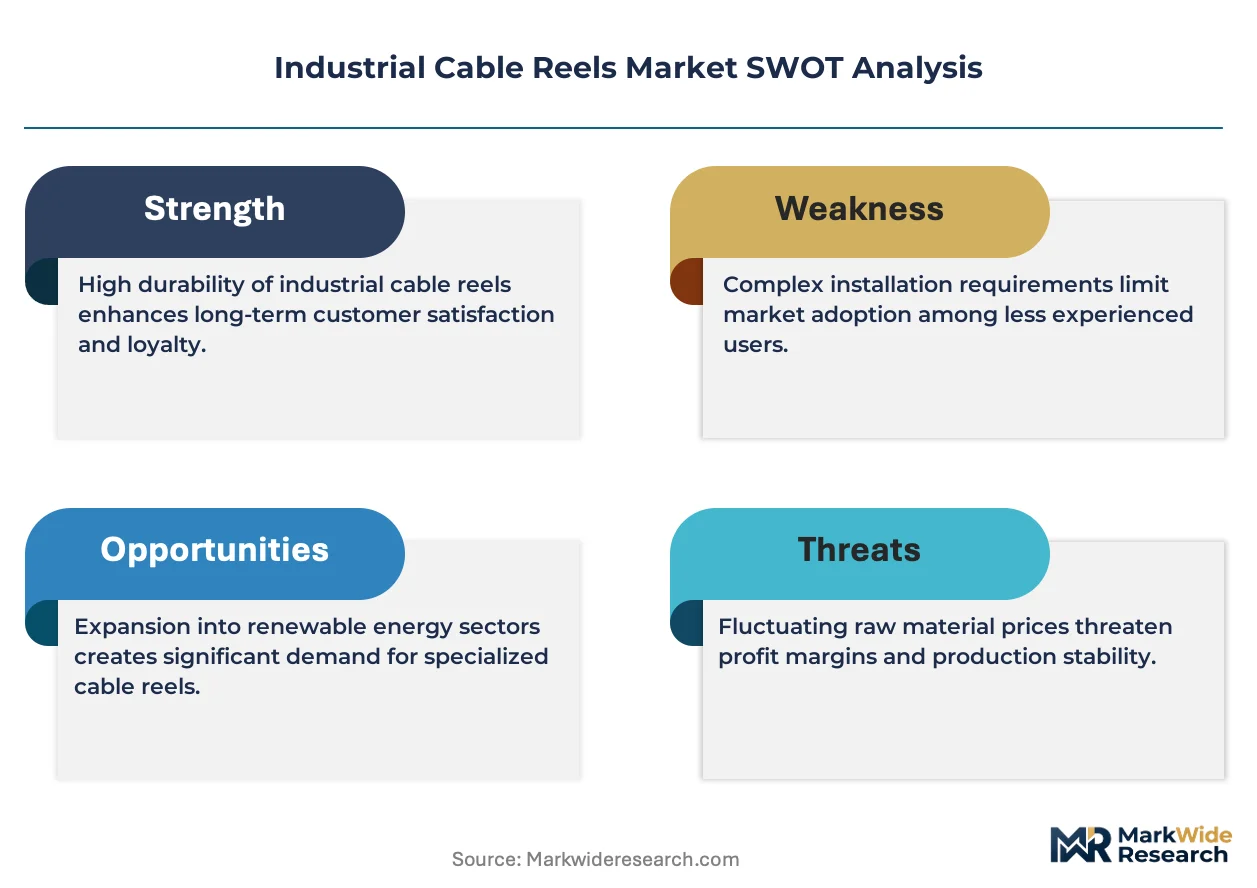
- Steel price volatility:Hot-rolled coil input costs swing with energy-intensive European smelter output, compressing margins on standard-duty steel reel production lines.
- REACH substance restrictions:ECHA limitations on chrome VI plating and certain polymer stabilizers force reformulation of corrosion-resistant drum coatings, extending qualification timelines for EU-bound exports.
- Manual reel substitution:Simple hand-cranked wooden and plywood cable storage remains entrenched in price-sensitive agricultural and small-scale construction segments, capping premium motorized system penetration.
Strategic Opportunities
- Chilean copper mine electrification:Codelco and Antofagasta Minerals are converting diesel truck fleets to trolley-assist and battery-electric systems, creating demand for extra-large reels capable of managing 1,000+ meter trailing cables.
- Ship-to-shore crane automation:Port operators in Hamburg and Rotterdam are retrofitting automated stacking cranes with intelligent motor-driven reels that integrate with terminal operating systems for predictive maintenance.
- EU Green Deal industrial retrofit incentives:Member state recovery funds are subsidizing energy-efficient manufacturing equipment upgrades, including cable management systems that reduce conductor resistance losses in automated production lines.
Industry Challenges
- Multi-standard certification complexity:Manufacturers must simultaneously satisfy FCC Part 15 for US motorized reels, CE Machinery Directive for EU access, and evolving GB standards for China, stretching engineering resources across divergent test protocols.
- Legacy system integration friction:Retrofitting intelligent reels with torque sensors and position feedback into existing PLC architectures requires custom interface development, delaying project commissioning and inflating installation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Cable Reels Market |
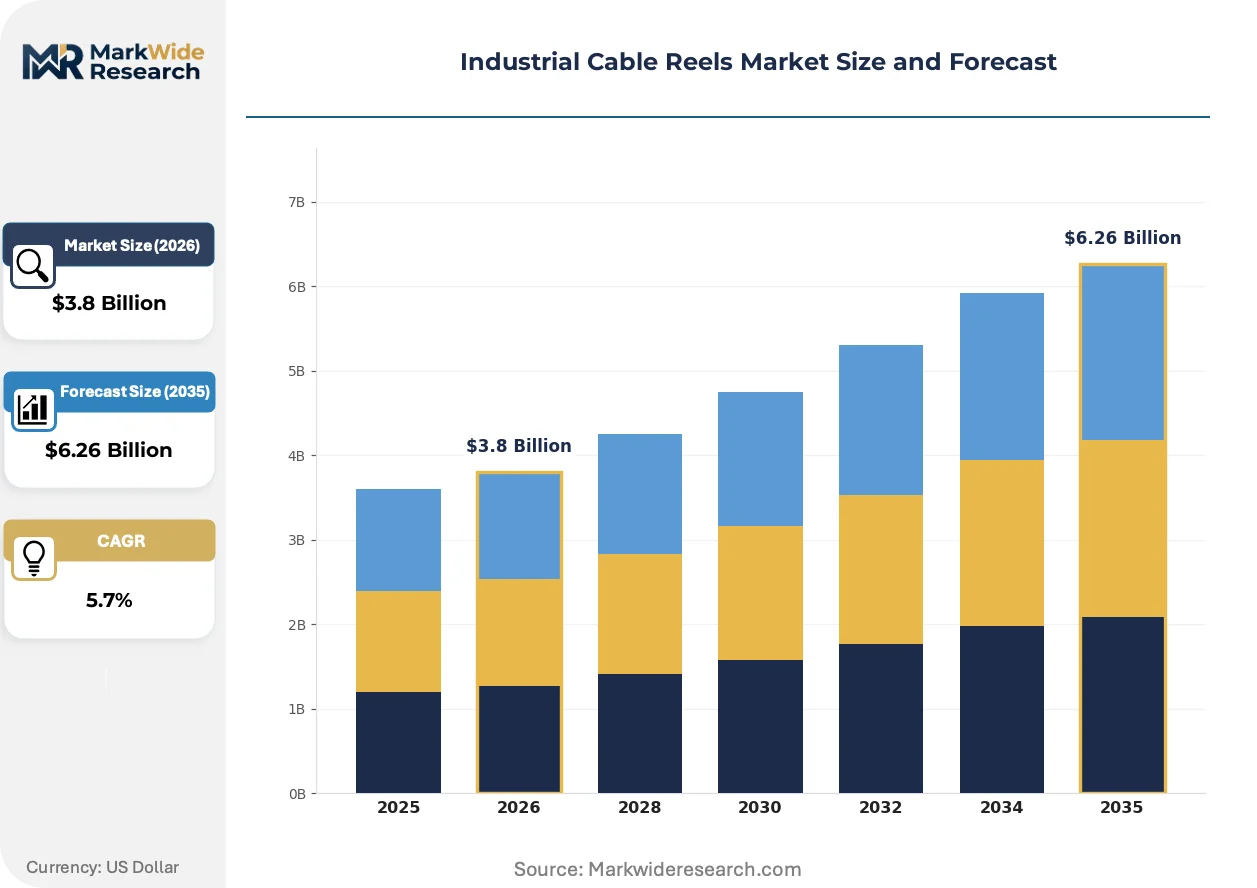
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Steel, Aluminum, Plastic, Composite Size: Small, Medium, Large, Extra Large Application: Construction, Manufacturing, Electrical, Mining End User: Contractors, Electrical Companies, OEMs, Aftermarket Providers |
| Companies Covered | Hannay Reels Inc., Reelcraft Industries, Duro Manufacturing, LLC, Ericson Manufacturing, Ely Road Reel Co, LTD., United Equipment Accessories, Inc., Coxreels, Schill GmbH & Co., Princetel, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Cable Reels Market Emerging Trajectories
Digital sensing and predictive maintenance capabilities are migrating from premium crane reels down to mid-tier construction and manufacturing applications, compressing the traditional technology tiering that once separated commodity and engineered products.
Carbon-fiber composite drum construction is fragmenting the historical steel-aluminum material hierarchy in industrial cable reels. The technology enables 40-60% weight reduction versus steel equivalents while maintaining bending radius integrity for high-flex cables. Mining truck OEMs in Australia and Chile are specifying composite reels for trailing cable systems where unsprung mass directly impacts fuel consumption and tire wear.
REACH substance restrictions and the EU Machinery Directive's updated safety requirements are forcing material substitutions across European supply chains. Chrome VI plating bans have pushed manufacturers toward zinc-nickel and thermal spray aluminum coatings for corrosion protection in marine and chemical environments. German construction equipment builders are now requiring full material declarations from reel suppliers to satisfy downstream CSRD reporting obligations.
Equipment-as-a-service contracting is displacing outright purchase in North American contractor channels. Rental fleet operators and job site service providers are demanding reels with telematics-enabled usage tracking to support outcome-based billing models. This shift concentrates procurement authority with national rental chains and integrated equipment lessors, compressing distributor margins and favoring suppliers with captive service networks.
Industrial Cable Reels Market Segmentation
Cable reel procurement channels diverge sharply by material grade and duty rating. OEMs source through direct mill relationships for fleet-scale orders, while contractors and aftermarket providers rely on distributor networks for rapid field replacement.
Material:
Steel and aluminum flow through mill-direct channels to heavy-equipment builders, while composites and plastics reach aerial work platform manufacturers through specialized component distributors.
- Steel:Hot-rolled coil construction delivers maximum tensile load capacity for mining trailing cables and ship-to-shore crane systems. Australian Pilbara operators specify steel reels for autonomous haul truck fleets where conductor fatigue resistance determines maintenance intervals.
- Composite:Carbon-fiber reinforced polymer drums achieve 40-60% weight reduction versus steel equivalents while maintaining bending radius integrity. Aerial work platform OEMs in Germany's Ruhr cluster specify these for boom-mounted cable carriers where unsprung mass limits hydraulic reach.
- Aluminum:Precision die-cast flanged drums from European fabricators serve automated manufacturing lines requiring corrosion resistance without steel's magnetic interference.
- Plastic:Injection-molded polypropylene reels address light-duty temporary power distribution for small contractors in price-sensitive agricultural segments.
Steel dominates installed base. Composite is where expansion concentrates.
Size:
Cost tiers separate commodity replacement reels from engineered systems carrying predictive maintenance premiums and telematics integration.
- Medium:Spring-driven mechanisms rated for 500-2,000 extension cycles serve construction site temporary power distribution. North American electrical contractors favor these for rapid deployment on remote job sites unwinding fixed infrastructure dependence.
- Large:Motor-driven drums with torque sensors manage high-flex cables for automated manufacturing lines. German steel producers in the Ruhr cluster specify these for continuous casting operations where downtime costs exceed reel replacement value.
- Small:Hand-cranked portable units address maintenance access in confined industrial spaces where motorized systems prove oversized.
- Extra Large:Custom-engineered drums exceeding 3-meter flange diameter manage 1,000+ meter trailing cables for Chilean copper mine trolley-assist conversions.
Medium and large categories anchor revenue volume. Extra large captures highest per-unit margins through engineering customization.
Application:
Volume concentration tracks mobile equipment electrification intensity across extraction and heavy construction sectors.
- Mining:Heavy-duty trailing cable systems for autonomous haul trucks and electric shovels require spring-driven reels rated for high-cycle operations in abrasive environments. Australian Bowen Basin operators compress replacement cycles to prioritize uptime reliability.
- Construction:Portable power distribution reels for remote job sites demand rapid deployment capabilities and OSHA-compliant cable protection protocols.
- Manufacturing:Automated production lines specify motor-driven reels with position feedback integration to reduce conductor resistance losses.
- Electrical:Utility infrastructure maintenance requires weather-resistant reels for overhead line servicing and substation upgrades.
Mining commands premium pricing through duty specifications. Manufacturing is climbing the fastest as energy-efficiency retrofits accelerate.
End User:
Customer type determines procurement authority concentration versus fragmentation across channel structures.
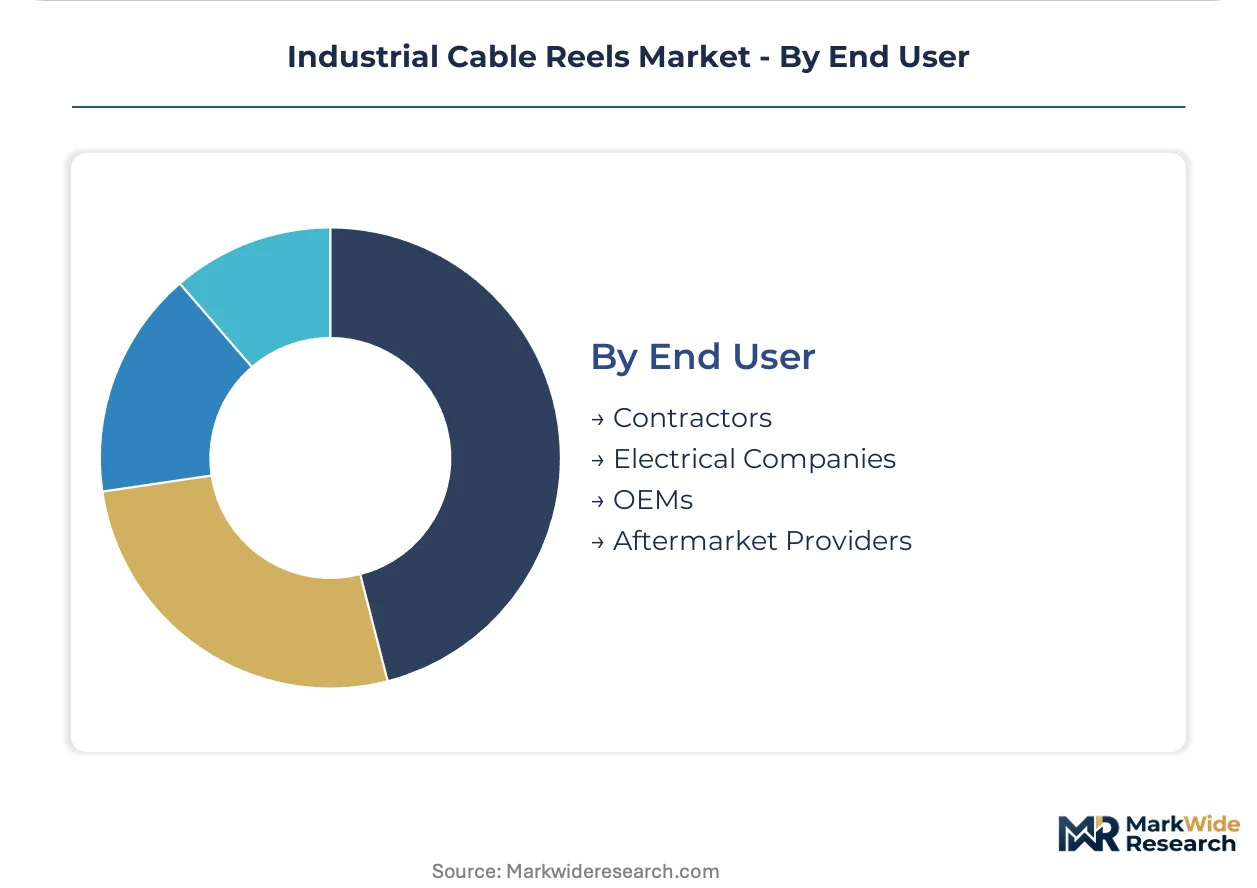
- OEMs:German construction equipment builders maintain direct mill relationships for aluminum and steel reel supply, requiring full material declarations for downstream CSRD reporting compliance.
- Contractors:North American job site service providers are shifting toward equipment-as-a-service models, demanding telematics-enabled usage tracking from rental fleet suppliers.
- Electrical Companies:Utility-scale procurement favors standardized medium-duty reels through national distributor networks with rapid fulfillment capabilities.
- Aftermarket Providers:Independent service networks source replacement reels through regional distributors, prioritizing inventory breadth over technical specification depth.
OEMs dominate engineered system demand. Contractors represent the fastest channel shift as rental consolidation concentrates buying power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara iron ore rail network and the Port of Hamburg container terminals anchor two distinct demand poles for heavy-duty cable management systems. Chile's Escondida copper concentrate pipeline and Australia's Bowen Basin coal rail corridors create comparable infrastructure-dependent procurement cycles. China's Yangtze River manufacturing belt completes the geographic spread.
United States
OSHA electrical safety standards mandate cable protection protocols for construction zone reel deployment. FCC Part 15 equipment authorization governs electromagnetic compatibility for motorized systems in industrial facilities. Reelcraft Industries leverages Midwest captive manufacturing to sustain rapid fulfillment for North American contractor channels.
Germany
CE marking requirements under the EU Machinery Directive shape material selection and export market access. ECHA REACH substance restrictions force reformulation of corrosion-resistant drum coatings for marine environments. Steel and composite reel procurement for automated manufacturing lines concentrates in the Ruhr industrial cluster.
China
MEE enforcement of GB standards tightens industrial electrical safety certifications, forcing facility upgrades. The Ministry of Ecology and Environment mandates motorized reel systems for compliant cable deployment in heavy industry. Yangtze River Delta manufacturing hubs drive procurement for automated production line retrofits.
Australia
Pilbara and Bowen Basin mining operators expand autonomous haul truck and electric shovel fleets requiring robust spring-driven reels. The country's national electrical safety regulator enforces trailing cable management standards for high-cycle operations. Perth-based equipment distributors coordinate fleet-scale orders for mobile electrification projects.
Chile
Codelco and Antofagasta Minerals convert diesel truck fleets to trolley-assist and battery-electric systems. The national mining regulator mandates trailing cable integrity standards for open-pit electrification. Santiago-based procurement offices coordinate extra-large reel specifications for 1,000+ meter cable management.
Industrial Cable Reels Market Vendor Landscape
Concentration sits with regional specialists commanding direct OEM relationships and captive manufacturing footprints. The vendor base splits between mill-direct steel fabricators serving mining fleets and precision aluminum die-casters supplying automated manufacturing lines. Three archetypes dominate: German engineering specialists with full material declaration capabilities, Midwest US manufacturers with rapid fulfillment networks, and composite drum innovators targeting weight-critical aerial applications. Competitive moves center on backward integration into aluminum die-casting and strategic partnerships with national rental chains.
Among US-based fabricators, Reelcraft Industries and Hannay Reels Inc. exemplify divergent positioning strategies. Reelcraft anchors the rapid-fulfillment archetype through Midwest captive manufacturing. Hannay occupies the custom-engineering tier for harsh-environment applications. Coxreels represents the construction-focused specialist segment. Schill GmbH & Co. sits within the European precision fabrication tier, leveraging direct OEM relationships with German equipment builders.
| Leading Market Players |
|---|
| Hannay Reels Inc. |
| Reelcraft Industries |
| Duro Manufacturing, LLC |
| Ericson Manufacturing |
| Ely Road Reel Co, LTD. |
| United Equipment Accessories, Inc. |
| Coxreels |
| Schill GmbH & Co. |
| Princetel, Inc. |
| Others |
Supply Flow & Price Mechanics
Carbon-fiber composite drum substitution for steel equivalents is redrawing procurement geography toward German precision fabricators and Chinese polymer compounders while compressing margin structures on legacy hot-rolled coil supply lines. This material transition simultaneously elevates engineering premiums for weight-critical aerial applications and erodes commodity pricing power among undifferentiated steel reel producers serving mining fleets.
Pricing Analysis
Volume-discount tiering structures separate fleet-scale OEM direct contracts from distributor-sourced aftermarket replacement. Three-tier pricing stratifies across premium motorized reels with telematics integration, standard spring-driven mechanisms for construction contractors, and economy hand-cranked units for agricultural segments. Price differentiation hinges on GB standard certification grade for China-bound exports and volume scale for Pilbara mining fleet orders. Cost compression in standard-duty steel reels is intensifying because European smelter energy costs transmit directly to hot-rolled coil input pricing. Electrical contractors sourcing through national rental chains exhibit highest price sensitivity, while German construction equipment builders demonstrate lowest sensitivity due to specification-locked OEM relationships.
Supply Chain Analysis
Strait of Malacca transit congestion threatens just-in-time delivery schedules for carbon-fiber prepreg feedstock bound for German composite drum fabricators. Manufacturing concentration centers on Germany for precision aluminum die-casting, China for steel flange stamping and polymer molding, and the US Midwest for rapid-turn contractor channel fulfillment. Raw material dependencies encompass hot-rolled coil from European mills, carbon-fiber tow from Japanese and South Korean producers, and aluminum billet from Norwegian smelters. Single-source vulnerability concentrates in specialized torque sensor supply for intelligent motor-driven reels. Distribution runs through mill-direct OEM partnerships for fleet-scale orders and national distributor networks for construction aftermarket demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through rental fleet consolidation in North America and direct mill relationships among German construction equipment builders, fragmenting historical distributor intermediation. This consolidation compresses margin capture for suppliers lacking captive service networks or telematics-enabled outcome-based contracting capabilities.
For Market Incumbents: Shield margin position through backward integration into aluminum die-casting for Ruhr cluster OEM supply and carbon-fiber drum molding for aerial work platform specifications. Composite reel specialists threaten steel incumbents in weight-critical mining applications. Certification investment in evolving MEE GB standard compliance represents the priority defensive lever for China market retention. For New Entrants and Emerging Players: Anchor in Chilean copper mine electrification white space where Codelco and Antofagasta Minerals seek extra-large reel engineering partnerships for 1,000+ meter trailing cable systems. Australian autonomous haul truck fleet expansion presents secondary penetration opportunity. Equipment-as-a-service contracting capabilities offer differentiated go-to-market positioning against transactional incumbent models. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed US contractor channel specialists lacking composite manufacturing capabilities or European regulatory compliance infrastructure. Long-term viability over a five-to-ten year horizon favors suppliers with dual steel-composite production flexibility and direct OEM relationships with German construction equipment builders. Monitor MEE enforcement intensity in China as inflection indicator for certification-driven replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composite Drum Molding | Captures 40-60% weight reduction premiums from Australian mining OEMs specifying carbon-fiber reels. |
| Telematics-Enabled Service Contracting | Aligns procurement authority with consolidated North American rental chains demanding usage-tracked billing models. |
| GB Standard Certification Investment | Secures facility upgrade-driven demand from Yangtze River Delta manufacturers facing MEE enforcement tightening. |
| Direct OEM Partnership Expansion | Locks in aluminum reel supply relationships with German construction equipment builders requiring CSRD material declarations. |
| Chilean Mining Electrification Engineering | Positions for extra-large reel specifications from Codelco trolley-assist conversion projects. |
Methodological Framework
Initial hypotheses were tested against primary input from maintenance directors at Australian mining operations, OEM procurement teams for German construction equipment builders, aftermarket service heads at North American rental chains, and plant engineers in China's Yangtze River Delta manufacturing belt, then refined against customs trade data for steel and aluminum reel shipments, SEC filings from listed industrial equipment suppliers, ECHA REACH substance restriction updates, and MEE regulatory enforcement bulletins. Bottom-up demand modeling from end-use application volumes was triangulated with top-down supply-side capacity assessments.
Variance-decomposition across the projection horizon isolates volume drivers by material grade, size category, and end-user channel against price elasticity assumptions for steel input cost pass-through. Segmentation dimensions encompass duty rating, drum construction material, deployment mechanism type, and geographic regulatory cluster. CAGRs were derived from installed base replacement cycle compression rates and fleet electrification intensity metrics. Industry-specific forecast inputs include autonomous haul truck deployment schedules in the Pilbara and Bowen Basin, and EU Green Deal industrial retrofit subsidy allocation patterns.
Decision-makers should treat outputs as directional under assumptions of sustained MEE enforcement intensity in China and stable European smelter output; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as Chilean mining electrification timelines and composite material cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Submarine Cable System Market
Cables
Cable Material Market
Cables
High-Temperature Superconducting Cables Market
Cables
Data Center Wire and Cable Market
Cables
Premise Cable Market
Cables
Solar Cable Market
Cables
Global Cable Gland Market
Cables
Multi-Core Land High Voltage Underground Cable Market
Cables
Patch Cable Market
Cables
Class 1E Electric Cables Market
Cables
Multicore Cables Market
Cables
Copper Cable Market
Cables
Cable Lugs Market
Cables
India Optic Fiber Cable and Accessories Market
Cables
Electric Vehicle Unshielded HV Cables Market
Cables
GCC Cable Accessories Market