
 Cable Trunking Market | 2026-2036
Cable Trunking Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Trunking Market Insights
India's manufacturing expansion is reconfiguring regional supply dynamics for cable management infrastructure. Atkore International leverages its North American steel conduit expertise to compete in high-specification industrial installations. Schneider Electric SE sustains broad portfolio coverage across flush-mounted and surface-mounted systems for commercial buildings. Legrand dominates European specification channels through its cable management heritage and installer relationships.
Cable trunking comprises enclosed rigid or semi-rigid channels, typically fabricated from galvanized steel, aluminum, PVC, or halogen-free compounds, designed to protect, route, and organize electrical power and data cables within buildings and industrial facilities. Wall thickness, ingress protection ratings, and fire performance classes determine suitability for specific environmental conditions and regulatory jurisdictions. Metal trunking retains primacy in heavy industrial and power distribution applications where electromagnetic shielding and mechanical impact resistance justify material cost premiums. PVC and flexible variants capture share in telecommunications and residential retrofits where weight reduction and installation speed outweigh thermal performance requirements.
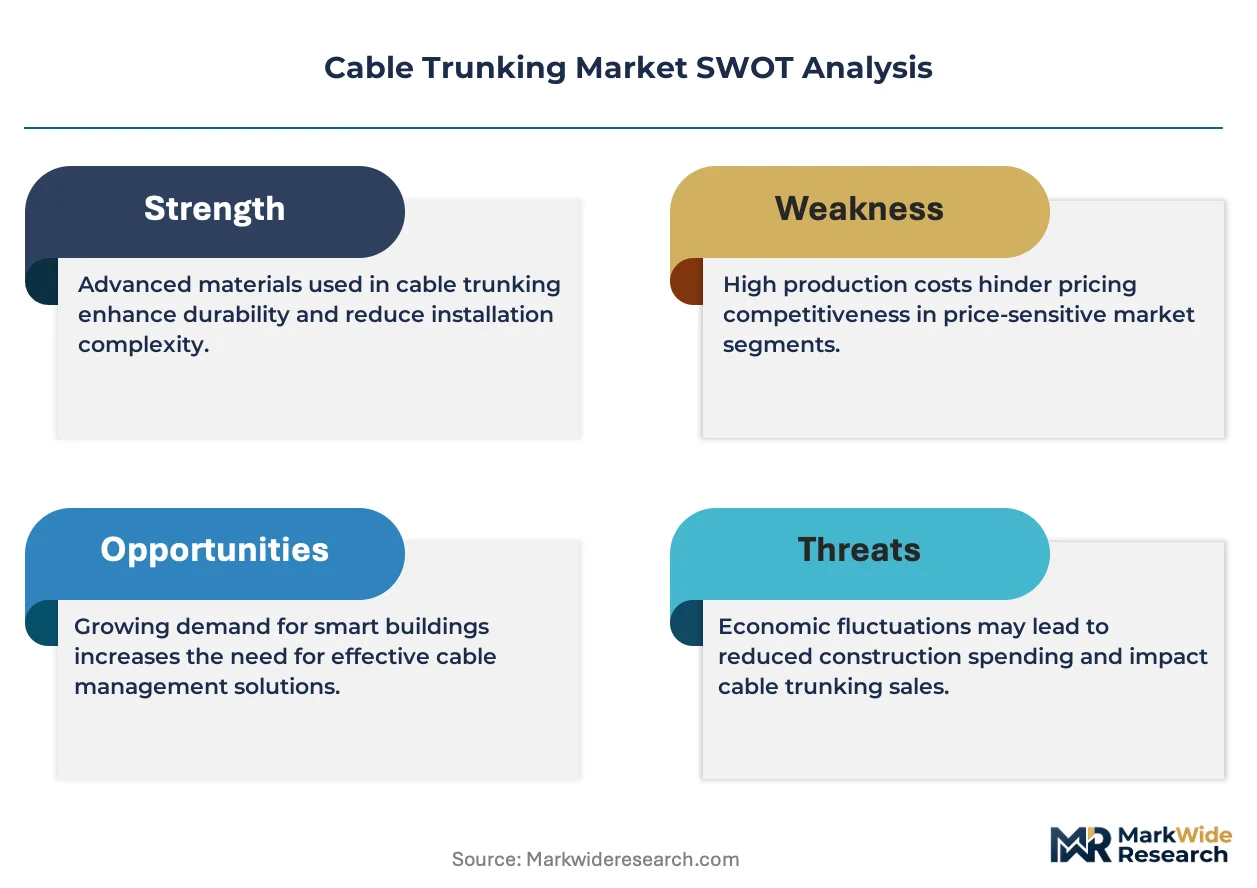
FCC Part 15 electromagnetic compatibility requirements and NFPA 70 National Electrical Code provisions govern product performance in US installations, while IEC 61439 and EN 50085 standards define European safety and construction benchmarks. India's BIS certification mandates and CEA technical standards for electrical infrastructure create compliance thresholds that filter import competition and shape local manufacturing investments. Stakeholders must evaluate how evolving fire safety regulations and copper price volatility will alter material substitution patterns and procurement strategies across end-use segments.
Market Dynamics
Data center construction across Southeast Asia is compressing specification cycles for cable management infrastructure, forcing manufacturers to reconcile IEC 61439 compliance with accelerated project timelines.
Growth Catalysts
- IEC 61439 Harmonization:European standard convergence is eliminating technical barriers between national markets, enabling cross-border procurement for multinational industrial installations.
- India Industrial Corridor Build-outs:Dedicated freight corridors and manufacturing zones under CEA technical standards are generating concentrated demand for heavy-gauge metal trunking systems.
- Halogen-Free Compound Adoption:Low-smoke zero-halogen formulations are displacing conventional PVC in commercial specifications where NFPA 70 egress requirements apply.
Market Restraints
- Copper Price Volatility:Raw material cost swings compress margin buffers for distributors holding inventory of metal-intensive trunking systems.
- Import Dependency in Southeast Asia:Regional manufacturing capacity gaps for high-specification galvanized steel channels create lead time vulnerability.
- Electromagnetic Shielding Limitations:PVC and aluminum alternatives fail to meet FCC Part 15 emissions containment requirements in heavy industrial power distribution.
Strategic Opportunities
- Indonesia Data Center Pipeline:Hyperscale facility commitments in Batam and Jakarta are creating first-mover advantage for flexible trunking system suppliers.
- CEA Grid Modernization Mandates:Indian central utility directives for smart substation infrastructure are opening specification channels for integrated cable management.
- Modular Prefabrication Convergence:Off-site construction methods are compressing on-site installation windows, favoring quick-connect trunking architectures over field-fabricated alternatives.
Industry Challenges
- BIS Certification Timelines:Indian standards body approval processes for imported trunking systems extend market entry cycles by 8-14 months.
- Installer Skill Fragmentation:Shortage of certified technicians for IP-rated sealing and fire-stopping integration creates quality liability exposure on complex projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Trunking Market |
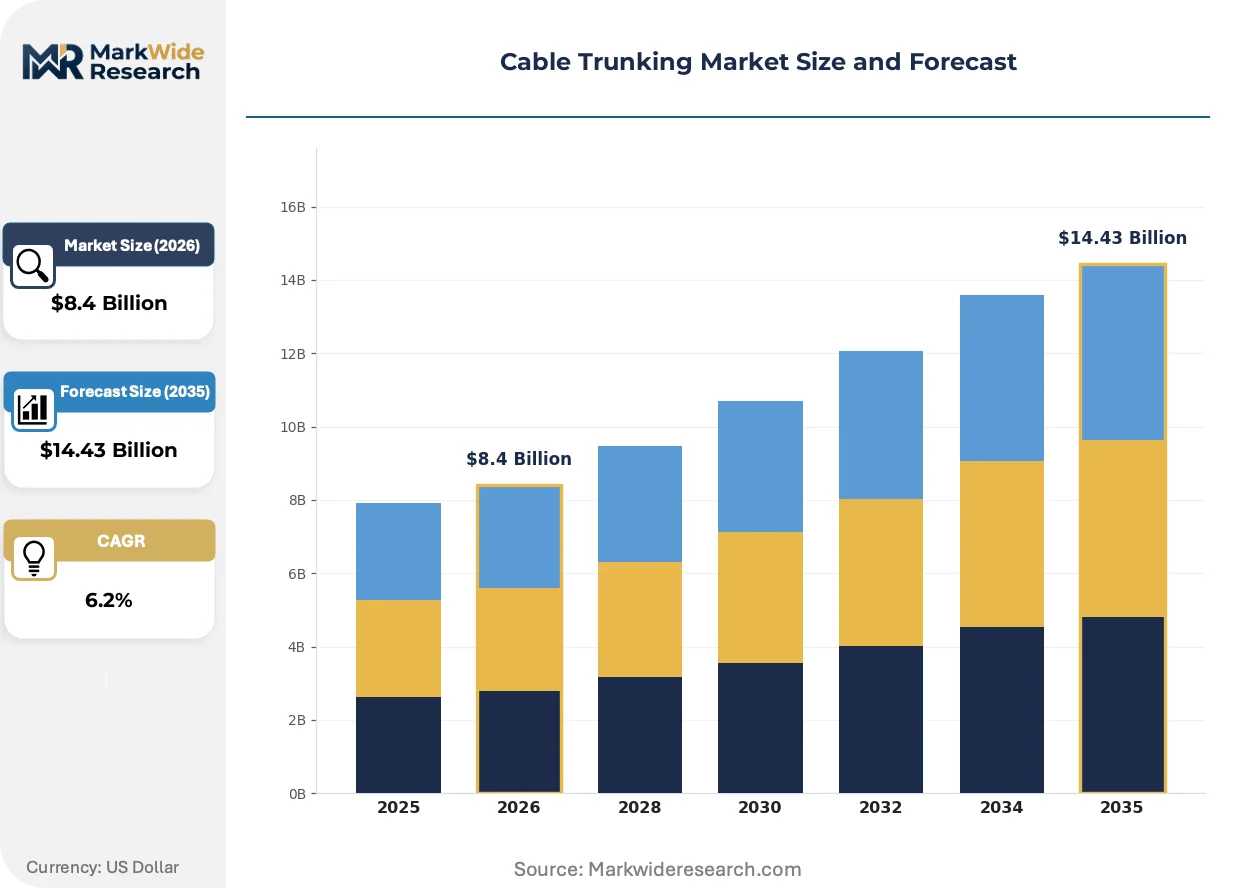
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal, PVC, Stainless Steel, Flexible End User: Telecommunications, Power Distribution, Manufacturing, Residential Installation Type: Surface Mounted, Flush Mounted, Underfloor, Ceiling Mounted Distribution Channel: Direct Sales, Online Retail, Wholesale, Specialty Stores |
| Companies Covered | Atkore International, Schneider Electric SE, ABB Ltd., Eaton Corporation plc, Legrand, OBO Bettermann Holding GmbH & Co. KG, Popular Pipes Group of Companies, Oglaend System, Hubbell Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Trunking Market Trends and Innovations
Specification authority is migrating from general contractors to specialized MEP consultants, compressing vendor access windows and elevating technical documentation requirements.
Smart trunking with embedded sensor channels is digitizing condition monitoring for temperature, humidity, and intrusion detection. Data center operators in Singapore and Malaysia are specifying these systems as standard for critical power distribution. The technology is digitizing maintenance scheduling from reactive to predictive models, reducing unplanned downtime exposure.
REACH restriction proposals on halogenated flame retardants are accelerating material substitution timelines across European commercial construction. Manufacturers are reformulating PVC compounds ahead of regulatory deadlines to maintain specification eligibility. Germany and France are seeing the fastest specification pivot, with DACH-region projects already mandating LSZH alternatives.
Consolidated procurement through engineering-procurement-construction firms is compressing distributor margins and elevating volume-commitment requirements. Tier-one contractors in India's industrial corridor are bypassing traditional electrical wholesalers for direct manufacturer relationships. The shift is most visible in Maharashtra and Gujarat, where integrated project delivery models dominate large manufacturing facility contracts.
Cable Trunking Market Segmentation
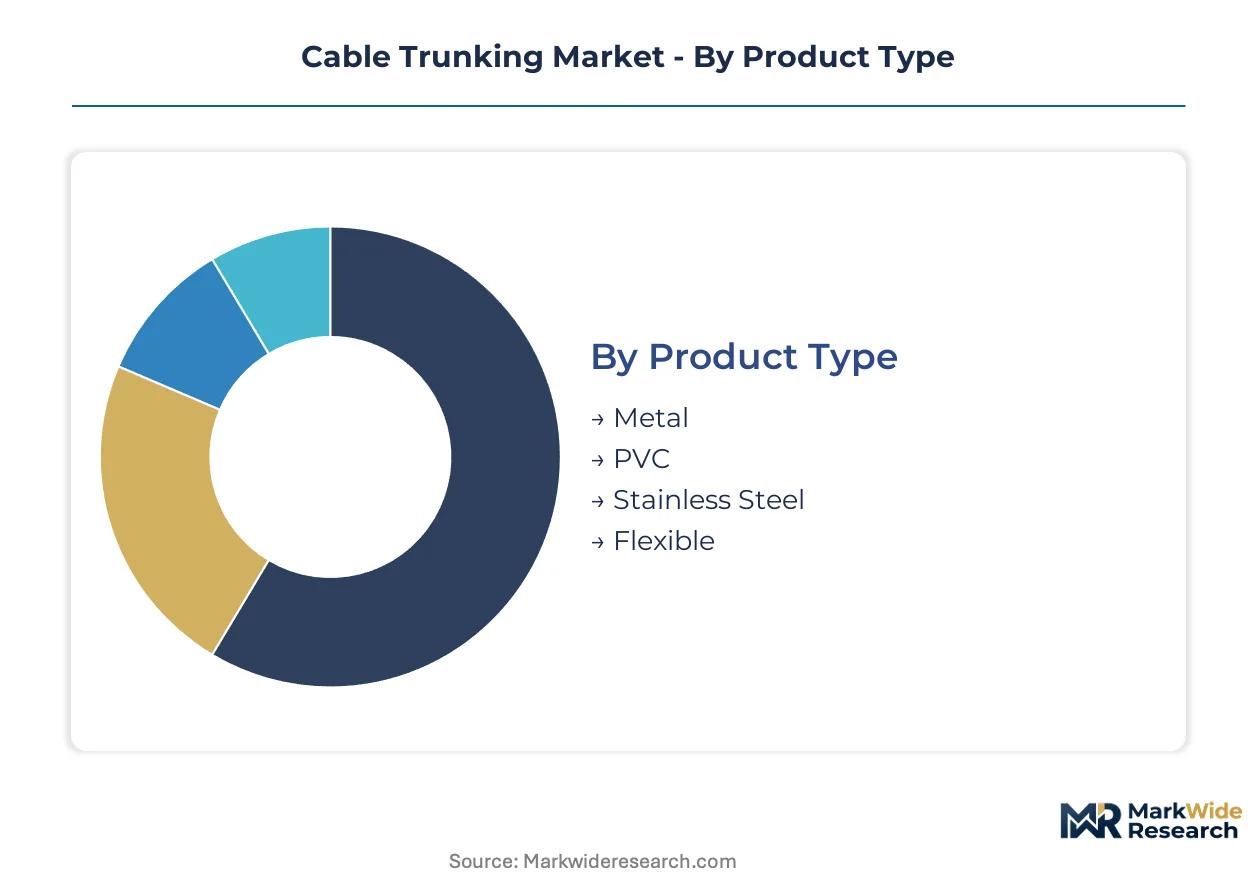
Cable trunking segmentation reveals divergent procurement rhythms across material grades and installation contexts. Specification cycles compress in data center builds while industrial corridors sustain extended tender timelines for heavy-gauge systems.
Product Type:
Replacement cycles vary dramatically: flexible trunking turns over fastest in retrofit environments, while stainless steel installations persist for decades in corrosive industrial settings.
- Metal:Fabricated from galvanized steel with wall thickness calibrated for mechanical impact resistance and electromagnetic shielding. India's industrial corridor projects under CEA technical standards are specifying heavy-gauge metal trunking for power distribution infrastructure where NFPA 70 conduit fill requirements apply.
- PVC:Extruded rigid or semi-rigid channels formulated with flame-retardant additives for commercial and residential applications. Telecommunications infrastructure across Southeast Asian data centers is driving specification of lightweight PVC variants where installation speed outweighs thermal performance needs.
- Stainless Steel:Corrosion-resistant grades 304 and 316 for chemical processing, marine, and food production environments requiring washdown compatibility.
- Flexible:Spiral-wound metal or polymer composites enabling cable routing through complex geometries and vibration-prone machinery zones.
Metal trunking dominates installed base across heavy industrial applications. Flexible systems are where expansion concentrates in data center and telecommunications retrofit segments.
End User:
Customer concentration patterns split between capital-project-driven verticals and maintenance-driven replacement cycles.
- Telecommunications:Fiber and copper cable management for central offices, cell towers, and hyperscale data centers. Singapore and Malaysia operators are standardizing smart trunking with embedded sensor channels for predictive maintenance of critical power distribution.
- Power Distribution:Utility substations, commercial building electrical rooms, and industrial motor control centers. Indian CEA grid modernization mandates are opening specification channels for integrated cable management in smart substation infrastructure.
- Manufacturing:Production line power and control cable routing requiring IP-rated sealing and electromagnetic compatibility containment.
- Residential:New construction and renovation applications prioritizing cost efficiency and aesthetic integration with interior finishes.
Power Distribution commands the largest project scale per installation. Telecommunications is climbing the fastest as data center construction accelerates across Southeast Asia.
Installation Type:
Mounting geometry determines labor content, with flush and underfloor systems demanding specialized trade coordination.
- Surface Mounted:Wall or ceiling attachment with visible raceway profiles. Commercial building specifications in Germany and France are mandating LSZH surface-mounted systems ahead of REACH restriction deadlines on halogenated flame retardants.
- Flush Mounted:Recessed wall or ceiling integration requiring precise rough-in coordination. Maharashtra and Gujarat manufacturing facilities are specifying flush-mounted metal trunking for cleanroom and production environments where surface protrusions create contamination or safety hazards.
- Underfloor:Raised access floor cable distribution for office and data center applications requiring frequent reconfiguration.
- Ceiling Mounted:Overhead routing for industrial and warehouse environments with high-bay storage and material handling equipment.
Surface Mounted retains the broadest applicability across building types. Flush Mounted is gaining share fastest in premium commercial and controlled-environment manufacturing specifications.
Distribution Channel:
Channel economics fragment between relationship-driven direct procurement and transaction-oriented spot purchasing.
- Direct Sales:Manufacturer-to-contractor relationships for large industrial and infrastructure projects. Tier-one EPC firms in India's industrial corridor are bypassing traditional electrical wholesalers for direct manufacturer relationships with volume-commitment structures.
- Wholesale:Electrical distributor networks carrying inventory for contractor spot purchasing and project fill-in. Copper price volatility compresses margin buffers for distributors holding metal-intensive trunking inventory.
- Online Retail:E-commerce platforms serving maintenance, repair, and operations procurement alongside small contractor orders.
- Specialty Stores:Local electrical supply houses providing technical consultation and same-day availability for urgent project needs.
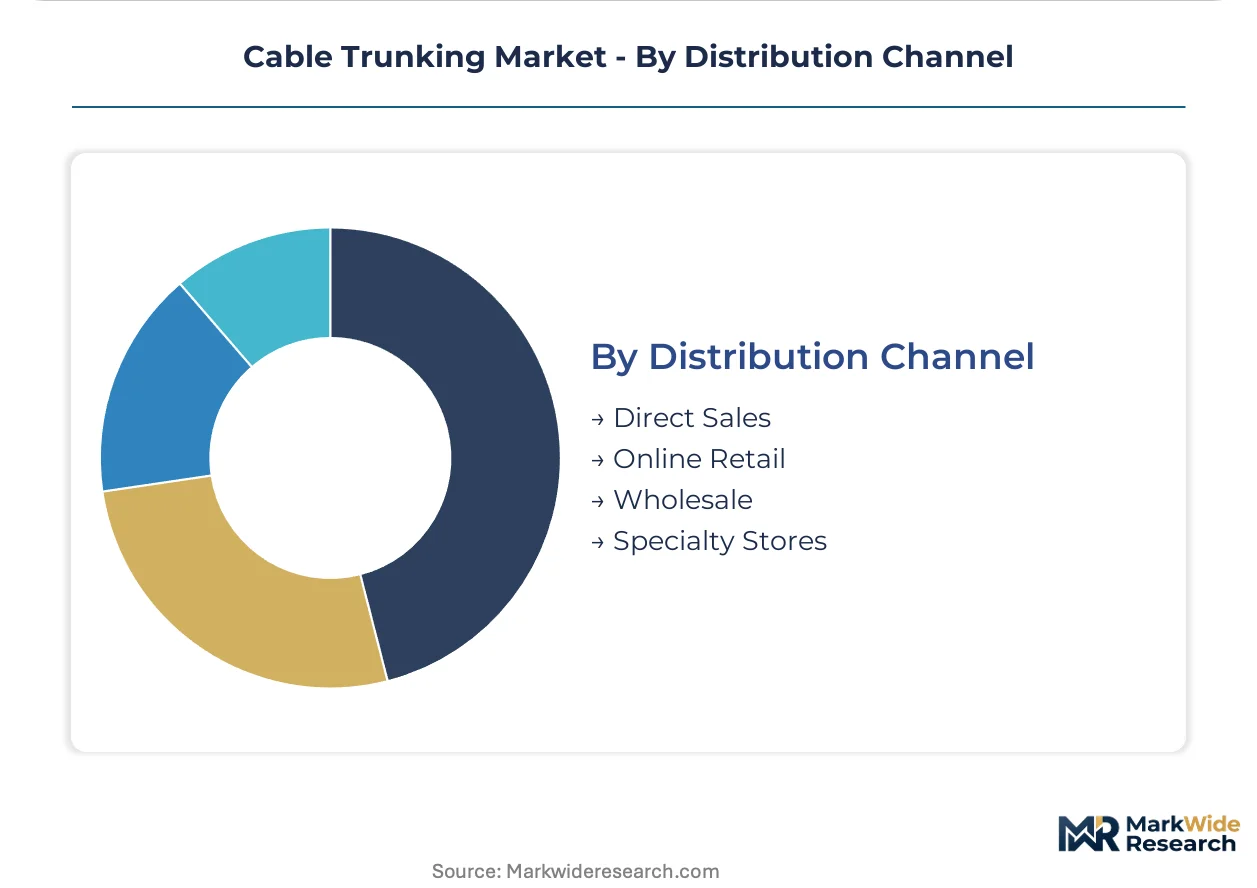
Wholesale channels maintain the deepest penetration across traditional construction workflows. Direct Sales is expanding most quickly as consolidated procurement through engineering-procurement-construction firms restructures vendor access patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Galvanized steel fabrication capacity clusters in India, Germany, China, and the United States, with regional output shaped by divergent certification regimes and infrastructure investment cycles. Each major manufacturing hub exhibits distinct specification authority patterns and procurement channel structures.
India
Dedicated freight corridors and manufacturing zones under CEA technical standards are driving concentrated demand for heavy-gauge metal trunking systems. BIS certification mandates for imported electrical infrastructure extend market entry timelines by 8-14 months, filtering competition. Maharashtra and Gujarat industrial clusters are bypassing traditional wholesalers for direct manufacturer relationships with volume-commitment structures.
Germany
DACH-region commercial construction projects are mandating LSZH alternatives ahead of REACH restriction deadlines on halogenated flame retardants. ECHA regulatory pressure is accelerating material substitution timelines across specification channels. Bavaria and North Rhine-Westphalia manufacturing facilities are specifying flush-mounted systems for cleanroom environments where surface protrusions create contamination hazards.
United States
Data center construction across Virginia and Texas is compressing specification cycles for flexible trunking systems. FCC Part 15 electromagnetic compatibility requirements and NFPA 70 National Electrical Code provisions govern product performance in heavy industrial power distribution. Midwest manufacturing corridors retain primacy for galvanized steel channel fabrication serving continental infrastructure projects.
China
Domestic construction activity and export-oriented manufacturing are sustaining dual demand tracks for PVC and metal trunking variants. GB standards and MIIT industrial policy directives shape local certification requirements and material substitution patterns. Yangtze River Delta and Pearl River Delta production clusters are consolidating capacity for Southeast Asian data center export markets.
Singapore
Hyperscale facility commitments are creating first-mover advantage specifications for smart trunking with embedded sensor channels. Telecommunications infrastructure operators are standardizing predictive maintenance systems for critical power distribution. The city-state's specification authority is migrating from general contractors to specialized MEP consultants, compressing vendor access windows.
Cable Trunking Market Competitive Landscape
Industrial conglomerates and specialized cable management fabricators split the market along specification complexity and geographic coverage vectors. The vendor base organizes into three strategic archetypes: diversified electrical equipment multinationals with integrated portfolios, regional metal fabrication specialists with certification depth in single jurisdictions, and flexible system innovators targeting data center retrofit cycles. Consolidated procurement through engineering-procurement-construction firms is compressing distributor margins, while direct manufacturer relationships are displacing traditional wholesale channels in large-scale industrial corridor projects.
Among diversified electrical equipment multinationals, Schneider Electric SE and Legrand exemplify the integrated portfolio archetype with broad coverage across flush-mounted and surface-mounted systems. Atkore International occupies a position representing North American steel conduit expertise applied to high-specification industrial installations. These three anchors illustrate how heritage in adjacent electrical infrastructure categories translates into cable trunking specification authority through installer relationships and technical documentation depth.
| Leading Market Players |
|---|
| Atkore International |
| Schneider Electric SE |
| ABB Ltd. |
| Eaton Corporation plc |
| Legrand |
| OBO Bettermann Holding GmbH & Co. KG |
| Popular Pipes Group of Companies |
| Oglaend System |
| Hubbell Incorporated |
| Others |
Pricing and Supply Chain Analysis
The Malacca Strait shipping corridor cost dynamics compress margin buffers for galvanized steel trunking imports into Southeast Asian data centers while amplifying price differentiation between IEC 61439-certified premium grades and uncertified economy alternatives. Copper price volatility feeds directly into procurement strategies, with distributors holding metal-intensive inventory facing working capital pressure that downstream buyers exploit in volume negotiations.
Pricing Analysis
IEC 61439 dictates the pricing tier structure across European and Southeast Asian procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates heavy-gauge metal systems with full electromagnetic shielding from lightweight PVC alternatives and uncertified imports. Price differentiation hinges on certification grade and volume scale, with tier-one EPC contractors in Maharashtra extracting double-digit discounts through direct manufacturer commitments. Cost compression in standard-grade metal trunking is intensifying because of copper price volatility and consolidated procurement leverage. Residential retrofit contractors exhibit highest price sensitivity, while data center operators in Singapore prioritize specification compliance over unit cost.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk calculations for PVC compound and galvanized steel channel sourcing. Manufacturing concentrates in India, Germany, and China, with Yangtze River Delta fabricators feeding Southeast Asian export demand. Raw material dependencies rest on copper cathode, zinc for galvanization, and halogen-free polymer resins. Single-source vulnerability persists for high-grade 316 stainless steel from European mills. Distribution runs through electrical wholesale networks for spot purchasing, though direct manufacturer relationships are displacing traditional channels in large industrial corridor projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart trunking with embedded sensor channels constitutes a high-growth disruption, with CEA grid modernization mandates in India and REACH halogen restrictions in Europe creating simultaneous regulatory inflection points that restructure competitive positioning.
For Market Incumbents: Insulate specification authority by deepening installer certification programs for IP-rated sealing and fire-stopping integration, countering the threat of MEP consultant migration to specialized technical documentation. Backward integration into halogen-free compound production secures supply continuity ahead of REACH restriction deadlines. Channel control through exclusive EPC volume commitments in Gujarat and Maharashtra manufacturing clusters defends margin position against distributor disintermediation.
For New Entrants and Emerging Players: Establish a beachhead in Indonesia's Batam and Jakarta data center pipeline, where hyperscale facility commitments outpace incumbent flexible trunking capacity. The most penetrable segment is smart trunking with predictive maintenance integration, underserved by legacy metal fabrication specialists. A direct-to-EPC go-to-market angle bypasses wholesale channel barriers that filter import competition.
For Investors and Strategic Acquirers: REACH restriction deadlines reshape the acquisition landscape by elevating the value of LSZH formulation capabilities and European certification infrastructure. Long-term viability centers on manufacturers with dual competence in heavy-gauge industrial metal trunking and lightweight data center flexible systems. The target archetype is regional specialists with BIS certification depth and CEA technical standards compliance. The signal to watch is consolidation velocity among Indian industrial corridor suppliers as tier-one EPC procurement centralizes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Halogen-Free Compounds | REACH compliance secures specification eligibility in DACH-region commercial construction ahead of regulatory deadlines. |
| Smart Trunking Sensor Channel Development | Singapore data center operators standardize predictive maintenance integration for critical power distribution infrastructure. |
| BIS Certification Investment | Indian standards compliance filters import competition and accelerates market entry timelines for domestic manufacturing. |
| Direct EPC Relationship Structure | Maharashtra and Gujarat manufacturing facilities bypass wholesale channels through volume-commitment procurement models. |
| Flexible System Capacity Expansion | Southeast Asian data center construction compresses specification cycles and rewards rapid-response manufacturing footprints. |
Research Methodology
Initial hypotheses were tested against primary input from electrical contractors, MEP consultants, EPC procurement managers, and cable management distributors and refined through secondary validation against IEC 61439 technical documentation, BIS certification registries, CEA grid modernization directives, and customs trade data for galvanized steel and PVC trunking imports. Bottom-up demand modeling from project-level data triangulated against top-down capacity assessments from manufacturing clusters in India, Germany, and China.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material grade, end-use vertical, installation type, and distribution channel structure. CAGRs were derived from installed base turnover analysis and new project pipeline assessment. Industry-specific forecast inputs incorporated copper price trajectory assumptions and data center construction commitment tracking across Southeast Asia.
Sensitivities concentrate around copper price volatility, REACH regulatory acceleration timelines, and BIS certification processing duration for imported systems. Forecasts reflect assumptions about infrastructure investment continuity and standards harmonization velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Global Cable Tie Market
Cables
Anti-Static Space Wires Market
Cables
Insulated Wire and Cable Market
Cables
Premise Cable Market
Cables
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market
Cables
Middle East Cable Market
Cables
United States Cable Accessories Market
Cables
Multi-Core Land High Voltage Underground Cable Market
Cables
North America Copper Wire and Cable Market
Cables
North America Coaxial Cable Market
Cables
Cable Clamp Market
Cables
Military Fiber Optic Cables Market
Cables
Coaxial Cable Market
Cables
Radio Frequency Cables Market
Cables
Global Low Voltage Cable Market
Cables
Fire Resistance Cable Market