
 South Africa Wire and Cable Market | 2026-2036
South Africa Wire and Cable Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Wire and Cable Market Outlook
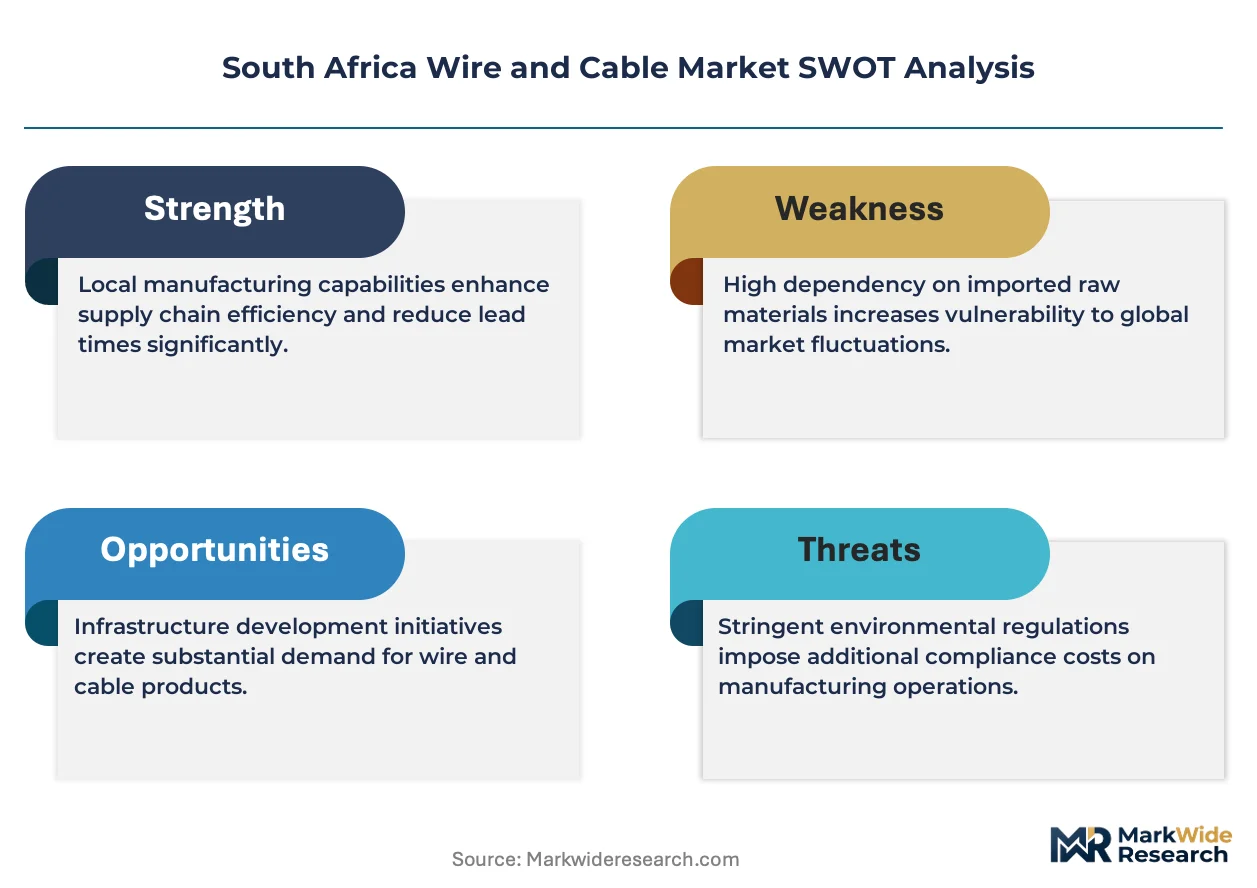
CE marking alignment pressure is restructuring import compliance costs for European-origin cable suppliers. Aberdare Cables leverages its Pietermaritzburg manufacturing base to dominate local medium voltage supply. Nexans sustains technology leadership through specialized high voltage submarine and terrestrial cable systems. Alvern Cables anchors downstream distribution across mining and industrial channels with extensive warehousing networks.
Wire and cable encompass electrically conductive assemblies of copper or aluminum strands insulated with PVC, XLPE, or rubber compounds, engineered to transmit power or data across rated voltage classes. Low voltage products serve building wiring and appliance connections, while medium and high voltage constructions integrate cross-linked polyethylene insulation for grid transmission and heavy industrial feed. Medium voltage cables command the deepest margin pools due to technical certification barriers and utility procurement specifications. Infrastructure applications are expanding fastest as Transnet and municipal electrification programs accelerate conductor pull-through across transport and water networks.
South Africa's National Regulator for Compulsory Specifications enforces SANS cable standards that dictate flame retardancy, conductor sizing, and insulation thickness for domestic sale. The country's central bank and Department of Trade, Industry and Competition administer local content thresholds that shape public procurement eligibility and manufacturing investment decisions. Stakeholders must monitor how embedded generation licensing reforms redistribute demand between utility-scale and private offtake cable specifications.
Market Dynamics
Eskom's transmission expansion program is redrawing copper cable demand geography across Gauteng and KwaZulu-Natal industrial corridors. The amended Electricity Regulation Act is accelerating private grid participation, fragmenting procurement authority between state utilities and independent power producers.
Growth Catalysts
- Transmission infrastructure buildout:Eskom's grid strengthening program is pulling medium voltage cable through Johannesburg's industrial corridor and Richards Bay mineral processing zones.
- Embedded generation licensing reforms:The amended Electricity Regulation Act is redistributing demand between utility-scale and private offtake cable specifications.
- Transnet electrification programs:Transport and water network conductor pull-through is expanding fastest across rail and port infrastructure.
Market Restraints
- Copper price volatility:LME copper fluctuations transmit directly into manufacturing cost structures with limited hedging depth in rand-denominated contracts.
- Import dependency for specialty compounds:XLPE and high-performance rubber insulation materials concentrate supply in European and Asian chemical producers.
- SANS certification timelines:National Regulator for Compulsory Specifications flame retardancy testing creates 12-18 month product approval cycles.
Strategic Opportunities
- Western Cape renewable clusters:Independent power producer zones around Saldanha and Atlantis are creating demand for specialized collector cables.
- Smart grid instrumentation convergence:Fiber optic sensing integration with power conductors is enabling real-time thermal monitoring for utilities.
- Department of Trade, Industry and Competition local content thresholds:Public procurement eligibility rules are incentivizing domestic manufacturing investment decisions.
Industry Challenges
- Cross-linked polyethylene compounding expertise:Medium voltage insulation manufacturing requires polymer chemistry skills concentrated in a narrow technical workforce pool.
- Legacy asbestos cable replacement:Mining and industrial sites face complex remediation protocols when upgrading aging infrastructure without operational shutdown.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Wire and Cable Market |
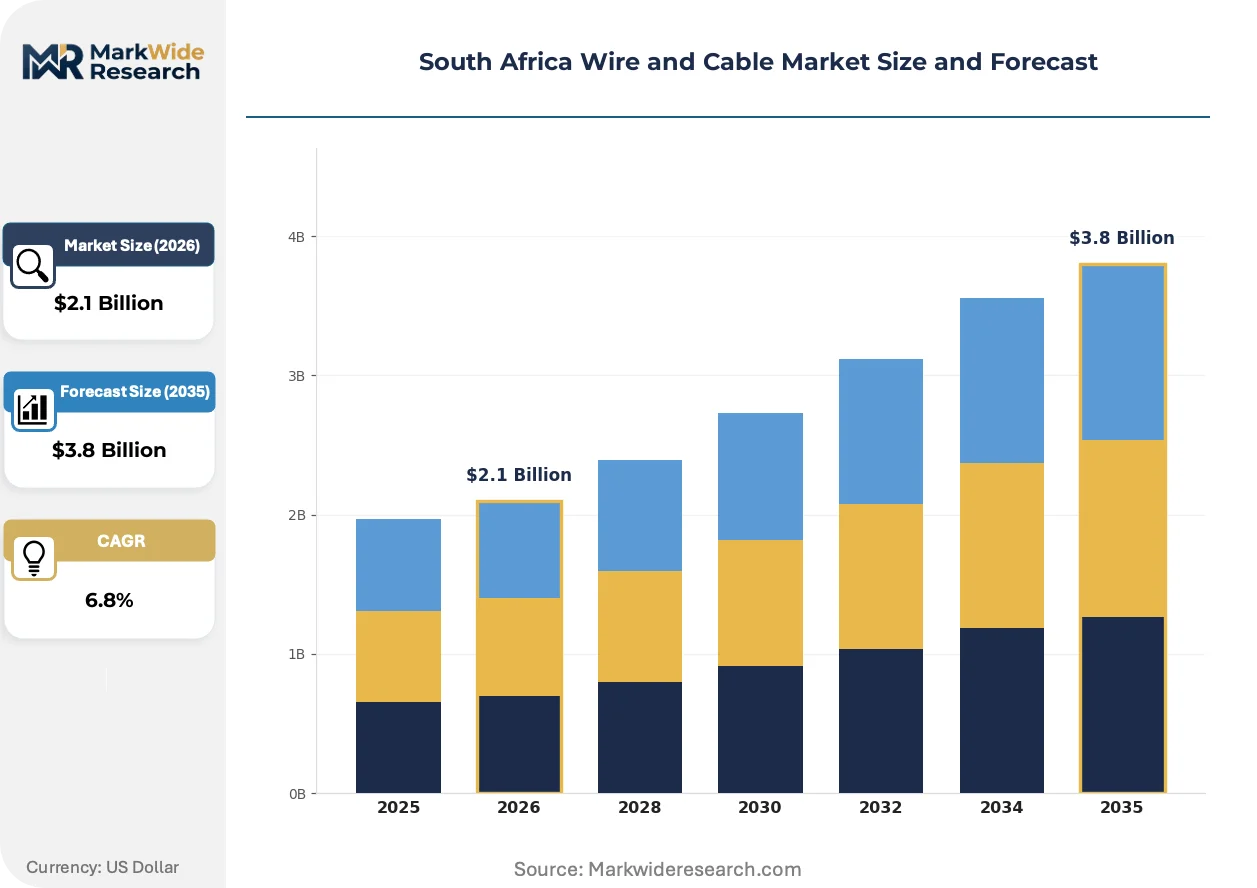
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Voltage, Medium Voltage, High Voltage, Specialty Cables Application: Residential, Commercial, Industrial, Infrastructure Material: Copper, Aluminum, Fiber Optic, PVC End User: Utilities, Telecommunications, Construction, Automotive |
| Companies Covered | Nexans, Southwire, Aberdare Cables, Belden Inc, LS Cable & System, Alvern Cables, NKT A/S, SACM, Prysmian SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Wire and Cable Market Strategic Shifts
Digital instrumentation is threading through power infrastructure, converting passive conductors into sensor networks. Material science advances and procurement recalibration are compressing traditional specification cycles.
High voltage direct current submarine cable technology is converging with terrestrial grid reinforcement needs. Eskom and large industrial offtakers are piloting cross-linked polyethylene insulated HVDC runs for long-distance transmission from coastal generation zones to inland demand centers. This convergence is collapsing the historical separation between offshore and onshore cable engineering disciplines.
South Africa's amended Electricity Regulation Act is restructuring grid access frameworks. The legislation creates licensing pathways for private transmission infrastructure, forcing cable specifications to accommodate bidirectional power flows and distributed generation interconnection standards. Medium voltage products face the most complex recertification burden as technical standards adapt.
Buyer concentration among independent power producers is compressing procurement cycles. Large renewable developers are consolidating cable purchasing through engineering-procurement-construction contractors, displacing traditional distributor networks in the Western Cape and Northern Cape solar zones. This channel shift is most visible where generation assets cluster near existing transmission backbones.
South Africa Wire and Cable Market Segmentation
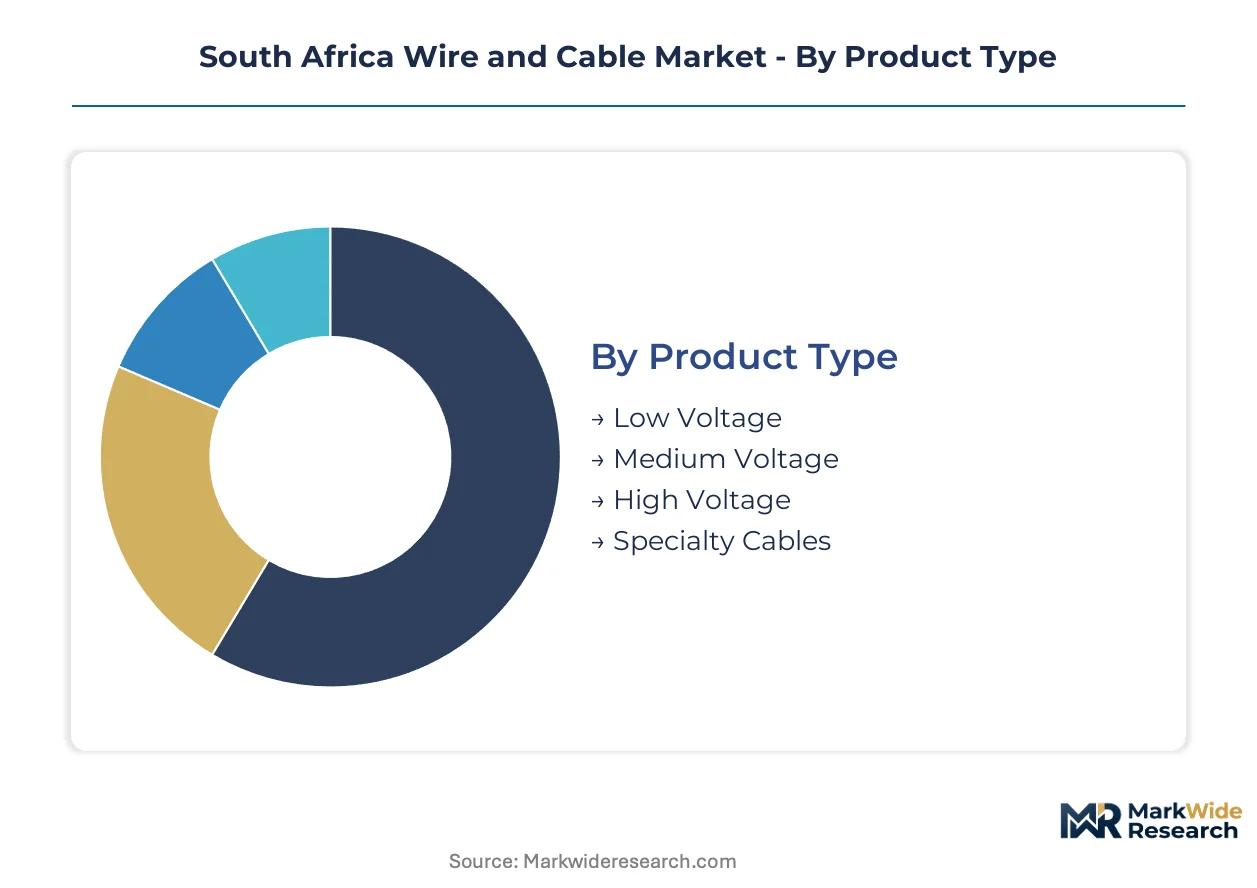
Segmentation in South Africa's wire and cable market reveals how procurement authority fragments across Eskom's centralized transmission purchasing, municipal distribution tenders, and private renewable developer specifications. Technical standards diverge sharply between utility-scale grid reinforcement and embedded generation interconnection, creating distinct margin pools and certification barriers for each buyer category.
Product Type:
Buyers differentiate by voltage class based on installation complexity, technical workforce availability, and SANS certification requirements rather than commodity pricing alone.
- Low Voltage:PVC and XLPE insulated conductors rated up to 1kV serve building wiring, appliance connections, and distribution feeder circuits. Demand concentrates in Gauteng residential construction and retail electrical distribution channels, where contractor familiarity with SANS 1507 standards simplifies procurement. Price sensitivity dominates purchasing decisions in this commoditized tier.
- Medium Voltage:Cross-linked polyethylene insulated constructions rated 1kV to 33kV integrate semiconducting screens and metallic armor for grid and industrial feed applications. Eskom's transmission expansion across Johannesburg's industrial corridor and Richards Bay mineral processing zones concentrates demand here, with technical certification barriers limiting supplier participation to Aberdare Cables and established tier-one manufacturers.
- High Voltage:Oil-filled or XLPE insulated systems rated above 33kV for transmission backbone reinforcement.
- Specialty Cables:Fire-resistant, submersible, and mining-grade constructions with enhanced mechanical or environmental protection ratings.
Medium Voltage leads volumes today; Specialty Cables is gaining share fastest through mining safety upgrades and smart grid instrumentation integration.
Application:
Project scale and funding source—state utility capex versus private developer equity—determine specification authority and channel structure.
- Infrastructure:Rail electrification, port power distribution, and water treatment plant feeder systems. Transnet's network modernization across Durban and Cape Town harbors drives conductor pull-through, with Department of Trade, Industry and Competition local content thresholds shaping procurement eligibility.
- Industrial:Heavy manufacturing feed circuits, mining extraction infrastructure, and mineral processing power distribution. Demand clusters in the platinum belt around Rustenburg and manganese corridors in Northern Cape, where 24/7 operational continuity mandates premium cable specifications.
- Commercial:Office complexes, retail centers, and hospitality installations.
- Residential:Single-family and multi-unit dwelling wiring systems.
Infrastructure leads volumes today; Industrial is expanding most quickly on mining mechanization and smelter expansion projects.
Material:
Conductivity requirements, weight constraints, and raw material cost exposure drive material selection across voltage classes and installation environments.
- Copper:Electrolytic tough pitch and oxygen-free high-conductivity grades deliver superior ampacity and corrosion resistance. Gauteng and KwaZulu-Natal industrial corridors anchor demand, with LME price volatility transmitting directly into manufacturing cost structures through limited rand-denominated hedging depth.
- Aluminum:Lightweight alloy conductors for long-span overhead transmission and cost-sensitive distribution networks. Western Cape renewable clusters around Saldanha favor aluminum for collector cable applications where weight reduction offsets conductivity penalties.
- Fiber Optic:Sensing-integrated power conductors for real-time thermal monitoring.
- PVC:General-purpose insulation and sheathing compound for low voltage building wire.
Copper leads volumes today; Fiber Optic is climbing the fastest on smart grid instrumentation convergence.
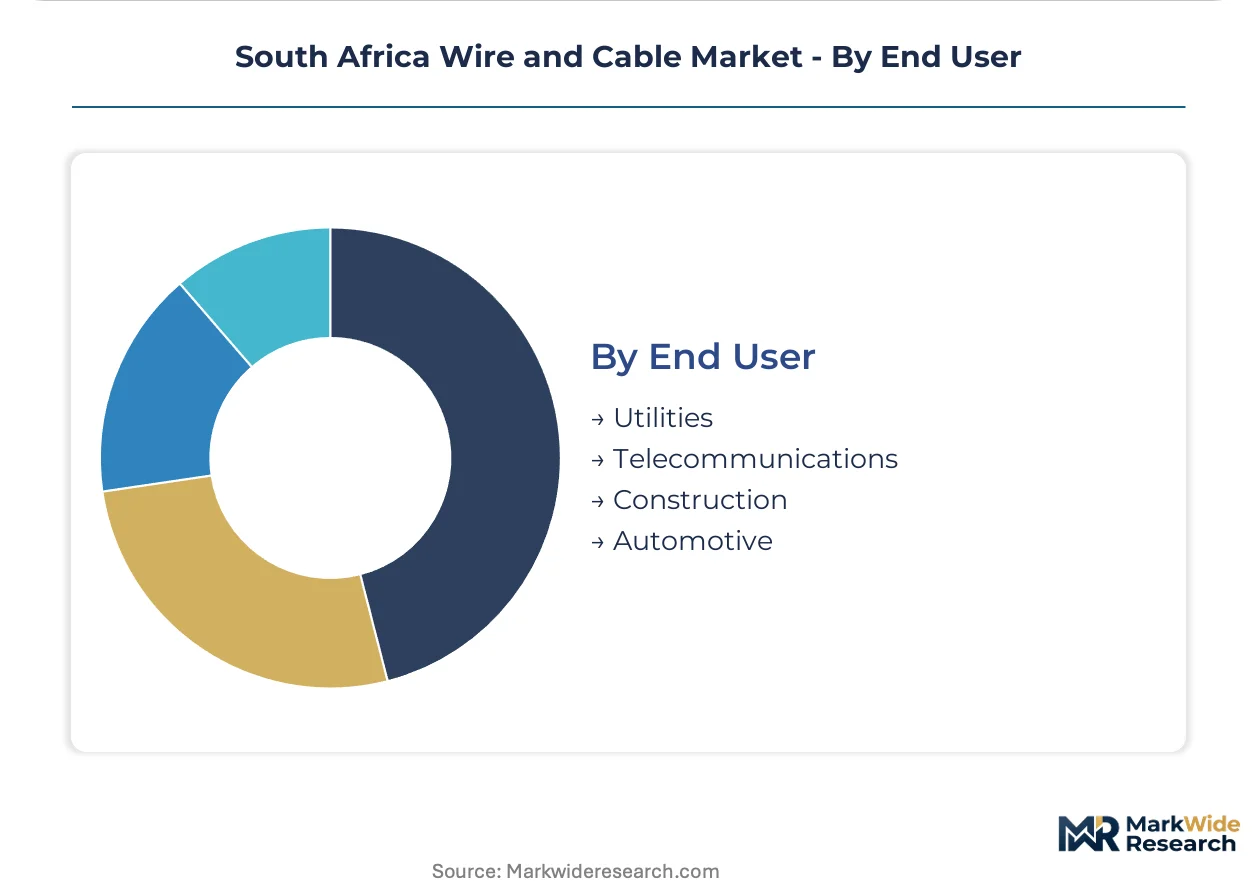
End User:
Procurement sophistication ranges from centralized utility technical specifications to fragmented construction contractor purchasing.
- Utilities:Eskom transmission and distribution divisions, municipal electricity departments, and emerging independent transmission system operators. Centralized technical specifications and multi-year framework agreements dominate, with amended Electricity Regulation Act licensing reforms redistributing demand between utility-scale and private offtake cable standards.
- Construction:Residential, commercial, and civil engineering contractors. Project-based purchasing through electrical wholesalers concentrates volume in Johannesburg and Durban metropolitan construction booms.
- Telecommunications:Fiber-to-the-home and mobile backhaul network operators.
- Automotive:Vehicle wiring harness manufacturers and aftermarket electrical component suppliers.
Utilities leads volumes today; Construction is gaining share fastest on urban densification and renewable energy buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer chemists and high-voltage insulation specialists cluster in Gauteng's industrial corridor, anchoring South Africa's cable manufacturing workforce. Their technical concentration shapes procurement geography across the country's transmission expansion zones.
Gauteng
Eskom's grid strengthening program and Johannesburg's industrial corridor drive medium voltage cable pull-through. The amended Electricity Regulation Act accelerates private grid participation, redistributing demand between utility-scale and independent power producer specifications. Pretoria's manufacturing belt concentrates cross-linked polyethylene compounding expertise for transmission-grade insulation.
KwaZulu-Natal
Richards Bay mineral processing zones and Durban port electrification expand conductor demand for heavy industrial feed. The National Regulator for Compulsory Specifications enforces SANS flame retardancy standards that dictate 12-18 month product approval cycles. Pietermaritzburg anchors medium voltage manufacturing capacity serving coastal industrial clusters.
Western Cape
Independent power producer zones around Saldanha and Atlantis create demand for specialized collector cables in renewable clusters. Department of Trade, Industry and Competition local content thresholds shape public procurement eligibility for transmission infrastructure. Cape Town's smart grid pilot programs integrate fiber optic sensing with power conductors for real-time thermal monitoring.
Northern Cape
Manganese corridor electrification and solar generation buildout expand aluminum conductor demand for long-span collector applications. Embedded generation licensing reforms fragment procurement authority between municipal distributors and private developers. Kathu and Hotazel mining belts require premium cable specifications for 24/7 operational continuity in extraction infrastructure.
South Africa Wire and Cable Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across South Africa's cable market. The supplier base organizes into tiered structures where technical certification barriers limit participation in medium and high voltage segments. Three archetypes dominate: integrated manufacturers with captive polymer compounding, distributors with extensive warehousing networks, and specialized engineering firms focused on submarine or smart grid applications. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms position for transmission infrastructure buildout.
Within the integrated manufacturing tier, Aberdare Cables and Alvern Cables exemplify archetypes with distinct channel positioning. Nexans occupies a position representing technology leadership in specialized high voltage systems. These three names anchor the competitive structure without exhausting the supplier landscape, as regional distributors and import-dependent traders fill gaps in low voltage and specialty construction segments.
| Leading Market Players |
|---|
| Nexans |
| Southwire |
| Aberdare Cables |
| Belden Inc |
| LS Cable & System |
| Alvern Cables |
| NKT A/S |
| SACM |
| Prysmian SpA |
| Others |
Value Chain & Pricing Dynamics
LME copper benchmark volatility cascades through South Africa's wire and cable value chain, compressing margins for distributors while amplifying procurement leverage for Eskom's centralized transmission purchasing. Rand-denominated hedging depth remains thin, forcing manufacturers to absorb spot price swings or push cost adjustments through annual framework renegotiations.
Pricing Analysis
Product-plus-installation bundling separates turnkey project quotes from commodity conductor sales, with medium voltage specifications commanding premium positioning through SANS certification barriers. Price differentiation rests on flame-retardancy grade and local content compliance tier, not raw copper content alone. Cost compression in low voltage building wire is intensifying because import-dependent traders are undercutting established manufacturers on PVC-insulated commodity grades. Municipal tender participants show highest price sensitivity; mining houses with 24/7 operational continuity mandates show lowest.
Supply Chain Analysis
Legacy asbestos cable recovery and refurbishment flows are creating secondary material streams for specialized remanufacturers serving mining remediation contracts. Manufacturing gravity centers on South Africa's domestic compounding base, with XLPE resin and high-performance rubber insulation drawing from Belgian, German, and South Korean chemical producers. Single-source vulnerability concentrates in semiconducting screen compounds where European suppliers dominate technical specifications. Distribution runs through electrical wholesalers in Johannesburg and Durban, with direct EPC contractor purchasing displacing traditional channels in Western Cape renewable zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's wire and cable market functions as a regulatory compounder where amended Electricity Regulation Act licensing reforms are structurally expanding addressable demand beyond traditional utility procurement.
For Market Incumbents: Extend medium voltage certification portfolios to capture bidirectional power flow specifications emerging under private grid participation rules. Aberdare Cables and established tier-one manufacturers should anchor backward integration into cross-linked polyethylene compounding to defend against import-dependent traders exploiting SANS approval timeline gaps. Channel control through captive warehousing networks in Richards Bay and Rustenburg mining belts remains the critical defensive lever against EPC contractor consolidation. For New Entrants and Emerging Players: Independent power producer engineering teams represent the most penetrable buyer archetype as procurement authority fragments from centralized utility specifications. White-space targets cluster around fiber optic sensing-integrated power conductors for smart grid pilot programs in Cape Town and specialized collector cables for Saldanha renewable zones. A technical partnership route with European insulation compound suppliers accelerates SANS certification timelines faster than greenfield polymer chemistry investment. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap distributors possessing deep Western Cape renewable developer relationships and existing medium voltage warehousing infrastructure. Long-term viability across the analysis window hinges on positioning for transmission infrastructure buildout rather than commoditized low voltage construction exposure. Monitor embedded generation licensing application volumes at the National Energy Regulator as the inflection indicator for private offtake cable demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive XLPE supply secures SANS certification timelines against European chemical producer bottlenecks. |
| Smart Grid Instrumentation Partnership | Fiber optic sensing integration with power conductors opens real-time thermal monitoring contracts with Eskom. |
| Western Cape Distribution Footprint Expansion | Proximity to Saldanha and Atlantis renewable clusters captures independent power producer procurement consolidation. |
| Legacy Asbestos Cable Remediation Service | Mining belt operational continuity mandates create premium-priced replacement contracts without shutdown windows. |
| Local Content Threshold Compliance Investment | Department of Trade, Industry and Competition eligibility unlocks Transnet and municipal tender participation. |
Study Parameters
Multiple input streams — primary interviews with utility planning officers, EPC contractor procurement leads, and polymer compounding technical directors; secondary validation through Eskom transmission capex disclosures, National Regulator for Compulsory Specifications approval databases, and Department of Trade, Industry and Competition local content registry filings; plus customs trade data on copper conductor imports — were reconciled through bottom-up project pipeline aggregation and top-down macroeconomic anchoring.
Historical transmission expansion patterns were cross-referenced against panel input from cable manufacturer sales executives and municipal tender monitoring to construct the analytical framework across voltage class, application, and regional demand center dimensions. CAGRs were derived from segment-level volume buildups tied to named infrastructure project commitments rather than extrapolated trend fitting. Forecast inputs incorporated amended Electricity Regulation Act implementation pace and Transnet electrification program phasing.
Underlying measurement precision varies by segment; medium voltage utility specifications carry tighter precision than fragmented low voltage construction demand. Forecasts reflect documented assumptions regarding copper price trajectory and licensing reform implementation. Practitioners should monitor National Energy Regulator embedded generation registration volumes and LME copper forward curve movements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
XLPE Cables Market
Cables
Military Fiber Optic Cables Market
Cables
Europe Wire and Cable Market
Cables
Power and Control Cable Market
Cables
Multi-Core Land High Voltage Underground Cable Market
Cables
Military Cable Market
Cables
Electric Submersible Cable Sales Market
Cables
Europe Cable Joints Market
Cables
Europe HVAC Cables Market
Cables
Usb Data Cable Market
Cables
Anti-Static Space Wires Market
Cables
Global Cable Tie Market
Cables
North America Coaxial Cable Market
Cables
LED Cable Market
Cables
Audio and Video Cables Market
Cables
Cable Testers Market