
 Active Optical Cable Market | 2026-2036
Active Optical Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Active Optical Cable Market Intelligence
Capital-intensity divergence between in-house photonics foundries and outsourced assembly houses is reorganizing competitive tiers in the Active Optical Cable landscape. Broadcom leverages captive VCSEL fabrication to command margins on 100G modules. Sumitomo Electric Industries anchors supply through integrated fiber-drawing and cable-assembly operations across Japan and Southeast Asia. Coherent Corp. specializes in indium phosphide lasers for extended-reach data center interconnects.
An active optical cable integrates optical transceivers, fiber, and control electronics into a single pluggable assembly, typically using multimode fiber with 850nm VCSEL sources for distances under 100 meters to replace bulky copper DACs in rack-dense environments. The 100G product type dominates volume shipments into hyperscale data centers, while 40G contracts in enterprise refresh cycles. High-performance computing applications command premium pricing due to strict latency budgets and custom form factors.
FCC equipment authorization rules govern AOC electromagnetic emissions in US deployments, while EU RoHS and REACH directives restrict hazardous substances in cable jacketing and connector plating. China's GB standards and MIIT certification requirements create a separate compliance pathway for domestic procurement. Stakeholders must monitor silicon photonics substitution timelines, as integrated optical engines threaten discrete VCSEL-based architectures without requiring module redesign.
Market Dynamics
Silicon photonics integration is decomposing the traditional VCSEL-based module architecture, forcing suppliers to retool wafer-level packaging lines while hyperscale buyers demand co-packaged optics for AI training clusters.
Growth Catalysts
- MIIT energy-efficiency mandates:China's tightened national standards for optical transceiver power consumption are accelerating domestic supplier migration to advanced silicon photonics architectures, creating procurement preference for certified low-power modules.
- AI training cluster buildouts:Hyperscale operators in Northern Virginia and Oregon are deploying multi-million-port AOC fabrics to support GPU-intensive workloads, generating sustained volume demand for 100G and 400G assemblies.
- Copper DAC displacement:Rack-dense data centers are systematically replacing bulky passive copper cables with pluggable AOCs for distances under 100 meters, driven by thermal and physical space constraints.
Market Restraints
- Indium phosphide laser supply concentration:Extended-reach data center interconnects depend on InP laser sources concentrated among limited specialty foundries, creating input cost volatility and allocation risk.
- VCSEL epitaxy capacity constraints:Captive vertical integration into 850nm VCSEL fabrication by dominant suppliers limits second-source options for 100G module producers without wafer-level capabilities.
- Silicon photonics substitution timeline:Integrated optical engines threaten discrete transceiver architectures without requiring module redesign, compressing upgrade cycles and stranding legacy assembly investments.
Strategic Opportunities
- High-performance computing custom form factors:Strict latency budgets in supercomputing environments command premium pricing for specialized AOC configurations with non-standard connector geometries.
- Emerging ASEAN data center corridors:Singapore and Johor are attracting hyperscale builds requiring localized AOC supply chains, offering first-mover advantages for integrated fiber-drawing and assembly operations.
- FCC equipment authorization streamlining:Simplified electromagnetic emissions certification pathways for pluggable optical modules are reducing time-to-market for US-focused suppliers.
Industry Challenges
- Silicon photonics packaging skill scarcity:Wafer-level optical engine assembly requires precision photonics packaging expertise that outstrips current foundry technician training pipelines.
- Multi-jurisdiction certification complexity:Simultaneous compliance with FCC electromagnetic rules, EU RoHS substance restrictions, and China's GB standards extends product validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Optical Cable Market |
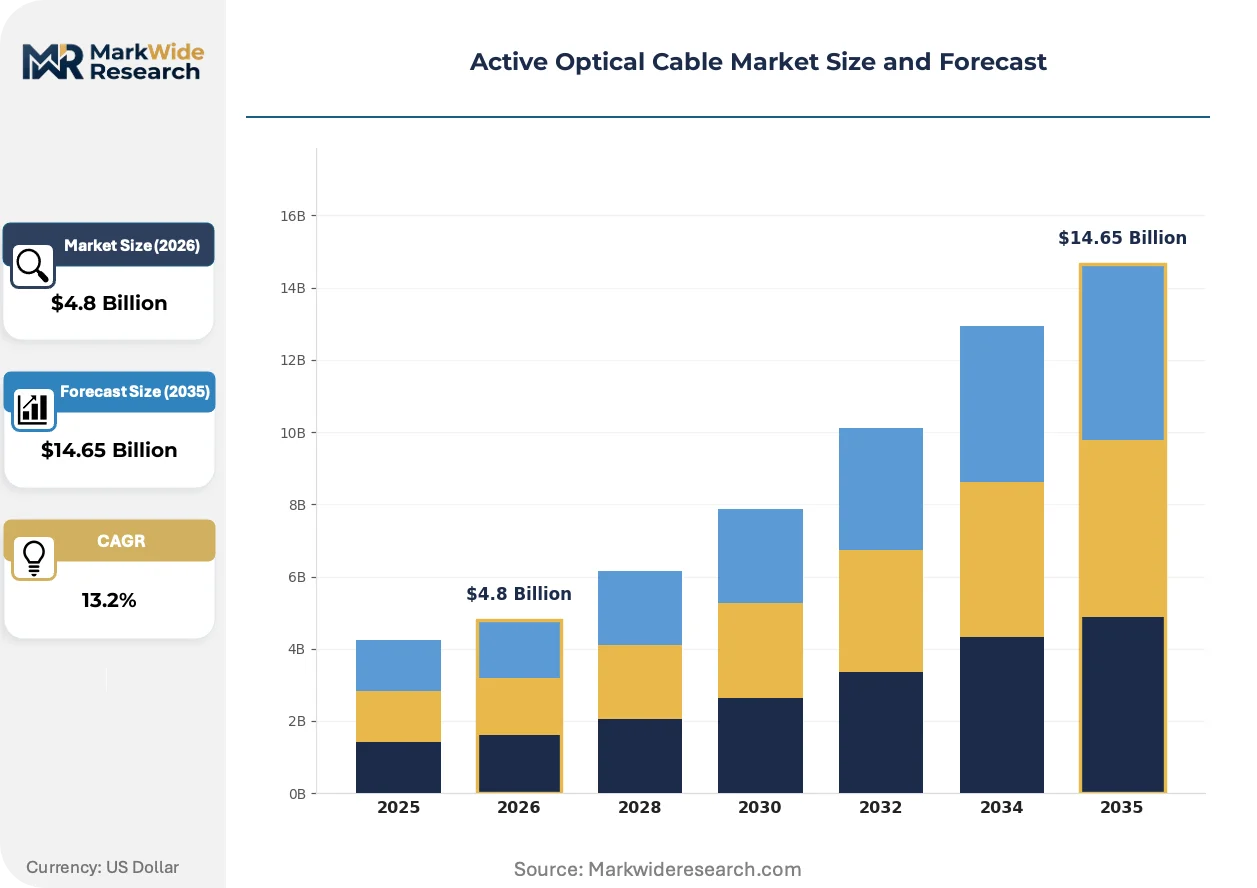
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $14.65 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 100G, 40G, 10G, 1G Application: Data Center, High-Performance Computing, Network Communication, Broadcast Connector Type: LC, SC, MTP/MPO, E2000 End User: Telecommunications, Enterprise, Industrial, Government |
| Companies Covered | Sumitomo Electric Industries, Broadcom, Amphenol Corporation, Fujikura, Nexans, Molex, Corning Incorporated, Coherent Corp., TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Optical Cable Market Strategic Shifts & Innovations
Optical integration is collapsing the traditional module supply chain into wafer-scale fabrication, while regulatory pressure on energy efficiency and buyer consolidation are reshaping competitive requirements.
Co-packaged optics is decomposing the discrete transceiver market by embedding optical I/O directly alongside switch ASICs. Hyperscale operators are piloting these architectures in AI training clusters to eliminate retimer power and latency. This technology is compressing the addressable market for traditional pluggable AOCs in highest-density deployments.
REACH substance restrictions are tightening constraints on cable jacketing and connector plating materials in European deployments. Manufacturers are reformulating halogen-free compounds and alternative surface finishes to maintain market access. Module suppliers serving EU cloud providers are accelerating material qualification programs ahead of enforcement deadlines.
Bundled optical-electrical procurement contracts are consolidating vendor relationships among hyperscale operators. Direct sourcing teams are negotiating multi-year AOC supply agreements with integrated fiber and transceiver producers, bypassing traditional distribution channels. This pattern is most visible in United States cloud builds, where procurement centralization has reduced qualified supplier lists.
Active Optical Cable Market Segmentation
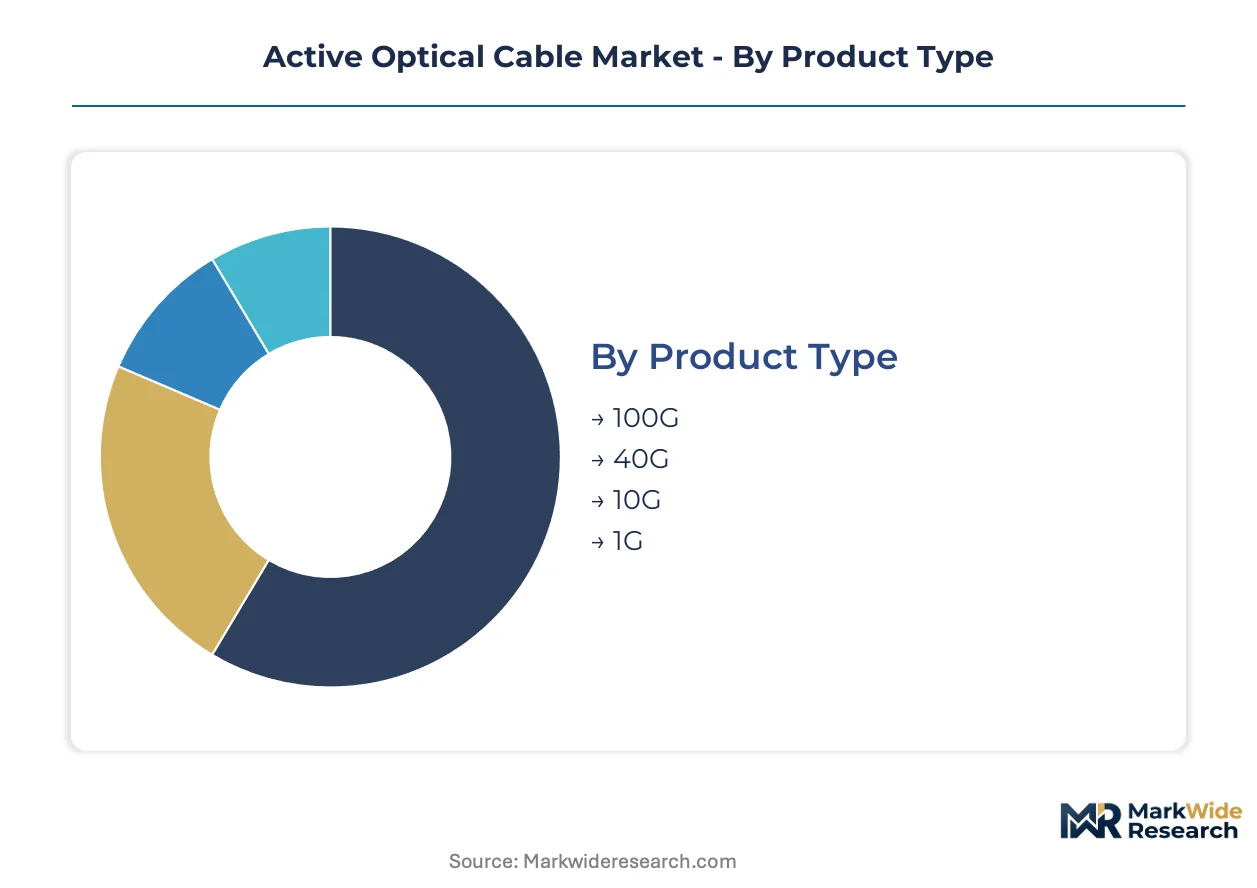
Active optical cable procurement patterns diverge sharply across speed grades, deployment environments, and connector ecosystems. Understanding these fault lines reveals where margin pools concentrate and which specifications hyperscale buyers prioritize in multi-year supply agreements.
Product Type:
Domestic absorption of 100G and 400G assemblies concentrates in United States hyperscale builds, while 10G and 1G volumes serve distributed enterprise refresh cycles across multiple geographies with longer replacement timelines.
- 100G:Dominates volume shipments into AI training clusters and cloud-scale fabrics, utilizing 850nm VCSEL arrays over multimode fiber for reaches under 100 meters. Northern Virginia and Oregon data center corridors generate sustained procurement for multi-million-port deployments, with MIIT energy-efficiency mandates in China accelerating parallel demand for certified low-power variants.
- 40G:Anchors enterprise data center modernization programs where existing switch infrastructure limits migration speed. Procurement concentrates in European and North American commercial facilities seeking intermediate bandwidth upgrades without full fabric replacement.
- 10G:Serves legacy enterprise server interconnects and industrial automation networks with stable, cost-sensitive demand.
- 1G:Persists in access-layer telecommunications and remote industrial monitoring applications with minimal growth trajectory.
100G commands the established base. The steepest expansion runs through 400G derivatives not separately itemized in standard taxonomies.
Application:
Cost tier stratification separates premium latency-optimized configurations from commodity interconnects, with pricing spreads widening as AI workloads impose stricter performance budgets.
- Data Center:Rack-dense environments systematically displace copper DACs with pluggable AOCs, driven by thermal constraints and physical space limitations. FCC equipment authorization rules govern electromagnetic emissions compliance for United States deployments, while EU RoHS and REACH directives restrict hazardous substances in cable jacketing for European facilities.
- High-Performance Computing:Strict latency budgets and custom form factors command premium pricing for specialized configurations with non-standard connector geometries. Supercomputing procurement runs through dedicated supply channels with extended qualification timelines.
- Network Communication:Telecommunications backhaul and metro aggregation utilize extended-reach variants with indium phosphide laser sources.
- Broadcast:Professional video transport applications require ruggedized cable assemblies with enhanced strain relief and environmental sealing.
Data Center absorbs the highest absolute volume. High-Performance Computing delivers the steepest margin expansion.
Connector Type:
Volume concentration favors push-pull multifiber interfaces in hyperscale procurement, while single-fiber latch mechanisms persist in enterprise and telecommunications legacy infrastructure.
- MTP/MPO:Twelve-fiber and sixteen-fiber push-pull interfaces dominate parallel optical links in cloud-scale deployments, enabling rapid polarity management and reduced installation labor. Singapore and Johor data center corridors in ASEAN are attracting localized supply chain investment to serve regional hyperscale builds.
- LC:Duplex latch-style connectors anchor enterprise storage area networks and telecommunications central office interconnects with established installation practices and broad tool compatibility.
- SC:Square push-pull housings persist in industrial and utility applications requiring positive mechanical feedback.
- E2000:Spring-loaded shuttered interfaces serve high-power laser applications and cleanroom environments with enhanced eye safety features.
MTP/MPO commands the established base. The steepest expansion runs through next-generation multifiber variants supporting 800G lane aggregation.
End User:
Customer type determines procurement channel structure, with telecommunications operators negotiating multi-year framework agreements while industrial buyers fragment across specialized distributors.
- Telecommunications:National carriers and mobile network operators consolidate AOC procurement with integrated fiber and transceiver producers, bypassing traditional distribution channels. China's MIIT certification requirements create a separate compliance pathway for domestic procurement alongside FCC and EU regulatory frameworks.
- Enterprise:Commercial data center operators balance performance requirements against capital constraints through tiered sourcing strategies.
- Industrial:Factory automation and process control networks demand temperature-hardened assemblies with extended operational ranges.
- Government:Defense and intelligence applications require domestic source verification and tamper-evident packaging protocols.
Telecommunications commands the established base. The steepest expansion runs through hyperscale-adjacent Enterprise procurement centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with United States hyperscale operators prioritizing 400G volume procurement while Chinese buyers emphasize MIIT-certified energy efficiency and European purchasers navigate REACH substance restrictions on cable assemblies.
United States
Hyperscale cloud operators in Northern Virginia and Oregon deploy multi-million-port AOC fabrics for AI training clusters, driving concentrated demand for 100G and 400G assemblies. FCC equipment authorization rules govern electromagnetic emissions compliance for pluggable optical modules. Ashburn and Hillsboro data center corridors anchor procurement volume, with direct sourcing teams negotiating multi-year supply agreements that bypass traditional distribution channels.
China
Domestic cloud providers and telecommunications operators absorb growing volumes of certified low-power modules under tightened MIIT energy-efficiency mandates for optical transceivers. GB standards and MIIT certification requirements create a separate compliance pathway distinct from FCC or EU frameworks. Yangtze River Delta manufacturing clusters host integrated fiber-drawing and transceiver assembly operations serving both domestic procurement and export demand.
Japan
Enterprise data center modernization and high-performance computing procurement sustain demand for specialized AOC configurations with strict latency budgets. METI industrial policy supports domestic silicon photonics development through targeted R&D programs. Tokyo-Osaka corridor facilities concentrate advanced packaging capabilities for wafer-level optical engine assembly.
Germany
Automotive and industrial automation sectors generate stable demand for temperature-hardened cable assemblies in factory networking applications. EU RoHS and REACH directives restrict hazardous substances in cable jacketing and connector plating, requiring accelerated material qualification programs. Bavaria-based industrial data centers anchor enterprise procurement for intermediate bandwidth upgrades.
Singapore
Hyperscale builds in Singapore and adjacent Johor corridors attract localized AOC supply chain investment to serve ASEAN data center expansion. EDB incentive programs support advanced manufacturing operations for optical components. Tuas and Jurong industrial zones concentrate fiber-assembly operations targeting regional cloud provider procurement.
Active Optical Cable Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the Active Optical Cable landscape. Captive VCSEL fabrication and in-house fiber-drawing operations distinguish the upper tier from assembly-dependent competitors. Three archetypes populate the market: vertically integrated photonics foundries controlling laser source production, integrated cable-transceiver houses with fiber manufacturing capabilities, and specialized packaging operations focused on wafer-level optical engine assembly. Competitive moves concentrate on silicon photonics retooling and multi-jurisdiction certification pre-positioning.
Within the integrated tier, Sumitomo Electric Industries and Fujikura exemplify the cable-transceiver house archetype through combined fiber and assembly operations. Broadcom anchors the photonics foundry segment. These three occupy positions that reflect divergent capital-intensity strategies: captive laser fabrication versus outsourced epitaxy, integrated fiber supply versus merchant sourcing, and wafer-level packaging versus discrete module assembly.
| Leading Market Players |
|---|
| Sumitomo Electric Industries |
| Broadcom |
| Amphenol Corporation |
| Fujikura |
| Nexans |
| Molex |
| Corning Incorporated |
| Coherent Corp. |
| TE Connectivity |
| Others |
Cost & Logistics Intelligence
Sixteen-week lead times for 850nm VCSEL epitaxy wafers concentrate pricing power among captive foundry operators in Japan and the United States, while hyperscale buyers with multi-year offtake agreements lock in volume discounts that compress spot-market margins for second-tier assemblers.
Pricing Analysis
Long-term offtake contracts dominate hyperscale procurement, with three-tier pricing structure across premium, standard, and economy levels separating MIIT-certified low-power modules from uncertified alternatives and legacy 40G inventory. Price differentiation hinges on energy-efficiency certification tier and volume scale, with 100G assemblies facing cost compression as silicon photonics alternatives enter pilot deployment. Enterprise buyers exhibit highest price sensitivity, while HPC procurement accepts premiums for custom form factors.
Supply Chain Analysis
Strategic stockpiling of indium phosphide laser wafers characterizes extended-reach module production, contrasting with just-in-time fiber inventory at cable-assembly houses. Manufacturing concentrates in China, Japan, and the United States, with raw material dependencies spanning gallium arsenide substrates, specialty optical fiber, and ceramic ferrules. Single-source vulnerability in VCSEL epitaxy capacity feeds from concentrated specialty foundry output. Distribution runs through direct sourcing teams at hyperscale operators, bypassing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent suppliers must defend against silicon photonics substitution that threatens to displace discrete transceiver architectures without requiring module redesign, eroding the addressable market for traditional pluggable AOCs in highest-density AI deployments.
For Market Incumbents: Secure captive VCSEL fabrication capacity or binding supply agreements with specialty epitaxy houses to defend against allocation risk during hyperscale buildout surges. Accelerate wafer-level packaging qualification to maintain relevance as co-packaged optics compress upgrade cycles. For New Entrants and Emerging Players: Anchor in ASEAN data center corridors where Singapore and Johor hyperscale builds require localized fiber-assembly operations without established incumbent presence. Target temperature-hardened industrial automation segments with extended operational range specifications that fall outside hyperscale procurement concentration. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized photonics divisions lacking hyperscale customer relationships. Long-term viability favors integrated cable-transceiver houses with fiber-drawing capabilities. Watch silicon photonics pilot deployment timelines at Northern Virginia cloud operators as inflection indicator for traditional module obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Retooling | Wafer-level optical engine assembly addresses MIIT energy-efficiency mandates and hyperscale co-packaged optics demand. |
| ASEAN Manufacturing Footprint | Singapore and Johor facilities capture localized supply chain requirements from regional hyperscale expansion. |
| Multi-Jurisdiction Certification Pre-Positioning | Simultaneous FCC, EU REACH, and MIIT compliance reduces validation timelines for global cloud provider procurement. |
| Captive VCSEL Capacity Expansion | In-house 850nm epitaxy fabrication secures margin control and allocation priority during demand surges. |
| High-Performance Computing Custom Form Factor Development | Specialized non-standard connector geometries command premium pricing in supercomputing procurement channels. |
Research Approach
A spread of perspectives from hyperscale data center procurement directors, optical transceiver engineering leads, fiber-cable plant managers, and regulatory compliance officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FCC equipment authorization filings, MIIT certification databases, EU REACH substance restriction updates, and hyperscaler capital expenditure disclosures. Bottom-up shipment estimates triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled include speed grade, deployment environment, connector ecosystem, and geographic regulatory cluster throughout the forecast period. CAGRs derived from shipment volume trajectories and average selling price evolution, with forecast inputs incorporating AI training cluster buildout schedules, MIIT mandate implementation timelines, and silicon photonics substitution curves.
Material uncertainties — silicon photonics commercialization acceleration, VCSEL epitaxy capacity expansion decisions, and ASEAN data center construction delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding hyperscale procurement centralization and energy-efficiency certification adoption. Revision becomes warranted when co-packaged optics deployment crosses pilot-to-production thresholds at major cloud operators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
USB Cable Market
Cables
Asia-Pacific Premise Cable Market
Cables
Cable Detector Market
Cables
Asia-Pacific Cable Joints Market
Cables
HVDC Cables Market
Cables
Global Cable Blowing Equipment Market
Cables
FFC/FPC Jumper Cables Market
Cables
Europe Wire and Cable Market
Cables
Usb Data Cable Market
Cables
LED Cable Market
Cables
Europe Cable Joints Market
Cables
Low Voltage Cable Accessories Market
Cables
United States Cable Accessories Market
Cables
Submarine Data Cables Market
Cables
Underground Cable Market
Cables
India Optic Fiber Cable and Accessories Market