
 Patch Cable Market | 2026-2036
Patch Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Patch Cable Market Intelligence
Value-added services like pre-terminated custom assemblies is reshaping margin pools away from bulk, un-terminated cable sales. CommScope leverages its extensive product portfolio to serve hyperscale data center clients across copper and fiber. Corning specializes in advanced fiber optic solutions, leading in high-bandwidth applications. Panduit differentiates through its comprehensive infrastructure solutions, including connectivity, cable management, and thermal management products for network environments.
A patch cable is a length of electrical or optical fiber cable terminated with connectors at each end for signal routing between devices. These components are manufactured to specific standards, such as maintaining a 100-ohm impedance for twisted-pair copper cables. Fiber optic cables represent the fastest-growing product type, driven by bandwidth needs in data centers. The telecommunication networks application demands high-reliability products, contrasting with the price-sensitive home networking segment.
Product compliance is shaped by frameworks like the EU's RoHS directive, which restricts hazardous materials, and performance standards enforced by bodies like the Underwriters Laboratories (UL) in the United States. These regulations directly influence material sourcing and market access. Navigating the divergent performance requirements between copper and fiber optic technologies for next-generation network deployments remains a central strategic decision for end users.
Market Dynamics
The structural transition to 400G and 800G Ethernet architectures within data centers is the central force shaping the patch cable market. This shift necessitates higher-specification fiber optic and copper cabling, altering end-user procurement criteria and supply chain priorities.
Growth Catalysts
- Hyperscale Data Center Expansion:New facilities in the United States and Ireland drive volume procurement of high-speed fiber optic patch cables for cloud services.
- 5G Network Densification:Government initiatives promoting 5G infrastructure, overseen by bodies like the FCC, necessitate extensive fiber connectivity for cell sites.
- Industrial IoT Integration:The growth of smart factories requires robust, shielded copper cabling for reliable machine-to-machine communication on the factory floor.
Market Restraints
- Input Cost Volatility:Fluctuations in copper and fluoropolymer prices impact manufacturer margins and create pricing instability for bulk cable procurement.
- Wireless Substitution:Performance gains in Wi-Fi 7 reduce the need for physical cabling in some enterprise and campus networking applications.
- Certification Barriers:The high cost and long timelines for achieving UL performance certifications for next-generation cable designs deter smaller innovators.
Strategic Opportunities
- Edge Computing Infrastructure:The build-out of edge data centers in markets like Brazil and India creates demand for modular cabling solutions.
- Automotive Ethernet:The adoption of Ethernet for in-vehicle ADAS and infotainment systems opens a new market for specialized, durable cables.
- Value-Added Assemblies:Services for pre-terminated, custom-length assemblies capture higher margins by reducing on-site labor and improving installation quality for end-users.
Industry Challenges
- Divergent Supply Chains:Managing distinct supply chains for copper cables and fiber optic cables, which depend on different raw materials, is a major operational challenge.
- Skilled Labor Scarcity:A shortage of technicians certified in advanced fiber optic testing and termination slows deployment and increases labor costs for network upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patch Cable Market |
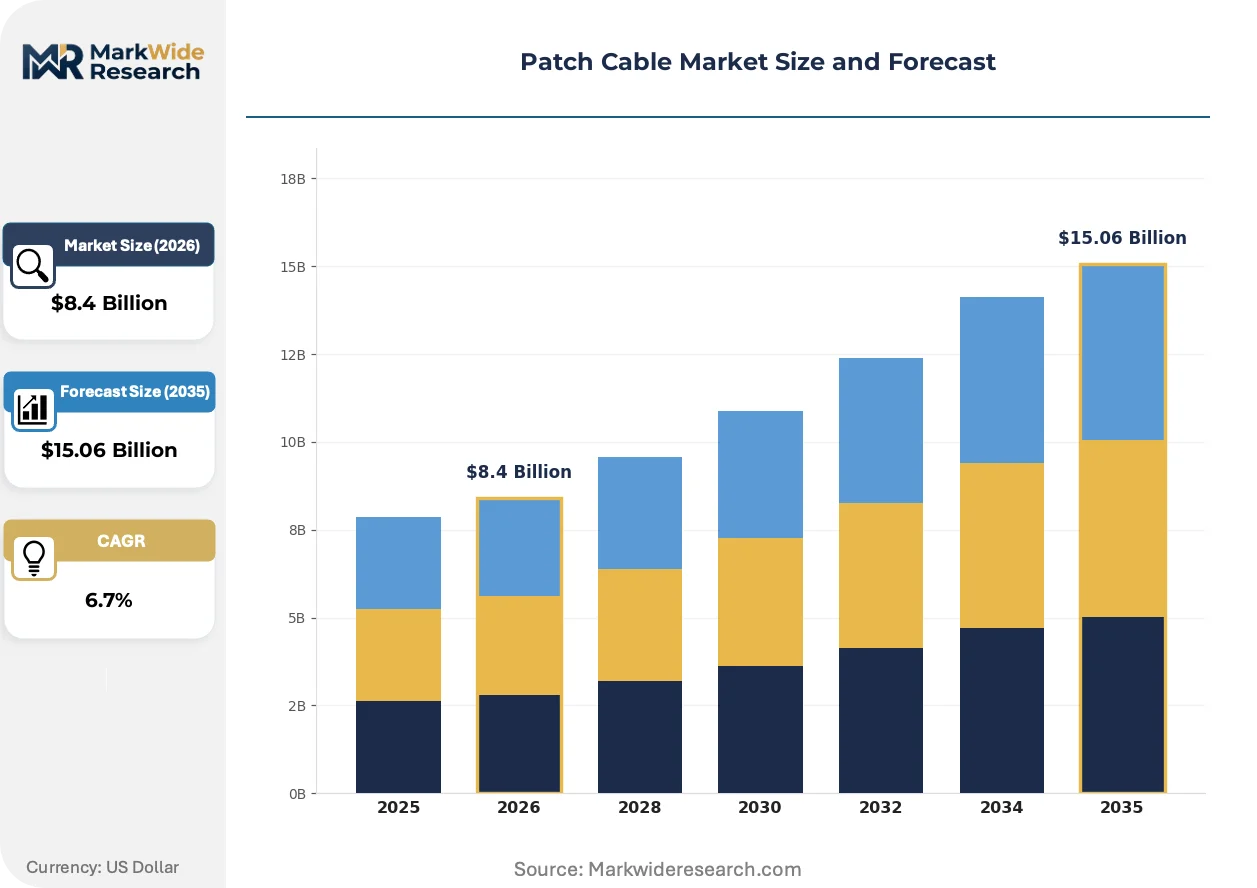
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cat5, Cat6, Cat6a, Cat7, Fiber Optic, Coaxial Application: Data Centers, Telecommunication Networks, Server Rooms, Audio/Video Systems, Home Networking, Network Testing Connector Type: RJ45, LC, SC, ST, BNC, USB End User: Internet Service Providers, Data Hosting Services, Broadcast Services, Telecommunications Equipment Manufacturers, IT Enterprises, Network Service Providers |
| Companies Covered | CommScope, Corning Incorporated, Belden Inc., Panduit, Legrand, Siemon, Leviton Manufacturing Co., Inc., Schneider Electric SE, Prysmian Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patch Cable Market Strategic Shifts & Innovations
The patch cable market is evolving from a component-centric model to one focused on integrated infrastructure. This transition is driven by the need for greater network intelligence, simplified deployment, and compliance with stringent environmental regulations.
Single-pair Ethernet (SPE) delivers power and data over a single twisted pair, optimized for IoT and industrial devices. The automotive and industrial automation sectors are early adopters, valuing its reduced size and cost. SPE is hybridizing the network edge, allowing legacy fieldbus systems and modern IP networks to coexist on a unified cabling infrastructure.
European Union regulations like the RoHS directive and the Corporate Sustainability Reporting Directive (CSRD) tighten material and supply chain scrutiny. These frameworks compel manufacturers to eliminate hazardous substances and report on the environmental impact of their products. Cable producers targeting the EU market must invest in compliant material sourcing and transparent lifecycle documentation to maintain access.
Direct sourcing and co-development models are altering purchasing dynamics for high-volume components. Hyperscale data center operators now bypass traditional distributors to work with manufacturers on custom-specified cabling. This trend is most prominent in the United States, giving buyers greater control over product performance and supply chain logistics.
Patch Cable Market Segmentation
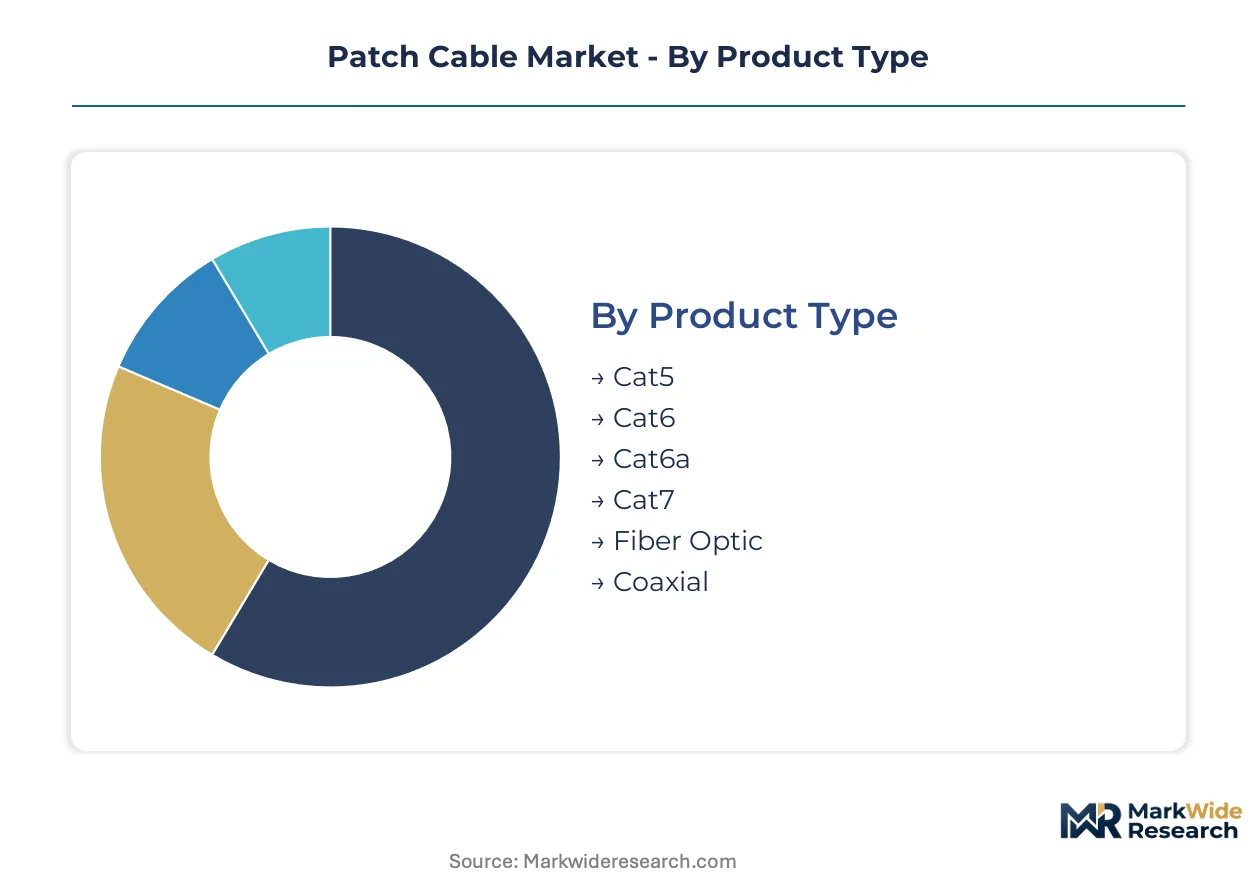
The patch cable market segments by distinct technical specifications and end-use environments. Understanding these divisions allows for precise targeting of product development and supply chain investments. Specific product types address varying bandwidth requirements, while application segments highlight diverse operational needs.
Product Type:
The product type segmentation reveals a market with both mature and rapidly expanding technologies. Copper-based cables like Cat5 and Cat6 maintain a significant installed base, while fiber optic solutions represent future growth.
- Cat5:These unshielded twisted pair cables support up to 100 Mbps over 100 meters, primarily found in legacy network installations. Demand for Cat5 patch cables has largely shifted to replacement cycles rather than new deployments.
- Cat6:Offering up to 1 Gbps over 100 meters, Cat6 cables are common in enterprise networks and small data centers. This cable type balances performance with cost-effectiveness for everyday Ethernet connections.
- Cat6a:Augmented Category 6 cables support 10 Gigabit Ethernet over 100 meters, crucial for high-density server rooms and data center interconnects. Hyperscale data center construction in the United States and Ireland drives significant procurement of these higher-specification copper solutions.
- Cat7:Shielded to reduce crosstalk, Cat7 cables provide 10 Gigabit Ethernet performance with enhanced noise immunity, suitable for specialized industrial environments. Adoption is less widespread due to higher cost and installation complexity compared to Cat6a.
- Fiber Optic:These cables transmit data using light pulses, supporting speeds up to 800G Ethernet for ultra-high bandwidth applications in data centers. The structural transition to 400G and 800G architectures necessitates extensive fiber optic cabling, particularly for hyperscale facilities in Singapore.
- Coaxial:Primarily used for video, satellite, and older broadband connections, coaxial cables have specific impedance characteristics. Broadcast services and legacy telecommunication infrastructure still require these robust, shielded cables.
Fiber Optic handles the majority of throughput; Cat6a is the fastest mover on share.
Application:
Application segments delineate where patch cables are deployed, reflecting diverse performance and reliability requirements. Each segment prioritizes different attributes, from high bandwidth to cost efficiency.
- Data Centers:These facilities demand high-density, high-bandwidth patch cables to support 400G and 800G Ethernet architectures. Network upgrades within data centers represent a primary growth driver for fiber optic solutions.
- Telecommunication Networks:This segment requires high-reliability, often outdoor-rated patch cables for connecting network equipment and cell sites. 5G network densification, supported by government initiatives, drives substantial fiber connectivity demand in markets like India.
- Server Rooms:These environments utilize a mix of copper and fiber patch cables for connecting servers, switches, and storage devices. Efficient cable management and robust connectivity are essential for maintaining uptime in server rooms.
- Audio/Video Systems:Specialized patch cables with specific impedance and shielding characteristics connect professional audio and video equipment. Broadcast studios and large event venues rely on these components for signal integrity.
- Home Networking:This price-sensitive segment uses standard copper patch cables for connecting consumer devices like routers, computers, and smart TVs. Wi-Fi 7 performance gains reduce the need for physical cabling in some home setups.
- Network Testing:High-quality, often custom-length patch cables are essential for diagnostic equipment and network performance validation. Precision and consistency are paramount for accurate testing results.
Demand for Data Centers remains foundational, while Telecommunication Networks drives innovation.
Connector Type:
The connector type segmentation highlights the various physical interfaces used to terminate patch cables, each suited to specific cable types and applications. These connectors ensure signal integrity and proper physical connection.
- RJ45:This is the standard connector for twisted-pair copper Ethernet cables, ubiquitous in enterprise networks and home networking. Its widespread adoption ensures compatibility across a vast range of networking equipment.
- LC:A small form-factor fiber optic connector, LC is prevalent in data centers and high-density network environments due to its compact size. Hyperscale operators frequently specify LC connectors for their fiber optic patch cables.
- SC:A larger, square-shaped fiber optic connector, SC is common in telecommunication networks and older fiber installations. Its robust design provides reliable connections for various fiber optic applications.
- ST:Featuring a bayonet-style twist-on mechanism, ST connectors are often found in campus networks and industrial fiber optic systems. Their secure connection makes them suitable for environments with potential vibration.
- BNC:Primarily used for coaxial cables in video, radio, and test equipment applications, BNC connectors offer a secure, quick-connect interface. Broadcast services rely on BNC for their video infrastructure.
- USB:While not a traditional patch cable connector, USB is used for device-to-device data transfer and power, particularly in industrial IoT. Specialized USB cables connect sensors and control systems in smart factories.
RJ45 dominates installations, with LC expanding most quickly.
End User:
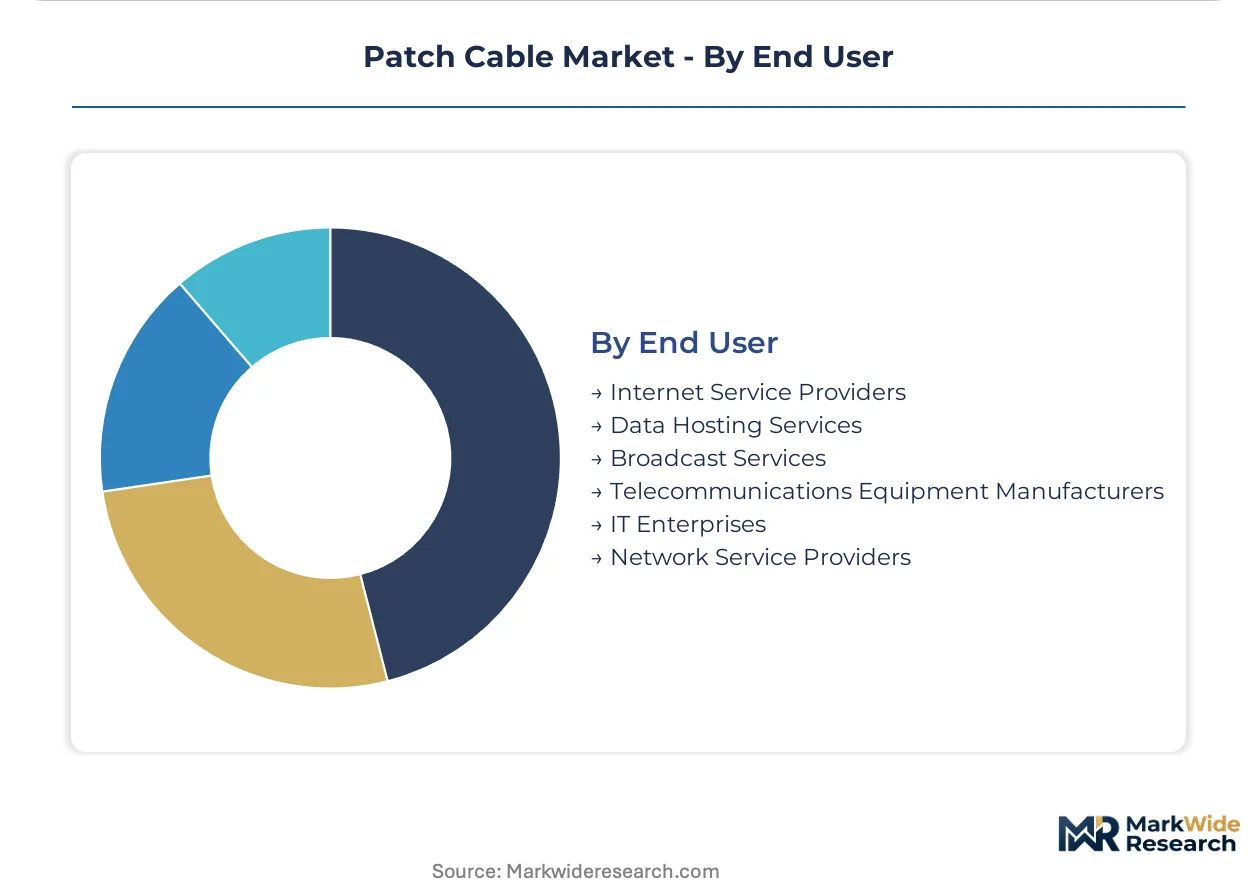
End-user segments reveal the primary customer groups purchasing patch cables, each with distinct procurement patterns and technical requirements. Hyperscale operators represent a significant volume driver.
- Internet Service Providers:These entities procure extensive volumes of fiber optic patch cables for their backbone networks and last-mile connectivity. 5G network densification initiatives in countries like the United States increase demand.
- Data Hosting Services:Companies offering cloud computing and data storage require high-speed fiber optic patch cables for their data centers. Hyperscale facilities in Ireland drive high-volume procurement for these services.
- Broadcast Services:This segment utilizes specialized coaxial and fiber optic patch cables for transmitting audio and video signals. Reliability and signal quality are critical for live productions and content delivery.
- Telecommunications Equipment Manufacturers:These companies integrate patch cables into their network infrastructure products, requiring consistent quality and compliance. They often work with manufacturers on custom specifications.
- IT Enterprises:Businesses across all sectors purchase copper and fiber patch cables for their internal network infrastructure. They prioritize a balance of performance, cost, and ease of installation.
- Network Service Providers:These companies manage and maintain network infrastructure for clients, sourcing a diverse range of patch cables. They often seek value-added services like pre-terminated assemblies.
Internet Service Providers represent a foundational volume base, with Data Hosting Services exhibiting steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption-mix differential for patch cables varies significantly across major global economies, reflecting distinct infrastructure development stages and technological adoption rates. Data centers in highly digitized markets prioritize fiber optic solutions for ultra-high bandwidth, while emerging regions often balance copper and fiber based on cost and immediate connectivity needs. Government initiatives and regulatory frameworks further shape procurement patterns and deployment strategies.
United States
Hyperscale data center expansion and 5G network densification drive substantial demand for high-speed fiber optic patch cables. The FCC's initiatives to expand broadband access across rural areas necessitate extensive fiber connectivity. Major cloud providers concentrate their build-outs in states like Virginia and Texas, creating significant procurement volumes for advanced cabling.
Germany
Industrial IoT integration and automotive Ethernet adoption are key demand drivers for robust, shielded copper and specialized fiber optic cables. Germany's national digital agenda promotes high-speed network infrastructure, influencing telecommunication network upgrades. The manufacturing heartland in Bavaria and Baden-Württemberg requires reliable connectivity for smart factory deployments.
Singapore
Ultra-high bandwidth requirements in data centers, particularly for 400G and 800G Ethernet architectures, fuel demand for advanced fiber optic patch cables. The Infocomm Media Development Authority (IMDA) supports the development of a resilient digital infrastructure. Singapore's role as a regional data hub concentrates significant fiber optic procurement for hyperscale facilities.
India
Telecommunication network expansion and the build-out of edge computing infrastructure generate demand for both fiber optic and modular copper cabling solutions. The PLI scheme for telecom and networking products encourages domestic manufacturing and deployment. Major metropolitan areas like Bangalore and Mumbai are seeing substantial investment in new data centers and network upgrades.
Ireland
Data hosting services and hyperscale data center construction represent primary demand drivers for high-volume fiber optic patch cables. The IDA Ireland promotes foreign direct investment in digital infrastructure, attracting major tech companies. Dublin and its surrounding areas host a high concentration of these facilities, necessitating vast quantities of advanced connectivity solutions.
Patch Cable Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a tiered market structure for patch cables. The market exhibits a mix of large, diversified infrastructure providers and specialized component manufacturers. Strategic archetypes include integrated solution providers, fiber optic specialists, and niche copper cable manufacturers. Portfolio diversification into value-added services and geographic expansion are common competitive moves.
Specialists in advanced connectivity solutions, such as CommScope, leverage extensive product portfolios to serve hyperscale data center clients across both copper and fiber. Corning Incorporated exemplifies leadership in high-bandwidth applications, focusing on advanced fiber optic solutions. Panduit differentiates through comprehensive infrastructure offerings, including connectivity and cable management products for complex network environments.
| Leading Market Players |
|---|
| CommScope |
| Corning Incorporated |
| Belden Inc. |
| Panduit |
| Legrand |
| Siemon |
| Leviton Manufacturing Co., Inc. |
| Schneider Electric SE |
| Prysmian Group |
| Others |
Cost & Logistics Intelligence
Southeast Asian manufacturing clusters' high-volume production capacity directly influences global patch cable pricing. This concentration of supply drives cost efficiencies, but also creates vulnerability to regional disruptions.
Pricing Analysis
Long-term offtake agreements characterize pricing for high-volume patch cable procurement by hyperscale data centers. Price differentiation stems from UL performance certification levels and the volume scale of orders. Cost compression intensifies due to volatile copper and fluoropolymer input prices. The home networking segment exhibits the highest price sensitivity, while hyperscale data centers prioritize performance and reliability over marginal cost savings.
Supply Chain Analysis
Contract manufacturers in China, Vietnam, and Mexico concentrate significant patch cable production capacity. The supply chain relies on critical raw materials such as copper, optical fiber, and fluoropolymers. Input cost volatility remains a structural risk, impacting manufacturer margins and procurement stability. Hyperscale data centers increasingly favor direct sourcing and co-development models, while traditional distributors serve a broader market.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The patch cable market presents a fragmentation opportunity, driven by the structural transition to 400G and 800G Ethernet architectures. This shift creates specialized niches for high-performance cabling solutions across various applications.
For Market Incumbents: Entrench market leadership by investing heavily in advanced fiber optic R&D for 800G and beyond. Consolidate market share through strategic acquisitions of specialized connectivity providers to expand portfolio depth. Wireless substitution, particularly Wi-Fi 7, poses a threat to traditional copper cabling in enterprise settings. Prioritize certification investment in UL performance standards to maintain a competitive edge and market access.
For New Entrants and Emerging Players: Build out specialized product lines targeting edge computing infrastructure in markets like India and Brazil. Focus on Automotive Ethernet solutions, which offer a new market for durable, high-reliability cables. Modular cabling solutions for these nascent edge deployments represent the most penetrable segment. A strong go-to-market angle involves offering value-added services like pre-terminated custom assemblies to reduce installation complexity.
For Investors and Strategic Acquirers: Long-term, this sits as a critical infrastructure play because global data consumption and network upgrades show no signs of abatement. Target acquisition archetypes include vertically integrated mid-cap specialists with strong positions in advanced fiber optic solutions. A key signal to watch as an inflection indicator is the consistent capital expenditure spending trends by hyperscale data center operators. Regulatory shifts, such as new EU RoHS directives, also present opportunities for compliant manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Line Diversification | Expands offerings to include specialized fiber optic cables for 800G Ethernet architectures. |
| Geographic Market Expansion | Targets emerging edge computing markets in India and Brazil for new demand. |
| Advanced Material Sourcing | Secures supply of fluoropolymers and optical fiber to mitigate input cost volatility. |
| Strategic Partnership | Collaborates with hyperscale data center operators for custom-specified cabling solutions. |
| Certification Investment | Ensures compliance with UL performance standards and EU RoHS directives for market access. |
Research Approach
Findings reconcile primary fieldwork against secondary review of industry association reports, government infrastructure initiatives, and company financial disclosures. Primary interviews included data center architects, telecom network engineers, procurement managers, and industrial IoT specialists. This approach ensured a robust understanding of market dynamics through both bottom-up and top-down triangulation. Academic publications also provided context for technological advancements.
Forecast inputs considered included historical growth rates, projected technology adoption, and expert consensus from industry practitioners. The analytical framework integrated quantitative models with qualitative insights across the analysis window. Segmentation dimensions modeled included product type, application, connector type, end-user, and regional infrastructure development. Key industry-specific inputs were 5G network rollout schedules and hyperscale data center construction pipelines.
Practitioners should monitor geopolitical tensions, raw material supply disruptions, and rapid technological obsolescence for early signals of market shifts. Forecasts reflect assumptions documented at the time of publication, acknowledging these inherent risk factors. Quarterly review of hyperscale build-out schedules and input commodity prices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
USB Cable Market
Cables
Cable Testers Market
Cables
Anti-Static Space Wires Market
Cables
Medium Voltage Cables Market
Cables
Cable Organisers Market
Cables
Asia-Pacific Cable Joints Market
Cables
Asia Pacific MV and HV Underground Cables and Accessories Market
Cables
High Voltage Cables Market
Cables
India Wire and Cable Market
Cables
North America Coaxial Cable Market
Cables
Copper Cable Market
Cables
Audio and Video Cables Market
Cables
North America HVAC Cables Market
Cables
GCC Cable Accessories Market
Cables
Wire and Cable Label Market
Cables
Europe Cable Management Market