
 Base Station Antenna Market | 2026-2036
Base Station Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Base Station Antenna Market Analysis
FCC mid-band spectrum auctions are repositioning the cost structure for antenna qualification and network deployment. Huawei Technologies Co. Ltd. leverages integrated radio-access portfolios to sustain pricing power across emerging markets. Ericsson AB anchors European supply chains through localized manufacturing footprints in Germany and Poland. Nokia Corporation competes on Open RAN interoperability, differentiating its antenna-radio combinations for multi-vendor network architectures.
Base station antennas are radio-frequency transducers engineered to radiate and receive electromagnetic signals across designated cellular bands, typically operating between 600 MHz and 6 GHz for macro deployments while extending into millimeter-wave spectra for dense urban 5G. Their primary commercial purpose is to establish directional or omnidirectional coverage patterns that maximize spectral efficiency and minimize interference across geographic cells. Passive antennas retain dominant volume share in retrofit markets where operators prioritize capital preservation, while active antenna systems with integrated transceivers capture expanding share in greenfield 5G builds where tower loading constraints favor consolidation. Smart antennas employing beamforming algorithms represent the fastest-expanding margin pool as Massive MIMO configurations become standard for capacity-layer deployments.
EMA equipment authorization frameworks in Europe, FCC OET certification requirements in the United States, and MIIT radio transmission equipment type-approval rules in China collectively dictate electromagnetic compatibility thresholds, radiation exposure limits, and environmental testing protocols that vendors must satisfy before commercial placement. These regulatory barriers extend development cycles by twelve to eighteen months but simultaneously insulate qualified manufacturers from commoditization pressures. Stakeholders must monitor spectrum reallocation proceedings and Open RAN security mandates as these proceedings will determine which antenna architectures qualify for public-safety and defense-adjacent network tenders.
Market Dynamics
Massive MIMO beamforming architectures are compressing deployment economics for 5G capacity layers, forcing passive-to-active antenna transitions that reshape vendor qualification requirements and tower loading specifications simultaneously.
Growth Catalysts
- MIIT Base Station Densification Mandates:China's Ministry of Industry and Information Technology has imposed aggressive coverage targets that compel state-owned carriers to triple macro site counts in tier-2 cities.
- Millimeter-Wave Spectrum Commercialization:Dense urban corridors in the United States and South Korea are activating 28 GHz and 39 GHz bands for fixed wireless access, requiring new antenna form factors with integrated beam-steering capabilities.
- Open RAN Interoperability Standards:The O-RAN Alliance's fronthaul specifications are unlocking multi-vendor procurement for radio units and antennas, fragmenting incumbent supply relationships.
Market Restraints
- Compound Semiconductor Supply Concentration:Gallium nitride and silicon germanium substrate fabrication concentrates in Taiwanese and South Korean foundries, exposing antenna OEMs to geopolitical supply interruptions.
- Electromagnetic Compatibility Certification Friction:FCC OET and EMA equipment authorization cycles extend twelve to eighteen months, freezing product roadmaps and delaying revenue recognition for new antenna variants.
- Passive Retrofit Preference:Capital-constrained operators in emerging markets favor refurbishing legacy antenna installations over greenfield active antenna system deployments, capping average selling price expansion.
Strategic Opportunities
- India's PLI Scheme for Telecom Equipment:Production-linked incentive structures are attracting antenna manufacturing investments to Gujarat and Tamil Nadu, creating localized supply hubs for South Asian network builds.
- Private 5G Network Deployments:Manufacturing campuses, mining operations, and port authorities are procuring dedicated base station antennas outside carrier procurement channels, opening enterprise-direct revenue streams.
- Beamforming-on-Silicon Convergence:Integration of phased-array control electronics onto CMOS substrates is collapsing radio and antenna boundaries, enabling new entrants with semiconductor heritage to capture RF front-end value.
Industry Challenges
- RF Engineer Talent Scarcity:Electromagnetic simulation expertise and antenna pattern optimization skills command premium compensation, constraining R&D throughput for mid-tier vendors.
- Legacy 2G/3G Decommissioning Coordination:Operators must synchronize antenna swap schedules with spectrum re-farming timelines, complicating inventory planning and field engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Base Station Antenna Market |
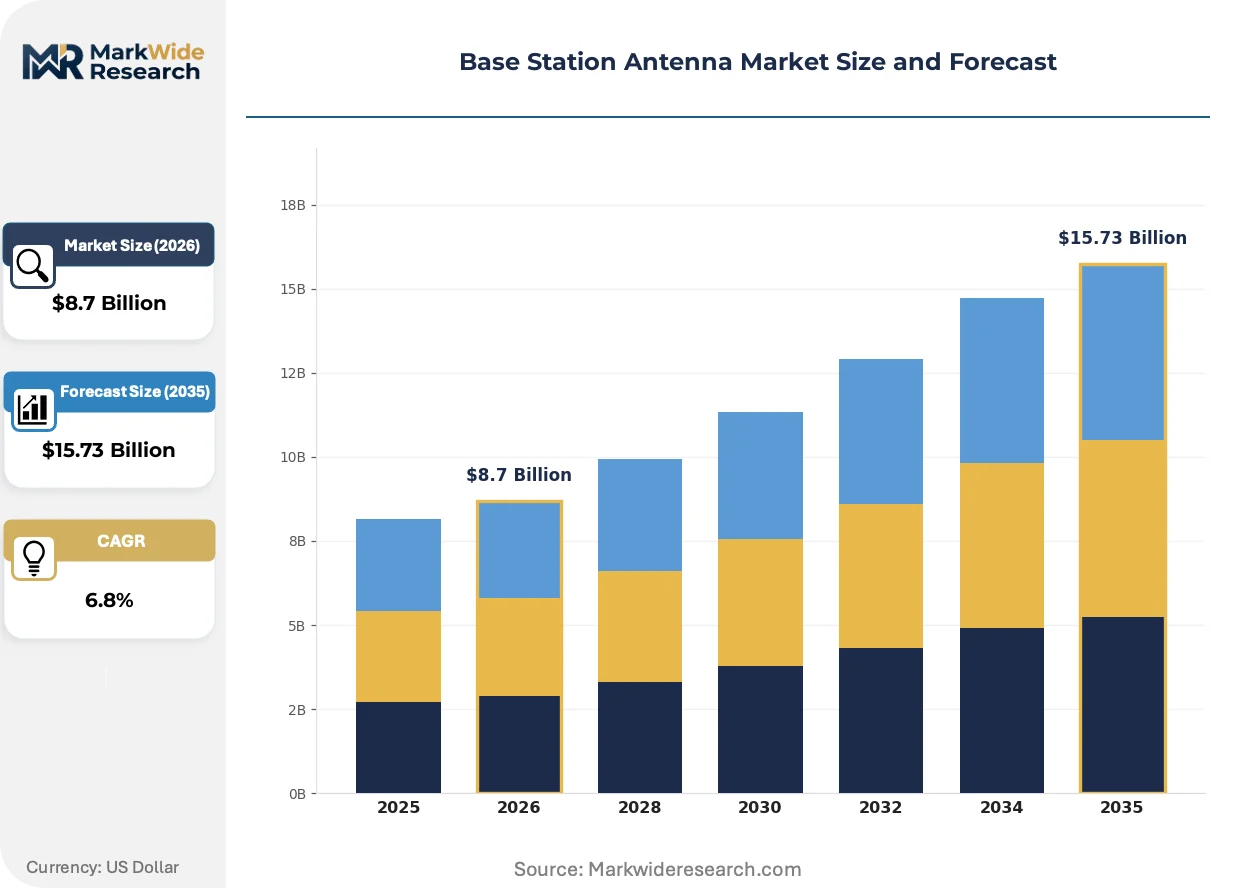
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Antennas, Active Antennas, Smart Antennas, Distributed Antennas Technology: 4G, 5G, LTE, Wi-Fi End User: Telecom Operators, Enterprises, Government, Service Providers Installation: Indoor, Outdoor, Rooftop, Pole-Mounted |
| Companies Covered | Huawei Technologies Co. Ltd., Ericsson AB, Nokia Corporation, CommScope Holding Company, Inc., Kathrein SE, Amphenol Corporation, Ace Technologies Corporation, RFS (Radio Frequency Systems), Comba Telecom Systems Holdings Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Base Station Antenna Market Emerging Trajectories
Antenna systems are evolving from passive radiating elements toward software-defined apertures with embedded intelligence, compressing the traditional boundary between RF hardware and baseband processing.
Digital beamforming silicon is automating real-time pattern adaptation for interference nulling and user-specific signal enhancement. Tier-1 carriers in South Korea and Japan are deploying these systems in stadium and transit hub deployments. The technology is automating site-specific optimization tasks previously requiring manual electrical tilt adjustments, reducing recurring engineering site visits.
REACH restrictions on per- and polyfluoroalkyl substances are forcing antenna manufacturers to reformulate radome materials and cable jacketing compounds. European OEMs face compliance deadlines that compress supplier qualification windows. Vendors serving Germany and France are accelerating bio-based polymer validation programs to maintain CE marking eligibility.
Carrier procurement organizations are consolidating antenna-radio unit sourcing decisions under single vendor accountability frameworks. Traditional antenna specialists now compete against integrated radio-access network suppliers for combined awards. This concentration is most pronounced in United States RFP processes where FCC buildout deadlines leave limited tolerance for multi-vendor integration risk.
Base Station Antenna Market Segmentation
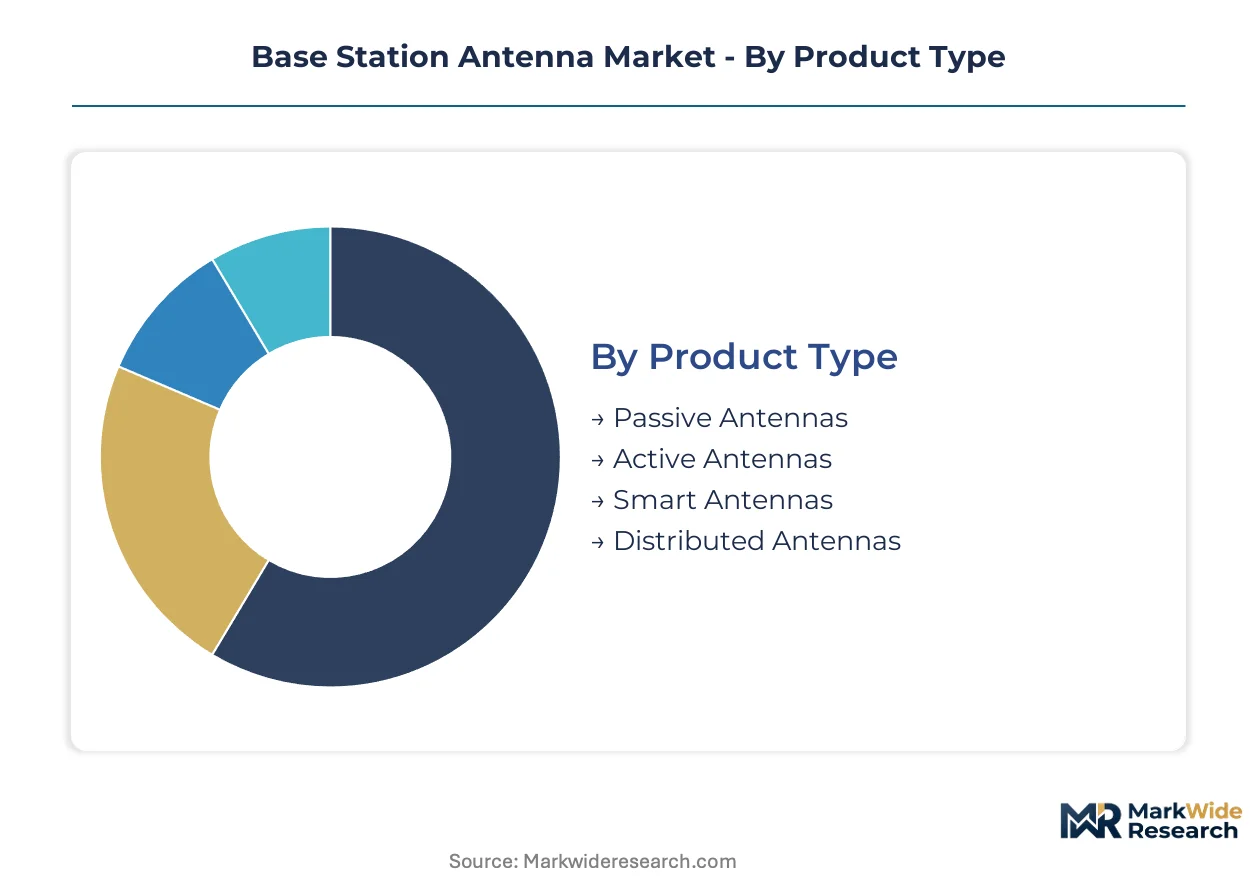
Base station antenna procurement decisions fragment across technical specifications, deployment environments, and regulatory compliance tiers. Each segment carries distinct certification burdens and margin profiles that reshape vendor positioning strategies.
Product Type:
FCC OET certification cycles vary sharply across this category, with active antennas requiring integrated radio equipment authorization while passive units face streamlined electromagnetic compliance testing.
- Passive Antennas:Radiating elements without integrated transceivers, constructed from aluminum alloys and dielectric substrates. Demand concentrates in India's tier-2 and tier-3 urban corridors where TRAI-mandated coverage expansion strains capital budgets. Operators favor passive refurbishment to preserve tower loading capacity and avoid active system integration complexity.
- Active Antennas:Integrated transceiver modules with embedded power amplifiers and filtering stages. Deployment accelerates across China's eastern seaboard cities where MIIT densification mandates compress installation timelines. Tower weight constraints and single-vendor accountability frameworks favor active consolidation in greenfield 5G builds.
- Smart Antennas:Beamforming arrays with embedded digital signal processing for real-time pattern adaptation. South Korean stadium and transit hub deployments drive procurement volumes.
- Distributed Antennas:Remote radio heads connected via fiber optic fronthaul for indoor coverage extension. German airport and healthcare campus installations anchor European demand.
Passive Antennas sits at the top of the volume ranking, with Active Antennas climbing the fastest.
Technology:
Cost tier stratification separates legacy spectrum equipment from millimeter-wave capable systems, with 5G-capable units commanding premium positioning against depreciating 4G inventory.
- 4G:Mature macro coverage systems operating across 700 MHz to 2.6 GHz bands. Refurbishment demand persists in Brazil and Indonesia where ANATEL and SDPPI timelines lag developed market decommissioning curves.
- 5G:Massive MIMO configurations with 64T64R and 32T32R element arrays. Deployment concentrates in United States urban corridors where FCC mid-band auction winners face compressed buildout deadlines. Beam-steering silicon integration differentiates vendor offerings.
- LTE:Interim capacity layer equipment bridging 4G infrastructure toward 5G non-standalone architectures. African and Southeast Asian operators prioritize LTE antenna swaps during spectrum re-farming transitions.
- Wi-Fi:Unlicensed spectrum access points for enterprise offload and private network extension. Manufacturing campus deployments in Japan's Aichi prefecture drive specialized form factor demand.
5G captures the steepest expansion trajectory as carrier procurement shifts toward capacity-layer densification, while 4G retains residual volume in emerging market retrofit cycles.
End User:
Customer type determines procurement channel structure, with telecom operators consolidating through carrier-grade certification frameworks while enterprises and government buyers operate outside traditional vendor qualification pathways.
- Telecom Operators:Tier-1 mobile network operators with FCC, EMA, or MIIT-mandated equipment authorization requirements. China Mobile, Verizon, and Deutsche Telekom anchor global procurement volumes through centralized RFP processes.
- Enterprises:Manufacturing, mining, and logistics campus operators procuring private 5G networks. German automotive facilities in Bavaria and Baden-Württemberg deploy dedicated antenna systems outside carrier channels.
- Government:Defense-adjacent and public-safety network tenders with enhanced security screening. United States FirstNet deployments impose additional supply chain verification beyond standard FCC certification.
- Service Providers:Neutral host and infrastructure-as-a-service operators aggregating multi-tenant antenna assets. Tower companies in the United States and Spain consolidate antenna-radio sourcing under single-vendor accountability.
Telecom Operators dominate procurement volume, with Enterprises gaining share fastest as private network deployments bypass traditional carrier channels.
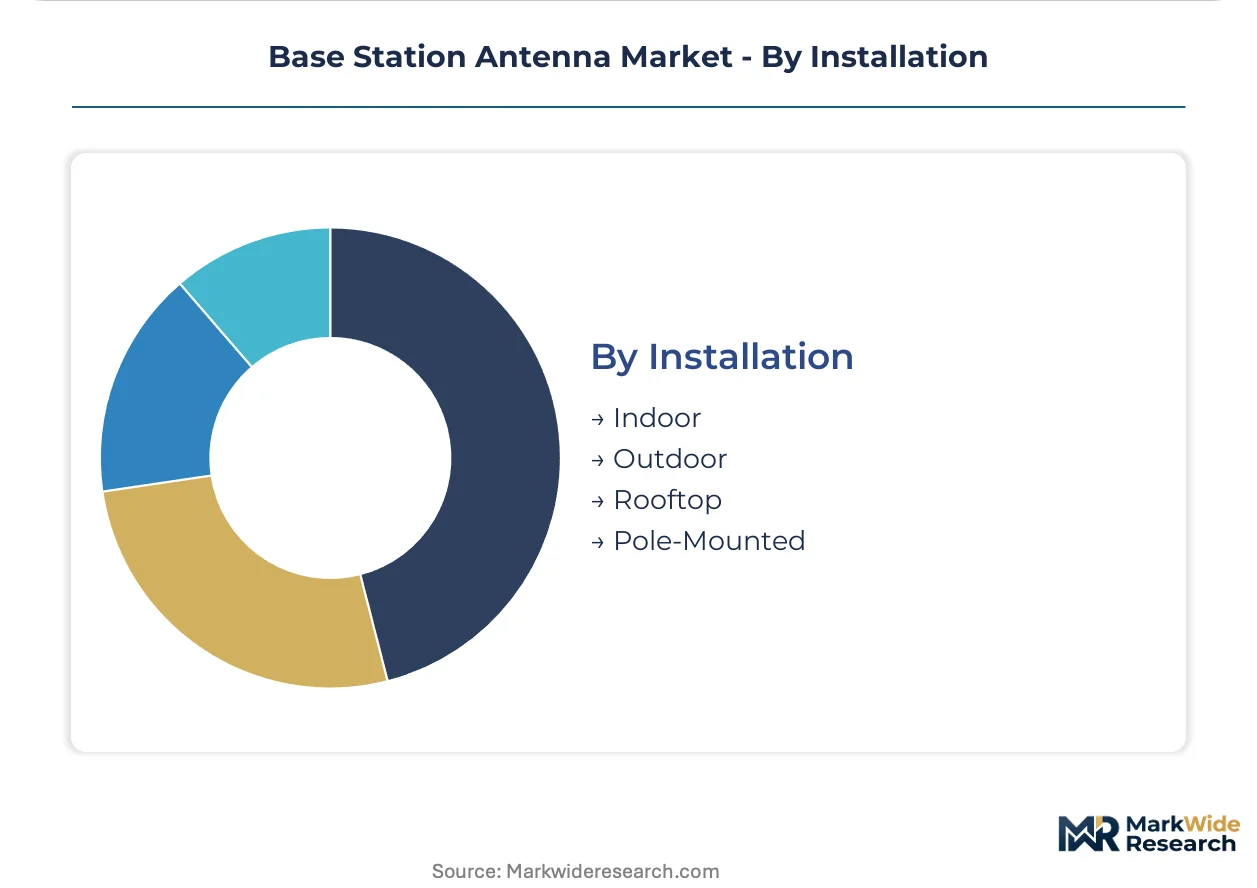
Installation:
Geography and zoning constraints reshape antenna form factors, with rooftop and pole-mounted deployments facing distinct municipal approval friction compared to controlled indoor environments.
- Indoor:Low-power distributed antenna systems for stadium, airport, and healthcare campus coverage. Japan's METI building codes drive specialized fire-safety and radome material requirements.
- Outdoor:Macro cell towers and monopoles with wind-loading and ice-loading specifications. Canadian deployments require PMRA environmental testing for extreme temperature cycling.
- Rooftop:Building-mounted installations in dense urban corridors with visual impact restrictions. Paris and Barcelona municipal zoning imposes aesthetic constraints on antenna housing design.
- Pole-Mounted:Street furniture and utility pole attachments for small cell densification. United States cities including New York and Los Angeles franchise agreements govern attachment fees and timeline coordination.
Outdoor installations retain volume leadership, with Pole-Mounted systems expanding most quickly as 5G densification penetrates urban streetscapes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF engineering talent clusters in Shenzhen, Seoul, and Munich anchor regional production networks for active antenna systems and beamforming silicon. These workforce concentrations shape procurement patterns and certification specialization across major deployment zones.
United States
Verizon and AT&T are compressing 5G mid-band buildout timelines following FCC Auction 110 and 108 spectrum awards. FCC OET equipment authorization cycles extend deployment schedules by fourteen months for integrated active antenna systems. Tower companies in Texas and Florida are consolidating antenna-radio sourcing under single-vendor accountability frameworks to meet coverage deadlines.
China
China Mobile and China Telecom are tripling macro site counts in tier-2 cities under MIIT base station densification mandates. MIIT radio transmission equipment type-approval rules compress vendor qualification windows to six months for domestic suppliers. Manufacturing clusters in Guangdong and Jiangsu provinces are scaling active antenna output for eastern seaboard urban corridors.
Germany
Deutsche Telekom is accelerating 5G standalone deployments across Bavaria and North Rhine-Westphalia for industrial automation backhaul. EMA equipment authorization frameworks and REACH substance restrictions are reformulating radome material specifications. Ericsson's localized manufacturing footprint in Poland feeds German supply chains with reduced customs friction.
South Korea
SK Telecom and KT Corporation are deploying 64T64R Massive MIMO configurations for stadium and transit hub density layers. MFDS electromagnetic compatibility thresholds align with international 3GPP specifications for millimeter-wave antenna certification. Seoul metropolitan area small cell densification is driving pole-mounted antenna demand through municipal franchise agreements.
India
Bharti Airtel and Reliance Jio are expanding 4G retrofit programs in tier-2 and tier-3 urban corridors ahead of 5G spectrum re-farming. TRAI coverage mandates and the PLI scheme for telecom equipment are attracting manufacturing investments to Gujarat and Tamil Nadu. Tower infrastructure providers in Maharashtra are consolidating passive antenna refurbishment contracts to preserve capital budgets.
Base Station Antenna Market Vendor Landscape
The competitive structure tilts toward integrated radio-access network suppliers with captive semiconductor sourcing and established carrier certification relationships. Three archetypes dominate: full-stack infrastructure vendors controlling antenna-radio integration, specialized antenna OEMs competing on electromagnetic design heritage, and semiconductor entrants leveraging beamforming-on-silicon convergence. Dominant competitive moves include strategic partnerships for Open RAN interoperability validation and geographic expansion through localized manufacturing investments to satisfy regional content requirements.
Among Asian integrated infrastructure suppliers, Huawei Technologies Co. Ltd. and Ace Technologies Corporation occupy positions shaped by domestic certification advantages and state-backed carrier procurement relationships. Ericsson AB anchors European competitive dynamics through its manufacturing presence in Germany and Poland. Nokia Corporation exemplifies the Open RAN interoperability archetype, with its antenna-radio combinations positioned for multi-vendor network architectures in North American and European carrier evaluations.
| Leading Market Players |
|---|
| Huawei Technologies Co. Ltd. |
| Ericsson AB |
| Nokia Corporation |
| CommScope Holding Company, Inc. |
| Kathrein SE |
| Amphenol Corporation |
| Ace Technologies Corporation |
| RFS (Radio Frequency Systems) |
| Comba Telecom Systems Holdings Ltd. |
| Others |
Supply Flow & Price Mechanics
RF engineering talent clusters in Shenzhen compress labor-cost differentials between premium active antenna systems and economy passive units, widening pricing-tier spreads as Massive MIMO configurations demand specialized electromagnetic simulation expertise.
Pricing Analysis
Antenna-radio bundling versus unbundled component procurement splits the market into distinct commercial models. Three-tier pricing structure across premium, standard, and economy levels separates integrated active systems with embedded transceivers from refurbished passive installations and entry-level 4G retrofit units. Price differentiation hinges on FCC OET certification grade and volume procurement scale, with tower companies commanding steepest discounts. Cost compression in economy passive tiers is intensifying because India's capital-constrained operators prioritize refurbishment over greenfield deployment. Emerging market carriers exhibit highest price sensitivity, while United States tier-1 operators prioritize single-vendor accountability over unit economics.
Supply Chain Analysis
Refurbishment flows for legacy passive antennas create reverse-logistics networks that compete with new equipment channels for tower company procurement slots. Gallium nitride substrate fabrication concentrates in Taiwan and South Korea, while aluminum alloy radome production anchors in China and Germany. Compound semiconductor wafer supply rests on Taiwanese foundry capacity and South Korean substrate vendors. Single-source vulnerability in GaN power amplifier sourcing exposes antenna OEMs to geopolitical interruption. Distribution runs through carrier-direct procurement frameworks and tower company consolidated sourcing programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with FCC mid-band spectrum auctions and MIIT densification mandates accelerating equipment replacement cycles and compressing vendor qualification windows.
For Market Incumbents: Lock in carrier certification relationships through accelerated FCC OET and EMA equipment authorization investments to defend against semiconductor entrants leveraging beamforming-on-silicon convergence. Prioritize backward integration into compound semiconductor sourcing to mitigate Taiwanese foundry concentration risk. Establish localized manufacturing footprints in India under PLI scheme incentives to capture South Asian procurement volumes.
For New Entrants and Emerging Players: Private 5G network operators in German automotive and Japanese manufacturing campuses represent the most penetrable buyer archetype outside carrier-dominated channels. Enterprise-direct procurement for dedicated campus coverage bypasses traditional telecom operator vendor qualification barriers. Beamforming-on-silicon convergence enables fabless entrants with RF CMOS heritage to capture radio front-end value previously controlled by integrated infrastructure vendors.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized antenna OEMs lacking integrated radio-access portfolios, as carrier procurement consolidation favors full-stack suppliers. Long-term viability hinges on Open RAN interoperability certification and captive compound semiconductor supply. Monitor O-RAN Alliance fronthaul specification adoption rates as the inflection signal for multi-vendor procurement fragmentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Interoperability Certification | O-RAN Alliance validation unlocks multi-vendor procurement for fragmented carrier networks. |
| Compound Semiconductor Backward Integration | Captive GaN substrate supply insulates antenna OEMs from Taiwanese foundry interruption. |
| India PLI Manufacturing Localization | Gujarat and Tamil Nadu production hubs capture South Asian network build volumes. |
| Enterprise Private 5G Direct Sales | Campus network deployments bypass carrier procurement channel concentration. |
| Digital Beamforming Silicon Development | CMOS-integrated phased arrays collapse radio-antenna boundaries for new entrants. |
Methodological Framework
Bottom-up carrier procurement modeling reconciled against top-down semiconductor supply tracking forms the analytical core of this study. Primary interviews with RF engineering directors, tower company procurement leads, carrier network planning executives, and regulatory compliance officers combined with secondary validation from FCC OET equipment authorization databases, MIIT radio transmission type-approval filings, EMA electromagnetic compatibility registers, and 3GPP specification releases. Triangulation across installation volume estimates and component bill-of-materials analysis validates segment-level outputs.
Input-output matrices map antenna unit shipments against spectrum auction timelines, densification mandates, and technology transition curves across the projection horizon. Segmentation dimensions modeled include product architecture, spectrum capability, end-user procurement channel, and installation environment. CAGRs derive from fitted growth curves against documented carrier deployment commitments and regulatory milestone schedules. Forecast inputs incorporate MIIT base station count targets and FCC buildout deadline compression effects.
Underlying measurement precision varies by segment; 5G active antenna volumes carry tighter precision than emerging private network deployments given carrier disclosure requirements. Forecasts reflect documented assumptions regarding spectrum reallocation timelines and Open RAN procurement adoption. Practitioners should monitor FCC OET certification backlog durations and compound semiconductor foundry utilization rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Telecom Electronic Manufacturing Services (EMS) Market
Telecom Hardware
Digital TV Soc Market
Telecom Hardware
Communication Base Station Equipment Pcb Market
Telecom Hardware
Telecom Equipment Market
Telecom Hardware
Asia Pacific Enterprise Routers Market
Telecom Hardware
Europe Zero-Touch Provisioning Market
Telecom Hardware
Repeaters Market
Telecom Hardware
DWDM Transceiver Market
Telecom Hardware
Global Virtualized Evolved Packet Core (VEPC) Market
Telecom Hardware
Global Ultra Portable Internet Device Market
Telecom Hardware
Global FPGA in Telecom Sector Market
Telecom Hardware
Europe Set-Top Box Market
Telecom Hardware
Global Time Sensitive Networking Market
Telecom Hardware
Laser Communications Terminals (Lcts) Market
Telecom Hardware
Low Power Wide Area Network (LPWAN) Market
Telecom Hardware
Subscriber Identity Module (SIM) Market