
 Submarine Data Cables Market | 2026-2036
Submarine Data Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Submarine Data Cables Market Analytics
Modular cable systems with fiber-pair leasing and incremental capacity upgrades is recalibrating how carriers procure subsea infrastructure. Alcatel Submarine Networks leverages its integrated marine installation fleet to control project timelines from factory to seabed. SubCom anchors trans-Pacific route dominance through repeated high-fiber-count deployments. NEC Corporation differentiates in the Asia-Pacific theater with specialized repeater technology and regional maintenance alliances.
Submarine data cables consist of optical fiber bundles encased in polyethylene insulation, steel armor wires, and copper power conductors, designed to transmit terabits per second across oceanic distances while withstanding hydrostatic pressures exceeding 10,000 psi. Their primary purpose is enabling intercontinental internet traffic exchange and private network connectivity for telecommunications and cloud computing infrastructure. Multi-core cables command the largest capital allocation due to escalating bandwidth requirements from video streaming and artificial intelligence workloads, while installation via ROV is gaining preference in deep-water zones where conventional ploughing proves impractical. Ring topology deployments are expanding fastest among connection types as operators prioritize redundancy against seismic disruption and anchor strikes.
The International Cable Protection Committee coordinates seabed corridor governance, while national regulators including the FCC in the United States and Japan's Ministry of Internal Affairs and Communications impose landing station security and data sovereignty conditions that shape route planning. The EU's Critical Entities Resilience Directive and GDPR cross-border data transfer rules add compliance layers for cables touching European territory. Stakeholders must weigh fiber-pair ownership models against open-cable consortium structures as geopolitical friction over seabed access intensifies.
Market Dynamics
Hyperscale cloud providers are consolidating subsea fiber-pair ownership models, shifting procurement from consortium structures toward private cable systems that guarantee dedicated capacity and operational control across trans-Pacific corridors.
Growth Catalysts
- AI Workload Proliferation:Machine learning training clusters in Singapore and Tokyo are demanding dedicated low-latency links to US data centers, pulling fresh cable deployments across the Pacific basin.
- FCC Landing Station Security Mandates:Enhanced physical access controls and supply chain vetting requirements are accelerating replacement cycles for aging cable landing infrastructure along the US coastline.
- Space-Division Multiplexing:Multi-core fiber architectures are multiplying per-cable capacity without proportional diameter increases, enabling cost-efficient upgrades on existing marine routes.
Market Restraints
- Optical Amplifier Supply Concentration:Erbium-doped fiber amplifier manufacturing concentrates among three specialized component suppliers, creating chokepoints for high-fiber-count repeater production.
- Copper Power Conductor Volatility:Raw copper price swings directly impact cable manufacturing economics, with power feed components representing substantial material cost exposure.
- GDPR Cross-Border Transfer Friction:EU data localization requirements complicate route planning for cables touching European territory, adding legal review layers to project timelines.
Strategic Opportunities
- Indonesia Archipelago Connectivity:The sprawling island nation remains underserved by direct submarine links, presenting greenfield deployment potential for domestic and international traffic aggregation.
- Open Cable Consortium Structures:Neutral ownership models allowing multiple carriers to lease fiber pairs on demand are displacing traditional bilateral cable investments.
- EU Critical Entities Resilience Directive:Mandatory redundancy requirements for subsea infrastructure are creating replacement and diversification demand across Mediterranean and Atlantic routes.
Industry Challenges
- Marine Survey Specialist Scarcity:Bathymetric route planning and seabed geohazard assessment expertise pools narrowly, extending pre-construction phases for deep-water deployments.
- Permitting Timeline Compression:Coastal state environmental reviews and fisheries coordination processes frequently exceed equipment manufacturing lead times, creating deployment synchronization risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Submarine Data Cables Market |
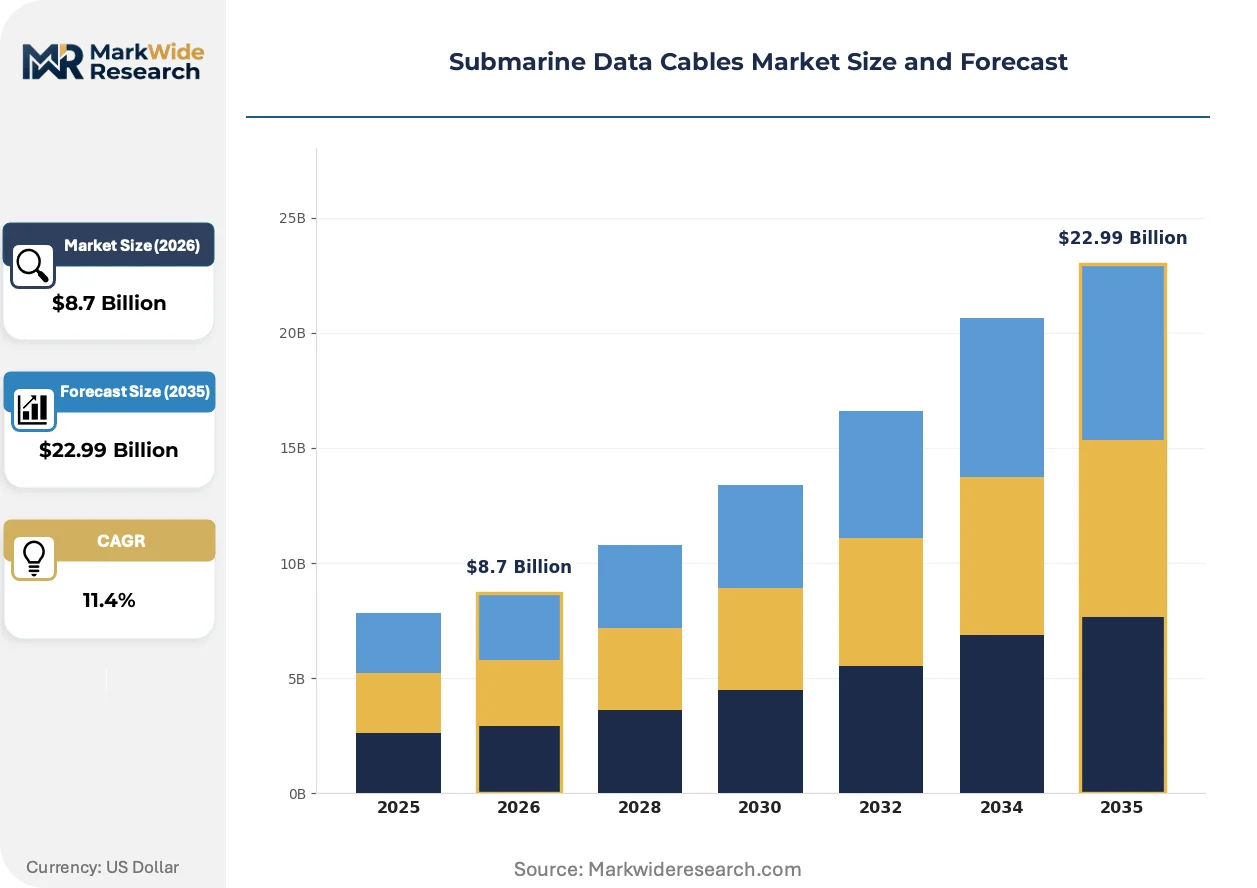
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-core Cables, Multi-core Cables, Armored Cables, Unarmored Cables Installation Method: Buried, Laid on Seabed, Ploughed, Installed via ROV Connection Type: Point-to-Point, Ring, Mesh, Star End User: Telecommunications Providers, Internet Service Providers, Government Agencies, Enterprises |
| Companies Covered | Alcatel Submarine Networks, SubCom, NEC Corporation, Prysmian Group, Nexans, HMN Tech, Hengtong Group, TE Subcom, Sumitomo Electric Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Submarine Data Cables Market Evolving Landscape
Submarine cable engineering is pivoting toward modular architectures that decouple fiber-pair activation from initial lay, allowing capacity scaling to trail demand confirmation by years rather than forcing speculative overbuild.
Multi-core fiber technology is consolidating manufacturing investment around space-division multiplexing platforms that multiply transmission paths within single fiber structures. Hyperscale operators are commissioning 24-fiber-pair systems as baseline configurations, compressing per-bit economics through density gains rather than spectral efficiency alone. This consolidation is marginalizing legacy 8-pair designs and forcing component suppliers to retool amplification and branching unit architectures.
The EU's Critical Entities Resilience Directive is mandating physical redundancy and rapid restoration capabilities for subsea infrastructure touching member states. Cable operators must now document alternative routing and maintain spare capacity reserves, adding capital intensity to European projects. Mediterranean corridor planning increasingly incorporates dual-path ring topologies to satisfy these continuity requirements.
Carrier procurement patterns are fragmenting as content providers bypass traditional consortium models to commission private cable systems. Wholesale bandwidth buyers in Southeast Asia are accessing capacity through fiber-pair leasing rather than long-term IRU commitments, shortening contract durations and shifting price risk to cable owners. This behavioral shift concentrates most acutely in Singapore, where cloud on-ramp density enables competitive neutral-cable access.
Submarine Data Cables Market Segmentation
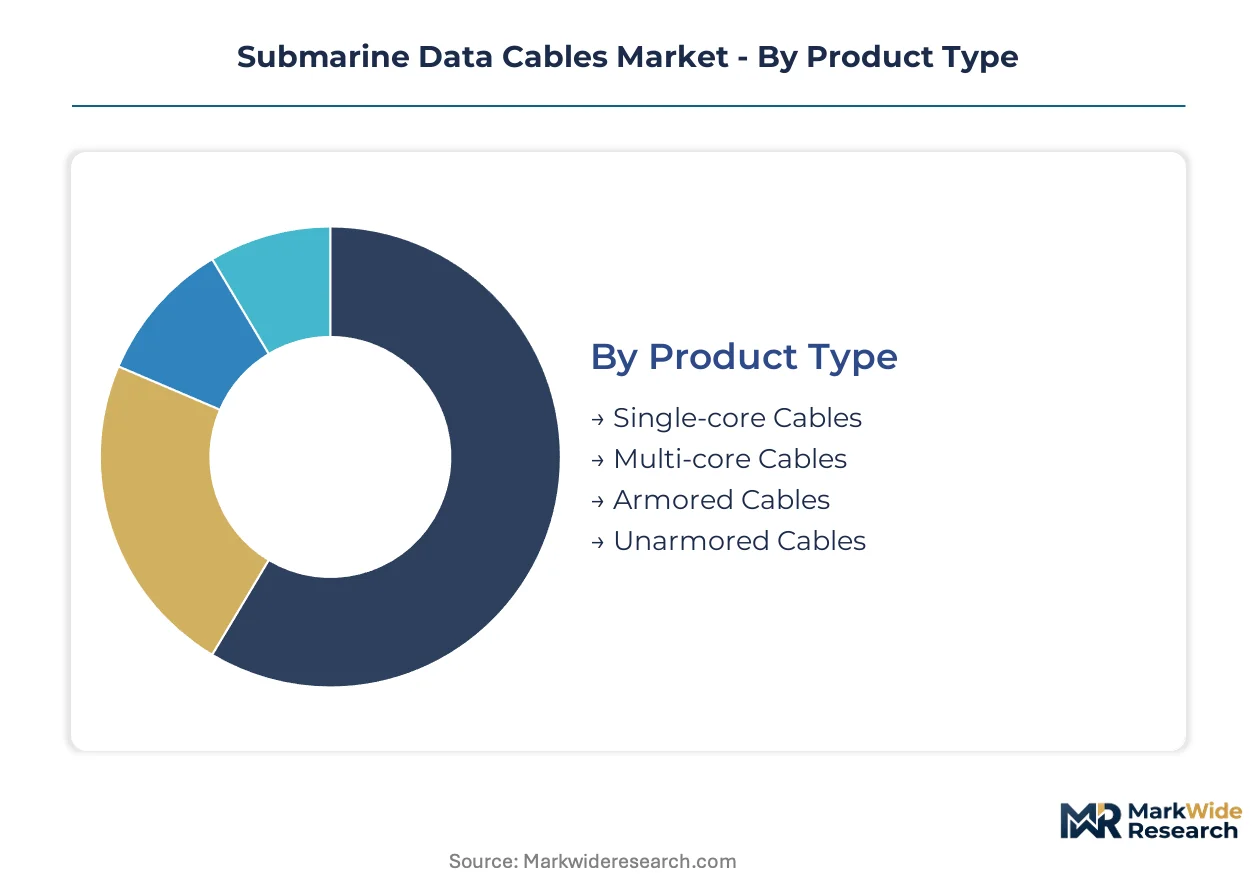
Segmentation in submarine data cables reveals how procurement decisions split between standardized commodity configurations and engineered-to-order systems. Each dimension carries distinct margin structures, lead times, and supplier qualification requirements that shape competitive positioning across the value chain.
Product Type:
Customization intensity varies sharply across this spectrum, from catalog-standard unarmored designs to specification-heavy multi-core systems requiring joint engineering with cable ship operators.
- Multi-core Cables:Bundled optical fiber arrays with 12 to 24 fiber pairs encased in polyethylene and steel armor. Hyperscale cloud providers in Singapore and Tokyo are pulling dedicated procurement of these high-count systems for AI training cluster interconnects, where latency constraints override capital cost sensitivity.
- Armored Cables:Heavy-gauge steel wire reinforcement surrounding power conductors and fiber bundles, rated for hydrostatic pressures exceeding 10,000 psi in deep ocean trenches. Fishing zone crossings and volcanic seabed corridors in the Pacific basin drive specification demand for enhanced mechanical protection.
- Single-core Cables:Legacy designs with 2-8 fiber pairs, now relegated to repair spares and regional spur routes where bandwidth requirements remain modest.
- Unarmored Cables:Lightweight polyethylene-sheathed construction for deep-water zones beyond fishing activity and anchor strike risk, optimizing transport and lay efficiency.
Leading the category by volume: Multi-core Cables. Growing fastest: Armored Cables.
Installation Method:
Water depth and seabed composition dictate method selection, with cost per kilometer escalating nonlinearly as techniques shift from surface lay to precision burial.
- Installed via ROV:Remotely operated vehicles maneuver cable and repeater hardware onto seabed features in depths exceeding 2,000 meters where ploughing is mechanically impossible. Japan's Ministry of Internal Affairs and Communications mandates ROV verification of repeater placement on critical routes crossing seismically active trenches.
- Ploughed:Seabed cutting and simultaneous cable burial to 1-3 meter depth in continental shelf zones, protecting against fishing gear interaction and anchor strikes along US Atlantic coastline routes subject to FCC landing station security reviews.
- Buried:Post-lay trenching using jetting sleds in sedimentary seabed conditions common to Mediterranean corridor planning under EU Critical Entities Resilience Directive redundancy requirements.
- Laid on Seabed:Surface placement on stable abyssal plains with minimal protection, reserved for deep-water transits where external threats are negligible and recovery accessibility is prioritized.
Dominant by route kilometers: Laid on Seabed. Climbing the fastest: Installed via ROV.
Connection Type:
Network topology selection reflects trade-offs between capital efficiency and resilience investment, with regulatory pressure increasingly mandating redundancy architectures.
- Ring:Closed-loop configurations providing automatic traffic rerouting upon single-point failure, now standard for EU-territory cables under resilience directive continuity requirements.
- Point-to-Point:Direct bilateral links between landing stations, remaining cost-preferred for private cable systems where hyperscale operators self-provide diversity through parallel route holdings.
- Mesh:Multi-node interconnection enabling dynamic capacity allocation across branching units, gaining traction in Southeast Asia's Indonesia archipelago connectivity initiatives.
- Star:Hub-and-spoke architectures with centralized branching to multiple coastal landing points, deployed for island nation domestic aggregation networks.
Most deployed historically: Point-to-Point. Steepest expansion trajectory: Ring.
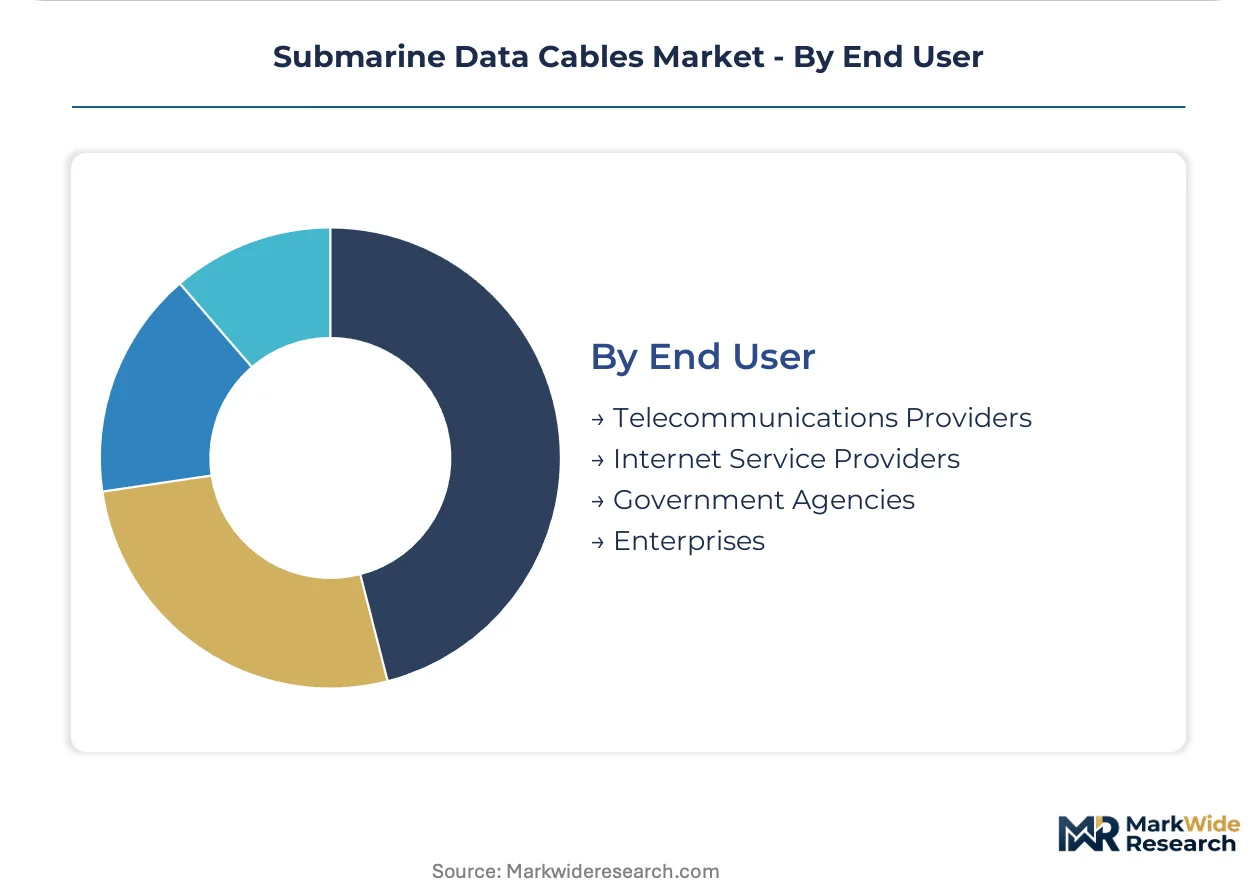
End User:
Procurement authority is fragmenting as traditional carrier consortiums yield to direct infrastructure ownership by content and cloud platforms.
- Telecommunications Providers:Incumbent carriers and consortium-operated cable systems, now shifting toward open-cable neutral host models to retain relevance as cloud providers bypass traditional wholesale channels.
- Internet Service Providers:Regional bandwidth aggregators accessing capacity through fiber-pair leasing rather than long-term IRU commitments, shortening contract durations and concentrating in Singapore's neutral-cable exchange environment.
- Government Agencies:Defense and research network operators with sovereign security requirements, driving demand for physically diverse routes and domestic landing station control.
- Enterprises:Financial services and multinational corporations procuring private fiber pairs for dedicated low-latency connectivity between trading hubs and cloud on-ramps.
Highest capital deployment: Telecommunications Providers. Gaining share fastest: Internet Service Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates among specialized marine cable fabricators in Europe and Asia, while consumption clusters along trans-Pacific corridors where hyperscale cloud operators anchor demand. The United States, Japan, and Singapore form the dominant traffic triangle, with emerging routes threading through Indonesia and Australia.
United States
Hyperscale cloud providers in Northern Virginia and Silicon Valley are commissioning private cable systems to secure dedicated trans-Pacific capacity. The FCC imposes enhanced landing station security mandates requiring physical access controls and supply chain vetting. Los Angeles anchors the primary US gateway for cables linking to Japan and Singapore.
Japan
Tokyo's AI training clusters are pulling low-latency cable deployments from US West Coast data centers. The Ministry of Internal Affairs and Communications mandates ROV verification of repeater placement on routes crossing seismically active trenches. Chiba Prefecture hosts critical landing infrastructure for trans-Pacific systems.
Singapore
Neutral-cable exchange density enables competitive fiber-pair leasing models for regional ISPs and cloud on-ramps. The Infocomm Media Development Authority coordinates landing station licensing with cybersecurity compliance requirements. The Tuas landing zone aggregates capacity for Southeast Asian traffic distribution.
Indonesia
The sprawling archipelago remains underserved by direct submarine links, creating greenfield deployment potential for domestic and international aggregation. The national telecommunications regulator coordinates route licensing across multiple maritime jurisdictions. Batam and Jakarta anchor emerging cable landing points for inter-island connectivity.
Australia
Sydney and Perth landing stations are diversifying route portfolios to reduce reliance on single-path US connectivity. The Australian Communications and Media Authority imposes security assessments for critical infrastructure designations. The Sunshine Coast cable landing station anchors new capacity for Asia-Pacific traffic exchange.
Submarine Data Cables Market Competitive Landscape
The competitive structure tilts toward integrated marine installation specialists with captive cable ship fleets. Three to four vertically integrated manufacturers control the majority of high-fiber-count system deployments. Strategic archetypes separate into full-service marine contractors, component-focused repeater specialists, and regional maintenance alliance builders. Dominant competitive moves include marine fleet expansion and fiber-pair leasing model adoption.
Among integrated marine contractors, Alcatel Submarine Networks, SubCom, and NEC Corporation exemplify the archetype of manufacturers controlling project timelines from factory to seabed. Alcatel Submarine Networks represents European-based full-service capability. SubCom anchors trans-Pacific route dominance through repeated high-fiber-count deployments. NEC Corporation occupies a position within Asia-Pacific theater specialization.
| Leading Market Players |
|---|
| Alcatel Submarine Networks |
| SubCom |
| NEC Corporation |
| Prysmian Group |
| Nexans |
| HMN Tech |
| Hengtong Group |
| TE Subcom |
| Sumitomo Electric Industries |
| Others |
Value Network & Pricing Analysis
Marine survey specialist pools concentrated in Japan and Norway widen labor-cost spreads between premium engineered-to-order systems and catalog-standard configurations. Cable ship crew scarcity in the North Sea relative to Mediterranean basin availability feeds into pricing-tier differentiation across installation contracts.
Pricing Analysis
Margin tightening in multi-core cable tiers reflects hyperscale cloud providers compressing per-fiber-pair economics through 24-pair baseline demands. Three-tier pricing structure across premium, standard, and economy levels separates armored deep-water specifications from unarmored abyssal plain deployments. Price differentiation hinges on fiber pair count and ROV installation certification. Government agencies show least price sensitivity given sovereign security mandates; regional ISPs in Southeast Asia exhibit highest sensitivity as they migrate from IRU commitments to short-term leasing.
Supply Chain Analysis
Erbium-doped fiber amplifier supply rests on Japanese and US specialty component producers, with final cable integration concentrating in France, Japan, and the United States. Raw copper conductor sourcing draws from Chilean mining operations and Chinese smelting capacity, while polyethylene sheathing feeds from Gulf Coast petrochemical complexes. Single-source vulnerability concentrates in deep-water repeater manufacturing. Distribution runs through vertically integrated marine contractors controlling captive cable ship fleets from factory to seabed.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Submarine cable manufacturing operates as a supply-constrained industry where marine installation fleet scarcity props pricing power for integrated contractors. Bathymetric survey bottlenecks and cable ship availability constraints limit capacity expansion regardless of demand pull.
For Market Incumbents: Lock in long-term fiber-pair leasing contracts with hyperscale cloud providers before open-cable consortium structures commoditize access. Expand ROV installation capabilities in the Asia-Pacific theater to defend against NEC Corporation's regional maintenance alliances. Secure captive supply of erbium-doped amplifiers to mitigate optical component chokepoint exposure. For New Entrants and Emerging Players: The 40-60% price-point gap between premium multi-core systems and legacy single-core repair spares opens white-space entry in Indonesia archipelago connectivity. Target domestic Indonesian traffic aggregation routes where incumbent consortium structures have underinvested. Pursue neutral-cable fiber-pair leasing models in Singapore's exchange-dense environment as the go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated marine contractors given EU Critical Entities Resilience Directive replacement demand across Mediterranean routes. Acquisition focus should center on cable ship operators with deep-water ROV capabilities and established landing station relationships. Watch hyperscale cloud provider capex disclosure trends as the inflection signal for capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Marine Fleet Expansion | Captive cable ship ownership compresses project timelines from factory to seabed. |
| Multi-Core Fiber R&D Investment | Space-division multiplexing platforms multiply transmission paths within single fiber structures. |
| Open-Cable Consortium Formation | Neutral ownership models displace traditional bilateral cable investments in Southeast Asia. |
| ROV Installation Capability Buildout | Japan's Ministry of Internal Affairs and Communications mandates ROV verification on seismically active routes. |
| EU Resilience Directive Compliance | Mandatory redundancy requirements create replacement demand across Mediterranean corridors. |
Research Methodology
Independent corroboration across cable system procurement officers, marine installation project managers, and optical component engineering directors underwrites the qualitative findings. Secondary validation draws from FCC landing station filings, Japan Ministry of Internal Affairs and Communications route licenses, EU Critical Entities Resilience Directive implementation guidance, and hyperscale cloud provider infrastructure capex disclosures. Bottom-up fiber-pair demand modeling triangulates against top-down trans-Pacific bandwidth growth projections.
Rate-of-change decomposition separates volume growth across the analysis window from value-per-fiber-pair trajectory. Segmentation dimensions include product type, installation method, connection topology, and end-user procurement authority. CAGRs derive from installed base replacement cycles and greenfield deployment pipelines. Forecast inputs incorporate AI training cluster interconnect demand from Singapore and Tokyo, plus EU-mandated redundancy requirements for Mediterranean route diversification.
Inputs from marine contractors and landing station operators were available through the study window; gaps in unannounced hyperscale cloud provider private cable commitments introduce uncertainty bands. Forecasts reflect assumptions about permitting timeline compression and optical amplifier supply expansion. A small set of triggers—copper price volatility, coastal state environmental review delays, and geopolitical seabed access friction—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Active Optical Cable Market
Cables
Cable Testers Market
Cables
Global Cable Tie Market
Cables
Low-Temperature Cable Market
Cables
EV Charging Cable and Connector Durability and Safety Test Equipment Market
Cables
Europe Wire and Cable Market
Cables
Aluminium Battery Cable Market
Cables
Power and Control Cable Market
Cables
Power and Signal Cables Market
Cables
Cable Accessories Market
Cables
South Africa Wire and Cable Market
Cables
Cable Tray Market
Cables
Asia-Pacific Cable Joints Market
Cables
Control Cable Market
Cables
Submarine Communication Cables Market
Cables
North America Wire and Cable Market