
 Connector Adapter Kits Market | 2026-2036
Connector Adapter Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Connector Adapter Kits Market Outlook
The transition from copper-based signal transmission to fiber-optic and hybrid interconnect architectures is reconfiguring how adapter kits are engineered for bandwidth-intensive applications. TE Connectivity leverages its vertical integration in precision stamping and plating to sustain cost leadership across high-volume automotive programs. Amphenol Corporation anchors its position through deep specialization in harsh-environment military and aerospace connector standards. Molex competes aggressively in the consumer electronics channel, where it controls shelf placement through direct OEM partnerships with device manufacturers.
Connector adapter kits are electromechanical assemblies designed to bridge incompatible interface standards, typically incorporating precision-machined contacts, dielectric housings, and shielding elements rated for specific insertion loss and impedance tolerances. Their primary purpose is to enable signal integrity across disconnection points in electronic systems without requiring complete cable replacement. Specialty adapters command premium positioning due to MIL-spec certification requirements and low-volume precision manufacturing, while USB and Ethernet connection types capture the highest absolute volumes driven by consumer electronics and enterprise infrastructure refresh cycles. Multi-port adapters represent the fastest-growing configuration as equipment designers consolidate interface density to save panel space and reduce bill-of-materials complexity.
FCC Part 15 emissions standards in the United States, EU RoHS substance restrictions under ECHA oversight, and REACH SVHC disclosure mandates collectively shape material selection, plating chemistry, and market access documentation across the supply chain. Automotive OEMs now require ISO 26262 functional safety traceability for in-vehicle adapter assemblies, adding compliance layers that favor established suppliers with documented quality systems. Stakeholders must monitor how USB-IF and HDMI Forum specification revisions will obsolete legacy inventory and force adapter portfolio refreshes before competitors capture design wins.
Market Dynamics
Automotive electrification is forcing connector adapter kit architectures to accommodate 48V mild-hybrid and 800V fast-charging interfaces within the same vehicle platforms, compressing design cycles and multiplying interface complexity for tier-one suppliers.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for fluorinated greenhouse gases are accelerating demand for hermetic sealing solutions in refrigeration and HVAC adapter assemblies, expanding addressable markets for specialized connector manufacturers.
- Electric vehicle platform consolidation:Automotive OEMs are standardizing on fewer high-voltage connector families across multiple nameplates, creating volume pull for adapter kits that bridge legacy charging infrastructure to new vehicle architectures.
- Fiber-optic signal transmission:In-vehicle infotainment and ADAS systems are displacing copper coaxial runs with optical fiber, generating adapter demand at media converter nodes where electrical-optical signal translation occurs.
Market Restraints
- Copper price volatility:Contact plating and shielding materials constitute 35-45% of raw material costs in precision connector manufacturing, exposing margins to London Metal Exchange copper fluctuations without effective hedging instruments at mid-tier suppliers.
- REACH SVHC disclosure mandates:ECHA's expanding candidate list of substances of very high concern requires continuous reformulation of housing polymers and plating chemistries, extending qualification timelines and freezing legacy product lines.
- Inductive wireless power transfer:Charging pad infrastructure for consumer electronics and light electric vehicles is obsoleting physical connector interfaces in specific power classes, permanently capping adapter demand in affected segments.
Strategic Opportunities
- India PLI scheme for electronics:Production-linked incentives for semiconductor and component manufacturing are attracting connector assembly investments to Tamil Nadu and Karnataka, creating localized supply bases for export-oriented automotive programs.
- USB4 and Thunderbolt convergence:Unified 40Gbps interface standards across computing and peripheral categories are collapsing multiple legacy adapter SKUs into single multi-protocol products, rewarding suppliers with flexible programmable architectures.
- Defense electronics reshoring:NATO member governments are mandating domestic content thresholds for military avionics and communications systems, opening captive demand for MIL-DTL-qualified adapter kits from regional manufacturing bases.
Industry Challenges
- ISO 26262 functional safety certification:Automotive adapter assemblies now require ASIL-rated traceability documentation that most mid-sized connector houses lack, forcing expensive quality system overhauls or exclusion from safety-critical vehicle domains.
- Legacy inventory obsolescence:USB-IF and HDMI Forum specification revisions are rendering millions of units in distributor channels technically non-compliant, creating write-down exposure and channel conflict over responsibility for stranded stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connector Adapter Kits Market |
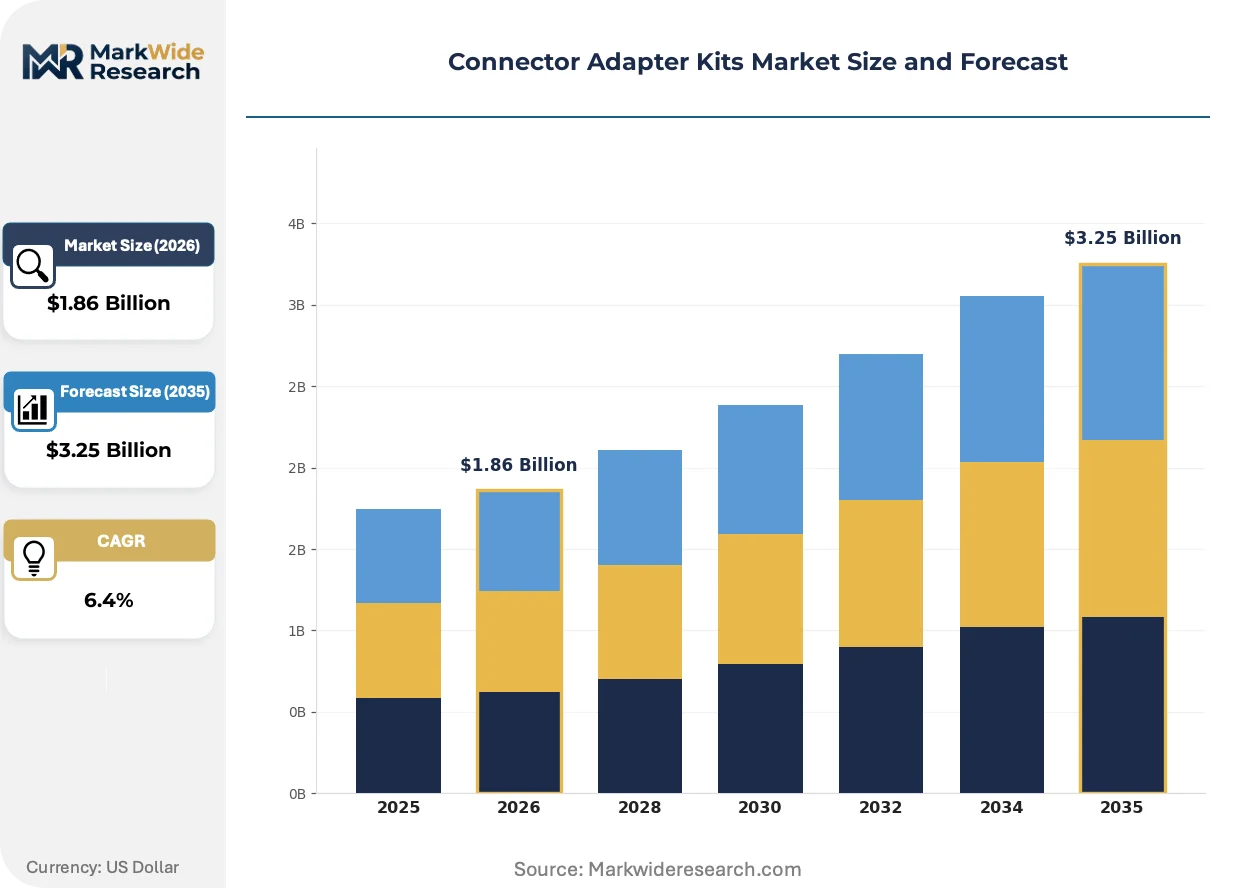
| Market Size in 2026 | $1.86 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Adapters, Specialty Adapters, Multi-Port Adapters, Audio Adapters Connection Type: USB, HDMI, Ethernet, Coaxial End User: Consumer Electronics, Telecommunications, Automotive Industry, Industrial Equipment Material: Plastic, Metal, Gold-Plated, Fiber Optic |
| Companies Covered | TE Connectivity, Amphenol Corporation, Molex, Samtec, 3M Company, Hirose Electric, Foxconn, ITT Cannon, Phoenix Contact, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connector Adapter Kits Market Strategic Shifts
Signal integrity requirements at multi-gigabit speeds are collapsing the boundary between passive interconnects and active signal conditioning components, transforming adapter kits from mechanical bridges into intelligent edge devices with embedded equalization and protocol translation.
Hybrid copper-fiber interconnect architectures are hybridizing signal paths within single adapter housings, enabling simultaneous power delivery and high-speed data transmission across dissimilar media. Data center operators and automotive tier-ones are adopting these solutions for 100Gbps+ backplane applications where pure copper solutions fail insertion loss budgets. The technology is hybridizing procurement categories, forcing buyers to evaluate electrical and optical performance in unified specifications rather than separate commodity purchases.
REACH substance restrictions under ECHA oversight are prohibiting cadmium and hexavalent chromium in plating chemistries used for corrosion-resistant military and aerospace connectors. Defense contractors must now qualify alternative surface finishes such as zinc-nickel and tin-zinc alloys that meet MIL-DTL salt spray requirements without restricted substances. European aerospace programs are experiencing the longest qualification delays, with some adapter families requiring 18-24 month re-certification cycles.
Automotive OEMs are consolidating supplier relationships around full-system interconnect partners capable of delivering complete signal path solutions rather than discrete components. Tier-one procurement teams are reducing qualified vendor lists from 15-20 connector suppliers to 3-5 strategic partners with end-to-end design capabilities. This concentration is most pronounced in Germany, where Volkswagen Group and BMW have implemented single-source adapter strategies for new electric vehicle platforms launching through 2028.
Connector Adapter Kits Market Segmentation
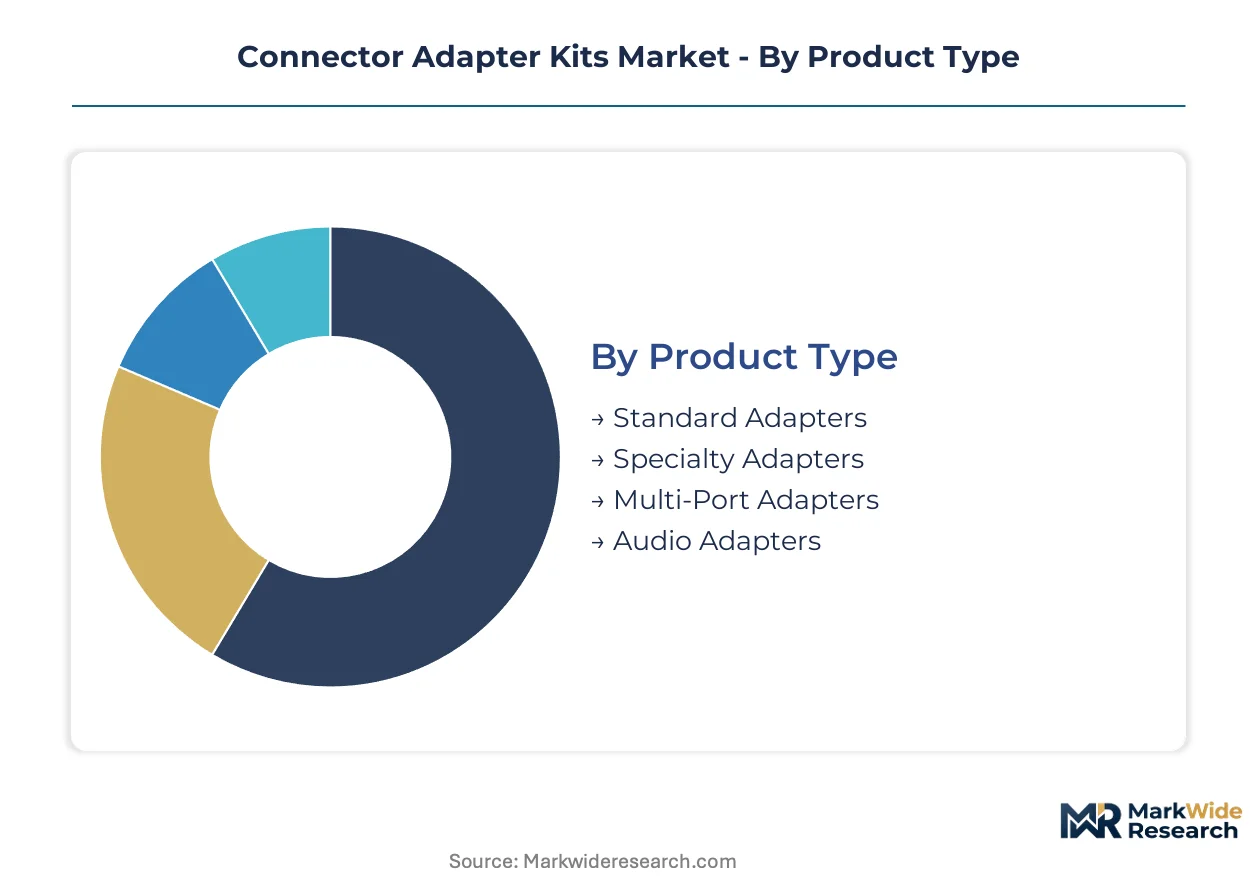
Adapter kit segmentation reveals how technical specifications, interface standards, and material choices determine replacement cycles and service attachment rates. Procurement teams use these categories to align supplier qualification with application-critical performance thresholds.
Product Type:
After-sales service intensity varies sharply across product categories, with field-replaceable units demanding rapid logistics networks and certified repair protocols that specialty manufacturers monetize through extended service contracts.
- Standard Adapters:Mass-produced electromechanical assemblies with standardized contact pitches and dielectric housings. Demand concentrates in enterprise IT refresh cycles across Germany and the United States, where FCC Part 15 emissions compliance and RoHS substance documentation are mandatory for channel placement.
- Specialty Adapters:Precision-machined units engineered for MIL-spec certification and extreme-environment operation. Procurement clusters in defense electronics reshoring programs across NATO member states, where domestic content thresholds and ISO 26262 functional safety traceability filter supplier eligibility.
- Multi-Port Adapters:Interface consolidation devices reducing panel space and bill-of-materials complexity.
- Audio Adapters:Signal integrity bridges for analog-digital conversion in consumer and professional sound systems.
Standard Adapters hold the largest share; momentum sits with Multi-Port Adapters.
Connection Type:
Cost tier stratification separates commodity interconnects from premium protocol translation hardware, with pricing spreads reflecting certification depth and bandwidth headroom.
- USB:Universal serial bus interfaces spanning legacy Type-A through USB4/Thunderbolt convergence. Volume leadership sits with computing peripheral OEMs in China and South Korea, where MIIT GB standards and USB-IF specification compliance govern design win eligibility.
- HDMI:High-definition multimedia interface adapters for video signal transmission. Demand concentrates in consumer electronics manufacturing clusters across Taiwan and Japan, where HDMI Forum licensing and HDCP content protection certification create vendor lock-in effects.
- Ethernet:RJ45 and industrial M12 variants for networked infrastructure.
- Coaxial:RF signal transmission adapters for broadcast and telecommunications.
USB commands absolute volume; Ethernet is climbing the fastest in industrial applications.
End User:
Application-specific qualification requirements fragment the vendor landscape, with automotive and aerospace programs demanding documentation depth that consumer channels ignore.
- Consumer Electronics:High-volume, short-lifecycle adapters for smartphones, laptops, and peripherals. Procurement concentrates with direct OEM partnerships in Shenzhen and Dongguan manufacturing corridors, where REACH SVHC disclosure mandates and WEEE recycling directives shape material selection.
- Automotive Industry:In-vehicle interconnect assemblies for infotainment, ADAS, and powertrain systems. Demand localizes around Volkswagen Group and BMW platform consolidation in Germany, where KBA type approval and ISO 26262 ASIL ratings enforce supplier concentration.
- Telecommunications:Carrier-grade infrastructure and 5G base station interconnects.
- Industrial Equipment:Harsh-environment adapters for factory automation and process control.
Consumer Electronics holds the largest share; Automotive Industry shows the steepest expansion trajectory.
Material:
Supply concentration in precious metal refining and polymer compounding directly shapes cost structures and qualification timelines across plating chemistry categories.
- Metal:Brass, phosphor bronze, and stainless steel substrates for shielding and structural integrity. Demand concentrates in military-aerospace programs across the United States, where Defense Logistics Agency sourcing restrictions and MIL-DTL salt spray requirements govern vendor selection.
- Fiber Optic:Glass and polymer optical fiber assemblies for high-bandwidth signal transmission. Procurement clusters in data center buildouts across Virginia and Frankfurt, where insertion loss budgets and MPO/MTP connector standards drive specification convergence.
- Plastic:Engineering thermoplastics for dielectric housings and cost-sensitive consumer applications.
- Gold-Plated:Precious metal surface finishes for corrosion resistance and contact reliability.
Metal holds the largest share; Fiber Optic is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs export high-voltage adapter assemblies to electric vehicle programs across China and North America, establishing a dominant trade corridor in precision interconnect components.
Germany
Volkswagen Group and BMW platform consolidation drives procurement of ISO 26262-certified adapter kits for 800V fast-charging architectures. KBA type approval requirements enforce supplier concentration around Stuttgart and Munich manufacturing corridors. Baden-Württemberg hosts dense clusters of tier-one automotive electronics suppliers qualifying multi-port adapters for consolidated electric vehicle platforms launching through 2028.
China
Shenzhen and Dongguan manufacturing corridors generate absolute volume demand for USB-C and HDMI adapter kits serving computing and consumer electronics OEMs. MIIT GB standards and USB-IF specification compliance govern design win eligibility for export-oriented production. Yangtze River Delta data center buildouts in Shanghai and Jiangsu provinces accelerate fiber-optic adapter procurement for 100Gbps+ backplane applications.
United States
Defense electronics reshoring programs and Virginia data center expansion create dual demand vectors for MIL-spec and high-speed optical adapters. Defense Logistics Agency sourcing restrictions filter vendor eligibility for military-aerospace programs. Northern Virginia's Ashburn-Loudoun corridor concentrates hyperscale facility construction, driving MPO/MTP connector standard adoption at media converter nodes.
India
Production-linked incentive schemes for electronics manufacturing attract connector assembly investments to Tamil Nadu and Karnataka, creating localized supply bases for automotive export programs. BIS certification requirements and DGFT export documentation shape material selection for qualified suppliers. Sriperumbudur and Bengaluru electronics manufacturing clusters host expanding precision stamping and plating operations serving German automotive OEMs.
Japan
HDMI Forum licensing and HDCP content protection certification lock in vendor relationships for video signal transmission adapters serving consumer electronics manufacturing. METI industrial policy supports domestic content thresholds for defense and aerospace interconnect programs. Nagoya automotive electronics suppliers qualify hybrid copper-fiber architectures for next-generation infotainment and ADAS platforms.
Connector Adapter Kits Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented tiers where scale economies clash with certification depth. The vendor base organizes around three strategic archetypes: full-system interconnect partners delivering end-to-end signal paths, precision-machining specialists capturing MIL-spec and aerospace premiums, and high-volume fabricators dominating consumer electronics shelf placement. Dominant competitive moves include strategic consolidation around fewer qualified vendor lists and geographic expansion into India PLI-subsidized manufacturing corridors.
Among diversified interconnect conglomerates, TE Connectivity, Amphenol Corporation, and Molex occupy distinct positioning vectors. TE Connectivity exemplifies the full-system partner archetype through captive precision stamping and plating operations. Amphenol Corporation anchors the harsh-environment specialist tier with deep certification in military and aerospace connector standards. Molex represents the high-volume consumer channel controller, leveraging direct OEM partnerships for computing and peripheral design wins. Each structure reflects divergent capital allocation priorities across automotive electrification, defense reshoring, and consumer electronics refresh cycles.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol Corporation |
| Molex |
| Samtec |
| 3M Company |
| Hirose Electric |
| Foxconn |
| ITT Cannon |
| Phoenix Contact |
| Others |
Value Chain & Pricing Dynamics
The Shenzhen-Frankfurt air freight corridor carries precision-machined connector assemblies at rates that compress margins for mid-tier European distributors, while simultaneously enabling German automotive OEMs to enforce three-tier pricing separation across premium MIL-spec, standard industrial, and economy consumer grades.
Pricing Analysis
USB4-to-Thunderbolt convergence pricing gaps separate current-gen 40Gbps multi-protocol adapters from prior-gen USB 3.2 single-function units and next-gen optical-electrical hybrid architectures still in qualification. The dominant structure is tiered transactional pricing across premium, standard, and economy certification levels, with differentiation driven by MIL-DTL salt spray ratings and automotive ISO 26262 ASIL traceability. Pricing pressure stems from copper price volatility on London Metal Exchange, which is squeezing plating cost buffers without hedging instruments at mid-tier suppliers. Consumer electronics OEMs in Shenzhen and Dongguan manufacturing corridors exhibit highest price sensitivity, while defense contractors in Virginia and Stuttgart accept premiums for domestic content compliance.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for connector manufacturers serving dual-use military-civilian markets. Production concentrates in China, Germany, and the United States, with precision stamping and plating operations drawing from brass and phosphor bronze feedstock, engineering thermoplastic resin compounding, and precious metal refining. Single-source vulnerability sits with hermetic sealing component suppliers qualified to EU F-Gas Regulation phase-down schedules. Distribution runs through authorized distributor networks for MIL-spec programs and direct OEM partnerships for high-volume consumer electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Inductive wireless power transfer for consumer electronics and light electric vehicles threatens physical connector demand in specific power classes, forcing incumbent adapter manufacturers to defend substitution through protocol consolidation and safety-critical automotive positioning.
For Market Incumbents: Entrench automotive electrification exposure by qualifying 800V fast-charging adapter families for Volkswagen Group and BMW platform consolidation, while backward integrating into precision plating operations to buffer copper price volatility. ISO 26262 ASIL certification investment is the critical lever for excluding mid-tier competitors from safety-critical vehicle domains threatened by wireless charging displacement. For New Entrants and Emerging Players: Establish a beachhead in India PLI-subsidized Tamil Nadu and Karnataka assembly corridors serving German automotive export programs, where BIS certification requirements filter qualified supplier lists shorter than in established markets. Target fiber-optic media converter nodes for data center buildouts in Virginia and Frankfurt, where MPO/MTP connector standard adoption outpaces incumbent capacity expansion. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming connector divisions lacking automotive safety certification depth. Long-term viability hinges on exposure to electrification and fiber-optic substitution waves rather than legacy copper consumer electronics. Monitor USB-IF specification revision announcements as inventory obsolescence inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| MIL-DTL Certification Investment | Opens NATO defense reshoring programs and excludes uncertified competitors from military avionics procurement. |
| Hybrid Copper-Fiber Architecture Development | Captures data center 100Gbps+ backplane demand where pure copper solutions fail insertion loss budgets. |
| India Manufacturing Footprint Expansion | Accesses PLI scheme subsidies and positions for German automotive OEM supplier concentration strategies. |
| ISO 26262 Quality System Overhaul | Qualifies for Volkswagen Group and BMW single-source adapter strategies launching through 2028. |
| REACH-Compliant Plating Chemistry Reformulation | Prevents ECHA SVHC disclosure mandate disruptions and extends product lifecycle compliance. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 automotive procurement officers, connector platform engineers, aftermarket distribution heads, and defense electronics program managers; and secondary validation through SEC 10-K filings, customs and trade data, USB-IF specification repositories, and ECHA SVHC candidate list updates. Bottom-up demand modeling across vehicle production databases and data center capex disclosures was triangulated against top-down market sizing from connector industry association reports.
Forecast inputs considered product type, connection standard, end-use vertical, material substrate, and regional regulatory cluster across the projection horizon. CAGRs were derived from segment-level growth rate synthesis anchored to automotive electrification penetration curves, fiber-optic displacement rates in infotainment architectures, and defense reshoring policy implementation timelines. USB-IF and HDMI Forum specification revision schedules were modeled as inventory obsolescence triggers.
Stress conditions across copper price volatility bands, REACH substance restriction expansion scenarios, and wireless charging adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about specification consolidation timelines and automotive platform standardization commitments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Underwater Connectors Market
Connectors
Latin America Connector Market
Connectors
Magnetic Connector Market
Connectors
Japan Connector Market
Connectors
Connector for PV System Market
Connectors
Global Wired Interface Market
Connectors
Hazardous Location Connectors Market
Connectors
Power Connector Market
Connectors
Australia Connector Market
Connectors
Space Grade Connectors Market
Connectors
Middle East Connector Market
Connectors
Connector and Terminal Systems for Harsh Environment Wiring Market
Connectors
SATA Connector Market
Connectors
Terminal Pins Market
Connectors
Mexico Connector Market
Connectors
Underwater Mate Connectors Market