
 Global Wires and Cables Market | 2026-2036
Global Wires and Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wires and Cables Market Outlook
Multi-source procurement among utility-scale buyers is consolidating into preferred-supplier arrangements with tier-one manufacturers. Prysmian Group leverages its integrated submarine cable plants in Italy and Finland to anchor long-term offshore wind contracts. Nexans competes through specialized high-voltage direct-current systems for interconnector projects across the North Sea. Sumitomo Electric Industries sustains technology leadership in superconducting and high-temperature cable architectures for dense urban grids.
Wires and cables are engineered conductors—typically copper or aluminum cores sheathed in cross-linked polyethylene or PVC insulation—manufactured through continuous extrusion and annealing processes to transmit electrical power or optical signals across industrial, commercial, and residential systems. Power cables dominate value generation due to capital intensity and project-linked pricing, while fiber optic data cables represent the fastest-expanding margin pool as telecommunications carriers replace legacy copper trunk lines. Aluminum material segments are gaining share in overhead transmission where weight reduction and cost engineering outweigh conductivity penalties.
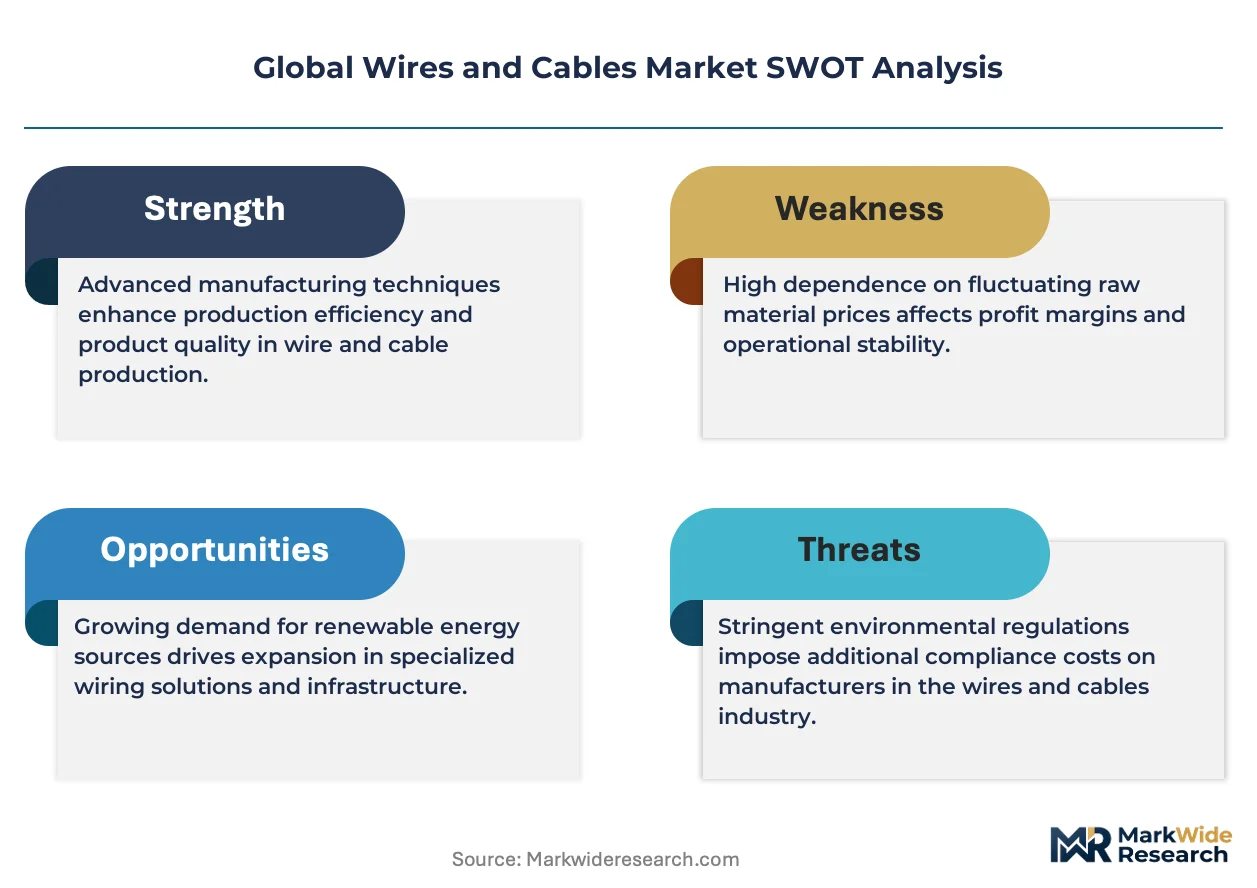
FDA oversight of cable jacketing compounds in medical facility installations, REACH restrictions on halogenated flame retardants in Europe, and China's GB standards for fire-resistant building wire collectively elevate compliance costs while disqualifying low-specification imports. The EU F-Gas Regulation and evolving ECHA substance evaluations are accelerating shifts toward non-PVC insulation chemistries. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and certification gaps.
Market Dynamics
Offshore wind developers are consolidating procurement around vertically integrated cable suppliers capable of delivering turnkey submarine and terrestrial interconnect systems, compressing vendor counts and elevating contract values per engagement.
Growth Catalysts
- EU Green Deal material mandates:Tightening recycled content requirements for copper and aluminum conductors are accelerating facility upgrades among European manufacturers seeking qualification status.
- India rural electrification:Grid modernization programs under the national power ministry are expanding orders for medium-voltage distribution cables into previously unserved districts.
- High-temperature superconducting architectures:Dense urban load centers in Japan and South Korea are piloting cryogenic cable systems to bypass right-of-way constraints.
Market Restraints
- Copper price volatility:Concentrated mining output from Chile and Peru creates input cost instability that manufacturers cannot fully pass through under fixed-price project contracts.
- Submarine cable plant scarcity:Only four facilities worldwide possess combined extrusion and armoring capabilities for high-voltage DC submarine cores, creating multi-year order backlogs.
- REACH halogen restrictions:ECHA evaluations of brominated flame retardants are forcing reformulation of PVC jacketing compounds before proven alternatives achieve scale.
Strategic Opportunities
- Southeast Asia manufacturing migration:Vietnam and Indonesia offer tariff-advantaged production locations for exporters serving Middle Eastern and African markets.
- Data center fiber trunk replacement:Hyperscale cloud operators are ripping out legacy copper backbones for single-mode fiber to support AI training cluster bandwidth.
- US Inflation Reduction Act domestic content:Bonus tax credits for projects using North American-made cables are reshoring production decisions for interconnector and solar farm developers.
Industry Challenges
- Submarine cable installation vessel shortage:Specialized heavy-lift ships with dynamic positioning systems face 18-24 month charter lead times, delaying project commissioning.
- Cross-jurisdiction certification complexity:Manufacturers must maintain parallel testing protocols for IEC, UL, and GB fire-resistance standards, fragmenting quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wires and Cables Market |
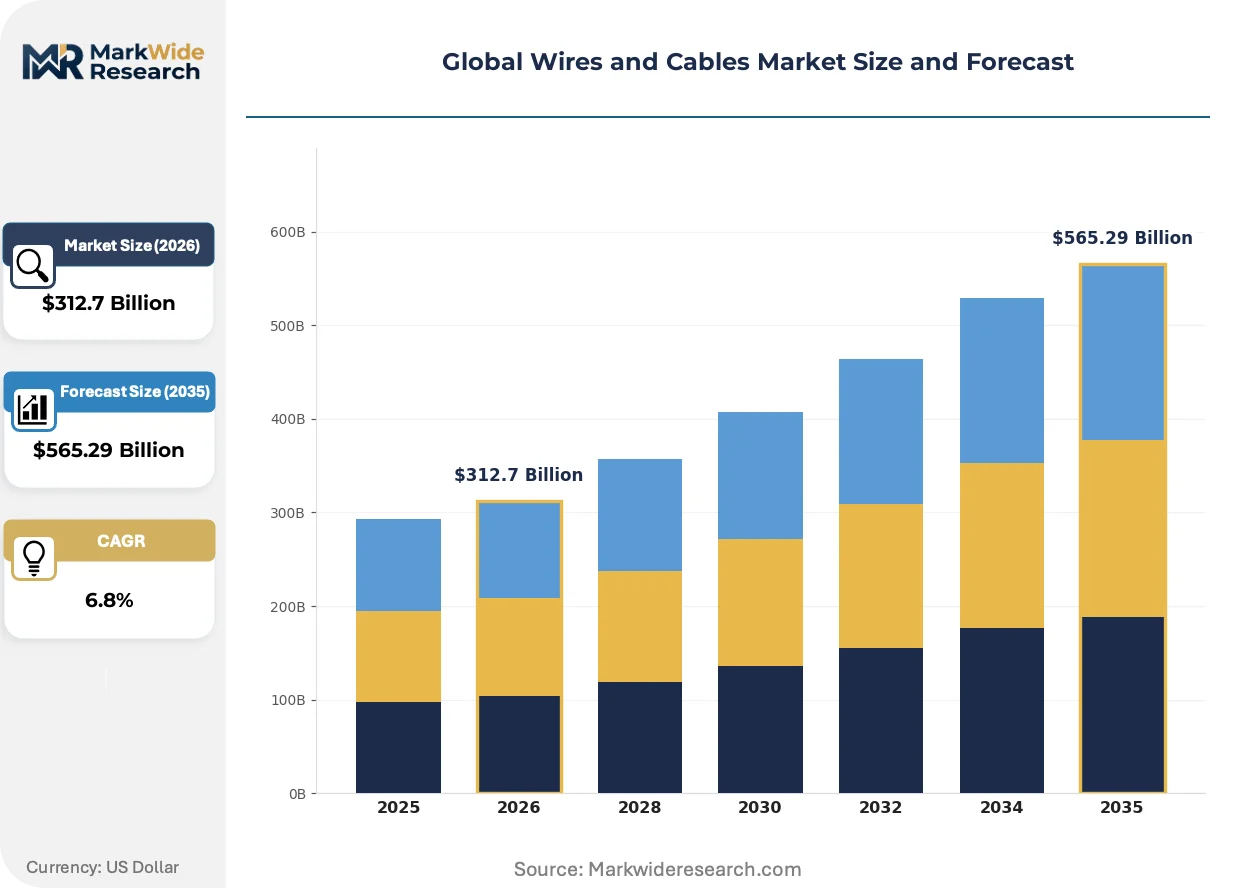
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Cables, Data Cables, Control Cables, Communication Cables Material: Copper, Aluminum, Fiber Optic, PVC End User: Telecommunications, Construction, Automotive, Industrial Installation Type: Above Ground, Underground, Aerial, Indoor/Outdoor |
| Companies Covered | Prysmian Group, Nexans, Sumitomo Electric Industries, LS Cable and System, Southwire Company, Fujikura, NKT, Belden, Amphenol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wires and Cables Market Strategic Shifts
Material chemistry and installation methodology are converging to reduce cable weight and environmental footprint while extending operational lifespans in harsh submarine and desert environments.
Cross-linked polyethylene (XLPE) insulation is consolidating its position as the dominant medium for high-voltage land cables, displacing older oil-filled paper systems. Transmission utilities in Germany and the United States are specifying XLPE for new 400 kV corridors. This consolidation is compressing demand for traditional fluid-impregnated cable manufacturing capacity.
REACH restrictions on halogenated flame retardants are compelling European manufacturers to adopt magnesium hydroxide-filled thermoplastic elastomers. ECHA substance evaluations have accelerated substitution timelines beyond original industry roadmaps. Low-smoke zero-halogen jacketing now dominates building wire specifications in France, Germany, and the Netherlands.
Utility procurement teams are bundling cable supply with installation and commissioning services into single-source EPC arrangements. This unbundling of traditional material-only contracts is elevating risk transfer to manufacturers. The pattern is most visible in North Sea offshore wind developments where developers lack internal cable-lay expertise.
Global Wires and Cables Market Segmentation
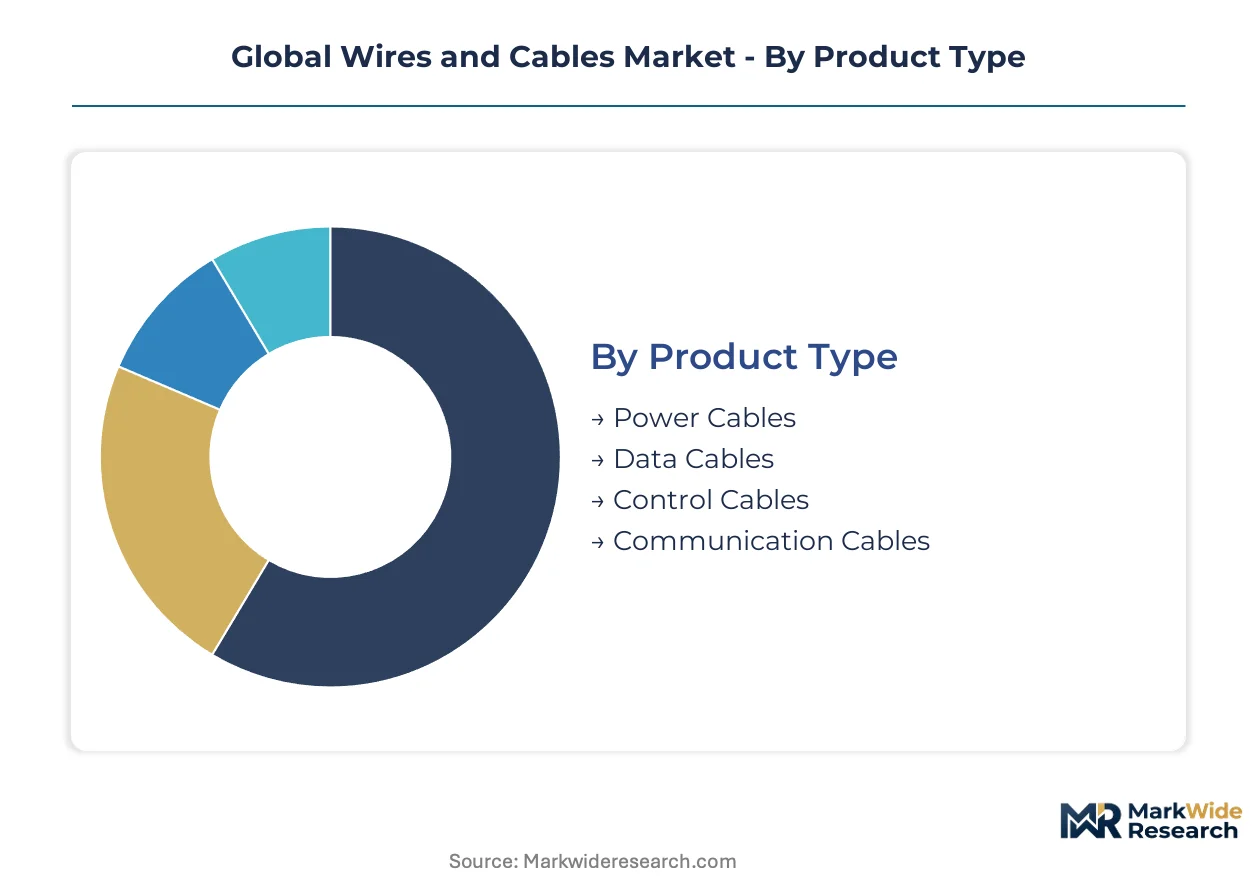
Segmentation in wires and cables reveals divergent margin structures: capital-intensive power transmission commands project-linked premiums, while fiber optic data cables scale through volume replacement cycles. Material chemistry and installation methodology further stratify competitive positioning across utility, industrial, and building wire applications.
Product Type:
Volume concentrates in standardized building and distribution cables, while premium capture belongs to engineered high-voltage and specialty architectures.
- Power Cables:Extruded copper or aluminum conductors with XLPE or EPR insulation rated from low-voltage distribution through 500 kV transmission. Offshore wind developers in the North Sea and solar farm EPCs in India are consolidating procurement around suppliers with integrated submarine and terrestrial capabilities.
- Data Cables:Twisted-pair copper and single-mode fiber constructions for signal transmission in enterprise and carrier networks. Hyperscale cloud operators in Virginia, Frankfurt, and Singapore are ripping out legacy copper backbones for fiber to support AI training cluster bandwidth.
- Control Cables:Multi-conductor flexible assemblies with shielded pairs for industrial automation and process control. Factory automation retrofits in Germany and Japan sustain steady replacement demand.
- Communication Cables:Coaxial and structured cabling for premises distribution and broadband access. Last-mile fiber-to-the-home deployments in Brazil and Indonesia are displacing older copper loop infrastructure.
Mature deployment sits with power cables across established transmission grids. Newer deployment is concentrated in data cables as telecommunications carriers execute generational infrastructure swaps.
Material:
Conductivity requirements versus weight-cost tradeoffs determine metal selection, while jacketing chemistry faces escalating regulatory pressure on halogen content.
- Copper:Electrolytic tough-pitch and oxygen-free high-conductivity grades for power transmission, motor windings, and precision electronics. Chilean and Peruvian mining concentration creates input cost volatility that manufacturers struggle to pass through under fixed-price project contracts.
- Aluminum:Alloy 1350 and 6201 for overhead transmission conductors where weight reduction outweighs conductivity penalties. India's rural electrification programs and Middle Eastern solar farm developers are specifying aluminum aerial cable for cost-engineered deployments.
- Fiber Optic:Glass-core silica fibers with polymer coatings for telecommunications and data center interconnect. Single-mode fiber is expanding most quickly as cloud operators scale AI training infrastructure.
- PVC:Polyvinyl chloride compounds for general-purpose insulation and jacketing in building wire. REACH halogen restrictions are forcing European manufacturers toward magnesium hydroxide-filled thermoplastic elastomer alternatives.
Established volume flows through copper in premium power applications. Aluminum and fiber optic are gaining share fastest where weight engineering and bandwidth scaling override legacy specifications.
End User:
Customer concentration and procurement sophistication vary sharply: utilities negotiate multi-year framework agreements while construction channels fragment across thousands of electrical contractors.
- Telecommunications:Carrier and hyperscale demand for fiber trunk, metro, and last-mile distribution. 5G densification in South Korea and Japan is accelerating orders for hybrid fiber-power feeder cables.
- Construction:Residential, commercial, and infrastructure building wire for power distribution and lighting. Fire-resistant specifications under China's GB standards are elevating compliance costs for low-smoke zero-halogen jacketing.
- Automotive:High-voltage cabling for electric vehicle powertrains and charging infrastructure. Battery OEMs in Germany and the United States are qualifying lightweight aluminum conductors to extend vehicle range.
- Industrial:Process automation, mining, and heavy manufacturing requiring armored and chemical-resistant constructions. Oil sands operators in Canada and petrochemical complexes on the US Gulf Coast specify lead-sheathed or metal-clad cables for hydrocarbon exposure.
Procurement maturity is highest in telecommunications with centralized technical specifications. Construction channels remain fragmented across regional electrical distributors and contractor purchasing cooperatives.
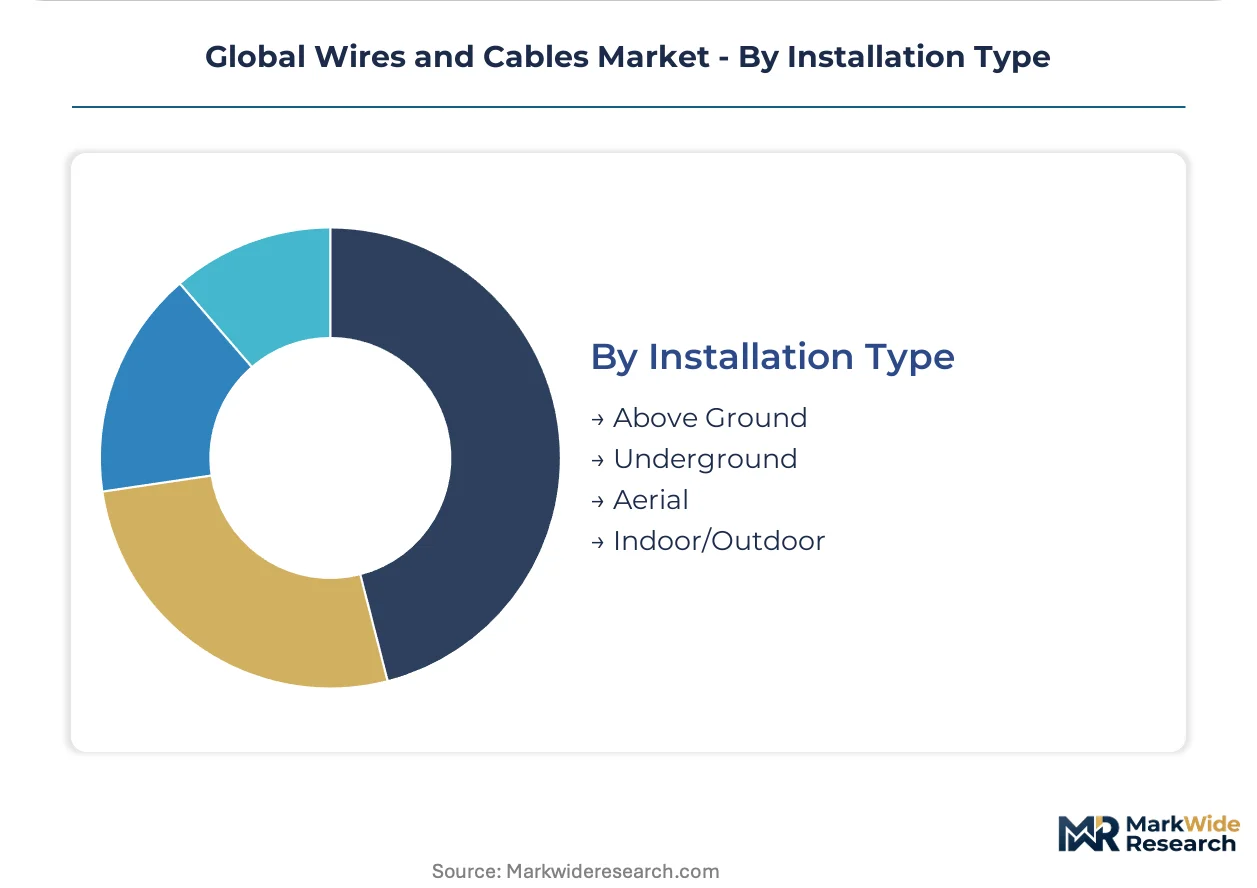
Installation Type:
Above-ground and aerial methods dominate transmission economics, while underground and submarine routes command premium engineering for right-of-way constrained corridors.
- Above Ground:Trench-laid direct-buried or conduit-drawn cables for distribution networks. German utilities are specifying XLPE-insulated 400 kV corridors to replace aging oil-filled paper systems.
- Underground:Direct-buried or duct-bank installations in urban and environmentally sensitive areas. Dense load centers in Tokyo and Seoul are piloting high-temperature superconducting cryogenic systems to bypass right-of-way constraints.
- Aerial:Messenger-supported or self-supporting overhead lines for transmission and distribution. Aluminum conductor steel-reinforced designs prevail in India and Brazil for cost-optimized rural electrification.
- Indoor/Outdoor:Building wire and flexible cords for premises applications with environmental exposure ratings. Low-smoke zero-halogen specifications now dominate commercial construction in France, Germany, and the Netherlands under evolving ECHA evaluations.
Cost-optimized deployment runs through aerial installations in developing markets. Underground and submarine methods are expanding most quickly where urban density and environmental permitting block overhead routes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilean and Peruvian copper mining belts supply raw material for cable fabrication across major manufacturing economies. Concentrated ore extraction creates input cost volatility that reverberates through extrusion plants in Italy, China, and the United States.
China
Dual carbon goals and GB fire-resistance standards are tightening material specifications for building wire and power transmission. MIIT mandates on recycled aluminum content are accelerating facility upgrades among Yangtze River Delta manufacturers. Shanghai and Jiangsu province cable plants are consolidating to meet qualification thresholds for state grid tenders.
Germany
EU Green Deal recycled content requirements and REACH halogen restrictions are forcing reformulation of PVC jacketing compounds. ECHA substance evaluations have compressed substitution timelines beyond original industry roadmaps. North Rhine-Westphalia industrial clusters are piloting magnesium hydroxide-filled thermoplastic elastomers for low-smoke zero-halogen specifications.
United States
IRA domestic content bonus tax credits are reshoring production decisions for interconnector and solar farm developers. FERC interconnection queue reforms are accelerating transmission buildout across Texas and California corridors. Georgia and South Carolina manufacturing plants are expanding extrusion capacity to capture utility-scale procurement.
India
Rural electrification programs under the national power ministry are expanding orders for medium-voltage distribution cables into previously unserved districts. BIS standards for fire-resistant building wire are elevating compliance costs for low-smoke zero-halogen jacketing. Gujarat and Maharashtra cable fabricators are scaling aluminum aerial conductor production for cost-engineered deployments.
Japan
METI funding for high-temperature superconducting pilot projects is advancing cryogenic cable architectures in dense urban load centers. JIS standards for submarine cable armoring are qualifying domestic suppliers for offshore wind interconnectors. Kanto region manufacturers are developing specialized extrusion capabilities for 500 kV XLPE systems.
Global Wires and Cables Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers race to capture offshore wind and data center procurement cycles. The vendor base stratifies across three tiers: integrated submarine-terrestrial suppliers, regional power cable specialists, and commodity building wire fabricators. Strategic archetypes include vertically integrated project developers, technology-licensing specialists, and scale-driven cost leaders. M&A activity and strategic partnerships represent the dominant competitive moves as firms seek extrusion capabilities and installation vessel access.
Among European integrated suppliers, Prysmian Group and Nexans occupy positions as archetype anchors for turnkey submarine and terrestrial interconnect systems. NKT exemplifies the specialized high-voltage direct-current segment serving North Sea interconnector developments. Southwire Company represents the North American scale-driven tier capturing IRA-linked domestic content demand.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| Sumitomo Electric Industries |
| LS Cable and System |
| Southwire Company |
| Fujikura |
| NKT |
| Belden |
| Amphenol Corporation |
| Others |
Value Chain & Pricing Dynamics
Copper cathode prices transmit volatility from Chilean and Peruvian mining belts through extrusion plants to project-linked contract tiers, compressing margins for manufacturers locked into fixed-price offshore wind and interconnector engagements.
Pricing Analysis
Warranty and commissioning service bundling separates integrated submarine-terrestrial suppliers from material-only vendors, with turnkey EPC arrangements commanding project-linked premiums. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—UL-listed and IEC-qualified cables for North American and European utilities versus GB-standard products for cost-engineered deployments. Cost compression in commodity building wire intensifies as Chinese Yangtze River Delta fabricators scale aluminum aerial conductor output. Construction channel electrical contractors exhibit highest price sensitivity, while offshore wind developers prioritize qualification status and installation vessel access over unit economics.
Supply Chain Analysis
Direct-to-utility channels handle framework agreement procurement for transmission utilities, while electrical distributor networks fragment building wire sales across thousands of contractor purchasing cooperatives. Manufacturing gravity centers on China, Italy, and the United States for extrusion capacity, with submarine cable armoring concentrated in Finland and Japan. Raw material flows draw from Chilean copper concentrates, Australian aluminum smelter output, and Saudi petrochemical feedstocks for XLPE insulation. Single-source vulnerability pervades high-voltage DC submarine core production, where only four facilities worldwide possess combined extrusion and armoring capabilities. Distribution runs through regional electrical distributors for construction channels and direct OEM supply for automotive and data center verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH halogen restrictions and China's GB fire-resistance standards erect compliance moats that disqualify low-specification imports, concentrating procurement among qualified tier-one manufacturers with parallel certification protocols.
For Market Incumbents: Extend captive supply of copper cathode and aluminum alloy through backward integration into smelter partnerships or long-term offtake agreements with Chilean and Australian miners. Lock in installation vessel access through charter pre-commitments or equity stakes in heavy-lift ship operators to defend against emerging Asian competitors securing North Sea offshore wind contracts. For New Entrants and Emerging Players: Regional electrical distributors in India's unserved districts represent the most penetrable buyer archetype for cost-engineered aluminum aerial cable. Target Southeast Asian manufacturing migration to Vietnam and Indonesia for tariff-advantaged export positioning into Middle Eastern and African markets. Pursue qualification under BIS fire-resistant standards to access India's rural electrification procurement cycles. For Investors and Strategic Acquirers: Submarine cable plant order backlogs stretching 18-24 months is the leading indicator that high-voltage DC capability scarcity will persist. Frame long-term viability around integrated submarine-terrestrial suppliers with extrusion assets in Italy, Finland, or Japan and proven installation track records. Monitor ECHA substance evaluation timelines for magnesium hydroxide-filled thermoplastic elastomer scale-up as inflection signal for low-smoke zero-halogen jacketing transition.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Supply | Long-term copper and aluminum offtake agreements with Chilean and Australian miners insulate margin compression from commodity volatility. |
| Installation Vessel Charter Pre-commitment | Dynamic positioning heavy-lift ship access secures commissioning schedules for North Sea offshore wind developers facing 18-24 month lead times. |
| Multi-jurisdiction Certification Investment | Parallel IEC, UL, and GB fire-resistance testing protocols qualify manufacturers for EU Green Deal, IRA domestic content, and India rural electrification tenders. |
| Green Chemistry Transition Partnership | Magnesium hydroxide-filled thermoplastic elastomer scale-up with European compounders accelerates REACH-compliant low-smoke zero-halogen jacketing substitution. |
| Regional Manufacturing Footprint Expansion | Vietnam and Indonesia extrusion capacity captures tariff advantages for Middle Eastern solar farm and African grid infrastructure exports. |
Study Parameters
Independent corroboration across executive interviews at Prysmian Group and Nexans, procurement officers at North Sea offshore wind developers, and regulatory affairs leads at ECHA and MIIT underwrites the qualitative findings. Primary fieldwork encompassed plant managers at Yangtze River Delta cable fabricators, utility planning officers at German transmission system operators, and electrical distributor principals in Gujarat and Maharashtra. Secondary validation drew from IEC standard publications, FERC interconnection queue filings, EIA electricity transmission data, and India Ministry of Power rural electrification progress reports. Bottom-up demand modeling across product type, material, end user, and installation type segments triangulated against top-down macroeconomic drivers.
Rate-of-change decomposition across the projection horizon segments volume and value outputs by power cable voltage tier, data cable fiber type, conductor material grade, and geographic regulatory cluster. CAGRs derive from historical trajectory analysis adjusted for policy inflection points including IRA domestic content phase-in, EU Green Deal recycled content mandates, and India PLI scheme qualification thresholds. Industry-specific forecast inputs incorporate submarine cable plant capacity utilization, installation vessel charter availability, and copper futures curve backwardation patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA substance evaluation acceleration, Chilean mining labor action frequency, and hyperscale cloud operator fiber trunk replacement cadence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Detector Market
Cables
US Cables Market
Cables
Copper Cabling Systems Market
Cables
Electric Submersible Cables (ESP) Market
Cables
SATA Power Cable Market
Cables
Asia-Pacific Premise Cable Market
Cables
Shipboard Cable Market
Cables
Anti-Static Space Wires Market
Cables
Cable Management Accessories Market
Cables
Cable Flange Market
Cables
Magnetic Charging Cable Market
Cables
Sensing Cable Market
Cables
Europe Cable Joints Market
Cables
Patch Cable Market
Cables
Flat Flexible Cables Market
Cables
Usb Data Cable Market