
 Radiation Therapy Market | 2026-2036
Radiation Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation Therapy Market Intelligence
The EU Medical Device Regulation is decoupling legacy equipment from new market access across European cancer centers, forcing upgrades to compliant linear accelerator platforms. Siemens Healthineers anchors its position through backward integration into imaging-therapy fusion systems. Elekta competes on software-defined workflow automation for multi-site hospital networks. IBA Worldwide specializes in proton therapy gantries for academic medical centers with heavy ion research mandates.
Radiation therapy delivers ionizing energy to malignant tissue through externally generated photon beams, proton streams, or internally placed radioactive sources, with linear accelerators producing X-rays in the 4–25 MV range to disrupt DNA replication in tumor cells. Intensity-Modulated Radiation Therapy leads installed base volumes due to mature reimbursement codes and broad clinical indications, while Proton Therapy captures concentrated margin pools at elite academic institutions despite capital costs exceeding photon systems by an order of magnitude. Image-Guided Radiation Therapy sustains the fastest expansion trajectory as real-time MRI and CT-integrated delivery reduces planning margins and enables hypofractionation protocols.
FDA 510(k) and PMA pathways govern US device commercialization, while the EU MDR and CE marking requirements extend clinical evidence burdens for software-as-medical-device treatment planning algorithms. Japan's PMDA enforces JIS-aligned quality management systems that delay market entry but confer durability for approved vendors. Stakeholders must monitor convergence between radiation therapy and immunotherapy protocols, as combination trial designs reshape capital allocation toward adaptive platforms capable of sequential or concurrent modality delivery.
Market Dynamics
The EU Medical Device Regulation is decoupling legacy equipment from new market access across European cancer centers, forcing upgrades to compliant linear accelerator platforms. Siemens Healthineers anchors its position through backward integration into imaging-therapy fusion systems. Elekta competes on software-defined workflow automation for multi-site hospital networks. IBA Worldwide specializes in proton therapy gantries for academic medical centers with heavy ion research mandates.
Growth Catalysts
- FDA 510(k) clearance pathways:Streamlined review for AI-enabled treatment planning software accelerates commercialization timelines for adaptive radiotherapy platforms in United States hospital systems.
- Hypofractionation protocols:Compressed treatment schedules reduce patient visit burdens and expand throughput capacity at urban oncology centers facing capacity constraints.
- Germany:Reimbursement frameworks favor capital-intensive oncology infrastructure, sustaining demand for advanced linear accelerator replacements at university hospitals.
Market Restraints
- Proton therapy capital intensity:Installation costs exceeding photon systems by an order of magnitude restrict adoption to elite academic institutions with dedicated research endowments.
- Isotope supply concentration:Molybdenum-99 production clusters in aging research reactors across Canada and Netherlands, creating vulnerability for brachytherapy seed manufacturing.
- EU MDR clinical evidence burdens:Extended documentation requirements for software-as-medical-device algorithms delay market entry for European treatment planning vendors.
Strategic Opportunities
- India:Underpenetrated linear accelerator density relative to cancer incidence creates whitespace for compact, single-vault systems at tier-2 city hospitals.
- MRI-linac convergence:Real-time soft-tissue visualization enables adaptive replanning during fraction delivery, opening premium positioning for integrated hardware-software bundles.
- Japan PMDA durability premium:JIS-aligned quality management systems confer vendor stickiness once approved, rewarding early compliance investment with sustained installed base protection.
Industry Challenges
- Medical physicist shortage:Specialized training pipelines fail to match linear accelerator deployment rates, constraining operational readiness at expanded treatment centers.
- Legacy system integration:Retrofitting AI planning tools into 1990s-era cobalt-60 vaults requires custom engineering that fragments vendor support obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation Therapy Market |
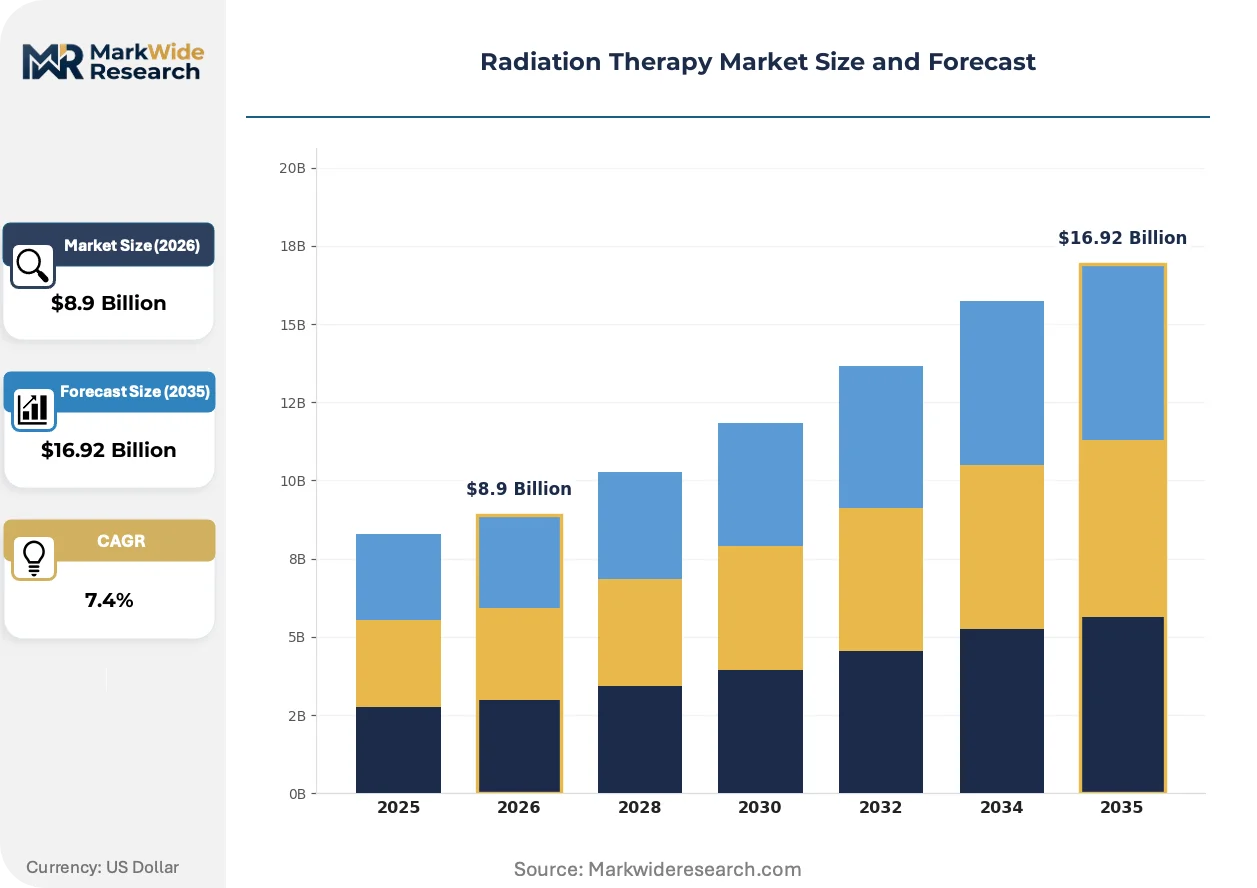
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $16.92 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Accelerators, Brachytherapy, Systemic Radiotherapy, Radiation Therapy Planning Systems Technology: Intensity-Modulated Radiation Therapy, Stereotactic Body Radiation Therapy, Proton Therapy, Image-Guided Radiation Therapy End User: Hospitals, Cancer Research Centers, Outpatient Clinics, Academic Institutions Application: Breast Cancer, Lung Cancer, Prostate Cancer, Brain Tumors |
| Companies Covered | Siemens Healthineers AG, Elekta AB, Accuray Incorporated, IBA Worldwide, ViewRay Technologies, Hitachi High-Tech Corporation, Canon Medical Systems Corporation, GE Healthcare, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation Therapy Market Strategic Shifts & Innovations
Adaptive radiotherapy platforms are compressing the gap between imaging and delivery, enabling same-day plan modifications based on anatomical changes during multi-week treatment courses. This convergence demands reconfiguration of capital allocation, staff workflows, and vendor service models.
Flash radiotherapy is overtaking conventional fractionation protocols in preclinical and early clinical evaluation. Ultra-high dose rates delivered in sub-second pulses spare normal tissue while maintaining tumor cytotoxicity. Academic medical centers in Germany and United States are installing dedicated research gantries to generate evidence for regulatory submission. This modality is overtaking incremental linac upgrades as the priority capital request at NCI-designated cancer centers.
Japan's PMDA has tightened software lifecycle documentation requirements for machine learning-based contouring algorithms, extending premarket review timelines by twelve to eighteen months. Vendors must submit training dataset provenance and performance drift monitoring protocols. European and United States developers seeking Japanese market access are establishing local quality management subsidiaries to satisfy JIS Q 13485 interpretations.
Hospital procurement departments are unbundling equipment purchases from multi-year service contracts, negotiating separate competitive bids for parts logistics, physicist training, and uptime guarantees. This disintermediation pressures vendor margins on the initial capital sale while expanding addressable market for independent service organizations. The pattern is most pronounced at United States hospital networks with centralized capital committees and standardized vendor scorecards.
Radiation Therapy Market Segmentation
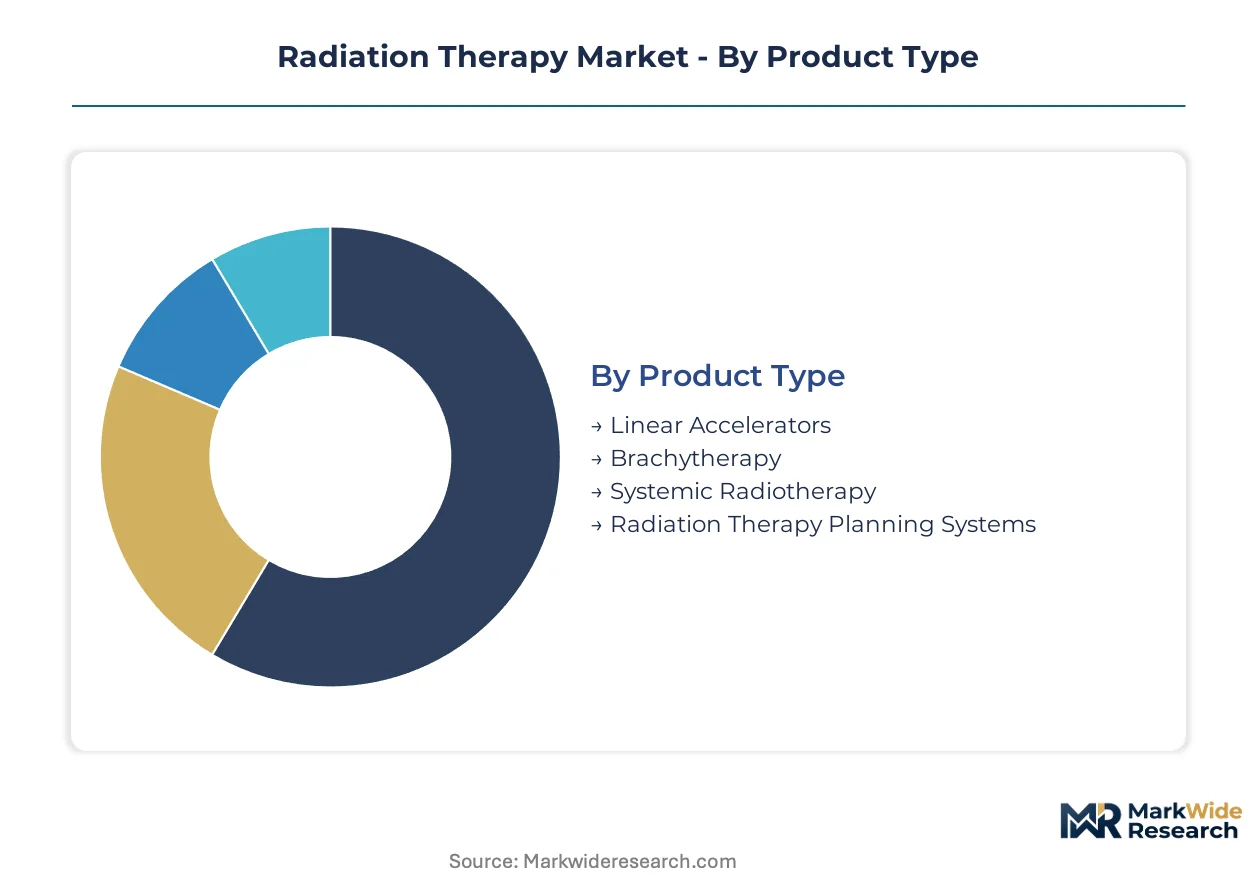
Segmentation in radiation therapy reveals how capital allocation, clinical workflow requirements, and reimbursement structures fragment demand across hardware platforms, treatment modalities, and care delivery settings. Equipment vendors configure product portfolios differently for academic medical centers versus community hospital networks, while software developers tier pricing by contouring automation depth.
Product Type:
Capital intensity varies dramatically across hardware categories, with installation costs spanning two orders of magnitude from compact afterloaders to proton gantries requiring dedicated vault construction.
- Linear Accelerators:These systems generate megavoltage X-rays through microwave-accelerated electron beams striking high-density targets. United States hospital networks prioritize dual-energy configurations with flattening-filter-free modes to compress treatment times and expand daily patient throughput.
- Brachytherapy:Radioactive seeds or temporary catheters deliver dose directly to tumor beds, minimizing exit radiation through tissue. Germany's university hospitals sustain demand for high-dose-rate afterloader replacements driven by mature reimbursement codes for gynecologic and prostate applications.
- Systemic Radiotherapy:Radiopharmaceuticals target metastatic lesions through molecular specificity, with lutetium-177 and radium-223 capturing oncology pharmacy budgets at tertiary referral centers.
- Radiation Therapy Planning Systems:Software platforms automate contouring, dose calculation, and plan optimization, with AI-enabled auto-segmentation commanding premium licensing at high-volume urban centers.
Linear accelerators absorb the bulk of installed capacity; radiation therapy planning systems are expanding most quickly as software subscriptions displace perpetual licenses.
Technology:
Clinical adoption patterns stratify by evidence maturity, with reimbursement availability determining which modalities penetrate community settings versus remaining confined to academic research protocols.
- Intensity-Modulated Radiation Therapy:Multi-leaf collimator modulation shapes dose distributions to concave tumor geometries while sparing adjacent organs at risk. Community hospitals in Japan favor this modality for its established PMDA reimbursement pathway and predictable service revenue.
- Image-Guided Radiation Therapy:Integrated CT or MRI imaging enables daily positional verification and adaptive replanning. Academic institutions in the United States deploy these systems for hypofractionated lung and prostate protocols where margin reduction justifies capital premium.
- Stereotactic Body Radiation Therapy:Ablative dose delivery in five or fewer fractions demands sub-millimeter mechanical precision, constraining adoption to centers with dedicated physics support.
- Proton Therapy:Bragg peak physics eliminates exit dose, sparing healthy tissue in pediatric and ocular applications. Capital requirements exceeding photon systems by an order of magnitude restrict installations to elite institutions with research endowments.
Intensity-modulated radiation therapy commands the largest installed base; image-guided radiation therapy is gaining share fastest as real-time adaptation becomes standard of care.
End User:
Procurement authority and funding mechanisms diverge sharply across institutional types, with capital committees evaluating equipment through distinct clinical and financial lenses.
- Hospitals:Integrated delivery networks negotiate enterprise-wide linear accelerator contracts, prioritizing vendor interoperability and centralized quality assurance across multi-site deployments.
- Cancer Research Centers:NCI-designated institutions access dedicated funding streams for experimental modalities including flash radiotherapy and heavy ion research gantries.
- Outpatient Clinics:Freestanding centers concentrate on high-margin, high-throughput indications with streamlined workflows and minimal inpatient backup requirements.
- Academic Institutions:Teaching hospitals balance clinical service demands against resident training needs, favoring platforms with comprehensive physics education packages.
Hospitals account for the dominant share of equipment procurement; outpatient clinics are climbing the fastest as site-of-care shifts accelerate.
Application:
Tumor site selection drives technology configuration, with anatomical constraints and fractionation tolerance determining which modalities achieve standard-of-care status.
- Prostate Cancer:Hypofractionated regimens and MRI-guided focal boosts have compressed standard treatment courses, expanding throughput capacity at urban centers.
- Lung Cancer:Motion management requirements and steep dose gradients favor stereotactic body radiation therapy for early-stage disease, with adaptive protocols gaining traction for centrally located lesions.
- Breast Cancer:Deep inspiration breath-hold techniques and prone positioning systems reduce cardiac exposure, with intraoperative radiation therapy capturing select cases at specialized centers.
- Brain Tumors:Stereotactic radiosurgery dominates for metastases, while fractionated proton therapy preserves neurocognitive function in pediatric patients with midline tumors.
Prostate cancer applications absorb the largest treatment volume; lung cancer is expanding most quickly as screening programs enlarge the early-stage addressable population.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MD Anderson Cancer Center in Houston anchors North American proton therapy research, while Heidelberg University Hospital drives European flash radiotherapy trials. Regulatory divergence across FDA, EMA, and PMDA pathways fragments vendor certification timelines.
United States
NCI-designated cancer centers in Boston and Houston deploy MRI-linac systems for adaptive protocols. FDA 510(k) clearance pathways streamline AI-enabled treatment planning software commercialization. The Texas Medical Center cluster concentrates proton therapy research gantries for pediatric oncology applications.
Germany
University hospitals in Munich and Heidelberg prioritize linear accelerator replacements under favorable reimbursement frameworks. The EU Medical Device Regulation forces compliance upgrades across legacy equipment installed bases. The Heidelberg Ion Beam Therapy Center anchors heavy ion research for academic medical centers.
Japan
Metropolitan oncology centers in Tokyo and Osaka expand image-guided radiation therapy for hypofractionated lung protocols. PMDA enforces JIS-aligned quality management systems that extend premarket review timelines. The National Cancer Center Hospital in Kashiwa drives clinical validation for machine learning-based contouring algorithms.
India
Tier-2 city hospitals in Maharashtra and Karnataka create demand for compact single-vault linear accelerator systems. CDSCO device registration requirements concentrate vendor resources on metropolitan demonstration sites. The Tata Memorial Hospital in Mumbai anchors training pipelines for medical physicists serving regional referral networks.
United Kingdom
NHS England procurement frameworks prioritize vendor interoperability across multi-site hospital networks. MHRA post-Brexit device regulations extend conformity assessment timelines for software-as-medical-device platforms. The Christie NHS Foundation Trust in Manchester leads adaptive radiotherapy implementation for lung and prostate protocols.
Radiation Therapy Market Key Industry Players
The competitive structure tilts toward diversified medical technology conglomerates with imaging-therapy fusion capabilities. Siemens Healthineers and GE Healthcare anchor the tier through backward integration into diagnostic imaging platforms. Elekta and Accuray occupy specialist positions in software-defined workflow automation. Consolidation pressure intensifies as hospital procurement committees unbundle equipment sales from service contracts.
Among European-based vendors, Siemens Healthineers AG and Elekta AB exemplify contrasting strategic archetypes. Siemens Healthineers represents the imaging-therapy convergence model through its healthcare conglomerate structure. Elekta AB occupies the radiation therapy pure-play position with software-centric automation for multi-site deployments. IBA Worldwide anchors the proton therapy specialization tier for academic medical centers with heavy ion research mandates.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| Elekta AB |
| Accuray Incorporated |
| IBA Worldwide |
| ViewRay Technologies |
| Hitachi High-Tech Corporation |
| Canon Medical Systems Corporation |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Others |
Cost & Logistics Intelligence
AI-enabled treatment planning software is compressing hardware margins while concentrating pricing power among vendors with integrated imaging-therapy platforms, simultaneously reshaping procurement economics and vendor consolidation trajectories across hospital networks.
Pricing Analysis
Outcome-based pricing tied to uptime guarantees and patient throughput metrics anchors vendor contracts at United States hospital systems. Three-tier pricing structure across premium, standard, and economy levels separates MRI-linac bundles from standalone linear accelerators and refurbished cobalt-60 systems. Cost compression in the economy tier is intensifying because independent service organizations are disintermediating legacy maintenance contracts. Community hospital networks in India exhibit highest price sensitivity, while NCI-designated cancer centers prioritize performance premiums over acquisition cost.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's NMPA localization requirements are reshaping sourcing patterns for linear accelerator components and radiation therapy planning software development centers. Manufacturing concentration clusters in Germany, Japan, and the United States for high-precision gantry assemblies, with microwave power sources and multi-leaf collimator arrays feeding from specialized component suppliers. Single-source vulnerability persists for molybdenum-99 isotope production concentrated in aging Canadian and Dutch research reactors. Distribution runs through authorized dealer networks for capital equipment, with direct vendor relationships dominating software licensing and service contract renewals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation's clinical evidence burdens and Japan's PMDA software lifecycle requirements erect formidable compliance moats, privileging vendors with established quality management infrastructure and documented algorithm training provenance.
For Market Incumbents: Deploy backward integration into imaging-therapy fusion systems to capture margin pools from AI-enabled adaptive platforms. Siemens Healthineers anchors this archetype through diagnostic imaging capture. Elekta counters with software-defined workflow automation for multi-site hospital networks. Consolidate service contract portfolios before independent service organizations fragment aftermarket revenue streams.
For New Entrants and Emerging Players: Tier-2 city hospitals in Maharashtra and Karnataka represent the most penetrable buyer archetype, with underdeployed linear accelerator density relative to cancer incidence creating whitespace for compact single-vault systems. Flash radiotherapy research gantries at academic medical centers in Germany and the United States offer a second entry vector through experimental modality validation partnerships. Pursue CDSCO registration through metropolitan demonstration sites to establish regulatory credibility for nationwide expansion.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified medical technology conglomerates seeking imaging-therapy convergence capabilities. Long-term viability hinges on installed base protection through JIS-aligned quality management systems in Japan and FDA 510(k) clearance velocity in the United States. Monitor PMDA software documentation tightening as an inflection signal for vendor compliance cost escalation and market access timeline extension.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Streamlined review accelerates commercialization timelines for adaptive radiotherapy platforms at United States hospital systems. |
| CE Marking Pathway | EU MDR compliance upgrades force legacy equipment replacements across European cancer centers, opening replacement cycles. |
| Hospital System Partnership | Enterprise-wide contracts with integrated delivery networks prioritize vendor interoperability and centralized quality assurance. |
| Software Companion Development | AI-enabled auto-segmentation commands premium licensing at high-volume urban centers, displacing perpetual licenses. |
| Reimbursement Strategy | Hypofractionation protocol validation secures favorable reimbursement codes, expanding throughput capacity at capacity-constrained centers. |
Research Approach
Independent corroboration across hospital procurement committees, biomedical engineering directors, and GPO contracts managers underwrites the qualitative findings, with secondary validation drawing from FDA 510(k) filings, PMDA approval databases, hospital equipment procurement records, and CMS Medicare reimbursement data. Bottom-up installed base enumeration triangulates against top-down capital expenditure flows across NCI-designated cancer centers, university hospitals, and outpatient clinic networks.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon, with segmentation modeling spanning technology modality, end-user institution type, application tumor site, and regional regulatory cluster. CAGRs derive from historical replacement cycle analysis, penetration rate assumptions for emerging modalities, and reimbursement pathway maturation timelines. Forecast inputs incorporate linear accelerator deployment rates, medical physicist training pipeline capacity, and isotope supply reactor operational status.
Revisions become necessary when flash radiotherapy clinical evidence generation accelerates regulatory pathway shifts, proton therapy capital intensity thresholds decline, or molybdenum-99 supply disruptions materialize. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Amyloidosis Treatment Market
Medical Treatment
Gunshot Injuries Treatment Market
Medical Treatment
Global Uterine Fibroids Treatment Market
Medical Treatment
Aspergillosis Treatment Market
Medical Treatment
Facial Spasm Treatment Market
Medical Treatment
Global Acromegaly Treatment Market
Medical Treatment
Myotonic Dystrophy Treatment Market
Medical Treatment
Laser Therapy Market
Medical Treatment
Behcet's Disease Treatment Market
Medical Treatment
Purpura Treatment Market
Medical Treatment
Kidney Stones Management Market
Medical Treatment
Brain Tumor Treatment Market
Medical Treatment
Non-Invasive Surgery Market
Medical Treatment
Goodpasture Syndrome Treatment Market
Medical Treatment
Thyroid Gland Disorders Treatment Market
Medical Treatment
Vaginitis Treatment Drugs Market