
 Laser Therapy Market | 2026-2036
Laser Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Therapy Market Outlook
Semiconductor diode arrays are restructuring cost structures across low-power therapeutic segments. Boston Scientific Corporation leverages its interventional cardiology footprint to anchor laser atherectomy deployment in hospital cath labs. Alma Lasers competes through geographic dominance in aesthetic clinics across Southern Europe and the Middle East. El.En. S.p.A. specializes in high-power CO2 surgical platforms for gynecology and general surgery applications.
Laser therapy employs coherent, monochromatic light energy delivered at precise wavelengths and power densities to induce photochemical, photothermal, or photomechanical biological effects for tissue modification, pain modulation, or pathogen destruction. Nd:YAG lasers operating at 1064 nm penetrate deeper into soft tissue, making them indispensable for orthopedic pain management and vascular lesion treatment. Diode lasers dominate the dermatology application segment due to compact form factors and reduced cooling requirements, while fractional technology commands premium positioning in aesthetic practices by minimizing patient downtime versus ablative alternatives.
The FDA's 510(k) premarket notification framework governs Class II laser device commercialization in the United States, with the Center for Devices and Radiological Health enforcing performance standards under 21 CFR 1040.10. Europe's Medical Device Regulation requires CE marking through notified body conformity assessment, with EMA coordination for laser-drug combination therapies. Stakeholders must monitor evolving harmonization gaps between FDA laser product codes and EU MDR classification rules to preempt market access delays.
Market Dynamics
Semiconductor diode arrays are collapsing unit economics across low-power therapeutic segments, forcing established CO2 and Nd:YAG manufacturers to defend installed base positions through service contract bundling and wavelength versatility claims.
Growth Catalysts
- Outpatient surgical center expansion:Ambulatory facilities across the United States are retrofitting procedure rooms with multi-wavelength platforms to capture displaced hospital volume under CMS site-neutral payment policies.
- EU MDR harmonization:The Medical Device Regulation's consolidated conformity assessment is streamlining cross-border commercialization for diode laser manufacturers targeting aesthetic clinic chains in Germany, Italy, and Spain.
- Photobiomodulation protocols:Standardized dosing guidelines for low-level laser therapy are penetrating sports medicine and physical therapy practices, creating pull-through demand for handheld 635-850 nm devices.
Market Restraints
- Gallium arsenide substrate volatility:Diode laser manufacturing depends on concentrated gallium arsenide wafer supply from Chinese and Taiwanese foundries, exposing cost structures to export control fluctuations.
- Technical depth limitations:Nd:YAG penetration in dark skin phototypes carries melanin absorption trade-offs that constrain safe fluence delivery in Fitzpatrick V-VI patient populations.
- IP thickets in fractional scanning:Dense patent landscapes around microarray beam delivery and thermal zoning algorithms create licensing friction for new market entrants.
Strategic Opportunities
- Home-use device deregulation:FDA's expanding over-the-counter clearance pathway for sub-5mW therapeutic lasers is opening direct-to-consumer channels previously restricted to prescription distribution.
- Veterinary oncology applications:Photodynamic therapy protocols for canine and feline cutaneous malignancies remain underpenetrated across North American and European companion animal practices.
- AI-assisted treatment planning:Integration of machine learning-based skin type classification and fluence optimization is creating premium positioning for connected laser platforms in high-volume dermatology chains.
Industry Challenges
- Laser safety officer certification gaps:State-level medical laser operator licensing requirements vary dramatically across the United States, creating compliance complexity for multi-site clinic operators.
- Legacy system integration:Aesthetic practices with 2015-2019 vintage fractional CO2 installations face upgrade friction due to proprietary handpiece architectures and locked service agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Therapy Market |
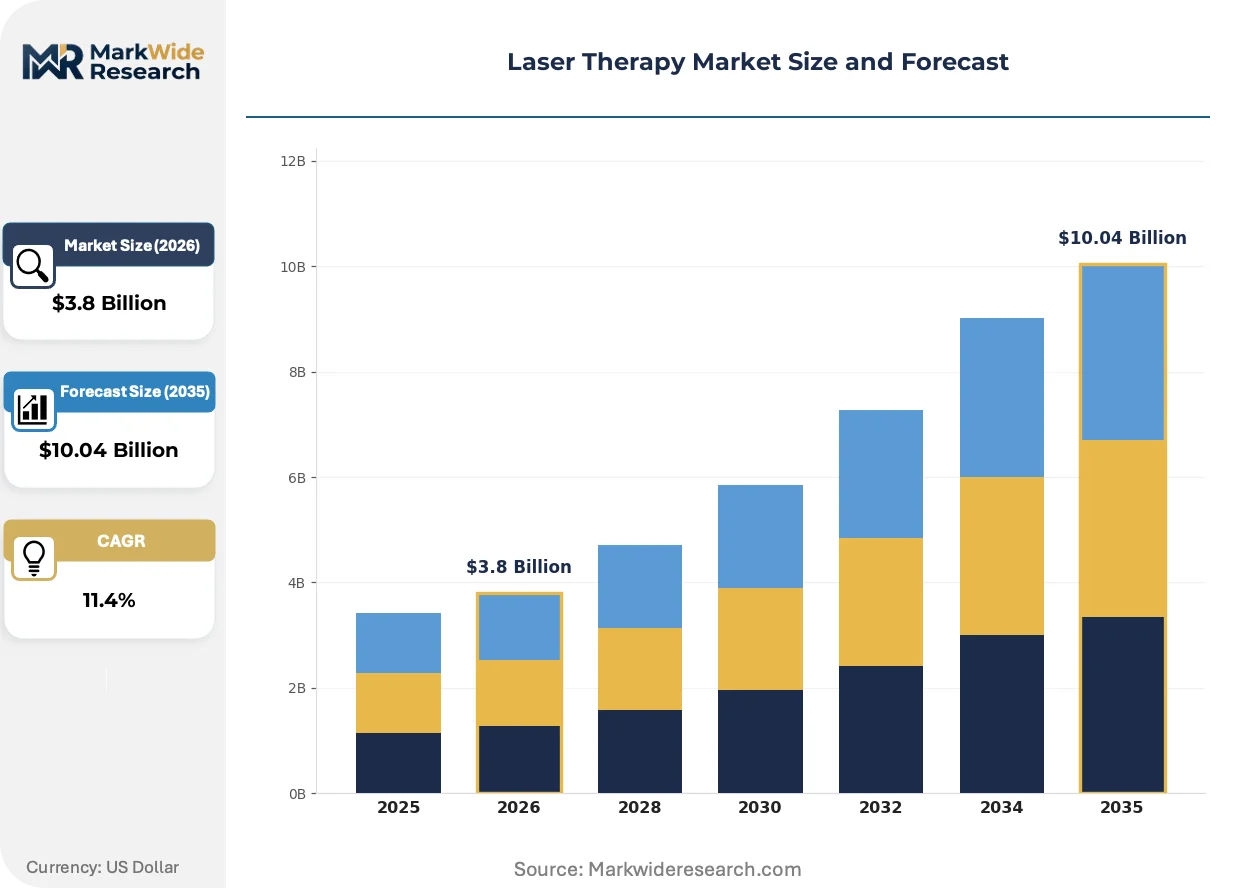
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diode Lasers, Nd:YAG Lasers, CO2 Lasers, Argon Lasers Application: Pain Management, Dermatology, Surgery, Dentistry End User: Hospitals, Clinics, Private Practices, Rehabilitation Centers Technology: Continuous Wave, Pulsed Wave, Fractional Technology, Q-Switch Technology |
| Companies Covered | LUMIBIRD, Boston Scientific Corporation, TOPCON CORPORATION, Cynosure, Alcon Inc., Alma Lasers, BIOLASE, Inc., Bausch + Lomb Corporation, El.En. S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Therapy Market Strategic Shifts
Platform convergence and intelligent automation are redefining competitive differentiation beyond raw power specifications, with software-defined treatment protocols and predictive maintenance capabilities emerging as primary purchase criteria.
Picosecond domain pulse technology is modularizing across dermatology and tattoo removal applications. Aesthetic chains in South Korea and the United States are adopting dual-wavelength 755/1064 nm platforms at replacement cycle compression rates below 36 months. This architecture is modularizing service revenue models by enabling wavelength upgrades through firmware rather than hardware swaps.
The EU Medical Device Regulation's post-market surveillance requirements are intensifying clinical evidence obligations for high-risk laser classifications. Manufacturers must now maintain active implantable device-level vigilance systems for Class IIb surgical lasers, driving consolidation of notified body relationships. Germany's aesthetic device distributors are responding by pre-qualifying suppliers with established EUDAMED registration track records.
Subscription-based equipment access is displacing capital purchase models in mid-tier dermatology practices. Third-party financing platforms are bundling preventive maintenance and consumable replenishment into per-procedure pricing structures. This shift is most visible across the United States, where private equity-backed clinic rollouts prioritize opex flexibility over balance sheet ownership.
Laser Therapy Market Segmentation
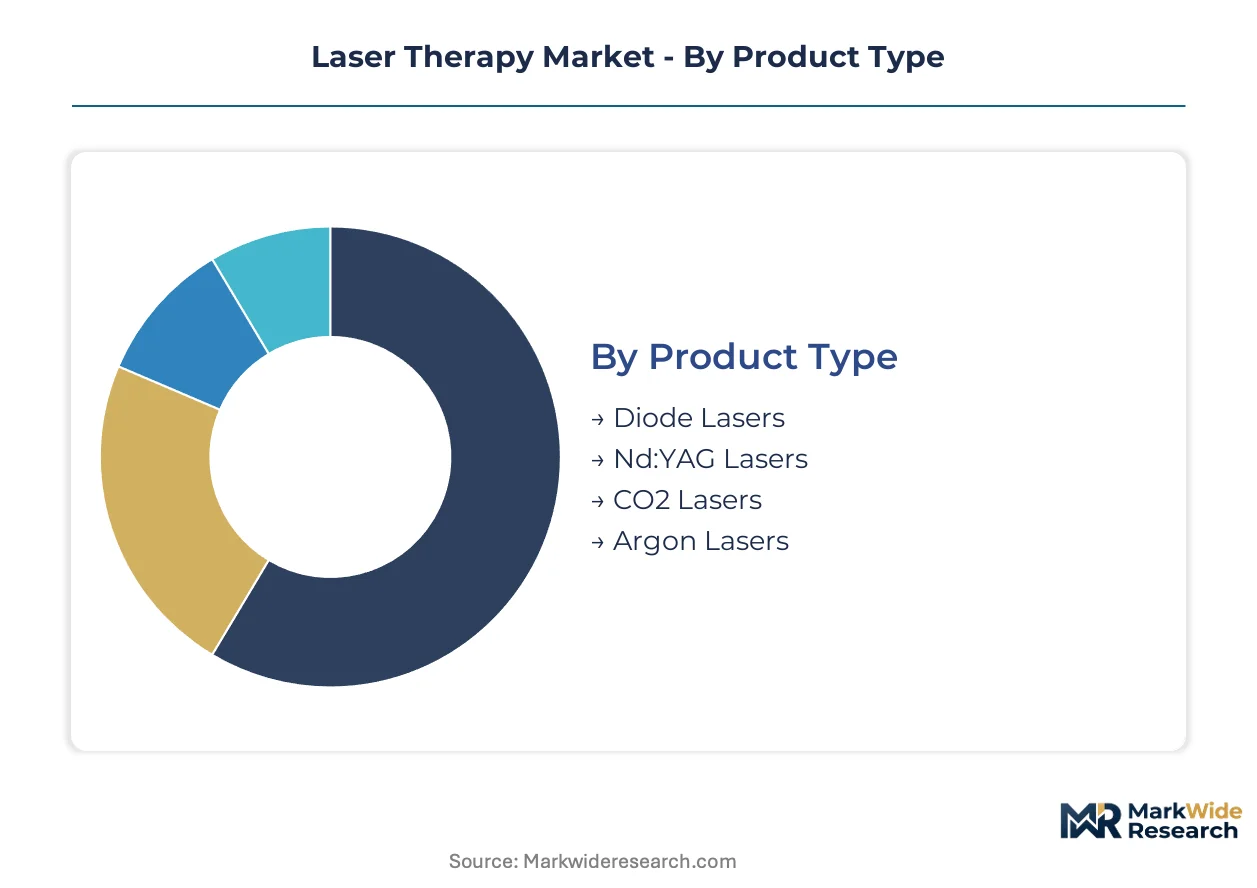
Laser therapy segmentation reflects divergent physics requirements across clinical disciplines. Wavelength penetration depth, thermal confinement, and beam delivery mode determine device selection for specific tissue interactions.
Product Type:
Semiconductor architecture and gain medium composition define cost structures and clinical versatility across installed bases.
- Diode Lasers:Compact semiconductor arrays operating at 800-980 nm wavelengths deliver precise thermal damage to superficial tissue with minimal collateral heating. Demand concentrates in dermatology clinics across Germany and Spain, where hair removal protocols favor portable units with reduced cooling infrastructure.
- Nd:YAG Lasers:Neodymium-doped yttrium aluminum garnet crystals generate 1064 nm emission with exceptional soft-tissue penetration depth. Orthopedic pain management practices in the United States deploy these systems for deep-joint photobiomodulation, constrained by melanin absorption trade-offs in darker skin phototypes.
- CO2 Lasers:Gas-discharge platforms at 10,600 nm provide ablative precision for surgical excision and skin resurfacing.
- Argon Lasers:Ionized noble-gas emission at 488-514 nm targets hemoglobin absorption for retinal photocoagulation and vascular lesion treatment.
Diode lasers lead on scale; Nd:YAG lasers lead on momentum.
Application:
Clinical outcome requirements drive specification differentiation across therapeutic domains.
- Dermatology:Aesthetic and medical skin procedures demand wavelength tunability for lesion-specific chromophore targeting. South Korean clinic chains are compressing replacement cycles below 36 months for dual-wavelength platforms combining 755 nm melanin absorption with 1064 nm depth penetration.
- Pain Management:Low-level laser therapy protocols at 635-850 nm modulate cellular metabolism without thermal damage. Physical therapy practices across the United States are standardizing dosing guidelines for sports medicine applications, creating pull-through demand for handheld devices.
- Surgery:High-power platforms enable precise tissue cutting and hemostasis across gynecology and general surgery specialties.
- Dentistry:Er:YAG and diode wavelengths address soft-tissue procedures and caries removal with reduced patient anxiety versus conventional instrumentation.
Dermatology leads on scale; pain management leads on momentum.
End User:
Capital intensity and procedure volume shape procurement patterns across facility types.
- Hospitals:Multi-disciplinary surgical departments require versatile platforms with service contract bundling. Outpatient surgical centers across the United States are retrofitting procedure rooms with multi-wavelength systems to capture displaced hospital volume under CMS site-neutral payment policies.
- Clinics:Specialized aesthetic and dermatology chains prioritize opex flexibility through subscription-based equipment access. Private equity-backed rollouts favor per-procedure pricing structures bundling maintenance and consumables.
- Private Practices:Solo practitioners face upgrade friction from proprietary handpiece architectures and locked service agreements on 2015-2019 vintage installations.
- Rehabilitation Centers:Sports medicine and physical therapy facilities standardize on low-power protocols with standardized dosing guidelines.
Hospitals lead on scale; clinics lead on momentum.
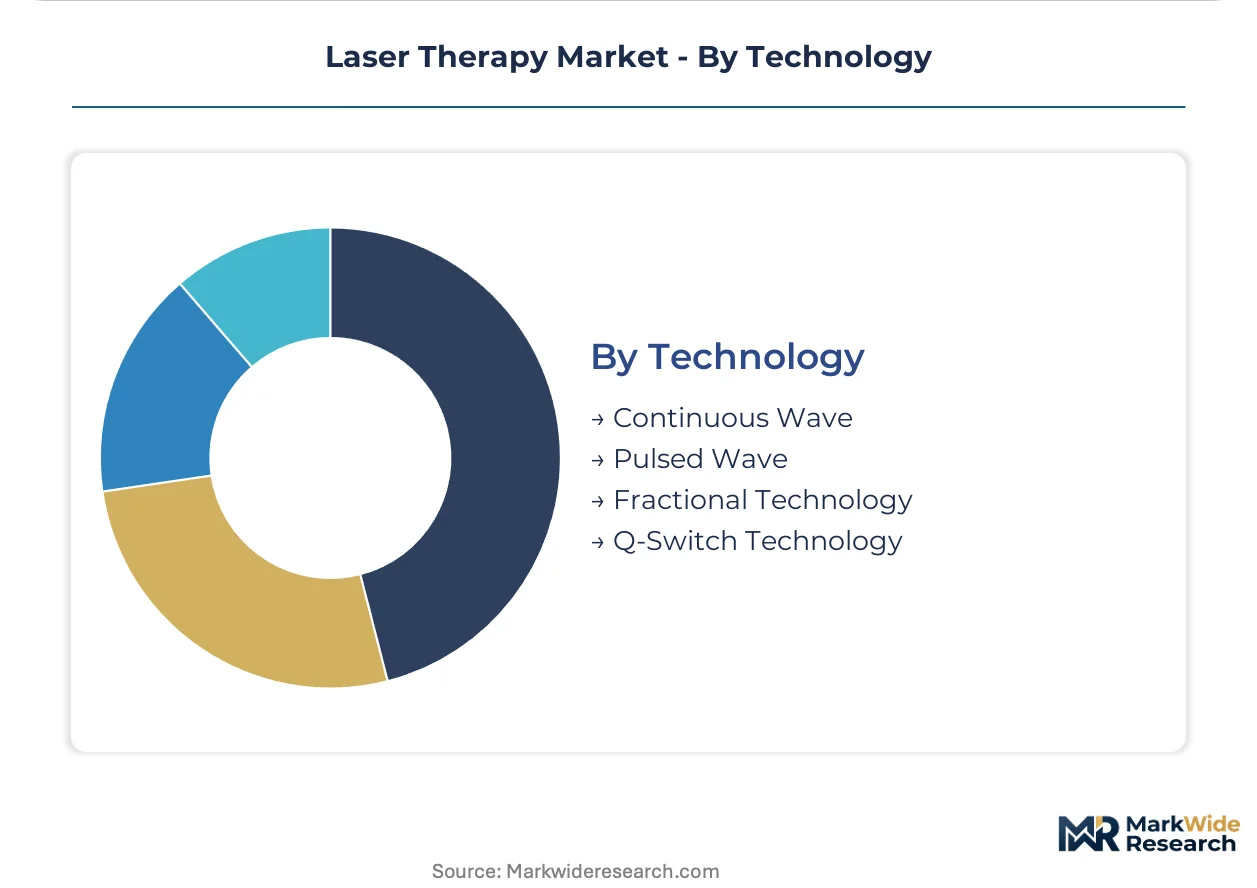
Technology:
Temporal emission characteristics determine tissue interaction mechanisms and safety profiles.
- Fractional Technology:Microarray beam delivery creates microscopic thermal zones surrounded by intact tissue, accelerating healing versus ablative alternatives. Aesthetic practices command premium positioning for reduced patient downtime, though dense patent landscapes around thermal zoning algorithms create licensing friction for new entrants.
- Q-Switch Technology:Nanosecond pulse generation enables photomechanical disruption of tattoo pigments and melanosomes without thermal damage. Picosecond domain modularization is compressing replacement cycles across dermatology applications.
- Continuous Wave:Steady-state emission provides predictable thermal accumulation for surgical cutting and coagulation.
- Pulsed Wave:Millisecond-duration pulses balance thermal confinement with depth penetration for vascular and pigmented lesion treatment.
Fractional technology leads on scale; Q-switch technology leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dermatology clinics anchor the European installed base for diode laser systems, while United States outpatient surgical centers drive multi-wavelength platform procurement under site-neutral reimbursement policies. Regulatory harmonization between FDA 510(k) pathways and EU MDR conformity assessments is compressing commercialization timelines for cross-border device manufacturers.
United States
Ambulatory surgical centers in Texas and Florida are retrofitting procedure rooms with CO2 and Nd:YAG systems to capture displaced hospital volume under CMS site-neutral payment policies. FDA's Center for Devices and Radiological Health enforces 21 CFR 1040.10 performance standards for Class II laser commercialization. The Dallas-Fort Worth metroplex concentrates aesthetic clinic chains deploying subscription-based equipment access models.
Germany
Dermatology practices in Bavaria and North Rhine-Westphalia are expanding diode laser installations for hair removal protocols with reduced cooling infrastructure requirements. EU Medical Device Regulation mandates CE marking through notified body conformity assessment with EUDAMED registration. Munich's medical technology cluster hosts distributors pre-qualifying suppliers with established post-market surveillance track records.
South Korea
Aesthetic clinic chains in Seoul are compressing replacement cycles below 36 months for dual-wavelength 755/1064 nm platforms combining melanin absorption with depth penetration. MFDS regulates laser medical devices under the Medical Device Act with risk-based classification. The Gangnam district anchors premium positioning for connected laser platforms with AI-assisted treatment planning capabilities.
Japan
Physical therapy practices in Tokyo and Osaka are standardizing photobiomodulation dosing guidelines for low-level laser therapy in sports medicine applications. PMDA oversees medical laser approval under the Pharmaceutical and Medical Device Act with QMS conformity assessment. The Kansai region concentrates rehabilitation centers procuring handheld 635-850 nm devices for outpatient pain management.
United Arab Emirates
Private dermatology chains in Dubai are importing fractional CO2 platforms for medical tourism markets serving Gulf and South Asian patient populations. MOHAP regulates medical device importation through the Emirates Drug Establishment with mandatory facility inspections. Dubai Healthcare City clusters aesthetic clinics prioritizing opex flexibility through third-party financing bundles.
Laser Therapy Market Competitive Environment
Service contract bundling dominates the current landscape as established CO2 and Nd:YAG manufacturers defend installed base positions against collapsing diode laser unit economics. The vendor base separates into three tiers: diversified medical technology conglomerates with interventional cardiology footprints, pure-play aesthetic device specialists with geographic concentration strategies, and high-power surgical platform fabricators serving gynecology and general surgery applications. Strategic archetypes include wavelength versatility defenders, subscription-based access providers, and AI-enabled connected platform developers. M&A activity and technology licensing agreements represent the primary competitive moves reshaping market structure.
Within the diversified medical technology tier, Boston Scientific Corporation occupies a position exemplifying interventional cardiology-anchored laser atherectomy deployment. Alma Lasers represents geographic dominance archetypes concentrated in Southern European and Middle Eastern aesthetic clinic chains. El.En. S.p.A. anchors the high-power surgical platform segment with specialization in CO2 systems for gynecology applications. These three entities collectively illustrate the strategic segmentation between conglomerate diversification, regional market concentration, and surgical specialty focus.
| Leading Market Players |
|---|
| LUMIBIRD |
| Boston Scientific Corporation |
| TOPCON CORPORATION |
| Cynosure |
| Alcon Inc. |
| Alma Lasers |
| BIOLASE, Inc. |
| Bausch + Lomb Corporation |
| El.En. S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Subscription-based equipment access models among United States dermatology chains are forcing diode laser manufacturers to restructure revenue recognition and component sourcing strategies, compressing margins on hardware while expanding service attachment rates.
Pricing Analysis
Gallium arsenide wafer costs pass through directly to diode laser unit economics, with Chinese and Taiwanese foundry pricing volatility translating into quarterly cost adjustments for device assemblers. Pricing stratifies across premium, standard, and economy tiers based on wavelength versatility and FDA clearance tier, with aesthetic clinic chains exhibiting highest price sensitivity versus hospital surgical departments. Cost compression in the mid-tier segment is intensifying because semiconductor array manufacturers are collapsing unit economics through volume scale. Private equity-backed clinic rollouts favor per-procedure pricing structures that bundle preventive maintenance and consumable replenishment.
Supply Chain Analysis
Dual-sourcing requirements for gallium arsenide substrates mandate qualification of both Chinese and Taiwanese foundries by major device manufacturers, with backup qualification timelines extending procurement cycles. Manufacturing draws from concentrated wafer supply in China, Taiwan, and Japan, with final assembly clustering in Germany, the United States, and South Korea. Single-source vulnerability persists around high-purity neodymium-doped yttrium aluminum garnet crystals for Nd:YAG gain media. Distribution runs through specialized medical device distributors with EUDAMED registration track records in Europe and GPO contracts in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laser therapy market reads as a late-cycle quality story where platform convergence and intelligent automation capabilities command premium positioning, justified by South Korean clinic chains compressing replacement cycles below 36 months for dual-wavelength systems with AI-assisted treatment planning.
For Market Incumbents: Anchor defensive positions through service contract bundling on installed CO2 and Nd:YAG bases while accelerating software-defined wavelength upgrade architectures that neutralize diode laser cost advantages. Patent thickets around fractional scanning algorithms provide licensing leverage against emerging entrants. Vertical integration into gallium arsenide wafer supply hedges foundry concentration risk. For New Entrants and Emerging Players: The mid-tier price-point gap between premium connected platforms and economy diode systems offers white-space entry for veterinary oncology photodynamic therapy protocols across North American companion animal practices. Home-use device deregulation under FDA over-the-counter clearance pathways enables direct-to-consumer channels previously restricted to prescription distribution. Target AI-assisted fluence optimization as the primary go-to-market differentiator. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play aesthetic device specialists possessing established EUDAMED registration track records and geographic concentration in Southern European clinic chains. Long-term viability hinges on post-market surveillance infrastructure compliance under EU MDR intensifying clinical evidence obligations. Watch AI-enabled connected platform adoption rates in high-volume dermatology chains as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Wavelength Architecture | Firmware-enabled upgrades neutralize hardware replacement cycles for aesthetic clinic chains. |
| EUDAMED Registration Pre-Qualification | German distributors filter suppliers based on established post-market surveillance track records. |
| AI-Assisted Treatment Planning Integration | Machine learning-based skin classification commands premium positioning in Gangnam district clinics. |
| Veterinary Oncology Protocol Development | Photodynamic therapy for canine cutaneous malignancies remains underpenetrated across North American practices. |
| Home-Use Device Deregulation Pathway | FDA over-the-counter clearance opens direct-to-consumer channels for sub-5mW therapeutic lasers. |
Study Parameters
Coverage spans the United States, Germany, South Korea, Japan, and the United Arab Emirates, with primary inputs from each market combining interviews with dermatology clinic operators, hospital purchasing committee members, biomedical engineers, and GPO contracts managers alongside secondary validation from FDA 510(k) filings, EMA coordination records, MFDS Medical Device Act submissions, and CMS site-neutral payment policy documentation. Bottom-up procedure volume estimates triangulate against top-down manufacturer shipment data.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon, with segmentation dimensions modeling product type, application, end user, and technology platform including temporal emission characteristics. CAGRs derive from logistic diffusion curves fitted to replacement cycle compression patterns and ambulatory surgical center expansion trajectories. Forecast inputs incorporate photobiomodulation protocol standardization rates and AI-enabled platform adoption curves.
Caveats apply where gallium arsenide export control fluctuations, EU MDR harmonization delays, or home-use deregulation reversals could materially shift the outlook. Forecasts reflect assumptions around reimbursement stability and clinic consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Global Sex Reassignment Surgery Market
Medical Treatment
China Nose Reconstruction Market
Medical Treatment
Peri-Implantitis Treatment Market
Medical Treatment
Middle Ear Infection Treatment Market
Medical Treatment
Europe Chronic Disease Management Market
Medical Treatment
Dementia and Alzheimers Disease Treatment Market
Medical Treatment
Ringworm Treatment Market
Medical Treatment
Global Autoimmune Treatment Market
Medical Treatment
Onchocerciasis Treatment Market
Medical Treatment
Acupuncture Treatment Market
Medical Treatment
Scalp Care Treatment Market
Medical Treatment
Lysosomal Storage Disease Treatment Market
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
Global Radiodermatitis Treatment Market
Medical Treatment
Tetanus Treatment Market
Medical Treatment
Rabies Treatment Market