
 Amyloidosis Treatment Market | 2026-2036
Amyloidosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Amyloidosis Treatment Market Analysis
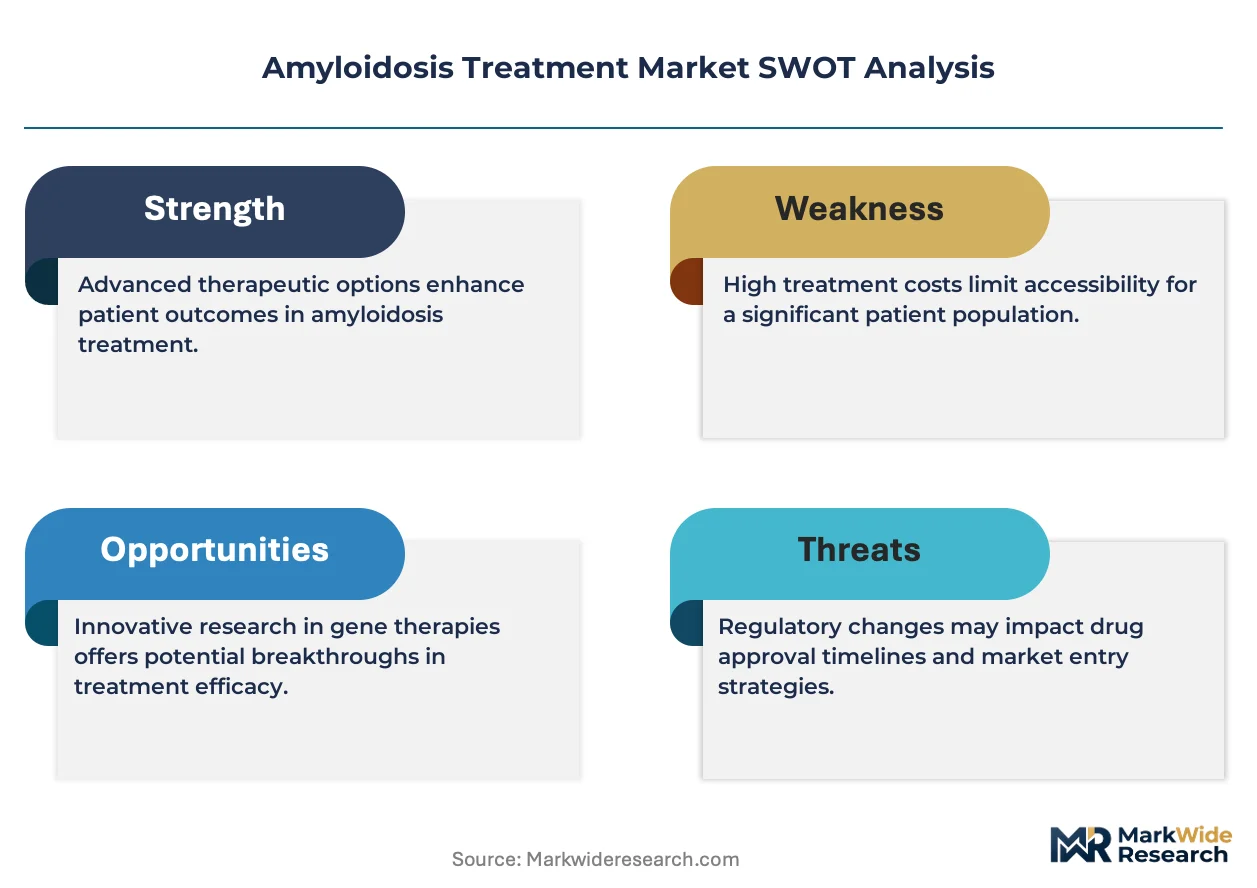
Platform licensing revenue from RNA interference assets is tilting toward large-cap biopharma partners with established rare disease infrastructure. Alnylam Pharmaceuticals sustains technology leadership through its GalNAc conjugate delivery system and commercial execution in hereditary ATTR amyloidosis. Pfizer Inc. leverages manufacturing scale and cardiovascular franchise integration to compete in the TTR-directed therapy segment. Johnson & Johnson Services, Inc. anchors its position through deep hematology expertise and global hospital channel access.
Amyloidosis treatment encompasses pharmacological interventions targeting pathogenic protein aggregation, including monoclonal antibodies that bind circulating light chains or stabilize transthyretin tetramers, and small interfering RNA molecules that suppress hepatic synthesis of amyloidogenic precursors. These therapies halt organ deposition, preserve cardiac and neurological function, and extend survival in systemic amyloidosis subtypes. Monoclonal antibodies capture the dominant share of current value owing to premium positioning in AL amyloidosis, while subcutaneous delivery formats represent the fastest-expanding modality as patients and payers prioritize reduced infusion center dependency. Early intervention stages command concentrated R&D investment, though maintenance therapy segments are deepening as relapse prevention protocols standardize across academic medical centers.
The FDA's accelerated approval and orphan drug designations compress development timelines and extend exclusivity periods for amyloidosis developers. EMA parallel scientific advice and national health technology assessment bodies, including NICE in the United Kingdom and HAS in France, condition reimbursement on demonstrated organ response and quality-of-life endpoints. Stakeholders must monitor evolving biomarker qualification pathways and real-world evidence requirements that will determine post-approval market access durability.
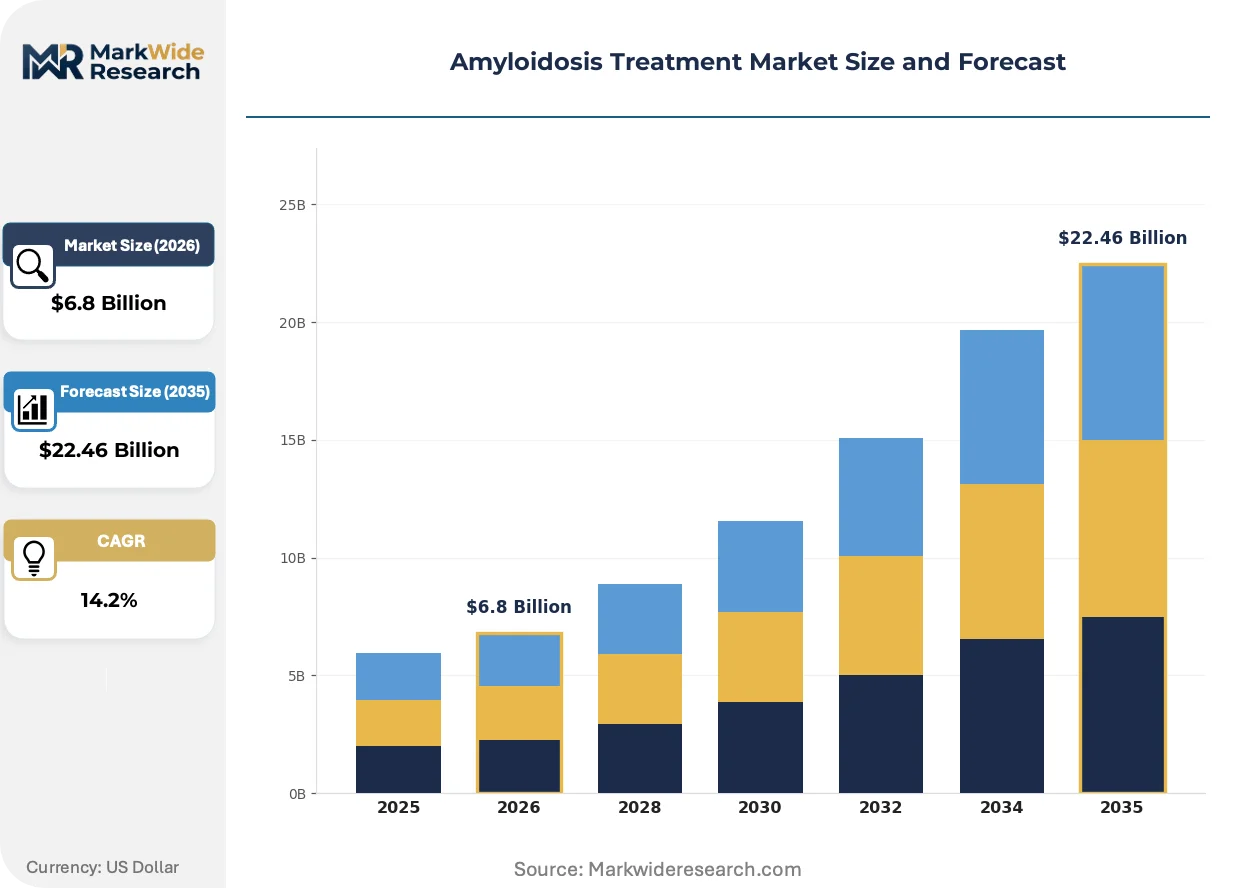
Market Dynamics
RNA interference therapeutics are compressing development timelines and forcing incumbent monoclonal antibody developers to accelerate subcutaneous formulation programs. The FDA's accelerated approval pathway for rare diseases has shortened commercialization cycles from eight years to under four, intensifying competitive pressure across all modality classes.
Growth Catalysts
- FDA Accelerated Approval Pathway:Orphan drug designation combined with breakthrough therapy status enables earlier market entry based on surrogate endpoints. This compresses Phase 3 requirements and extends exclusivity periods for novel mechanisms.
- Subcutaneous Delivery Migration:Patient advocacy groups and infusion center capacity constraints are driving demand for self-administered formulations. Specialty pharmacy networks are expanding cold-chain infrastructure to support at-home administration.
- Cardiology-Hematology Convergence:Academic medical centers are integrating amyloidosis programs across departments, creating unified referral pathways that concentrate treatment volume at tertiary centers with advanced diagnostic capabilities.
Market Restraints
- Plasma-Derived API Concentration:Immunoglobulin supply chains depend on US and European plasma collection networks, creating vulnerability to donor availability fluctuations and viral screening protocol changes.
- Biomarker Validation Gaps:N-terminal pro-BNP and free light chain assays lack harmonized standards across reference laboratories, complicating multi-center trial enrollment and regulatory submission consistency.
- Specialized Infusion Infrastructure:Tafamidis and patisiran require monitored administration settings with cardiac telemetry capabilities, limiting site expansion in rural and secondary markets.
Strategic Opportunities
- Japan's Elderly Population:Wild-type ATTR amyloidosis prevalence correlates with age demographics, positioning Japanese healthcare systems as high-volume early adopters for disease-modifying therapies with cardiovascular endpoints.
- Real-World Evidence Mandates:EMA's post-authorization study requirements and FDA's guidance on natural history data create openings for registry-based trial designs that reduce placebo arm needs.
- Gene Silencing-Small Molecule Combinations:Stacking RNAi knockdown with tetramer stabilizers offers mechanistic synergy that could displace sequential monotherapy protocols in treatment-naïve patients.
Industry Challenges
- Cardiac Biopsy Expertise Scarcity:Endomyocardial sampling requires specialized electrophysiology training that concentrates at fewer than 200 US institutions, creating diagnostic bottlenecks that delay treatment initiation.
- Cross-Border Reimbursement Fragmentation:NICE, HAS, and G-BA apply divergent cost-effectiveness thresholds to quality-adjusted life year calculations, forcing developers to maintain multiple health economics modeling frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amyloidosis Treatment Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Chemotherapy, Immunomodulators, Corticosteroids Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Clinics, Home Care, Specialty Pharmacies Treatment Stage: Early Intervention, Advanced Disease, Palliative Care, Maintenance Therapy |
| Companies Covered | Pfizer Inc., Alnylam Pharmaceuticals, Inc., Johnson & Johnson Services, Inc., Takeda Pharmaceutical Company Limited, GSK plc, Novartis AG, Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd, Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amyloidosis Treatment Market Emerging Trajectories
Gene silencing platforms are forcing reformulation of competitive strategies across the transthyretin and light chain amyloidosis segments. Technology migration, regulatory pathway evolution, and site-of-care redistribution are the three forces restructuring commercial execution.
GalNAc-conjugated siRNA chemistry is migrating from intravenous to subcutaneous administration, reducing dosing frequency from every three weeks to quarterly intervals. Academic medical centers in Boston and San Francisco are adopting these platforms as first-line therapy for hereditary ATTR, compressing hospital infusion revenue and shifting margin capture to specialty pharmacy channels.
EMA's parallel scientific advice procedure now coordinates with national health technology assessment bodies during Phase 2, compressing the gap between regulatory approval and reimbursement listing. Developers engaging early with NICE and HAS are securing conditional access agreements that tie pricing to organ response rates, fundamentally altering contract structures for rare disease therapies.
Hospital procurement departments are consolidating amyloidosis drug purchasing through integrated delivery networks, displacing individual physician preference as the primary purchasing determinant. This concentration is most visible in the United States, where IDNs representing over 40 million covered lives now mandate prior authorization through centralized pharmacy and therapeutics committees.
Amyloidosis Treatment Market Segmentation
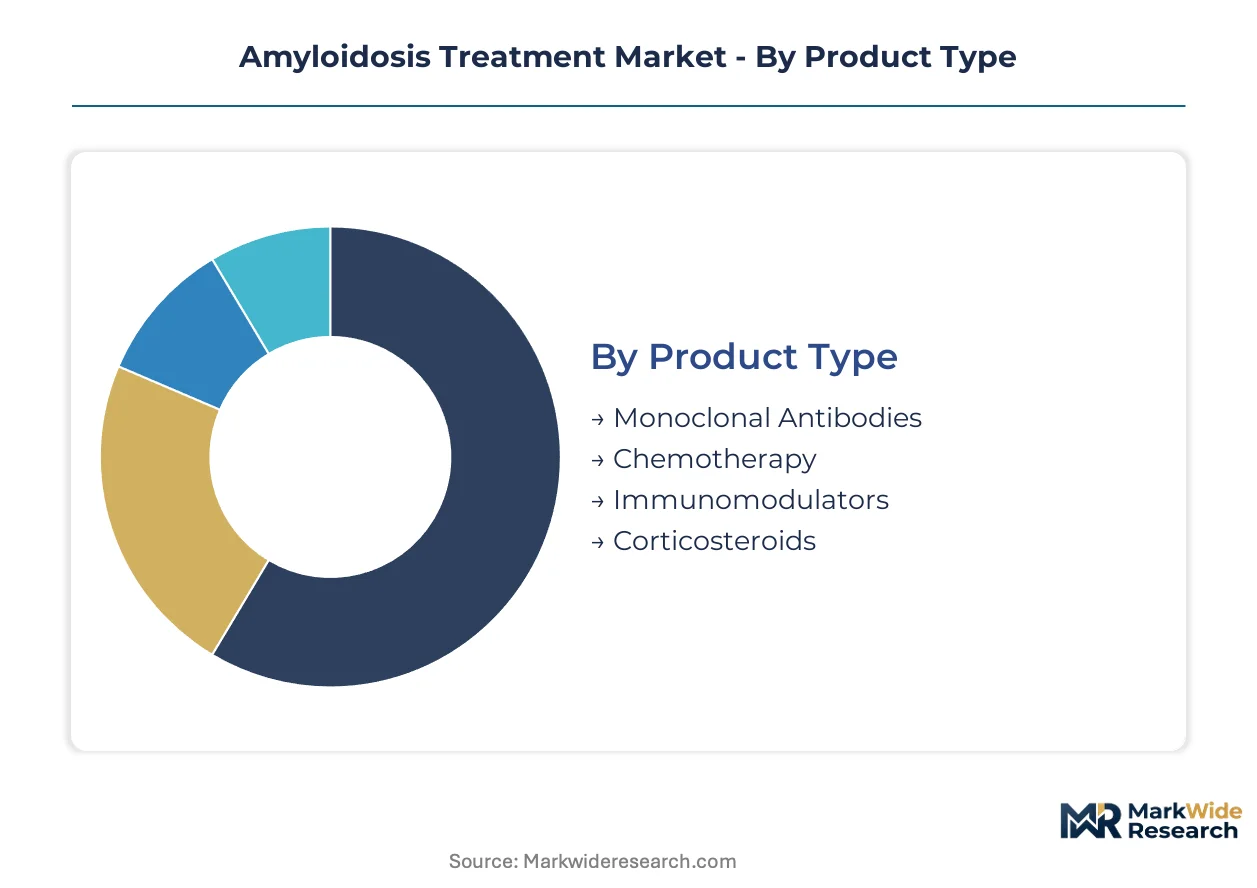
Amyloidosis treatment segmentation reveals divergent service intensity requirements across delivery modes and care settings. Patient acuity, organ involvement patterns, and reimbursement pathways create distinct operational footprints for each segment category.
Product Type:
After-sales service intensity varies sharply across product categories, with monoclonal antibodies requiring cold-chain logistics, patient monitoring programs, and infusion nursing support that chemotherapy and corticosteroid regimens do not demand.
- Monoclonal Antibodies:Engineered immunoglobulins targeting circulating light chains or stabilizing transthyretin tetramers through specific epitope binding. Demand concentrates at academic medical centers in Boston and San Francisco where cardiac amyloidosis programs integrate hematology and cardiology expertise, constrained by electrophysiology-trained biopsy capacity. These therapies command premium positioning through orphan drug exclusivity and breakthrough therapy designations.
- Chemotherapy:Alkylating agents and proteasome inhibitors that suppress clonal plasma cell proliferation in AL amyloidosis. Oncology infusion centers in Germany and France drive volume for melphalan-based protocols, facing pressure from RNA interference alternatives that reduce treatment burden.
- Immunomodulators:Thalidomide and lenalidomide derivatives modulating cytokine signaling in refractory cases.
- Corticosteroids:Dexamethasone-based pulsed regimens for rapid organ response induction.
By volume, chemotherapy leads due to historical protocol penetration. By growth pace, monoclonal antibodies are expanding most quickly as subcutaneous formulations reduce site-of-care dependency.
Delivery Mode:
Margin profiles diverge across administration routes, with subcutaneous formats capturing higher per-dose margins through reduced healthcare utilization while intravenous maintains volume through hospital reimbursement mechanics.
- Intravenous:Hospital-based infusion requiring cardiac telemetry capabilities for TTR-directed therapies. Tertiary centers in the United States and Japan concentrate demand where electrophysiology monitoring infrastructure exists, limited by rural site expansion constraints.
- Subcutaneous:Self-administered or caregiver-assisted injection enabling home-based care. Specialty pharmacy networks in the United Kingdom and Netherlands are expanding cold-chain distribution to support quarterly siRNA dosing, driven by patient advocacy prioritizing reduced infusion center dependency.
- Oral:Small molecule tetramer stabilizers for wild-type ATTR with cardiovascular endpoints.
- Topical:Localized corticosteroid delivery for cutaneous amyloidosis variants.
By volume, intravenous leads through established hospital contracts. By growth pace, subcutaneous formats are climbing the fastest as payers shift toward site-neutral reimbursement.
End User:
Customer concentration patterns reshape procurement dynamics, with integrated delivery networks consolidating purchasing decisions away from individual physician preference toward centralized pharmacy and therapeutics committees.
- Hospitals:Academic medical centers with advanced diagnostic capabilities including cardiac MRI and endomyocardial biopsy expertise. Major clusters in New York, London, and Tokyo generate concentrated treatment volume where multidisciplinary amyloidosis programs exist.
- Specialty Pharmacies:Hub-and-spoke distribution networks managing prior authorization, patient assistance programs, and adherence monitoring. United States-based operators are capturing margin as subcutaneous therapies shift site of care from infusion centers.
- Clinics:Community oncology practices managing stable patients on oral regimens.
- Home Care:Nursing services supporting subcutaneous administration in patient residences.
By volume, hospitals lead through diagnostic gatekeeping function. By growth pace, specialty pharmacies are gaining share fastest as delivery mode migration accelerates.
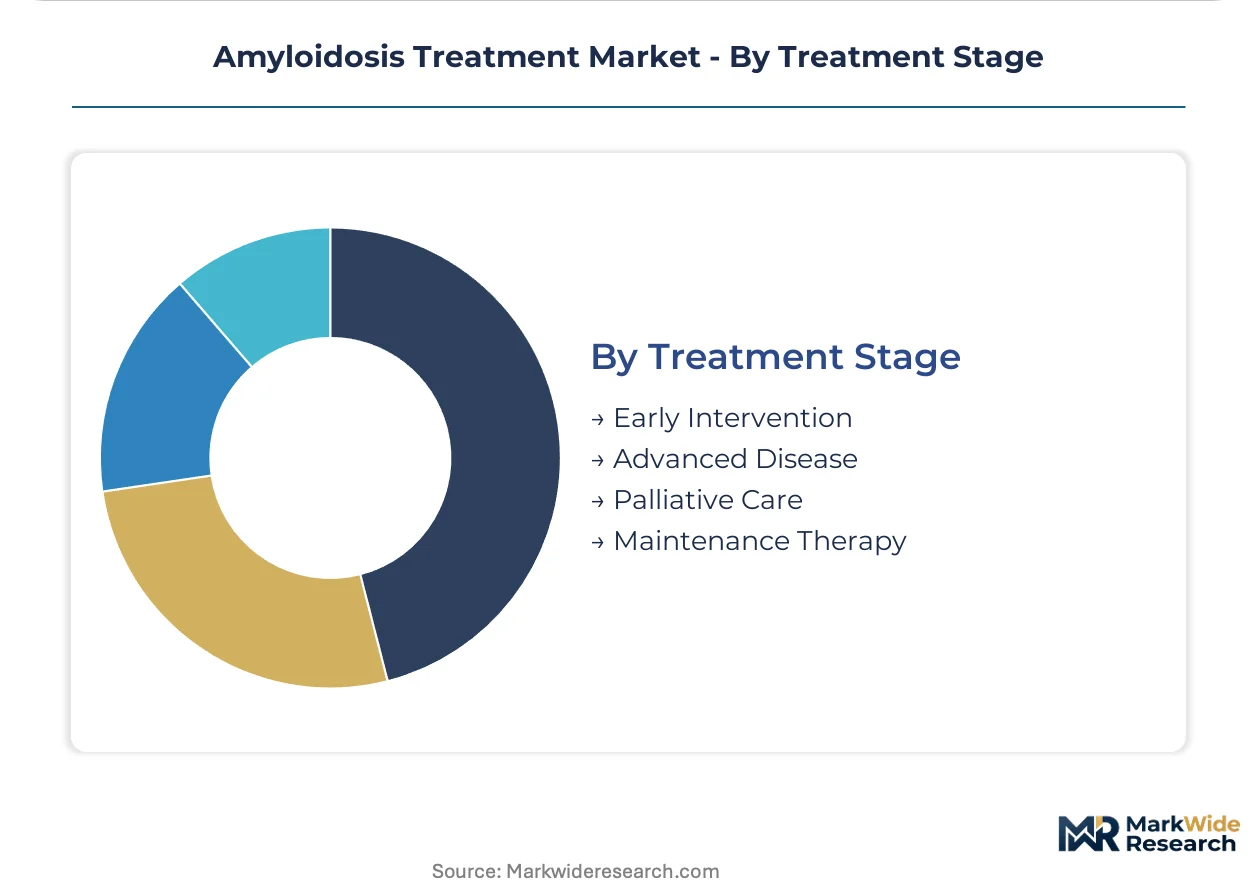
Treatment Stage:
Supply concentration aligns with disease progression, with early intervention commanding R&D investment while maintenance therapy segments deepen as relapse prevention protocols standardize.
- Early Intervention:First-line therapy for treatment-naïve patients with preserved organ function. Enrollment concentrates at centers participating in N-terminal pro-BNP harmonization initiatives, constrained by biomarker validation gaps across reference laboratories.
- Maintenance Therapy:Long-term suppression protocols preventing amyloid deposition recurrence. German and French academic centers are standardizing minimal residual disease monitoring to guide duration decisions, creating durable revenue streams.
- Advanced Disease:Salvage regimens for refractory cases with significant organ involvement.
- Palliative Care:Symptom management for end-stage cardiac or neurological impairment.
By volume, early intervention leads through incident case capture. By growth pace, maintenance therapy is expanding most quickly as survival improvements extend treatment duration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma collection networks and amyloidosis diagnostic expertise concentrate in the United States, Germany, Japan, the United Kingdom, and Switzerland. These five countries generate the majority of clinical trial enrollment and commercial revenue for TTR-directed and AL-directed therapies.
United States
FDA breakthrough therapy designations and orphan drug exclusivity accelerate commercialization timelines for RNA interference assets. The Centers for Medicare & Medicaid Services maintains site-neutral reimbursement policies that favor subcutaneous administration. Boston and San Francisco academic medical centers integrate cardiology-hematology amyloidosis programs, concentrating biopsy expertise and referral volume at fewer than 200 institutions nationwide.
Germany
The Federal Joint Committee (G-BA) applies cost-effectiveness thresholds to quality-adjusted life year calculations that condition reimbursement on demonstrated organ response. Heidelberg and Munich university hospitals standardize minimal residual disease monitoring protocols for maintenance therapy decisions. German plasma collection networks supply immunoglobulin raw material to European manufacturing facilities.
Japan
PMDA Sakigake designation and priority review vouchers compress regulatory review periods for wild-type ATTR therapies targeting the elderly population. Tokyo and Osaka medical centers deploy cardiac MRI and nuclear scintigraphy for non-invasive diagnosis, reducing dependency on endomyocardial biopsy. Japan's aging demographics position the country as an early adopter for cardiovascular endpoint trials.
United Kingdom
NICE single technology appraisals mandate real-world evidence collection through post-authorization studies that tie pricing to organ response rates. London and Cambridge academic centers participate in N-terminal pro-BNP harmonization initiatives to standardize biomarker assays across reference laboratories. National Health Service England consolidates amyloidosis drug purchasing through specialized commissioning frameworks.
Switzerland
Swissmedic expedited review pathways align with EMA parallel scientific advice procedures for rare disease therapies. Basel and Zurich university hospitals maintain international referral networks for hereditary ATTR genetic testing and family screening. Swiss plasma fractionation infrastructure supports immunoglobulin supply chains serving European therapeutic markets.
Amyloidosis Treatment Market Vendor Landscape
RNA interference specialists and large-cap cardiovascular franchises split the market between mechanism-driven innovation and commercial scale. The competitive structure concentrates around technology licensing transactions and subcutaneous formulation races. Two strategic archetypes dominate: platform technology owners with GalNAc delivery capabilities, and integrated biopharma operators with rare disease infrastructure. Competitive moves center on manufacturing capacity expansion and specialty pharmacy channel partnerships.
Within the platform technology tier, Alnylam Pharmaceuticals, Inc. and its GalNAc conjugate system exemplify RNA interference leadership. Pfizer Inc. occupies a position at the scale-driven end, leveraging cardiovascular franchise integration. Johnson & Johnson Services, Inc. anchors the hematology-specialist archetype through hospital channel access. These three companies represent the dominant competitive configurations in transthyretin and light chain amyloidosis segments.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Alnylam Pharmaceuticals, Inc. |
| Johnson & Johnson Services, Inc. |
| Takeda Pharmaceutical Company Limited |
| GSK plc |
| Novartis AG |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche Ltd |
| Amgen Inc. |
| Others |
Supply Flow & Price Mechanics
Plasma-derived API concentration risk determines both pricing tier spreads and supply chain shape in amyloidosis therapeutics. Single-source dependency on US and European plasma collection networks creates vulnerability that widens price differentials between secured-contract and spot-market immunoglobulin supplies.
Pricing Analysis
Orphan drug exclusivity dictates the pricing tier structure across amyloidosis modalities, with breakthrough therapy designation commanding premium positioning against standard-of-care chemotherapy. Three-tier pricing structure across premium, standard, and economy levels separates RNA interference assets from monoclonal antibodies and generic alkylating agents. Cost compression in chemotherapy regimens is intensifying because RNAi alternatives reduce treatment burden and hospital utilization. Academic medical centers show lowest price sensitivity due to consolidated purchasing through integrated delivery networks, while community oncology practices face highest sensitivity to reimbursement mechanics.
Supply Chain Analysis
Export-control restrictions on biologics manufacturing equipment limit capacity expansion in emerging production regions. Plasma collection concentrates in the United States, Germany, and Austria, with fractionation infrastructure anchored in Switzerland and Ireland. Supply chains draw from immunoglobulin raw material, GalNAc conjugate chemistry, and specialized cold-chain packaging. Single-source vulnerability runs through electrophoresis-grade plasma protein separation technology. Distribution runs through specialty pharmacy hub-and-spoke networks with last-mile cold-chain integrity requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RNA interference platform substitution threatens incumbent monoclonal antibody franchises, forcing defensive repositioning around formulation innovation and channel control.
For Market Incumbents: Harden market position through backward integration into plasma collection networks and captive manufacturing of subcutaneous delivery devices. Accelerate cardiac telemetry-enabled infusion site expansion to defend against specialty pharmacy channel capture. Prioritize GalNAc conjugate delivery system licensing to neutralize mechanism-of-action substitution risk from gene silencing competitors. For New Entrants and Emerging Players: Rural and secondary US markets present underpenetrated referral pathways where diagnostic bottlenecks delay treatment initiation. Target Japanese elderly populations for wild-type ATTR cardiovascular endpoint trials, leveraging PMDA Sakigake designation compression. Pursue registry-based trial designs that reduce placebo arm requirements through natural history data partnerships. For Investors and Strategic Acquirers: FDA biomarker qualification pathway reshapes the acquisition landscape by validating surrogate endpoints that accelerate approval timelines. Five-to-ten year viability hinges on organ response rate durability and real-world evidence generation capabilities. Monitor EMA parallel scientific advice engagement depth as an inflection indicator for reimbursement access probability. Prioritize platform technology owners with demonstrated GalNAc chemistry scale-up over asset-dependent developers.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Reduces infusion center dependency and shifts margin capture to specialty pharmacy channels. |
| Plasma Collection Network Expansion | Secures immunoglobulin raw material supply against donor availability fluctuations. |
| Biomarker Harmonization Partnership | Standardizes N-terminal pro-BNP assays across reference laboratories to accelerate trial enrollment. |
| Integrated Delivery Network Contracting | Captures concentrated purchasing decisions through centralized pharmacy and therapeutics committees. |
| Gene Silencing-Small Molecule Combination Trials | Creates mechanistic synergy that could displace sequential monotherapy protocols. |
Methodological Framework
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation anchored market size estimation.
Scenario-bracketing framed analytical projections across the analysis window, with segmentation dimensions spanning treatment line, administration route, patient population, and regional regulatory cluster. CAGRs derived from epidemiological incidence modeling, pricing elasticity assumptions, and therapy penetration curves. Forecast inputs incorporated plasma collection volume trends and specialty pharmacy channel share migration.
Practitioners should monitor biomarker qualification pathway progress and real-world evidence mandate evolution for early signals of forecast deviation. Forecasts reflect assumptions around orphan drug exclusivity durability and site-neutral reimbursement policy stability. Material shifts in FDA accelerated approval stringency or plasma supply chain disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Global Hyperhidrosis Treatment Market
Medical Treatment
Dementia Treatment Market
Medical Treatment
Dengue Fever Treatment Market
Medical Treatment
Tissue Repair Technologies Market
Medical Treatment
Purpura Treatment Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Myotonic Dystrophy Treatment Market
Medical Treatment
Cysticercosis (Taeniasis) Treatment Market
Medical Treatment
Allergy Treatment Market
Medical Treatment
Uterine Fibroid Treatment Drugs Market
Medical Treatment
Urea Cycle Disorders Treatment Market
Medical Treatment
Middle Ear Infection Treatment Market
Medical Treatment
Achalasia Treatment Market
Medical Treatment
Lysosomal Disease Treatment Market
Medical Treatment
Lyme Disease Treatment Market
Medical Treatment
Merkel Cell Carcinoma (MCC) Treatment Market