
 Global Metastatic Melanoma Drugs Market | 2026-2036
Global Metastatic Melanoma Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metastatic Melanoma Drugs Market Foresight
Aftermarket biomarker testing revenue is narrowing as pharmaceutical manufacturers bundle companion diagnostics with front-line therapy contracts. Bristol-Myers Squibb Company leverages its PD-1 franchise to dominate combination therapy development. Merck & Co. Inc. sustains clinical trial investment across acral and mucosal melanoma subtypes. Novartis AG anchors European market access through centralized EMA pricing negotiations.
Metastatic melanoma drugs comprise systemic therapeutic agents targeting unresectable Stage III or Stage IV melanoma, including monoclonal antibodies, small-molecule kinase inhibitors, and cytotoxic agents formulated for intravenous or oral delivery. These agents function by blocking immune checkpoints, interrupting MAPK pathway signaling, or directly inducing tumor cell apoptosis in BRAF-mutant and wild-type populations. Immune checkpoint inhibitors command the largest margin pool as first-line standards shift toward nivolumab-relaglimab combinations. BRAF and MEK inhibitor pairing captures residual demand in mutation-positive patients who progress on or contraindicate immunotherapy. Intravenous infusion maintains infrastructure dominance, though subcutaneous injection formats gain traction in outpatient cancer treatment centers seeking reduced chair time.
FDA breakthrough therapy designation and EMA conditional marketing authorization compress regulatory review timelines, reshaping competitive launch sequencing. WHO essential medicines criteria and national health technology assessments in Germany and Japan determine reimbursement tiers and volume access. Stakeholders must monitor evolving PD-L1 expression thresholds and ctDNA response criteria that redefine label expansions and payer contracts.
Market Dynamics
Checkpoint inhibitor combination protocols are compressing first-line treatment windows and redrawing competitive positioning across oncology networks. FDA breakthrough therapy designations and EMA conditional marketing authorizations accelerate pipeline velocity, forcing incumbents to defend label expansions against novel bispecific constructs.
Growth Catalysts
- Accelerated Approval Pathways:FDA breakthrough therapy designation compresses Phase II-to-launch timelines for novel checkpoint inhibitors. EMA conditional marketing authorization enables European access while confirmatory trials complete.
- Biomarker-Guided Patient Stratification:ctDNA monitoring and PD-L1 expression thresholds refine responder identification. Oncology clinics deploy liquid biopsy protocols to sequence combination therapies.
- Japan:PMDA sakigake designation fast-tracks innovative immunotherapies. METI reimbursement frameworks favor premium biologics in tertiary cancer centers.
Market Restraints
- Platinum-Based Manufacturing Inputs:Supply concentration for monoclonal antibody production chemicals in South Korea creates input cost volatility.
- Primary Resistance Mechanisms:Intrinsic non-response to PD-1 blockade limits addressable population in wild-type melanoma subtypes.
- IRB and Ethics Review Complexity:Multi-site oncology trial activation delays patient enrollment across European academic medical centers.
Strategic Opportunities
- Brain Metastasis Indications:Underpenetrated CNS-penetrant therapy development addresses unmet need in leptomeningeal disease.
- Subcutaneous Formulation Conversion:Outpatient cancer centers seek reduced infusion chair time through self-administered injection formats.
- India:CDSCO streamlined approval for orphan oncology indications opens access to mutation-positive patient pools.
Industry Challenges
- Immuno-oncology Talent Scarcity:Clinical pharmacologists with bispecific antibody experience command premium compensation across contract research organizations.
- Companion Diagnostic Co-development:Synchronized FDA validation of PD-L1 assays with drug approval creates timeline misalignment risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metastatic Melanoma Drugs Market |
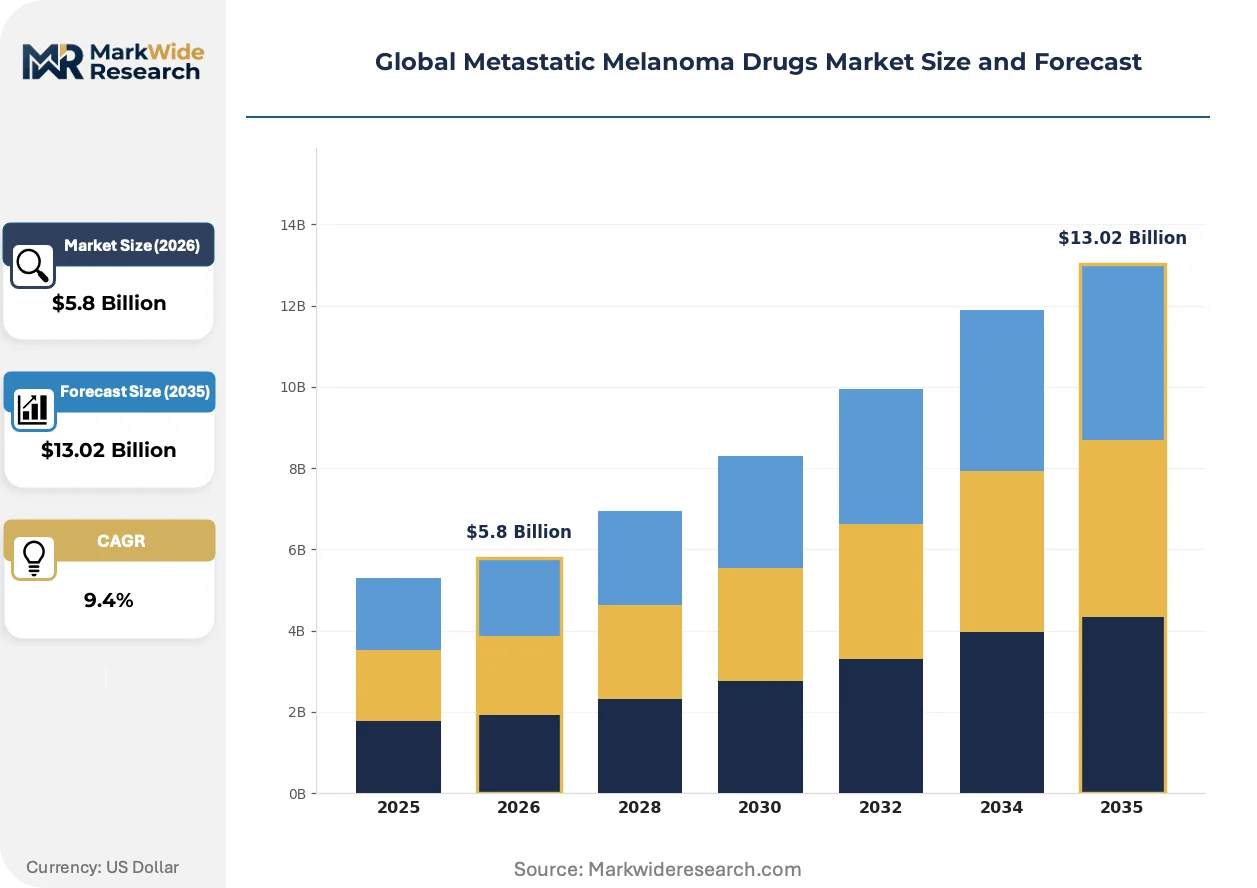
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $13.02 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Immune Checkpoint Inhibitors, BRAF Inhibitors, MEK Inhibitors, Cytotoxic Chemotherapy Therapy Area: Cutaneous Melanoma, Acral Melanoma, Mucosal Melanoma, Ocular Melanoma End User: Oncology Clinics, Specialty Hospitals, Research Institutes, Cancer Treatment Centers Delivery Mode: Oral Administration, Intravenous Infusion, Subcutaneous Injection, Topical Application |
| Companies Covered | Bristol-Myers Squibb Company, Merck & Co. Inc., Novartis AG, F. Hoffmann-La Roche AG, Pfizer Inc., AstraZeneca PLC, Amgen Inc., Regeneron Pharmaceuticals Inc., Exelixis Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metastatic Melanoma Drugs Market Shifts & Advancements
Real-world evidence generation and decentralized trial execution are compressing traditional clinical development paradigms. Digital biomarker integration and adaptive protocol designs enable faster go/no-go decisions.
Liquid biopsy platforms are digitizing treatment response monitoring through ctDNA quantification. Community oncology practices adopt point-of-care sequencing to guide second-line switches. This capability is digitizing the interval between progression detection and protocol modification.
EMA's new oncology trial guidance mandates diversity quotas and decentralized participation. Pharmaceutical sponsors restructure Phase III designs to include satellite sites in Poland and Spain. The policy is compressing patient recruitment timelines while elevating data management complexity.
Hospital purchasing consortia in Germany are consolidating immunotherapy procurement through centralized tenders. University hospitals negotiate multi-year checkpoint inhibitor contracts with outcome-linked rebates. This concentration is visible across the Nordrhein-Westfalen and Bavaria regional hospital networks.
Global Metastatic Melanoma Drugs Market Segmentation
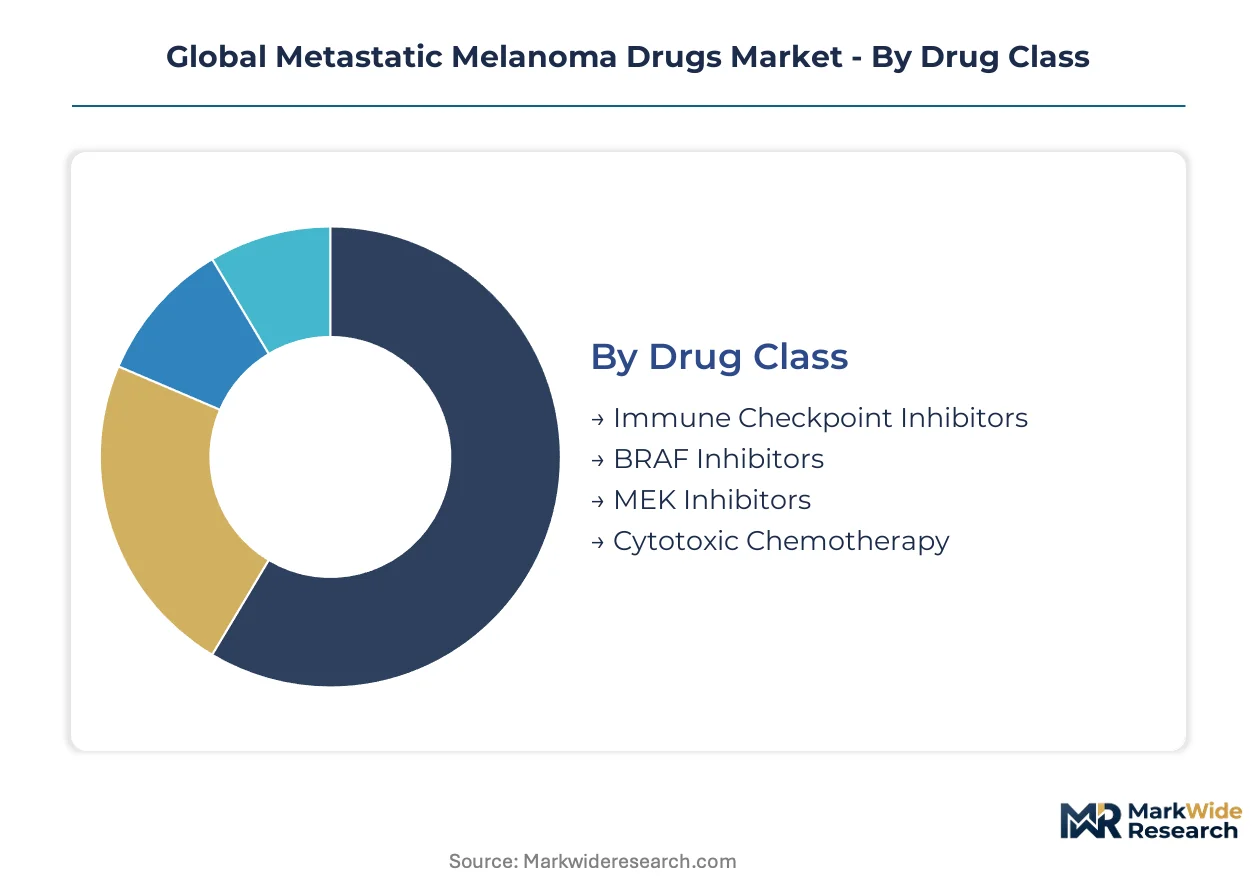
Segmentation in metastatic melanoma therapeutics reveals how treatment protocols stratify across mutation status, anatomical presentation, and care delivery infrastructure. Drug class selection hinges on BRAF mutation testing results, while therapy area distinctions dictate regulatory trial endpoints and reimbursement coding.
Drug Class:
Use-case spectrum spans front-line immunotherapy through salvage chemotherapy, with each class occupying distinct positions in sequencing algorithms and margin structures.
- Immune Checkpoint Inhibitors:Monoclonal antibodies targeting PD-1, PD-L1, and CTLA-4 receptors activate anti-tumor immunity in both wild-type and mutation-positive populations. Demand concentrates in United States oncology networks where CMS reimbursement favors combination nivolumab-ipilimumab protocols despite toxicity monitoring requirements.
- BRAF Inhibitors:Small-molecule kinase inhibitors interrupt MAPK signaling in V600E-mutation-positive disease, delivering rapid radiographic responses. German university hospitals prioritize vemurafenib-dabrafenib sequencing for symptomatic patients requiring disease control ahead of immunotherapy initiation.
- MEK Inhibitors:Downstream pathway blockers paired with BRAF inhibitors delay resistance emergence in combination protocols.
- Cytotoxic Chemotherapy:Alkylating agents and taxanes reserved for refractory cases after checkpoint and targeted therapy failure.
The dominant share belongs to Immune Checkpoint Inhibitors, while BRAF Inhibitors is closing the gap fastest through mutation-testing expansion in community oncology settings.
Therapy Area:
Margin profiles diverge sharply across anatomical subtypes, with rare variants commanding orphan pricing premiums and distinct clinical trial infrastructure.
- Cutaneous Melanoma:Sun-exposure-related disease represents the trial-ready population powering FDA breakthrough designations and label expansions. Japanese tertiary cancer centers drive volume through PMDA sakigake fast-track access for novel PD-1 combinations in this segment.
- Acral Melanoma:Palmoplantar and subungual presentations predominate in Asian and African-ancestry populations with distinct genomic drivers. CDSCO streamlined approvals in India target this subtype where BRAF mutation rates diverge from cutaneous benchmarks.
- Mucosal Melanoma:Anogenital and head-neck primaries carry poor immunotherapy response rates, creating unmet need for novel mechanisms.
- Ocular Melanoma:Uveal primaries metastasize hematogenously to liver with limited checkpoint inhibitor efficacy, driving specialized interventional oncology demand.
Cutaneous Melanoma anchors current revenue, though Acral Melanoma is expanding most quickly through Asia-Pacific trial enrollment and mutation-guided protocol adoption.
End User:
Procurement authority and infusion capacity determine site-level drug selection, with hospital networks consolidating purchasing through outcome-linked contracts.
- Oncology Clinics:Ambulatory infusion centers handle the majority of checkpoint inhibitor administration, capturing patients through community-based medical oncology referrals. Chair-time optimization and prior authorization staffing differentiate competitive positioning in United States metropolitan markets.
- Specialty Hospitals:Comprehensive cancer centers manage complex cases requiring multidisciplinary tumor boards and clinical trial access. German Nordrhein-Westfalen regional networks centralize immunotherapy procurement through university hospital consortia.
- Research Institutes:Academic medical centers host Phase I-II investigator-initiated studies and correlative science programs.
- Cancer Treatment Centers:Dedicated oncology facilities balance volume efficiency with subspecialty access for rare melanoma subtypes.
Oncology Clinics hold the dominant share, while Specialty Hospitals are gaining share fastest through centralized tender consolidation and biosimilar substitution protocols.
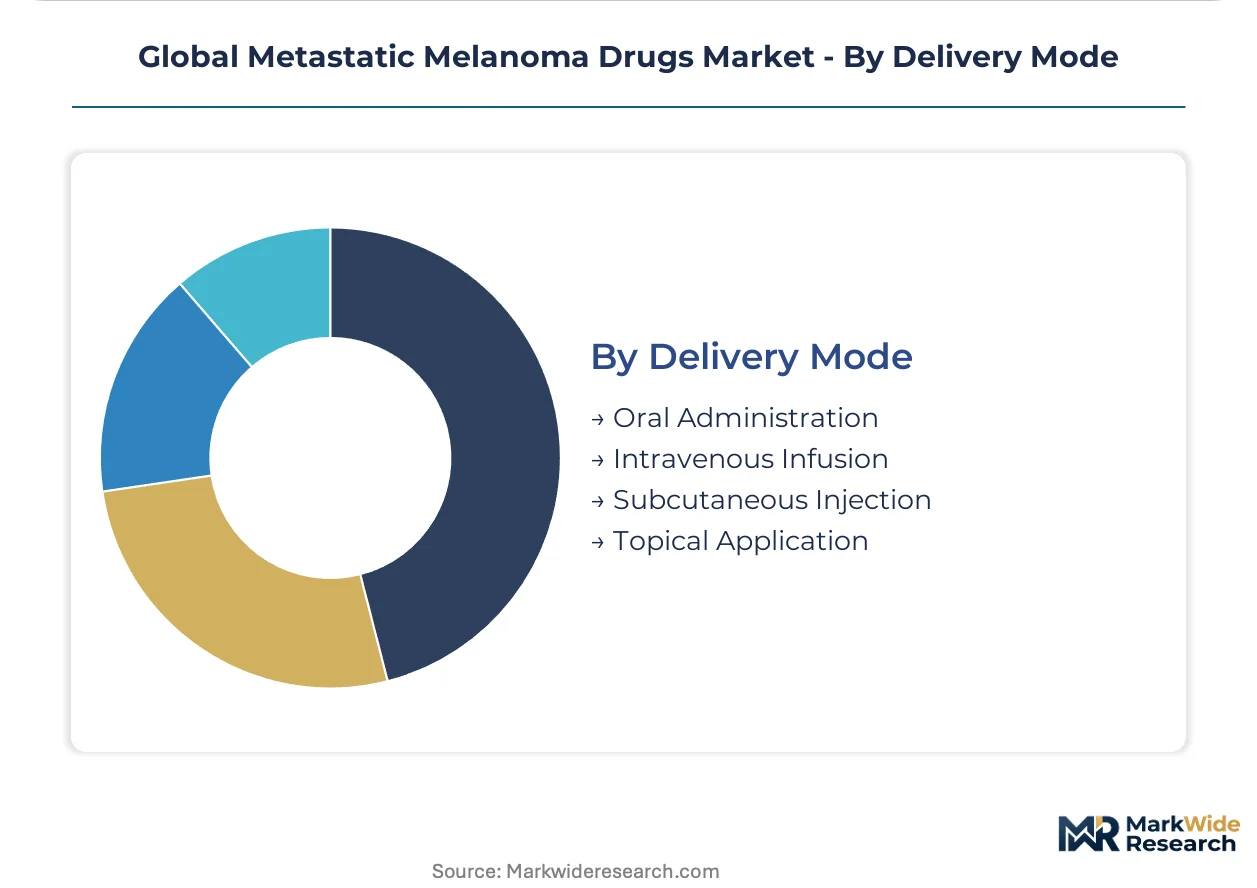
Delivery Mode:
Administration format shapes site-of-care economics, with self-administration options disrupting traditional infusion center revenue models.
- Intravenous Infusion:Established infrastructure for checkpoint inhibitors maintains infrastructure dominance despite chair-time costs. United States outpatient cancer centers defend this format through bundled payment structures capturing laboratory and pharmacy services.
- Subcutaneous Injection:Self-administered formulations reduce healthcare utilization while preserving efficacy in PD-1 maintenance settings. Japanese home healthcare nursing networks facilitate adoption in rural prefectures distant from infusion centers.
- Oral Administration:BRAF and MEK inhibitor tablets enable patient-controlled dosing with pharmacy benefit manager formulary placement determining access.
- Topical Application:Limited to superficial cutaneous metastases and palliative lesion-directed therapy in select clinical scenarios.
Intravenous Infusion retains the dominant share, though Subcutaneous Injection is climbing the fastest as biosimilar developers prioritize patient convenience differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across oncology reimbursement systems. United States buyers absorb premium biologic pricing through Medicare Part B pass-through mechanisms. German statutory health insurance funds extract outcome-linked rebates that compress net realized prices.
United States
Community oncology networks drive volume through prior authorization efficiency. FDA breakthrough therapy designation accelerates novel checkpoint inhibitor launches. Memorial Sloan Kettering Cancer Center in New York anchors investigator-initiated combination trials.
Germany
University hospital consortia in Nordrhein-Westfalen centralize immunotherapy procurement through multi-year tenders. EMA conditional marketing authorization enables early access while confirmatory trials complete. Heidelberg University Hospital manages correlative biomarker programs for PD-1 resistance mechanisms.
Japan
PMDA sakigake designation fast-tracks innovative immunotherapies through priority review. METI reimbursement frameworks favor premium biologics in designated cancer care hospitals. National Cancer Center Hospital in Tokyo coordinates Phase I-II trials for acral melanoma subtypes.
India
CDSCO streamlined approval pathways target mutation-positive patient pools in tertiary care centers. National cancer grid institutions in Maharashtra and Tamil Nadu expand molecular testing infrastructure. Tata Memorial Hospital in Mumbai anchors real-world evidence generation for BRAF inhibitor sequencing.
United Kingdom
NICE technology appraisals impose cost-effectiveness thresholds that filter high-price immunotherapies. Cancer Drugs Fund provides conditional funding for promising agents awaiting final guidance. Royal Marsden NHS Foundation Trust in London hosts adaptive trial platforms for novel bispecific constructs.
Global Metastatic Melanoma Drugs Market Competitive Landscape
Large-cap pharmaceutical conglomerates and mid-sized oncology specialists split the market across development-stage risk profiles. Incumbents defend positions through label expansion litigation and biosimilar delay tactics. Two archetypes dominate: checkpoint inhibitor franchise holders and targeted therapy combination developers. Competitive intensity concentrates on M&A for clinical-stage assets and co-development partnerships for companion diagnostics.
Within the franchise-holder tier, Bristol-Myers Squibb Company and Merck & Co. Inc. occupy positions defined by PD-1 platform scale. Novartis AG represents the European-access archetype through centralized EMA pricing negotiation capabilities. These three entities anchor distinct strategic postures without exhausting the competitive spectrum.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Merck & Co. Inc. |
| Novartis AG |
| F. Hoffmann-La Roche AG |
| Pfizer Inc. |
| AstraZeneca PLC |
| Amgen Inc. |
| Regeneron Pharmaceuticals Inc. |
| Exelixis Inc. |
| Others |
Supply & Pricing Matrix
Platinum-based manufacturing inputs concentrated in South Korean chemical suppliers anchor cost volatility that cascades through monoclonal antibody production economics. This upstream concentration funnels margin pressure toward finished-dose manufacturers while concentrating pricing power with contract development organizations possessing captive metal sourcing relationships.
Pricing Analysis
Companion diagnostic bundling with front-line therapy contracts is reshaping lifetime value capture for pharmaceutical manufacturers. Pricing stratifies across premium biologics in United States Medicare Part B settings, standard-tier checkpoint inhibitors in German statutory insurance frameworks, and economy-positioned biosimilars in Indian tertiary care centers. Cost compression in European markets stems from outcome-linked rebate negotiations that compress net realized prices. Hospital purchasing consortia in Germany exhibit highest price sensitivity due to centralized tender consolidation, while United States oncology networks absorb premium pricing through pass-through reimbursement mechanisms.
Supply Chain Analysis
Upstream biologics manufacturing feedstock draws from South Korea, Germany, and the United States for platinum-group catalysts and specialized cell culture media. Monoclonal antibody production rests on Chinese-sourced recombinant proteins, Singapore-based sterile fill-finish capacity, and Swiss contract manufacturing for high-potency cytotoxics. Single-source vulnerability concentrates in South Korean platinum salt suppliers where geopolitical tension threatens input continuity. Distribution runs through cold-chain logistics networks anchored by United States specialty pharmacy distributors, European hospital consortia direct purchasing, and Japanese regional medical cooperative depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FDA breakthrough therapy designation and EMA conditional marketing authorization creates substantial switching costs for oncology clinics locked into established infusion protocols.
For Market Incumbents: Entrench market position through backward integration into companion diagnostic co-development capabilities that synchronize assay validation with drug approval timelines. Expand manufacturing footprint into Singapore and Switzerland to diversify platinum-input exposure while securing capacity for subcutaneous formulation launches that reduce site-of-care competition from infusion centers.
For New Entrants and Emerging Players: India CDSCO streamlined approval pathways for orphan oncology indications offer the most penetrable entry point for mutation-positive targeted therapy developers. Focus initial commercialization on acral melanoma subtypes where BRAF mutation rates diverge from cutaneous benchmarks, leveraging real-world evidence generation partnerships with Tata Memorial Hospital to accelerate label expansion.
For Investors and Strategic Acquirers: Capital is best deployed toward clinical-stage bispecific antibody developers possessing PD-1 resistance mechanism intellectual property. Long-term viability hinges on CNS-penetrant therapy pipelines addressing leptomeningeal disease where checkpoint inhibitor efficacy remains limited. Monitor ctDNA response criteria adoption by United States payers as the inflection signal for reimbursement contract restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Decentralized trial execution in Poland and Spain compresses patient recruitment timelines for EMA submissions. |
| Regulatory Approval Pathway | PMDA sakigake designation in Japan accelerates priority review for novel immunotherapy combinations in acral subtypes. |
| Licensing Agreement | Companion diagnostic co-development partnerships with liquid biopsy platforms synchronize FDA validation timelines. |
| Manufacturing Scale-Up | Singapore sterile fill-finish capacity expansion reduces dependence on South Korean platinum-input supply chains. |
| Pipeline Diversification | Brain metastasis indication development addresses underpenetrated CNS-penetrant therapy demand in leptomeningeal disease. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchors the qualitative findings against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-flow modeling triangulates with top-down pharmaceutical revenue aggregation across the analysis window.
Calibration against historical approval timelines and launch uptake curves in comparable oncology indications informs the analytical framework. Segmentation dimensions span drug class, therapy area, end user, and delivery mode with regional regulatory cluster overlays. CAGRs derive from patent expiry modeling, biosimilar entry assumptions, and mutation-testing penetration curves. Forecast inputs incorporate checkpoint inhibitor combination protocol adoption rates and subcutaneous formulation conversion timelines.
Practitioners should monitor PD-L1 expression threshold revisions and ctDNA response criteria adoption for early signals of label expansion and payer contract restructuring. Forecasts reflect assumptions regarding accelerated approval pathway utilization and confirmatory trial completion rates. Cross-checking against CMS Medicare Part B spending data and German G-BA benefit assessment outcomes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Global Hurthle Cell Carcinoma Treatment Market
Oncology
Asia-Pacific Cancer Therapy Market
Oncology
Osteosarcoma Market
Oncology
Head and Neck Cancer Market
Oncology
Metastatic Cancer Drug Market
Oncology
Small Cell Lung Cancer (SCLC) Treatment Market
Oncology
Musculoskeletal Oncology Therapeutics Market
Oncology
Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Europe Proton Therapy Market
Oncology
Metastases Spinal Tumor Market
Oncology
Paraneoplastic Syndromes Market
Oncology
Pancreatic Cancer Market
Oncology
Small Cell Lung Cancer (SCLC) Therapeutics Market
Oncology
Kinase Inhibitors for Cancer Treatment Market
Oncology
Germany Radiotherapy Market
Oncology
Radiotherapy Market