
 Goodpasture Syndrome Treatment Market | 2026-2036
Goodpasture Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Goodpasture Syndrome Treatment Market Foresight
EMA's updated MDR requirements for immunosuppressive biologics is repositioning the cost-of-entry calculus for European market participants. Roche leverages its diagnostic-therapeutic integration to sustain leadership in autoimmune rare disease portfolios. CSL Limited anchors its position through captive plasma collection networks that secure raw material supply. Grifols differentiates via vertical control over fractionation capacity spanning multiple continents.
Goodpasture syndrome treatment encompasses therapeutic interventions targeting anti-glomerular basement membrane antibody-mediated disease, combining high-dose corticosteroid pulse therapy with plasmapheresis to remove circulating autoantibodies and halt alveolar-capillary inflammation. The primary purpose centers on preserving renal function and preventing irreversible pulmonary hemorrhage in acute presentations. Plasma exchange commands the deepest margin pools due to supply-constrained albumin and immunoglobulin feedstock economics, while rituximab segments expand fastest as B-cell depletion protocols gain protocol adoption in refractory cases. Intravenous administration dominates hospital revenue capture, though subcutaneous formulations are gaining traction in outpatient specialty clinic settings seeking reduced infusion center burden.
FDA oversight of plasma-derived products, EMA's MDR framework for immunosuppressive devices, and Japan's PMDA orphan drug incentives collectively shape product standards and market access pathways across major jurisdictions. Regulatory stringency on viral inactivation and supply chain traceability directly determines which manufacturers can sustain commercial participation. Stakeholders must monitor evolving biosimilar entry timelines for rituximab and plasma exchange capacity expansion decisions in concentrated supplier geographies.
Market Dynamics
Plasma fractionation capacity concentration in the United States, Germany, and Japan is reshaping treatment availability and pricing power for immunoglobulin-based therapies across the Goodpasture syndrome landscape.
Growth Catalysts
- Japan's PMDA orphan drug incentives:Accelerated review pathways and tax credits for rare autoimmune indications are drawing development investment toward refractory case protocols.
- B-cell depletion technology maturation:Rituximab biosimilar entry timelines are compressing, expanding protocol adoption in tertiary nephrology centers previously constrained by originator pricing.
- Hospital-based nephrology expansion:Tertiary centers in Germany and the United States are consolidating autoimmune renal services, creating dedicated plasmapheresis units with standardized immunosuppressive protocols.
Market Restraints
- Albumin and immunoglobulin feedstock scarcity:Plasma collection economics limit fractionation output, constraining supply expansion despite protocol demand.
- EMA MDR compliance burden:Updated device regulations for immunosuppressive delivery systems are extending certification timelines and elevating quality management costs for European manufacturers.
- Substitution ceiling in acute presentations:High-dose corticosteroid pulse therapy remains non-displaceable for initial alveolar-capillary stabilization, limiting biologic penetration in emergency settings.
Strategic Opportunities
- Outpatient specialty clinic channel development:Subcutaneous formulation adoption is enabling treatment migration from hospital infusion centers to ambulatory settings in the United States.
- Diagnostic-therapeutic integration:Anti-GBM antibody quantification platforms paired with treatment response monitoring are creating protocol personalization revenue streams.
- Captive plasma collection network expansion:Vertically integrated supply control over raw material sourcing is insulating margin pools from spot market volatility.
Industry Challenges
- Viral inactivation validation complexity:FDA and EMA stringency on pathogen reduction documentation is extending batch release timelines for plasma-derived therapies.
- Specialized nephrology-pulmonology coordination:Cross-disciplinary protocol standardization requires investment in integrated care pathways that many hospital systems lack operational maturity to execute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Goodpasture Syndrome Treatment Market |
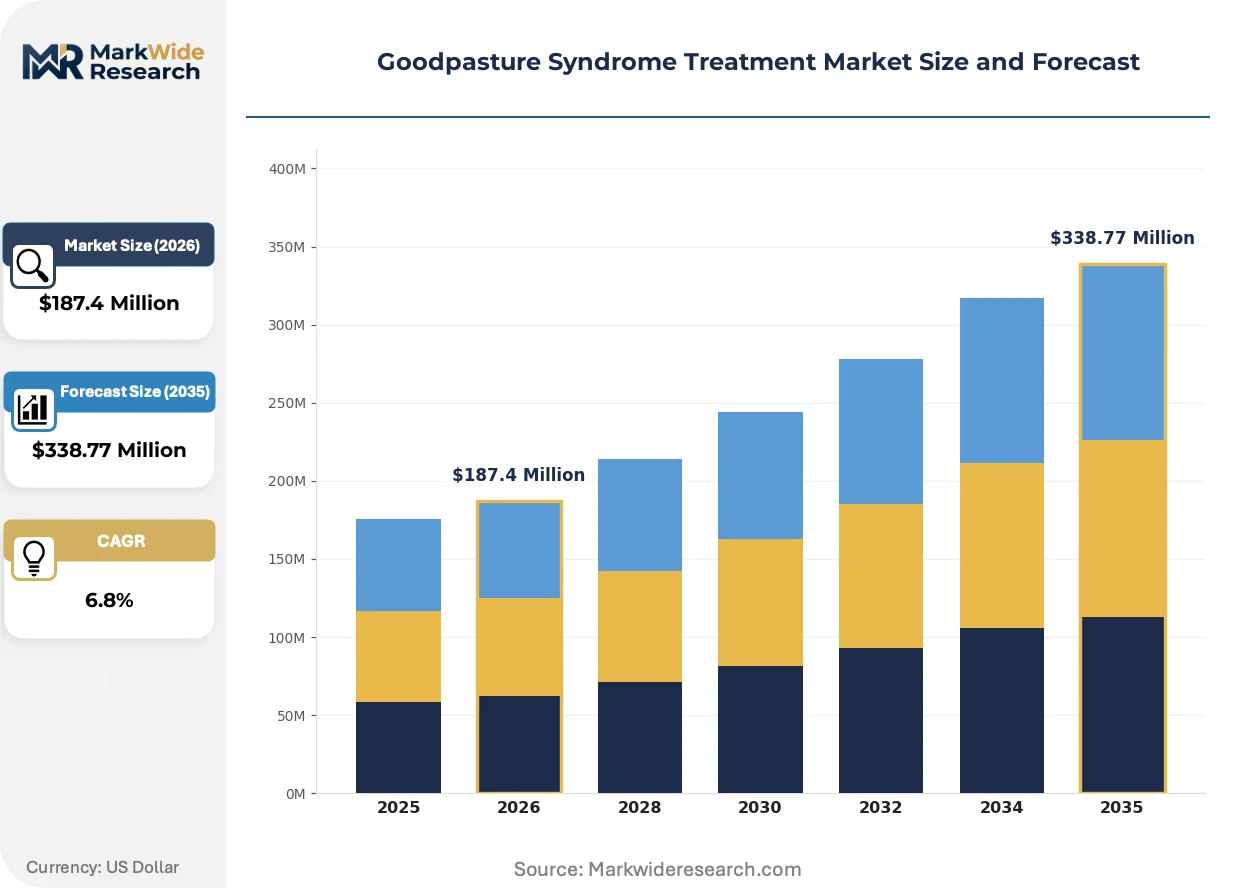
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Corticosteroids, Plasma Exchange, Immunosuppressants, Rituximab Administration Route: Intravenous, Oral, Subcutaneous, Intramuscular End User: Hospitals, Specialty Clinics, Outpatient Centers, Research Institutions Patient Demographics: Adults, Elderly, Pediatric, Gender-Specific |
| Companies Covered | Roche, Novartis, Amneal Pharmaceuticals, CSL Limited, Merck & Co., Bristol-Myers Squibb, Pfizer, Grifols, Sandoz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Goodpasture Syndrome Treatment Market Shifts & Advancements
Autoimmune rare disease treatment is converging toward precision protocol design, with biomarker-guided dosing and channel migration reshaping how therapies reach acute and maintenance patient populations.
B-cell depletion biologics are expanding into maintenance-phase protocols following acute plasmapheresis stabilization, with tertiary nephrology departments in Germany and Japan adopting rituximab consolidation cycles to reduce relapse incidence. Hospital pharmacy committees are accelerating biosimilar formulary placement as originator patents expire, compressing per-protocol costs while expanding eligible patient pools. This expansion is displacing prolonged high-dose corticosteroid exposure as the default maintenance strategy.
EMA's updated MDR framework for immunosuppressive device classification is forcing European manufacturers to revalidate delivery system biocompatibility and software components under stricter clinical evidence requirements. Fractionators with existing notified body relationships are securing CE mark continuity faster than mid-cap entrants, consolidating device supply relationships around established plasma therapy suppliers. German and French hospital procurement offices are now requiring MDR compliance documentation in tender specifications.
Consolidated buyer power among integrated delivery networks in the United States is unbundling infusion services from product procurement, with specialty pharmacy benefit managers negotiating direct rituximab distribution separate from hospital markup structures. Academic medical centers in Boston and Houston are piloting risk-based contracting for refractory case bundles, transferring outcome accountability from payer to provider. This behavioral shift is most pronounced in markets with concentrated nephrology group practice ownership.
Goodpasture Syndrome Treatment Market Segmentation
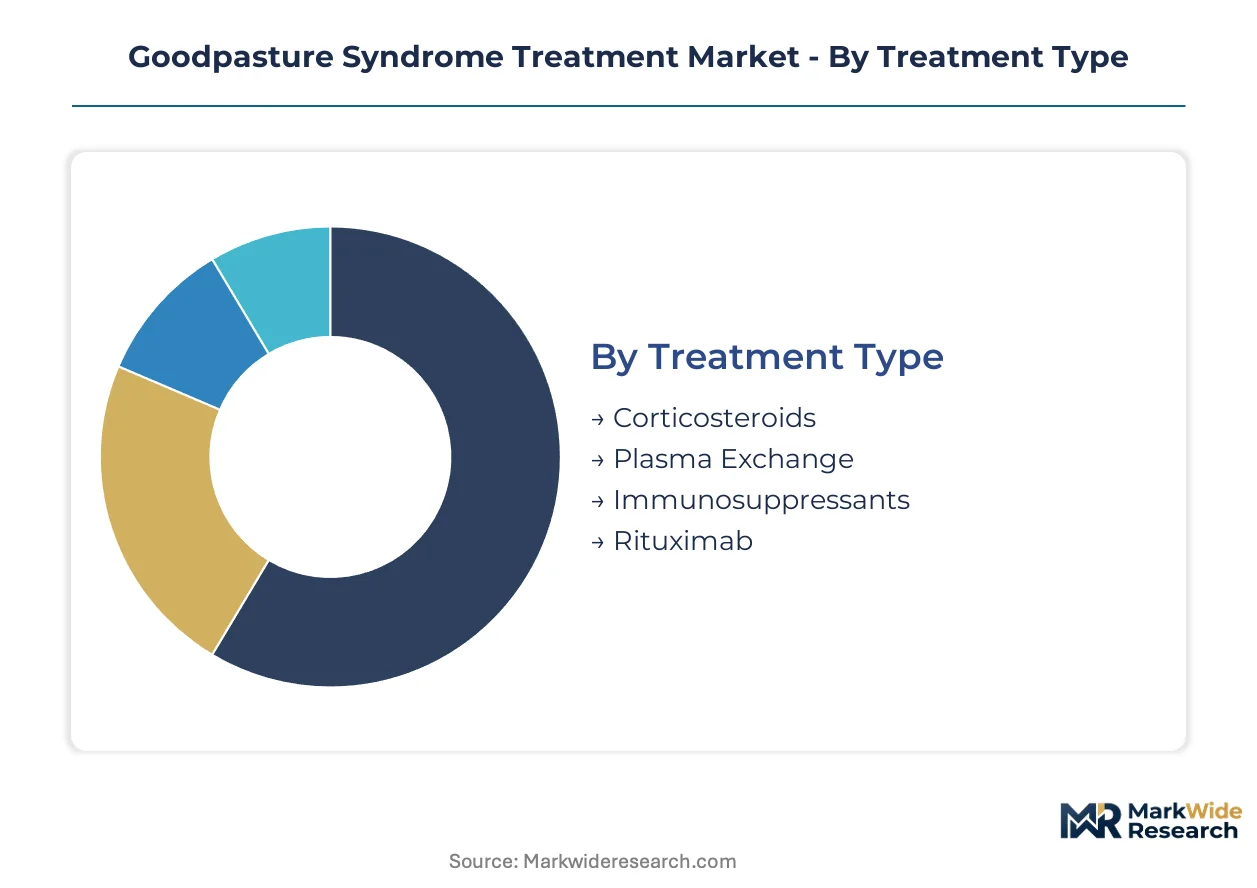
Goodpasture syndrome treatment protocols vary sharply by disease severity, care setting economics, and patient immunological profile. Segmentation reveals where pharmaceutical margins concentrate versus where procedural services capture value across the acute-to-maintenance care continuum.
Treatment Type:
Hospital pharmacy committees weight cost-effectiveness against relapse risk when selecting first-line versus salvage protocols for anti-GBM antibody-positive patients.
- Corticosteroids:High-dose methylprednisolone pulse therapy remains the emergency standard for alveolar-capillary stabilization. Demand concentrates in United States and German tertiary centers where rapid pulmonary hemorrhage control dictates protocol selection, though prolonged exposure drives bone density and infection complications that limit maintenance-phase utility.
- Plasma Exchange:Therapeutic apheresis removes circulating anti-GBM antibodies and complement factors through centrifugal or membrane-based separation. United States hospital systems with captive collection networks secure preferential immunoglobulin and albumin feedstock allocation, insulating margin pools from spot market volatility that constrains European availability.
- Immunosuppressants:Cyclophosphamide and mycophenolate mofetil provide steroid-sparing maintenance through T-cell suppression pathways.
- Rituximab:Anti-CD20 monoclonal antibody depletes B-cell precursors to halt autoantibody production in refractory or relapsing cases.
Plasma Exchange leads volumes today; Rituximab is gaining share fastest.
Administration Route:
Route selection hinges on care setting infrastructure, patient vascular access, and reimbursement mechanics for facility-based versus ambulatory delivery.
- Intravenous:Hospital infusion centers dominate acute-phase delivery for corticosteroid pulses, plasma exchange, and rituximab loading doses. German nephrology departments maintain dedicated vascular access teams that reduce catheter-related bloodstream infections below benchmark rates.
- Subcutaneous:Maintenance immunoglobulin and select biologic formulations migrate to outpatient specialty clinics seeking reduced infusion center burden. United States integrated delivery networks in Texas and Massachusetts pilot home-based subcutaneous protocols with remote monitoring to unbundle site-of-service economics.
- Oral:Maintenance immunosuppressants and tapering corticosteroid regimens permit patient self-administration post-discharge.
- Intramuscular:Depot formulations see limited application in Goodpasture-specific protocols due to pharmacokinetic unpredictability in acute renal failure states.
Intravenous administration anchors revenue capture; subcutaneous delivery is expanding most quickly into maintenance populations.
End User:
Facility type determines protocol complexity, reimbursement tier, and cross-disciplinary coordination requirements for simultaneous renal and pulmonary management.
- Hospitals:Tertiary academic medical centers concentrate plasmapheresis capacity, intensive care for pulmonary hemorrhage, and joint nephrology-pulmonology staffing. Japanese designated cancer hospitals with expanded autoimmune mandates are adding dedicated anti-GBM rapid response protocols.
- Specialty Clinics:Nephrology-focused ambulatory centers manage maintenance-phase monitoring and subcutaneous biologic administration. United States specialty pharmacy benefit managers now contract directly with these sites to bypass hospital markup structures.
- Outpatient Centers:Standalone infusion facilities compete on throughput and scheduling flexibility for stable maintenance patients.
- Research Institutions:Academic centers with NIH or MHLW funding drive biomarker-guided protocol trials and refractory case registries.
Hospitals dominate acute-phase value capture; Specialty Clinics show the steepest expansion trajectory in maintenance care migration.
Patient Demographics:
Age and physiological reserve shape treatment intensity tolerance, while gender-specific presentation patterns influence diagnostic suspicion thresholds.
- Adults:Patients aged 18-65 present the classic pulmonary-renal syndrome with highest therapeutic response rates to combined plasmapheresis and immunosuppression. German and Japanese registries document superior renal survival in this cohort when protocols initiate before serum creatinine exceeds specific thresholds.
- Elderly:Age-related immunosenescence and comorbidity burden complicate cytotoxic agent selection. United States Medicare Advantage plans are developing risk-adjusted bundled payments for elderly Goodpasture cases that transfer outcome accountability to nephrology group practices.
- Pediatric:Rare childhood presentations require weight-based dosing protocols and specialized pediatric nephrology consultation networks.
- Gender-Specific:Male predominance in classic anti-GBM disease and female skew in overlapping ANCA-positive cases inform differential diagnostic workups.
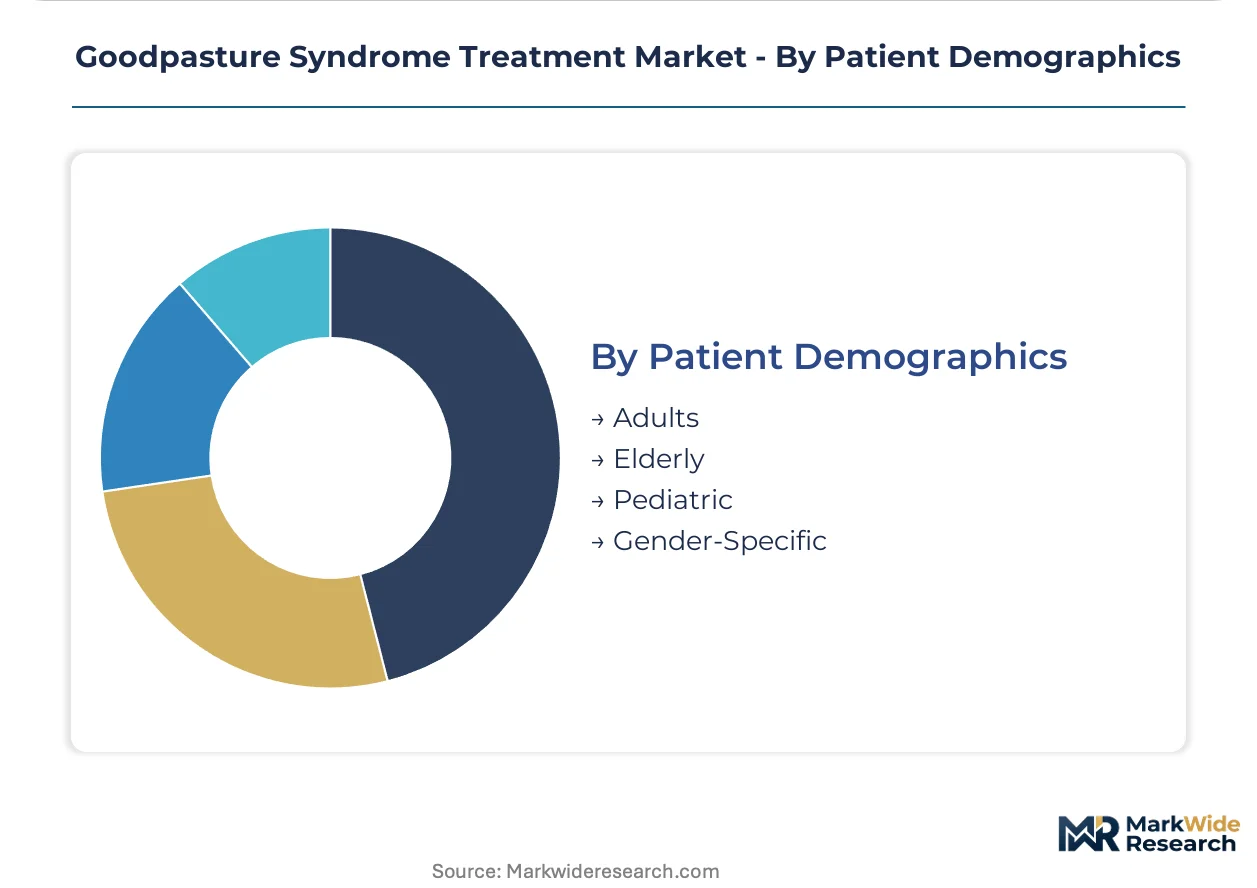
Adults generate the highest absolute treatment volumes; Elderly segments are expanding fastest as population aging extends into autoimmune disease prevalence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized nephrology and pulmonology talent clusters in the United States, Germany, and Japan anchor the highest protocol volumes for anti-GBM disease management. These concentrations determine where plasma fractionation capacity expands and where diagnostic-therapeutic integration advances fastest.
United States
Integrated delivery networks in Texas and Massachusetts consolidate autoimmune renal services into dedicated plasmapheresis units. FDA oversight of plasma-derived products shapes viral inactivation standards that determine which fractionators sustain commercial participation. Boston and Houston academic medical centers pilot risk-based contracting for refractory case bundles, transferring outcome accountability from payer to provider.
Germany
Tertiary nephrology departments maintain dedicated vascular access teams that reduce catheter-related bloodstream infections below benchmark rates. EMA's updated MDR requirements for immunosuppressive biologics extend certification timelines for European device manufacturers. Bavarian and North Rhine-Westphalian hospital procurement offices now require MDR compliance documentation in tender specifications for delivery systems.
Japan
Designated cancer hospitals with expanded autoimmune mandates add dedicated anti-GBM rapid response protocols to existing nephrology infrastructure. PMDA orphan drug incentives provide accelerated review pathways and tax credits for rare autoimmune indications. Tokyo and Osaka medical centers drive biomarker-guided protocol trials through MHLW-funded refractory case registries.
United Kingdom
NHS England specialized commissioning frameworks concentrate plasmapheresis capacity in London and Manchester renal networks. MHRA alignment with EMA device regulations ensures continuity in immunosuppressive delivery system standards post-Brexit. Cambridge and Oxford academic clusters advance anti-GBM antibody quantification platforms paired with treatment response monitoring.
France
Parisian tertiary centers coordinate cross-disciplinary nephrology-pulmonology protocols through Assistance Publique-Hôpitaux de Paris network structures. ANSM oversight of plasma-derived therapies maintains stringent batch release documentation requirements. Lyon and Marseille hospital systems invest in integrated care pathways for simultaneous renal and pulmonary management.
Goodpasture Syndrome Treatment Market Competitive Landscape
The competitive structure tilts toward plasma fractionation specialists with captive collection networks and diagnostic-therapeutic integrators. Consolidation around immunoglobulin feedstock security separates sustainable participants from spot-market-dependent entrants. Three archetypes dominate: vertically integrated plasma collectors securing raw material supply, biologic manufacturers expanding B-cell depletion portfolios, and diagnostic platforms bundling antibody quantification with protocol guidance. Dominant competitive moves include capacity expansion in concentrated supplier geographies and strategic partnerships bridging nephrology-pulmonology coordination gaps.
Within the plasma fractionation tier, CSL Limited and Grifols exemplify supply-anchored positioning through captive collection infrastructure spanning multiple continents. Roche occupies a position on the diagnostic-therapeutic integration vector, leveraging autoimmune rare disease portfolio breadth. These three names represent how feedstock security, vertical control, and platform bundling separate sustainable margin pools from commodity-exposed competitors.
| Leading Market Players |
|---|
| Roche |
| Novartis |
| Amneal Pharmaceuticals |
| CSL Limited |
| Merck & Co. |
| Bristol-Myers Squibb |
| Pfizer |
| Grifols |
| Sandoz |
| Others |
Supply & Pricing Matrix
Specialized nephrology nursing talent clusters in Germany and Japan command wage premiums that widen pricing spreads between academic medical centers and community hospitals for plasmapheresis protocols. Labor-cost differentials across these concentrated markets stratify service tiers, with EMA MDR compliance investments further separating premium-certified providers from standard-tier competitors.
Pricing Analysis
Bundled hospital-based plasmapheresis services versus unbundled specialty pharmacy distribution for rituximab maintenance now defines the pricing landscape. Three-tier pricing structure across premium academic centers, standard community hospitals, and economy outpatient clinics reflects certification grade and vascular access team availability. Cost compression in the economy tier intensifies as biosimilar entry compresses per-protocol biologic costs. Community hospitals with limited captive collection networks exhibit highest price sensitivity; tertiary academic centers with integrated delivery network scale demonstrate lowest sensitivity due to risk-based contracting leverage.
Supply Chain Analysis
Japan's PMDA domestic-content incentives for plasma-derived therapies are reshaping raw material sourcing toward local collection infrastructure investments. Plasma fractionation capacity concentrates in the United States, Germany, and Austria, drawing from source plasma, albumin feedstock, and immunoglobulin intermediate dependencies. Single-source vulnerability in albumin supply constrains European protocol availability during collection disruptions. Distribution runs through hospital pharmacy committees for acute-phase products and specialty pharmacy benefit managers for maintenance biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EMA MDR compliance costs in Europe and PMDA orphan drug tax credits in Japan, with regulatory cost differentials exceeding operational labor spreads.
For Market Incumbents: Extend captive plasma collection networks into PMDA-incentivized Japanese regions to secure feedstock cost advantages against European competitors facing EMA MDR certification delays. Deepen backward integration into source plasma logistics to insulate margin pools from spot market volatility. Prioritize diagnostic-therapeutic platform bundling to defend against rituximab biosimilar commoditization. For New Entrants and Emerging Players: Telemedicine-enabled remote monitoring platforms offer the lowest-friction entry path for maintenance-phase patient management outside hospital infusion centers. Target United States integrated delivery networks in Texas and Massachusetts seeking to unbundle site-of-service economics for stable patients. Pursue direct specialty pharmacy contracting to bypass incumbent hospital markup structures. For Investors and Strategic Acquirers: Vertically integrated plasma fractionators with multi-continent collection infrastructure are the most active acquirer in this space, consolidating distressed European device manufacturers facing MDR revalidation costs. Long-term viability hinges on feedstock security rather than biologic patent duration. Watch rituximab biosimilar formulary placement velocity as the inflection signal for maintenance-phase market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Plasma Collection Network Expansion | CSL Limited and Grifols secure raw material supply against spot market volatility through vertically controlled infrastructure. |
| Diagnostic-Therapeutic Platform Integration | Roche bundles anti-GBM antibody quantification with protocol guidance to capture personalization revenue streams. |
| EMA MDR Compliance Certification | European device manufacturers extend quality management timelines to meet stricter clinical evidence requirements for immunosuppressive delivery systems. |
| Subcutaneous Formulation Development | Specialty clinics in Massachusetts pilot home-based protocols to reduce hospital infusion center burden and capture ambulatory margin pools. |
| Rituximab Biosimilar Formulary Placement | Hospital pharmacy committees accelerate originator displacement to compress per-protocol costs and expand eligible refractory case pools. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with nephrology department heads, hospital pharmacy directors, plasma fractionation procurement managers, and regulatory affairs specialists with secondary validation against FDA filings, EMA MDR documentation, PMDA orphan drug submissions, and ClinicalTrials.gov protocol registries. Bottom-up protocol volume estimates triangulated against top-down plasma fractionation capacity data.
Segment-weighting approaches applied treatment type, administration route, end user facility category, and patient demographic dimensions across the projection horizon. CAGRs derived from modeled protocol adoption curves and pricing trajectory assumptions, incorporating immunoglobulin feedstock elasticity, biosimilar entry timelines, and regulatory compliance cost pass-through effects.
The model assumes a particular technology adoption path for B-cell depletion maintenance protocols; alternative pathways for high-dose corticosteroid pulse therapy persistence would alter the outlook. Forecasts reflect documented assumptions regarding plasma collection economics, MDR certification timelines, and PMDA incentive continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Necrotizing Skin Infections Treatment Market
Medical Treatment
Histoplasmosis Treatment Market
Medical Treatment
Anti-Fungal Treatment Market
Medical Treatment
Gunshot Injuries Treatment Market
Medical Treatment
Liver Transplantation Market
Medical Treatment
Tennis Elbow Treatment Market
Medical Treatment
Scalp Care Treatment Market
Medical Treatment
Corneal Transplant Market
Medical Treatment
Bloch-Sulzberger Treatment Market
Medical Treatment
Hereditary Amyloidosis Treatment Market
Medical Treatment
Global Systemic Lupus Erythematosus Treatment Market
Medical Treatment
Anemia Treatment Market
Medical Treatment
Adenomyosis Treatment Market
Medical Treatment
Europe Chronic Disease Management Market
Medical Treatment
Middle Ear Infection Treatment Market
Medical Treatment
Lyme Disease Treatment Market