
 Radiotherapy Devices Market | 2026-2036
Radiotherapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Radiotherapy Devices Market Outlook
CE marking under the EU Medical Device Regulation is bifurcating the competitive landscape between established multinationals and emerging device developers. Siemens Healthineers leverages its imaging-therapy integration portfolio to dominate integrated delivery networks seeking unified platforms. Elekta anchors Nordic and Western European markets through its longstanding linear accelerator installed base and service contracts.
Radiotherapy devices generate ionizing radiation through linear accelerators producing 6-25 MV X-ray beams or cobalt-60 gamma emitters to destroy malignant tissue with sub-millimeter targeting precision. Linear accelerators command the largest installed base and replacement revenue pool across mature markets, while stereotactic radiosurgery systems capture premium pricing in neuro-oncology and oligometastatic disease settings. Brachytherapy devices occupy a narrower but defensible niche in gynecological and prostate applications where dose escalation protocols favor internal source placement.
The FDA's 21 CFR Part 11 electronic records framework and the EU MDR's post-market surveillance requirements impose substantial compliance costs that filter smaller participants from commercialization pathways. Health Canada's alignment with IMDRF software-as-a-medical-device guidance further tightens algorithmic transparency standards for adaptive planning systems. Stakeholders must weigh regulatory capital intensity against the margin compression risk of commoditized external beam hardware as proton and carbon-ion alternatives mature.
Market Dynamics
EU MDR software validation requirements are forcing radiotherapy device manufacturers to restructure R&D pipelines around algorithmic transparency, while proton therapy capacity expansion in Germany signals a modality shift that threatens conventional linear accelerator replacement cycles.
Growth Catalysts
- Hypofractionated reimbursement protocols:Medicare coverage decisions in the United States compress equipment refresh timelines as clinics seek dose-escalation capable platforms.
- AI-driven adaptive planning:Machine learning integration into treatment planning systems enables real-time anatomical tracking that expands eligible patient populations.
- France:ANSM accelerated assessment pathways for breakthrough radiotherapy software reduce commercialization lag for adaptive planning modules.
Market Restraints
- Cobalt-60 supply concentration:Isotope production relies on aging nuclear reactors concentrated in Canada and Russia, creating source material vulnerability for gamma-based devices.
- Proton facility capex intensity:Cyclotron and synchrotron installations require $100-200 million capital commitments that limit addressable site selection to academic medical centers.
- EU MDR clinical evidence requirements:Legacy linear accelerator software upgrades now demand prospective validation studies that extend recertification timelines.
Strategic Opportunities
- Carbon-ion therapy:Japan's NIRS facility network demonstrates curative potential for radioresistant histologies, creating white space for heavy ion system deployment in Europe.
- Teletherapy service unbundling:Independent service organizations are capturing linear accelerator maintenance contracts from OEM captive service arms.
- Swissmedic parallel review:Switzerland's regulatory alignment with EU MDR creates early market access for CE-marked adaptive planning systems before full EU rollout.
Industry Challenges
- Medical physics workforce scarcity:Treatment planning algorithm validation requires specialized competency that outpaces training program output.
- Legacy LINAC integration complexity:Adaptive planning software retrofits face interoperability barriers with 15-20 year installed base control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiotherapy Devices Market |
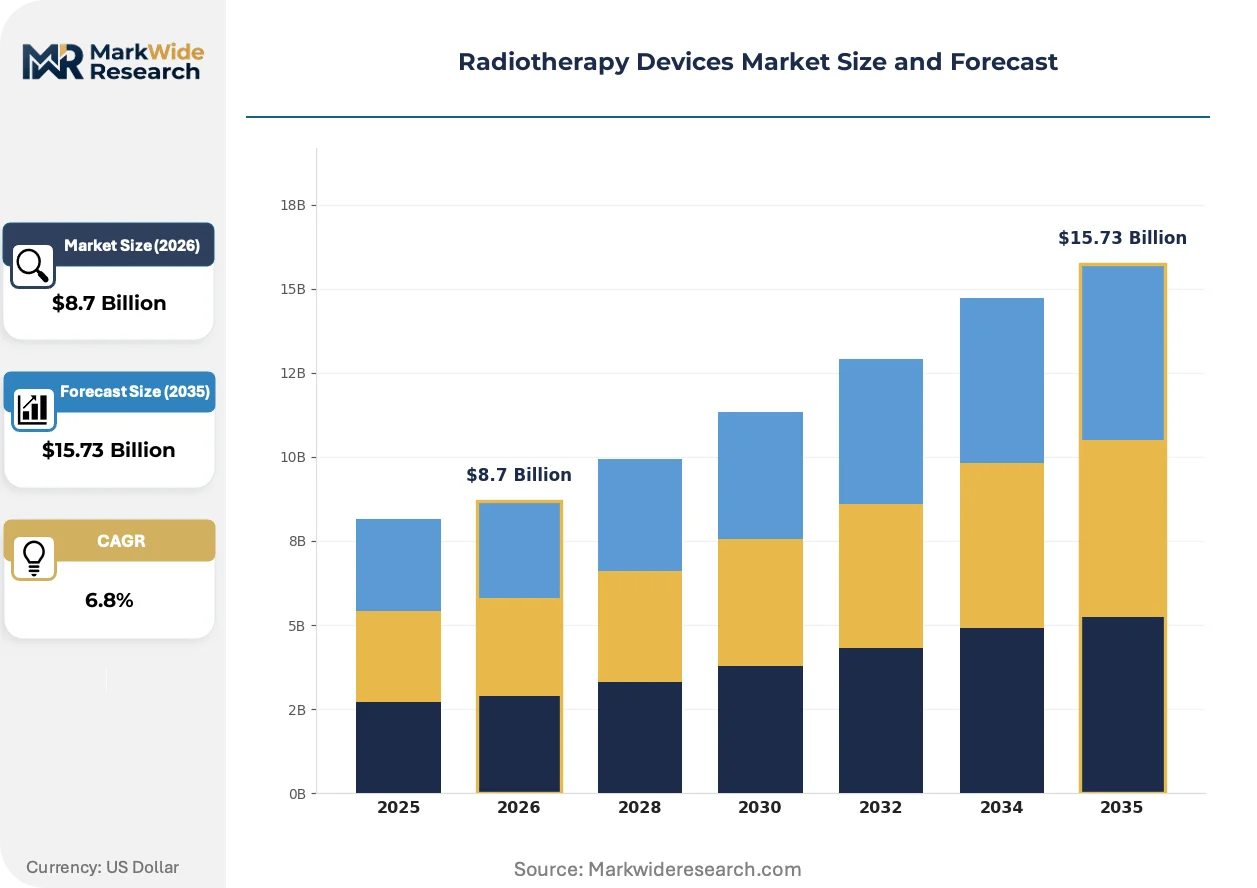
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Linear Accelerators, Brachytherapy Devices, Radioisotope Devices, Systems End User: Hospitals, Oncology Clinics, Research Institutions, Diagnostic Centers Treatment Technique: External Beam Radiotherapy, Internal Radiotherapy, Stereotactic Radiosurgery, Image-Guided Therapy Application: Cancer Treatment, Palliative Care, Pediatric Therapy, Emerging Therapies |
| Companies Covered | Accuray Incorporated, Hitachi, Siemens Healthineers, ViewRay, IBA Worldwide, Elekta, Philips Healthcare, Mevion Medical Systems, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiotherapy Devices Market Strategic Shifts
Magnetic resonance-guided radiotherapy is collapsing the imaging-therapy workflow into unified delivery platforms, while regulatory software reclassification and procurement model fragmentation are simultaneously reshaping competitive entry points.
MR-linac systems combine diagnostic-quality soft tissue visualization with megavoltage beam delivery, enabling daily adaptive replanning. Academic medical centers in the Netherlands and United States are deploying these platforms for abdominal and pelvic malignancies where motion management is critical. The technology is bifurcating the external beam market between premium integrated systems and commodity photon hardware facing margin compression.
Health Canada's alignment with IMDRF software-as-a-medical-device guidance reclassifies adaptive planning algorithms as standalone regulated products. Algorithm update cycles now require pre-market notification rather than post-hoc documentation. Canadian oncology networks are responding by centralizing software procurement through provincial health authorities to amortize compliance costs.
Integrated delivery networks in the United States are consolidating radiotherapy equipment purchasing through single-source platform contracts that bundle linear accelerators, planning software, and long-term service agreements. Independent oncology practices face exclusion as IDNs demand unified vendor ecosystems. This concentration is most visible in Texas and Florida markets where health system consolidation has advanced furthest.
Radiotherapy Devices Market Segmentation
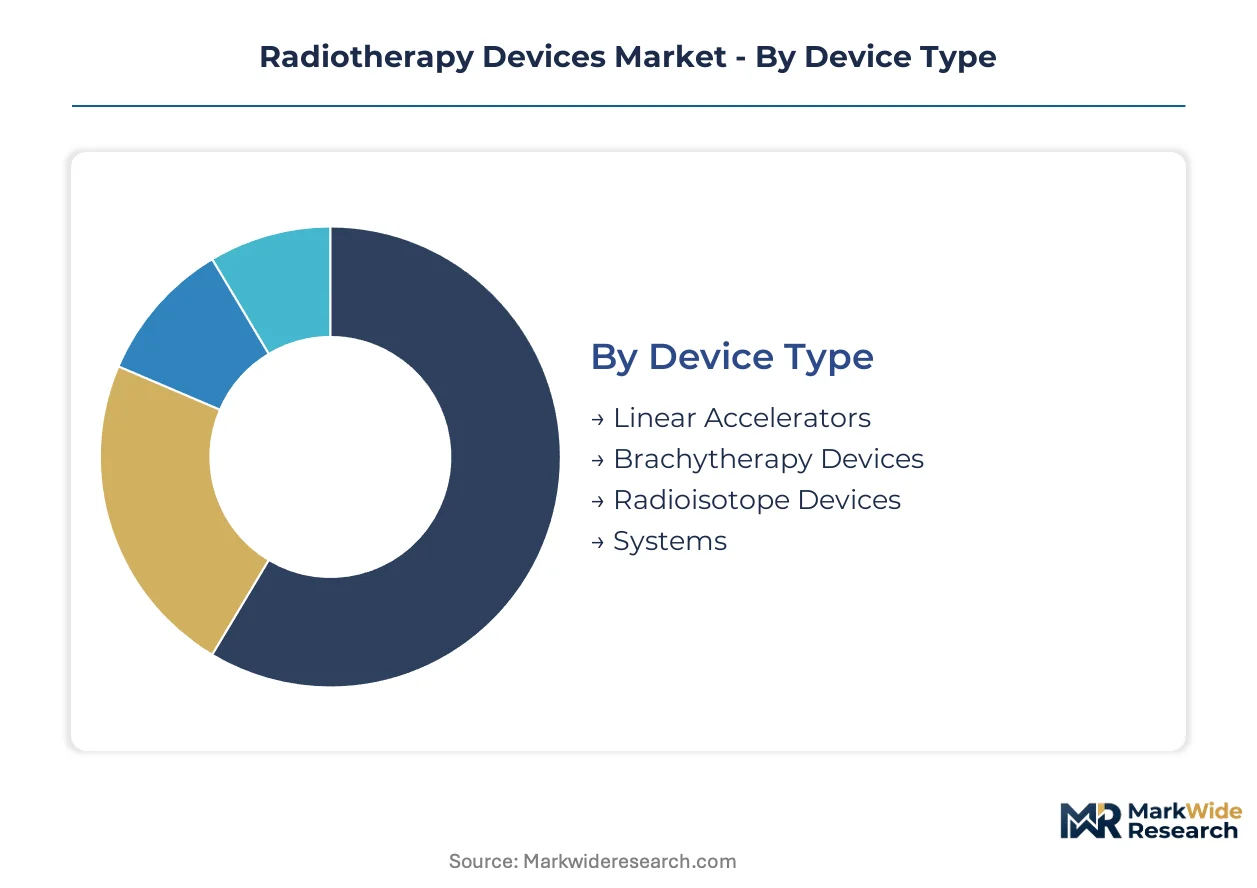
Radiotherapy device segmentation reveals divergent capital intensity and regulatory pathways across hardware categories. Treatment technique and end-user configuration determine reimbursement eligibility and facility certification requirements in ways that reshape procurement patterns.
Device Type:
Linear accelerators dominate domestic installed base renewal cycles across mature markets, while proton and radioisotope systems concentrate in export-led academic medical center deployments.
- Linear Accelerators:These systems generate megavoltage X-ray beams through microwave-accelerated electrons striking high-density targets. Demand concentrates in United States integrated delivery networks replacing aging gantries to capture hypofractionated Medicare reimbursement. The installed base in Germany and France drives replacement revenue as EU MDR software recertification deadlines approach.
- Brachytherapy Devices:Afterloaders and applicators deliver radioactive sources directly to tumor beds through catheters or intracavitary placement. Gynecological oncology units in Spain and Italy anchor European demand, while prostate brachytherapy faces volume pressure from alternative focal therapies in North American markets.
- Radioisotope Devices:Gamma-emitting cobalt-60 units serve markets with limited linear accelerator infrastructure.
- Systems:Integrated MR-linac and proton therapy platforms command premium positioning in academic tertiary centers.
Linear accelerators command the established base. The steepest expansion runs through proton and heavy-ion systems.
End User:
Procurement scale bifurcates between high-volume hospital networks negotiating enterprise contracts and specialized clinics seeking modality-specific platforms.
- Hospitals:Comprehensive cancer centers with captive radiation oncology departments aggregate multiple linear accelerators under unified vendor relationships. These facilities in Texas and Florida health systems leverage volume concentration to extract service bundling concessions.
- Oncology Clinics:Freestanding radiation therapy centers optimize throughput through dedicated linear accelerator operations. German proton therapy clinic expansion reflects this segment's capital mobilization capacity for cyclotron-based modalities.
- Research Institutions:Academic medical centers host adaptive planning algorithm validation studies required under EU MDR and Health Canada frameworks.
- Diagnostic Centers:Imaging-focused facilities rarely maintain radiotherapy capacity, creating referral dependencies with treatment providers.
Hospitals retain volume leadership. The fastest share gains are emerging in specialized oncology clinics.
Treatment Technique:
Reimbursement differentiation between fractionation protocols is concentrating investment in image-guided and stereotactic modalities.
- External Beam Radiotherapy:Conventional fractionated photon therapy remains the default modality for most solid malignancies. Capacity in United States community oncology settings sustains this segment despite margin compression from commoditized hardware.
- Internal Radiotherapy:Brachytherapy and radioembolization deliver dose escalation through temporary or permanent source placement. Prostate and gynecological applications in French and Italian clinics preserve this technique's clinical relevance.
- Stereotactic Radiosurgery:Single-fraction or hypofractionated delivery with sub-millimeter precision captures premium positioning in neuro-oncology and oligometastatic disease.
- Image-Guided Therapy:Daily anatomical tracking through onboard imaging enables margin reduction and dose escalation.
External beam retains procedure volume dominance. Stereotactic radiosurgery is climbing the fastest on expanded indication approvals.
Application:
Pediatric and emerging therapy segments carry distinct regulatory and facility certification requirements that filter site eligibility.
- Cancer Treatment:Curative-intent radiotherapy for solid and hematologic malignancies drives the majority of device utilization. Lung, breast, and prostate indications in United States Medicare populations sustain baseline demand.
- Palliative Care:Symptom-directed fractionation for bone metastases and obstruction requires simpler planning protocols. Community hospitals in rural United States markets deploy basic linear accelerator configurations for this application.
- Pediatric Therapy:Childhood cancer protocols demand specialized anesthesia support and long-term toxicity monitoring. Dedicated proton facilities in Japan and select European centers address this segment's normal tissue sparing requirements.
- Emerging Therapies:FLASH radiotherapy and spatially fractionated approaches remain investigational.
Cancer treatment absorbs the installed base. Pediatric applications are gaining share fastest on proton therapy network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement for hypofractionated regimens in the United States accelerates linear accelerator replacement cycles, while EU MDR software validation deadlines compress commercialization timelines across European markets. Germany's proton therapy expansion and Japan's heavy-ion network demonstrate modality diversification beyond conventional photon systems.
United States
Integrated delivery networks in Texas and Florida consolidate radiotherapy procurement through single-source platform contracts bundling hardware, software, and long-term service agreements. The FDA's 21 CFR Part 11 electronic records framework imposes substantial compliance costs that filter smaller device developers from commercialization pathways. Academic medical centers in Boston and Houston host adaptive planning algorithm validation studies required for regulatory clearance.
Germany
Oncology clinics expand proton therapy capacity following the EU Medical Device Regulation's tightened software validation requirements for AI-driven treatment planning. CE marking under EU MDR bifurcates the competitive landscape between established multinationals and emerging device developers. The Heidelberg Ion Beam Therapy Center anchors heavy-ion research infrastructure while university hospitals in Munich and Essen deploy MR-linac systems for abdominal malignancies.
Japan
The National Institute of Radiological Sciences facility network demonstrates curative potential for carbon-ion therapy in radioresistant histologies, creating deployment precedent for heavy ion systems. METI funding supports domestic cyclotron manufacturing capacity. Treatment centers in Chiba and Hyogo prefectures concentrate pediatric proton therapy capacity addressing normal tissue sparing requirements.
France
ANSM accelerated assessment pathways for breakthrough radiotherapy software reduce commercialization lag for adaptive planning modules entering the market. Gynecological oncology units in Paris and Lyon anchor European brachytherapy demand through afterloader installations. University hospital networks centralize software procurement through regional health authorities to amortize EU MDR compliance costs.
Canada
Health Canada's alignment with IMDRF software-as-a-medical-device guidance reclassifies adaptive planning algorithms as standalone regulated products requiring pre-market notification. Provincial oncology networks in Ontario and Quebec respond by consolidating procurement through centralized health authorities. The Cross Cancer Institute in Edmonton hosts MR-linac deployment for motion-critical pelvic malignancies.
Radiotherapy Devices Market Competitive Environment
Player mix skews toward diversified health technology conglomerates with imaging-therapy integration portfolios alongside specialized proton therapy system developers. Market structure concentrates around vendors capable of absorbing EU MDR and FDA compliance capital intensity. Three archetypes dominate: integrated imaging-therapy platform vendors, proton and heavy-ion modality specialists, and independent service organizations capturing maintenance contract unbundling. Competitive moves center on enterprise contract consolidation with integrated delivery networks and regulatory pre-certification partnerships with academic medical centers.
Within the diversified health technology tier, Siemens Healthineers AG and GE Healthcare occupy positions exemplifying imaging-therapy convergence strategies. Among proton therapy specialists, IBA Worldwide and Mevion Medical Systems represent modality-specific capital equipment archetypes facing cyclotron deployment constraints. Elekta AB anchors the linear accelerator installed base and service contract segment through longstanding Nordic market presence. Accuray Incorporated sits within the stereotactic radiosurgery specialization vector targeting neuro-oncology applications.
| Leading Market Players |
|---|
| Accuray Incorporated |
| Hitachi |
| Siemens Healthineers |
| ViewRay |
| IBA Worldwide |
| Elekta |
| Philips Healthcare |
| Mevion Medical Systems |
| GE Healthcare |
| Others |
Value Chain & Pricing Dynamics
Proton therapy cyclotrons replacing conventional linear accelerators in German oncology clinics simultaneously shifts supply geography toward specialized heavy-ion component manufacturers and compresses pricing premiums for photon-based hardware. This substitution dynamic concentrates procurement leverage within academic medical centers capable of absorbing capital intensity while fragmenting service contract markets.
Pricing Analysis
Certification level under EU MDR and FDA 21 CFR Part 11 creates the primary spread between premium adaptive planning systems and commodity linear accelerator hardware. Three-tier pricing structure across premium, standard, and economy levels stratifies by algorithmic transparency grade and after-sales bundling depth. Cost compression in standard-tier photon systems intensifies as proton alternatives mature and Medicare hypofractionated reimbursement accelerates replacement cycles. Independent oncology practices exhibit highest price sensitivity, while integrated delivery networks in Texas and Florida absorb premium positioning through volume concentration.
Supply Chain Analysis
Extended lead times for superconducting magnet assemblies and RF power systems constrain cyclotron manufacturing throughput. Component sourcing concentrates in Germany, Japan, and the United States for precision gantry fabrication and software control systems. Supply chain vulnerability hinges on cobalt-60 isotope production concentrated in aging Canadian and Russian nuclear reactors. Distribution runs through OEM captive service arms facing unbundling pressure from independent service organizations capturing linear accelerator maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where software subscription revenue and long-term maintenance contracts expand faster than capital hardware sales. The recurring revenue layer from adaptive planning algorithm updates and proton facility service agreements outpaces equipment replacement cycles.
For Market Incumbents: Shield installed base retention through backward integration into AI-driven treatment planning software and preemptive EU MDR certification investments. Siemens Healthineers and Elekta must defend against proton therapy modality displacement by embedding imaging-therapy convergence deeper into IDN platform contracts. Captive service contract renewal rates represent the critical defensive lever against independent service organization encroachment. For New Entrants and Emerging Players: Independent service organization capability gaps in legacy linear accelerator retrofit compatibility create white-space entry points. Carbon-ion therapy system development and MR-linac software modules targeting abdominal malignancies offer the most penetrable segments. Go-to-market positioning through Swissmedic parallel review pathways enables early CE-marked adaptive planning system access before full EU rollout completion. For Investors and Strategic Acquirers: Capital is best deployed toward proton therapy modality specialists with cyclotron manufacturing capacity and heavy-ion clinical validation networks. Long-term viability across the projection horizon favors vendors with regulatory pre-certification partnerships at academic medical centers in Germany and Japan. The signal to monitor is ANSM and Health Canada accelerated assessment pathway utilization rates as inflection indicators for adaptive planning software commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR software validation requirements filter smaller developers from commercialization pathways. |
| Hospital System Partnership | Integrated delivery networks in Texas consolidate procurement through single-source platform contracts. |
| Software Companion Development | Adaptive planning algorithm updates generate recurring revenue streams beyond hardware replacement cycles. |
| Reimbursement Strategy | Medicare hypofractionated coverage decisions accelerate linear accelerator refresh timelines in United States. |
| Backward Integration | Captive control over superconducting magnet supply reduces cyclotron manufacturing lead time vulnerability. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with radiation oncology department heads, biomedical engineers, hospital purchasing committee members, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EUDAMED device registrations, CMS Medicare reimbursement databases, and proton therapy facility commissioning records. Bottom-up equipment shipment tracking and top-down healthcare capital expenditure triangulation anchored market sizing.
Across the analysis window, projections model device type segmentation by capital intensity tier, treatment technique by reimbursement eligibility, end-user configuration by procurement scale, and application by facility certification requirements. CAGRs derive from installed base renewal cycle analysis and modality shift elasticity. Forecast inputs incorporate EU MDR recertification deadline impacts and Medicare coverage decision velocity for hypofractionated regimens.
Underlying assumptions cover reimbursement policy continuity and isotope supply stability, with deviation risk concentrated in cobalt-60 production disruptions and proton facility financing availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
France Ophthalmic Devices Market
Medical Devices
Global Holter ECG Market
Medical Devices
Ocular Trauma Devices Market
Medical Devices
Intraoral Scanners Market
Medical Devices
Mexico Respiratory Devices Market
Medical Devices
Global Smart Implants Market
Medical Devices
Global Skin Grafting Device Market
Medical Devices
Pelvic Floor Stimulators Market
Medical Devices
Syringe Filling Machine Market
Medical Devices
Volumetric Arc Therapy Market
Medical Devices
Transplant Monitoring Kits Market
Medical Devices
Urinary Flow Meters Market
Medical Devices
Powered Wheelchair Market
Medical Devices
C-Arms Devices Market
Medical Devices
Dynamic Spinal Tethering Systems Market
Medical Devices
Powered Mattress System Market