
 Brain Tumor Treatment Market | 2026-2036
Brain Tumor Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Brain Tumor Treatment Market Outlook
Advances in tumor-treating fields and convection-enhanced delivery are reshaping how clinicians approach drug penetration across the blood-brain barrier. F. Hoffmann-La Roche Ltd leverages its neuro-oncology pipeline to anchor European precision medicine networks. Bristol-Myers Squibb competes through checkpoint inhibitor combinations for recurrent glioblastoma. Novartis AG differentiates with radioligand therapy platforms targeting meningioma subtypes.
Brain tumor treatment encompasses surgical resection, radiation protocols, systemic agents, and emerging biologics administered to destroy or control neoplastic growth within the cranial vault, with five-year survival rates for glioblastoma multiforme remaining below ten percent despite maximal therapy. The primary purpose centers on extending progression-free survival while preserving neurological function. Surgery and radiation therapy constitute the mature revenue base, though targeted therapy captures expanding margin pools as biomarker-driven patient stratification improves. Immunotherapy within the treatment modality dimension represents the fastest-growing segment, driven by CAR-T engineering and vaccine platforms entering late-phase trials.
The FDA's breakthrough therapy designation and orphan drug incentives shape how developers prioritize indications for rare pediatric and adult brain malignancies. EMA's centralized marketing authorization and health technology assessment processes govern European commercial access, while WHO's essential medicines list influences procurement in lower-income health systems. Stakeholders must monitor how radiopharmaceutical manufacturing capacity constraints and reimbursement negotiations for personalized medicine platforms determine which modalities achieve scalable adoption.
Market Dynamics
The FDA's breakthrough therapy designation compresses glioblastoma drug development timelines while tumor-treating fields and convection-enhanced delivery systems reshape how clinicians overcome the blood-brain barrier. These converging forces are accelerating modality shifts across neuro-oncology.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's breakthrough therapy and orphan drug incentives compress Phase II-to-approval timelines for rare pediatric and adult brain malignancies, redirecting R&D investment toward high-unmet-need indications.
- Precision Medicine Networks:European neuro-oncology centers are integrating liquid biopsy and molecular profiling into standard care pathways, expanding addressable patient populations for biomarker-driven therapies.
- CAR-T Engineering Platforms:Autologous cell therapy manufacturing advances are reducing vein-to-vein timelines for recurrent glioblastoma candidates, opening new treatment windows previously closed by disease progression.
Market Restraints
- Isotope Supply Concentration:Radioligand therapy production depends on a handful of cyclotron facilities in the United States and Europe, creating geographic access inequities and dose-limiting bottlenecks for meningioma protocols.
- Reimbursement Friction:EMA centralized authorization does not guarantee national health technology assessment acceptance, delaying commercial access in Germany, France, and Italy despite marketing approval.
- Blood-Brain Barrier Physiology:Systemic agent penetration remains fundamentally limited by tight junction architecture, constraining efficacy for large-molecule biologics regardless of target validation.
Strategic Opportunities
- Underpenetrated Asia-Pacific Markets:Japan's aging demographic and South Korea's national cancer center networks present expansion vectors for tumor-treating field devices not yet optimized for Asian cranial anatomy standards.
- WHO Essential Medicines Influence:Inclusion of temozolomide and radiotherapy protocols on the WHO essential medicines list creates procurement anchors for lower-income health systems previously dependent on philanthropic access programs.
- AI-Augmented Surgical Planning:Convergence of intraoperative MRI navigation with machine learning segmentation is reducing residual tumor margins in academic medical centers, creating upgrade cycles for installed radiation therapy bases.
Industry Challenges
- Neuro-Oncology Workforce Scarcity:Fellowship-trained neuro-oncologists concentrate in coastal United States academic centers, limiting protocol enrollment capacity in community hospital settings where the majority of glioblastoma patients receive initial care.
- Multimodal Integration Complexity:Synchronous administration of tumor-treating fields with checkpoint inhibitors requires coordination across radiation oncology, medical oncology, and device specialty nursing—workflows most centers have not operationalized.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brain Tumor Treatment Market |
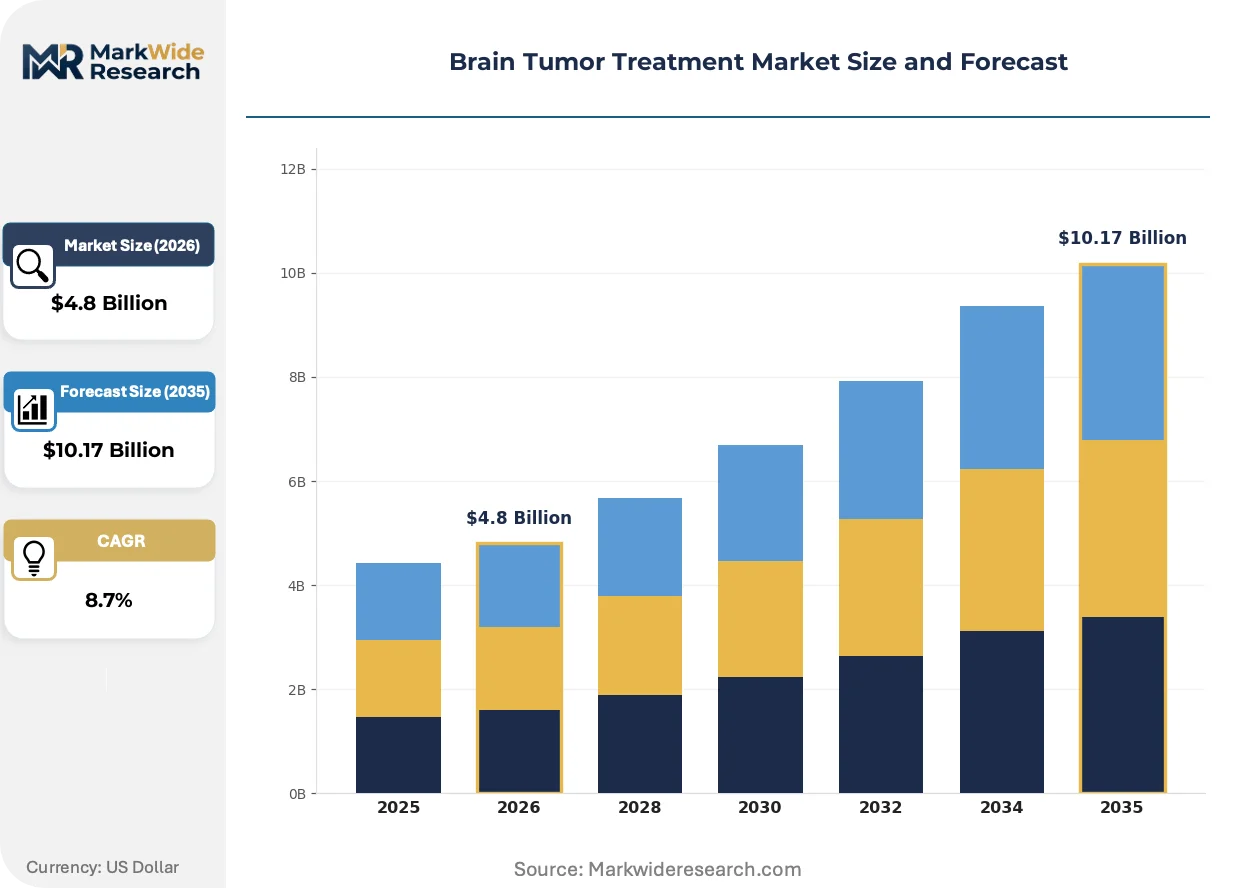
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgery, Radiation Therapy, Chemotherapy, Targeted Therapy End User: Hospitals, Clinics, Specialized Cancer Centers, Research Institutions Treatment Modality: Stereotactic Radiosurgery, Systemic Therapy, Immunotherapy, Personalized Medicine Administration Route: Intravenous, Oral, Intrathecal, Topical |
| Companies Covered | F. Hoffmann-La Roche Ltd, Merck & Co., Inc., Bristol-Myers Squibb, AstraZeneca, Novartis AG, Pfizer Inc., Bayer AG, Amgen Inc., Eisai Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brain Tumor Treatment Market Strategic Shifts
Tumor-treating fields are migrating from maintenance monotherapy to synchronous combination platforms, while regulatory frameworks and procurement models co-evolve to accommodate personalized medicine manufacturing requirements.
Optune device technology is hybridizing with systemic therapy administration schedules. Neuro-oncology departments at academic medical centers in the United States are adopting continuous delivery protocols concurrent with temozolomide cycles rather than sequential sequencing. This convergence is compressing progression-free survival endpoints in clinical trials and forcing comparator arm redesign for investigational agents.
EMA's centralized marketing authorization now incorporates parallel health technology assessment submissions under the EU pharmaceutical strategy. Manufacturers must submit cost-effectiveness modeling alongside clinical data, altering trial design to capture quality-of-life endpoints earlier. Recurrent glioblastoma indications face particular scrutiny in Germany's AMNOG process, where added-benefit ratings determine reimbursement levels.
Hospital procurement committees are unbundling device acquisition from disposable supply agreements for tumor-treating field systems. IDN-level contracting in the United States is replacing single-site negotiations, with supply chain directors demanding multi-year total cost of ownership guarantees. This consolidation is most visible in the Midwest, where Catholic health system networks are standardizing neuro-oncology device portfolios across fifteen-state footprints.
Brain Tumor Treatment Market Segmentation
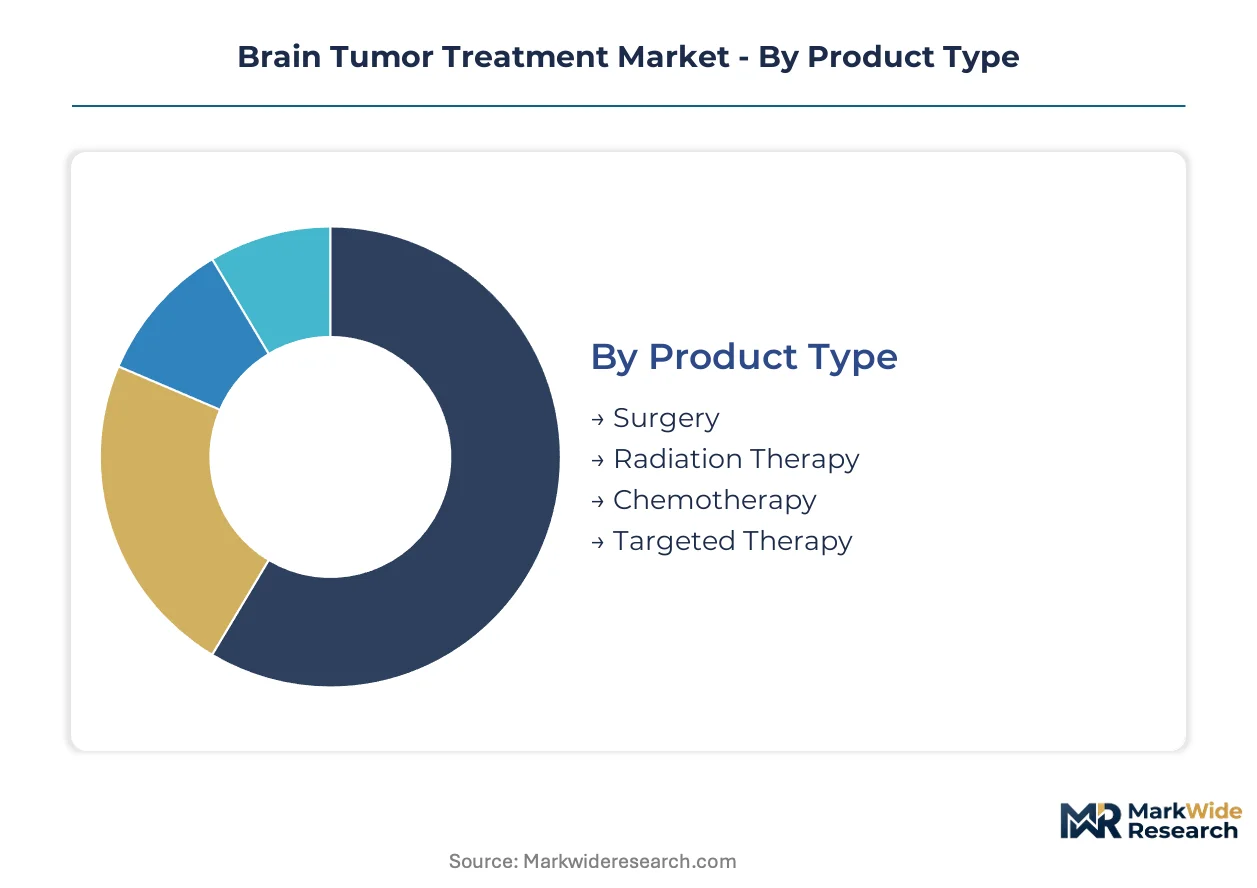
Brain tumor treatment markets fragment across intervention maturity and care delivery infrastructure. Segmentation reveals where capital deployment concentrates versus where novel modalities are displacing standards of care.
Product Type:
Mature resection and radiation platforms anchor revenue, while emerging modalities reshape margin structures.
- Surgery:Craniotomy and transsphenoidal approaches remain first-line for accessible lesions, with intraoperative MRI navigation now standard at academic medical centers in the United States. Resection volume concentrates in hospitals maintaining dedicated neurosurgical suites.
- Radiation Therapy:Fractionated external beam and stereotactic radiosurgery constitute the installed base revenue foundation, with proton centers in Florida and Texas drawing interstate referral flows for pediatric ependymoma protocols.
- Chemotherapy:Alkylating agents, primarily temozolomide, represent the systemic backbone for glioblastoma maintenance regimens.
- Targeted Therapy:Biomarker-directed small molecules are penetrating IDH-mutant glioma populations as companion diagnostics reach community oncology practices.
Surgery and radiation therapy handle the majority of throughput; targeted therapy is climbing the fastest on share.
End User:
Care delivery infrastructure stratifies by case complexity and protocol eligibility requirements.
- Hospitals:General acute care facilities manage initial diagnosis and stabilization, though cranial procedure volume is consolidating toward centers of excellence with dedicated neuro-ICU capacity.
- Specialized Cancer Centers:NCI-designated comprehensive cancer centers in Boston, Houston, and New York dominate enrollment for experimental immunotherapy trials and CAR-T manufacturing slots.
- Clinics:Community oncology practices handle routine surveillance imaging and toxicity management for stable patients on maintenance therapy.
- Research Institutions:Academic medical centers with GMP-compliant cell therapy facilities control access to autologous platform trials for recurrent disease.
Hospitals absorb the greatest patient volume; specialized cancer centers are expanding most quickly on per-case revenue intensity.
Treatment Modality:
Technology generations overlap as device-platform hybrids complicate traditional therapy classification.
- Systemic Therapy:Cytotoxic and targeted small molecules administered intravenously or orally remain the default for diffuse infiltrating gliomas where local control fails.
- Immunotherapy:Checkpoint inhibitors, oncolytic viruses, and vaccine platforms are reshaping trial design for recurrent glioblastoma, with dendritic cell therapies manufactured at Johns Hopkins and UCSF drawing national referral networks.
- Stereotactic Radiosurgery:Gamma Knife and CyberKnife systems deliver ablative dose distributions for metastases and selected primary tumors.
- Personalized Medicine:Molecular profiling-directed sequencing of targeted agents and clinical trial matching is operational at European precision medicine networks anchored by F. Hoffmann-La Roche Ltd partnerships.
Systemic therapy handles the majority of throughput; immunotherapy shows the steepest expansion trajectory in trial enrollment.
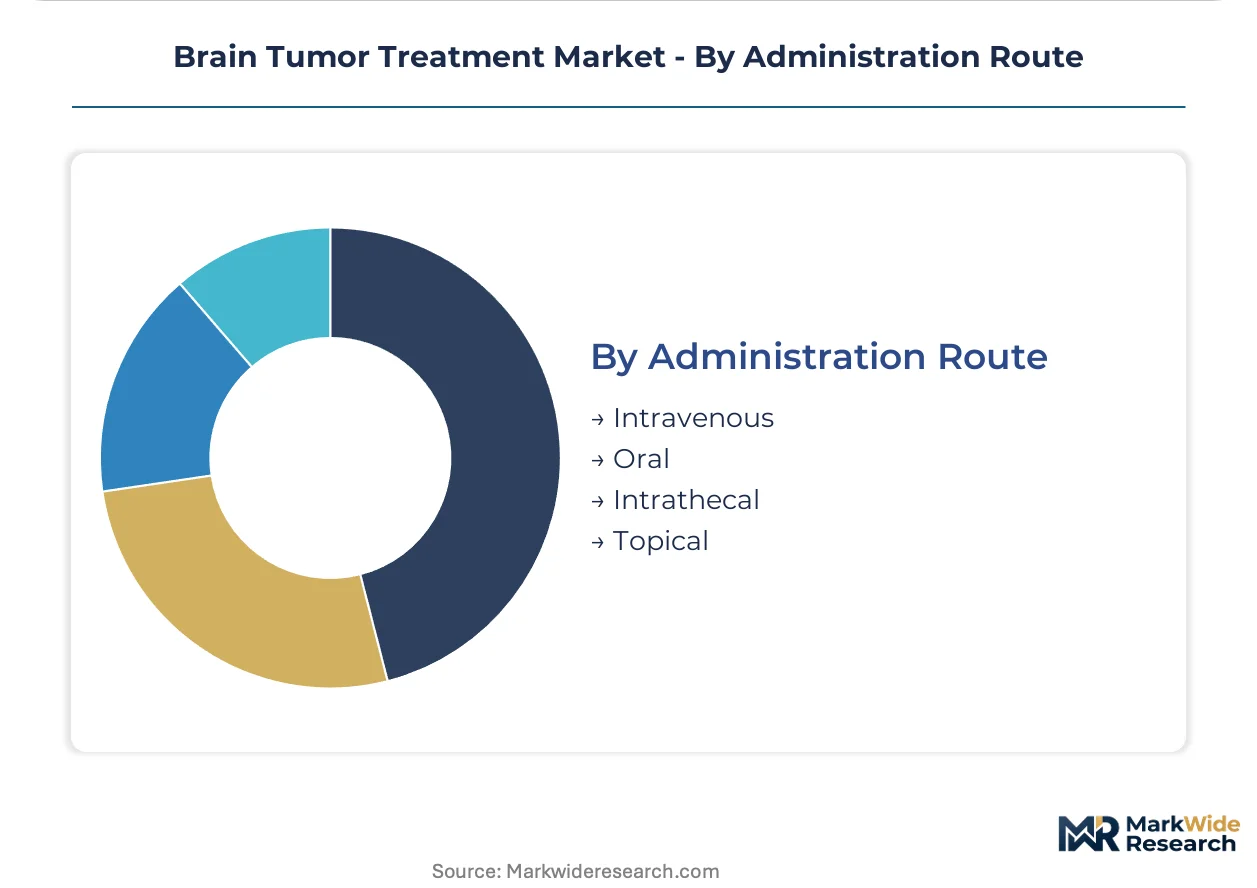
Administration Route:
Delivery physiology dictates which agent classes can access the tumor microenvironment.
- Intravenous:Standard infusion protocols for cytotoxics and monoclonal antibodies, with port placement and line maintenance burdening community oncology nursing capacity.
- Oral:Temozolomide and emerging small molecule inhibitors enable outpatient maintenance, though adherence monitoring and CYP450 interaction management fall to community practices.
- Intrathecal:Ommaya reservoir and lumbar puncture delivery for leptomeningeal carcinomatosis and primary CNS lymphoma, restricted to centers with neuro-oncology nursing specialization.
- Topical:Limited to investigational convection-enhanced delivery catheters and intraoperative local agent instillation in trial settings.
Intravenous delivery handles the majority of throughput; oral regimens are gaining share fastest on patient preference and site-of-care economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision medicine networks export neuro-oncology expertise to Eastern European referral centers. United States academic medical centers attract cross-border glioblastoma patients from Canada and Latin America.
United States
NCI-designated comprehensive cancer centers in Boston and Houston enroll the majority of recurrent glioblastoma immunotherapy trials. FDA breakthrough therapy designation compresses Phase II-to-approval timelines for rare pediatric brain malignancies. The MD Anderson and Memorial Sloan Kettering clusters anchor referral networks drawing interstate and international patients for CAR-T manufacturing slots.
Germany
EMA centralized authorization processes govern commercial access for radioligand therapies targeting meningioma subtypes. The AMNOG health technology assessment framework determines reimbursement levels for novel agents despite marketing approval. Heidelberg and Munich academic medical centers integrate liquid biopsy profiling into standard neuro-oncology pathways, expanding biomarker-driven patient stratification.
Japan
PMDA regulatory pathways accommodate tumor-treating field device approvals for aging demographics with rising glioma incidence. METI industrial policy supports domestic manufacturing of neuro-navigation systems for cranial procedures. Tokyo and Osaka metropolitan hospital networks standardize intraoperative MRI protocols, creating upgrade demand for installed radiation therapy bases.
United Kingdom
NHS England specialized commissioning frameworks govern access to proton beam therapy for pediatric ependymoma. The MHRA post-Brexit regulatory autonomy enables accelerated approval timelines for glioblastoma drug candidates. London and Manchester neuro-oncology centers participate in European precision medicine networks anchored by pharmaceutical partnerships.
India
CDSCO regulatory pathways for orphan drug incentives attract glioblastoma development programs from multinational sponsors. Government medical colleges in Delhi and Mumbai expand neurosurgical residency training to address workforce scarcity in community hospital settings. Private hospital chains in Bangalore and Hyderabad invest in Gamma Knife systems to capture medical tourism flows from South Asia and the Middle East.
Brain Tumor Treatment Market Competitive Environment
Channel-controlling players compete with product-specialist players across neuro-oncology device and pharmaceutical segments. The market exhibits tiered concentration: multinational pharmaceutical conglomerates anchor precision medicine networks, while regional device distributors capture tumor-treating field system installations. Three archetypes dominate: vertically integrated biopharma majors with neuro-oncology pipelines, device-platform specialists with disposable recurring revenue models, and academic medical center spin-outs commercializing cellular therapy platforms. Competitive moves concentrate on strategic partnerships bridging device and pharmaceutical modalities, plus geographic licensing arrangements for radioligand manufacturing technology.
Among Swiss and German pharmaceutical conglomerates, F. Hoffmann-La Roche Ltd and Bayer AG occupy positions anchoring European precision medicine networks. Novartis AG represents the radioligand therapy archetype with platforms targeting meningioma subtypes. These three exemplify how geographic origin and corporate structure correlate with modality specialization in neuro-oncology competitive positioning.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Merck & Co., Inc. |
| Bristol-Myers Squibb |
| AstraZeneca |
| Novartis AG |
| Pfizer Inc. |
| Bayer AG |
| Amgen Inc. |
| Eisai Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Air freight corridors connecting Basel and Boston govern radioligand therapy distribution economics, concentrating pricing power with cyclotron facility operators while forcing device manufacturers to absorb logistics premiums or pass through to hospital procurement committees.
Pricing Analysis
Technology-generation pricing gaps separate first-line temozolomide generics from next-generation CAR-T manufacturing slots and tumor-treating field device bundles. Three-tier pricing structure across premium, standard, and economy levels reflects FDA breakthrough therapy designation status, companion diagnostic bundling, and after-sales service intensity. Pricing pressure stems from IDN-level contracting consolidation in the United States Midwest, where Catholic health system networks demand multi-year total cost of ownership guarantees. Community oncology practices exhibit highest price sensitivity due to Medicare reimbursement compression, while NCI-designated comprehensive cancer centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Tariff exposure between the United States and European Union radiopharmaceutical precursor suppliers dominates supply chain risk assessment for meningioma therapy protocols. Cyclotron manufacturing concentrates in Belgium, the Netherlands, and select United States academic medical centers, creating geographic access inequities for dose-critical isotope production. Raw material dependencies include lutetium-177, actinium-225, and specialized polymer substrates for convection-enhanced delivery catheters. Single-source vulnerability characterizes isotope supply given reactor maintenance schedules and geopolitical export controls. Distribution runs through pharmaceutical specialty distributors with cold-chain certification rather than general medical-surgical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection centers on interoperability between tumor-treating field devices and electronic health record systems, with Epic and Cerner integration becoming the new table stakes for academic medical center procurement committees.
For Market Incumbents: Pre-empt CAR-T engineering platform commoditization by securing exclusive liquid biopsy partnerships with F. Hoffmann-La Roche Ltd and Foundation Medicine networks. Consolidate neuro-oncology workforce training programs through acquisition of fellowship pipeline assets in coastal United States academic centers. Anchor defensive positioning against checkpoint inhibitor biosimilar entrants by deepening device-platform hybrid offerings that complicate pure pharmaceutical substitution. For New Entrants and Emerging Players: South Korean national cancer center networks present white-space opportunity for tumor-treating field devices optimized to Asian cranial anatomy standards. Target underpenetrated community hospital settings in the United States Sun Belt where neuro-oncology fellowship scarcity limits incumbent protocol enrollment capacity. Pursue go-to-market angles through GPO contracts managers rather than direct hospital sales forces to bypass established IDN relationships. For Investors and Strategic Acquirers: Academic medical center spin-outs with GMP-compliant cell therapy facilities represent the highest-conviction acquisition target archetype given manufacturing slot scarcity and national referral network control. Long-term viability framing emphasizes radioligand therapy platform economics over small-molecule oncology given isotope supply concentration moats. Monitor FDA accelerated approval pathway expansion for pediatric brain malignancies as inflection indicator for platform valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| CAR-T Manufacturing Scale-Up | Reduces vein-to-vein timelines for recurrent glioblastoma candidates at Johns Hopkins and UCSF facilities. |
| Radioligand Therapy Licensing Agreement | Secures cyclotron capacity access for meningioma protocols amid isotope supply concentration. |
| AI-Augmented Surgical Planning Partnership | Integrates intraoperative MRI navigation with machine learning segmentation at academic medical centers. |
| Precision Medicine Network Expansion | Extends liquid biopsy profiling into community oncology practices through Roche companion diagnostic platforms. |
| Reimbursement Strategy Development | Navigates Germany's AMNOG process for added-benefit ratings in recurrent glioblastoma indications. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with neuro-oncology department chairs, hospital procurement directors, GPO contracts managers, and regulatory affairs leads at EMA and FDA; and secondary validation against FDA breakthrough therapy designation filings, EMA centralized marketing authorization submissions, ClinicalTrials.gov glioblastoma protocol registries, and hospital procurement database records. Bottom-up patient-flow modeling triangulated with top-down pharmaceutical revenue segmentation across treatment modalities.
Forecast inputs considered therapy line positioning, administration route migration patterns, biomarker-driven patient stratification adoption curves, and regional regulatory cluster differentiation across the analysis window. Segmentation dimensions modeled include product type maturity, end-user infrastructure tier, treatment modality technology generation, and administration route physiology constraints. CAGRs derived from weighted scenario analysis of immunotherapy trial enrollment trajectories and tumor-treating field device penetration curves in aging demographic markets.
Practitioners should monitor radiopharmaceutical manufacturing capacity expansion announcements, IDN consolidation pace in United States Midwest markets, and WHO essential medicines list revision cycles for early signals of forecast revision triggers. Forecasts reflect assumptions about blood-brain barrier penetration technology advancement rates and health technology assessment acceptance timelines in European national markets. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Radioactive Iodine Ablation Therapy Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Pompe Disease Treatment Market
Medical Treatment
Vulvovaginal Candidiasis Treatment Market
Medical Treatment
Hypercoagulability Treatment Market
Medical Treatment
Global Fabry Disease Treatment Market
Medical Treatment
Andersen Tawil Syndrome Treatment Market
Medical Treatment
North America Nerve Repair and Regeneration Market
Medical Treatment
Cervical Cancer Treatment Market
Medical Treatment
Lysosomal Storage Disease Treatment Market
Medical Treatment
Rotator Cuff Injury Treatment Market
Medical Treatment
Systemic Sclerosis Treatment Market
Medical Treatment
Endovenous Laser Therapy Market
Medical Treatment
Anti-Rickettsial Treatment Market
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
Europe Nerve Repair and Regeneration Market