
 Non-Invasive Surgery Market | 2026-2036
Non-Invasive Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Invasive Surgery Market Analytics
North American medical device manufacturers is pivoting toward compact, office-based non-invasive surgical platforms. Medtronic leverages its integrated surgical ecosystem to control distribution across ambulatory settings. Intuitive Surgical dominates robotic-assisted procedures through sustained R&D intensity in minimally invasive platforms. Johnson & Johnson anchors its position through backward integration into advanced energy devices for soft-tissue applications.
Non-invasive surgery encompasses therapeutic interventions performed without incisions or body cavity entry, typically employing directed energy modalities such as radiofrequency, focused ultrasound, or coherent light within wavelength-specific parameters to achieve tissue modification or destruction. These procedures serve primarily to reduce perioperative risk, shorten recovery intervals, and lower infection rates relative to conventional open or laparoscopic techniques. Robotic surgery systems command the largest installed base and associated service revenue pools across hospital networks. Radiofrequency technology captures expanding utilization in cardiac ablation and pain management applications where thermal precision matters. Ambulatory surgery centers represent the fastest-growing end-user channel as payers redirect lower-acuity procedures away from inpatient settings.
FDA premarket notification pathways and ISO 13485 quality management standards govern device commercialization, with the former dictating clinical evidence requirements and the latter shaping manufacturing process controls for multi-site production. The EU Medical Device Regulation imposes stricter post-market surveillance obligations on manufacturers seeking CE-marked access. Stakeholders must monitor reimbursement coding decisions by national health technology assessment bodies, as these determinations directly dictate provider adoption velocity across hospital and outpatient environments.
Market Dynamics
Hospital procurement departments are consolidating vendor relationships around integrated surgical platforms that bundle capital equipment with disposable consumables and long-term service contracts, compressing supplier margins while locking in multi-year revenue streams for platform owners.
Growth Catalysts
- EU Medical Device Regulation:Stricter post-market surveillance obligations accelerate replacement cycles for legacy devices as manufacturers refresh product portfolios to maintain CE-marked access across German and French hospital networks.
- Ambulatory surgery centers:Payer-driven site-of-service shifts redirect lower-acuity procedures from inpatient wards to outpatient facilities, expanding addressable volume for compact non-invasive platforms.
- Radiofrequency thermal precision:Cardiac electrophysiology and interventional pain management protocols standardize around temperature-controlled ablation, displacing older cryogenic methods in US teaching hospitals.
Market Restraints
- Capital intensity:Robotic-assisted surgical systems require seven-figure upfront investment plus annual service contracts, limiting penetration to well-capitalized health systems and constraining mid-tier hospital adoption.
- Supply concentration:High-purity optical fibers and specialized radiofrequency generators depend on Japanese and German component suppliers, exposing manufacturers to geographic concentration risk.
- Reimbursement lag:National health technology assessment bodies in multiple jurisdictions delay coding decisions for novel ablation modalities, stretching provider payback periods.
Strategic Opportunities
- Office-based surgical suites:Dermatology and ophthalmology practices in the United States seek compact laser and ultrasound platforms that bypass hospital facility fees entirely.
- Focused ultrasound-neurology convergence:Blood-brain barrier disruption protocols for Alzheimer's and Parkinson's therapeutics open neurodegenerative applications beyond established oncology use cases.
- India's PLI scheme:Production-linked incentives for medical device manufacturing attract component suppliers to establish domestic assembly, reducing landed cost for price-sensitive South Asian markets.
Industry Challenges
- Electrophysiology fellowship pipeline:Training programs produce insufficient operators to match installed base expansion, creating utilization bottlenecks for cardiac ablation systems.
- ISO 13485 audit complexity:Multi-site manufacturing footprints require harmonized quality management across cleanroom facilities, extending certification timelines for platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Invasive Surgery Market |
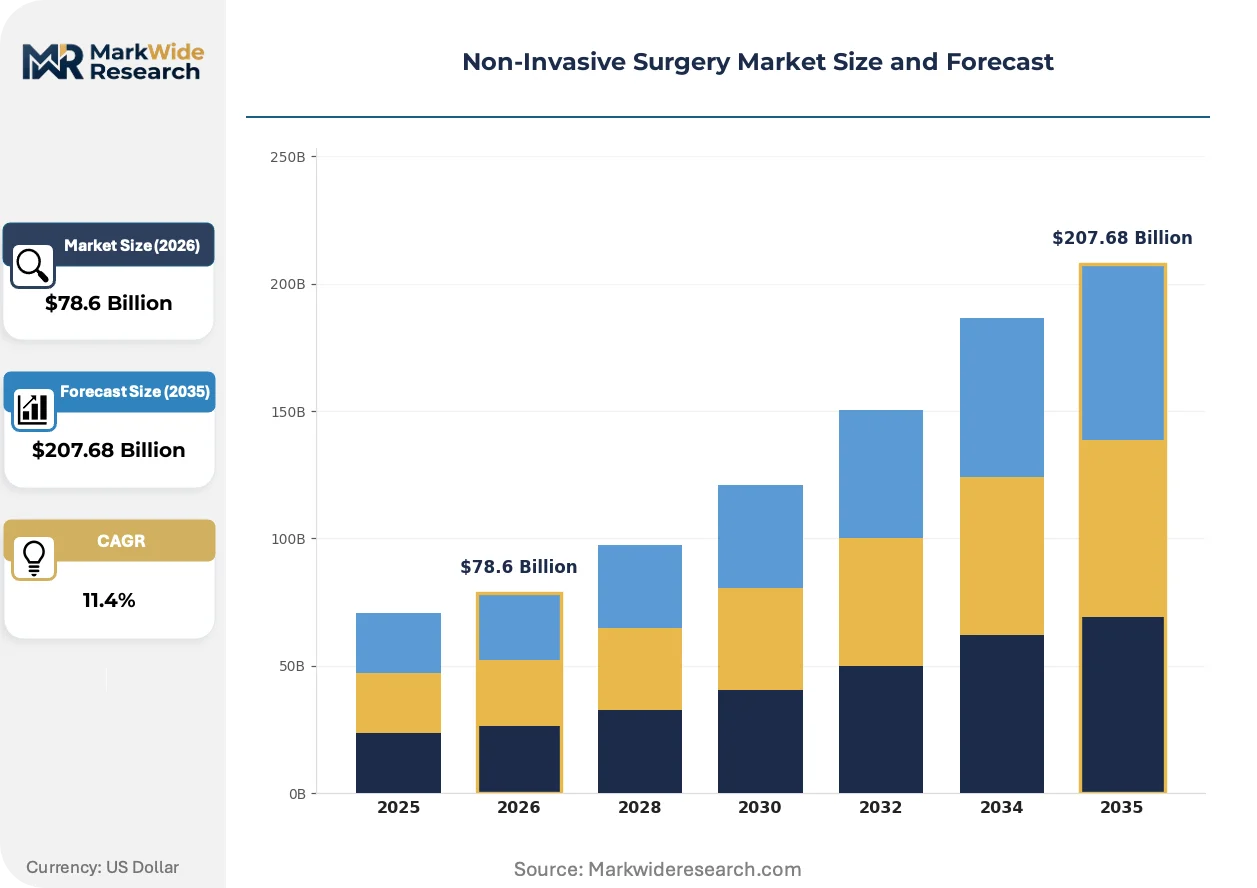
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $207.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Surgery, Robotic Surgery, Endoscopic Surgery, Thermal Ablation Technology: Ultrasound, Electromagnetic, Photonic, Radiofrequency Application: Cardiology, Oncology, Gastroenterology, Urology End User: Hospitals, Ambulatory Surgery Centers, Clinics, Research Institutions |
| Companies Covered | Medtronic, Johnson & Johnson, Stryker, Intuitive Surgical, Olympus Corporation, Boston Scientific Corporation, Siemens Healthineers, Zimmer Biomet, Koninklijke Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Invasive Surgery Market Evolving Landscape
Real-time tissue feedback mechanisms and artificial intelligence-guided targeting are compressing procedure variability while expanding treatable patient populations beyond traditional selection criteria.
Electromagnetic navigation systems for catheter-based interventions are integrating with pre-procedural imaging to enable three-dimensional trajectory planning without fluoroscopic guidance. Academic medical centers in the United States and Germany are piloting these platforms for complex arrhythmia cases. The technology is integrating surgical planning software with intraoperative robotics, collapsing the distinction between diagnostic imaging and therapeutic delivery.
FDA premarket notification pathways for breakthrough device designation are compressing clinical evidence requirements for novel energy modalities. Manufacturers submit smaller patient cohorts for electromagnetic ablation and histotripsy platforms. Cardiac and urological applications receive priority review slots, accelerating competitive entry against established thermal technologies.
Service contract unbundling is fragmenting traditional vendor-hospital relationships as procurement departments negotiate equipment and maintenance separately. Independent service organizations now capture 15-20% of robotic system maintenance in mature US markets. German university hospital networks are replicating this model, pressuring original equipment manufacturers to defend attachment rates through software exclusivity rather than hardware lock-in.
Non-Invasive Surgery Market Segmentation
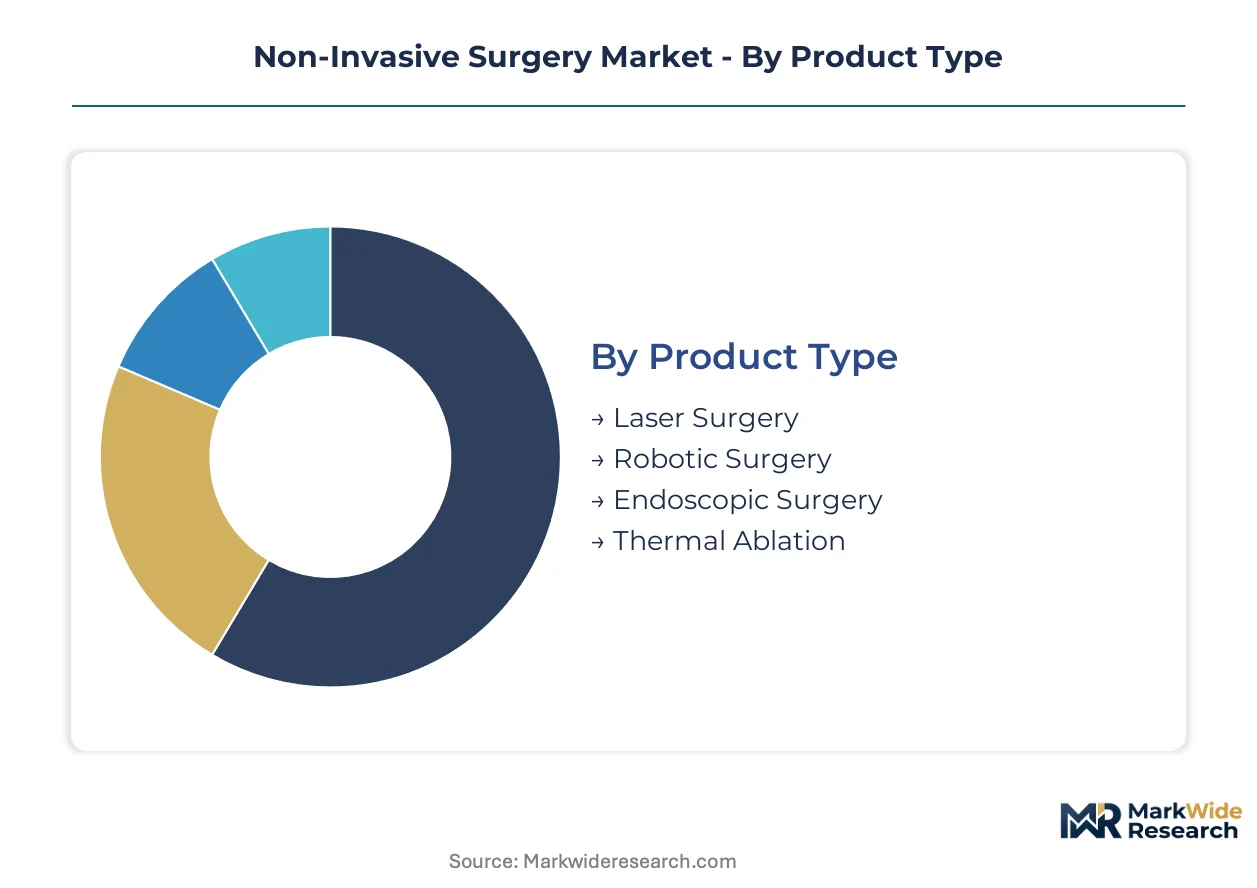
Segmentation reveals divergent capital requirements and adoption timelines across the non-invasive surgery landscape. Equipment-heavy modalities demand distinct financing structures compared to disposable-centric platforms, shaping how vendors structure contracts and how providers evaluate payback periods.
Product Type:
Capital intensity varies dramatically across surgical platforms, with robotic systems requiring the steepest upfront commitment while thermal ablation devices offer lower barriers to entry.
- Robotic Surgery:Multi-arm platforms with haptic feedback and 3D visualization capabilities dominate complex procedures. Demand concentrates in US academic medical centers where fellowship-trained surgeons drive utilization rates and service contract renewals.
- Laser Surgery:Coherent light systems operating at wavelength-specific parameters enable precise tissue modification without thermal diffusion. German university hospital networks standardize these platforms for ophthalmology and dermatology applications where micron-level accuracy determines outcomes.
- Endoscopic Surgery:Flexible insertion systems with integrated imaging channels serve gastrointestinal and pulmonary interventions.
- Thermal Ablation:Temperature-controlled tissue destruction devices address cardiac arrhythmias and pain management protocols.
Robotic surgery absorbs the bulk of installed capacity; thermal ablation is expanding most quickly.
Technology:
Energy modality selection determines regulatory pathway complexity and reimbursement coding stability across target applications.
- Radiofrequency:Alternating current generates controlled thermal lesions with real-time impedance monitoring. Cardiac electrophysiology labs in US teaching hospitals displace cryogenic methods as temperature-controlled protocols standardize ablation workflows.
- Photonic:Laser and LED platforms deliver wavelength-selective energy for tissue cutting and coagulation. French hospital networks prioritize these systems for retinal procedures where thermal precision prevents collateral damage.
- Ultrasound:High-frequency mechanical waves enable imaging-guided therapeutic delivery.
- Electromagnetic:Magnetic field-based navigation and ablation systems integrate with pre-procedural imaging.
Radiofrequency captures the largest procedure volume; electromagnetic platforms are gaining share fastest.
Application:
Clinical specialty dictates reimbursement rates, regulatory evidence requirements, and operator training pipeline availability.
- Cardiology:Arrhythmia ablation and structural heart interventions drive recurring procedure demand. Ambulatory surgery centers in the United States redirect lower-acuity electrophysiology cases from inpatient wards to capture site-of-service differentials.
- Oncology:Tumor ablation and intraoperative margin assessment command premium reimbursement. Japanese tertiary centers adopt focused ultrasound for liver and prostate applications where thermal mapping preserves organ function.
- Urology:Benign prostatic hyperplasia and renal mass ablation procedures.
- Gastroenterology:Endoscopic mucosal resection and submucosal dissection techniques.
Cardiology anchors current revenue pools; oncology applications show the steepest expansion trajectory.
End User:
Facility type determines equipment footprint constraints, staffing models, and payer mix exposure.
- Hospitals:Integrated health systems amortize seven-figure capital investments across high-volume service lines. Procurement departments bundle robotic platforms with disposable contracts and multi-year service agreements to compress supplier margins.
- Ambulatory Surgery Centers:Freestanding facilities prioritize compact, office-compatible platforms that bypass hospital facility fees entirely. US dermatology and ophthalmology practices drive demand for portable laser systems.
- Clinics:Specialty practices with limited procedure rooms require mobile equipment configurations.
- Research Institutions:Academic medical centers pilot novel energy modalities and train operator pipelines.
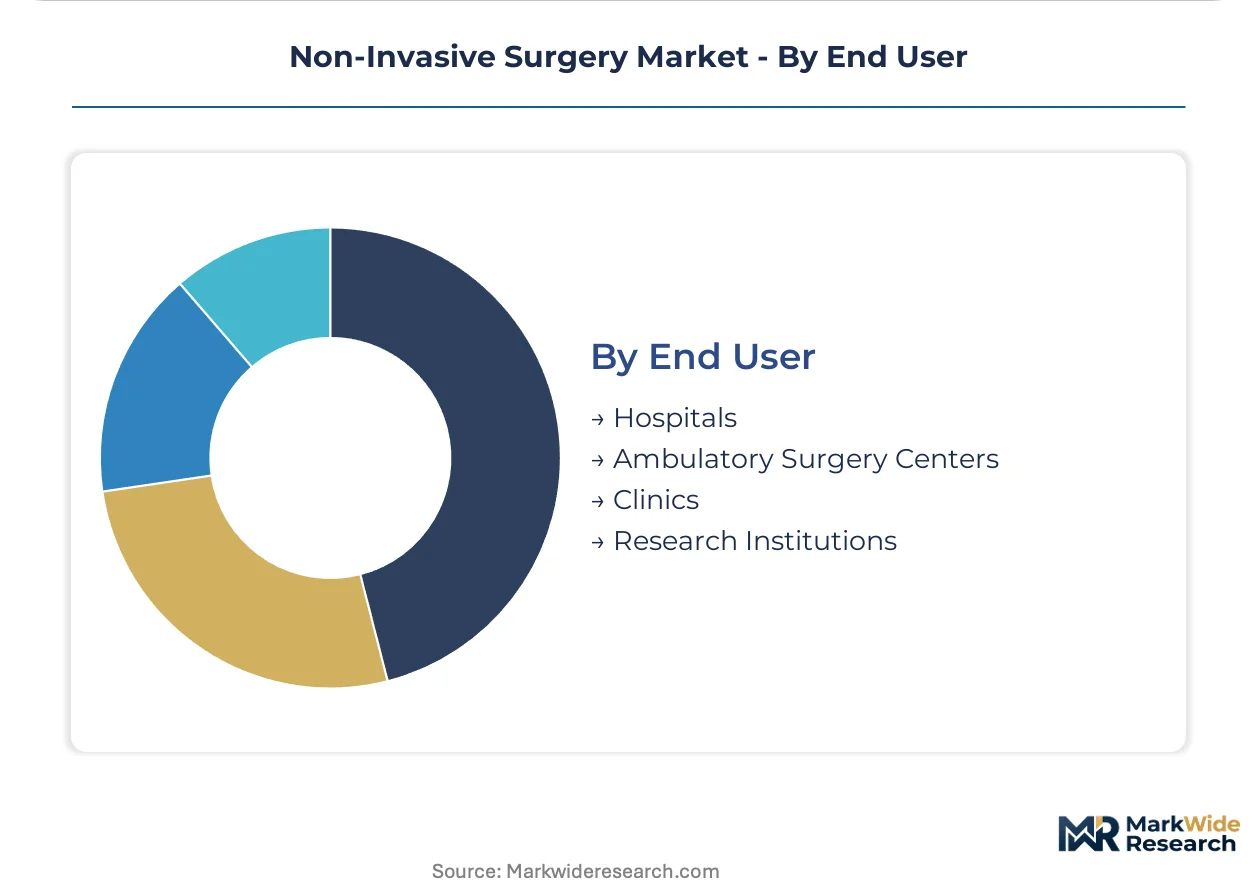
Hospitals retain the dominant installed base; ambulatory surgery centers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision optics manufacturers supply high-purity laser fibers anchoring European non-invasive surgery equipment production. Japanese component fabricators dominate specialized radiofrequency generator supply. United States hospital networks drive installed base expansion through bundled procurement contracts.
United States
Ambulatory surgery centers redirect cardiac ablation and pain management procedures from inpatient wards to capture site-of-service reimbursement differentials. FDA breakthrough device designation compresses clinical evidence requirements for novel electromagnetic ablation platforms. The Greater Boston cluster anchors electrophysiology training programs that feed operator pipelines across academic medical centers.
Germany
University hospital networks standardize laser platforms for ophthalmology and dermatology applications requiring micron-level thermal precision. EU Medical Device Regulation post-market surveillance obligations accelerate replacement cycles for legacy surgical equipment. The Baden-Württemberg industrial corridor concentrates precision optics manufacturing for coherent light delivery systems.
Japan
Tertiary centers adopt focused ultrasound for liver and prostate oncology applications where thermal mapping preserves organ function. PMDA regulatory pathways prioritize review for histotripsy and electromagnetic navigation platforms. The Nagoya manufacturing belt supplies high-purity optical fibers and specialized radiofrequency components to global device assemblers.
India
Production-linked incentive schemes attract component suppliers to establish domestic assembly operations for price-sensitive South Asian markets. CDSCO regulatory harmonization with international standards accelerates import substitution for surgical consumables. The Maharashtra-Gujarat pharmaceutical corridor expands cleanroom manufacturing capacity for disposable ablation catheters.
United Kingdom
NHS England procurement frameworks bundle capital equipment with long-term service contracts across integrated care systems. MHRA post-Brexit regulatory autonomy enables accelerated approval pathways for novel energy modalities. The Cambridge-Oxford-London triangle anchors surgical robotics R&D partnerships between academic medical centers and device manufacturers.
Non-Invasive Surgery Market Competitive Landscape
Global majors compete with regional champions across integrated platform ecosystems versus specialized component supply. The vendor base organizes around three tiers: diversified conglomerates controlling full surgical workflows, mid-scale specialists dominating single energy modalities, and emerging challengers attacking price-sensitive ambulatory segments. Consolidated procurement departments favor bundled contracts that lock in disposable consumables and multi-year service agreements. Competitive positioning hinges on backward integration into advanced energy devices and software exclusivity that defends attachment rates against independent service organizations.
Within the diversified conglomerate tier, Medtronic leverages its integrated surgical ecosystem to control distribution across ambulatory settings. Johnson & Johnson anchors its position through in-house production of advanced energy devices for soft-tissue applications. Intuitive Surgical exemplifies the platform-centric archetype through sustained R&D intensity in robotic-assisted minimally invasive systems. These three entities represent contrasting strategic postures: ecosystem breadth, upstream component control, and focused platform dominance respectively.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Stryker |
| Intuitive Surgical |
| Olympus Corporation |
| Boston Scientific Corporation |
| Siemens Healthineers |
| Zimmer Biomet |
| Koninklijke Philips |
| Others |
Value Network & Pricing Analysis
High-purity optical fiber costs cascade through robotic surgical system pricing tiers, with Japanese and German component suppliers commanding premium positioning for coherent light delivery systems while Indian assembly operations undercut landed costs for price-sensitive South Asian markets.
Pricing Analysis
Service contract unbundling now separates multi-year maintenance agreements from capital equipment purchases, with independent service organizations capturing 15-20% of robotic system maintenance in mature US markets. Pricing stratifies across premium, standard, and economy tiers based on software exclusivity bundles and ISO 13485 certification levels. Cost compression in mid-tier thermal ablation devices is intensifying as procurement departments negotiate disposable consumables separately from hardware. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers prioritize performance specifications over unit economics.
Supply Chain Analysis
India's PLI scheme for medical device manufacturing is reshaping sourcing patterns, attracting component suppliers to establish domestic cleanroom assembly for disposable ablation catheters. Supply concentrates in Japan for specialized radiofrequency generators, Germany for precision laser optics, and the United States for integrated robotic platforms. Raw material dependencies include high-purity silica fibers, rare-earth doping elements, and biocompatible catheter polymers. Single-source vulnerability from Japanese component fabricators exposes manufacturers to geographic concentration risk. Distribution runs through hospital procurement departments consolidating vendor relationships around bundled contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-invasive surgery market is becoming a vertical-integration race, with control over advanced energy devices and software exclusivity determining who captures multi-year service revenue streams.
For Market Incumbents: Deepen backward integration into radiofrequency generator and optical fiber production to defend margins against independent service organizations. Lock in hospital system relationships through software exclusivity that prevents unbundling of maintenance contracts, while expanding CE-marked product portfolios to satisfy EU Medical Device Regulation post-market surveillance obligations. For New Entrants and Emerging Players: Launch via direct-to-ambulatory-surgery-center distribution models that bypass hospital procurement consolidation. Target office-based dermatology and ophthalmology suites in the United States with compact laser platforms, and exploit India's PLI scheme for cost-competitive manufacturing of disposable thermal ablation catheters. For Investors and Strategic Acquirers: FDA breakthrough device designation for electromagnetic ablation platforms is the leading indicator that novel energy modalities are achieving accelerated regulatory pathways. Focus acquisition screening on mid-scale specialists with captive supply of high-purity optical components and established ISO 13485 quality management systems. Watch for independent service organization market share expansion as a signal of platform commoditization pressure.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU Medical Device Regulation compliance unlocks German and French hospital network access. |
| Hospital System Partnership | Bundled procurement contracts with integrated health systems lock in multi-year disposable revenue. |
| Software Companion Development | AI-guided targeting and real-time tissue feedback defend service contract attachment rates. |
| Backward Integration into Energy Devices | In-house production of radiofrequency generators compresses supplier margins and secures component supply. |
| Reimbursement Strategy | Coding decisions by national health technology assessment bodies dictate provider adoption velocity. |
Research Methodology
Document review covered FDA 510(k) premarket notification databases, EU Medical Device Regulation technical documentation, and hospital procurement contract records, complemented by interviews with electrophysiology fellowship directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from ISO 13485 audit reports, CMS Medicare reimbursement coding decisions, and Japanese PMDA approval filings. Bottom-up installed base modeling and top-down expenditure flow analysis were triangulated against manufacturer service revenue disclosures.
Segment-level outputs across the projection horizon reflect equipment type, energy modality, clinical application, and end-user facility category. The analytical framework incorporated operator training pipeline constraints, regulatory pathway complexity differentials, and site-of-service shift elasticities. CAGRs were derived from procedure volume trajectories and capital equipment replacement cycle assumptions, with cross-validation against academic medical center capital expenditure surveys and ambulatory surgery center formation rates.
The model assumes a particular technology adoption path; alternative pathways for electromagnetic navigation and histotripsy platforms would alter the outlook if FDA breakthrough device designation criteria expand or contract. Forecasts reflect assumptions regarding reimbursement coding stability, fellowship training program expansion rates, and supply chain geographic diversification timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Merkel Cell Carcinoma (MCC) Treatment Market
Medical Treatment
Nasal Allergy Treatment Market
Medical Treatment
Motion Sickness Treatment Market
Medical Treatment
Global Systemic Lupus Erythematosus Treatment Market
Medical Treatment
Penile Cancer Treatment Market
Medical Treatment
Familial Hypercholesterolemia Treatment Market
Medical Treatment
Myotonic Dystrophy Treatment Market
Medical Treatment
Peanut Allergy Treatment Market
Medical Treatment
Histoplasmosis Treatment Market
Medical Treatment
Tetanus Treatment Market
Medical Treatment
Angioedema Treatment Market
Medical Treatment
Cleft Lip Surgery Market
Medical Treatment
Birch Allergy Treatment Market
Medical Treatment
Pelvic Organ Prolapse Repair Market
Medical Treatment
Systemic Mastocytosis Treatment Market
Medical Treatment
Postoperative Nausea and Vomiting (PONV) Management Market