
 Aspergillosis Treatment Market | 2026-2036
Aspergillosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Aspergillosis Treatment Market Outlook
Hospital-centric purchasing of intravenous antifungals is unwinding as specialty clinics and home care settings gain share under value-based reimbursement models. Pfizer leverages its manufacturing scale to dominate hospital pharmacy supply chains for parenteral formulations. Merck & Co. anchors its position through R&D intensity in novel echinocandin derivatives. Astellas Pharma differentiates via geographic dominance in Japanese transplant centers where prophylactic protocols are most advanced.
Aspergillosis treatment encompasses pharmaceutical interventions targeting invasive, chronic, and allergic pulmonary infections caused by Aspergillus species, with azoles inhibiting fungal ergosterol synthesis through cytochrome P450-dependent lanosterol demethylation. These therapies serve primarily to reduce mortality in immunocompromised hosts including stem cell and solid organ transplant recipients. Azoles occupy the largest revenue pool due to oral bioavailability and outpatient suitability, while echinocandins represent the fastest-growing class driven by azole-resistant Aspergillus fumigatus emergence. Combination therapy segments command premium positioning where salvage protocols in refractory disease justify higher therapeutic intensity.
The FDA's qualified infectious disease product designation and EMA's PRIME scheme for unmet medical needs shape clinical trial investment and accelerated market access for novel antifungal agents. REACH and FDA good manufacturing practice standards enforce stringent purity specifications for active pharmaceutical ingredients and finished dosage forms, elevating compliance costs for generic entrants. Stakeholders must monitor resistance surveillance data from the CDC and ECDC to anticipate shifts in first-line therapy recommendations and corresponding procurement volumes.
Market Dynamics
Azole resistance surveillance is compressing first-line therapy duration and accelerating combination protocol adoption across transplant centers, fundamentally altering pharmaceutical procurement volumes and inventory management practices.
Growth Catalysts
- Orphan Drug Incentives:The FDA's qualified infectious disease product designation reduces clinical trial costs and accelerates approval timelines for novel antifungal agents targeting refractory aspergillosis strains.
- Stem Cell Transplant Volume:Rising allogeneic hematopoietic stem cell procedures in the United States, Germany, and Japan expand the immunocompromised patient pool requiring prophylactic azole therapy.
- Resistance Surveillance Networks:CDC and ECDC molecular tracking programs identify emerging Aspergillus fumigatus resistance patterns, driving therapeutic protocol updates and replacement drug demand.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for triazole antifungals concentrates in Chinese and Indian chemical clusters, exposing finished dose producers to geopolitical disruption and customs delays.
- Hepatotoxicity Monitoring Burden:Cytochrome P450 drug-drug interaction profiles and liver enzyme surveillance requirements limit outpatient prescribing flexibility and expand specialist referral volumes.
- Diagnostic Latency:Galactomannan antigen testing and PCR confirmation delays prolong empirical therapy initiation, compressing addressable therapeutic windows and treatment completion rates.
Strategic Opportunities
- Home Infusion Services:Specialty pharmacy networks and ambulatory infusion centers in the United States capture echinocandin administration previously confined to inpatient settings, reducing per-dose facility fees.
- Companion Diagnostics:Pharmacogenomic screening for CYP2C19 polymorphisms enables voriconazole dose personalization, differentiating precision medicine offerings in high-volume transplant programs.
- Biosimilar Echinocandins:EMA biosimilar guidance and FDA interchangeability standards create pathway for generic caspofungin and micafungin entrants to capture expired patent volume in European hospital formularies.
Industry Challenges
- Antifungal Stewardship Compliance:Institutional protocols restricting broad-spectrum azole empiricism require clinical pharmacy specialists to justify every therapeutic course against microbiology confirmation.
- Cold Chain Integrity:Liposomal amphotericin B and echinocandin formulations demand continuous 2-8°C storage through last-mile distribution to home care settings, elevating logistics complexity and spoilage risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aspergillosis Treatment Market |
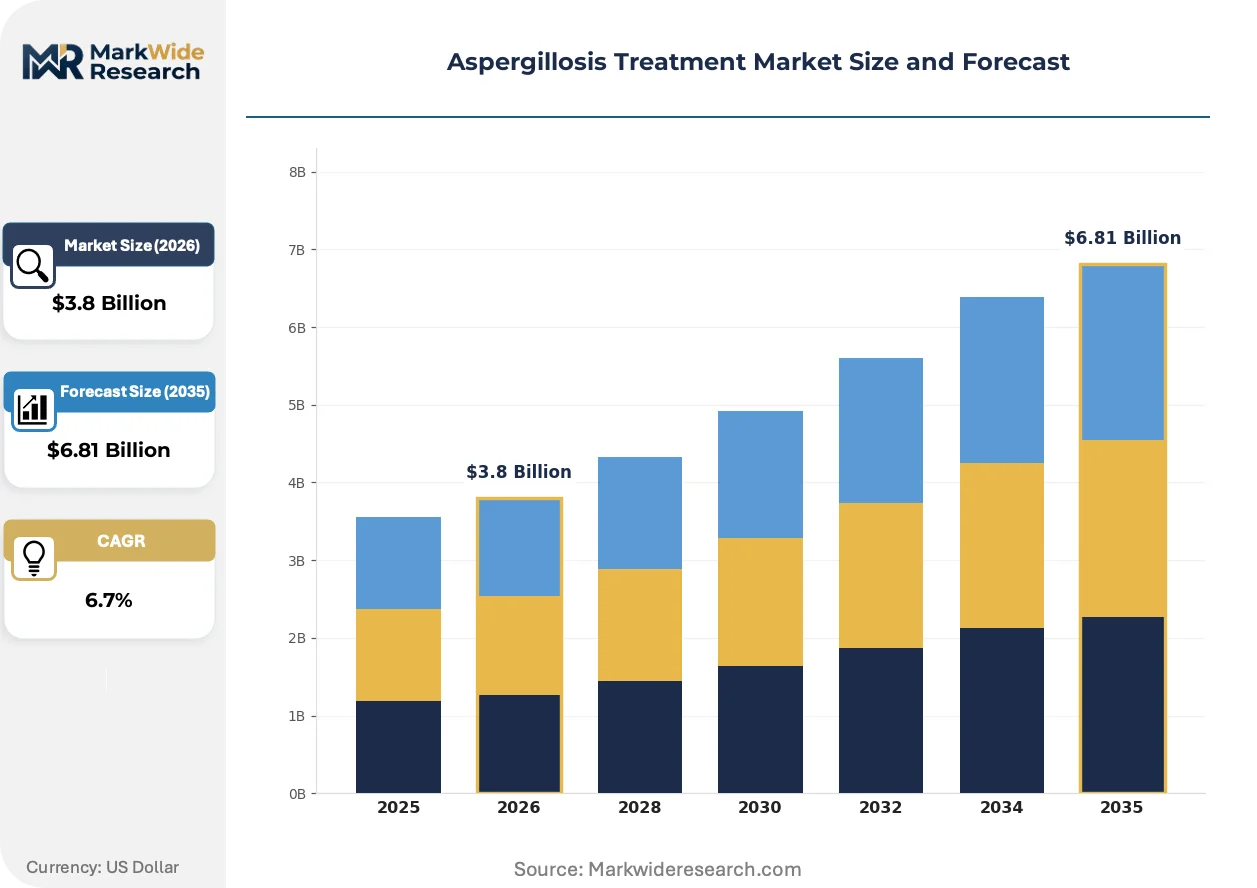
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Azoles, Echinocandins, Polyenes, Combination Therapy End User: Hospitals, Specialty Clinics, Home Care Settings, Research Laboratories Administration Route: Oral, Intravenous, Inhalation, Topical Distribution Channel: Hospital Pharmacies, Retail Pharmacies, E-commerce, Wholesalers |
| Companies Covered | Pfizer, Merck & Co., Astellas Pharma, Novartis AG, Bayer AG, GlaxoSmithKline, Abbott Laboratories, Gilead Sciences, F2G, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aspergillosis Treatment Market Strategic Shifts
Antifungal development pipelines are pivoting toward resistance-agnostic mechanisms and oral bioavailability improvements that enable earlier hospital discharge and prolonged outpatient suppression therapy.
Next-generation tetrazole and isavuconazole derivatives are bifurcating the azole class into broad-spectrum empiric options and narrow-spectrum salvage agents. Transplant infectious disease specialists at major academic medical centers are adopting these agents for CYP2C19 poor metabolizers and prior triazole failures. This molecular stratification is compressing traditional one-size-fits-all protocol designs and forcing formulary committees to maintain parallel inventory tiers.
REACH authorization requirements for active pharmaceutical ingredient impurities are tightening acceptable limits for genotoxic nitrosamines and residual solvents. European manufacturers must retrofit synthesis pathways or qualify alternative suppliers to maintain EMA marketing authorization. Finished dose producers serving EU markets are absorbing validation costs through selective portfolio pruning of legacy azole formulations with non-compliant supply chains.
Specialty pharmacy carve-out contracts are displacing traditional hospital pharmacy purchasing for oral antifungal maintenance therapy. United States payers are directing transplant recipients to limited distribution networks that manage prior authorization, adherence monitoring, and laboratory scheduling as bundled services. This channel migration is most advanced in Medicare Advantage plans covering solid organ transplantation in Florida, Texas, and California metropolitan clusters.
Aspergillosis Treatment Market Segmentation
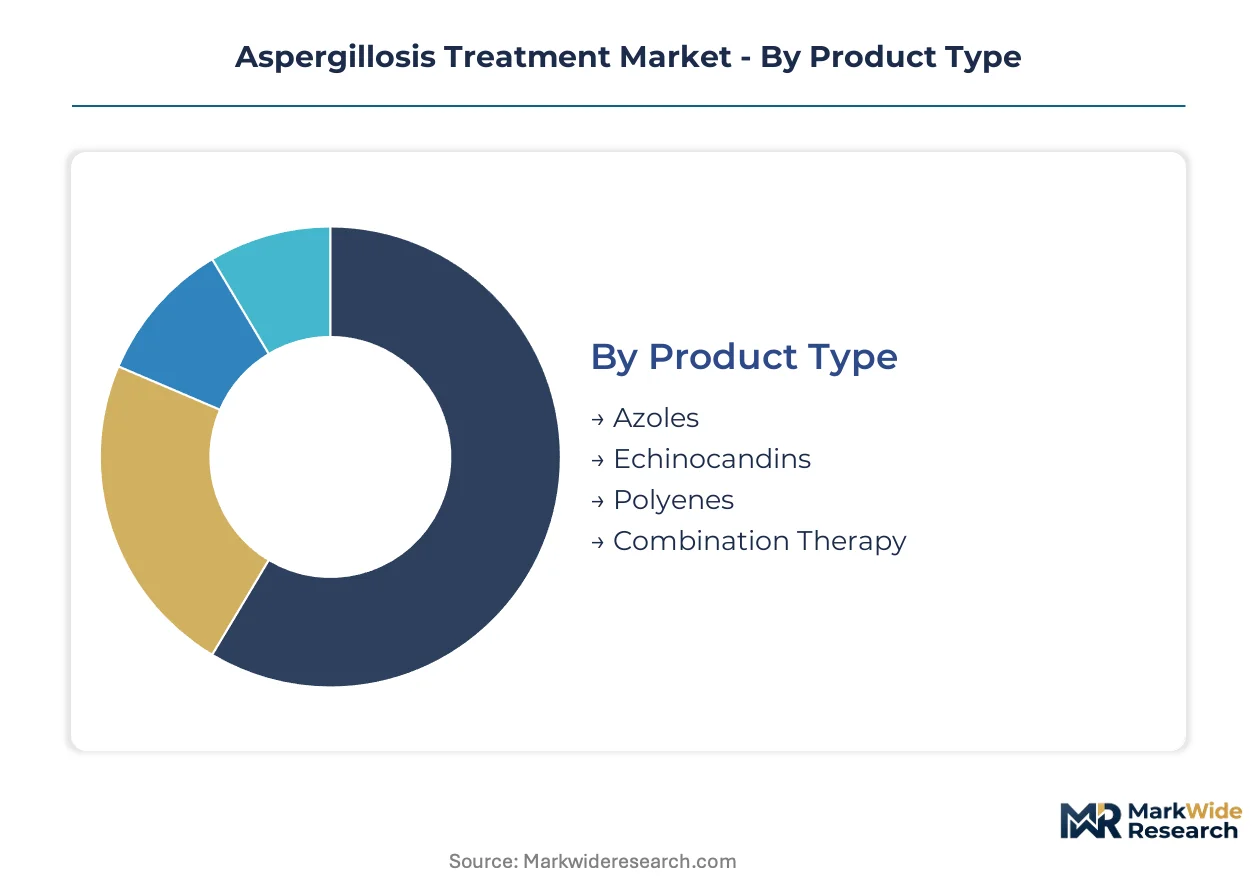
Segmentation in aspergillosis treatment reveals how resistance patterns, site-of-care economics, and reimbursement rules reshape procurement across molecular classes and delivery settings. Understanding these divides exposes where formulary committees face the toughest substitution decisions.
Product Type:
Azoles face the most acute substitution pressure as echinocandins and novel polyenes encroach on first-line protocols amid rising Aspergillus fumigatus resistance.
- Azoles:Triazole antifungals inhibit ergosterol synthesis through cytochrome P450-dependent lanosterol demethylation. Demand concentrates in United States and German transplant centers where oral bioavailability enables outpatient prophylaxis, though hepatotoxicity surveillance requirements limit primary care prescribing flexibility.
- Echinocandins:These agents disrupt fungal cell wall synthesis by inhibiting β-1,3-D-glucan synthase. Japanese hematology wards and United States academic medical centers drive consumption as azole salvage therapy, with liposomal formulations gaining share in refractory invasive disease protocols.
- Polyenes:Amphotericin B derivatives bind membrane ergosterol to create permeability channels.
- Combination Therapy:Dual-agent regimens pair azoles with echinocandins for refractory cases.
Azoles retain volume leadership; echinocandins hold the steepest expansion curve.
End User:
Cost tier stratification separates high-acuity inpatient settings from lower-cost ambulatory alternatives as payer pressure intensifies.
- Hospitals:Tertiary medical centers manage acute invasive aspergillosis with intravenous echinocandins and liposomal amphotericin B. United States transplant programs in Boston, Houston, and Seattle anchor procurement volumes for empirical therapy initiation.
- Specialty Clinics:Ambulatory infusion centers administer long-acting antifungals under observation protocols. German onco-hematology day clinics and Japanese cancer centers drive adoption of shortened observation windows.
- Home Care Settings:Skilled nursing facilities manage oral azole continuation therapy post-discharge.
- Research Laboratories:Academic medical centers conduct resistance surveillance and clinical trials.
Hospitals dominate absolute spending; specialty clinics are expanding most quickly as site-of-care migration accelerates.
Administration Route:
Application logic governs this split: acute severity demands intravenous bioavailability while chronic suppression favors oral convenience.
- Oral:Voriconazole and posaconazole tablets enable outpatient maintenance. United States Medicare Advantage plans in Florida and California metropolitan clusters drive volume through specialty pharmacy carve-outs.
- Intravenous:Parenteral formulations deliver therapeutic concentrations in critically ill patients. German and Japanese intensive care units prioritize this route for galactomannan-positive neutropenic fever.
- Inhalation:Nebulized antifungals target localized pulmonary infection.
- Topical:Cutaneous aspergillosis management in burn and wound care settings.
Oral administration captures the largest patient volume; intravenous holds the highest per-dose value concentration.
Distribution Channel:
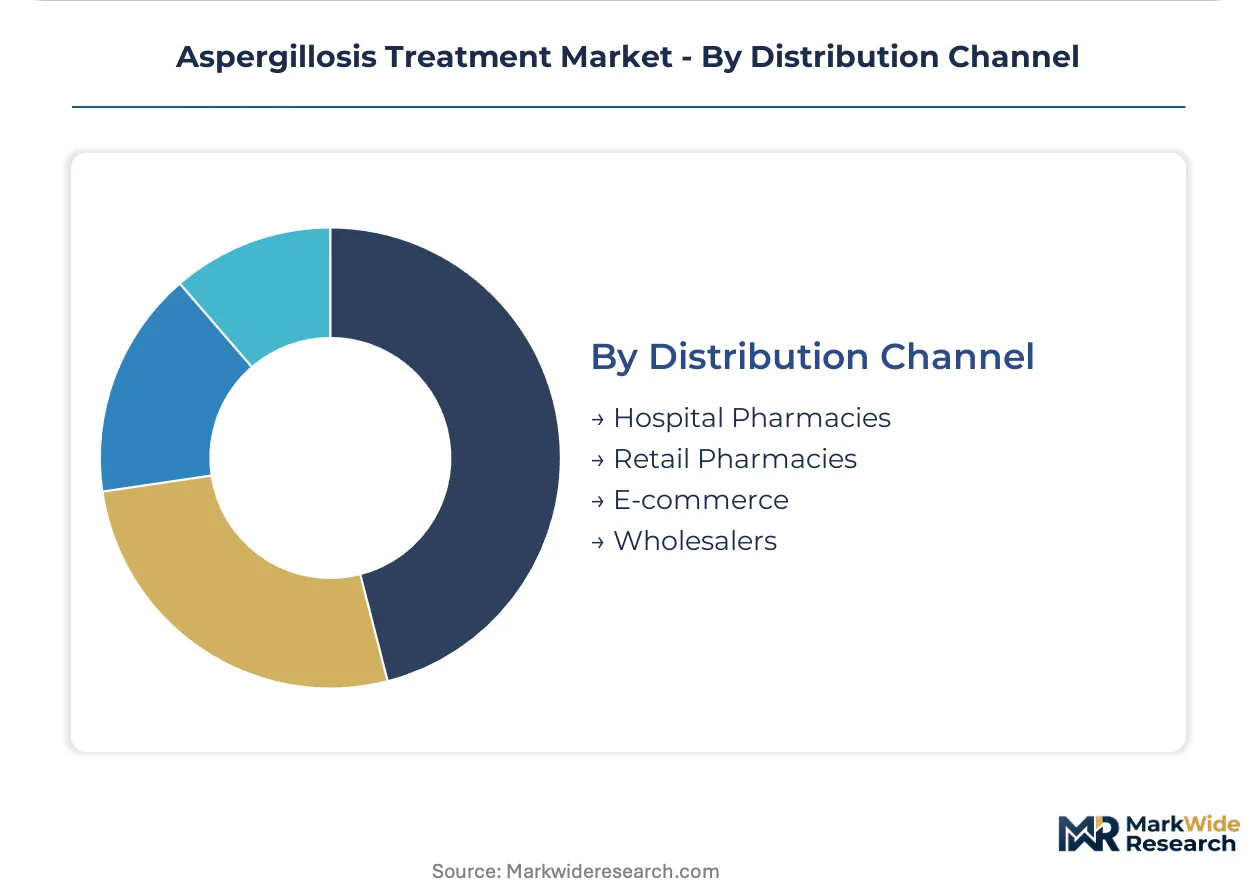
Supply concentration and cold chain requirements determine channel viability for temperature-sensitive biologics versus stable small molecules.
- Hospital Pharmacies:Captive distribution for inpatient echinocandin and liposomal amphotericin B. United States health system formularies in academic medical centers maintain tight inventory control.
- Retail Pharmacies:Community dispensing for oral azole maintenance. German Apotheken and Japanese neighborhood pharmacies handle refill compliance monitoring.
- E-commerce:Direct-to-patient platforms for chronic oral therapy.
- Wholesalers:Three-tier distribution for multi-site health system contracts.
Hospital pharmacies retain the steepest revenue per outlet; specialty pharmacy networks through retail and e-commerce are gaining share fastest in oral maintenance segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian and Chinese active pharmaceutical ingredient manufacturers export triazole intermediates to finished dose producers in the United States, Germany, and Japan, creating a trade-flow corridor that concentrates supply risk in East Asian chemical clusters while demand anchors in Western transplant centers.
United States
Allogeneic hematopoietic stem cell transplant volumes at Boston, Houston, and Seattle academic medical centers drive voriconazole and posaconazole consumption. The FDA's qualified infectious disease product designation accelerates novel antifungal approvals for refractory strains. Medicare Advantage specialty pharmacy carve-outs in Florida and California metropolitan clusters are displacing hospital-based oral azole purchasing.
Germany
Onco-hematology day clinics in Munich and Berlin administer shortened observation window protocols for ambulatory echinocandin infusion. REACH authorization requirements for nitrosamine impurity limits force API supplier requalification. The EMA's PRIME scheme for unmet medical needs channels accelerated assessment resources toward novel azole derivatives.
Japan
Prophylactic antifungal protocols at Tokyo and Osaka transplant centers are the most advanced globally, driving micafungin and liposomal amphotericin B volumes. PMDA consultation programs for orphan drug designation reduce clinical trial burden for resistant aspergillosis indications. METI pharmaceutical supply chain resilience initiatives incentivize domestic API buffer stockpiling.
India
Hyderabad and Ahmedabad chemical clusters manufacture voriconazole and posaconazole intermediates for export to European and North American formulators. CDSCO manufacturing facility inspections enforce data integrity standards for export-oriented production. The country's national pharmaceutical regulator harmonizes with ICH Q7 guidelines to maintain EU and US market access.
United Kingdom
London and Manchester transplant infectious disease units participate in ECDC resistance surveillance networks tracking Aspergillus fumigatus azole resistance patterns. NHS England specialty pharmacy frameworks negotiate bundled oral antifungal maintenance contracts. The MHRA's reliance procedure post-Brexit accelerates EMA-approved antifungal market entry timelines.
Aspergillosis Treatment Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions. The market structure consolidates around three to five multinational pharmaceutical corporations with integrated manufacturing and distribution capabilities, while mid-tier specialists occupy narrow therapeutic niches. Strategic archetypes divide into scale-driven hospital supply contractors, R&D-intensive novel mechanism developers, and regionally focused prophylactic protocol sponsors. Dominant competitive moves include strategic partnerships for companion diagnostic co-development and selective portfolio pruning of legacy formulations with non-compliant supply chains.
Within the scale-driven tier, Pfizer and Merck & Co. exemplify hospital pharmacy supply chain dominance through parenteral formulation manufacturing depth. Astellas Pharma occupies a position as the Japanese market anchor where transplant center relationships concentrate prophylactic protocol influence. These three entities represent the archetype spectrum from global manufacturing scale to regional therapeutic specialization.
| Leading Market Players |
|---|
| Pfizer |
| Merck & Co. |
| Astellas Pharma |
| Novartis AG |
| Bayer AG |
| GlaxoSmithKline |
| Abbott Laboratories |
| Gilead Sciences |
| F2G |
| Others |
Value Chain & Pricing Dynamics
Isavuconazole uptake in United States transplant centers is displacing legacy voriconazole protocols while simultaneously pulling API sourcing toward European fermentation capacity and compressing margins on first-generation triazoles manufactured in Asian chemical clusters.
Pricing Analysis
Next-generation tetrazole derivatives command 40-60% premiums over prior-generation voriconazole and itraconazole formulations, while economy-tier generic posaconazole erodes toward commodity levels. Pricing stratifies across premium novel agents, standard-of-care branded azoles, and economy generic maintenance therapy, with differentiation anchored in CYP2C19 pharmacogenomic compatibility and resistance coverage breadth. Cost compression in the oral maintenance tier intensifies as United States Medicare Advantage plans consolidate specialty pharmacy carve-outs. Academic medical centers show lowest price sensitivity due to protocol rigidity, while skilled nursing facilities face acute budget constraints.
Supply Chain Analysis
Shanghai port congestion and Red Sea transit disruptions expose liposomal amphotericin B formulations to temperature excursion risks during Atlantic crossing. Active pharmaceutical ingredient production clusters in Hyderabad, Ahmedabad, and Zhejiang province feed finished dose manufacturers in the United States, Germany, and Japan. Triazole intermediate synthesis rests on Chinese acetic anhydride and Indian piperazine derivative supply. Single-source vulnerability concentrates in liposomal formulation manufacturing where sterile nanoparticle production requires specialized GMP infrastructure. Distribution runs through hospital pharmacy captive networks for parenteral products and specialty pharmacy limited distribution networks for oral maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aspergillosis treatment market sits in early-cycle expansion as azole-resistant Aspergillus fumigatus strains drive protocol upgrades and combination therapy adoption across transplant centers.
For Market Incumbents: Shield formulary position through backward integration into liposomal formulation manufacturing and captive API buffer stocks. Pfizer and Merck & Co. should secure Indian and Chinese intermediate suppliers under long-term offtake agreements before EMA REACH nitrosamine enforcement tightens further. Vertical control over sterile nanoparticle production represents the critical defensive lever against biosimilar echinocandin entrants. For New Entrants and Emerging Players: Anchor in Japanese prophylactic protocol customization where transplant center relationships concentrate purchasing influence. F2G and mid-tier specialists should target CYP2C19 poor metabolizer subpopulations with pharmacogenomic companion diagnostics bundled to precision dosing platforms. The most penetrable white space sits in home infusion services for ambulatory echinocandin administration. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors R&D-intensive developers with resistance-agnostic mechanisms over scale-driven hospital suppliers. Long-term viability hinges on pipeline depth against emerging azole resistance patterns. Acquisition targets should display clinical-stage tetrazole or novel cell wall-active compounds. The signal to watch is CDC and ECDC surveillance data showing voriconazole breakthrough rates exceeding institutional protocol thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA qualified infectious disease product designation accelerates novel antifungal approval timelines for refractory strains. |
| Companion Diagnostic Development | Pharmacogenomic screening for CYP2C19 polymorphisms enables voriconazole dose personalization in transplant programs. |
| Manufacturing Scale-Up | Liposomal amphotericin B sterile nanoparticle capacity expansion secures supply for refractory invasive disease protocols. |
| Regulatory Approval Pathway | EMA PRIME scheme channels accelerated assessment resources toward novel azole derivatives targeting unmet needs. |
| Specialty Pharmacy Partnership | Medicare Advantage carve-outs in Florida and California consolidate oral antifungal maintenance purchasing power. |
Study Parameters
Operator-level perspectives from transplant infectious disease specialists, hospital formulary directors, specialty pharmacy procurement managers, and antifungal stewardship pharmacists anchored the qualitative base. These primary insights combined with secondary validation from FDA filings, EMA assessment reports, ClinicalTrials.gov protocol databases, and CDC resistance surveillance publications. Bottom-up patient-volume modeling across treatment lines and administration routes triangulated against top-down pharmaceutical revenue estimates.
Sensitivity analysis tested forecast robustness across azole resistance prevalence scenarios and stem cell transplant volume trajectories throughout the projection horizon. The analytical framework segmented by product type, end user, administration route, and distribution channel, with patient population severity and regional regulatory cluster as cross-cutting dimensions. CAGRs derived from logistic diffusion curves modeling novel agent uptake against generic erosion patterns, incorporating EMA REACH compliance cost pass-through and FDA orphan drug incentive effects.
Material uncertainties — resistance surveillance network findings, API supply disruptions, and payer formulary restriction shifts — sit outside the modeled envelope. Forecasts reflect assumptions about protocol persistence and regulatory pathway timelines that empirical validation may revise. Practitioners should keep alternative scenarios live as azole resistance prevalence and transplant center consolidation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
US Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Malaria Treatment Market
Medical Treatment
Pompe Disease Treatment Market
Medical Treatment
Prion Disease Treatment Market
Medical Treatment
Monkeypox Treatment Market
Medical Treatment
Global Hyperhidrosis Treatment Market
Medical Treatment
Mesotherapy Market
Medical Treatment
Precocious Puberty Treatment Market
Medical Treatment
Tissue Repair Technologies Market
Medical Treatment
Global Thyroid Disorder Treatment Market
Medical Treatment
Uterine Fibroid Treatment Drugs Market
Medical Treatment
Bromhidrosis Disease Treatment Market
Medical Treatment
Polycystic Ovary Syndrome (PCOS) Treatment Market
Medical Treatment
Epiglottitis Treatment Market
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Avian Flu Treatment Market