
 Behcet's Disease Treatment Market | 2026-2036
Behcet's Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Behcet's Disease Treatment Market Outlook
Aftermarket patient support and adherence program revenue is fragmenting across competing service models as manufacturers seek stickier relationships beyond the prescription fill. AbbVie leverages its immunology infrastructure to sustain high-touch nursing networks for injectable biologics. Eisai Co. Ltd. anchors its position through specialized distribution partnerships in Asian markets. Novartis AG differentiates via integrated digital monitoring tools that track treatment response between clinic visits.
Behcet's disease treatment encompasses pharmacological interventions targeting systemic vasculitis with mucocutaneous, ocular, and vascular manifestations, primarily employing corticosteroids, immunosuppressants, and biologics that modulate TNF-alpha and interleukin pathways to interrupt autoimmune-mediated endothelial damage. Biologics command the most favorable margin profile among product types due to limited biosimilar penetration and orphan pricing flexibility. TNF inhibitors retain the largest share within drug classes though interleukin inhibitors represent the fastest-expanding category driven by improved ocular outcomes. Intravenous administration routes concentrate in hospital settings while subcutaneous injectable formats enable outpatient and homecare migration.
The FDA's orphan drug program shapes development economics through tax credits and market exclusivity provisions, while the EMA's centralized procedure governs pan-European access for biologic therapies. Japan's PMDA maintains distinct efficacy requirements for mucocutaneous versus ocular endpoints that influence trial design. Stakeholders must monitor evolving interchangeability standards for biosimilars and their potential to compress pricing power in the TNF inhibitor segment.
Market Dynamics
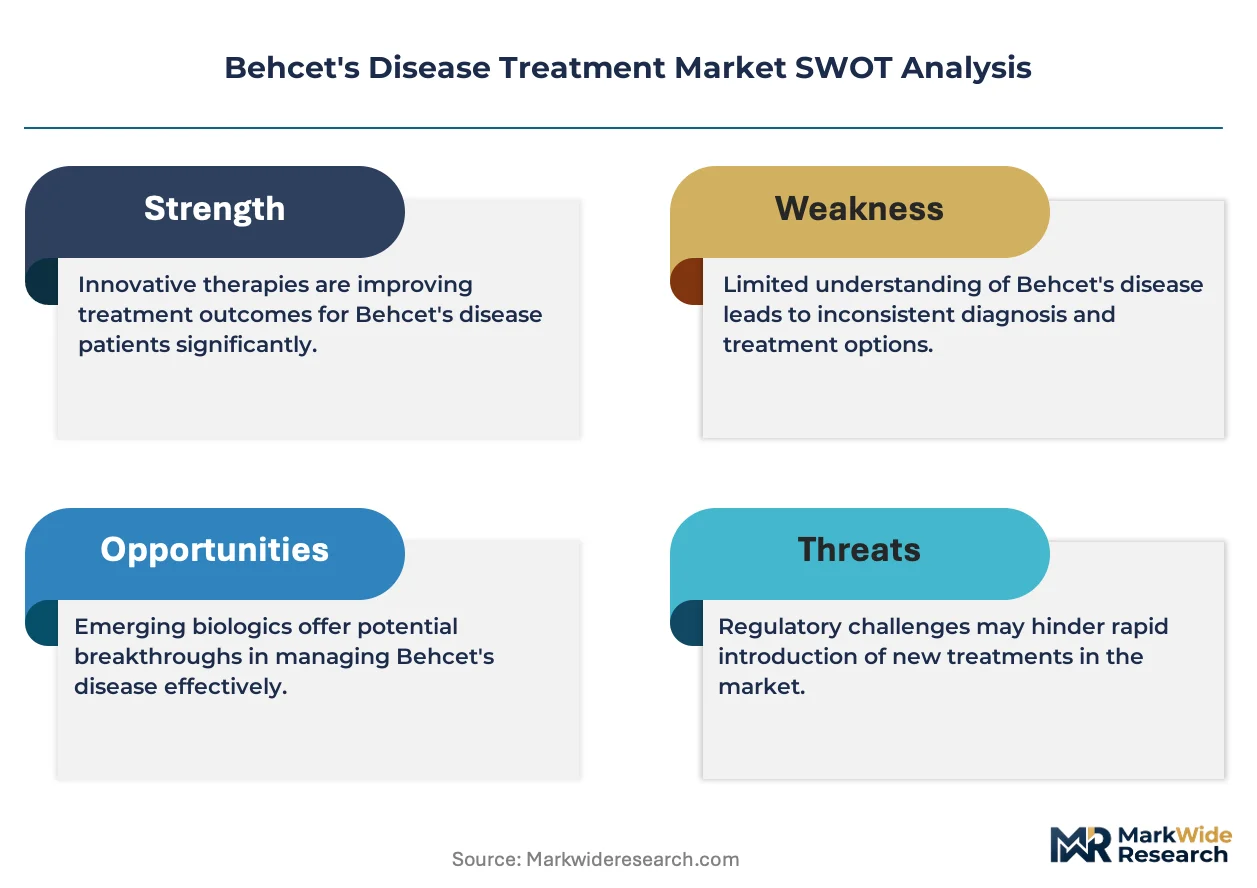
The FDA's orphan drug designation framework is compressing development timelines for rare disease biologics while simultaneously concentrating pricing power among manufacturers with approved interleukin and TNF-alpha pathway inhibitors.
Growth Catalysts
- Orphan Drug Tax Credits:The FDA's 25% clinical trial tax credit reduces net development costs for biologic therapies targeting mucocutaneous and ocular manifestations.
- Specialty Pharmacy Networks:High-touch nursing infrastructure for subcutaneous biologic administration is expanding patient adherence programs beyond hospital settings.
- EMA Centralized Procedure:Pan-European market access through single regulatory submission accelerates reimbursement negotiations across France, Germany, and Italy.
Market Restraints
- Biosimilar Pipeline Concentration:South Korean and Indian contract manufacturers are developing TNF inhibitor biosimilars that threaten originator pricing flexibility.
- Interchangeability Standards:Evolving FDA guidance on automatic pharmacy-level substitution creates uncertainty around brand loyalty for infused biologics.
- Reimbursement Fragmentation:Germany's AMNOG early benefit assessment imposes cost-effectiveness hurdles that delay market access for novel interleukin inhibitors.
Strategic Opportunities
- Digital Therapeutic Adjuncts:Remote monitoring platforms tracking ocular inflammation between clinic visits enable outcome-based contracting with US payers.
- Home Infusion Migration:Subcutaneous formulations are displacing hospital-based intravenous administration, opening specialty pharmacy channel expansion.
- Asian Market Development:Japan's PMDA distinct efficacy requirements for vascular versus mucocutaneous endpoints reward tailored clinical trial designs.
Industry Challenges
- Rare Disease Trial Recruitment:Patient identification for Behcet's disease studies requires specialized rheumatology networks that extend enrollment timelines.
- Cold Chain Integrity:Temperature-controlled distribution for biologics demands redundant logistics infrastructure across secondary and tertiary markets.
- Cross-Border Reimbursement:Divergent health technology assessment methodologies between England's NICE and Scotland's SMC create pricing complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Behcet's Disease Treatment Market |
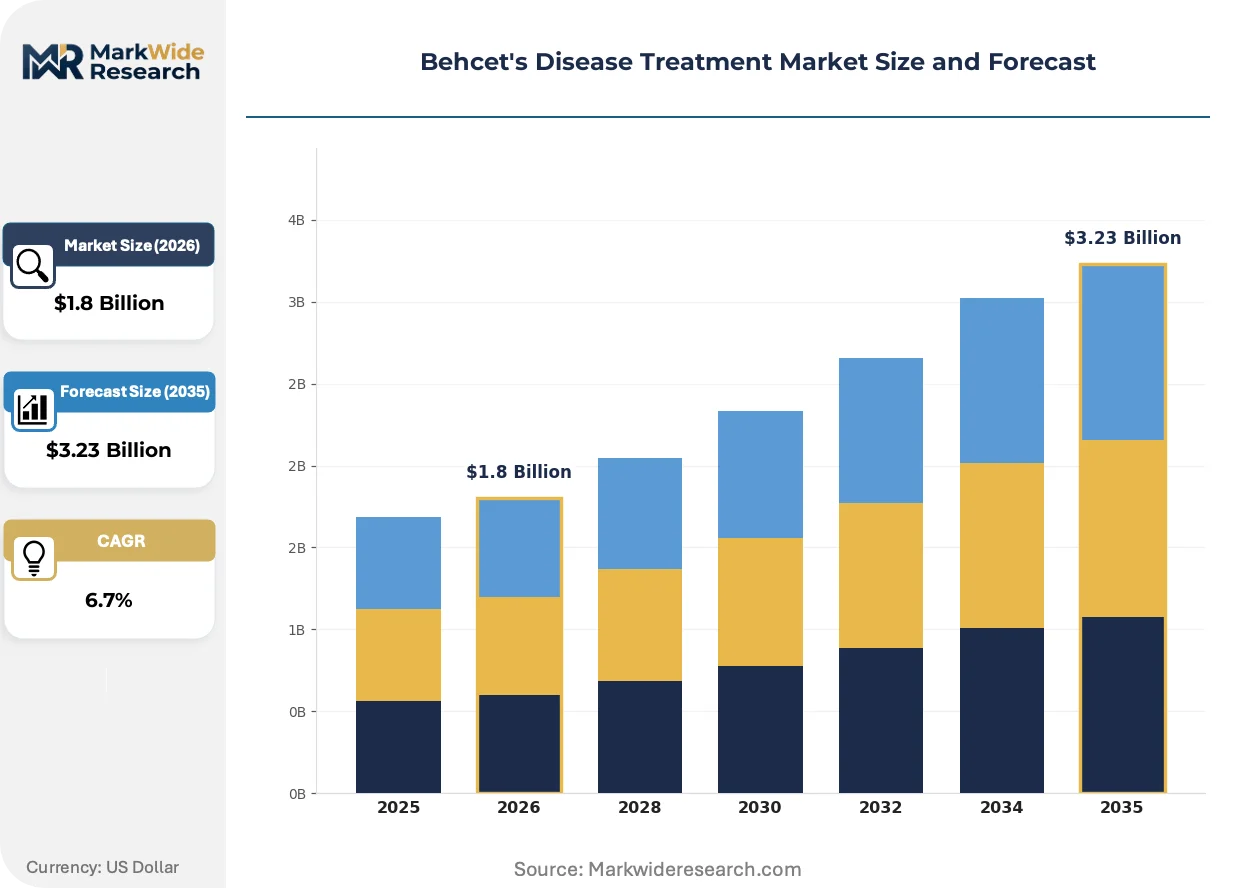
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Immunosuppressants, Biologics, Topical Treatments Drug Class: TNF Inhibitors, Interleukin Inhibitors, Cytotoxic Agents, Others Administration Route: Oral, Injectable, Intravenous, Topical End User: Hospitals, Outpatient Clinics, Specialty Pharmacies, Homecare Providers |
| Companies Covered | AbbVie, Eisai Co. Ltd., Novartis AG, F. Hoffmann-La Roche Ltd., Pfizer Inc., Amgen Inc., Mitsubishi Tanabe Pharma Corporation, Takeda Pharmaceutical Company Limited, Celltrion Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Behcet's Disease Treatment Market Strategic Shifts
Digital biomarker platforms are virtualizing traditional clinical endpoints while regulatory agencies accelerate novel approval pathways for rare disease indications.
Teleophthalmology with AI-assisted retinal imaging is virtualizing the standard of care for posterior uveitis monitoring. Academic medical centers in the United States and Germany are deploying these systems for remote disease activity assessment. This virtualization is compressing the interval between symptomatic flares and therapeutic intervention, reducing permanent visual acuity loss.
Japan's PMDA has implemented a conditional early approval system for biologics demonstrating efficacy in refractory ocular Behcet's disease. This framework permits post-marketing confirmatory studies rather than requiring complete Phase III data packages. European manufacturers are responding by prioritizing Japanese trial sites to secure priority review vouchers.
Patients are consolidating prescription fulfillment through integrated specialty pharmacy hubs that coordinate prior authorization, nursing support, and adherence tracking. This channel consolidation is displacing fragmented retail pharmacy relationships. The United States exhibits the most pronounced concentration, with three national specialty pharmacies controlling the majority of biologic dispensing for rare immunologic conditions.
Behcet's Disease Treatment Market Segmentation
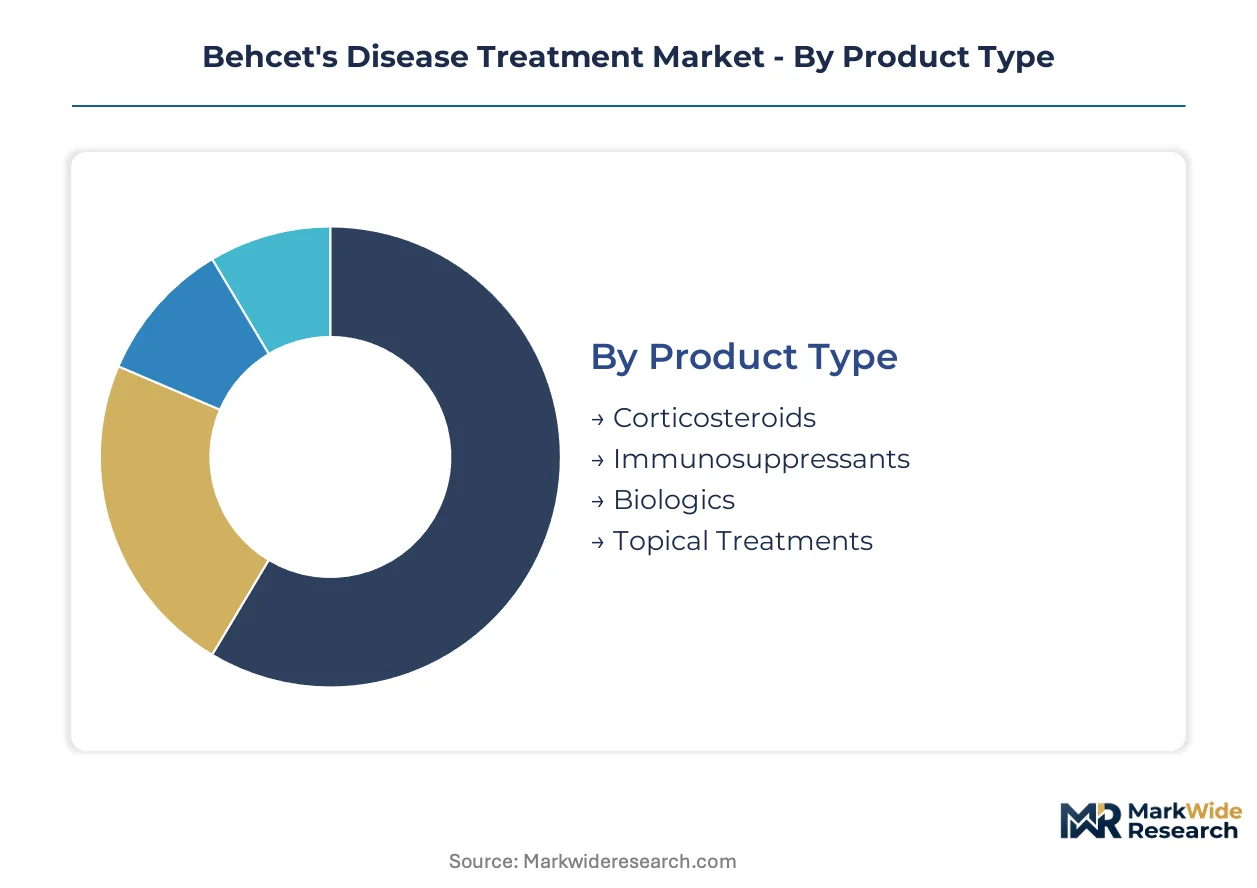
Behcet's disease treatment segmentation reveals distinct service intensity requirements across product tiers, with biologics demanding cold chain logistics and nursing support while corticosteroids flow through conventional pharmacy channels. Understanding these structural differences shapes go-to-market investment and partnership priorities for manufacturers.
Product Type:
After-sales service intensity varies dramatically across product tiers, with biologics requiring temperature monitoring, patient training, and adherence programs versus standardized dispensing for conventional therapies.
- Corticosteroids:First-line systemic therapy administered orally or topically for mucocutaneous flares. Demand concentrates in outpatient clinics across Turkey and the United States where diagnostic pathways for oral ulcers are well-established, though generic pricing limits manufacturer service investment.
- Immunosuppressants:Azathioprine and cyclosporine bridge therapy for moderate disease activity requiring laboratory monitoring. German rheumatology networks favor this class for ocular-sparing protocols, balancing efficacy against infection risk through structured monitoring programs.
- Biologics:High-cost injectable and infused therapies targeting TNF-alpha and interleukin pathways with orphan pricing flexibility.
- Topical Treatments:Localized corticosteroid and anesthetic preparations for genital and oral lesions.
By volume, corticosteroids lead. By growth pace, biologics are expanding most quickly.
Drug Class:
Cost tier stratification separates originator biologics from conventional immunosuppression, with pricing power concentrated among agents demonstrating superior ocular outcomes.
- TNF Inhibitors:Established anti-TNF-alpha antibodies with the longest commercial track record in refractory disease. United States payers maintain broad prior authorization coverage for adalimumab and infliximab, though biosimilar pressure is mounting from South Korean contract manufacturers.
- Interleukin Inhibitors:IL-1 and IL-6 pathway antagonists demonstrating superior visual acuity preservation in posterior uveitis. Japanese PMDA conditional approval pathways accelerate access for refractory ocular cases, driving trial site investment from European sponsors.
- Cytotoxic Agents:Cyclophosphamide reserved for life-threatening vascular and neurological manifestations.
- Others:Colchicine and interferon-alpha for select mucocutaneous presentations.
By revenue concentration, TNF inhibitors lead. By clinical momentum, interleukin inhibitors are gaining share fastest.
Administration Route:
Volume distribution shifts toward patient-administered formats as specialty pharmacy infrastructure matures, reducing hospital dependency for maintenance therapy.
- Oral:Corticosteroids, immunosuppressants, and colchicine enabling self-managed chronic therapy. Turkish and Iranian markets exhibit heavy reliance on oral methylprednisolone pulses due to infusion infrastructure gaps in secondary cities.
- Injectable:Subcutaneous biologics permitting home administration with nursing support. United States specialty pharmacies have built high-touch networks for patient training, displacing hospital-based infusion for maintenance regimens.
- Intravenous:Hospital-administered infliximab and cyclophosphamide for induction and severe flares.
- Topical:Localized delivery for mucosal lesions with minimal systemic exposure.
By patient volume, oral formulations lead. By channel margin, injectable formats are climbing the fastest.
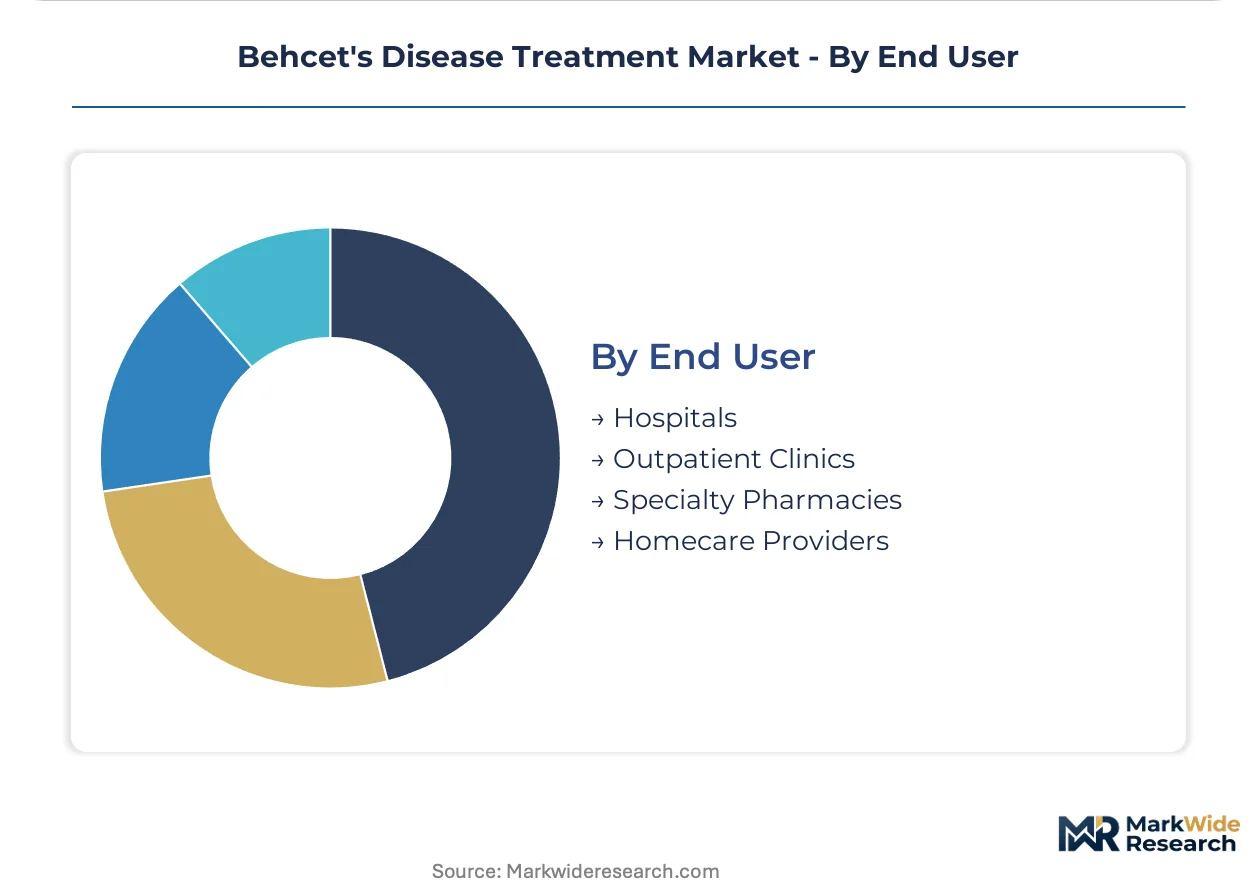
End User:
Customer type determines purchasing authority and service bundling requirements, with specialty pharmacies capturing biologic dispensing through integrated prior authorization management.
- Hospitals:Academic medical centers managing severe ocular and vascular manifestations through multidisciplinary rheumatology-ophthalmology teams. German university hospitals anchor regional referral networks for neurological Behcet's, concentrating complex case volumes.
- Outpatient Clinics:Community rheumatology practices diagnosing and stabilizing mucocutaneous disease. United States clinic consolidation into health systems is standardizing formulary decisions and biologic access pathways.
- Specialty Pharmacies:Hub models coordinating nursing, adherence, and reimbursement support for biologics.
- Homecare Providers:Infusion nursing services for subcutaneous maintenance therapy.
By prescription volume, outpatient clinics lead. By revenue per patient, specialty pharmacies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes biologic therapies at intensities unmatched elsewhere, while Turkey and Iran rely predominantly on oral corticosteroid pulses due to infrastructure constraints. Germany and Japan present divergent regulatory pathways that reshape trial investment priorities. Consumption patterns thus split between high-cost biologic markets and volume-driven conventional therapy regions.
United States
Specialty pharmacy networks and prior authorization infrastructure concentrate biologic dispensing among three national hubs. The FDA's orphan drug tax credit reduces net development costs for interleukin pathway inhibitors. Academic medical centers in Boston and the Research Triangle anchor referral networks for refractory ocular cases.
Germany
Rheumatology networks favor azathioprine bridging protocols that balance efficacy against infection risk through structured monitoring. The AMNOG early benefit assessment imposes cost-effectiveness hurdles that delay market access for novel interleukin inhibitors. University hospitals in Berlin and Munich concentrate complex neurological Behcet's case volumes.
Japan
Conditional early approval pathways for refractory ocular disease accelerate access ahead of complete Phase III packages. The PMDA maintains distinct efficacy requirements for vascular versus mucocutaneous endpoints that influence sponsor trial design. Tokyo and Osaka trial sites attract priority investment from European manufacturers seeking priority review vouchers.
Turkey
Diagnostic pathways for oral ulcers are well-established in outpatient clinics across Ankara and Istanbul. The country's national pharmaceutical regulator emphasizes bioequivalence standards for immunosuppressant generics that shape local procurement. Secondary cities exhibit heavy reliance on oral methylprednisolone due to infusion infrastructure gaps.
South Korea
Contract manufacturers are developing TNF inhibitor biosimilars that threaten originator pricing flexibility in export markets. The MFDS maintains accelerated review pathways for biosimilar applications that compress development timelines. Seoul-based biotech clusters supply active pharmaceutical ingredients to Indian and Southeast Asian formulation facilities.
Behcet's Disease Treatment Market Competitive Environment
Capability concentration sits with integrated immunology specialists; scale advantage sits with diversified pharmaceutical conglomerates. The market structure tiers between originator biologic developers defending orphan pricing and biosimilar manufacturers compressing margins through manufacturing efficiency. Three archetypes dominate: high-touch nursing network operators, Asian distribution partnership anchors, and digital monitoring platform integrators. Competitive moves center on subcutaneous formulation migration and specialty pharmacy channel capture.
Among the integrated immunology specialists, AbbVie and Novartis AG exemplify divergent service models for injectable biologics. AbbVie occupies a position anchored in high-touch nursing infrastructure for patient-administered therapies. Novartis AG exemplifies the digital integration archetype through remote monitoring platforms that track treatment response between clinic visits. Eisai Co. Ltd. represents the Asian market development specialist, with positioning shaped by specialized distribution partnerships in regional markets.
| Leading Market Players |
|---|
| AbbVie |
| Eisai Co. Ltd. |
| Novartis AG |
| F. Hoffmann-La Roche Ltd. |
| Pfizer Inc. |
| Amgen Inc. |
| Mitsubishi Tanabe Pharma Corporation |
| Takeda Pharmaceutical Company Limited |
| Celltrion Inc. |
| Others |
Value Chain & Pricing Dynamics
Amsterdam-Rotterdam-Antwerp freight corridors govern cold chain cost dynamics for temperature-sensitive biologics, concentrating supply leverage among manufacturers with redundant distribution nodes while forcing three-tier pricing stratification across originator, biosimilar, and conventional therapy tiers.
Pricing Analysis
Long-term offtake agreements between originator manufacturers and national specialty pharmacy hubs anchor pricing stability for TNF-alpha and interleukin pathway inhibitors, while spot procurement for corticosteroid generics erodes margin through tender-based competition. Price differentiation rests on orphan drug exclusivity status and cold chain service bundling rather than molecular differentiation alone. Cost compression in the TNF inhibitor segment is intensifying as South Korean contract manufacturers advance biosimilar interchangeability filings. Hospital procurement committees exhibit highest price sensitivity for conventional immunosuppressants; specialty pharmacies demonstrate lowest sensitivity due to pass-through reimbursement structures.
Supply Chain Analysis
Contract manufacturing concentration sits with Lonza and Samsung Biologics for mammalian cell culture production of monoclonal antibodies, while Boehringer Ingelheim and Catalent hold fill-finish capacity for subcutaneous formulations. Active pharmaceutical ingredient sourcing draws from Ireland, Switzerland, and Singapore for biologic drug substances; secondary packaging feeds from Poland and Mexico for regional distribution efficiency. Single-source vulnerability concentrates in temperature-controlled logistics nodes serving tertiary markets. Distribution runs through three national specialty pharmacy hubs in the United States, with hospital-based infusion centers retaining intravenous induction therapy allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across administration routes, reimbursement pathways, and regional regulatory clusters creates multiple niche entry points as patient-administered subcutaneous formats displace hospital-centric infusion models.
For Market Incumbents: Harden formulary position through backward integration into captive fill-finish capacity for subcutaneous formulations, insulating against biosimilar substitution pressure. Deepen nursing network density in secondary US markets to preempt specialty pharmacy channel capture by emerging interleukin inhibitor developers. Lock in long-term offtake terms with integrated delivery networks before AMNOG-style cost-effectiveness assessments proliferate.
For New Entrants and Emerging Players: Establish a beachhead in remote monitoring platform development for ocular Behcet's disease, where digital biomarker validation lags clinical need. Japan's conditional early approval pathway for refractory cases offers the most penetrable regulatory entry point, rewarding tailored trial designs with accelerated market access. Pursue distribution partnerships with established Asian specialty pharmacy networks rather than building de novo infrastructure.
For Investors and Strategic Acquirers: Digital therapeutic developers with validated retinal imaging algorithms represent the most defensible acquisition archetype as outcome-based contracting gains traction with US payers. Long-term viability hinges on demonstrating measurable visual acuity preservation against standard-of-care biologics across a five-to-ten year horizon. Watch for FDA draft guidance on biosimilar interchangeability as the critical inflection signal for TNF inhibitor portfolio repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Migration | AbbVie's high-touch nursing networks capture patient-administered therapy share from hospital infusion centers. |
| Digital Biomarker Platform Development | Novartis AG's remote monitoring tools enable outcome-based contracting with Medicare Advantage plans. |
| Asian Distribution Partnership Anchoring | Eisai Co. Ltd.'s specialized regional networks secure PMDA conditional approval pathway access. |
| Biosimilar Manufacturing Scale-Up | Celltrion Inc.'s contract manufacturing capacity threatens originator pricing in TNF inhibitor segment. |
| Specialty Pharmacy Channel Consolidation | Three national US hubs now control majority dispensing for rare immunologic conditions. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists; and secondary validation against FDA orphan drug filings, EMA centralized procedure submissions, ClinicalTrials.gov recruitment data, and Japanese PMDA review documentation. Bottom-up patient volume estimates by treatment line and administration route were triangulated against top-down manufacturer revenue disclosures.
Forecast inputs incorporated treatment paradigm evolution across first-line corticosteroid, bridging immunosuppressant, and biologic therapy tiers; dosage form migration from intravenous to subcutaneous; and regional regulatory cluster adoption curves. CAGRs were derived from segment-level growth rate reconciliation against aggregate market value anchors. Pipeline progression probabilities for interleukin pathway inhibitors and biosimilar interchangeability timing shaped scenario-weighted outputs.
Macroeconomic conditions sit as an overlay; deviation in US Medicare reimbursement rates, German AMNOG benefit assessment stringency, or Japanese yen-denominated pricing would shift the trajectory. Quarterly review of specialty pharmacy dispensing data, PMDA conditional approval grant rates, and FDA biosimilar guidance publication is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market
Medical Treatment
Nasal Allergy Treatment Market
Medical Treatment
Nose Reconstruction Market
Medical Treatment
Thyroid Gland Disorders Treatment Market
Medical Treatment
Microwave Ablation Market
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Asthma Treatment Market
Medical Treatment
Scabies Treatment Market
Medical Treatment
Lymphedema Treatment Market
Medical Treatment
Iron Deficiency Anemia Treatment Market
Medical Treatment
Neglected Tropical Disease Treatment Market
Medical Treatment
Facial Spasm Treatment Market
Medical Treatment
Diphtheria Treatment Market
Medical Treatment
Giardiasis Treatment Market
Medical Treatment
Anti-Rickettsial Treatment Market
Medical Treatment
Hemorrhoids Treatment Market