
 Vaginitis Treatment Drugs Market | 2026-2036
Vaginitis Treatment Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Vaginitis Treatment Drugs Market Analytics
Aftermarket service revenue from patient support programs is tilting toward pharmacy-led adherence monitoring. Pfizer leverages its manufacturing scale to sustain supply chain control across multiple dosage forms. Bayer anchors its position through geographic dominance in European OTC distribution channels.
Vaginitis treatment drugs comprise pharmaceutical agents formulated to restore vaginal microbiome balance, typically containing active compounds such as azole antifungals, nitroimidazole antibiotics, or lactic acid-producing bacterial cultures, and are manufactured through sterile fermentation or chemical synthesis processes for targeted pathogen elimination. Antifungals occupy the largest margin pool due to recurrent candidiasis prevalence, while probiotics represent the fastest-growing category as clinicians shift toward microbiome-sparing protocols. The delivery mode dimension shows topical formulations retaining volume leadership, though vaginal inserts gain share through extended-release polymer innovations.
FDA bioequivalence standards shape generic substitution patterns, while EMA pharmacovigilance requirements influence post-market surveillance investments across European portfolios. The WHO Essential Medicines List inclusion criteria drive access programs in low-resource settings, altering procurement specifications for multinational tenders. Stakeholders must monitor regulatory divergence between FDA fast-track designations and EMA conditional approval pathways when prioritizing development pipelines.
Market Dynamics
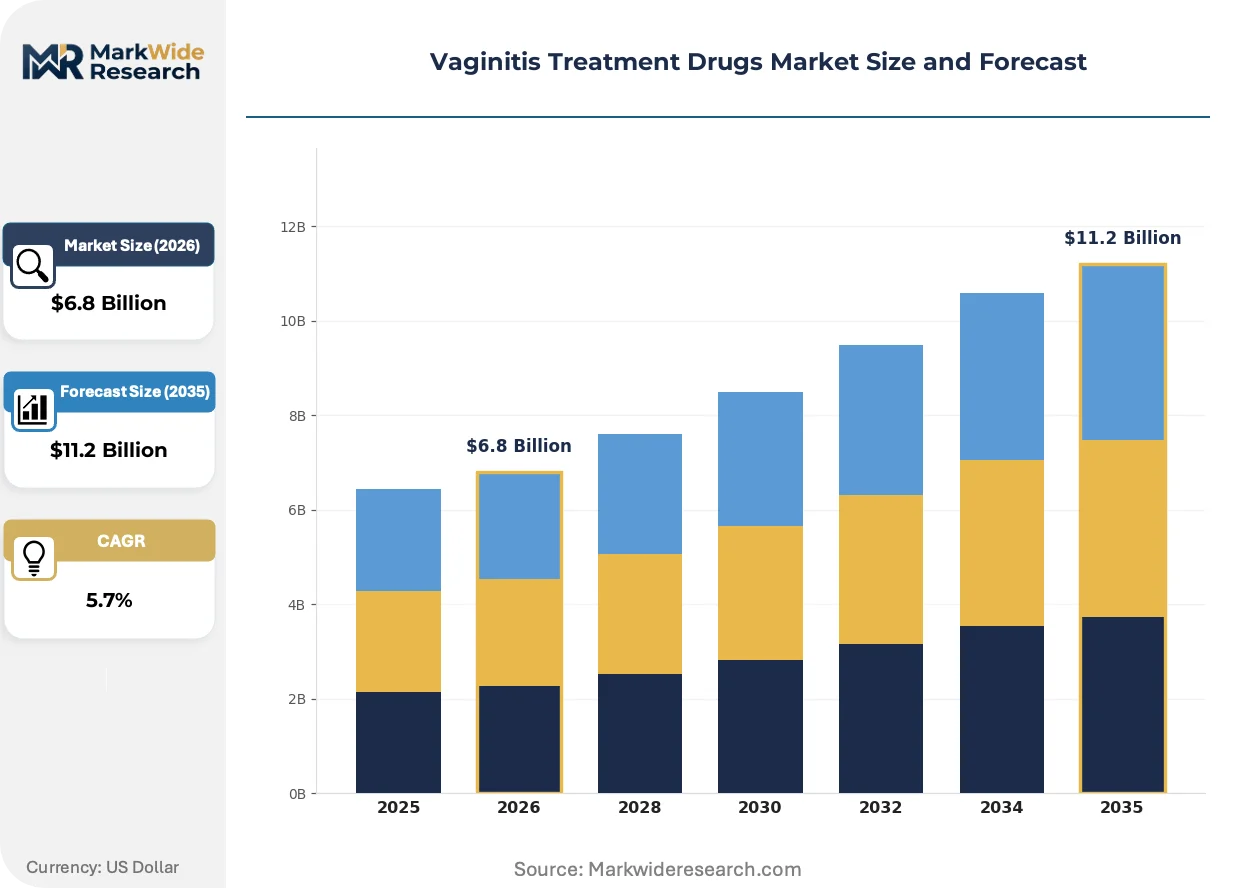
The vaginitis treatment drugs market pivots on regulatory acceleration of generic entry through FDA's streamlined ANDA review, compressing branded exclusivity windows while expanding patient access to lower-cost therapeutics across outpatient and hospital channels.
Growth Catalysts
- FDA ANDA Streamlining:The abbreviated new drug application pathway reduces generic approval timelines, expanding affordable antifungal access in United States outpatient settings and driving volume substitution.
- Microbiome-Sparing Protocols:Clinicians increasingly prioritize lactic acid bacterial cultures over broad-spectrum agents, pulling probiotic formulations into standard-of-care discussions for recurrent cases.
- Extended-Release Polymer Innovation:Vaginal insert technologies with controlled-release kinetics improve patient adherence compared to multi-day topical regimens, reshaping formulation preferences.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Azole precursor supply chains cluster in specific Asian manufacturing hubs, exposing formulators to geopolitical disruption and input cost volatility.
- Antimicrobial Resistance Surveillance:EMA pharmacovigilance requirements mandate costly post-market resistance monitoring, elevating compliance burdens for nitroimidazole antibiotic portfolios.
- Diagnostic Substitution:Molecular point-of-care testing for pathogen identification delays empiric prescribing, compressing immediate treatment initiation rates in primary care.
Strategic Opportunities
- Combination Formulation Development:Convergent antifungal-probiotic delivery systems address both pathogen elimination and microbiome restoration in single-administration products.
- Pharmacy-Led Adherence Monitoring:Patient support programs administered through retail pharmacy networks capture recurring revenue streams beyond initial prescription fulfillment.
- WHO Essential Medicines Access Programs:Inclusion criteria for low-resource procurement tenders open volume opportunities for simplified formulation manufacturers meeting prequalification standards.
Industry Challenges
- Sterile Fermentation Scale-Up:Probiotic manufacturing requires validated aseptic production environments that demand capital-intensive facility reconfiguration for traditional chemical synthesis operators.
- Bioequivalence Study Design:FDA requirements for topical vaginal product equivalence create complex clinical endpoint selection, extending development timelines for generic entrants.
- Multinational Regulatory Divergence:Conditional approval pathways at EMA diverge from FDA fast-track designations, forcing parallel track strategies that fragment development resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaginitis Treatment Drugs Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antifungals, Antivirals, Probiotics Application: Self-Care, Hospital Treatment, Prescription Medication, OTC Delivery Mode: Topical, Oral, Vaginal Insert, Injectable End User: Healthcare Professionals, Patients, Pharmacies, Clinics |
| Companies Covered | Pfizer, Bayer, Sanofi, Teva Pharmaceutical Industries, Merck & Co., Novartis, GlaxoSmithKline, Lupin Pharmaceuticals, Organon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaginitis Treatment Drugs Market Evolving Landscape
Formulation science and diagnostic integration are restructuring how vaginitis therapeutics reach patients, with polymer chemistry and point-of-care testing converging to reshape both delivery mechanisms and prescribing workflows.
Extended-release vaginal inserts employing bioadhesive polymer matrices is migrating from niche specialty applications toward mainstream adoption. Gynecology practices in United States metropolitan markets are integrating these formulations into first-line protocols for recurrent candidiasis. The technology is compressing traditional multi-day topical regimen adherence failures while commanding premium positioning against conventional creams.
EMA's strengthened pharmacovigilance requirements for antimicrobial agents now mandate systematic resistance surveillance across European nitroimidazole portfolios. Manufacturers must maintain active post-authorization safety study infrastructure, elevating operating costs for antibiotic-focused product lines. Smaller European formulators are responding through portfolio rebalancing toward antifungal and probiotic categories with lighter surveillance obligations.
Self-diagnostic test kits sold through direct-to-consumer channels are fragmenting traditional physician-mediated prescribing pathways. United States retail pharmacy chains now bundle over-the-counter testing with pharmacist consultation services, displacing gynecological office visits for initial symptom assessment. This pattern concentrates in suburban markets where appointment access constraints drive consumer preference for immediate resolution options.
Vaginitis Treatment Drugs Market Segmentation
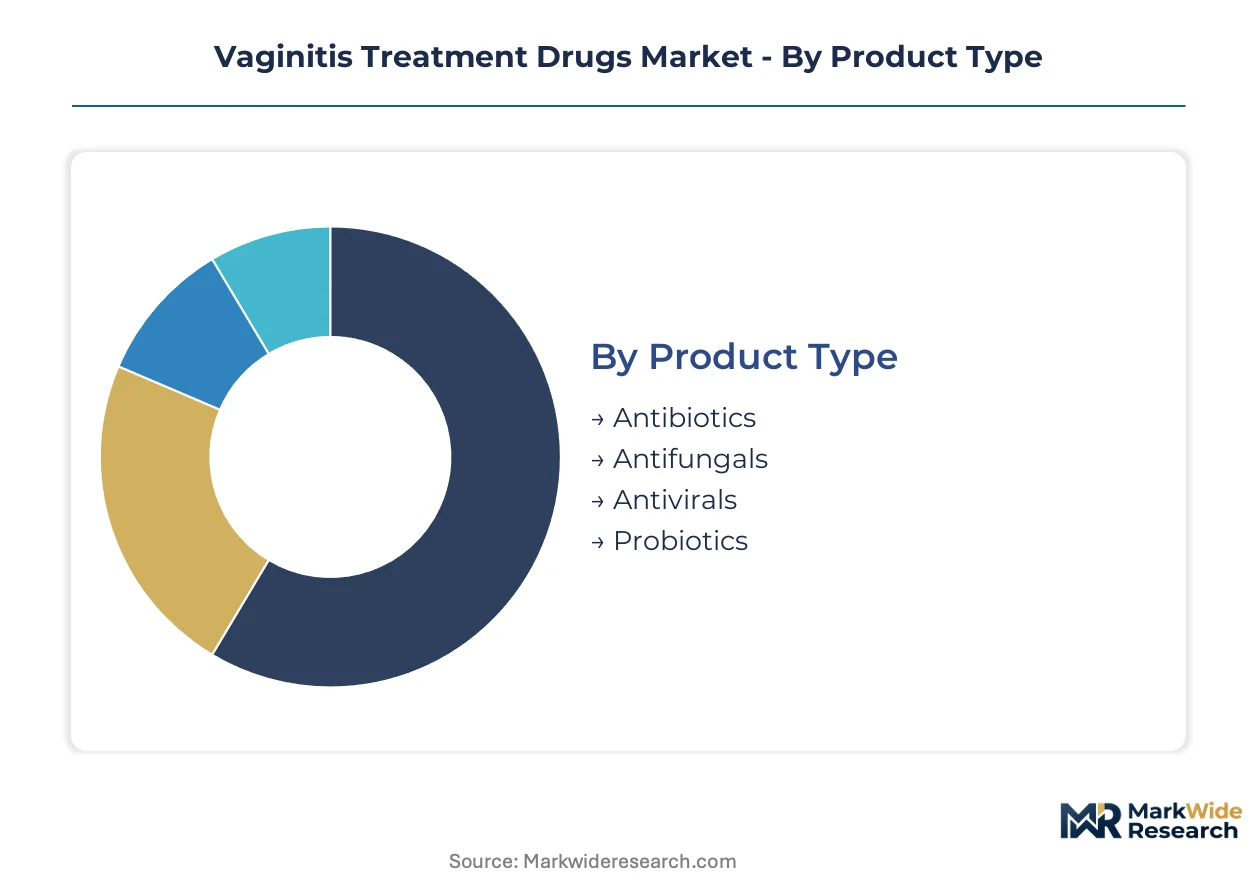
Segmentation in vaginitis therapeutics reveals distinct margin profiles and regulatory pathways. Product chemistry, care setting, delivery mechanism, and prescriber authority each create separate competitive arenas with unique investment requirements and access barriers.
Product Type:
Clinical decision protocols span empiric pathogen elimination through targeted microbiome restoration, with each compound class carrying distinct resistance surveillance obligations and manufacturing complexity.
- Antifungals:Azole compounds dominate prescription volume for candidiasis management. United States outpatient gynecology practices drive demand concentration, though recurrent infection rates sustain extended-release formulation premiums against generic cream substitutions.
- Probiotics:Lactic acid bacterial cultures require validated sterile fermentation infrastructure. European clinicians are expanding adoption fastest as EMA pharmacovigilance burdens push portfolios away from surveillance-heavy antibiotic categories.
- Antibiotics:Nitroimidazole agents face escalating post-market resistance monitoring costs under EMA mandates.
- Antivirals:Narrow indication scope limits volume to confirmed viral etiology cases with diagnostic confirmation.
Established volume favors antifungals; emerging adoption favors probiotics.
Application:
Care setting determines reimbursement architecture and regulatory scrutiny intensity, with hospital channels demanding formal pharmacoeconomic evidence and self-care segments prioritizing immediate accessibility.
- Prescription Medication:Physician-mediated prescribing carries prior authorization requirements and step-therapy protocols. United States managed care formularies increasingly require documented treatment failure on OTC alternatives before antifungal approval.
- Self-Care:Direct-to-consumer test-and-treat bundles bypass traditional diagnostic workflows. Retail pharmacy chains in suburban United States markets capture patient volume through pharmacist consultation services paired with over-the-counter azole access.
- Hospital Treatment:Inpatient protocols emphasize IV-to-oral step-down with resistance profiling.
- OTC:Pharmacy-shelf availability competes on packaging differentiation and dosing convenience.
Prescription channels anchor revenue stability; self-care segments gain share through diagnostic integration.
Delivery Mode:
Patient adherence patterns and pharmacokinetic requirements shape formulation selection, with polymer innovation compressing multi-day regimens into single-administration alternatives.
- Topical:Cream and ointment formulations retain manufacturing scale advantages and lowest per-unit production costs. Volume concentrates in mature markets where patient familiarity sustains preference despite adherence limitations from multi-day application schedules.
- Vaginal Insert:Bioadhesive polymer matrices with controlled-release kinetics command premium positioning. Gynecology practices in United States metropolitan markets are integrating these into first-line protocols for recurrent cases, displacing traditional cream prescriptions through improved completion rates.
- Oral:Systemic fluconazole tablets compete on convenience against topical alternatives with equivalent efficacy.
- Injectable:Limited to severe or refractory infections requiring parenteral administration in supervised settings.
Topical formulations maintain volume leadership; vaginal inserts climb the fastest on adherence advantages.
End User:
Procurement authority and clinical decision autonomy fragment across prescriber types, with pharmacy networks gaining influence through diagnostic bundling and adherence program administration.
- Healthcare Professionals:Gynecologists and primary care physicians control initial diagnosis and empiric therapy selection. Prescribing patterns in United States fee-for-service settings favor immediate symptom resolution through prescription-strength agents over OTC trial periods.
- Pharmacies:Retail chains capture recurring revenue through patient support program administration. Point-of-care testing integration positions pharmacists as gatekeepers for treatment escalation decisions previously reserved for physician consultation.
- Patients:Direct purchasing decisions concentrate in self-diagnosed first episodes with mild symptom presentation.
- Clinics:Federally qualified health centers and urgent care facilities prioritize lowest-acquisition-cost formularies.
Healthcare professionals retain diagnosis authority; pharmacies expand influence through service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States outpatient gynecology practices consume prescription antifungals at triple the per-capita rate of European markets, while Asian markets favor probiotic formulations due to traditional medicine integration and lower antibiotic prescribing norms.
United States
Fee-for-service gynecology practices in metropolitan markets drive prescription volume for extended-release vaginal inserts. FDA's streamlined ANDA review process accelerates generic substitution, compressing branded exclusivity windows. Boston and New York City medical centers pilot microbiome-sparing protocols using lactic acid bacterial cultures.
Germany
EMA pharmacovigilance requirements for antimicrobial agents elevate compliance costs for nitroimidazole portfolios, pushing formulators toward antifungal alternatives. The country's statutory health insurance system reimburses prescription probiotics for recurrent candidiasis cases. Frankfurt and Munich pharmaceutical clusters specialize in sterile fermentation infrastructure for bacterial culture production.
India
CDSCO regulatory pathways for fixed-dose combination therapies attract domestic manufacturers targeting simplified formulation exports. Tier-2 city gynecology practices drive volume for low-cost topical azole creams. Hyderabad and Ahmedabad API manufacturing hubs supply azole precursors to multinational formulators.
Japan
PMDA's stringent bioequivalence standards for topical vaginal products extend generic approval timelines, preserving branded market share. Aging demographics elevate recurrent infection prevalence among postmenopausal patient segments. Tokyo and Osaka metropolitan hospitals integrate point-of-care molecular diagnostics into empiric prescribing workflows.
Brazil
ANVISA's alignment with WHO prequalification standards opens procurement pathways for domestic manufacturers targeting Latin American tenders. Self-diagnostic test kit adoption concentrates in São Paulo and Rio de Janeiro suburban pharmacy chains. Retail networks bundle over-the-counter azole access with pharmacist consultation services.
Vaginitis Treatment Drugs Market Competitive Landscape
Capability concentration sits with specialized probiotic manufacturers possessing validated sterile fermentation infrastructure; scale advantage sits with diversified pharmaceutical conglomerates commanding multi-continental distribution networks. The market structure segments into three tiers: global diversified incumbents with hospital formulary relationships, regional generic specialists exploiting FDA ANDA streamlining, and emerging microbiome-focused biotechnology developers. Dominant competitive moves include portfolio rebalancing toward surveillance-light therapeutic categories and backward integration into API precursor manufacturing.
Among diversified pharmaceutical conglomerates, Pfizer and Bayer exemplify contrasting geographic strategies. Pfizer leverages manufacturing scale across multiple dosage forms to sustain supply chain control in United States outpatient channels. Bayer anchors its position through dominance in European OTC distribution networks. Sanofi occupies a position bridging prescription and self-care segments through integrated diagnostic-therapeutic bundling approaches.
| Leading Market Players |
|---|
| Pfizer |
| Bayer |
| Sanofi |
| Teva Pharmaceutical Industries |
| Merck & Co. |
| Novartis |
| GlaxoSmithKline |
| Lupin Pharmaceuticals |
| Organon |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor's freight cost volatility feeds directly into azole precursor landed costs, compressing margins for European formulators while amplifying price spreads between Asian-manufactured generics and branded polymer-based inserts in United States outpatient channels.
Pricing Analysis
Long-term offtake contracts for azole active pharmaceutical ingredients anchor pricing stability for multinational formulators, though spot market exposure among Indian generic specialists generates periodic cost compression in United States retail pharmacy channels. Three-tier pricing structure across premium extended-release inserts, standard topical creams, and economy generic tablets reflects formulation complexity and FDA bioequivalence certification tiers. Pricing pressure stems from FDA's streamlined ANDA review accelerating generic substitution in outpatient settings. Hospital procurement committees exhibit lowest price sensitivity due to formulary lock-in agreements, while self-care consumers at suburban pharmacy chains demonstrate highest elasticity.
Supply Chain Analysis
Upstream azole precursor manufacturing clusters in India and China, with Hyderabad and Shanghai chemical parks supplying fermentation-derived intermediates to multinational formulators. Sterile fermentation infrastructure for probiotic cultures draws from German and Danish specialty manufacturers, creating dual-track dependency patterns. Single-source vulnerability concentrates in Asian API hubs exposed to export license restrictions. Distribution runs through hospital group purchasing organizations in United States metropolitan markets, retail pharmacy chains in European OTC segments, and government procurement tenders in low-resource settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vaginitis treatment drugs market functions as a defensive-moat arena where regulatory entrenchment through FDA bioequivalence standards and EMA pharmacovigilance compliance creates durable barriers against rapid competitive displacement.
For Market Incumbents: Entrench market position through backward integration into azole precursor manufacturing, securing captive supply from Indian API hubs against geopolitical disruption. Prioritize sterile fermentation capacity expansion in European clusters to capture probiotic category migration driven by EMA antimicrobial surveillance burdens. Channel control through exclusive hospital formulary agreements defends against generic substitution accelerated by FDA ANDA streamlining. For New Entrants and Emerging Players: Pharmacy-led adherence monitoring services in United States suburban markets represent the most penetrable entry point, bypassing physician-mediated prescribing bottlenecks through diagnostic bundling partnerships. WHO Essential Medicines prequalification pathways for simplified formulations unlock low-resource procurement tenders with lighter competitive intensity. Direct-to-consumer test-and-treat platforms offer a go-to-market angle that fragments traditional diagnostic workflows. For Investors and Strategic Acquirers: Specialized probiotic manufacturers possessing validated sterile fermentation infrastructure and established EMA compliance records present the most attractive acquisition target archetype for portfolio diversification. Long-term viability hinges on microbiome-sparing protocol adoption sustaining category growth against antimicrobial resistance headwinds. Monitor FDA fast-track designation velocity versus EMA conditional approval timelines as an inflection indicator for parallel-track development resource allocation efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA ANDA streamlining compresses generic entry timelines for azole antifungals in United States outpatient channels. |
| Manufacturing Scale-Up | Sterile fermentation capacity expansion in Frankfurt pharmaceutical clusters captures European probiotic demand migration. |
| Backward Integration | Upstream azole precursor control from Hyderabad manufacturing hubs insulates formulators against supply disruption. |
| Pipeline Diversification | Convergent antifungal-probiotic combination formulations address both pathogen elimination and microbiome restoration. |
| Distribution Channel Expansion | Pharmacy-led patient support programs capture recurring adherence monitoring revenue beyond initial prescription fulfillment. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors anchored the qualitative base. Primary interview data combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up prescription volume modeling and top-down pharmaceutical spending allocation triangulated market sizing across dosage form, treatment line, and regional regulatory cluster dimensions.
Scenario-bracketing around FDA approval velocity assumptions and EMA pharmacovigilance cost trajectories structured the analytical framework across the projection horizon. Segmentation modeling incorporated product chemistry, care setting, delivery mechanism, and prescriber authority dimensions alongside patient population stratification by recurrence frequency. CAGRs derived from prescription volume trend extrapolation adjusted for generic substitution elasticity and probiotic adoption curve inflection points. Forecast inputs included outpatient gynecology visit rates, point-of-care diagnostic penetration, and sterile fermentation capacity expansion timelines.
Practitioners should monitor FDA ANDA approval backlog fluctuations and azole precursor export license restrictions from Indian manufacturing hubs for early signals of forecast revision. Cross-checking against CMS Medicare Part D prescription claims data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Ligament Repair and Reconstruction Market
Medical Treatment
Squamous Cell Carcinoma Treatment Market
Medical Treatment
Porphyria Treatment Market
Medical Treatment
US and Japan Platelet Rich Plasma Market
Medical Treatment
Infertility Treatment Market
Medical Treatment
Psittacosis Treatment Market
Medical Treatment
Factor XIII Deficiency Treatment Market
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
Seropositive Rheumatoid Arthritis Treatment Market
Medical Treatment
Intensity Modulated Radiation Therapy Market
Medical Treatment
Basal Cell Carcinoma Treatment Market
Medical Treatment
Global Radiodermatitis Treatment Market
Medical Treatment
Congenital Hyperinsulinism Treatment Market
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
Vulvovaginal Candidiasis Treatment Market
Medical Treatment
Postoperative Nausea and Vomiting (PONV) Management Market