
 Purpura Treatment Market | 2026-2036
Purpura Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Purpura Treatment Market Outlook
Biologic manufacturing platforms is tilting toward recombinant thrombopoietin receptor agonist production, reducing batch-to-batch variability in platelet-stimulating therapies. Bristol-Myers Squibb Company leverages its immuno-oncology infrastructure to sustain development of hematology biologics with overlapping mechanism expertise. Novartis AG anchors its position through deep manufacturing scale in recombinant protein production. Pfizer Inc. competes by extending its hospital specialty sales network into coagulation centers across North America and Western Europe.
Purpura treatment encompasses pharmacologic interventions targeting thrombocytopenia-driven bleeding disorders, including corticosteroids that suppress immune-mediated platelet destruction, immunoglobulins that block Fc receptors on macrophages, and thrombopoietin receptor agonists that stimulate megakaryopoiesis in bone marrow. These therapies serve primary commercial purposes in acute bleeding control, chronic platelet maintenance, and perioperative hematologic stabilization. Corticosteroids and immunoglobulins occupy mature, high-volume positions with established generic competition and thin margins, while platelet growth factors and eltrombopag concentrate in premium-priced segments where biologic manufacturing complexity protects pricing power. The intravenous route dominates hospital administration, though subcutaneous formulations are gaining traction in home care settings where patient convenience and infusion center capacity constraints create structural openings.
FDA orphan drug designations and EMA PRIME eligibility frameworks shape development prioritization, with both regulators offering protocol assistance and fee waivers that reduce barriers for rare hematology indications. Health Canada's Special Access Programme and Japan's PMDA sakigake designation add further geographic layers to regulatory strategy. WHO prequalification pathways for immunoglobulin products influence procurement standards in lower-resource settings. Stakeholders must monitor how evolving platelet count threshold guidelines from hematology societies reshape treatment initiation criteria and addressable patient pools.
Market Dynamics
Hospital hematology departments are consolidating purchasing authority around platelet-stimulating biologics, compressing vendor access points and favoring manufacturers with integrated infusion support capabilities.
Growth Catalysts
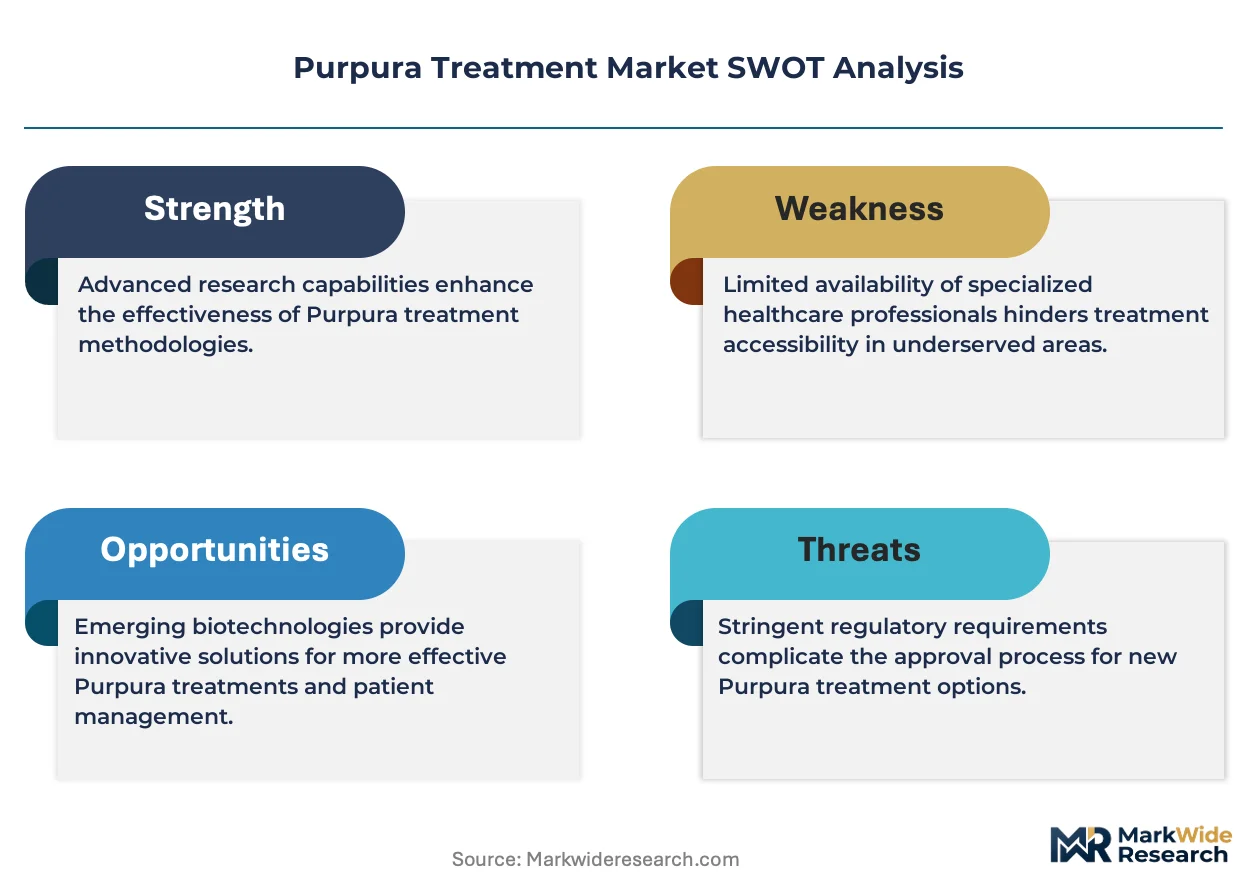
- FDA Orphan Drug Designation:Accelerated review timelines and fee waivers for rare hematology indications reduce development barriers for thrombocytopenia therapies targeting niche patient populations.
- Subcutaneous formulation advancement:Self-administration routes are expanding addressable patient pools beyond hospital infusion centers into home care settings.
- Japan PMDA Sakigake:Priority review pathways for innovative hematology biologics compress time-to-market for first-in-class platelet receptor agonists.
Market Restraints
- Plasma-derived immunoglobulin supply concentration:Dependence on fractionation facilities in the United States and Germany creates vulnerability to donor pool fluctuations and viral screening protocol changes.
- EMA PRIME eligibility thresholds:Stringent unmet medical need documentation requirements exclude mid-stage development programs from protocol assistance benefits.
- Corticosteroid generic saturation:First-line immune suppression therapies face commoditization pressure from multi-source manufacturers, eroding branded pricing power.
Strategic Opportunities
- Pediatric indication expansion:Chronic immune thrombocytopenia in patients under 18 remains underpenetrated by thrombopoietin receptor agonists due to limited pediatric trial data.
- WHO Prequalification pathway:Immunoglobulin products meeting international procurement standards unlock access to national health systems in lower-resource settings.
- Perioperative hematologic stabilization:Elective surgery protocols requiring platelet count thresholds create demand for rapid-acting interventions in orthopedic and cardiac centers.
Industry Challenges
- Biologics manufacturing workforce scarcity:Recombinant protein production requires specialized cell culture expertise that concentrates at a limited number of contract manufacturing organizations.
- Health Technology Assessment timelines:National reimbursement bodies in Germany and France extend market access negotiations by 18-24 months beyond regulatory approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Purpura Treatment Market |
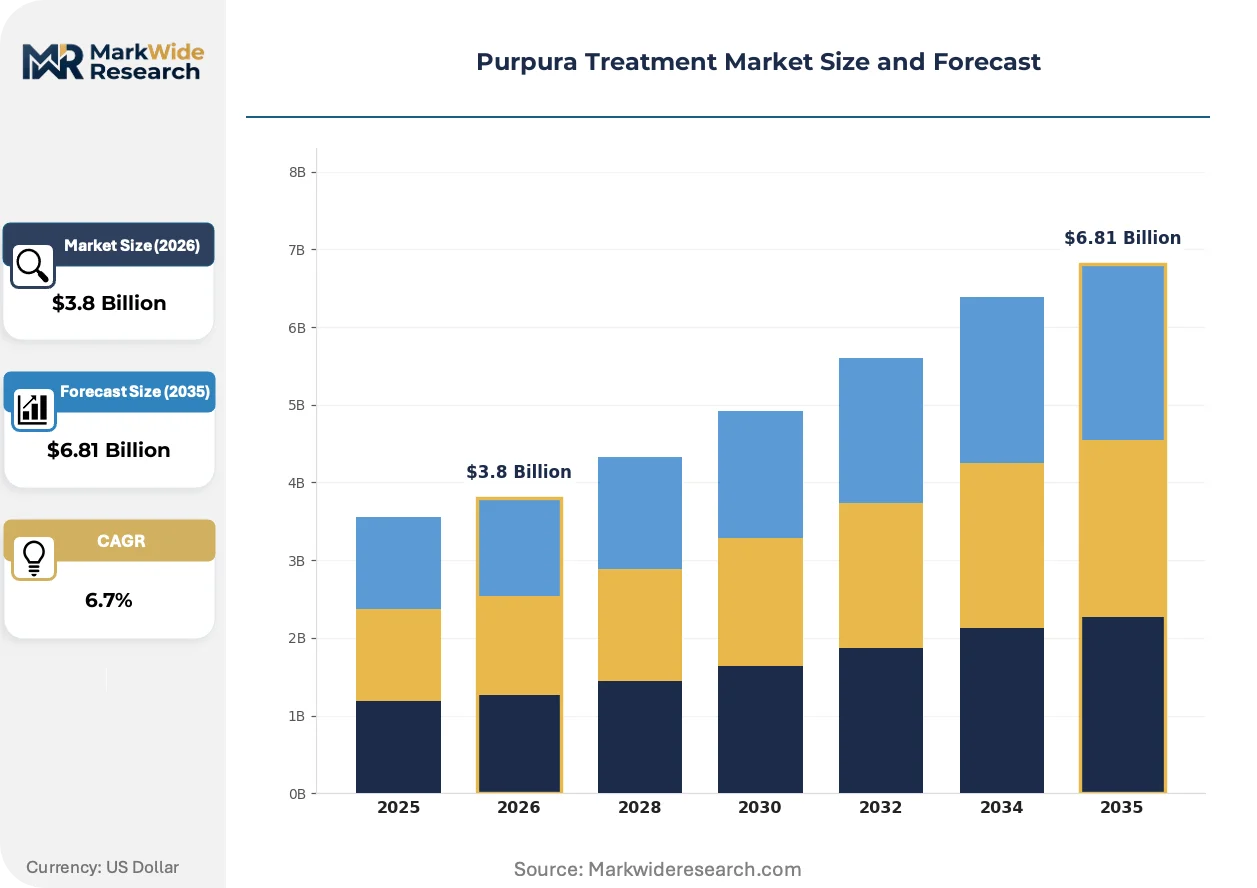
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Immunoglobulins, Platelet Growth Factors, Eltrombopag End User: Hospitals, Specialty Clinics, Home Care, Research Institutions Therapy Area: Pediatrics, Hematology, Immunology, Oncology Route of Administration: Intravenous, Oral, Subcutaneous, Intraosseous |
| Companies Covered | Bristol-Myers Squibb Company, Novartis AG, Pfizer Inc., F. Hoffmann-La Roche Ltd, Amgen Inc, GlaxoSmithKline Plc., Sanofi, Grifols Biologicals Inc, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Purpura Treatment Market Strategic Shifts
Digitization of platelet monitoring and therapy management is compressing the gap between laboratory values and clinical decision-making, enabling tighter therapeutic control loops.
Continuous glucose monitoring platforms adapted for hematology applications are virtualizing platelet count surveillance, allowing hematology departments at Mayo Clinic and Memorial Sloan Kettering to reduce in-person phlebotomy visits by half. Remote monitoring infrastructure is enabling home-based dose titration of thrombopoietin receptor agonists, compressing the traditional hospital-centric care model into distributed patient-managed protocols.
EMA's PRIME eligibility framework is tightening evidentiary standards for breakthrough therapy designation in rare hematologic conditions, forcing sponsors to commit to larger pre-approval safety databases. The industrial consequence is extended Phase IIb program duration and elevated development costs for platelet-stimulating biologics. Manufacturers are responding by front-loading natural history studies to establish comparator benchmarks before pivotal trial initiation.
Buying committees at integrated delivery networks are consolidating immunoglobulin purchasing across multiple hospital systems, displacing individual physician preference in favor of standardized formularies. This concentration is compressing the number of contracted suppliers per network from five to two in major metropolitan markets. The shift is most visible in the United States, where Catholic health systems and for-profit chains are centralizing hematology biologic procurement decisions at regional headquarters.
Purpura Treatment Market Segmentation
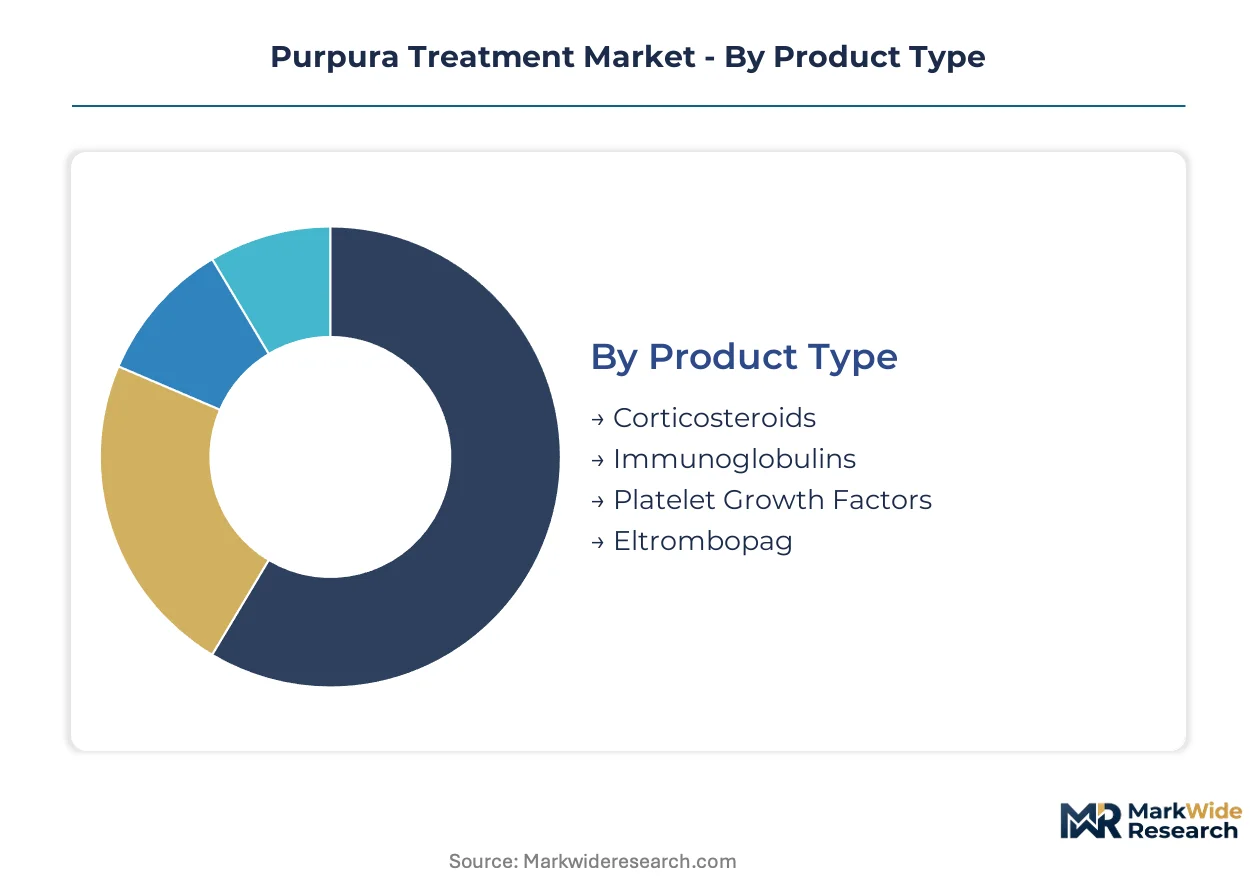
Segmentation in purpura treatment reveals divergent margin structures across therapeutic modalities. Route of administration and care setting determine reimbursement pathways and competitive intensity more than molecular mechanism alone.
Product Type:
Use-case spectrum spans acute immune suppression through chronic platelet maintenance, with manufacturing complexity separating commodity from premium tiers.
- Corticosteroids:First-line immune suppression via prednisone and dexamethasone protocols. Hospital formularies in the United States and Germany standardize these for initial ITP management despite bone toxicity concerns with prolonged exposure.
- Immunoglobulins:Intravenous immunoglobulin (IVIG) delivers rapid platelet recovery through Fc receptor blockade on splenic macrophages. Demand concentrates in emergency departments and perioperative settings where rapid onset outweighs cost considerations, though plasma supply constraints in North American and German fractionation centers create intermittent shortage vulnerability.
- Platelet Growth Factors:Recombinant thrombopoietin receptor agonists manufactured in CHO cell lines.
- Eltrombopag:Small-molecule TPO receptor agonist with oral bioavailability enabling outpatient chronic management.
The dominant share belongs to Corticosteroids, while Platelet Growth Factors is closing the gap fastest.
End User:
Care setting migration is redistributing revenue capture between institutional and distributed delivery models.
- Hospitals:Acute bleeding episodes and perioperative stabilization anchor inpatient hematology departments. Tertiary centers at Mayo Clinic and Memorial Sloan Kettering consolidate complex cases requiring multi-modality intervention.
- Specialty Clinics:Dedicated coagulation centers in Germany and Japan manage chronic ITP with scheduled monitoring protocols. These facilities capture stable patients requiring quarterly platelet surveillance rather than emergency intervention.
- Home Care:Subcutaneous formulation availability and remote monitoring infrastructure.
- Research Institutions:Academic medical centers conducting natural history studies and pivotal trials.
Hospitals retain the largest patient volume, though Home Care is expanding most quickly as self-administration protocols mature.
Therapy Area:
Patient age and underlying disease mechanism dictate treatment sequencing and duration economics.
- Pediatrics:Chronic immune thrombocytopenia in patients under 18 remains underpenetrated by thrombopoietin receptor agonists due to limited pediatric trial data and FDA/EMA label restrictions.
- Hematology:Primary ITP and secondary thrombocytopenias from marrow failure syndromes. Academic hematology departments at Johns Hopkins and Heidelberg University Hospital drive protocol standardization and guideline development.
- Immunology:Autoimmune-mediated platelet destruction including SLE-associated cytopenias.
- Oncology:Chemotherapy-induced thrombocytopenia requiring platelet support during myelosuppressive regimens.
Hematology commands the established revenue base, while Pediatrics offers the steepest expansion trajectory as label extensions proceed.
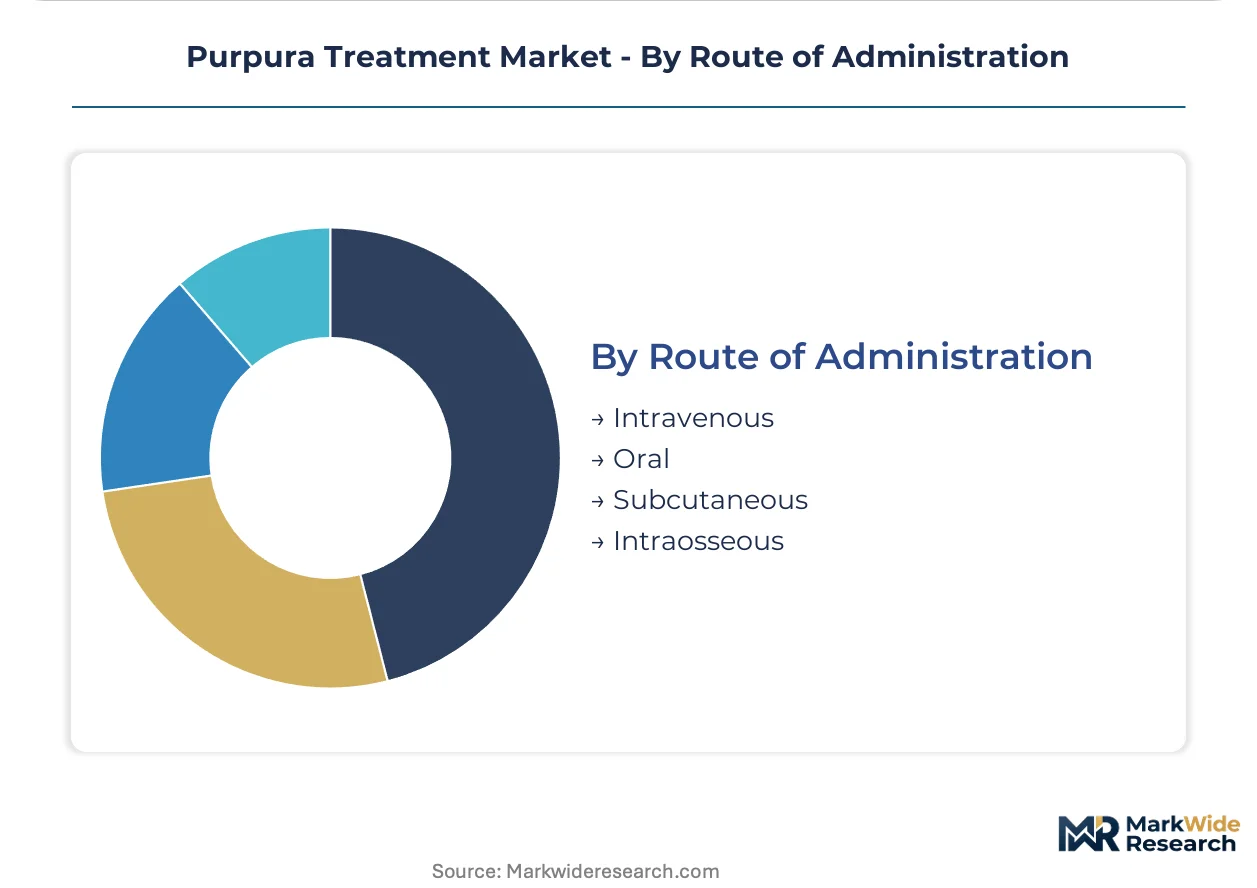
Route of Administration:
Delivery mechanism determines site-of-care economics and patient autonomy trade-offs.
- Intravenous:Hospital and infusion center administration for IVIG and romiplostim. Medicare reimbursement in the United States and German DRG codes sustain this channel despite higher facility costs.
- Oral:Eltrombopag and avatrombopag tablets enable daily self-management without infusion infrastructure.
- Subcutaneous:Weekly patient-administered injections of romiplostim.
- Intraosseous:Emergency vascular access for platelet transfusion in catastrophic hemorrhage when peripheral IV placement fails.
Intravenous maintains procedural dominance, yet Subcutaneous is gaining share fastest as home administration protocols achieve payer acceptance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and Japan concentrate purchasing authority for platelet-stimulating biologics, creating concentrated demand nodes that reshape vendor access strategies across developed markets.
United States
Mayo Clinic and Memorial Sloan Kettering anchor tertiary hematology networks that standardize thrombopoietin receptor agonist protocols. FDA orphan drug designation accelerates review timelines for rare hematology indications. The Mayo Clinic Rochester campus operates as a natural history study hub that establishes comparator benchmarks for pivotal ITP trials.
Germany
Heidelberg University Hospital and Charité Berlin drive protocol standardization through academic hematology departments with embedded coagulation centers. EMA PRIME eligibility frameworks offer protocol assistance for innovative biologics targeting unmet needs. The Rhine-Neckar metropolitan region concentrates fractionation capacity for plasma-derived immunoglobulin production.
Japan
PMDA sakigake designation compresses time-to-market for first-in-class platelet receptor agonists through priority review pathways. Tokyo and Osaka metropolitan areas host specialized coagulation centers that manage chronic ITP with quarterly monitoring protocols. The Kanto region anchors clinical trial activity for pediatric indication expansions.
United Kingdom
NHS England's specialized commissioning frameworks concentrate rare hematology treatment at designated tertiary centers in London and Manchester. NICE technology appraisals extend market access negotiations by 18-24 months beyond regulatory approval. The Oxford-Cambridge-London golden triangle anchors academic medical center research partnerships.
Switzerland
Swissmedic maintains alignment with EMA centralized procedures while offering national protocol assistance for hematology biologics. Basel and Zurich host manufacturing scale in recombinant protein production. The Basel biotech cluster concentrates cell culture expertise for thrombopoietin receptor agonist supply.
Purpura Treatment Market Competitive Environment
Channel-controlling players compete with product-specialist players across hospital formulary access and home care distribution. The vendor base organizes around three tiers: integrated pharmaceutical conglomerates with immuno-oncology infrastructure, recombinant protein specialists with manufacturing scale, and plasma fractionation operators with immunoglobulin supply chains. Consolidation pressure concentrates purchasing authority at integrated delivery networks while biologics manufacturing workforce scarcity limits contract manufacturing options. Dominant competitive moves include strategic partnerships for infusion support capabilities and geographic expansion into coagulation center networks.
Among integrated pharmaceutical conglomerates, Bristol-Myers Squibb Company and Novartis AG occupy positions that exemplify channel-control strategies through hospital specialty sales networks. Pfizer Inc. represents the archetype of extending immuno-oncology infrastructure into hematology biologics with overlapping mechanism expertise. These three companies anchor the competitive structure by leveraging manufacturing scale and regulatory navigation capabilities that smaller plasma fractionation specialists cannot replicate.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Novartis AG |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd |
| Amgen Inc |
| GlaxoSmithKline Plc. |
| Sanofi |
| Grifols Biologicals Inc |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Neckar metropolitan region anchors plasma fractionation capacity for immunoglobulin production, where donor pool fluctuations in German and North American collection centers transmit directly into IVIG pricing volatility for hospital buyers. Recombinant thrombopoietin receptor agonist manufacturing in Basel and Boston biotech clusters operates on contrasting economics, with CHO cell line production costs insulating premium pricing against plasma supply shocks.
Pricing Analysis
Cost-plus contracts with plasma cost pass-through indexation dominate IVIG procurement, tying hospital formulary prices to fractionation input costs. Three-tier pricing structure across premium biologics, standard immunoglobulins, and generic corticosteroids reflects manufacturing complexity and regulatory burden. Pricing pressure stems from corticosteroid commoditization, while thrombopoietin receptor agonists retain pricing power through biologic exclusivity. Integrated delivery networks exhibit highest price sensitivity in immunoglobulin tenders, whereas academic medical centers prioritize clinical efficacy over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and European Union threatens recombinant protein equipment and cell culture media flows. Supply concentrates in the United States, Germany, and Switzerland for plasma fractionation and recombinant manufacturing. Raw material dependencies include human plasma donations, CHO cell lines, and specialized chromatography resins. Single-source vulnerability characterizes contract manufacturing organization capacity for biologics. Distribution runs through hospital centralized purchasing committees and specialty pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Purpura Treatment Market exhibits cyclical recovery characteristics as post-pandemic plasma collection normalization restores immunoglobulin supply equilibrium. Cyclical driver: donor pool expansion following COVID-era collection disruptions.
For Market Incumbents:Harden manufacturing scale advantages through captive cell culture capacity expansion in Basel and Boston clusters. Consolidate infusion support capabilities to defend against biosimilar entrants in thrombopoietin receptor agonists. Vertical integration into plasma collection networks mitigates donor pool volatility threatening IVIG margins.
For New Entrants and Emerging Players:Japanese pediatric indication expansion offers underpenetrated white-space as PMDA sakigake pathways compress regulatory timelines. Home care subcutaneous formulation development represents the most penetrable segment, with remote monitoring infrastructure enabling patient-managed protocols. Go-to-market angle: partnership with Catholic health system centralized purchasing committees for immunoglobulin tender access.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors recombinant protein specialists with CHO platform expertise over plasma fractionation operators facing structural supply constraints. Long-term viability hinges on manufacturing workforce development and regulatory navigation capabilities. Signal to watch: FDA pediatric label expansion approvals for thrombopoietin receptor agonists as inflection indicator for addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Enables home care migration and reduces infusion center capacity constraints for chronic ITP patients. |
| Pediatric Indication Expansion | Unlocks FDA and EMA label extensions for thrombopoietin receptor agonists in underpenetrated patient populations. |
| Plasma Collection Network Integration | Secures donor pool access and insulates IVIG supply against fractionation center concentration risk. |
| Remote Monitoring Platform Deployment | Supports Mayo Clinic and Memorial Sloan Kettering protocols for distributed platelet surveillance. |
| WHO Prequalification Pathway | Opens procurement access for immunoglobulin products in lower-resource national health systems. |
Study Parameters
A spread of perspectives from hematology department directors, hospital procurement managers, plasma fractionation executives, regulatory affairs specialists, and payer access leads converged on the working assumptions. Primary interview insights combined with secondary validation against FDA orphan drug filings, EMA PRIME submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up patient population sizing and top-down manufacturer revenue triangulation anchored volume estimates.
Demand-supply balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled include therapeutic modality, route of administration, care setting, and regional regulatory cluster. CAGRs derived from patient prevalence trends, treatment penetration assumptions, and pricing trajectory analysis. Forecast inputs incorporated plasma collection recovery rates and thrombopoietin receptor agonist label expansion timelines.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement policy and biologics manufacturing labor availability would shift the trajectory. Forecasts reflect documented assumptions on donor pool recovery and regulatory approval timelines. Material shifts in FDA pediatric indication requirements or EMA PRIME evidentiary standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
US and Japan Platelet Rich Plasma Market
Medical Treatment
Rotator Cuff Injury Treatment Market
Medical Treatment
Systemic Mastocytosis Treatment Market
Medical Treatment
Ringworm Treatment Market
Medical Treatment
Disseminated Intravascular Coagulation (DIC) Treatment Market
Medical Treatment
Meningococcal Meningitis Treatment Market
Medical Treatment
Isovaleric Acidemia Treatment Market
Medical Treatment
Global Sex Reassignment Surgery Market
Medical Treatment
Migraine Treatment Market
Medical Treatment
Babesiosis Treatment Market
Medical Treatment
Prion Disease Treatment Market
Medical Treatment
Global Uterine Fibroids Treatment Market
Medical Treatment
Frozen Skin Graft Market
Medical Treatment
Radioimmunotherapy Treatment Market
Medical Treatment
Postoperative Nausea and Vomiting (PONV) Management Market
Medical Treatment
Morquio Syndrome Treatment Market