
 Global Proton Therapy Market | 2026-2036
Global Proton Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Proton Therapy Market Foresight
Modular single-room system configurations is broadening buyer choice among hospitals with constrained capital budgets and limited facility footprints. Ion Beam Applications leverages its installed base across European academic medical centers to sustain recurring service revenue. Hitachi competes through integrated proton and heavy-ion therapy platforms that anchor its position in Asian oncology markets.
Proton therapy delivers targeted radiation treatment using accelerated proton beams that deposit energy at precise tissue depths defined by the Bragg peak phenomenon, sparing adjacent healthy structures. The technology serves primarily for treating localized tumors near critical organs in pediatric, brain, and head and neck indications. Multi-room systems dominate capital expenditure flows among flagship cancer institutes, while single-room installations represent the fastest-growing configuration as community hospitals seek proton capability without billion-scale investments. Pencil beam scanning technology commands premium positioning due to superior dose conformality compared with passive scattering approaches.
FDA clearance pathways govern system commercialization in the United States, while CE marking under the EU MDR shapes European market access requirements for proton therapy devices. The EPA oversees radioactive material handling protocols that constrain facility siting and operational licensing across American installations. Stakeholders must monitor evolving reimbursement decisions by CMS and parallel national health technology assessment bodies, as these determinations directly dictate provider willingness to commit capital toward proton center development.
Market Dynamics
Pencil beam scanning technology is compressing treatment planning cycles while intensifying competition among system vendors for installation contracts at mid-sized oncology centers.
Growth Catalysts
- Bragg peak physics:Proton energy deposition at precise tissue depths enables dose escalation to tumors adjacent to critical organs in pediatric and cranial indications.
- CMS reimbursement pathways:Medicare coverage determinations for proton therapy in specific cancer types sustain hospital capital commitment to facility development across United States metropolitan markets.
- Japan's aging oncology infrastructure:Replacement demand for aging cobalt units at Japanese university hospitals is redirecting capital toward proton and heavy-ion capabilities.
Market Restraints
- Cyclotron manufacturing concentration:Superconducting magnet supply chains concentrate among specialized cryogenic engineering firms in Germany and Switzerland, creating procurement bottlenecks for system assemblers.
- Facility siting restrictions:EPA radioactive materials licensing requirements constrain proton center development near dense urban populations in the United States, extending project timelines.
- Linear accelerator alternatives:Advanced MRI-guided radiotherapy systems from conventional vendors present substitute competition for certain CNS and prostate indications.
Strategic Opportunities
- India's tertiary hospital expansion:Corporate hospital chains in Mumbai, Delhi, and Chennai are evaluating proton capability as differentiation for medical tourism segments.
- FLASH radiotherapy convergence:Ultra-high dose rate delivery protocols are integrating with existing proton beam lines to reduce treatment fractions and expand patient throughput.
- Carbon ion therapy authorization:European national health technology assessment bodies in France, Italy, and Germany are revisiting reimbursement frameworks for heavier particle modalities.
Industry Challenges
- Medical physicist specialization:Treatment planning for intensity-modulated proton therapy requires expertise in Monte Carlo dose calculation methods that outpaces current training pipeline output.
- Legacy cobalt unit decommissioning:Proton center construction frequently requires concurrent management of radioactive source disposal from predecessor facilities, complicating project sequencing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Proton Therapy Market |
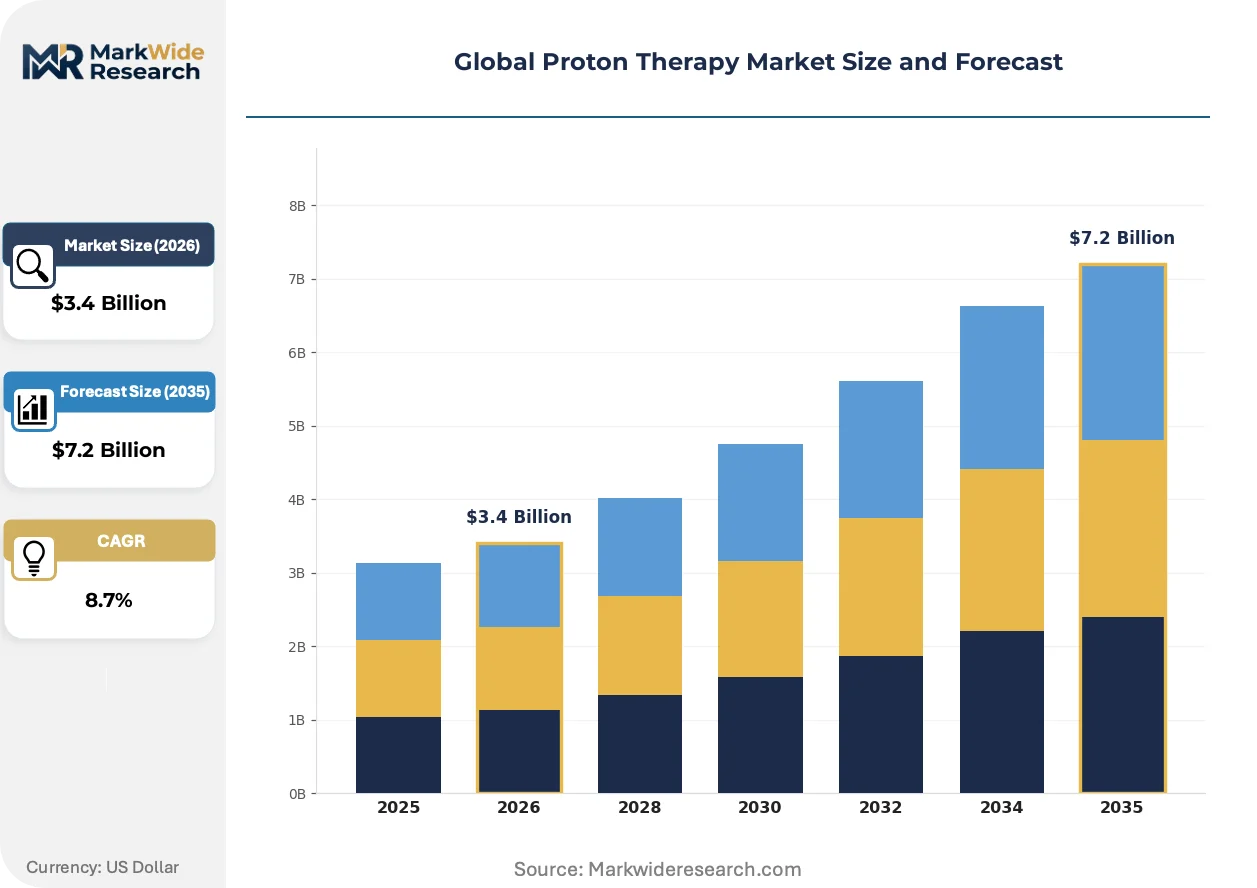
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Room Systems, Multi-Room Systems, Gantry Systems, Fixed Beam Systems Application: Brain Tumors, Head & Neck Cancer, Lung Cancer, Prostate Cancer, Pediatric Cancer End User: Hospitals, Cancer Research Institutes, Oncology Centers, Academic Medical Centers Technology: Spot Scanning, Uniform Scanning, Passive Scattering, Pencil Beam Scanning |
| Companies Covered | Ion Beam Applications, Hitachi, Mevion Medical Systems, Varian Medical Systems, Sumitomo Heavy Industries, Siemens Healthineers, Mitsubishi Electric, ProNova Solutions, Optivus Proton Therapy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Proton Therapy Market Shifts & Advancements
Adaptive planning workflows and real-time imaging integration are compressing the gap between simulation and first treatment delivery, reshaping operational metrics for proton center profitability.
Artificial intelligence-based auto-segmentation is integrating with treatment planning systems to reduce contouring time for organs-at-risk in head and neck protocols. Community proton centers in Texas and Florida are adopting these tools to maintain patient volumes without expanding physics staffing. The technology is integrating previously separate quality assurance steps into unified planning workflows, compressing the time from simulation to beam-on.
The EU Medical Device Regulation's clinical evidence requirements for software-as-a-medical-device are extending certification timelines for proton therapy planning algorithms. European notified bodies are demanding prospective validation datasets that exceed prior CE marking standards for passive scattering legacy systems. German and Dutch proton centers are responding by consolidating purchasing decisions to vendors with established MDR technical documentation.
Hospital procurement committees are unbundling service contracts from initial capital purchases, treating multi-year maintenance agreements as separately negotiable spend categories. Academic medical centers in the United States are leading this shift, using independent service organization alternatives to benchmark OEM pricing. The practice is most visible among National Cancer Institute-designated centers with established in-house engineering capabilities.
Global Proton Therapy Market Segmentation
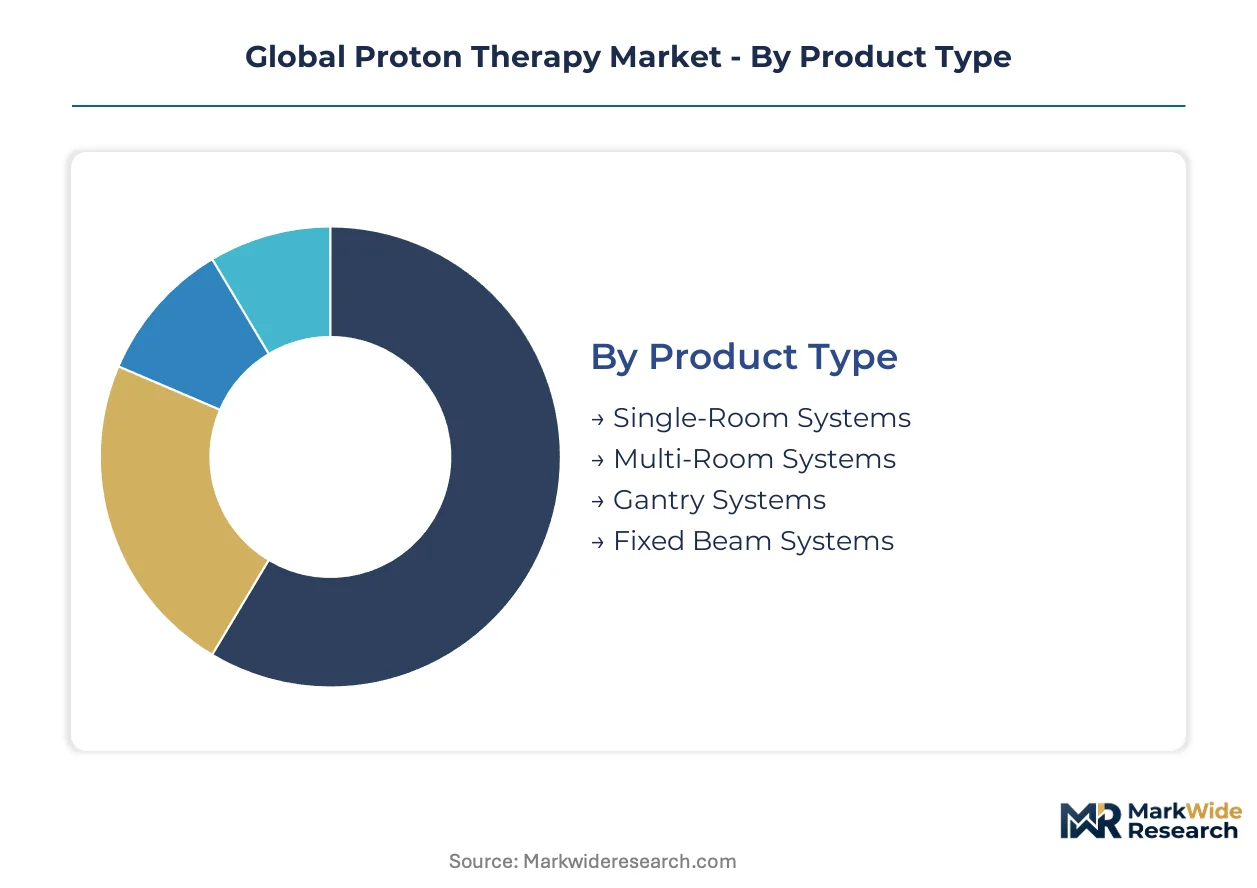
Proton therapy system configurations diverge sharply by capital intensity and clinical throughput requirements. Treatment protocols vary by tumor location sensitivity, while procurement authority concentrates among distinct institutional types with divergent budget cycles.
Product Type:
Replacement cycles for legacy cyclotron facilities are accelerating procurement decisions as first-generation proton centers reach end-of-life.
- Single-Room Systems:Compact accelerator-isocenter configurations reduce shielding requirements and construction timelines for community hospitals. Demand concentrates in Texas and Florida where independent oncology groups seek proton capability without academic medical center scale.
- Multi-Room Systems:Centralized beam delivery infrastructure serving 3-5 treatment rooms maximizes patient throughput at flagship cancer institutes. German university hospitals in Heidelberg and Essen anchor European demand for these configurations.
- Gantry Systems:Rotational beam delivery enabling 360-degree patient positioning commands premium positioning in cranial and spinal protocols.
- Fixed Beam Systems:Stationary horizontal/vertical beam lines serve ocular and shallow tumor indications with reduced mechanical complexity.
Multi-Room Systems sit at the top of the volume ranking, with Single-Room Systems climbing the fastest.
Application:
Clinical evidence thresholds vary by tumor site, determining reimbursement authorization timelines across national health technology assessment bodies.
- Brain Tumors:Proximity to optic nerves and brainstem makes dose conformality critical for glioma and meningioma protocols. Japanese neuro-oncology centers in Tokyo and Osaka prioritize proton capability for skull base lesions.
- Pediatric Cancer:Developing tissue sensitivity to radiation damage drives proton preference for solid tumors in children. St. Jude Children's Research Hospital and Boston Children's Hospital anchor North American demand.
- Head & Neck Cancer:Parotid gland and spinal cord sparing requirements favor proton delivery for oropharyngeal protocols.
- Lung Cancer:Cardiac and esophageal dose reduction potential is expanding proton evaluation for locally advanced non-small cell cases.
- Prostate Cancer:Rectal and bladder sparing claims face comparative effectiveness scrutiny from CMS coverage determinations.
Pediatric Cancer commands the steepest expansion trajectory, with Brain Tumors maintaining the largest installed treatment base.
End User:
Budget authority and depreciation schedules fragment procurement patterns across institutional categories with distinct capital allocation processes.
- Academic Medical Centers:Research mission requirements and NIH funding access enable multi-room system commitments. University of Pennsylvania and MD Anderson anchor United States capacity expansion.
- Oncology Centers:Specialized cancer focus without teaching obligations permits faster technology adoption cycles. Texas Oncology and Florida Cancer Specialists evaluate single-room configurations.
- Hospitals:General acute care institutions with proton capability concentrate in metropolitan markets with elevated commercial payer density.
- Cancer Research Institutes:Dedicated research facilities prioritize beam time allocation for clinical trial protocols over routine patient volumes.
Academic Medical Centers retain the dominant share of active installations, with Oncology Centers gaining share fastest.
Technology:
Dose delivery precision and planning complexity create tiered competitive positioning among beam modulation approaches.
- Pencil Beam Scanning:Layer-by-layer dose painting with millimeter-scale spot positioning enables intensity-modulated proton therapy. University Hospital Zurich and Massachusetts General Hospital pioneered clinical adoption.
- Passive Scattering:Range modulation using patient-specific compensators and apertures dominates legacy installed base but faces replacement pressure.
- Spot Scanning:Discrete spot delivery without continuous beam motion offers intermediate precision for uniform target volumes.
- Uniform Scanning:Expanded spot spacing reduces delivery time for large-field targets at modest conformality cost.
Passive Scattering retains the largest legacy footprint, with Pencil Beam Scanning displacing predecessor systems fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Proton therapy originated at research institutions in the United States and Switzerland during the mid-20th century, with clinical scaling accelerating through Japanese university hospitals in the 1990s. These three countries now anchor the installed base while emerging markets evaluate capital commitments.
United States
CMS reimbursement determinations for pediatric and CNS indications sustain hospital investment in proton capability. The FDA governs system clearance under 21 CFR 892.5050 while the EPA restricts radioactive material licensing near dense urban cores. Texas Medical Center in Houston and MD Anderson Cancer Center anchor multi-room system deployment, with community oncology groups in Florida adopting single-room configurations.
Germany
University hospitals in Heidelberg and Essen drive replacement demand for first-generation cyclotron facilities. CE marking under the EU MDR extends certification timelines for proton therapy planning software. The Heidelberg Ion Beam Therapy Center and West German Proton Therapy Centre in Essen concentrate European clinical expertise and training capacity.
Japan
Aging cobalt units at university hospitals in Tokyo and Osaka redirect capital toward proton and heavy-ion replacement. METI oversees medical device approval pathways that favor domestic heavy-ion platforms alongside proton systems. National Cancer Center Hospital and Hyogo Ion Beam Medical Center anchor patient volume concentration in the Kanto and Kansai regions.
Switzerland
Specialized cryogenic engineering firms in Geneva and Zurich supply superconducting magnets for cyclotron manufacturing. Swissmedic regulates medical device market access with requirements that align with EU MDR standards. Paul Scherrer Institute near Zurich maintains research beam lines that transition into clinical protocols.
India
Corporate hospital chains in Mumbai and Delhi evaluate proton capability as differentiation for medical tourism segments. CDSCO governs medical device import registration and clinical trial requirements for proton system installation. Tata Memorial Centre in Mumbai and All India Institute of Medical Sciences in Delhi anchor oncology infrastructure planning.
Global Proton Therapy Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and service bundling dimensions. The vendor base stratifies between integrated heavy-ion/proton platforms, compact single-room specialists, and legacy multi-room system providers. Two archetypes dominate: research-anchor institutions leveraging academic partnerships, and throughput-optimized vendors targeting community hospital procurement. Competitive moves concentrate on unbundling service contracts from capital sales and FLASH radiotherapy protocol integration.
Within the integrated platform tier, Hitachi and Mitsubishi Electric occupy positions exemplifying heavy-ion and proton convergence strategies. Ion Beam Applications represents the recurring-revenue archetype through European academic medical center service relationships. Mevion Medical Systems anchors the compact single-room configuration segment targeting constrained capital budgets.
| Leading Market Players |
|---|
| Ion Beam Applications |
| Hitachi |
| Mevion Medical Systems |
| Varian Medical Systems |
| Sumitomo Heavy Industries |
| Siemens Healthineers |
| Mitsubishi Electric |
| ProNova Solutions |
| Optivus Proton Therapy |
| Others |
Supply & Pricing Matrix
Academic medical center consortia and sovereign-backed hospital networks anchor capital procurement decisions, translating concentrated buyer power into extended payment terms and unbundled service contract negotiations that compress vendor margins while rewarding established installation track records.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pencil beam scanning configurations from passive scattering legacy systems and compact single-room alternatives. Price differentiation hinges on FDA 510(k) clearance tier and integrated heavy-ion capability, with German and Japanese academic centers least sensitive due to research funding access. Cost compression in single-room segments intensifies as community hospitals in Texas and Florida benchmark independent service organization alternatives against OEM maintenance agreements. Oncology centers without teaching obligations exhibit highest price sensitivity, driving procurement committees to treat multi-year service contracts as separately negotiable spend categories.
Supply Chain Analysis
Superconducting magnet supply rests on specialized cryogenic engineering firms concentrated in Switzerland, Germany, and Japan, creating procurement bottlenecks for cyclotron assemblers during facility expansion cycles. Niobium-titanium superconducting wire, precision-machined vacuum chambers, and radiation-hardened power electronics constitute critical input dependencies. Single-source vulnerability in superconducting coil winding expertise constrains manufacturing scale-up timelines. Distribution runs through direct vendor-hospital contracting with extended installation phases, supplemented by regional service hubs maintained by Ion Beam Applications and Hitachi near flagship cancer institutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between CMS reimbursement density in United States metropolitan corridors and capital subsidy availability through Japan's METI-directed hospital modernization programs, with cost differentials favoring Asian manufacturing integration.
For Market Incumbents: Lock in recurring service revenue through multi-year physics staffing contracts at European academic medical centers, insulating against independent service organization encroachment. Deepen backward integration into superconducting magnet production through captive supply arrangements with Geneva and Zurich engineering specialists, securing cyclotron manufacturing capacity against German and Swiss procurement bottlenecks. Prioritize FLASH radiotherapy protocol integration to differentiate pencil beam scanning platforms from MRI-guided linear accelerator substitutes encroaching on CNS indications. For New Entrants and Emerging Players: Enter via India's corporate hospital chains in Mumbai and Delhi, where medical tourism positioning creates proton capability demand without established vendor relationships. Target single-room system procurement at Florida and Texas community oncology groups seeking differentiation from academic medical center competitors. Pursue CDSCO import registration pathways alongside local clinical trial partnerships to anchor reference sites at Tata Memorial Centre and All India Institute of Medical Sciences. For Investors and Strategic Acquirers: Valuations sit cheapest among compact single-room specialists with constrained installed bases relative to recurring revenue potential. Long-term viability hinges on FLASH radiotherapy convergence and carbon ion therapy authorization timelines across European national health technology assessment bodies. Acquisition target archetype: vendors with established MDR technical documentation and unbundled service contract capabilities. Watch CMS coverage determination revisions for prostate and lung indications as volume inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates United States commercialization for pencil beam scanning upgrades at MD Anderson and University of Pennsylvania. |
| CE Marking Under EU MDR | Extends certification timelines for proton therapy planning software at German and Dutch notified bodies. |
| Hospital System Partnership | Secures multi-room installation commitments through research collaboration frameworks at Heidelberg and Essen university hospitals. |
| Software Companion Development | Integrates AI-based auto-segmentation with treatment planning systems at Texas and Florida community proton centers. |
| Reimbursement Strategy | Aligns CMS coverage determinations with pediatric and CNS indication expansion across United States metropolitan markets. |
Research Methodology
Multiple input streams — primary interviews with proton center medical physicists, hospital procurement committees, and cyclotron manufacturing engineers; secondary validation through FDA 510(k) filings, CE marking databases under EU MDR, and CMS Medicare reimbursement determinations; plus hospital procurement database analysis — were reconciled through bottom-up installation tracking and top-down market sizing triangulation.
Data-stream reconciliation across the projection horizon modeled system configuration segmentation by room count, beam delivery technology tier, and end-user institutional type, with geographic regulatory clusters capturing FDA, EPA, and CMS interactions in the United States alongside CE marking and national health technology assessment body dynamics in Europe. CAGRs were derived from installed base replacement cycles and greenfield expansion pipelines, incorporating cyclotron manufacturing lead times and radioactive materials licensing timelines as industry-specific forecast inputs.
Inputs from proton center operators and system vendors were available through the study window; gaps in FLASH radiotherapy clinical validation timelines and carbon ion therapy reimbursement decisions introduce uncertainty bands around adoption trajectory assumptions. Forecasts reflect documented assumptions regarding CMS coverage determination stability and EU MDR certification pathway durations. A small set of triggers — CMS prostate indication reversals, superconducting magnet supply disruptions, and India CDSCO regulatory acceleration — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Metastatic Cancer Drug Market
Oncology
Triple-Negative Breast Cancer Market
Oncology
South Korea Radiotherapy Market
Oncology
Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
PD1 Non-Small Cell Lung Cancer Treatment Market
Oncology
Cancer Cachexia Market
Oncology
AI in Oncology Market
Oncology
Testicular Cancer Treatment Market
Oncology
Cancer Supportive Care Products Market
Oncology
Kinase Inhibitors for Cancer Treatment Market
Oncology
Interventional Oncology Ablation Market
Oncology
Asia-Pacific Radiation Oncology Market
Oncology
Europe Proton Therapy Market
Oncology
Head and Neck Cancer Market
Oncology
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market