
 Global Acromegaly Treatment Market | 2026-2036
Global Acromegaly Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acromegaly Treatment Market Foresight
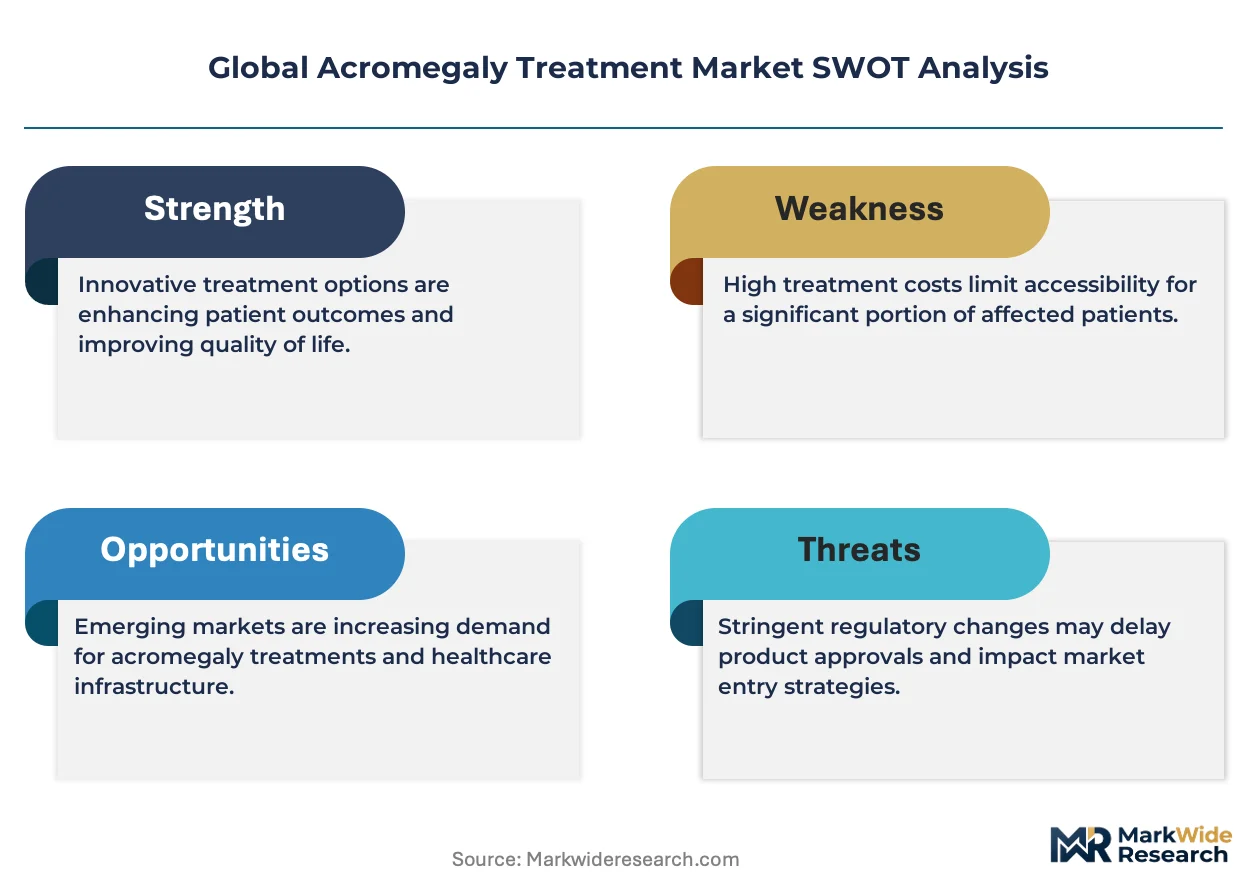
ISO 14155 clinical investigation standards for medical devices is unwinding competitive access for surgical device entrants in acromegaly care. Novartis AG dominates long-acting somatostatin analog supply through manufacturing scale and established orphan drug infrastructure. Pfizer Inc competes in growth hormone receptor antagonist therapy with specialized endocrinology sales channels. Chiasma, Inc. positions around oral delivery technology to differentiate from injectable-heavy treatment paradigms.
Acromegaly treatment encompasses pharmacological and surgical interventions targeting growth hormone hypersecretion from pituitary adenomas, with somatostatin analogs functioning through somatostatin receptor subtype 2 and 5 binding to suppress hormone release. The primary purpose is biochemical normalization of insulin-like growth factor-1 and growth hormone levels alongside tumor mass control. Somatostatin analogs anchor the product type landscape due to decades of clinical validation and reimbursement familiarity, while growth hormone receptor antagonists capture margin pools in refractory cases. Among delivery modes, injectables sustain dominant volume though oral formulations represent the fastest-growing structural opportunity as patient compliance pressures intensify.
FDA orphan drug incentives, EMA's centralized rare disease assessment pathways, and Japan's PMDA sakigake designation collectively shape development economics and market access timelines for novel acromegaly therapies. These frameworks elevate regulatory investment requirements while compressing commercialization risk for qualifying sponsors. Stakeholders must monitor oral bioavailability breakthroughs and pituitary surgery robotics integration as forces that could redistribute value across delivery modes and end-user settings.
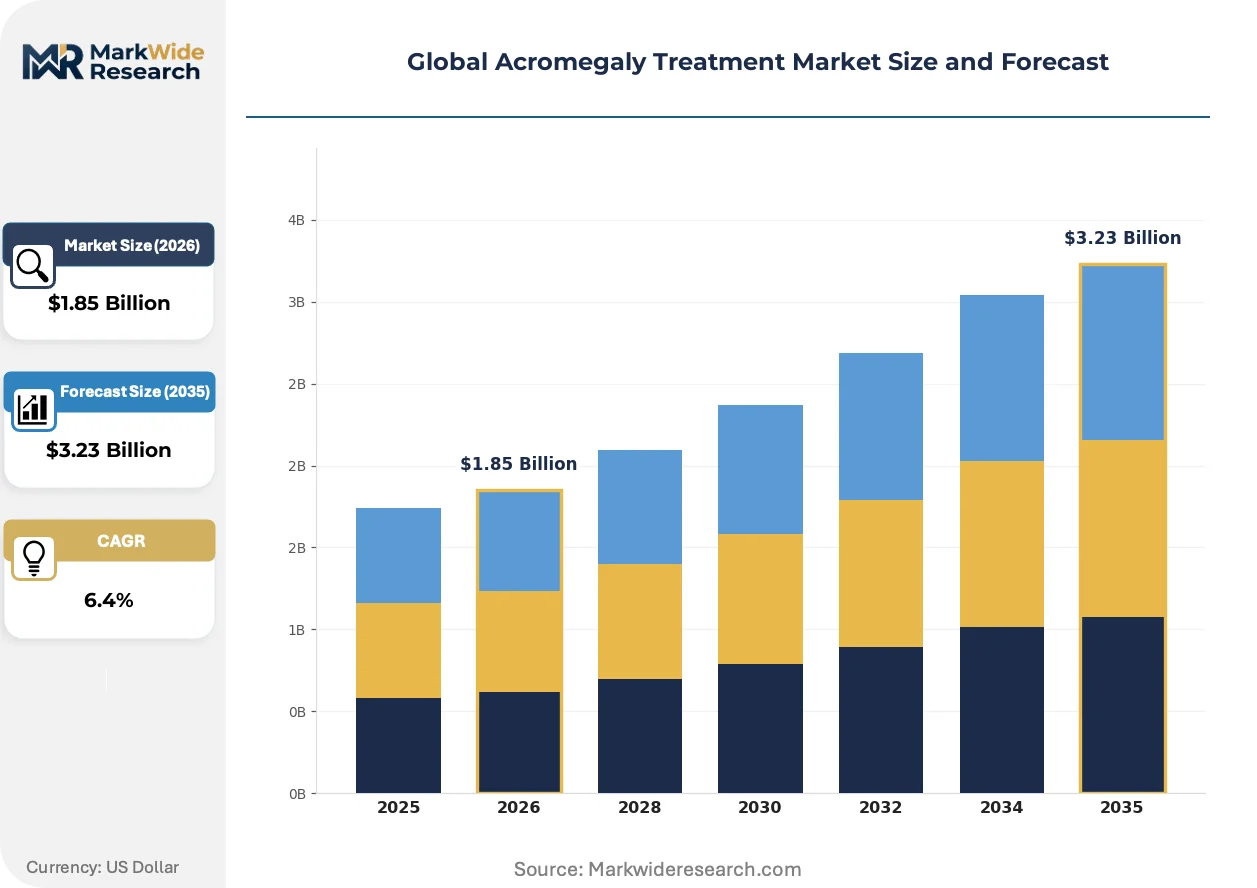
Market Dynamics
Oral bioavailability breakthroughs are compressing the dominance of long-acting injectable somatostatin analogs, forcing incumbents to defend reimbursement positions against patient compliance-driven formulary shifts.
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits and market exclusivity provisions accelerate novel therapy development timelines for sponsors targeting refractory patient populations.
- Pituitary Surgery Robotics:Minimally invasive endoscopic approaches expand eligible patient pools and reduce postoperative recovery periods at academic medical centers.
- IGF-1 Biomarker Standardization:Harmonized laboratory reference ranges improve diagnostic consistency and treatment monitoring precision across referral networks.
Market Restraints
- Peptide API Supply Concentration:Active pharmaceutical ingredient manufacturing for somatostatin analogs clusters among Swiss and Italian contract manufacturers, creating single-source vulnerability.
- EMA Centralized Assessment Complexity:Rare disease designation applications require extensive natural history data, extending pre-submission preparation cycles.
- Oral Formulation Bioavailability Ceiling:Cyclodextrin-based absorption enhancers face physiological limits in achieving therapeutic equivalence to parenteral delivery.
Strategic Opportunities
- Brazil Diagnostic Underpenetration:Endocrinology referral infrastructure expansion in São Paulo and Rio de Janeiro creates first-mover positioning for biochemical screening programs.
- Telemedicine-Enabled Monitoring:Remote IGF-1 level tracking and symptom assessment platforms extend specialist reach into secondary care catchment areas.
- Japan Sakigake Fast-Track:PMDA priority review vouchers compress regulatory timelines for sponsors demonstrating superiority in tumor shrinkage endpoints.
Industry Challenges
- Neuroendocrine Surgery Fellowship Scarcity:Transphenoidal procedure training programs graduate insufficient specialists to match pituitary center expansion plans.
- Biomarker Assay Harmonization:Growth hormone suppression test protocols vary across reference laboratories, complicating multicenter trial data pooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acromegaly Treatment Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Somatostatin Analogs, Growth Hormone Receptor Antagonists, Dopamine Agonists, Surgical Devices Application: Hormonal Regulation, Tumor Size Reduction, Symptom Management, Post-Surgical Care End User: Specialized Clinics, Academic Medical Centers, Diagnostic Laboratories, Ambulatory Surgical Centers Delivery Mode: Injectables, Oral Medications, Surgical Intervention, Radiotherapy |
| Companies Covered | Novartis AG, Ipsen Pharma, Pfizer Inc, Recordati S.p.A., Sun Pharmaceutical Industries Ltd, Chiasma, Inc., Amryt Pharma plc, Crinetics Pharmaceuticals, Ionis Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acromegaly Treatment Market Shifts & Advancements
Acromegaly care is fragmenting across delivery modes as oral formulations gain pharmacokinetic credibility and surgical robotics compress hospitalization duration. Incumbents must now compete on convenience vectors previously considered secondary to efficacy.
Chiasma's transient permeability enhancer technology is supplanting subcutaneous depot injections in patient preference studies. Endocrinology practices in Germany and the United States are piloting oral-first protocols for newly diagnosed cases. The shift is compressing manufacturing scale advantages previously held by long-acting injectable suppliers.
EMA's MDR recertification requirements for pituitary surgical instruments are elevating documentation burdens on device manufacturers. Small-cap entrants face capital constraints in assembling clinical investigation dossiers under ISO 14155 standards. German and French academic hospitals are consolidating purchasing around suppliers with established MDR technical files.
Patient advocacy networks are demanding unbundled pharmacy benefit designs that separate medical from pharmacy channel reimbursement. Large self-insured employers in the United States are negotiating carve-out arrangements for rare endocrine therapies. The pressure is most visible in pharmacy benefit manager formulary negotiations, where compliance metrics now influence tier placement decisions.
Global Acromegaly Treatment Market Segmentation
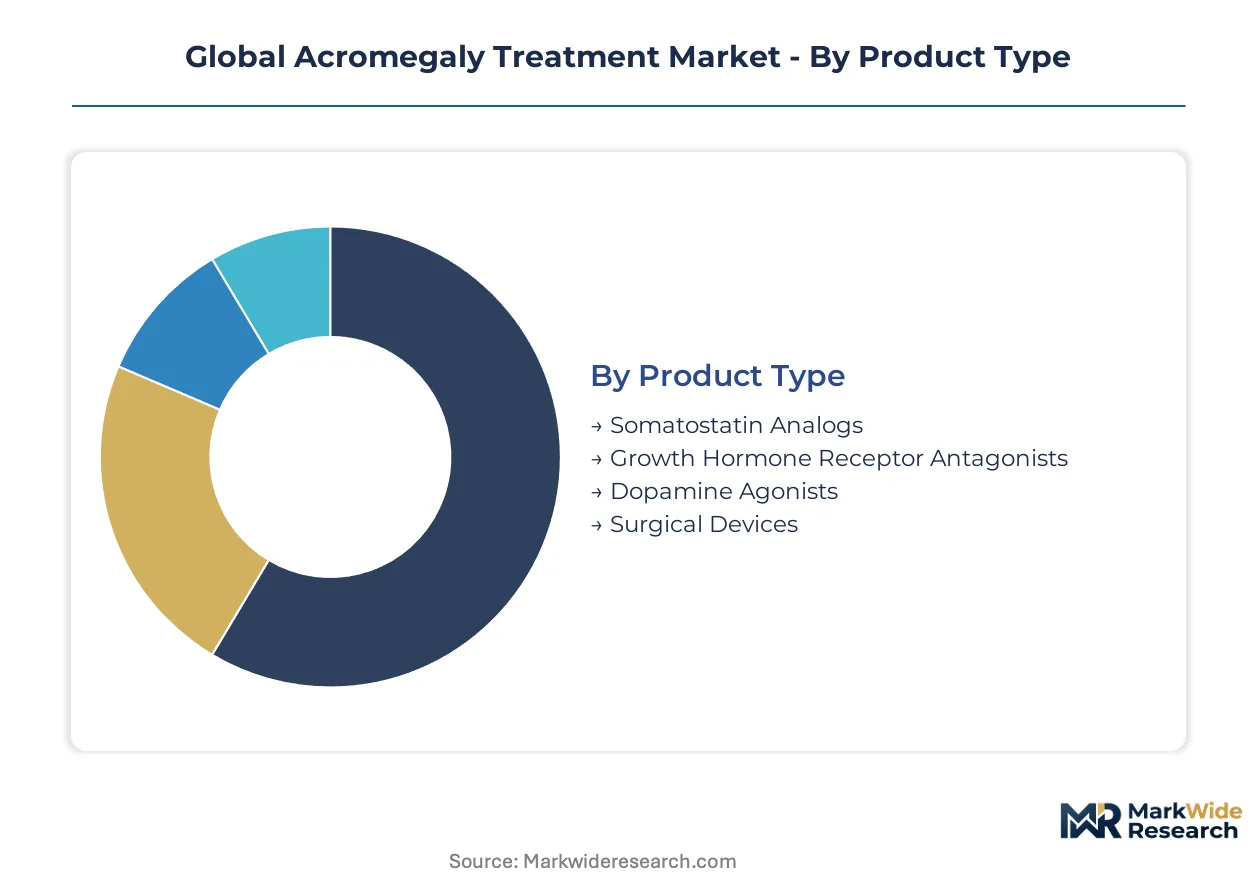
Acromegaly treatment segmentation reveals distinct margin architectures across pharmacological and interventional modalities. Product type and delivery mode categories concentrate profitability differently, with long-acting formulations commanding premium positioning against emerging oral alternatives.
Product Type:
Margin pools concentrate in peptide-based therapeutics with manufacturing complexity barriers, while surgical devices face pricing pressure from robotics standardization.
- Somatostatin Analogs:Synthetic peptide formulations binding somatostatin receptor subtypes 2 and 5 to suppress growth hormone secretion. Demand clusters in the United States and Germany where Novartis AG's manufacturing scale supports established orphan drug reimbursement. EMA centralized assessment pathways reinforce incumbent positioning through clinical data requirements.
- Growth Hormone Receptor Antagonists:Pegvisomant-based therapy blocking peripheral GH action through competitive receptor antagonism. Academic medical centers in Japan and the United States deploy this modality for refractory cases, with PMDA sakigake designation accelerating access timelines for novel entrants.
- Dopamine Agonists:Ergot-derived compounds offering partial efficacy in prolactin-co-secreting adenomas.
- Surgical Devices:Endoscopic instruments and navigation systems for transsphenoidal adenoma resection.
Somatostatin analogs retain the dominant share, though growth hormone receptor antagonists are expanding most quickly in refractory patient pools.
Application:
Revenue concentration tracks biochemical normalization endpoints versus tumor mass control, with monitoring-intensive applications sustaining recurring revenue streams.
- Hormonal Regulation:Primary therapeutic objective targeting insulin-like growth factor-1 and growth hormone level normalization. Specialized clinics in the United States structure care pathways around quarterly biomarker monitoring, with IGF-1 assay standardization improving treatment precision.
- Tumor Size Reduction:Neoadjuvant and primary cytoreductive therapy to decompress optic apparatus and restore pituitary function. Academic medical centers in Germany integrate volumetric MRI assessment into treatment algorithms, with robotics-enabled surgery expanding eligible patient populations.
- Symptom Management:Addressing arthropathy, sleep apnea, and metabolic comorbidities of chronic GH exposure.
- Post-Surgical Care:Adjuvant pharmacological therapy following incomplete resection.
Hormonal regulation commands the largest application share, while tumor size reduction is gaining share fastest through surgical robotics adoption.
End User:
Procurement authority and reimbursement complexity determine account profitability across institutional settings.
- Specialized Clinics:Dedicated pituitary disorder units within endocrinology practices managing stable patients on chronic therapy. São Paulo and Rio de Janeiro clinic networks are expanding diagnostic infrastructure, creating first-mover positioning for biochemical screening programs in Brazil.
- Academic Medical Centers:Tertiary referral hubs integrating surgery, radiation oncology, and medical management. Centers in the United States, Germany, and Japan concentrate complex case volume, with fellowship-trained neuroendocrine surgeons driving device procurement decisions.
- Diagnostic Laboratories:Reference facilities performing GH suppression testing and IGF-1 quantification.
- Ambulatory Surgical Centers:Outpatient settings for select transsphenoidal procedures.
Academic medical centers hold the dominant end user position, while specialized clinics are climbing the fastest through telemedicine-enabled monitoring expansion.
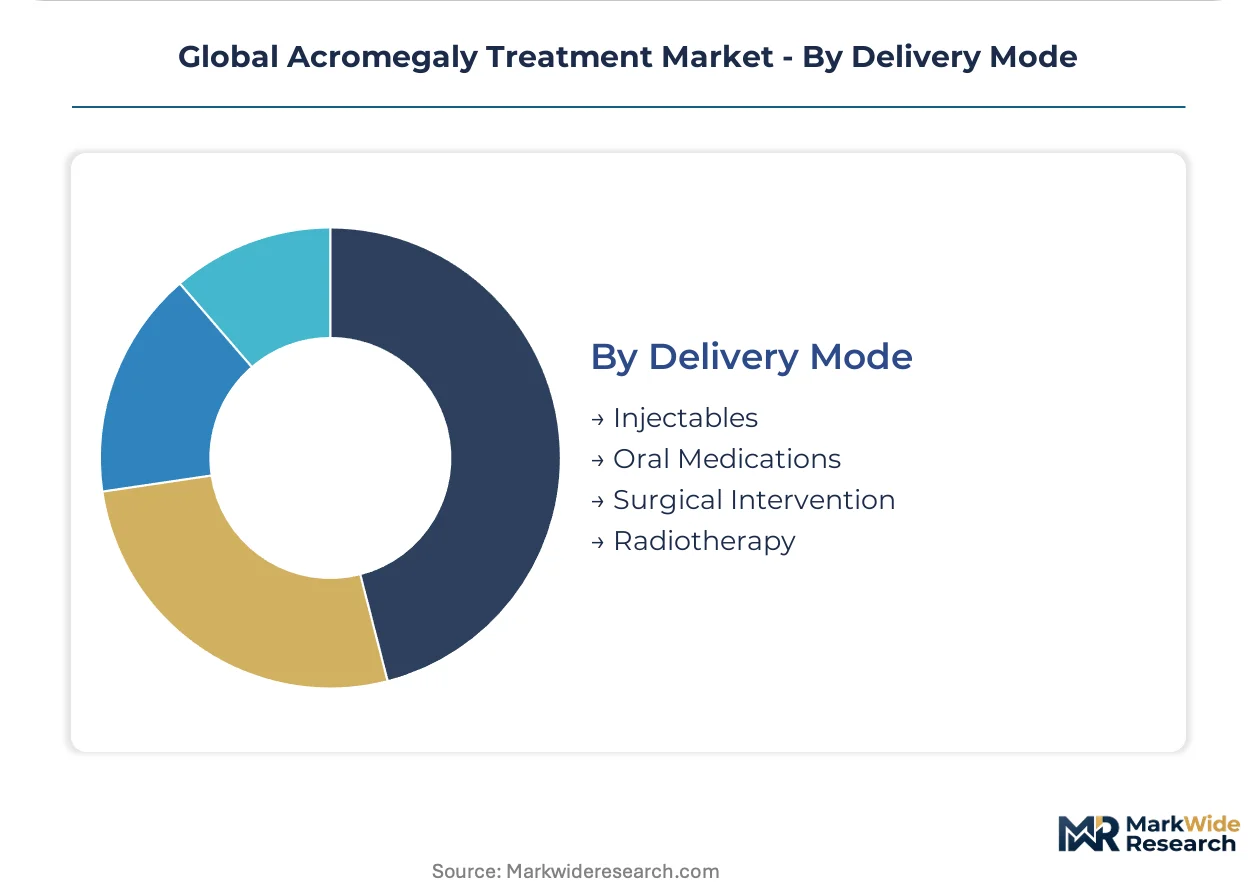
Delivery Mode:
Patient compliance economics and manufacturing scale advantages create divergent profitability profiles across administration routes.
- Injectables:Subcutaneous depot formulations including long-acting somatostatin analogs and growth hormone receptor antagonists. Manufacturing concentration among Swiss and Italian contract suppliers creates API supply vulnerability, while established reimbursement codes protect incumbent positions.
- Oral Medications:Chiasma's transient permeability enhancer technology and cyclodextrin-based absorption systems. Patient preference studies in Germany and the United States show oral-first protocol adoption, with pharmacy benefit manager tier negotiations increasingly weighting compliance metrics.
- Surgical Intervention:Transsphenoidal and transcranial approaches for adenoma resection.
- Radiotherapy:Stereotactic radiosurgery for residual or recurrent disease.
Injectables maintain the dominant delivery mode share, though oral medications are gaining share fastest through bioavailability breakthroughs and formulary prioritization of adherence outcomes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's orphan drug designation pathway anchors United States market access infrastructure, while EMA centralized assessment frameworks and PMDA sakigake fast-tracks create parallel regulatory highways across developed economies.
United States
Specialized endocrinology referral networks concentrate demand in Boston, New York, and Houston academic medical centers. FDA orphan drug incentives compress development timelines for sponsors targeting refractory patient populations. Novartis AG's manufacturing scale supports established reimbursement codes for long-acting somatostatin analogs through dedicated orphan drug infrastructure.
Germany
Endocrinology departments at Heidelberg, Berlin, and Munich university hospitals are expanding dedicated pituitary disorder units. EMA MDR recertification requirements for surgical instruments are elevating documentation burdens on device manufacturers. German academic hospitals are consolidating purchasing around suppliers with established MDR technical files under ISO 14155 standards.
Japan
PMDA sakigake designation accelerates access timelines for novel entrants demonstrating superiority in tumor shrinkage endpoints. Tokyo and Osaka academic centers concentrate complex case volume with fellowship-trained neuroendocrine surgeons. Growth hormone receptor antagonist therapy captures margin pools in refractory cases through specialized endocrinology sales channels.
Brazil
Endocrinology referral infrastructure expansion in São Paulo and Rio de Janeiro creates first-mover positioning for biochemical screening programs. ANVISA regulatory pathways for rare disease therapies are stabilizing as the agency builds specialized review capacity. Diagnostic underpenetration in secondary cities is driving telemedicine-enabled monitoring platform adoption.
Switzerland
Active pharmaceutical ingredient manufacturing for somatostatin analogs clusters among Swiss contract manufacturers, creating single-source vulnerability for peptide supply. Swissmedic maintains alignment with EMA centralized assessment pathways for rare disease designations. Basel and Zurich host concentrated pharmaceutical manufacturing infrastructure serving global orphan drug supply chains.
Global Acromegaly Treatment Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and delivery mode innovation. The market structure concentrates around peptide-based therapeutic incumbents with established orphan drug infrastructure, while oral formulation specialists challenge injectable dominance through patient compliance vectors. Three archetypes define competitive positioning: long-acting injectable scale players, oral bioavailability technology disruptors, and surgical robotics device suppliers. Dominant competitive moves include M&A to secure API manufacturing capacity and strategic partnerships to accelerate oral formulation development.
Within the scale-driven tier, Novartis AG and Pfizer Inc occupy positions anchored by manufacturing infrastructure and specialized endocrinology sales channels. Chiasma, Inc. exemplifies the oral delivery technology archetype, positioning around transient permeability enhancer systems to differentiate from injectable-heavy treatment paradigms. These three entities collectively represent the competitive tension between incumbent manufacturing advantages and emerging patient preference shifts.
| Leading Market Players |
|---|
| Novartis AG |
| Ipsen Pharma |
| Pfizer Inc |
| Recordati S.p.A. |
| Sun Pharmaceutical Industries Ltd |
| Chiasma, Inc. |
| Amryt Pharma plc |
| Crinetics Pharmaceuticals |
| Ionis Pharmaceuticals, Inc. |
| Others |
Supply & Pricing Matrix
Oral bioavailability breakthroughs displacing long-acting injectable somatostatin analogs simultaneously reshape API sourcing geography toward cyclodextrin and permeability enhancer suppliers in the United States and Japan, while compressing manufacturing scale premiums previously captured by Swiss and Italian peptide contract manufacturers.
Pricing Analysis
Certification level creates the primary spread across the acromegaly treatment landscape, with FDA orphan drug designation and EMA centralized rare disease assessment commanding premium positioning against standard therapeutic categories. Three-tier pricing structure across premium, standard, and economy levels stratifies by biochemical normalization efficacy and tumor shrinkage endpoints. Pricing pressure stems from pharmacy benefit manager formulary negotiations increasingly weighting patient compliance metrics over legacy efficacy data. Self-insured employers in the United States demonstrate highest price sensitivity through carve-out demands, while academic medical centers in Germany and Japan retain lowest sensitivity due to bundled reimbursement pathways.
Supply Chain Analysis
Strategic stockpiling of peptide active pharmaceutical ingredients dominates inventory strategy among Swiss and Italian contract manufacturers serving somatostatin analog production, contrasting with just-in-time preferences for oral formulation absorption enhancers. API manufacturing concentrates in Switzerland, Italy, and India, with cyclodextrin-based systems sourcing from Japan and the United States. Supply chain vulnerability rests on single-source peptide synthesis capacity for long-acting depot formulations. Distribution runs through specialized orphan drug channels and hospital pharmacy procurement at academic medical centers, with direct-to-specialist-clinic models emerging for oral alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acromegaly care is approaching a platform-economics inflection as telemedicine-enabled IGF-1 monitoring and remote symptom assessment create interoperable data layers that reward ecosystem orchestrators over single-modality suppliers.
For Market Incumbents: Fortify manufacturing scale advantages through backward integration into peptide API capacity in Switzerland and Italy, securing supply continuity against single-source vulnerabilities. Deepen orphan drug infrastructure investments to defend reimbursement positions against oral formulation entrants leveraging patient compliance metrics in pharmacy benefit manager negotiations. Prioritize certification maintenance under EMA MDR recertification requirements to preserve device purchasing consolidation at German and French academic hospitals.
For New Entrants and Emerging Players: Lead with oral bioavailability technology targeting specialized clinics in São Paulo and Rio de Janeiro, where diagnostic underpenetration creates white-space positioning for biochemical screening programs. Capture telemedicine-enabled monitoring adoption in United States secondary care catchment areas, extending specialist reach without capital-intensive center builds. Deploy pharmacy benefit manager direct contracting as the primary go-to-market angle, unbundling medical from pharmacy channel reimbursement to circumvent incumbent formulary blocks.
For Investors and Strategic Acquirers: PMDA sakigake designation acceleration reshapes the acquisition landscape toward Japan-registered assets demonstrating tumor shrinkage superiority, compressing regulatory timelines and expanding addressable refractory patient pools. Long-term viability centers on platform economics capture through monitoring data integration, with five-to-ten-year windows favoring ecosystem orchestrators over single-modality developers. Target oral formulation specialists with transient permeability enhancer intellectual property and established United States pharmacy channel relationships. Watch oral-first protocol adoption rates in Germany and United States endocrinology practices as the primary inflection signal for injectable displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Oral Formulation Development | Chiasma's transient permeability enhancer technology compresses injectable dominance through patient preference validation. |
| API Manufacturing Scale-Up | Swiss and Italian contract manufacturers expand peptide synthesis capacity to address single-source supply vulnerabilities. |
| Telemedicine Platform Integration | Remote IGF-1 monitoring extends specialist reach into secondary care catchment areas without center capital deployment. |
| EMA MDR Recertification Pathway | ISO 14155 clinical investigation dossiers elevate documentation burdens that consolidate purchasing among established device suppliers. |
| Orphan Drug Infrastructure Investment | FDA tax credits and market exclusivity provisions accelerate novel therapy timelines for refractory population sponsors. |
Research Methodology
A standing panel of pituitary center directors, formulary access specialists at pharmacy benefit managers, orphan drug regulatory affairs leads, and biomedical procurement officers at academic medical centers provided ongoing calibration across primary interview waves. Secondary validation drew from FDA orphan drug designation filings, EMA centralized rare disease assessment decisions, PMDA sakigake designation records, and hospital GPO contract databases. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored segmentation outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical framework approaches segmenting by product type, delivery mode, application endpoint, and end-user procurement authority. CAGRs were derived from patient prevalence trajectories, treatment penetration curves, and pricing evolution assumptions. Forecast inputs incorporated biomarker assay harmonization progress, surgical robotics adoption rates at academic medical centers, and oral formulation bioavailability advancement timelines.
The analysis sits within stated boundaries; outcomes outside sustained orphan drug incentive frameworks, stable peptide API supply continuity, and current regulatory assessment timelines would require recalibration. Forecasts reflect documented assumptions regarding patient compliance preference shifts and reimbursement pathway evolution. Practitioners should keep alternative scenarios live as oral bioavailability equivalence data, telemedicine regulatory clarity, and pharmacy benefit unbundling negotiations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Secondary Hyperparathyroidism Treatment Market
Medical Treatment
Squamous Cell Carcinoma Treatment Market
Medical Treatment
Phototherapy Treatment Market
Medical Treatment
Tetanus Treatment Market
Medical Treatment
Peri-Implantitis Treatment Market
Medical Treatment
Lysosomal Disease Treatment Market
Medical Treatment
Alagille Syndrome Treatment Market
Medical Treatment
Hypothermia Management Market
Medical Treatment
Nontuberculous Mycobacterium Treatment Market
Medical Treatment
Global Rotator Cuff Treatment Market
Medical Treatment
Hyponatremia Treatment Market
Medical Treatment
Global Von Willebrand Disease Treatment Market
Medical Treatment
Asthma Treatment Market
Medical Treatment
Necrotizing Skin Infections Treatment Market
Medical Treatment
Psittacosis Treatment Market
Medical Treatment
Encephalitis Treatment Market