
 Global Intraoperative Radiation Therapy Market | 2026-2036
Global Intraoperative Radiation Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intraoperative Radiation Therapy Market Foresight
Software-defined treatment planning and remote system monitoring is shifting how vendors monetize intraoperative radiation therapy platforms. Elekta AB leverages its installed base of linear accelerators to bundle cloud-based dose optimization subscriptions. IntraOp Medical, Inc. anchors its competitive position through dedicated electron beam IORT specialization rather than general radiotherapy diversification. Varian Medical Systems, Inc. extends its reach via hospital-based deployment partnerships that lock in long-term service contracts.
Intraoperative radiation therapy delivers a concentrated dose of ionizing radiation directly to a tumor bed during surgical resection, typically using electron beams or low-energy x-rays at doses ranging from 10 to 20 Gy in a single fraction. The intervention aims to sterilize residual microscopic disease while sparing adjacent healthy tissue from the toxicity of conventional external beam fractionation. Linear accelerators and portable x-ray systems capture divergent margin profiles, with the former dominating capital-intensive academic installations and the latter penetrating ambulatory surgical centers seeking workflow flexibility. Breast cancer applications sustain the largest procedure volume, though gynecological malignancies represent a faster-growing addressable pool as cytoreductive surgery protocols expand.
The FDA regulates IORT devices under 21 CFR 1020.32 for diagnostic x-ray systems and radiation-emitting product performance standards, while the EMA's Medical Device Regulation imposes stricter clinical evidence requirements for CE-marked electron beam and brachytherapy platforms in Europe. Japan's PMDA maintains distinct technical standards for accelerator-based intraoperative systems that delay market entry relative to Western clearance pathways. Stakeholders must weigh regulatory capital requirements against the contracting risk of reimbursement denials as payors scrutinize single-fraction IORT cost-effectiveness against multi-week external beam alternatives.
Market Dynamics
Software-defined treatment planning and remote system monitoring is compressing vendor monetization models toward recurring revenue streams, displacing traditional capital-only sales cycles in intraoperative radiation therapy platforms.
Growth Catalysts
- EMA Medical Device Regulation:Stricter clinical evidence requirements for CE-marked electron beam platforms are accelerating quality differentiation among compliant manufacturers, advantaging prepared vendors in European university hospital procurement.
- Oncology departments:Academic medical centers in Germany, the United States, and Japan are expanding dedicated IORT programs as alternatives to fractionated external beam protocols, driving installed base growth.
- Electron beam specialization:Dedicated IORT linear accelerator technology is capturing preference over general radiotherapy systems in high-volume surgical oncology units seeking workflow integration.
Market Restraints
- Reimbursement scrutiny:United States payors are applying cost-effectiveness frameworks that disadvantage single-fraction IORT against multi-week external beam alternatives, constraining procedure volume expansion.
- Capital intensity:Linear accelerator installations require dedicated shielded surgical suites and specialized physics support, limiting penetration beyond academic medical centers and major metropolitan hospital systems.
- Technical limitation:Electron beam depth penetration constraints restrict IORT applicability to superficial tumor beds, excluding deep pelvic and thoracic malignancies from addressable procedure volumes.
Strategic Opportunities
- Gynecological malignancies:Cytoreductive surgery protocols are expanding IORT applicability beyond breast cancer into faster-growing procedure categories with unmet radiation therapy needs.
- Portable x-ray systems:Low-energy intraoperative platforms are penetrating ambulatory surgical centers seeking workflow flexibility without capital-intensive linear accelerator infrastructure.
- Japan PMDA pathway:Distinct technical standards for accelerator-based systems create first-mover advantages for manufacturers investing in early regulatory engagement and local clinical evidence generation.
Industry Challenges
- Medical physics workforce scarcity:Qualified intraoperative radiation therapy physicists remain concentrated in major academic centers, limiting program expansion into community hospital settings.
- FDA 21 CFR 1020.32 compliance:Radiation-emitting product performance standards require extensive documentation and testing protocols that extend certification timelines for device modifications and software updates.
- Legacy system integration:Surgical workflow coordination between IORT platforms and existing operating room equipment demands custom interfacing that fragments implementation timelines across hospital IT environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intraoperative Radiation Therapy Market |
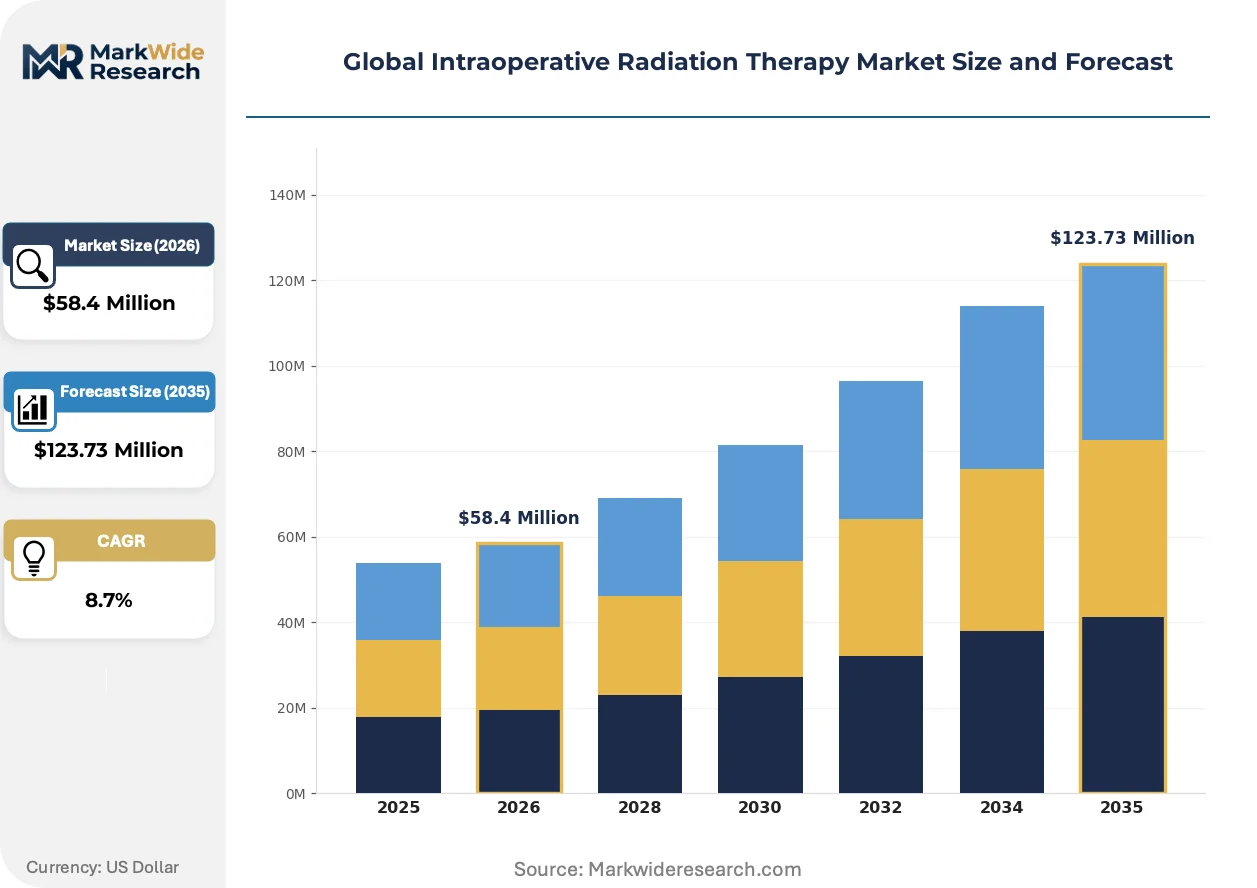
| Market Size in 2026 | $58.4 Million |
| Market Size in 2035 | $123.73 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Accelerators, Portable X-Ray Systems, Intrabeam Systems, Electron Beam Therapy Devices Application: Breast Cancer, Colorectal Cancer, Brain Tumors, Gynecological Malignancies End User: Cancer Treatment Centers, Specialty Clinics, Research Institutes, Ambulatory Surgical Centers Deployment Type: Hospital-based Units, Standalone Units, Mobile Units, Hybrid Systems |
| Companies Covered | Carl Zeiss Meditec AG, IntraOp Medical, Inc., Elekta AB, Eckert & Ziegler, iCAD, Inc., Varian Medical Systems, Inc., S.I.T. Sordina IORT Technologies S.p.A., IBA Worldwide, IsoRay, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intraoperative Radiation Therapy Market Shifts & Advancements
Cloud-native architecture and subscription monetization are displacing perpetual licensing in treatment planning software, restructuring how vendors capture lifetime value from intraoperative radiation therapy installations.
Mobile electron beam systems with integrated dose verification are unifying surgical and radiation oncology workflows into single-procedure protocols. Community hospital systems in the United States are piloting these platforms to avoid dedicated bunker construction. The technology is unifying previously separate capital budgets into consolidated surgical oncology investments.
Japan's PMDA maintains distinct technical standards for accelerator-based intraoperative systems that delay market entry relative to Western clearance pathways. Manufacturers targeting Japanese university hospitals must duplicate clinical evidence generation under local protocols. Electron beam platform vendors with early PMDA engagement are capturing preferred supplier status in Tokyo and Osaka metropolitan procurement cycles.
Hospital procurement committees are consolidating vendor relationships through long-term service contracts that bundle hardware, software, and physics support. This displaces transactional equipment purchasing in German and United States academic medical centers. Breast cancer centers in Heidelberg and Munich exemplify this shift toward total-cost-of-ownership contracting frameworks.
Global Intraoperative Radiation Therapy Market Segmentation
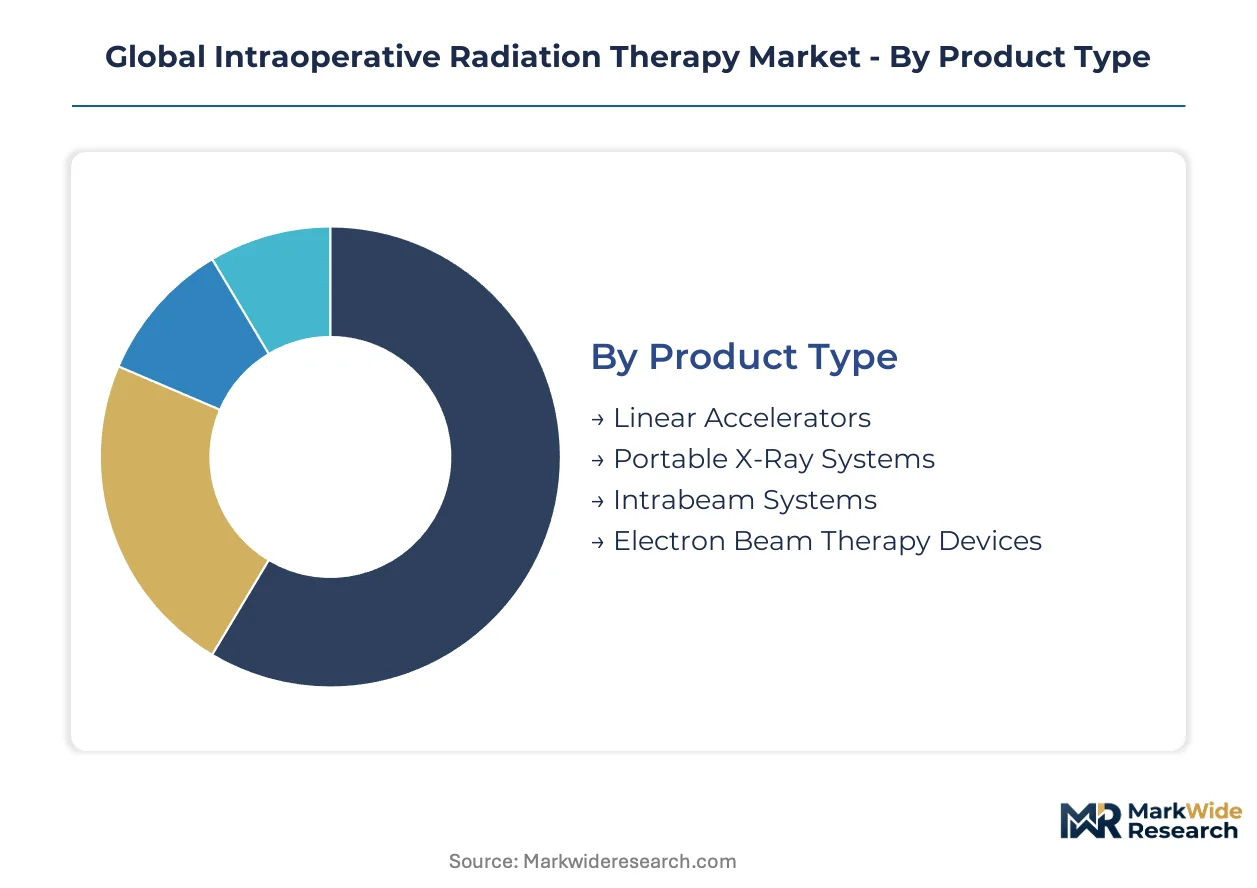
Technology differentiation across IORT platforms determines capital requirements, shielding infrastructure, and clinical workflow integration. Product specifications directly constrain addressable procedure volumes and shape vendor competitive positioning.
Product Type:
Electron beam penetration depth and dose rate specifications define the technical boundary between high-volume academic installations and flexible ambulatory deployments.
- Linear Accelerators:These systems generate high-energy electron beams with precise dose modulation and real-time verification. Demand concentrates in German university hospitals such as Heidelberg and Munich, where dedicated shielded surgical suites support high-throughput oncology programs.
- Portable X-Ray Systems:Low-energy intraoperative platforms eliminate bunker construction requirements and enable point-of-care deployment. Ambulatory surgical centers in the United States are adopting these systems to bypass capital-intensive infrastructure while maintaining single-fraction treatment capability.
- Intrabeam Systems:Spherical applicator technology delivers localized low-energy x-ray dose directly to tumor beds.
- Electron Beam Therapy Devices:Dedicated mobile units integrate surgical and radiation workflows without general-purpose linear accelerator overhead.
Linear accelerators lead on scale; portable x-ray systems lead on momentum.
Application:
Procedure volume distribution reflects the intersection of surgical resectability, residual disease risk, and reimbursement economics across malignancy types.
- Breast Cancer:Lumpectomy cavity irradiation during partial mastectomy sustains the largest installed base utilization. Academic medical centers in Germany and the United States anchor procedure concentration, though payor cost-effectiveness scrutiny constrains volume expansion.
- Gynecological Malignancies:Cytoreductive surgery protocols for ovarian and cervical cancer are expanding IORT applicability. University hospitals in Japan and Germany are pioneering these applications as faster-growing procedure categories with unmet radiation therapy needs.
- Colorectal Cancer:Pelvic recurrence after rectal resection represents a targetable but technically challenging indication.
- Brain Tumors:Resection cavity sterilization applications remain limited by electron beam depth penetration constraints and neurosurgical workflow complexity.
Breast cancer leads on scale; gynecological malignancies lead on momentum.
End User:
Capital intensity and physics workforce requirements fragment the customer base between integrated academic systems and distributed community settings.
- Cancer Treatment Centers:Comprehensive oncology programs with embedded surgical and radiation departments capture the majority of linear accelerator installations. These centers in Germany, the United States, and Japan dominate high-complexity IORT procedure volumes.
- Ambulatory Surgical Centers:Outpatient facilities are piloting portable x-ray platforms to avoid dedicated shielding infrastructure. United States community hospital systems represent the primary expansion vector for workflow-flexible deployment models.
- Specialty Clinics:Breast-focused surgical practices concentrate portable system adoption in metropolitan markets.
- Research Institutes:Academic medical centers with clinical trial portfolios drive protocol innovation and regulatory evidence generation.
Cancer treatment centers lead on scale; ambulatory surgical centers lead on momentum.
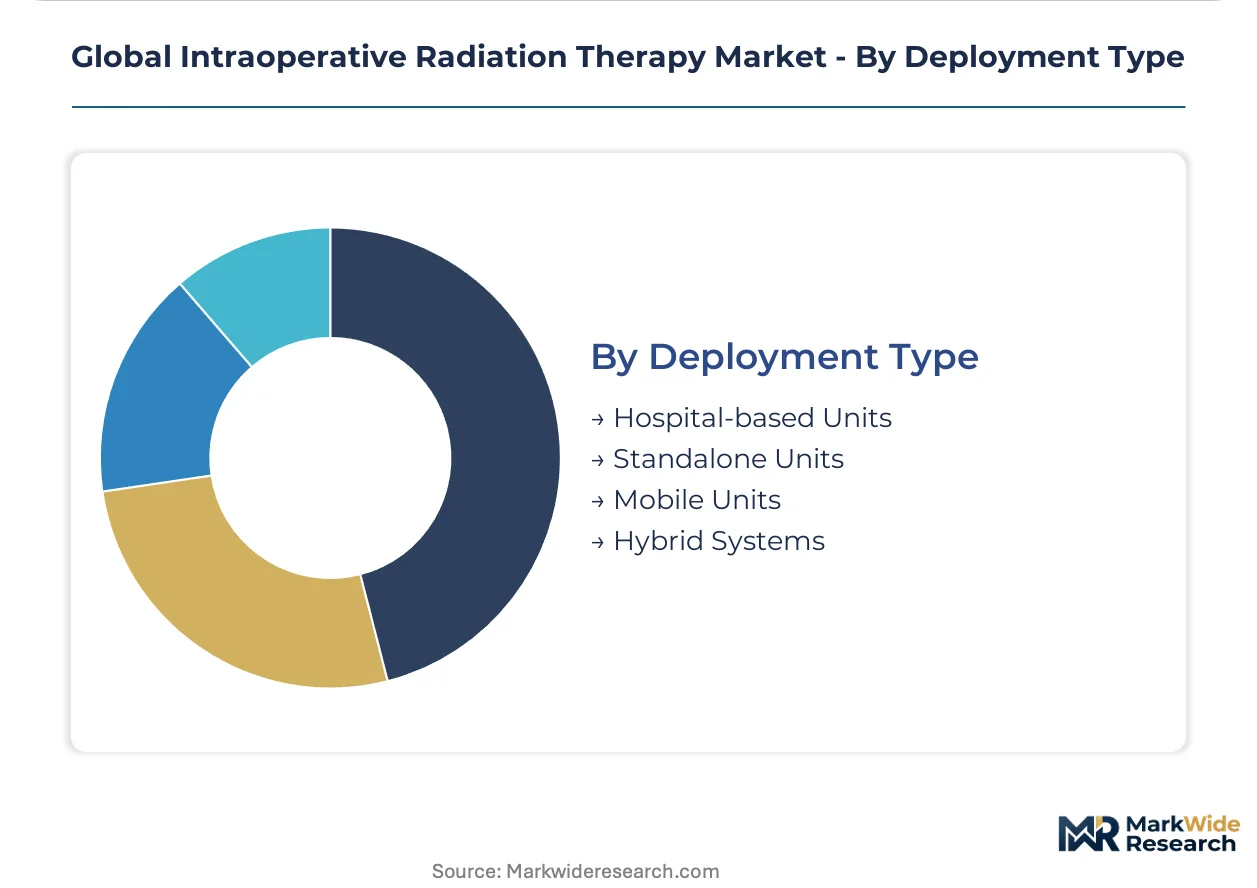
Deployment Type:
Physical integration architecture determines procurement committee composition and lifetime service contracting structures.
- Hospital-based Units:Fixed installations within dedicated surgical suites require coordination between radiation oncology, surgical services, and facilities management. German university hospitals exemplify this model with consolidated capital budgeting and long-term vendor service agreements.
- Mobile Units:Transportable electron beam systems enable equipment sharing across multiple surgical suites or hospital sites. United States health systems are deploying these platforms to maximize utilization rates without duplicating shielded infrastructure.
- Standalone Units:Dedicated IORT facilities separate from general radiotherapy departments serve high-volume referral networks.
- Hybrid Systems:Configurable platforms alternate between intraoperative and external beam delivery modes.
Hospital-based units lead on scale; mobile units lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany operates the highest-volume IORT programs in Europe, while the United States concentrates the largest installed base of linear accelerator systems. Japan maintains distinct regulatory pathways that delay market entry but reward early compliance investments. Academic medical centers across all three markets anchor procedure volume and technology adoption curves.
United States
FDA 21 CFR 1020.32 compliance requirements extend certification timelines for radiation-emitting device modifications. The agency's evolving guidance on medical device software updates accelerates review pathways for cloud-native treatment planning platforms. University hospitals in Boston and Houston operate among the highest-throughput IORT programs, with Massachusetts General and MD Anderson anchoring clinical evidence generation for breast cancer applications.
Germany
EMA Medical Device Regulation imposes stricter clinical evidence requirements for CE-marked electron beam platforms, advantaging prepared vendors in procurement cycles. The country's national pharmaceutical regulator maintains harmonized standards with notified bodies that streamline parallel conformity assessments. University hospitals in Heidelberg and Munich exemplify consolidated vendor relationships through long-term service contracts bundling hardware, software, and physics support.
Japan
PMDA maintains distinct technical standards for accelerator-based intraoperative systems that delay market entry relative to Western clearance pathways. METI coordinates industrial policy supporting domestic medical device manufacturing while facilitating foreign manufacturer registration. Tokyo and Osaka metropolitan procurement cycles favor electron beam platform vendors with early PMDA engagement and localized clinical evidence generation.
United Kingdom
NHS England's specialized commissioning frameworks concentrate IORT service delivery within designated cancer centers, limiting community hospital penetration. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device regulations with retained EU MDR provisions. London's Royal Marsden and Manchester's Christie Hospital anchor national procedure volume through integrated surgical oncology programs.
India
CDSCO regulates radiation-emitting medical devices under the Medical Device Rules 2017, with recent notifications bringing IORT platforms under stricter import licensing requirements. The country's national pharmaceutical regulator accelerates review timelines for devices with prior US FDA or EU CE approvals. Apollo Hospitals in Chennai and Tata Memorial Centre in Mumbai pioneer IORT adoption through public-private partnership models.
Global Intraoperative Radiation Therapy Market Competitive Landscape
Top-tier vendors anchor the linear accelerator segment, while specialized electron beam manufacturers occupy workflow-integrated niches. The vendor base stratifies across three tiers: diversified radiation oncology conglomerates with bundled service portfolios, dedicated IORT technology specialists, and emerging portable platform developers. Strategic archetypes include hardware-software integrators leveraging installed base advantages, electron beam pure-plays emphasizing surgical workflow specialization, and ambulatory-focused innovators bypassing capital-intensive infrastructure. Competitive moves concentrate on long-term service contracting and cloud-native treatment planning subscriptions.
Within the diversified radiation oncology tier, Elekta AB and Varian Medical Systems, Inc. exemplify hardware-software integration strategies leveraging broad linear accelerator installed bases. IntraOp Medical, Inc. occupies a distinct position as a dedicated electron beam IORT specialist, anchoring competitive differentiation through surgical workflow integration rather than general radiotherapy diversification. These three entities collectively represent the spectrum of vendor archetypes: conglomerate bundling, technology specialization, and platform-specific innovation.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| IntraOp Medical, Inc. |
| Elekta AB |
| Eckert & Ziegler |
| iCAD, Inc. |
| Varian Medical Systems, Inc. |
| S.I.T. Sordina IORT Technologies S.p.A. |
| IBA Worldwide |
| IsoRay, Inc. |
| Others |
Supply & Pricing Matrix
Electron beam versus portable x-ray platform divergence creates distinct pricing architectures and supply chain configurations across the intraoperative radiation therapy market. Premium linear accelerator systems command bundled service contracting in German university hospitals while low-energy portable platforms penetrate ambulatory surgical centers through subscription-based monetization models.
Pricing Analysis
Capacity additions in portable x-ray manufacturing are reshaping price floors for entry-level IORT platforms. The dominant pricing structure stratifies across premium linear accelerator installations, mid-tier mobile electron beam units, and economy portable x-ray systems with software-as-a-service treatment planning subscriptions. Price differentiation hinges on FDA 21 CFR 1020.32 certification tier and after-sales physics support bundling. Cost compression in the portable segment is intensifying because ambulatory surgical centers prioritize workflow flexibility over maximum dose precision. Community hospital systems exhibit highest price sensitivity while academic medical centers in Heidelberg and Munich demonstrate lowest sensitivity due to consolidated capital budgeting.
Supply Chain Analysis
Qualified medical physicist scarcity in Germany and the United States constrains manufacturing scale-up for electron beam system assembly. Supply concentration centers on precision radiation source production in Germany, linear accelerator component fabrication in the United States, and x-ray tube manufacturing in Japan. Raw material dependencies draw from high-purity tungsten for electron beam targets, specialized ceramic insulators for accelerator waveguides, and cloud infrastructure for treatment planning software delivery. Single-source vulnerability in linear accelerator magnet supply creates structural risk. Distribution runs through direct hospital system contracting with long-term service agreements displacing equipment-only transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as cytoreductive surgery protocols shift demand toward premium electron beam platforms with integrated dose verification and surgical workflow specialization.
For Market Incumbents: Anchor competitive position through backward integration into linear accelerator magnet production and captive medical physics training programs to offset workforce scarcity. Defend against portable x-ray disruptors by deepening hospital-based deployment partnerships that lock in long-term service contracts with consolidated vendor relationships. Certification investment in Japan's PMDA pathway serves as the priority lever for Tokyo and Osaka metropolitan procurement cycles. For New Entrants and Emerging Players: FDA 21 CFR 1020.32 compliance acceleration opens a window for cloud-native treatment planning specialists to bypass capital-intensive hardware manufacturing. Target ambulatory surgical centers in the United States as the most penetrable segment given their avoidance of bunker construction requirements and preference for subscription monetization. Go-to-market execution should emphasize workflow flexibility and point-of-care deployment without dedicated shielding infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where medical physics workforce scarcity fragments service delivery capability across community hospital settings. Long-term viability favors platforms with installed base advantages in recurring revenue software subscriptions rather than transactional equipment sales. Electron beam pure-plays with early PMDA engagement and localized clinical evidence generation represent the target acquisition archetype. Material deviation in reimbursement policy toward single-fraction IORT cost-effectiveness frameworks warrants pause and re-evaluation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EMA Medical Device Regulation compliance accelerates quality differentiation in European university hospital procurement. |
| Hospital System Partnership | Long-term service contracts with Heidelberg and Munich academic centers consolidate vendor relationships. |
| Software Companion Development | Cloud-native dose optimization subscriptions capture lifetime value from linear accelerator installed bases. |
| Reimbursement Strategy | Cost-effectiveness evidence generation addresses United States payor scrutiny of single-fraction IORT alternatives. |
| FDA Submission Acceleration | Evolving guidance on radiation-emitting medical device software updates compresses certification timelines. |
Research Methodology
Multiple input streams — primary interviews with radiation oncologists and hospital procurement managers, secondary validation through FDA 510(k) filings and EMA CE marking databases, and trade data reconciliation — were synthesized to construct market estimates. Conversations with biomedical engineers, GPO contracts managers, and medical physicists in Germany, the United States, and Japan informed installed base and procedure volume assumptions. Secondary sources included hospital procurement databases, CMS Medicare reimbursement data, and PMDA device registration records. Bottom-up procedure volume modeling and top-down equipment revenue triangulation cross-validated segment-level outputs.
Data-stream reconciliation across technology type, application, end user, and deployment architecture dimensions anchored the analytical framework. Segmentation modeling incorporated electron beam versus portable x-ray platform differentiation, breast cancer versus gynecological malignancy procedure categories, academic medical center versus ambulatory surgical center customer archetypes, and hospital-based versus mobile unit deployment configurations. CAGRs were derived from installed base expansion trajectories and procedure volume intensity assumptions. Forecast inputs included PMDA regulatory pathway timelines and United States payor reimbursement policy evolution.
Revisions become necessary when reimbursement denials for single-fraction IORT intensify, medical physics workforce scarcity worsens beyond academic center concentration, or portable x-ray platform reliability failures trigger regulatory enforcement. Forecasts reflect assumptions about cytoreductive surgery protocol adoption and cloud-native treatment planning subscription conversion rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Terminal Sterilization Market
Medical Equipment
Medical Oxygen Systems Market
Medical Equipment
Medical Automation Market
Medical Equipment
Medication Pouch Inspection Systems Market
Medical Equipment
Cryogenic Freezers Market
Medical Equipment
Medical Suction Units Market
Medical Equipment
Global Mobile Operating Tables Market
Medical Equipment
Global Vacuum Mixing Devices Market
Medical Equipment
X-Ray Generator Market
Medical Equipment
Faecal Extraction System Market
Medical Equipment
ECG Equipment and Management Systems Market
Medical Equipment
Healthcare Simulators Market
Medical Equipment
Global Hospital Equipment and Supplies Market
Medical Equipment
Global Medical Equipment Calibration Market
Medical Equipment
Global Renal Dialysis Equipment Market
Medical Equipment
Asia-Pacific Medical Device Cleaning Market